
 Veterinary Wellness Market | 2026-2036
Veterinary Wellness Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Wellness Market Analytics
North American pharmaceutical manufacturing capacity is consolidating as large-scale producers expand their veterinary health infrastructure. Zoetis Inc. leverages its integrated diagnostics and therapeutics portfolio to anchor its position across companion and livestock segments. Merck Animal Health sustains competitive strength through its global vaccine production network and livestock biologics specialization. Boehringer Ingelheim Animal Health differentiates via its emphasis on parasiticides and respiratory disease prevention products for cattle and swine operations.
Veterinary wellness encompasses preventive health management, nutritional optimization, and behavioral interventions for companion and production animals, typically delivered through pharmaceutical formulations with defined active ingredient concentrations, stability profiles, and species-specific dosing protocols. The primary commercial purpose centers on reducing disease incidence, extending productive lifespan, and improving quality-of-life metrics across animal populations. Supplements and vaccines currently occupy the largest product type positions, while preventive care applications generate the fastest expansion as pet owners shift from reactive treatment to scheduled wellness protocols. Nutrition and behavior management segments attract emerging margin pools as functional pet foods and anxiety therapeutics gain veterinary endorsement.
The FDA Center for Veterinary Medicine governs feed additives, drug approvals, and medicated feed manufacturing in the United States, while the USDA Animal and Plant Health Inspection Service regulates interstate movement and disease eradication programs that directly shape vaccine demand. The EPA additionally oversees topical parasiticide environmental safety, creating multi-agency compliance requirements for product developers. Stakeholders must monitor evolving regulatory convergence between human and veterinary pharmaceutical standards, as this alignment will determine which manufacturers can sustain cross-species R&D economies without duplicative approval investments.
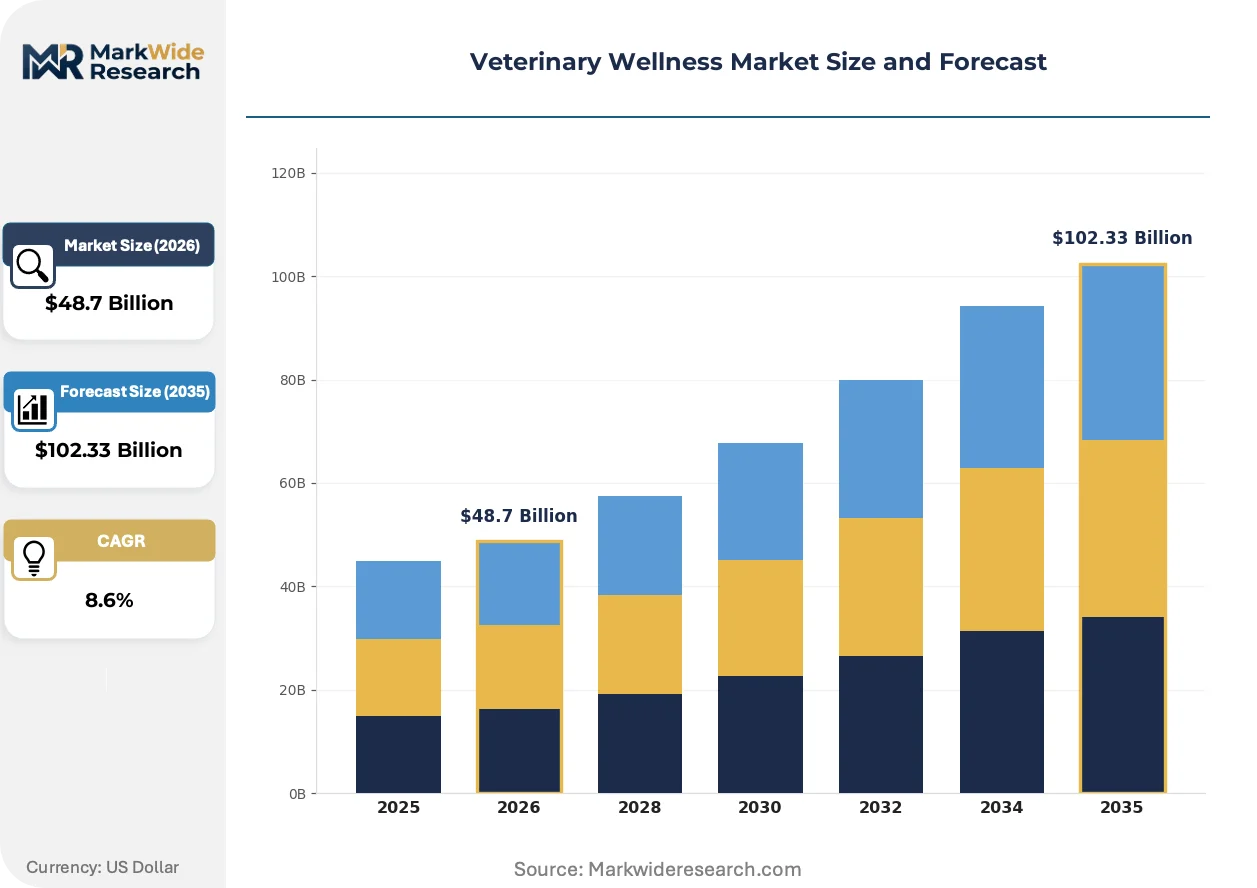
Market Dynamics
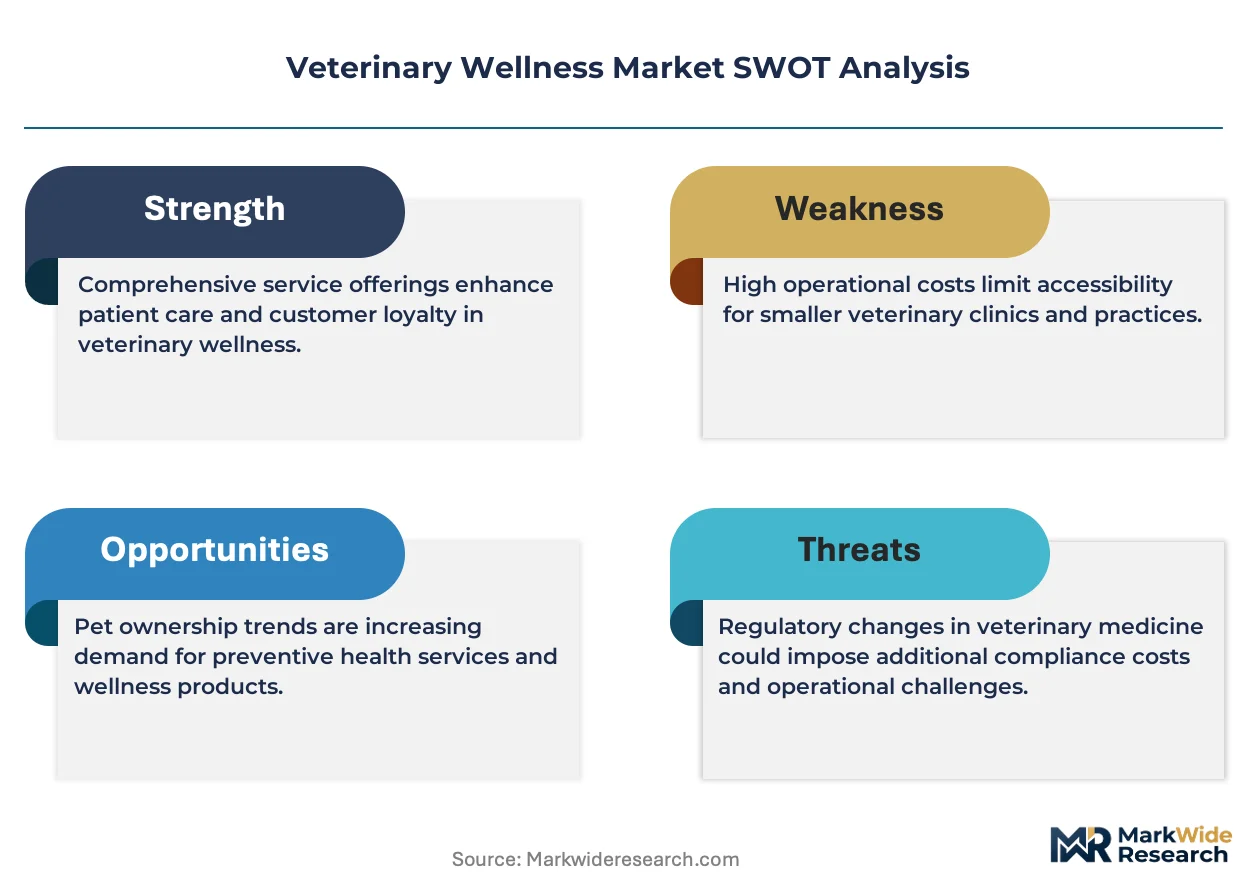
Preventive care protocols are displacing reactive treatment models across companion animal practices, compressing visit frequency while expanding per-encounter service intensity and diagnostic bundling.
Growth Catalysts
- Companion Animal Humanization:Pet owners in the United States now schedule wellness examinations at intervals previously reserved for pediatric care, expanding routine bloodwork and dental cleaning volumes.
- FDA Center for Veterinary Medicine Streamlining:The agency's expanded conditional approval pathways for minor use and minor species drugs accelerates therapeutic access for exotic and farmed fish populations.
- Telehealth Infrastructure:Remote consultation platforms are converging with diagnostic imaging workflows, enabling asynchronous specialist review of radiographs and dermatology cases.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Synthesis of veterinary-specific compounds relies on a limited base of contract manufacturers in India and China, creating supply vulnerability during geopolitical friction.
- USDA Interstate Movement Restrictions:Livestock wellness product distribution faces quarantine-triggered logistics interruptions that fragment demand forecasting for vaccine producers.
- Generic Substitution Pressure:Patent-expired parasiticides face price erosion from compounded alternatives, compressing margin pools for originator formulations.
Strategic Opportunities
- Underpenetrated Production Animal Segments:Poultry and aquaculture operations in Brazil present untapped demand for automated vaccination delivery systems and feed-additive monitoring.
- EU Green Deal Alignment:The European Commission's Farm to Fork strategy incentivizes reduced antibiotic usage, creating pull for phytogenic feed additives and microbiome modulation products.
- Behavioral Health Integration:Separation anxiety and noise phobia therapeutics represent an emerging application where pharmaceutical intervention is converging with wearable monitoring devices.
Industry Challenges
- Veterinary Specialist Shortage:Board-certified nutritionists and behaviorists remain concentrated in metropolitan corridors, limiting service scalability for rural and exurban practices.
- Multi-Agency Compliance Complexity:Product developers must simultaneously satisfy FDA drug approval timelines, EPA environmental fate studies, and USDA biologics licensing, extending commercialization cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Wellness Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $102.33 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Supplements, Diets, Grooming Products, Vaccines Application: Preventive Care, Therapeutic Care, Nutrition, Behavior Management End User: Pet Owners, Veterinary Clinics, Animal Shelters, Zoos Distribution Channel: Retail Stores, Online Platforms, Veterinary Distributors, Wholesale |
| Companies Covered | Zoetis Inc., Merck Animal Health, Boehringer Ingelheim Animal Health, Elanco Animal Health, Ceva Santé Animale, Virbac, Dechra Pharmaceuticals, IDEXX Laboratories, Vetoquinol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Wellness Market Evolving Landscape
Digital biomarker capture and artificial intelligence-assisted diagnostic interpretation are compressing the latency between symptom presentation and therapeutic intervention across species.
Point-of-care PCR platforms are converging with cloud-based pathogen surveillance networks, enabling same-day infectious disease confirmation. Small animal emergency and specialty hospitals in the United States and Western Europe have adopted these systems at accelerating rates since 2022. Real-time genomic data submission is converging with centralized resistance mapping, allowing clinics to adjust empiric therapy before culture results return.
The FDA's expanded animal food ingredient review process is reshaping novel protein and additive commercialization pathways. Manufacturers must now submit comprehensive safety dossiers for cell-cultured meat ingredients and insect-based proteins intended for pet consumption. Functional pet food startups are responding by front-loading toxicology investments to secure Generally Recognized as Safe affirmations before formulation scale-up.
Subscription-based preventive care plans are displacing fee-for-service billing in companion animal general practice. United States veterinary groups are bundling vaccinations, parasite screening, and telehealth access into monthly payment structures. This model concentrates most visibly in corporate-owned practice networks across Texas, Florida, and California, where client retention metrics now drive valuation multiples.
Veterinary Wellness Market Segmentation
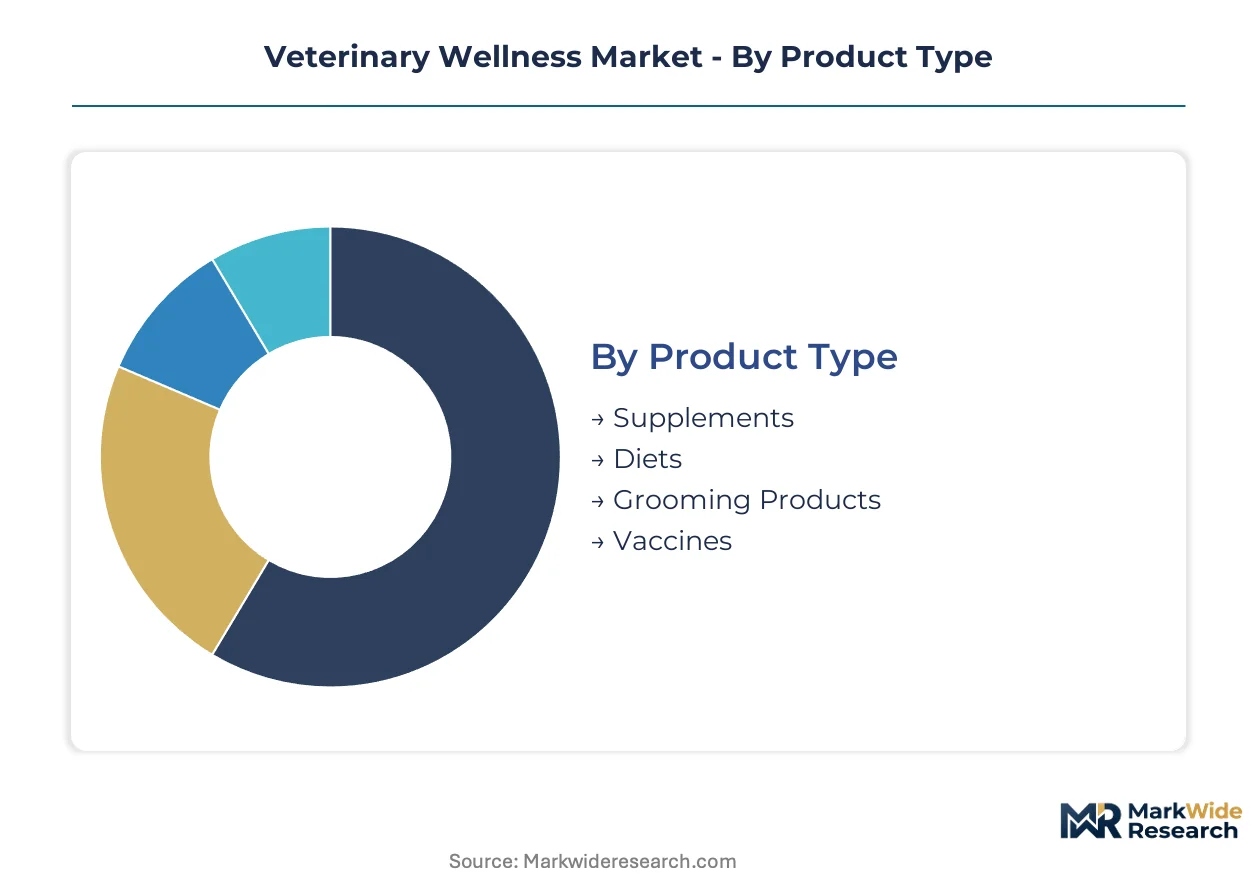
Veterinary wellness segmentation reflects divergent purchasing logics across companion versus production animal contexts, with product form and channel access determining margin capture. Understanding these divides enables targeted portfolio construction against distinct clinical and consumer decision frameworks.
Product Type:
Formulation science and dosing precision drive veterinarian endorsement and owner compliance across product categories.
- Supplements:Formulations containing defined concentrations of omega fatty acids, glucosamine, and probiotics target joint mobility and digestive health in aging companion animals. Demand clusters in urban United States households seeking veterinary-grade alternatives to retail commodity offerings, constrained by variable bioavailability across species.
- Vaccines:Attenuated and recombinant viral preparations with established cold-chain stability profiles anchor preventive protocols for core infectious diseases. United States small animal practices and Brazilian poultry operations generate concentrated procurement volumes, shaped by USDA and MAPA regulatory compliance requirements for interstate and international movement documentation.
- Diets:Prescription-grade therapeutic nutrition with controlled mineral and protein content addresses renal, hepatic, and allergic conditions.
- Grooming Products:Medicated shampoos and dermatological wipes integrate active pharmaceutical ingredients for otitis externa and pyoderma management.
Vaccines lead on scale; Supplements lead on momentum.
Application:
Service intensity and reimbursement pathways determine pricing power and customer lifetime value across use cases.
- Preventive Care:Scheduled wellness examinations, parasite screening, and vaccination protocols reduce emergency intervention frequency. United States corporate practice networks in Texas and Florida bundle these services into subscription plans, accelerating per-patient revenue predictability.
- Behavior Management:Pharmaceutical interventions for separation anxiety and noise phobia converge with wearable monitoring and telehealth consultation. Metropolitan United States markets show concentrated uptake where board-certified veterinary behaviorists maintain practice presence.
- Therapeutic Care:Disease treatment protocols following diagnostic confirmation, including antimicrobial and anti-inflammatory administration.
- Nutrition:Customized feeding programs optimizing body condition and metabolic health across life stages.
Preventive Care dominates revenue contribution; Behavior Management exhibits steepest expansion trajectory.
End User:
Purchasing authority and volume scale create distinct commercial engagement models across customer types.
- Veterinary Clinics:Licensed practices with diagnostic and dispensing authority generate concentrated demand for prescription diets, vaccines, and therapeutics. United States general and emergency hospitals in California and New York anchor volume, with procurement decisions influenced by group purchasing organization contracts and manufacturer rebate structures.
- Pet Owners:Individual consumers purchasing over-the-counter supplements and grooming products through retail and digital channels. Direct-to-consumer subscription models gain traction in United States urban corridors, driven by convenience positioning and auto-replenishment mechanics.
- Animal Shelters:Non-profit and municipal facilities managing population health with constrained budgets.
- Zoos:Specialized institutions requiring exotic species formulations and minor species regulatory pathways.
Veterinary Clinics anchor volume concentration; Pet Owners represent the most rapidly diversifying access point.
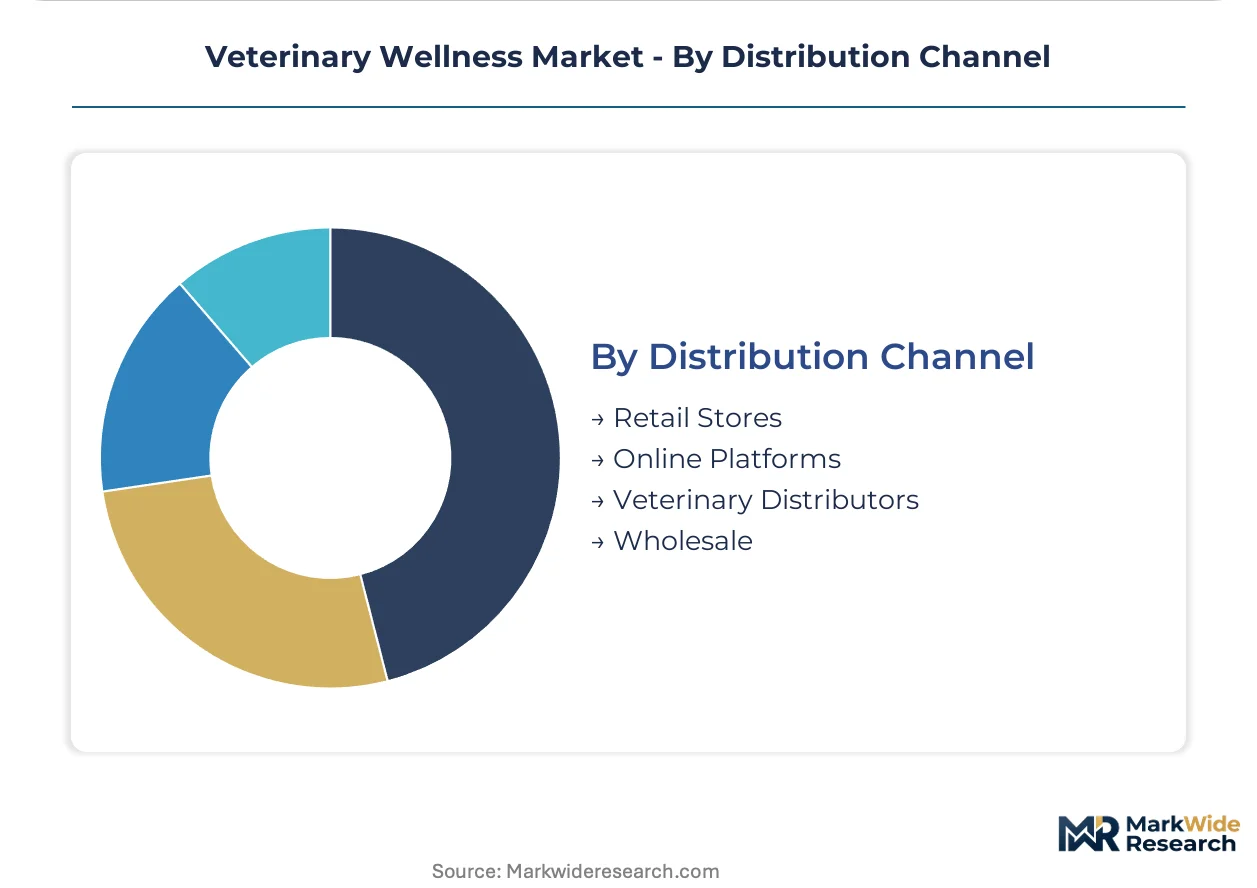
Distribution Channel:
Channel selection determines margin retention and customer data access across the value chain.
- Veterinary Distributors:Specialized logistics networks with cold-chain capabilities and controlled substance licensing serve clinic-centric procurement. United States distributors maintain inventory positions across multiple manufacturer lines, enabling consolidated ordering for independent practices.
- Online Platforms:Digital marketplaces and direct manufacturer storefronts bypass traditional wholesale markups for supplement and grooming categories. United States pet owner adoption accelerates through mobile-optimized subscription interfaces with veterinary telehealth integration.
- Retail Stores:Mass merchandisers and specialty pet supply chains carrying over-the-counter wellness products.
- Wholesale:Bulk procurement channels serving production animal operations and institutional buyers.
Veterinary Distributors retain the largest transaction volume; Online Platforms show the fastest channel share gain.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping where veterinary wellness manufacturing concentrates, with producers migrating toward jurisdictions offering streamlined approval pathways for novel ingredients and reduced environmental compliance burdens relative to the United States.
United States
Urban households in Texas, Florida, and California drive premium pet nutrition and telehealth veterinary services adoption. The FDA Center for Veterinary Medicine oversees pet food labeling and safety standards, while the USDA Animal and Plant Health Inspection Service regulates interstate vaccine movement. Corporate-owned practice networks across metropolitan corridors anchor subscription-based preventive care plan proliferation.
Germany
Livestock operations in Lower Saxony and North Rhine-Westphalia generate concentrated demand for reduced-antibiotic wellness protocols aligned with EU Green Deal Farm to Fork targets. The European Commission's phytogenic feed additive incentives pull manufacturers toward microbiome modulation product development. Munich and Stuttgart host specialized veterinary pharmaceutical research clusters advancing species-specific dosing formulations.
Brazil
Poultry and aquaculture producers in São Paulo and Paraná present untapped demand for automated vaccination delivery systems and feed-additive monitoring technologies. MAPA regulatory compliance requirements shape international movement documentation for vaccine procurement. Campinas anchors emerging manufacturing capacity serving Latin American export markets.
China
Contract manufacturers in Zhejiang and Jiangsu provinces supply active pharmaceutical ingredients for veterinary-specific compounds, creating supply vulnerability during geopolitical friction. The National Medical Products Administration governs veterinary drug registration and manufacturing practice standards. Shanghai's biotech corridor attracts joint ventures targeting companion animal therapeutic development.
United Kingdom
Specialty and emergency hospital networks in London and the Southeast concentrate diagnostic imaging and point-of-care PCR platform adoption. The Veterinary Medicines Directorate regulates product marketing authorizations and pharmacovigilance requirements. Cambridge-Oxford research clusters advance artificial intelligence-assisted diagnostic interpretation tools for asynchronous specialist review.
Veterinary Wellness Market Competitive Landscape
United States producers anchor one tier of consolidated pharmaceutical manufacturing; European specialists hold differentiated positions in parasiticides and respiratory disease prevention. The market structure reflects vertical integration advantages among originators with captive diagnostic platforms, while mid-scale manufacturers compete through compounded generic alternatives. Three archetypes dominate: integrated diagnostics-therapeutics conglomerates, livestock biologics specialists, and functional nutrition formulators. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with manufacturers securing cold-chain logistics networks and cloud-based pathogen surveillance integrations.
Within the integrated platform tier, Zoetis Inc. and Merck Animal Health exemplify archetypes combining vaccine production networks with point-of-care diagnostic deployment. Boehringer Ingelheim Animal Health occupies a position emphasizing parasiticide development for cattle and swine operations. These entities represent varying geographic origins and corporate structures, with each anchoring distinct competitive vectors across companion and production animal segments.
| Leading Market Players |
|---|
| Zoetis Inc. |
| Merck Animal Health |
| Boehringer Ingelheim Animal Health |
| Elanco Animal Health |
| Ceva Santé Animale |
| Virbac |
| Dechra Pharmaceuticals |
| IDEXX Laboratories |
| Vetoquinol |
| Others |
Value Network & Pricing Analysis
Active pharmaceutical ingredient synthesis costs in India and China flow through contract manufacturing markups into originator parasiticide pricing tiers, with FDA and EPA compliance investments stratifying final product positioning across premium veterinary-grade and economy generic segments.
Pricing Analysis
Distributor margins for vaccines and therapeutics compress as group purchasing organization contracts consolidate procurement volume across United States corporate practice networks. Pricing stratifies across premium, standard, and economy tiers based on FDA approval pathway and cold-chain certification level. Price erosion intensifies in patent-expired parasiticides where compounded alternatives capture price-sensitive rural clinics. Corporate-owned practices in Texas and Florida show lowest price sensitivity due to subscription bundling; independent exurban clinics remain most exposed to generic substitution.
Supply Chain Analysis
Dual-sourcing mandates from United States veterinary distributors require API qualification across at least two contract manufacturers, typically split between Zhejiang province facilities and Jiangsu province operations in China. Supply chains draw from concentrated veterinary-specific chemical synthesis capacity, with cold-chain logistics for attenuated vaccines resting on specialized distributor networks. Single-source vulnerability in Chinese API production creates tariff exposure risk during geopolitical friction. Distribution runs through veterinary distributors with controlled substance licensing and temperature-validated warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The veterinary wellness market compounds steadily as companion animal humanization sustains recurring revenue predictability through subscription preventive care models.
For Market Incumbents: Cement diagnostic-therapeutic integration by embedding point-of-care PCR platforms within corporate practice networks, defending against telehealth-enabled new entrants. Prioritize backward integration into cold-chain logistics to secure vaccine distribution control against distributor consolidation.
For New Entrants and Emerging Players: Telehealth platforms offer the most penetrable channel wedge, enabling asynchronous specialist consultation for dermatology and radiology cases without board-certified specialist density. Target behavioral health integration in metropolitan United States corridors where anxiety therapeutics converge with wearable monitoring devices.
For Investors and Strategic Acquirers: Roll-up economics work for functional pet food formulators because FDA's expanded animal food ingredient review process creates compliance moats that scale across brand portfolios. Watch FDA conditional approval pathway expansion for minor species drugs as the inflection signal indicating regulatory arbitrage opportunity.
| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic Platform Integration | Point-of-care PCR deployment within corporate practice networks anchors vaccine and therapeutic bundling. |
| Conditional Approval Pathway Investment | FDA minor species drug acceleration opens exotic and aquaculture therapeutic access before full approval. |
| Cold-Chain Logistics Acquisition | Controlled temperature distribution networks secure vaccine stability compliance and distributor margin capture. |
| Phytogenic Feed Additive Development | EU Green Deal Farm to Fork alignment creates pull for microbiome modulation in German livestock operations. |
| Behavioral Health Wearable Partnership | Convergence of separation anxiety therapeutics with monitoring devices builds veterinary endorsement in urban markets. |
Research Methodology
Direct dialogue with veterinary practice owners, pharmaceutical regulatory affairs directors, distributor procurement managers, and companion animal nutrition formulators combined with secondary validation against FDA Center for Veterinary Medicine filings, USDA APHIS interstate movement records, and EPA environmental fate study databases. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored segmentation outputs.
Market size and growth trajectory outputs across the projection horizon reflect multivariate modeling across product type, application, end user, and distribution channel dimensions. CAGRs derived from historical volume elasticity analysis against pet ownership demographics and preventive care protocol adoption curves. Companion animal humanization indices and telehealth platform penetration rates served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA regulatory convergence with human pharmaceutical standards and geopolitical friction affecting Chinese API supply. Deviation in conditional approval pathway timelines or USDA interstate quarantine triggers would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Medicine
Global Brucellosis Vaccines Market
Veterinary Medicine
Global Newcastle Disease Vaccine Market
Veterinary Medicine
Animal Drugs Market
Veterinary Medicine
US Veterinary Orthopedic Medicine Market
Veterinary Medicine
Middle East Veterinary Vaccines Market
Veterinary Medicine
Veterinary Anesthesia Machines Market
Veterinary Medicine
Veterinary Assistive Reproduction Technology Market
Veterinary Medicine
Global Veterinary/Animal Vaccines Market
Veterinary Medicine
Global Veterinary Eye Care Market
Veterinary Medicine
Global Companion Animal Pharmaceuticals Market
Veterinary Medicine
Veterinary Dental Elevators Market
Veterinary Medicine
US Veterinary Diagnostics Market
Veterinary Medicine
South Africa Veterinary Medicine Market
Veterinary Medicine
Monoclonal Antibodies in Veterinary Health Market
Veterinary Medicine
Veterinary Forceps Market
Veterinary Medicine
Veterinary Anti-Infectives Market