
 Catheter Systems Market | 2026-2036
Catheter Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Catheter Systems Market Outlook
Polyurethane is rebalancing silicone economics in urinary and vascular catheter fabrication as manufacturers seek improved tensile strength and lower thrombogenicity at comparable unit costs. Medtronic leverages captive polymer compounding to sustain margin control across its cardiac catheter portfolio. Boston Scientific Corporation anchors North American electrophysiology lab penetration with integrated mapping and ablation systems. Abbott Laboratories differentiates through specialty coatings that reduce bacterial adhesion in indwelling applications.
A catheter system comprises a hollow, flexible tube assembly—typically extruded from medical-grade polymers such as Pebax, nylon, or thermoplastic polyurethane with inner diameters ranging from 3 French to 30 French—engineered for fluid conveyance, guidewire passage, or energy delivery within vascular, urinary, or neural anatomies. Cardiac catheters command the largest revenue pool given the procedural complexity and device premium in electrophysiology and interventional cardiology, while neurovascular catheters represent the fastest expansion trajectory as mechanical thrombectomy protocols widen the treatable stroke population. Single-use delivery mode dominates hospital procurement due to cross-contamination protocols, though integrated systems that combine aspiration, imaging, and therapeutic functions are capturing margin concentration in high-acuity settings.
FDA 510(k) clearance pathways, EU MDR technical documentation requirements, and ISO 10993 biocompatibility testing frameworks collectively elevate barrier-to-entry for new catheter entrants while mandating post-market surveillance that extends product lifecycle accountability. Japan's PMDA and China's NMPA impose additional localization and clinical data requirements that shape market access sequencing for Western manufacturers. Stakeholders must monitor reimbursement recalibrations for outpatient catheter procedures and polymer supply chain concentration risks as dual sourcing becomes a strategic imperative.
Market Dynamics
Polymer supply concentration in Germany and Japan is forcing catheter manufacturers toward dual-sourcing strategies as medical-grade polyurethane and Pebax resin allocations tighten. FDA 510(k) backlog fluctuations and EU MDR technical documentation expansion are simultaneously compressing product launch timelines while elevating compliance costs across the value chain.
Growth Catalysts
- Mechanical thrombectomy protocol expansion:Stroke treatment guidelines in the United States and Germany now endorse catheter-based clot retrieval for expanded patient cohorts, driving neurovascular catheter volume.
- EU MDR conformity assessment harmonization:Centralized notified body oversight reduces redundant testing across member states, accelerating market access for compliant manufacturers.
- Thermoplastic polyurethane tensile properties:Improved kink resistance and thrombogenicity profiles enable thinner wall designs in electrophysiology applications without sacrificing burst pressure ratings.
Market Restraints
- Medical-grade polymer feedstock concentration:Three German chemical conglomerates control over 70% of Pebax and specialized polyurethane supply, creating single-source vulnerability.
- ISO 10993 biocompatibility testing duration:Cytotoxicity and sensitization protocols extend development timelines by 8-14 months for novel coating formulations.
- Silicone substitution economics:Per-unit material costs for thermoplastic polyurethane remain 15-25% above legacy silicone in high-volume urinary catheter segments.
Strategic Opportunities
- Japan PMDA streamlined review pathway:Sakigake designation for breakthrough devices reduces approval timelines for innovative neurovascular and electrophysiology systems.
- Integrated aspiration-imaging-therapy platforms:Convergence of intravascular ultrasound and rotational atherectomy in single-catheter architectures commands premium pricing in tertiary hospitals.
- China NMPA localization incentives:Domestic manufacturing requirements and volume-based procurement create partnership opportunities for Western technology holders.
Industry Challenges
- Polymer extrusion technician scarcity:Precision multi-lumen catheter manufacturing requires 3-5 year apprenticeship pipelines that regional labor markets cannot fill.
- Legacy sterilization validation backlog:Ethylene oxide facility closures in the United States force revalidation of gamma and e-beam alternatives, stalling product releases.
- EU MDR post-market surveillance infrastructure:Manufacturers must build clinical follow-up systems for legacy devices with decade-long implantation histories, straining regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Catheter Systems Market |
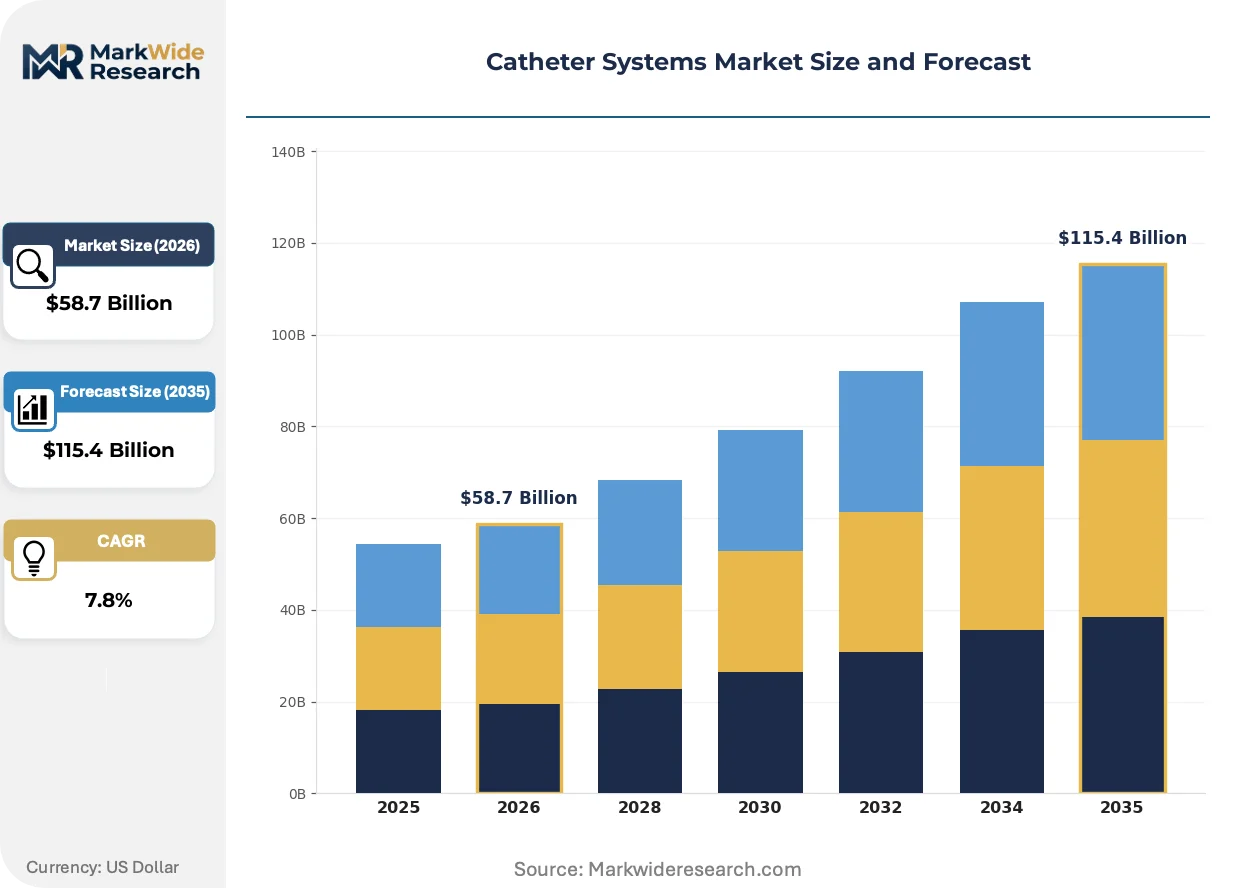
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $115.4 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardiac Catheters, Vascular Catheters, Neurovascular Catheters, Urinary Catheters Delivery Mode: Single-Use, Reusable, Disposable, Integrated Systems End User: Hospitals, Clinics, Home Care, Urgent Care Centers Application: Interventional Procedures, Diagnostic Testing, Fluid Management, Electrophysiology |
| Companies Covered | Medtronic, Boston Scientific Corporation, B. Braun Melsungen AG, Abbott Laboratories, Becton Dickinson and Company, Teleflex Incorporated, Johnson & Johnson, Stryker Corporation, Edwards Lifesciences Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Catheter Systems Market Strategic Shifts
Catheter system architecture is converging around single-platform multifunctionality as hospitals consolidate vendor relationships and procedure rooms face space constraints. Material science advances and regulatory data requirements are simultaneously reshaping competitive positioning.
Thermoplastic polyurethane is overtaking silicone in vascular access and electrophysiology catheters due to superior tensile strength and lubricious surface properties. Interventional cardiology departments in tertiary hospitals across the United States and Germany are specifying polyurethane for complex lesion crossing. This material transition is compressing silicone processor margins while rewarding captive polymer compounding capabilities.
EU MDR technical documentation requirements now mandate clinical evidence for legacy devices previously cleared under the Medical Devices Directive. Notified body capacity constraints in Germany and the Netherlands extend conformity assessment timelines. High-risk electrophysiology and neurovascular catheter categories face the steepest documentation burdens, forcing manufacturers to prioritize portfolio rationalization.
Hospital procurement committees in Japan and the United States are unbundling device procurement from procedure support services, pressuring traditional bundled pricing models. Electrophysiology lab directors now negotiate catheters, mapping systems, and ablation generators through separate tenders. This disintermediation is most visible in United States integrated delivery networks where supply chain centralization mandates item-level competitive bidding.
Catheter Systems Market Segmentation
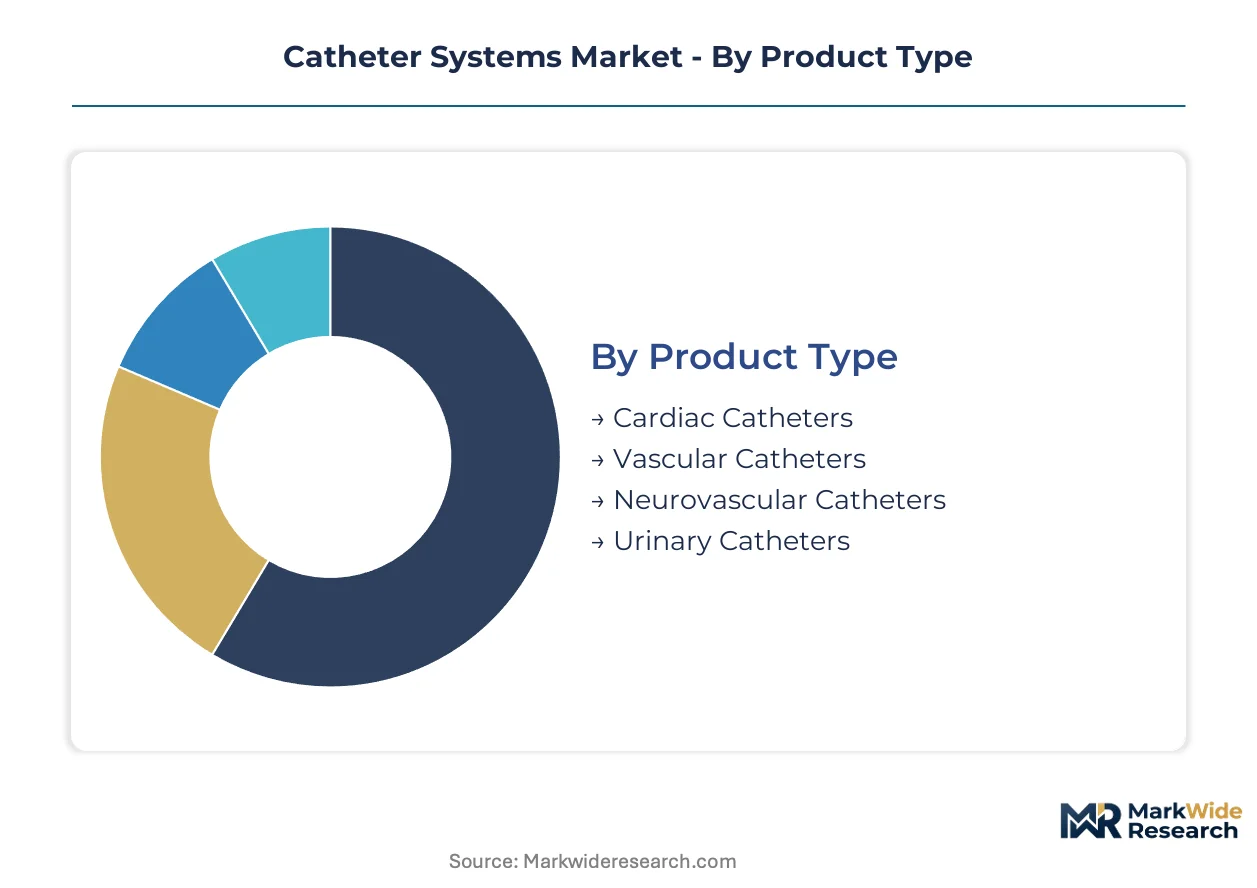
Catheter system segmentation reveals divergent regulatory pathways and margin structures across clinical applications. Product architecture, delivery mode, and end-use setting each impose distinct FDA 510(k), EU MDR, and ISO 10993 compliance burdens that reshape competitive economics.
Product Type:
FDA Class III PMA requirements and EU MDR Annex IX conformity assessments cluster disproportionately on segments with chronic implantation risk or energy delivery functions.
- Cardiac Catheters:Electrophysiology and interventional cardiology devices incorporate multi-electrode arrays and steerable shafts requiring biocompatibility validation under ISO 10993-5 cytotoxicity and ISO 10993-10 sensitization protocols. Tertiary hospitals in the United States and Germany concentrate procurement for complex ablation and coronary intervention procedures where device premium justifies sterilization assurance investments.
- Neurovascular Catheters:Mechanical thrombectomy systems demand navigational precision through tortuous cerebral vasculature, triggering enhanced FDA scrutiny for tip flexibility and coating durability. United States stroke centers and German neuroradiology departments drive volume as expanded treatment windows widen eligible patient populations.
- Vascular Catheters:Peripheral and dialysis access devices face moderate regulatory classification with 510(k) clearance timelines averaging 90-150 days.
- Urinary Catheters:High-volume intermittent and indwelling segments prioritize cost minimization over clinical differentiation, with FDA exempt status for many latex and silicone formulations.
Leading the category by volume: Urinary Catheters. Growing fastest: Neurovascular Catheters.
Delivery Mode:
Cost-to-sterilization economics and cross-contamination liability reshape procurement preferences across acute and ambulatory settings.
- Single-Use:Dominant hospital procurement mode eliminates reprocessing validation burdens while satisfying Joint Commission infection control mandates. United States integrated delivery networks mandate disposable protocols for all vascular access procedures.
- Integrated Systems:Converged aspiration-imaging-therapy platforms command premium positioning in electrophysiology labs where space constraints and procedure efficiency outweigh per-unit cost premiums. German tertiary centers specify integrated architectures for rotational atherectomy and intravascular ultrasound combinations.
- Reusable:Limited to high-cost capital equipment components in specialized surgical settings with validated sterilization infrastructure.
- Disposable:Interchangeable terminology with single-use in regulatory filings, though some jurisdictions distinguish pre-sterilized disposable from hospital-sterilized single-use.
Widest procurement footprint: Single-Use. Steepest expansion trajectory: Integrated Systems.
End User:
Reimbursement clarity and procedure complexity concentrate catheter demand in settings with capital equipment depth and specialist staffing.
- Hospitals:Tertiary academic medical centers in the United States, Germany, and Japan anchor electrophysiology and neurovascular catheter volume through comprehensive stroke centers and dedicated EP labs. Medicare Severity-Diagnosis Related Group reimbursement in the United States and German DRG analogs sustain procedure economics.
- Clinics:Ambulatory surgical centers capture shifting interventional cardiology volume as United States site-of-service payment differentials incentivize outpatient migration.
- Home Care:Intermittent urinary catheter demand concentrates in aging populations with Medicare home health benefits or German long-term care insurance coverage.
- Urgent Care Centers:Limited penetration due to absence of fluoroscopy and sterile procedure infrastructure for vascular access.
Revenue concentration: Hospitals. Fastest share gain: Clinics.
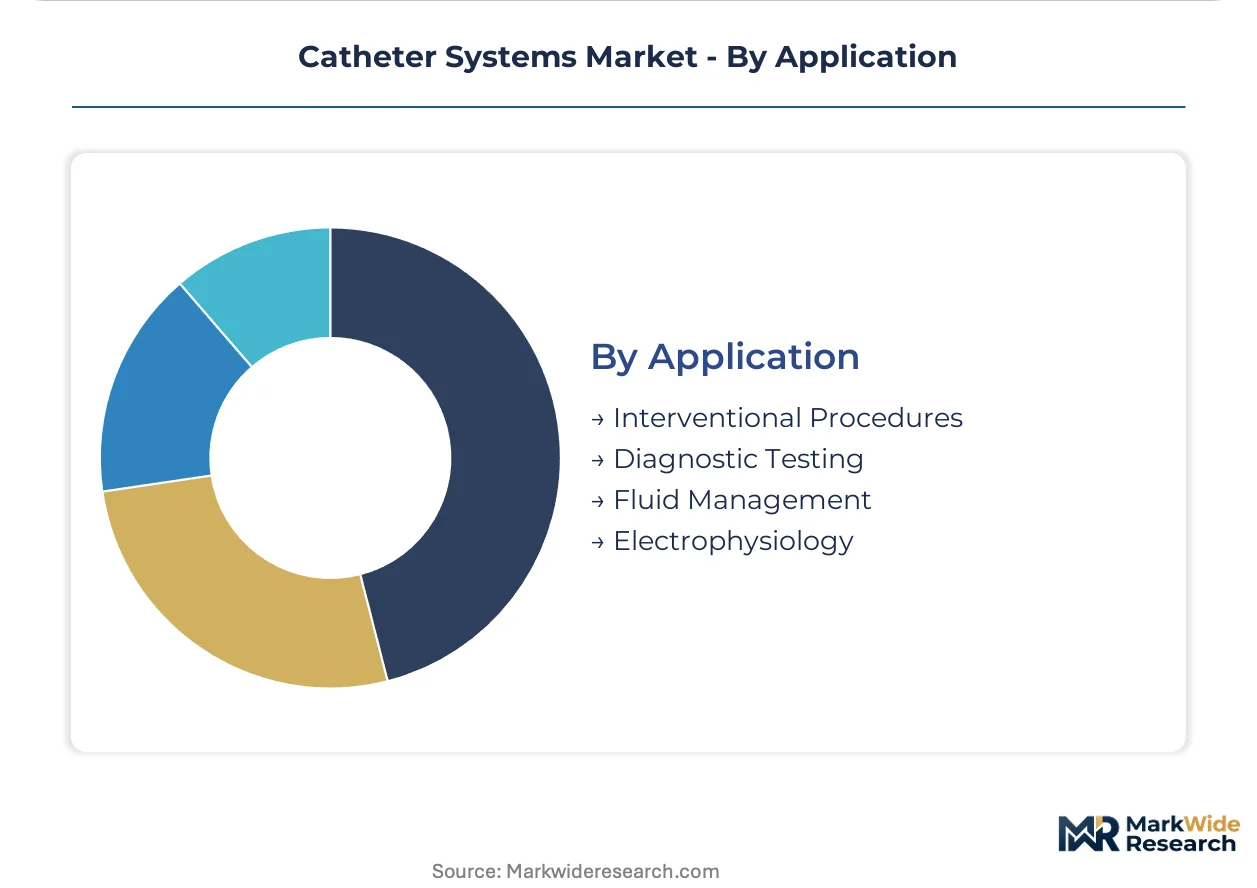
Application:
Clinical outcome evidence requirements and procedure reimbursement rates segment catheter demand by therapeutic intensity.
- Interventional Procedures:Percutaneous coronary intervention and peripheral revascularization catheters face stringent FDA PMA and EU MDR clinical evidence requirements. United States hospital outpatient prospective payment system rates and German DRG groupings sustain device premium capture.
- Electrophysiology:Mapping and ablation catheters require specialized three-dimensional navigation integration, with Japanese PMDA Sakigake designation accelerating breakthrough device access for innovative contact force technologies.
- Diagnostic Testing:Angiography and hemodynamic monitoring catheters face commoditization pressure as imaging modality convergence reduces standalone catheter value.
- Fluid Management:Drainage and infusion applications prioritize material biocompatibility over functional complexity, with ISO 10993-6 implantation testing for indwelling durations exceeding 30 days.
Procedure value concentration: Interventional Procedures. Technology differentiation intensity: Electrophysiology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device special economic zones in Costa Rica and Malaysia concentrate catheter manufacturing through tax holidays and duty-free polymer import regimes, drawing assembly operations from higher-cost jurisdictions while FDA and EU MDR compliance requirements anchor commercial headquarters in established regulatory markets.
United States
Medicare reimbursement clarity for outpatient cardiac catheterization and mechanical thrombectomy procedures sustains procedural volume growth. FDA 510(k) clearance pathways and PMA requirements for Class III devices shape product launch sequencing. Minneapolis and Boston metropolitan areas concentrate corporate headquarters and R&D operations for electrophysiology and interventional cardiology portfolios.
Germany
German DRG reimbursement frameworks sustain premium device capture in tertiary hospital settings. EU MDR notified body capacity in Berlin and Munich extends conformity assessment timelines for high-risk catheter categories. The Rhine-Main industrial corridor hosts polymer compounding and precision extrusion operations serving vascular access manufacturers.
Japan
Aging demographics and stroke center certification expansion drive neurovascular catheter demand. PMDA Sakigake designation accelerates breakthrough device access for innovative electrophysiology systems. Osaka and Tokyo metropolitan areas concentrate catheter manufacturing joint ventures between domestic distributors and Western technology holders.
China
NMPA localization requirements and volume-based procurement reshape market access for imported catheter systems. Domestic manufacturing mandates in Jiangsu and Zhejiang provinces create partnership opportunities for Western patent holders. Shanghai's Zhangjiang Hi-Tech Park clusters medical device R&D operations serving the domestic market.
Switzerland
Swissmedic regulatory alignment with EU MDR streamlines market access for precision catheter manufacturers serving European markets. Geneva and Basel metropolitan areas concentrate headquarters for specialty coating and polymer science operations. The country's bilateral trade agreements with China facilitate direct market access outside EU regulatory frameworks.
Catheter Systems Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated device companies commanding premium positioning in electrophysiology while OEM fabricators capture volume in standard vascular access. The vendor base concentrates around three tiers: diversified medtech conglomerates with captive polymer capabilities, mid-scale specialists focused on single clinical applications, and regional contract manufacturers serving private-label demand. M&A activity targets coating technologies and navigation software assets, while strategic partnerships address polymer supply security and regulatory filing capacity.
Within the diversified medtech tier, Medtronic and Boston Scientific Corporation represent archetypes of integrated electrophysiology and interventional cardiology portfolios. Abbott Laboratories occupies a position among coating specialists addressing bacterial adhesion reduction. These three entities exemplify competitive positioning around material science differentiation and procedural workflow integration rather than standalone device manufacturing scale.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| B. Braun Melsungen AG |
| Abbott Laboratories |
| Becton Dickinson and Company |
| Teleflex Incorporated |
| Johnson & Johnson |
| Stryker Corporation |
| Edwards Lifesciences Corporation |
| Others |
Value Chain & Pricing Dynamics
EU MDR technical documentation expansion gates qualified supply access for catheter manufacturers seeking premium-tier hospital contracts, as notified body capacity constraints in Germany and the Netherlands extend conformity assessment timelines and elevate compliance costs that pass through to pricing structures. Buyers with validated sterilization infrastructure and polymer compounding capabilities command preferential procurement positioning, while secondary manufacturers face margin compression from dual-sourcing mandates and biocompatibility testing investments.
Pricing Analysis
Short lead-time premiums dominate catheter procurement economics, with United States integrated delivery networks paying contract premiums for 30-day delivery windows on cardiac and neurovascular devices while spot inventory clears at discounted rates through secondary distributors. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 10993 certification tier and FDA clearance pathway, with Class III PMA devices capturing substantial premiums over 510(k) equivalents. Cost compression in high-volume urinary catheter segments intensifies as thermoplastic polyurethane substitution economics squeeze silicone processor margins. Ambulatory surgical centers exhibit highest price sensitivity due to site-of-service reimbursement differentials, while tertiary academic medical centers prioritize device performance and sterilization assurance over per-unit cost.
Supply Chain Analysis
Polymer extrusion technician scarcity in Costa Rica and Malaysia constrains catheter manufacturing expansion despite favorable tax holiday regimes, as three-to-five-year apprenticeship pipelines cannot match demand from medical device special economic zones. Medical-grade polyurethane and Pebax resin allocations draw from German and Japanese chemical conglomerates, creating single-source vulnerability for Western manufacturers dependent on specialized thermoplastic formulations. Distribution runs through hospital procurement committees and group purchasing organizations in the United States, direct tender processes in German DRG frameworks, and joint venture distribution networks in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The catheter systems market sits in a material-transition phase as thermoplastic polyurethane displaces silicone across vascular access and electrophysiology applications, rewarding manufacturers with captive polymer compounding capabilities and punishing pure-play silicone processors.
For Market Incumbents: Anticipate EU MDR post-market surveillance infrastructure requirements by building clinical follow-up systems for legacy devices with extended implantation histories, and secure dual-source polymer supply agreements with German and Japanese resin producers to mitigate single-source vulnerability. Defensive consolidation of coating technology assets and navigation software capabilities will protect margin positioning against integrated system competitors. For New Entrants and Emerging Players: PMDA Sakigake designation in Japan opens a window for breakthrough neurovascular and electrophysiology systems seeking accelerated approval timelines, while NMPA localization requirements in China create partnership opportunities for Western technology holders lacking domestic manufacturing footprints. Target mechanical thrombectomy protocol expansion in United States stroke centers as the most penetrable segment, and pursue hospital system partnerships that bundle device procurement with procedure support services. For Investors and Strategic Acquirers: FDA 510(k) backlog fluctuations are the leading indicator that regulatory filing capacity will become a constraining asset class, signaling acquisition premiums for notified body relationships and regulatory affairs infrastructure. Long-term viability in this market centers on material science differentiation and procedural workflow integration rather than standalone device manufacturing scale. Monitor polymer supply concentration metrics as the critical inflection signal for margin compression risk across the value chain.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market access for moderate-risk vascular access devices in United States hospital networks. |
| EU MDR CE Marking Pathway | Notified body capacity in Germany determines competitive positioning for electrophysiology catheter portfolios. |
| Hospital System Partnership | Integrated delivery network contracts secure volume commitments and disintermediate traditional distribution channels. |
| Software Companion Development | Three-dimensional navigation integration commands premium pricing in electrophysiology lab capital equipment. |
| Reimbursement Strategy | Medicare outpatient prospective payment system alignment sustains device premium capture in interventional cardiology. |
Study Parameters
Multi-period observation of catheter procedure volumes, polymer resin allocations, and regulatory filing timelines anchored the trend analysis, supplemented by interviews with electrophysiology lab directors, hospital purchasing committee members, biomedical engineers, and group purchasing organization contracts managers. Secondary validation drew from FDA 510(k) and PMA filings, EU MDR notified body capacity reports, CMS Medicare reimbursement schedules, and Japanese PMDA Sakigake designations. Bottom-up demand modeling across clinical application segments triangulated with top-down market sizing from polymer consumption data and hospital procurement databases.
Segment-weighting approaches distributed value estimates across cardiac, neurovascular, vascular, and urinary catheter categories, with further stratification by delivery mode and end-use setting. Growth trajectories across the analysis window derived from procedure volume elasticity to aging demographics, reimbursement rate adjustments, and mechanical thrombectomy protocol expansion. Forecast inputs incorporated ISO 10993 biocompatibility testing duration assumptions, polymer supply concentration risk factors, and EU MDR technical documentation burden estimates.
Caveats apply where FDA 510(k) backlog fluctuations, EU MDR notified body capacity constraints, or polymer feedstock allocation disruptions could materially shift the outlook. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
China Diabetes Devices Market
Medical Devices
Global Blood Warmer Devices Market
Medical Devices
Cranial Stabilization Devices Market
Medical Devices
Global Transcatheter Pulmonary Valve Market
Medical Devices
Nano Healthcare Technology for Medical Equipment Market
Medical Devices
US C-Arms Market
Medical Devices
Consumer Grade EEG Device Market
Medical Devices
Radial Head Resection Implant Market
Medical Devices
Global Abdominal Surgical Robot Market
Medical Devices
Global Surgical Microscopes Market
Medical Devices
Asthma Device Market
Medical Devices
Wearable Cardioverter Defibrillators Market
Medical Devices
Smart Pill Boxes and Bottles Market
Medical Devices
Global Brain Monitoring Devices Market
Medical Devices
Breast Lesion Localization Device Market
Medical Devices
Auto-Transfusion Systems Market