
 Annuloplasty Rings Market | 2026-2036
Annuloplasty Rings Market Size, Share, and Industry Trends Forecast 2026-2036
Annuloplasty Rings Market Analysis
Aftermarket service revenue from valve repair training and surgical support is narrowing as manufacturers bundle education with device sales. Edwards Lifesciences anchors its position through surgeon certification programs that lock in hospital loyalty. Medtronic leverages extensive field clinical specialist networks to sustain implant utilization rates. Abbott Laboratories differentiates via adjustable ring technology that commands premium positioning in complex redo procedures.
Annuloplasty rings are implantable prosthetic devices that reinforce or reshape diseased heart valve annuli, typically fabricated from biocompatible polymers or metal alloys with fabric sewing cuffs to enable suture fixation by cardiac surgeons. Semi-rigid rings currently lead product type segmentation due to their balance of annular flexibility and durable remodeling force, while adjustable rings represent the fastest-growing category as surgeons demand intraoperative fine-tuning capability for complex anatomies. Polyester dominates material selection for its proven tissue integration and handling properties, though titanium-reinforced designs are gaining traction in high-risk patient cohorts seeking permanent structural support.
FDA premarket approval requirements and EMA Medical Device Regulation conformity assessments shape product development timelines and clinical trial investment for all manufacturers seeking transatlantic market access. The EU F-Gas Regulation indirectly affects sterilization process validation, while ISO 13485 quality management certification remains mandatory for supplier qualification by tier-one cardiac device firms. Stakeholders must monitor evolving CMS reimbursement decisions for transcatheter versus surgical valve repair, as coverage determinations will redirect hospital capital allocation and surgeon procedure preferences across integrated delivery networks.
Market Dynamics
Minimally invasive valve repair techniques are compressing hospital length-of-stay metrics and redirecting capital toward catheter-compatible annuloplasty platforms. This procedural shift is forcing manufacturers to revalidate ring designs for transcatheter delivery systems while maintaining surgical-grade durability.
Growth Catalysts
- EU Medical Device Regulation:MDR Article 10 clinical evaluation requirements are accelerating evidence-generation investments, which consolidates market access for well-capitalized firms with robust trial infrastructure.
- Japan's super-aged demographic:Patients over 75 now comprise over 30% of cardiac surgery volumes in Tokyo and Osaka medical centers, sustaining demand for durable repair solutions.
- Adjustable ring technology:Intraoperative sizing flexibility is displacing fixed-diameter implants in complex redo procedures where annular calcification limits preoperative planning accuracy.
Market Restraints
- Titanium supply concentration:Sponge production clusters in Kazakhstan and Ukraine create input volatility for reinforced ring substrates, pressuring COGS for premium implant lines.
- FDA PMA pathway duration:Class III cardiovascular device reviews now average 18-24 months, compressing effective patent life and extending capital lockup periods for novel ring geometries.
- Transcatheter valve replacement:TAVR platforms are capturing intermediate-risk patients who previously underwent surgical repair, narrowing the addressable population for annuloplasty in aortic indications.
Strategic Opportunities
- India's cardiac surgery infrastructure:Medanta, Narayana Health, and Apollo chains are expanding valve repair programs in tier-2 cities where penetration remains below 15% of metropolitan rates.
- CMS reimbursement expansion:Proposed coverage determinations for transcatheter mitral repair are training surgeon cohorts on annular anatomy, indirectly building surgical repair referral pipelines.
- Digital surgical planning:Preoperative CT modeling fused with 3D-printed sizing templates is hybridizing with conventional ring selection protocols in German university hospitals.
Industry Challenges
- ISO 13485 supplier qualification:Polyester fabric vendors face extended audit cycles as tier-one device firms tighten incoming material traceability requirements.
- Surgeon training pipeline:Declining median case volumes per graduating resident are compressing proficiency acquisition in open valve repair techniques.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Annuloplasty Rings Market |
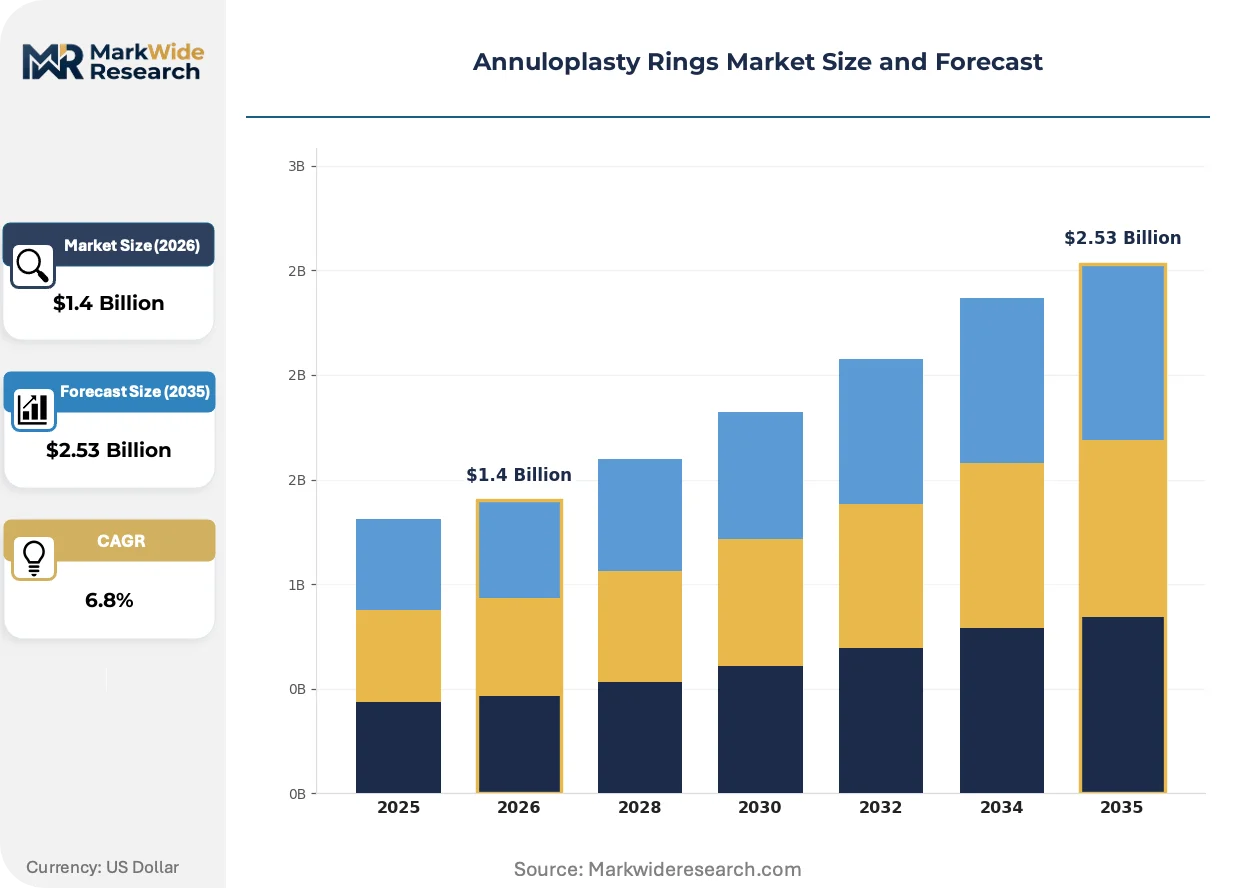
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Rings, Semi-rigid Rings, Rigid Rings, Adjustable Rings Material: Silicone, Polyester, Polypropylene, Titanium End User: Hospitals, Cardiac Clinics, Ambulatory Surgical Centers, Research Institutions Application: Mitral Valve Repair, Aortic Valve Repair, Tricuspid Valve Repair, Others |
| Companies Covered | Corcym, Biostable Science and Engineering, Edwards Lifesciences, Labcor, Braile Biomedica, Medtronic, Boston Scientific, Medtentia International, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Annuloplasty Rings Market Emerging Trajectories
Digital integration is reshaping how annuloplasty rings are sized, implanted, and monitored across the postoperative continuum. Three distinct vectors are compressing traditional workflows and creating new capability requirements for manufacturers.
Polyetheretherketone (PEEK) reinforced with continuous carbon fiber is hybridizing the structural properties of metallic and polymer rings. Cardiac surgeons in Munich and Boston academic centers are adopting these platforms for younger patients requiring lifelong implant durability. The material convergence is compressing the historical trade-off between radiopacity and MRI compatibility that constrained titanium-based designs.
The EU F-Gas Regulation is forcing sterilization process revalidation across ethylene oxide-dependent manufacturing lines. Contract sterilizers in Ireland and the Netherlands are investing in alternative modality capacity, which is extending validation timelines for ring manufacturers with single-source sterilization arrangements. Smaller device firms without captive sterilization assets face disproportionate compliance burdens.
Hospital purchasing committees are consolidating valve repair device contracts into single-source agreements that bundle rings, delivery systems, and training credits. Integrated delivery networks in Texas and Florida are replacing surgeon-specific preference cards with standardized formulary tiers. This concentration is visible most acutely in US markets where health system consolidation has reduced independent hospital purchasing autonomy.
Annuloplasty Rings Market Segmentation
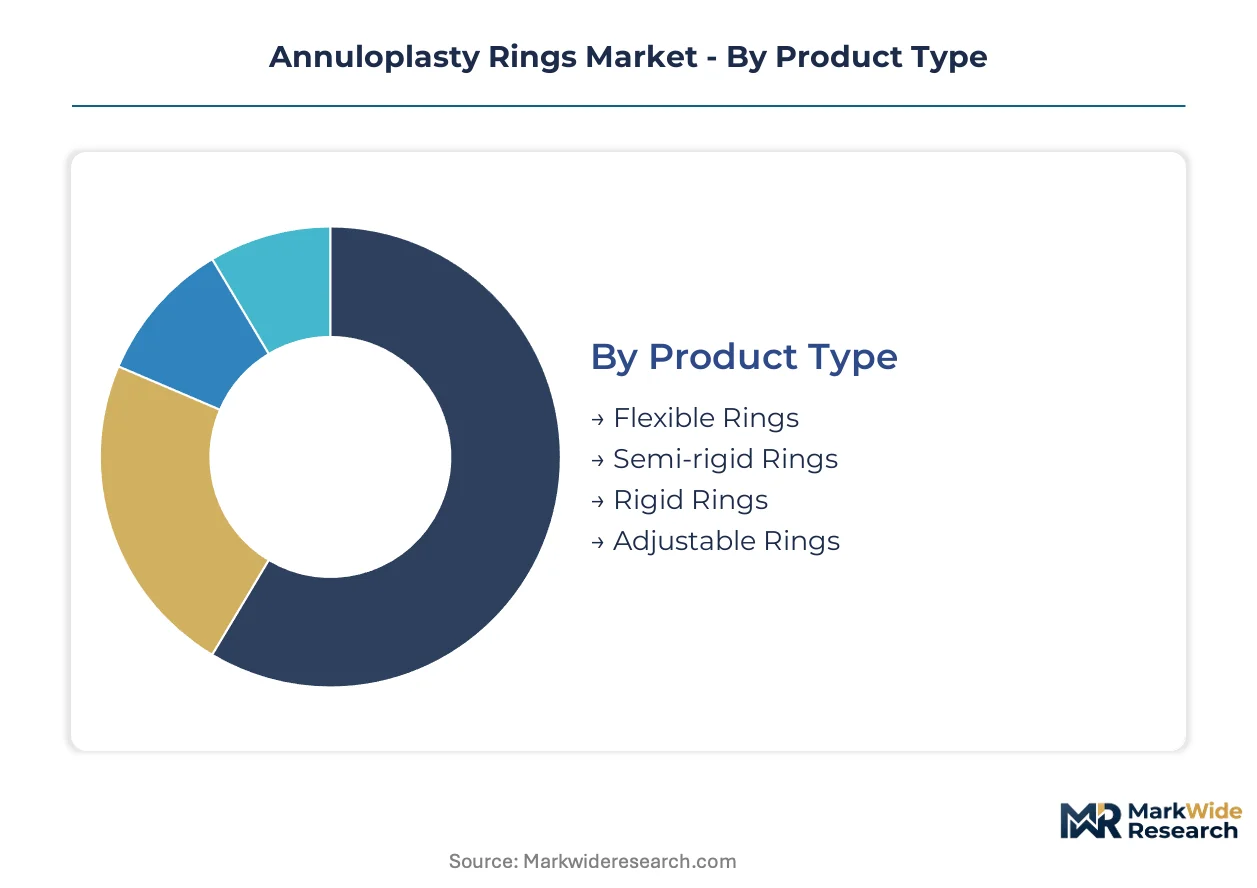
Annuloplasty ring segmentation reflects divergent surgical philosophies across repair complexity levels, material biocompatibility requirements, and care setting economics. Manufacturers configure product portfolios around these axes to capture volume in high-throughput hospital systems while defending premium positioning in specialized cardiac centers.
Product Type:
Surgeon preference spans the flexibility spectrum from pliable remodeling to rigid structural fixation.
- Semi-rigid Rings:Hybrid construction combines annular conformability with sufficient remodeling force to correct dilated valve geometries. Cardiac surgery departments in German university hospitals favor these platforms for their predictable handling characteristics across routine mitral repair volumes.
- Adjustable Rings:Intraoperative diameter modulation enables real-time optimization when preoperative imaging underestimates annular calcification. Complex redo procedures in Tokyo and Osaka medical centers are expanding adoption fastest as surgeons confront distorted anatomies.
- Flexible Rings:Complete annular pliability preserves native valve kinematics for younger patients with preserved tissue quality.
- Rigid Rings:Fixed structural support addresses severe annular dilation where flexible remodeling proves insufficient.
Established volume favors semi-rigid configurations; emerging adoption favors adjustable mechanisms.
Material:
Substrate selection trades off tissue integration speed, radiopacity, and MRI compatibility.
- Polyester:Woven fabric construction delivers proven tissue ingrowth and suture retention. US hospital purchasing committees specify polyester-based platforms as formulary standards due to decades of clinical surveillance data.
- Titanium:Reinforced substrates provide permanent structural support for high-risk patient cohorts with connective tissue disorders. Japanese regulatory pathways under PMDA have streamlined approval for titanium-reinforced designs targeting super-aged surgical populations.
- Silicone:Elastomeric cores enable flexible ring construction with controlled elastic recoil.
- Polypropylene:Monofilament structures resist creep deformation in rigid ring applications.
Polyester dominates current implant volumes; titanium-reinforced variants are climbing the fastest in premium segments.
End User:
Procedure location determines device specification, sterilization protocols, and training support requirements.
- Hospitals:Integrated cardiac surgery suites handle the majority of complex multivalve repairs requiring full cardiopulmonary bypass capability. US health system consolidation in Texas and Florida has concentrated purchasing authority within centralized supply chains.
- Cardiac Clinics:Specialized valve centers are expanding minimally invasive repair programs with dedicated surgeon teams. German outpatient cardiac surgery units under national DRG reimbursement frameworks are capturing intermediate-risk cases previously routed to academic medical centers.
- Ambulatory Surgical Centers:Limited penetration due to bypass infrastructure requirements; emerging for diagnostic catheterization with hybrid repair potential.
- Research Institutions:Preclinical and first-in-human trials drive demand for custom geometries and investigational materials.
Hospital systems command procurement scale; cardiac clinics are gaining share fastest in minimally invasive segments.
Application:
Valve-specific anatomical constraints dictate ring design parameters and sizing protocols.
- Mitral Valve Repair:Annuloplasty rings address functional regurgitation from annular dilation and leaflet prolapse. Japanese cardiac surgery registries report mitral repair volumes exceeding aortic procedures in patients over 75.
- Aortic Valve Repair:Subcommissural annuloplasty and root remodeling procedures require specialized ring geometries. German centers in Munich and Heidelberg are refining aortic repair techniques to preserve native valve tissue in younger patients.
- Tricuspid Valve Repair:Underserved anatomical segment with growing recognition of secondary tricuspid regurgitation impact.
- Others:Pulmonary valve and complex congenital repair applications represent niche volumes.
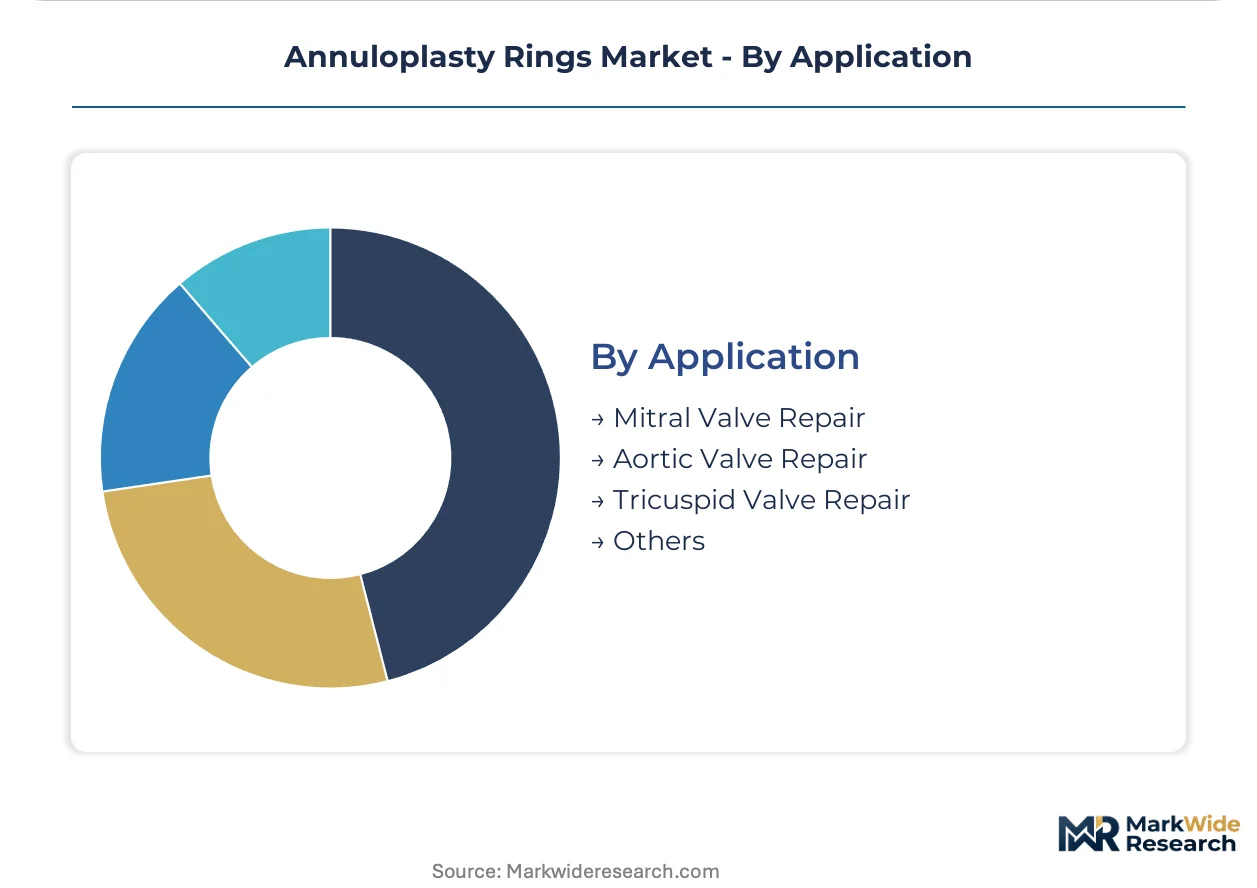
Mitral applications anchor current procedure volumes; aortic repair techniques are expanding fastest as surgeons pursue valve-sparing alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across cardiac surgery markets. German and Japanese health systems absorb premium device costs through established reimbursement frameworks. Indian and Brazilian markets demand value-engineered alternatives that compress manufacturer margins.
United States
Integrated delivery networks in Texas and Florida concentrate purchasing authority within centralized supply chains. FDA PMA pathway requirements for Class III cardiovascular devices extend validation timelines for novel ring geometries. The Cleveland Clinic and Mayo Clinic cardiac surgery departments anchor clinical evidence generation for transcatheter-compatible platforms.
Germany
University hospitals in Munich and Heidelberg refine aortic valve repair techniques to preserve native tissue in younger patients. EU Medical Device Regulation Article 10 clinical evaluation requirements accelerate evidence-generation investments for market access. The Bavarian cardiac surgery cluster generates procedural volume data that shapes European annuloplasty adoption patterns.
Japan
Patients over 75 now comprise over 30% of cardiac surgery volumes in Tokyo and Osaka medical centers. PMDA regulatory pathways have streamlined approval timelines for titanium-reinforced designs targeting super-aged surgical populations. The Kanto region's concentration of cardiac surgery residency programs sustains surgeon training pipelines for complex repair techniques.
India
Medanta, Narayana Health, and Apollo chains expand valve repair programs in tier-2 cities where penetration remains below 15% of metropolitan rates. CDSCO medical device registration requirements create compliance barriers for imported premium implants. The Delhi-NCR and Hyderabad clusters concentrate cardiac surgery infrastructure that trains regional surgeon cohorts.
Brazil
Public health system procurement through SUS channels prioritizes cost containment over device premium features. ANVISA medical device conformity assessment pathways extend market entry timelines for foreign manufacturers. The São Paulo and Rio de Janeiro cardiac surgery centers anchor private-sector demand for adjustable ring technologies.
Annuloplasty Rings Market Vendor Landscape
Capability concentration sits with specialized cardiovascular device firms; scale advantage sits with diversified medical technology conglomerates. The vendor base stratifies across three tiers: integrated cardiac surgery platforms with catheter-compatible portfolios, standalone annuloplasty specialists with surgeon training ecosystems, and regional fabricators serving price-sensitive emerging markets. Dominant competitive moves include strategic partnerships for sterilization capacity access and portfolio diversification into transcatheter delivery systems.
Within the diversified cardiovascular technology tier, Edwards Lifesciences and Medtronic occupy positions defined by extensive field clinical specialist networks and surgeon certification infrastructure. Abbott Laboratories exemplifies the premium-specialist archetype through adjustable ring technology positioning. Corcym represents the focused European manufacturer archetype with concentrated cardiac surgery device portfolios.
| Leading Market Players |
|---|
| Corcym |
| Biostable Science and Engineering |
| Edwards Lifesciences |
| Labcor |
| Braile Biomedica |
| Medtronic |
| Boston Scientific |
| Medtentia International |
| Abbott Laboratories |
| Others |
Supply Flow & Price Mechanics
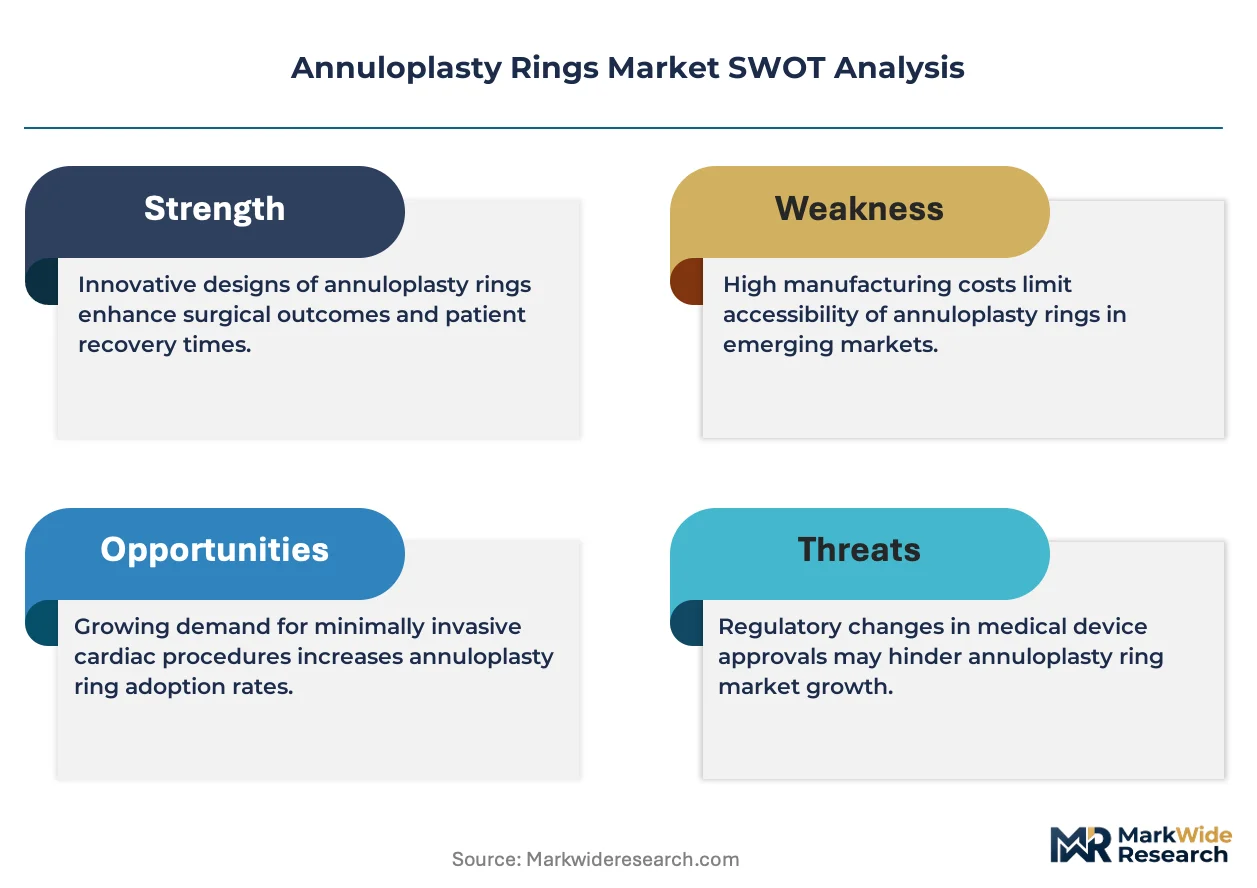
Titanium sponge concentration in Kazakhstan and Ukraine creates input volatility that compresses margin spreads between premium titanium-reinforced rings and standard polyester platforms while forcing manufacturers toward dual-source qualification strategies. This raw material chokepoint shapes both the three-tier pricing structure across premium, standard, and economy levels and the geographic distribution of sterilization and fabrication assets.
Pricing Analysis
Aftermarket service revenue from surgeon certification and procedural support drives lifetime value beyond the initial implant transaction. Three-tier pricing structure across premium, standard, and economy levels stratifies by material reinforcement grade and FDA PMA approval status, with titanium-reinforced designs commanding substantial premiums over polyester standards. Cost compression in economy tiers is intensifying because Indian and Brazilian procurement committees prioritize SUS and CDSCO-registered alternatives over premium features. Cardiac clinics in German outpatient settings exhibit lowest price sensitivity due to DRG reimbursement frameworks, while tier-2 Indian hospitals face acute budget constraints.
Supply Chain Analysis
Contract sterilization capacity concentrates in Ireland and the Netherlands among ethylene oxide-dependent providers serving tier-one cardiac device firms. Fabrication draws from the United States, Germany, and Japan for precision polymer molding and metal alloy processing, with polyester fabric weaving anchored in established textile manufacturing clusters. Single-source vulnerability pervades sterilization arrangements as smaller device firms lack captive assets. Distribution runs through integrated delivery network centralized supply chains in Texas and Florida, with GPO contracts consolidating hospital purchasing authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Surgeon training and certification programs represent a service-attach opportunity expanding faster than hardware revenue as manufacturers bundle education with device sales to lock in hospital loyalty. This recurring-revenue layer from procedural support and implant follow-up monitoring outpaces implant unit growth in established cardiac surgery markets.
For Market Incumbents: Entrench market position through backward integration into titanium sponge sourcing and captive sterilization capacity to insulate against Kazakhstan-Ukraine supply disruptions. Expand surgeon certification infrastructure in Tokyo and Osaka to defend against adjustable ring competitors targeting complex redo procedures. Prioritize ISO 13485 supplier audit programs to tighten material traceability and disqualify second-tier competitors. For New Entrants and Emerging Players: Establish a beachhead in India's tier-2 cities where valve repair penetration remains below 15% of metropolitan rates at Medanta and Narayana Health expansion sites. Target tricuspid valve repair as an underserved anatomical segment with limited incumbent focus. Pursue CDSCO registration pathways for value-engineered polyester platforms priced below premium import tiers. For Investors and Strategic Acquirers: EU MDR Article 10 clinical evaluation requirements reshape the acquisition landscape by elevating evidence-generation infrastructure as a scarce capability. Five-to-ten year viability favors targets with robust trial networks and PMA submission track records over pure technology plays. Watch CMS reimbursement determinations for transcatheter mitral repair as the signal indicating surgical repair referral pipeline strength.| Strategic Initiative | Industry Significance |
|---|---|
| Surgeon Certification Program Expansion | Locks hospital loyalty through Edwards Lifesciences-style training ecosystems that reduce switching. |
| Titanium Sponge Backward Integration | Insulates COGS from Kazakhstan-Ukraine concentration risk affecting reinforced ring substrates. |
| CE Marking Pathway Acceleration | Compresses EMDR Article 10 compliance timelines for transcatheter-compatible platform launches. |
| Hospital System Partnership | Secures formulary placement within Texas and Florida integrated delivery network tiers. |
| Reimbursement Strategy Development | Aligns CMS coverage determinations with surgeon training investments in annular anatomy. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with cardiac surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation through FDA PMA filings, EMA MDR submission databases, CMS Medicare reimbursement data, and hospital procurement records. Bottom-up implant volume modeling triangulated against top-down health system expenditure analysis across the projection horizon.
Forecast inputs span product type segmentation across semi-rigid, adjustable, flexible, and rigid rings; material tiers from polyester through titanium-reinforced designs; and end-user categories from integrated hospital systems to specialized cardiac clinics. CAGRs were derived from procedure volume elasticity to aging demographic penetration and surgical infrastructure expansion rates. The modeling framework incorporates PMDA approval timeline differentials and CDSCO registration barriers as regional access variables.
Macroeconomic conditions sit as an overlay; deviation in healthcare reimbursement rates, titanium commodity pricing, or EU F-Gas Regulation enforcement stringency would shift the trajectory. Forecasts reflect documented assumptions regarding procedure migration toward minimally invasive platforms and transcatheter valve replacement capture rates. Quarterly review of CMS coverage determinations, PMDA approval announcements, and titanium sponge spot pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
I.V. Fluid Warmer Market
Medical Devices
3D-Printed Maxillofacial Implants Market
Medical Devices
Ambulatory Aids Market
Medical Devices
Global Anesthesia Video Laryngoscope Market
Medical Devices
Phoropters Market
Medical Devices
Asia-Pacific Vaginal Slings Market
Medical Devices
Global Closed System Transfer Devices Market
Medical Devices
Global Brachytherapy Devices Market
Medical Devices
Middle East and Africa Refractive Surgery Devices Market
Medical Devices
US Bathroom and Toilet Assist Devices Market
Medical Devices
Venturi Mask Market
Medical Devices
Trial Prostheses Market
Medical Devices
Tattoo Removal Devices Market
Medical Devices
Global Medical Devices Market
Medical Devices
Posterior Chamber Lens Market
Medical Devices
Global Stabilometric Platform Market