
 Cryosurgery Devices Market | 2026-2036
Cryosurgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Cryosurgery Devices Market Outlook
Germany is narrowing its cryosurgery device supply gap through expanded precision manufacturing clusters in Baden-Württemberg. Medtronic leverages its integrated surgical ecosystem to sustain catheter-based cryoablation leadership across European hospital networks. Boston Scientific Corporation anchors its position through R&D intensity in cardiac cryotherapy applications. IceCure Medical specializes in percutaneous tumor cryoablation systems, competing on probe miniaturization and imaging compatibility.
Cryosurgery devices employ extreme cold—typically delivered via liquid nitrogen at minus 196 degrees Celsius or argon gas expansion—to destroy targeted tissue through rapid freeze-thaw cycles, with primary purpose spanning oncologic lesion ablation, dermatologic lesion removal, and cardiac arrhythmia correction. Cryoablation probes dominate procedural volume in tumor removal applications, while cryo-console units capture the largest margin pools due to capital equipment pricing and recurring gas cartridge revenue. Carbon dioxide technology leads in dermatology procedures for its portability and lower infrastructure requirements, whereas argon gas systems represent the fastest-growing segment in interventional oncology for their rapid cooling rates and precise ice ball control.
The FDA enforces 510(k) clearance pathways for cryosurgical instruments, while the EU Medical Device Regulation mandates clinical evidence for cryoablation systems marketed under CE marking, collectively elevating barriers for new entrants and favoring established quality management systems. ISO 13485 certification shapes supplier qualification across OEM procurement channels, particularly for probe assemblies requiring biocompatibility validation. Stakeholders must monitor evolving reimbursement coding for office-based cryosurgical procedures, as category shifts between inpatient and outpatient settings will determine addressable market expansion for device manufacturers and service providers alike.
Market Dynamics
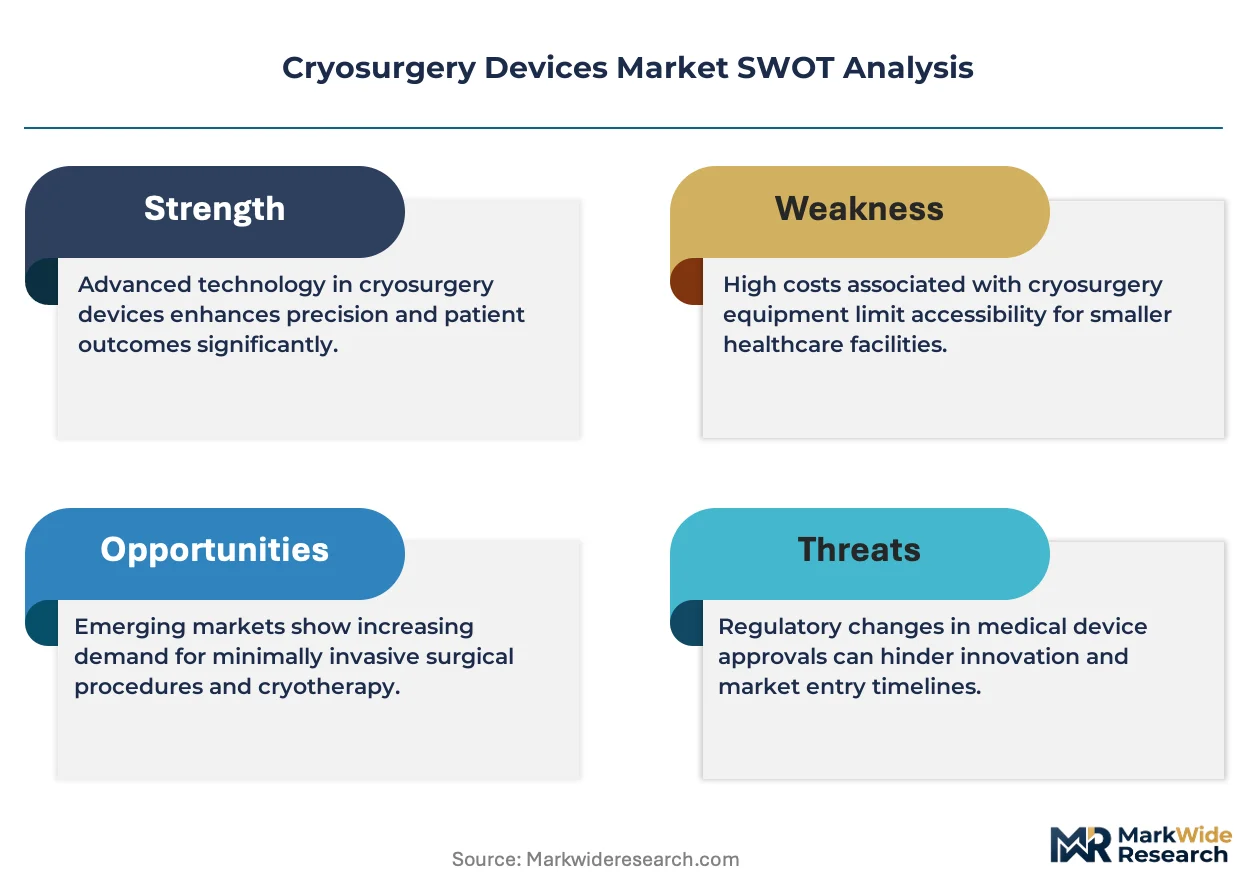
The cryosurgery device market is undergoing a structural transformation driven by the FDA's intensified scrutiny of temperature monitoring systems, compelling manufacturers to redesign probe architectures and validate real-time sensing capabilities before 510(k) clearance.
Growth Catalysts
- Oncology Procedure Migration:Tertiary hospitals in the United States are redirecting tumor ablation volumes from open surgery toward percutaneous cryoablation, spurring capital equipment replacement cycles.
- CE Marking Pathway Clarity:The EU Medical Device Regulation's crystallized clinical evidence requirements for Class IIb cryoablation systems are filtering out marginal competitors and concentrating procurement among validated suppliers.
- Argon Gas Infrastructure:Expanded liquid argon distribution networks across Germany and France are reducing operational friction for interventional radiology departments adopting rapid-cooling platforms.
Market Restraints
- Capital Equipment Intensity:Cryo-console units require substantial upfront investment and dedicated gas supply infrastructure, limiting penetration in ambulatory surgical centers.
- Supply Concentration Risk:Precision-manufactured probe assemblies depend on specialized nitinol suppliers concentrated in Baden-Württemberg, creating vulnerability to regional production disruptions.
- Reimbursement Coding Lag:CMS and private payers maintain inconsistent category definitions for office-based versus hospital-based cryosurgical procedures, compressing provider margins.
Strategic Opportunities
- Cardiac Cryotherapy Expansion:Electrophysiology labs are expanding cryoablation for atrial fibrillation treatment, creating demand for catheter systems with enhanced mapping integration.
- Portable CO₂ Platforms:Dermatology practices are adopting self-contained carbon dioxide devices for lesion removal, bypassing centralized gas supply dependencies.
- ISO 13485 Certification Arbitrage:Contract manufacturers with established quality management systems are capturing OEM probe assembly volumes from suppliers facing recertification delays.
Industry Challenges
- Biocompatibility Validation Bottlenecks:Probe materials must undergo extended cytotoxicity and sensitization testing under ISO 10993, extending product development timelines.
- Cross-Functional Talent Scarcity:The intersection of cryogenic engineering and interventional radiology expertise remains thinly staffed across device manufacturers and clinical training programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryosurgery Devices Market |
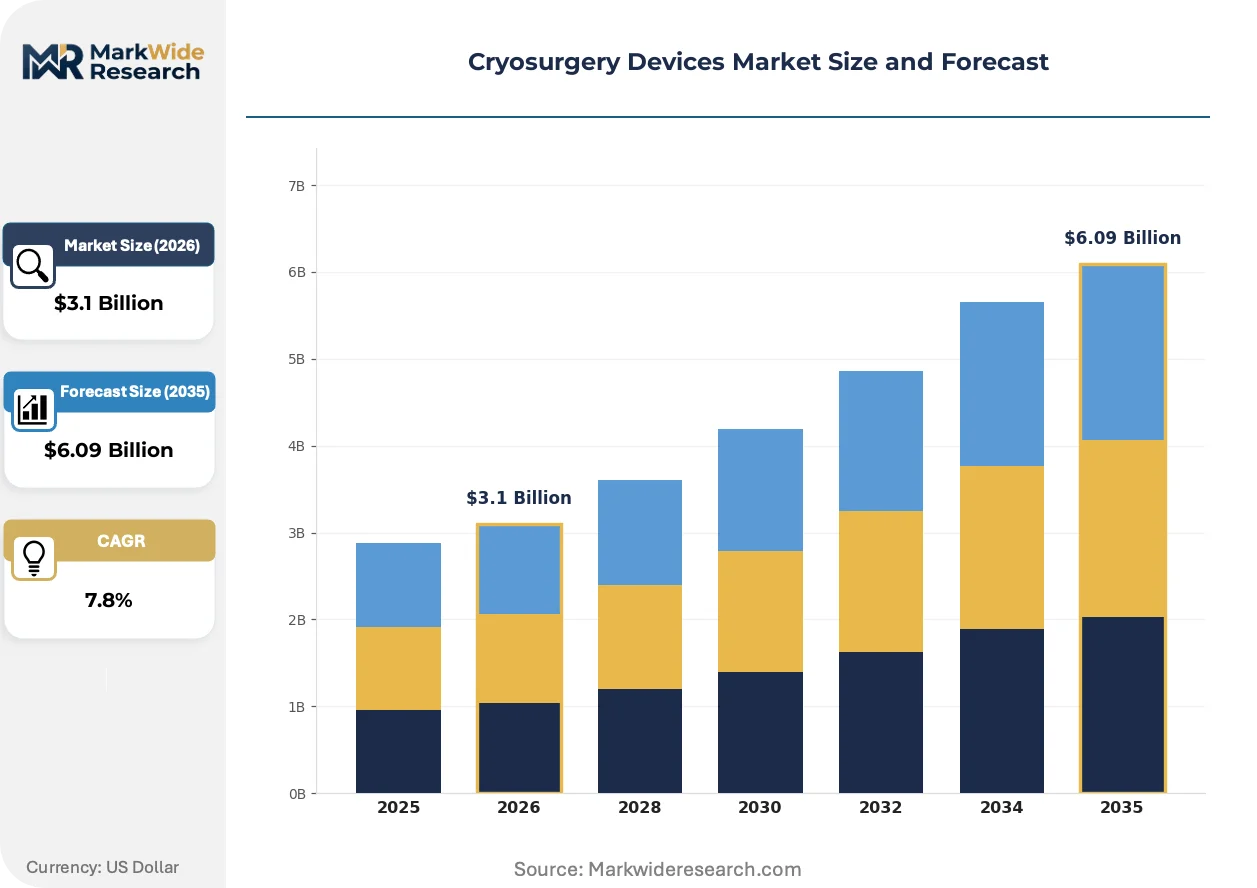
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.09 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Cryotherapy, Ice Packs, Cryoablation Probes, Cryo-Console Units End User: Hospitals, Specialty Clinics, Research Institutions, Outpatient Facilities Application: Tumor Removal, Dermatology Procedures, Pain Management, Organ Preservation Technology: Liquid Nitrogen, Carbon Dioxide, Argon Gas, Xenon Gas |
| Companies Covered | Medtronic, Boston Scientific Corporation, CooperSurgical, IceCure Medical, AtriCure, Brymill Cryogenic Systems, CryoConcepts, Galil Medical, Cortex Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryosurgery Devices Market Strategic Shifts
Probe miniaturization and imaging compatibility are converging to redefine procedural boundaries, with manufacturers racing to integrate real-time ice ball visualization into standard clinical workflows.
Thermocouple-integrated cryoablation probes are hybridizing with electromagnetic tracking systems to enable sub-millimeter positioning accuracy during tumor ablation. Interventional radiology departments at academic medical centers are piloting these platforms for hepatic and renal lesions. This convergence is compressing the learning curve for complex percutaneous procedures while raising performance expectations for basic probe configurations.
The EU F-Gas Regulation is restricting hydrofluorocarbon propellants in medical device applications, forcing manufacturers to reformulate gas expansion mechanisms or secure alternative refrigerant pathways. Industrial consequences include accelerated R&D spending on argon-based systems and supply chain requalification for gas cartridge suppliers. Cardiac cryotherapy applications face the steepest compliance burden given their reliance on precise pressure-temperature relationships.
Hospital procurement committees are consolidating cryosurgery device purchasing under centralized capital equipment frameworks, displacing the traditional model of department-level vendor relationships. Group purchasing organizations are capturing negotiating leverage for cryo-console acquisitions and long-term gas supply contracts. This concentration is most visible in United States integrated delivery networks, where standardization across multiple facilities has become a stated strategic priority.
Cryosurgery Devices Market Segmentation
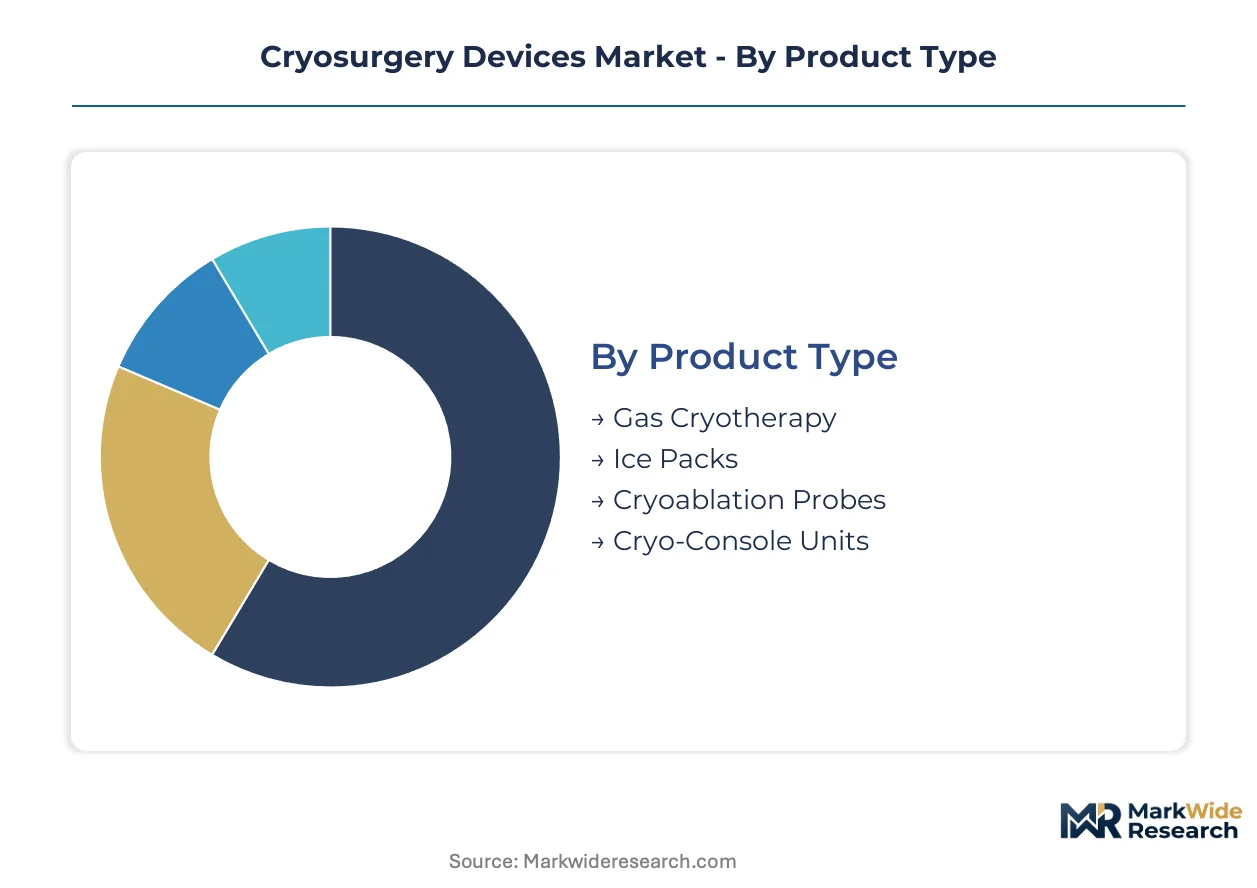
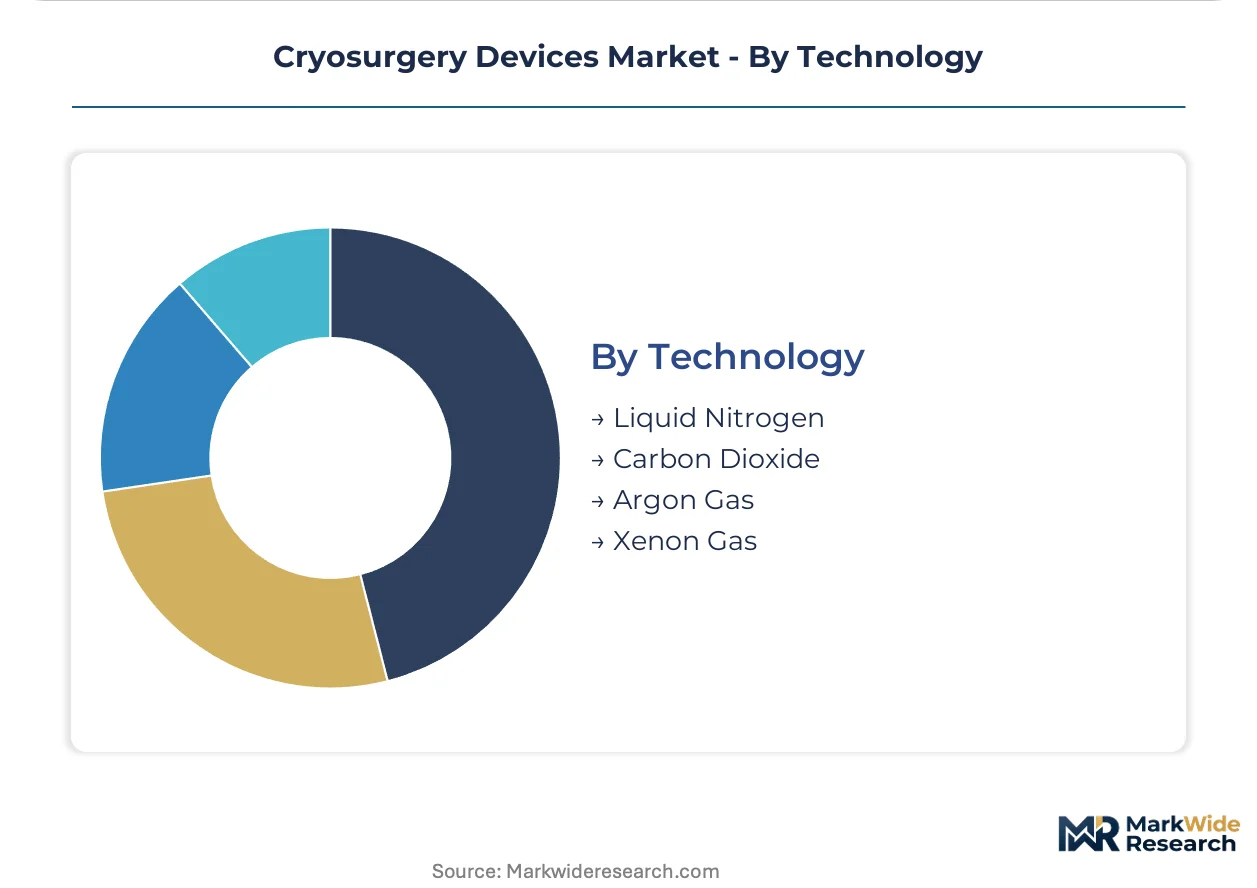
Segmentation in cryosurgery devices reveals divergent margin structures across product architectures and cooling modalities. Procurement patterns vary sharply between capital-intensive hospital systems and ambulatory settings with constrained infrastructure budgets.
Product Type:
Mature console platforms dominate installed base metrics while emerging probe technologies capture procedural volume expansion.
- Cryoablation Probes:Percutaneous delivery instruments manufactured from nitinol alloys with integrated thermocouple arrays for real-time temperature feedback. Tertiary oncology departments in the United States are standardizing on multi-probe configurations for hepatic and renal lesion treatment, driven by minimally invasive procedure migration and reduced recovery protocols.
- Cryo-Console Units:Capital equipment platforms managing gas flow regulation, pressure modulation, and freeze-thaw cycle programming. Procurement concentrates in German and French hospital networks expanding interventional radiology capabilities, constrained by extended replacement cycles and CE marking compliance costs for Class IIb systems.
- Gas Cryotherapy:Self-contained spray and contact devices for superficial lesion treatment.
- Ice Packs:Passive cooling systems for post-procedural pain management and superficial dermatologic applications.
Cryoablation probes handle the majority of throughput; cryo-console units are the fastest mover on share as replacement cycles accelerate in European markets.
End User:
Cost tier stratification separates high-infrastructure hospital systems from lean outpatient operators seeking portable alternatives.
- Hospitals:Integrated delivery networks with dedicated interventional radiology suites and captive gas supply infrastructure. Academic medical centers in the United States are consolidating vendor relationships under centralized capital frameworks, prioritizing systems with electromagnetic tracking compatibility.
- Outpatient Facilities:Ambulatory surgical centers and dermatology practices emphasizing procedure throughput and reduced overhead. German private clinics are adopting carbon dioxide platforms to bypass liquid argon distribution dependencies.
- Specialty Clinics:Focused operators in cardiology and oncology with procedure-specific equipment requirements.
- Research Institutions:Preclinical and clinical trial sites investigating expanded cryoablation indications.
Hospitals anchor equipment procurement volume; outpatient facilities are expanding most quickly as reimbursement coding stabilizes for office-based procedures.
Application:
Geographic concentration in oncology applications contrasts with dispersed demand patterns in dermatology and pain management.
- Tumor Removal:Percutaneous ablation of hepatic, renal, pulmonary, and prostate lesions using image-guided probe placement. United States tertiary hospitals are redirecting surgical volumes toward cryoablation, supported by established Category III CPT coding and commercial payer contracts.
- Dermatology Procedures:Superficial lesion destruction for actinic keratosis, warts, and benign growths. French and Italian dermatology practices favor portable carbon dioxide devices for office-based lesion removal.
- Pain Management:Cryoneurolysis for peripheral nerve ablation in chronic pain conditions.
- Organ Preservation:Experimental and clinical applications in transplant medicine and fertility preservation.
Tumor removal commands the dominant procedure share; dermatology procedures are gaining share fastest with carbon dioxide platform adoption.
Technology:
Supply concentration in gas distribution networks shapes technology adoption trajectories across regional markets.
- Argon Gas:Rapid-cooling systems achieving minus 160 degrees Celsius through Joule-Thomson expansion, enabling precise ice ball control for interventional oncology. Expanded liquid argon infrastructure across Germany and France is reducing operational friction for hospital-based adoption.
- Liquid Nitrogen:Minus 196 degrees Celsius cryogen with established supply chains and lower per-procedure costs. United States dermatology and veterinary applications maintain steady demand despite slower cooling rates versus argon alternatives.
- Carbon Dioxide:Minus 78 degrees Celsius systems prioritizing portability and reduced infrastructure requirements.
- Xenon Gas:Emerging cryogen with superior thermal properties and regulatory headwinds from EU F-Gas restrictions.
Liquid nitrogen maintains the broadest installed base; argon gas shows the steepest expansion trajectory with oncology procedure migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's liquid argon terminal throughput underwrites Germany's role as the primary cryogen logistics hub for European interventional oncology, while the Rhine corridor gas pipeline network distributes cooling agents to Baden-Württemberg precision manufacturing clusters.
United States
Tertiary hospitals in Houston and Boston redirect tumor ablation volumes toward percutaneous cryoablation, supported by stabilized Category III CPT reimbursement coding. The FDA intensifies 510(k) scrutiny of temperature monitoring systems, compelling probe redesigns. Academic medical centers in the Midwest consolidate vendor relationships under centralized capital equipment frameworks.
Germany
Expanded liquid argon distribution networks across Bavaria and North Rhine-Westphalia reduce operational friction for interventional radiology departments. The EU Medical Device Regulation's crystallized clinical evidence requirements filter marginal competitors from CE marking pathways. Precision manufacturing clusters in Baden-Württemberg narrow the national supply gap for nitinol probe assemblies.
France
Dermatology practices in Île-de-France and Provence-Alpes-Côte d'Azur adopt portable carbon dioxide devices to bypass centralized gas supply dependencies. The EU F-Gas Regulation restricts hydrofluorocarbon propellants, forcing equipment reformulation. Hospital procurement committees in Lyon consolidate cryo-console purchasing under regional capital frameworks.
Japan
Electrophysiology labs in Tokyo and Osaka expand cryoablation for atrial fibrillation treatment, creating catheter system demand with enhanced mapping integration. METI guidelines shape quality management expectations for imported probe assemblies. The Kansai region's medical device distribution networks prioritize systems with electromagnetic tracking compatibility.
United Kingdom
Private clinics in London and the Southeast adopt self-contained carbon dioxide platforms for office-based lesion removal. MHRA post-Brexit regulatory pathways diverge from EU MDR timelines, creating parallel compliance obligations. Research institutions in Cambridge and Oxford pilot thermocouple-integrated probes for hepatic lesion applications.
Cryosurgery Devices Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in probe and gas cartridge supply. The vendor base concentrates among diversified surgical device conglomerates with established 510(k) clearance track records and dedicated interventional radiology sales forces. Three archetypes dominate: integrated surgical ecosystem providers, cardiac-focused electrophysiology specialists, and percutaneous tumor ablation pure-plays. Competitive moves center on electromagnetic tracking compatibility certification and captive argon gas supply contracting.
Among diversified platform providers, Medtronic and Boston Scientific Corporation occupy positions anchoring the catheter-based cryoablation segment across European and North American hospital networks. IceCure Medical exemplifies the percutaneous tumor ablation specialist archetype, competing on probe miniaturization and imaging compatibility. These three entities represent distinct strategic postures: ecosystem breadth, cardiac application depth, and oncology procedure focus respectively.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| CooperSurgical |
| IceCure Medical |
| AtriCure |
| Brymill Cryogenic Systems |
| CryoConcepts |
| Galil Medical |
| Cortex Technology |
| Others |
Value Chain & Pricing Dynamics
The Port of Hamburg's liquid argon terminal throughput shapes cost dynamics across European interventional oncology supply chains, concentrating upstream pricing power among German gas distributors while forcing downstream differentiation between hospital-based console systems and ambulatory CO₂ platforms.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates electromagnetic-tracking-compatible probe systems from basic configurations and portable dermatology devices. Price differentiation hinges on ISO 13485 certification tier and after-sales service bundling, with academic medical centers showing lowest sensitivity and ambulatory surgical centers highest. Pricing pressure stems from group purchasing organization consolidation in United States integrated delivery networks, compressing margins on cryo-console capital equipment.
Supply Chain Analysis
Supplier-financing facilities extended by Baden-Württemberg precision manufacturers are stabilizing working capital for nitinol probe assembly producers facing CE marking compliance delays. Geographic supply concentrates in Germany, France, and United States, with raw material dependencies on liquid argon, nitinol alloys, and thermocouple sensors. Single-source vulnerability runs through specialized nitinol suppliers concentrated in southwestern Germany. Distribution runs through group purchasing organizations and regional hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as procedure migration from open surgery to percutaneous cryoablation creates specialty niches for probe miniaturization and imaging-integrated platforms.
For Market Incumbents: Entrench electromagnetic tracking compatibility certification across probe portfolios to defend against emerging catheter-based electrophysiology specialists. Deepen backward integration into nitinol supply through captive manufacturing partnerships in Baden-Württemberg precision clusters. Prioritize ISO 13485 recertification investment ahead of EU MDR audit waves. For New Entrants and Emerging Players: Establish a beachhead in portable carbon dioxide dermatology platforms where gas infrastructure dependencies are lowest and reimbursement coding for office-based procedures is stabilizing. Target French and Italian private clinics with self-contained lesion removal systems. Pursue direct-to-practice distribution bypassing consolidated hospital procurement frameworks. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified surgical device conglomerates seeking to divest non-core cryoablation assets amid portfolio rationalization. Five-to-ten-year viability favors percutaneous tumor ablation pure-plays with FDA 510(k) clearance track records and installed base expansion potential. Monitor FDA guidance finalization on temperature monitoring requirements as inflection indicator for probe redesign capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Temperature monitoring validation requirements are compressing clearance timelines for redesigned probe architectures. |
| CE Marking Pathway Investment | EU MDR clinical evidence mandates filter marginal competitors from Class IIb cryoablation system markets. |
| Hospital System Partnership | Academic medical centers in Houston and Boston consolidate vendor relationships under centralized capital frameworks. |
| Software Companion Development | Real-time ice ball visualization integration raises performance expectations for basic probe configurations. |
| Reimbursement Strategy | Category III CPT coding stabilization across commercial payers anchors United States procedure volume expansion. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interviews with interventional radiologists, hospital purchasing committee members, biomedical engineers, and group purchasing organization contracts managers. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body documentation, CMS Medicare reimbursement filings, and hospital procurement transaction records. Bottom-up equipment installation tracking and top-down gas supply volume analysis were triangulated.
Calibration against historical cryo-console replacement cycles and probe shipment data anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, cooling modality, end-user infrastructure tier, application specialty, and regional regulatory cluster. CAGRs were derived from procedure volume migration patterns and capital equipment replacement elasticity. Industry-specific forecast inputs incorporated liquid argon terminal throughput and nitinol alloy spot pricing dynamics.
Sensitivities concentrate around FDA guidance finalization timelines, EU F-Gas Regulation enforcement intensity, and reimbursement coding category shifts between inpatient and outpatient settings. Forecasts embody assumptions regarding continued procedure migration toward minimally invasive tumor ablation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Electrosurgery Generator Market
Medical Devices
Epilepsy Treatment Devices Market
Medical Devices
Capsulorhexis Forceps Market
Medical Devices
France Ophthalmic Devices Market
Medical Devices
Global Nebuliser Market
Medical Devices
Air Oxygen Blender Market
Medical Devices
3D Surgical Microscope Systems Market
Medical Devices
Veterinary Stereotactic Radiosurgery System Market
Medical Devices
Global Surgical Power Tools Market
Medical Devices
Smart Mask Market
Medical Devices
Lactate Meter Market
Medical Devices
AI-enabled Medical Devices Market
Medical Devices
Global 3D Printed Surgical Models Market
Medical Devices
Wearable Artificial Kidney Market
Medical Devices
North America Ultrasound Probe Disinfection Market
Medical Devices
Intubation Accessories Market