
 Veterinary Endotracheal Tubes Market | 2026-2036
Veterinary Endotracheal Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Endotracheal Tubes Market Analytics
Silicone is hardening its position as the preferred material for premium veterinary endotracheal tubes, displacing PVC in high-value surgical applications where biocompatibility and repeated sterilization cycles matter. Medtronic leverages its human medical device heritage to anchor product development pipelines that cross over into veterinary specifications. B. Braun Vet Care sustains manufacturing scale across European production facilities, while Jorgensen Laboratories specializes in distribution depth through independent veterinary clinics across North America.
Veterinary endotracheal tubes are hollow cylindrical devices inserted into the trachea to maintain patent airways and deliver inhalant anesthetics or oxygen during surgical and emergency procedures, typically manufactured with radiopaque lines and Murphy eyes to verify placement and prevent occlusion. The cuffed product configuration dominates revenue contribution because inflation mechanisms command premium pricing in anesthesia workflows, while silicone material segments capture expanding margin pools as referral practices upgrade from disposable PVC to sterilizable alternatives. Emergency care applications are growing fastest as trauma and critical care units expand within university veterinary medical centers.
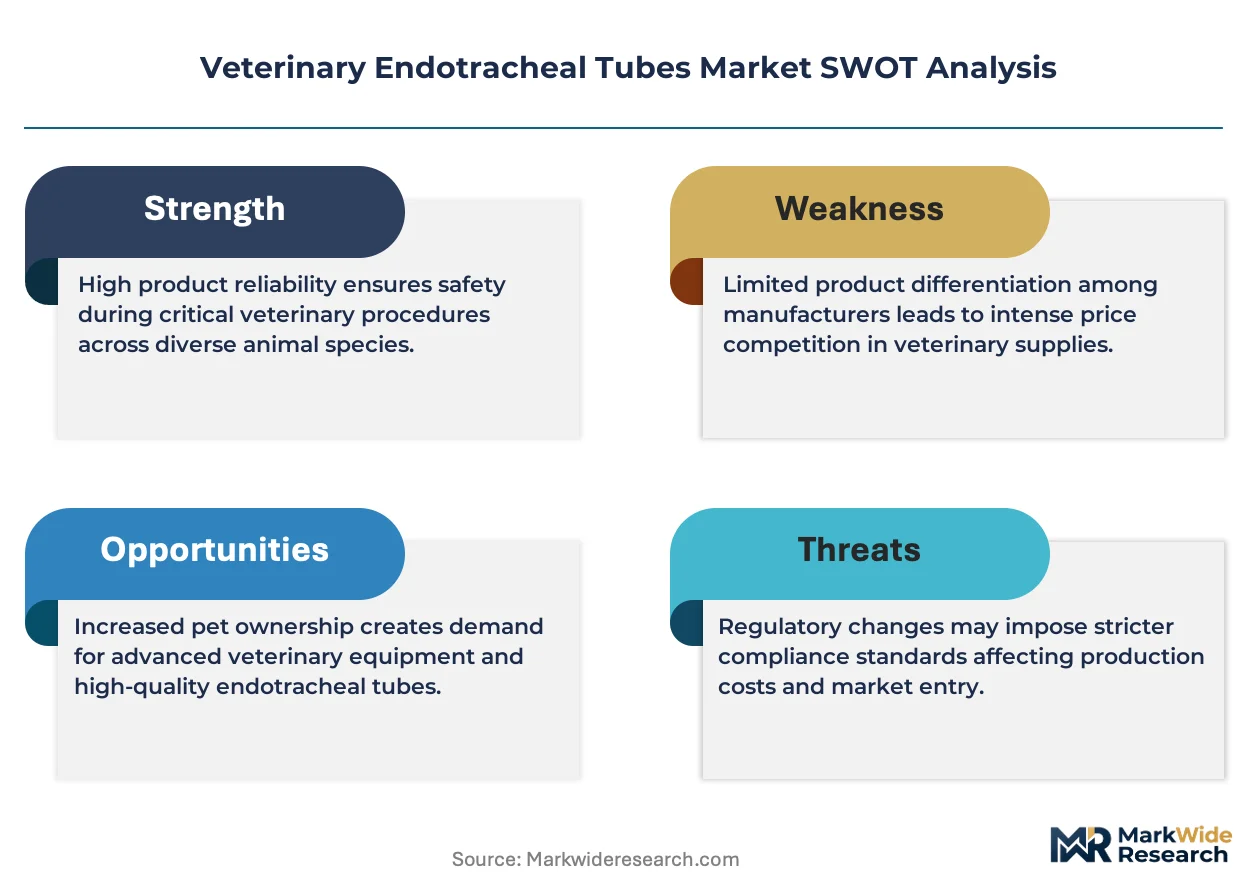
FDA Center for Veterinary Medicine oversight intersects with EU MDR requirements and ISO 10993 biocompatibility standards to define material acceptance criteria and quality system expectations for manufacturers seeking multi-regional market access. These frameworks elevate compliance costs for new entrants while rewarding incumbent suppliers with established regulatory dossiers and notified body relationships. Stakeholders must monitor how FDA guidance on reprocessed single-use devices evolves relative to veterinary exemptions, as this boundary condition will determine whether silicone reusable tubes gain share against disposables in cost-sensitive practice settings.
Market Dynamics
Silicone sterilizable tubes are compressing replacement cycles in referral practices while FDA single-use reprocessing guidance creates material selection friction across procurement workflows.
Growth Catalysts
- EU MDR material compliance mandates:Biocompatibility testing requirements under ISO 10993 are elevating silicone adoption in European companion animal hospitals seeking notified body certification.
- University veterinary medical center expansion:Trauma and critical care unit buildouts across tertiary referral institutions are accelerating cuffed tube consumption in emergency anesthesia workflows.
- North American specialty referral clustering:Concentration of board-certified veterinary anesthesiologists in metropolitan corridor practices is driving premium product specification.
Market Restraints
- Medical-grade silicone supply concentration:Raw material sourcing dependence on specialized elastomer suppliers creates input cost volatility and allocation risk during demand surges.
- FDA Center for Veterinary Medicine oversight intersection:Cross-jurisdictional compliance with human medical device standards elevates documentation burdens without proportional market scale.
- Disposable PVC substitution threat:Cost-sensitive general practice settings retain single-use polymer tubes despite inferior sterilization tolerance.
Strategic Opportunities
- German specialty clinic densification:Underserved secondary cities within the federal veterinary referral network present distribution whitespace for sterilizable product lines.
- Telemedicine-integrated anesthesia consultation:Remote perioperative monitoring adoption creates bundled device-service procurement channels linking tube selection to platform contracts.
- United States tax-advantaged equipment depreciation:Section 179 deduction structures incentivize capital equipment purchases of reusable silicone systems over disposable alternatives.
Industry Challenges
- Veterinary anesthesiologist workforce scarcity:Limited residency program output constrains sophisticated tube utilization in expanding practice settings.
- Legacy practice management system integration:Inventory tracking software incompatibility complicates sterilization cycle documentation for regulatory audit trails.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Endotracheal Tubes Market |
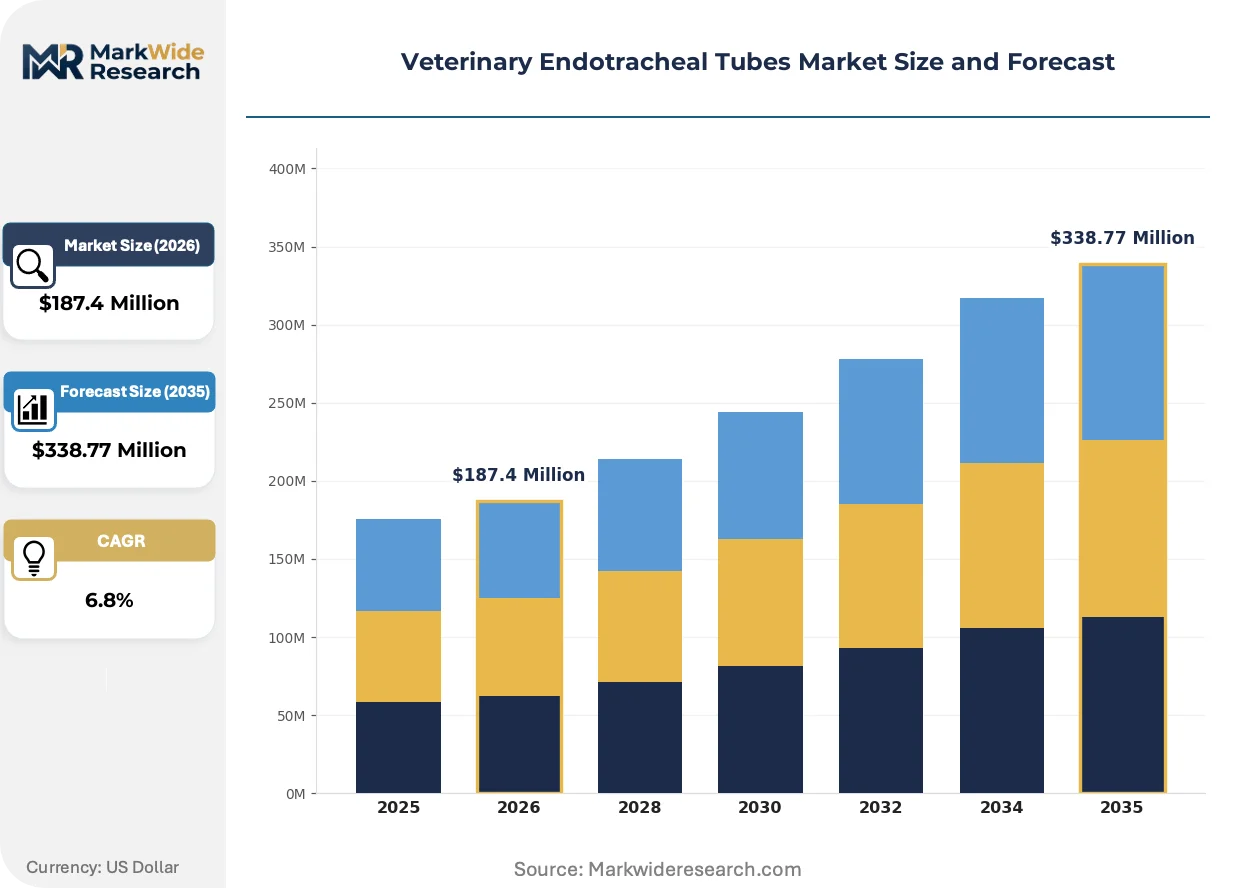
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Murphy, Magill, Cole, Cuffed Material: PVC, Silicone, Rubber, Latex Size: Small, Medium, Large, Extra Large Application: Emergency Care, Anesthesia, Surgery, Diagnostic Procedures |
| Companies Covered | Medtronic, B. Braun Vet Care, Conduct Science, Harvard Apparatus, Intriquip Instruments, Inc., Jorgensen Laboratories, RWD Life Science Co., Ltd., Vetamac, Inc., Supera Anesthesia Innovations, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Endotracheal Tubes Market Evolving Landscape
Material science advances and regulatory boundary-setting are compressing product lifecycles while reshaping procurement criteria across veterinary anesthesia departments.
Silicone formulation technology with platinum-cured elastomer matrices is decentralizing manufacturing quality control from centralized OEM facilities to qualified veterinary clinic sterilization departments. Academic referral centers with in-house biomedical engineering capacity are validating local reprocessing protocols that bypass single-use disposable economics. This capability diffusion is fragmenting supplier service revenue streams while elevating clinic capital equipment requirements.
EU MDR Article 10 general safety and performance requirements are mandating clinical evidence documentation for legacy tube designs previously grandfathered under withdrawn directives. Notified body capacity constraints are extending conformity assessment timelines for modified product submissions. German and French veterinary device distributors are consolidating supplier portfolios to reduce regulatory dossier maintenance burdens.
Consolidated procurement through veterinary group purchasing organizations is compressing individual practice autonomy in material specification. Independent clinic acquisition by corporate platforms standardizes device selection across multi-site anesthesia departments. This concentration is most visible in United States metropolitan markets where platform ownership exceeds forty percent of small animal practice volume.
Veterinary Endotracheal Tubes Market Segmentation
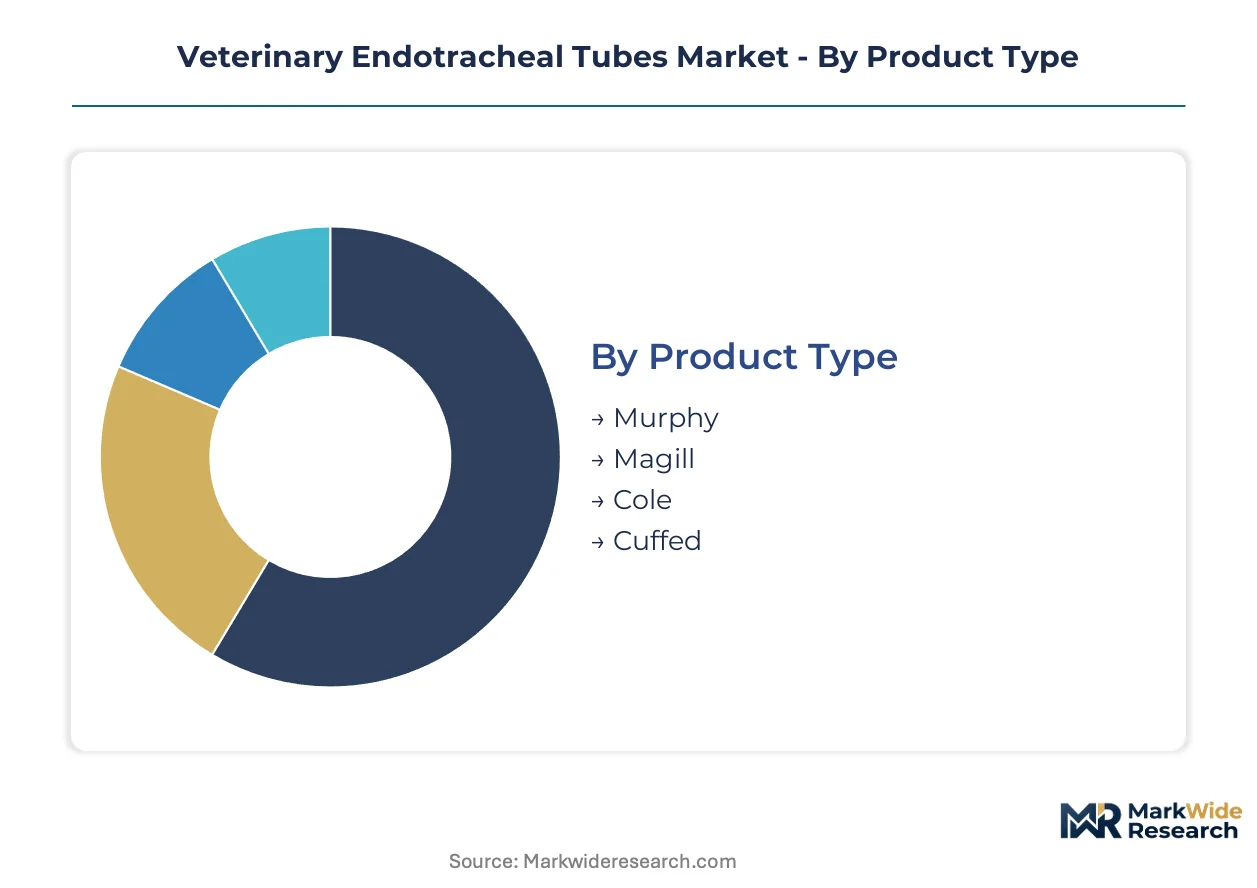
Veterinary endotracheal tube segmentation reflects divergent clinical workflows across companion animal hospitals, emergency trauma centers, and specialty referral practices. Procurement patterns split sharply between high-volume disposable consumption in general practice and capital-intensive reusable systems in university medical centers.
Product Type:
Volume concentration favors standard designs with universal airway compatibility, while premium configurations capture margin in controlled anesthesia environments requiring precise cuff pressure management.
- Cuffed:Inflatable sealing mechanisms enable positive pressure ventilation and protect against aspiration during prolonged procedures. Demand clusters in United States metropolitan referral centers where board-certified anesthesiologists mandate controlled airway management. Cuffed configurations command procurement priority in university veterinary medical center expansion projects.
- Murphy:Distal side-eye aperture prevents complete occlusion against the tracheal wall during positioning shifts. Murphy tubes dominate emergency care workflows in German and French specialty clinics where rapid intubation under visualization constraints requires fail-safe patency. ISO 10993 biocompatibility compliance elevates material specification in EU MDR jurisdictions.
- Magill:Curved design with beveled tip optimizes orotracheal insertion in feline and small canine patients. Magill tubes retain penetration in United Kingdom general practice settings with legacy anesthesia machine configurations.
- Cole:Tapered construction with shoulder stop prevents bronchial intubation in neonatal and exotic species. Cole specifications concentrate in avian and exotic animal referral centers with dedicated anesthesia protocols.
Mature deployment sits with Murphy and Magill designs in established general practice. Newer deployment is concentrated in cuffed configurations across expanding university trauma units.
Material:
Cost tier stratification separates single-use polymer economics from sterilizable elastomer capital investments, with regulatory compliance thresholds determining viable procurement pathways.
- Silicone:Platinum-cured elastomer matrices withstand repeated autoclave cycles without degradation, enabling lifecycle economics that offset higher acquisition cost. Silicone adoption accelerates in United States specialty practices leveraging Section 179 equipment depreciation structures. EU MDR notified body certification requirements favor silicone documentation portfolios.
- PVC:Medical-grade polymer delivers unit economics compatible with high-throughput general practice workflows. PVC retains dominance in cost-sensitive independent clinics across North American secondary markets where disposable protocols minimize sterilization infrastructure investment.
- Rubber:Red rubber formulations persist in legacy equipment compatibility scenarios with dated anesthesia circuit connectors. Rubber maintains residual presence in developing veterinary markets with limited silicone supply chain access.
- Latex:Natural rubber elastomer faces declining utilization due to hypersensitivity documentation requirements under ISO 10993 sensitization testing protocols. Latex procurement concentrates in price-driven emerging markets with relaxed biocompatibility enforcement.
Material procurement is shifting toward silicone in referral-tier practices with in-house sterilization capacity. PVC retains volume leadership in corporate-owned platform clinics with centralized supply contracts.
Size:
Patient weight distribution across companion animal populations creates demand concentration in mid-range specifications, with extreme sizes capturing premium positioning in specialized exotic and large breed applications.
- Medium:Internal diameters compatible with 10-25 kg canine patients match the modal weight distribution in United States small animal practice. Medium tubes anchor procurement volume in German companion animal hospitals serving mixed-breed urban populations.
- Large:Specifications for 25-40 kg patients align with retriever and shepherd breed prevalence in North American suburban markets. Large sizes command inventory priority in emergency care settings managing trauma cases without breed-specific advance knowledge.
- Small:Feline and toy breed dimensions require reinforced construction to prevent kinking during positioning. Small tube utilization concentrates in feline-exclusive practices and urban markets with high companion animal density.
- Extra Large:Giant breed and equine specifications serve niche referral centers with exotic animal capacity. Extra large procurement depends on specialized distributor relationships with limited stock-keeping unit breadth.
Size specification standardization is accelerating through corporate practice platform consolidation. Independent clinic inventory autonomy persists in university-adjacent referral centers with diverse caseload requirements.
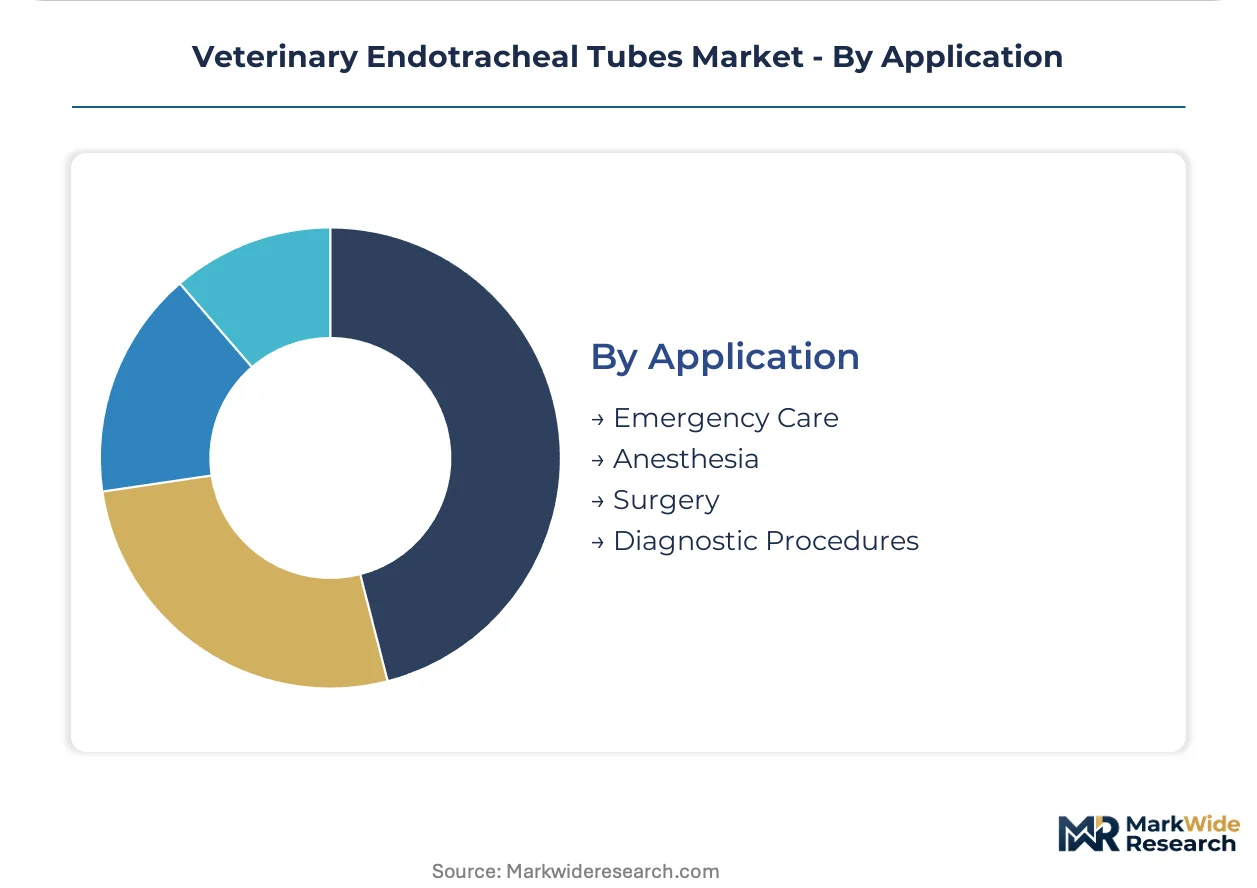
Application:
Clinical setting determines performance requirements, with emergency workflows demanding rapid deployment reliability and elective surgery prioritizing precision control features.
- Emergency Care:Trauma and critical care intubation requires visualization-compatible designs with rapid insertion characteristics. Emergency applications are climbing the fastest as university veterinary medical centers expand 24-hour critical care units across United States metropolitan corridors.
- Anesthesia:Inhalant delivery workflows mandate cuff integrity for scavenging system efficiency and personnel safety. Anesthesia departments in French and German specialty clinics drive specification for integrated pressure monitoring ports.
- Surgery:Procedural duration compatibility and positional stability requirements elevate material tolerance specifications. Surgery applications concentrate in orthopedic and soft tissue referral centers with extended anesthetic protocols.
- Diagnostic Procedures:Brief airway management for imaging and endoscopic examination favors low-profile designs minimizing patient stress. Diagnostic utilization clusters in United States academic institutions with advanced imaging infrastructure.
Application demand is concentrating in emergency care as trauma unit buildouts reshape university hospital capital allocation. Elective surgery specifications retain margin contribution through premium material conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States specialty veterinary referral centers concentrate demand for cuffed silicone tubes, while German university hospitals anchor European procurement volumes. Companion animal hospital expansion in metropolitan corridors drives regional performance disparities.
United States
Board-certified veterinary anesthesiologist clustering in metropolitan corridor practices elevates premium product specification. FDA Center for Veterinary Medicine oversight intersects with human medical device standards, elevating documentation burdens for cross-over suppliers. The Boston-Cambridge corridor anchors academic referral center density with expanding trauma unit buildouts.
Germany
Federal veterinary referral network densification in secondary cities creates distribution whitespace for sterilizable product lines. EU MDR notified body certification requirements favor silicone documentation portfolios under ISO 10993 biocompatibility mandates. The Munich-Stuttgart corridor concentrates specialty clinic infrastructure with university-adjacent referral capacity.
United Kingdom
Legacy anesthesia machine configurations in general practice sustain Magill tube penetration despite material upgrade trends. Medicines and Healthcare products Regulatory Agency alignment with EU MDR timelines compresses conformity assessment windows. Greater London veterinary corporate platforms standardize procurement across multi-site anesthesia departments.
France
French specialty clinics drive specification for integrated pressure monitoring ports in cuffed configurations. ANSM oversight of veterinary medical devices elevates quality system expectations for notified body submissions. The Lyon-Grenoble corridor clusters exotic animal referral centers with dedicated Cole tube protocols.
Japan
PMDA regulatory frameworks for veterinary devices imported from human medical standards create compliance cost barriers for new entrants. Metropolitan Tokyo veterinary medical centers expand 24-hour critical care units with emergency intubation workflows. Osaka-Kobe specialty practices anchor Kansai region silicone adoption through academic hospital affiliation.
Veterinary Endotracheal Tubes Market Competitive Landscape
Portfolio diversification dominates the current landscape as suppliers navigate material compliance thresholds and procurement channel consolidation. The vendor base concentrates around three strategic archetypes: diversified medical device conglomerates with veterinary cross-over pipelines, veterinary-exclusive specialists with distribution depth, and regional fabricators serving price-sensitive general practice. M&A activity and strategic partnerships represent the dominant competitive moves, with corporate veterinary platform acquisition driving standardization mandates.
Among diversified medical device suppliers, Medtronic and B. Braun Vet Care exemplify the conglomerate archetype leveraging human medical heritage for veterinary specification pipelines. Jorgensen Laboratories occupies a position within the veterinary-exclusive distribution tier, anchoring independent clinic penetration across North American secondary markets. RWD Life Science Co., Ltd. represents the Asia-Pacific regional specialist segment with manufacturing scale advantages.
| Leading Market Players |
|---|
| Medtronic |
| B. Braun Vet Care |
| Conduct Science |
| Harvard Apparatus |
| Intriquip Instruments, Inc. |
| Jorgensen Laboratories |
| RWD Life Science Co., Ltd. |
| Vetamac, Inc. |
| Supera Anesthesia Innovations |
| Others |
Value Network & Pricing Analysis
Platinum-cured silicone formulation advances are simultaneously elevating material compliance costs and concentrating manufacturing capability among notified body-certified European suppliers, compressing margin pools for non-compliant fabricators while rewarding incumbent OEMs with established ISO 10993 documentation portfolios.
Pricing Analysis
Volume concentration in disposable PVC tubes competes with margin capture in sterilizable silicone configurations. Three-tier pricing structure across premium silicone, standard PVC, and economy rubber levels reflects certification grade differentiation under FDA and EU MDR frameworks. Cost compression in the PVC tier intensifies because corporate veterinary platforms negotiate centralized supply contracts. General practice settings exhibit highest price sensitivity, while university referral centers prioritize lifecycle economics over unit acquisition cost.
Supply Chain Analysis
ISO 10993 biocompatibility certification and EU MDR notified body qualification gate access to European and North American procurement channels. Medical-grade silicone sourcing centers on Germany, the United States, and Japan, with platinum-cured elastomer production drawing from specialized chemical suppliers. Raw material dependencies include platinum catalysts, high-purity silica, and medical-grade polymer resins. Single-source vulnerability concentrates in platinum catalyst supply. Distribution runs through veterinary group purchasing organizations and independent specialty distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR Article 10 clinical evidence requirements function as a cost-of-compliance moat, elevating capital barriers for new entrants while entrenching incumbent suppliers with grandfathered regulatory dossiers and established notified body relationships.
For Market Incumbents: To counter corporate veterinary platform procurement consolidation, deepen backward integration into platinum-cured silicone compounding and secure dedicated notified body capacity for accelerated conformity assessments. Prioritize sterilizable product line capacity expansion in Germany to capture federal veterinary referral network densification. For New Entrants and Emerging Players: Begin with underserved secondary cities in the German federal veterinary referral network where sterilizable silicone tube penetration remains below metropolitan corridor levels. Target independent specialty clinics with legacy practice management systems requiring inventory tracking software integration. Pursue telemedicine-integrated anesthesia consultation platforms as bundled device-service procurement channels. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified medical device conglomerates seeking veterinary cross-over pipelines. Five-to-ten year viability hinges on EU MDR compliance cost absorption capability and silicone supply chain anchoring. Target acquisition archetype: veterinary-exclusive distributors with independent clinic relationships in North American secondary markets. Monitor FDA guidance evolution on reprocessed single-use devices as inflection indicator for reusable silicone tube share expansion against disposables.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Certification | Secures market access across German and French specialty clinic procurement channels. |
| Platinum-Cured Silicone Compounding Integration | Captures margin pool from medical-grade elastomer supply concentration. |
| Telemedicine Platform Partnership | Creates bundled anesthesia consultation and device procurement revenue streams. |
| Independent Clinic Distribution Acquisition | Penetrates North American secondary markets outside corporate platform consolidation. |
| Section 179 Depreciation-Eligible Product Development | Aligns reusable silicone system economics with United States tax-advantaged equipment purchasing. |
Research Methodology
Regulatory filings, veterinary medical center procurement databases, and ISO 10993 biocompatibility standards documentation formed the secondary backbone, cross-referenced with primary interviews with board-certified veterinary anesthesiologists, hospital purchasing committee members, biomedical engineering directors, and group purchasing organization contracts managers. Bottom-up and top-down triangulation validated segment-level volume estimates against supplier production capacity and end-use consumption patterns.
Bottom-up modeling anchored projections in procedure volume extrapolation from university veterinary medical center expansion announcements, while top-down constraints applied macro-level veterinary healthcare expenditure trends. Segmentation dimensions included product configuration, material compliance tier, patient size specification, and clinical application setting across the analysis window. CAGR derivation incorporated silicone adoption curve modeling and referral practice capital equipment depreciation incentive sensitivity. Forecast inputs integrated FDA reprocessing guidance trajectory and EU MDR notified body capacity constraints.
Underlying measurement precision varies by segment; cuffed silicone configurations in United States metropolitan referral centers carry tighter precision than exotic animal Cole tube specifications in dispersed avian practices. Forecasts reflect assumptions regarding regulatory enforcement continuity and platinum catalyst supply stability. A model refresh is warranted upon material change in FDA reprocessed single-use device guidance or EU MDR notified body capacity allocation policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Pet Cancer Therapeutics Market
Veterinary
Europe Veterinary Antibiotics Market
Veterinary
Pet Light Therapy Devices Market
Veterinary
Global Pet Obesity Management Market
Veterinary
Europe Veterinarians Market
Veterinary
Australia Veterinary Healthcare Market
Veterinary
Veterinary Wound Sprays Market
Veterinary
Global Cattle Vaccines Market
Veterinary
Otc Pet Medication Market
Veterinary
Veterinary Vaccine Adjuvants Market
Veterinary
Pet Veterinary Diet Market
Veterinary
Pet DNA Testing Market
Veterinary
Global Veterinary Point of Care Market
Veterinary
Germany Veterinary Healthcare Market
Veterinary
Veterinary Contract Development and Manufacturing Organizations (CDMO) Market
Veterinary
Veterinary Supplements Market