
 Automatic Clotting Timer Systems Market | 2026-2036
Automatic Clotting Timer Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Clotting Timer Systems Market Outlook
Procurement from single-source hematology suppliers is shifting toward multi-vendor coagulation platforms across integrated delivery networks. Siemens Healthineers leverages its installed base of automated analyzers to sustain recurring reagent revenue in European hospital chains. Sysmex Corporation anchors its position in Asia-Pacific through dedicated coagulation product lines with localized service infrastructure. Werfen differentiates via specialized hemostasis diagnostics that compete with broader laboratory conglomerates.
Automatic clotting timer systems are electromechanical or optically driven instruments that measure prothrombin time, activated partial thromboplastin time, and fibrinogen concentration through turbidimetric or impedance-based detection methods, primarily serving perioperative bleeding risk assessment and anticoagulant therapy monitoring. Fully-automated systems command the dominant installed base due to labor cost reduction and error-rate improvements, while portable devices represent the fastest-expanding category as point-of-care coagulation testing migrates into emergency departments and outpatient surgical centers. Optical technology leads the technology dimension with mature assay menus, though electrical impedance gains traction in compact platforms where reagent stability and ambient temperature tolerance matter.
The FDA oversees premarket notification pathways for coagulation timer systems under hematology and pathology device classifications, while the EU Medical Device Regulation mandates notified body involvement for all but the lowest-risk variants, extending certification timelines and favoring established manufacturers with quality management infrastructure. The Clinical Laboratory Improvement Amendments in the United States govern personnel qualifications and quality control frequencies, directly shaping hospital purchasing criteria for moderate-complexity coagulation equipment. Stakeholders must monitor evolving harmonization between FDA and EU regulatory expectations as both jurisdictions tighten post-market surveillance requirements for in-vitro diagnostic devices.
Market Dynamics
The automatic clotting timer systems market is experiencing structural compression as hospital laboratories consolidate vendor relationships around multi-parameter hematology platforms that integrate coagulation, chemistry, and immunoassay workflows on unified automation tracks.
Growth Catalysts
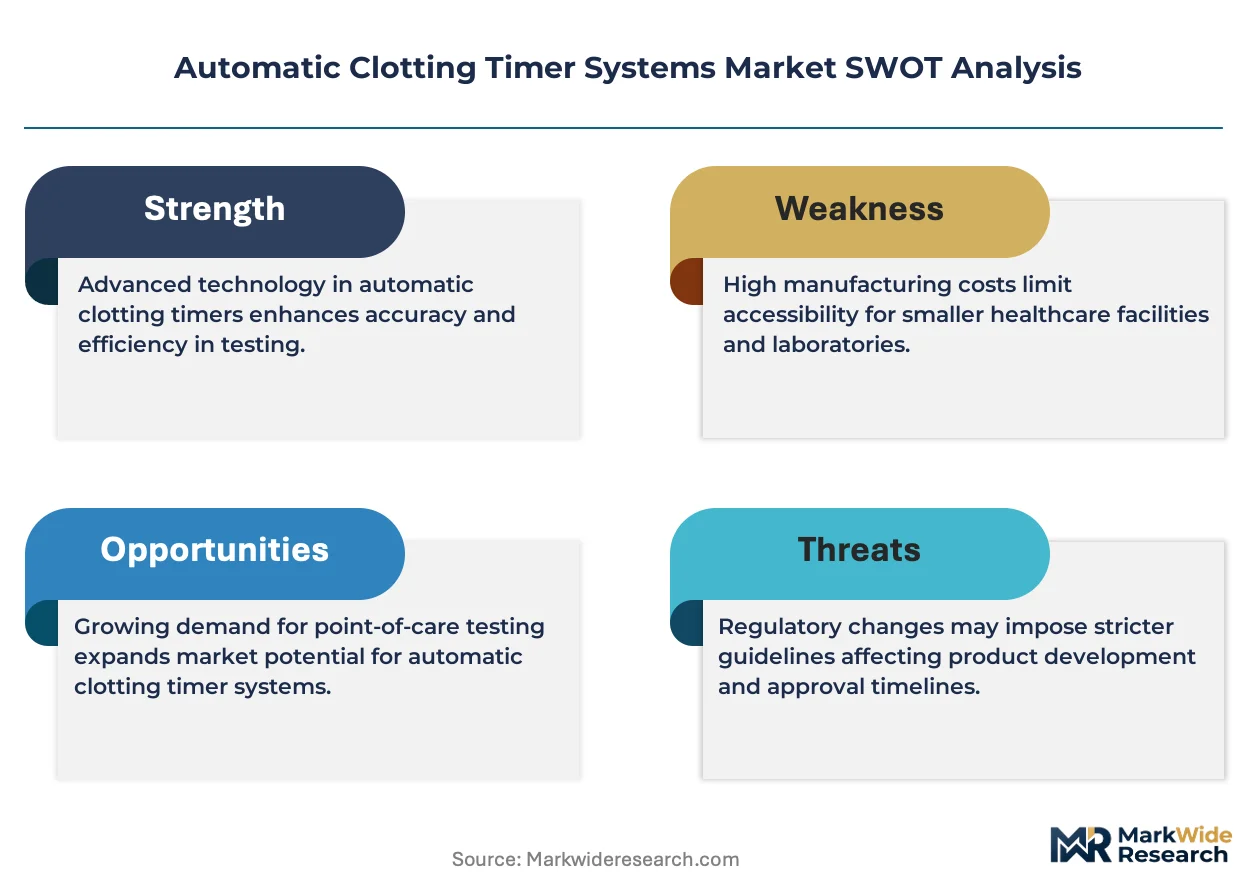
- EU Medical Device Regulation (MDR) harmonization:Stricter conformity assessment pathways are accelerating hospital upgrades from legacy manual systems to validated automated platforms that streamline notified body recertification.
- Perioperative bleeding risk protocols:Surgical departments in tertiary hospitals are mandating continuous coagulation monitoring for cardiac and trauma procedures, expanding analyzer utilization rates.
- Optical turbidimetry advancement:Improved reagent stability at ambient temperatures is extending point-of-care deployment into emergency departments without climate-controlled infrastructure.
Market Restraints
- Reagent supply concentration:Proprietary consumable lock-in with original equipment manufacturers creates switching costs that limit price competition across integrated delivery networks.
- Specialized technician scarcity:Clinical Laboratory Improvement Amendments (CLIA) personnel requirements for moderate-complexity testing constrain expansion into smaller outpatient surgical centers.
- Capital equipment cycles:Seven-to-ten-year depreciation schedules for installed analyzers delay replacement demand despite superior next-generation specifications.
Strategic Opportunities
- Point-of-care decentralization:Portable coagulation devices are penetrating ambulatory surgical centers in Germany and Japan where same-day discharge protocols require rapid turnaround testing.
- Anticoagulant therapy expansion:Direct oral anticoagulant monitoring guidelines are creating demand for specialized assays in cardiology clinics and anticoagulation management services.
- Electrical impedance miniaturization:Solid-state detection methods are converging with microfluidic cartridge designs to enable battery-operated field deployment in military and disaster medical response units.
Industry Challenges
- Interoperability fragmentation:Proprietary data protocols between coagulation analyzers and laboratory information systems require expensive middleware development for multi-vendor environments.
- Quality control frequency burdens:CLIA-mandated control runs every eight hours of operation consume reagent volume and technician time that erode operational margins in lower-throughput settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Clotting Timer Systems Market |
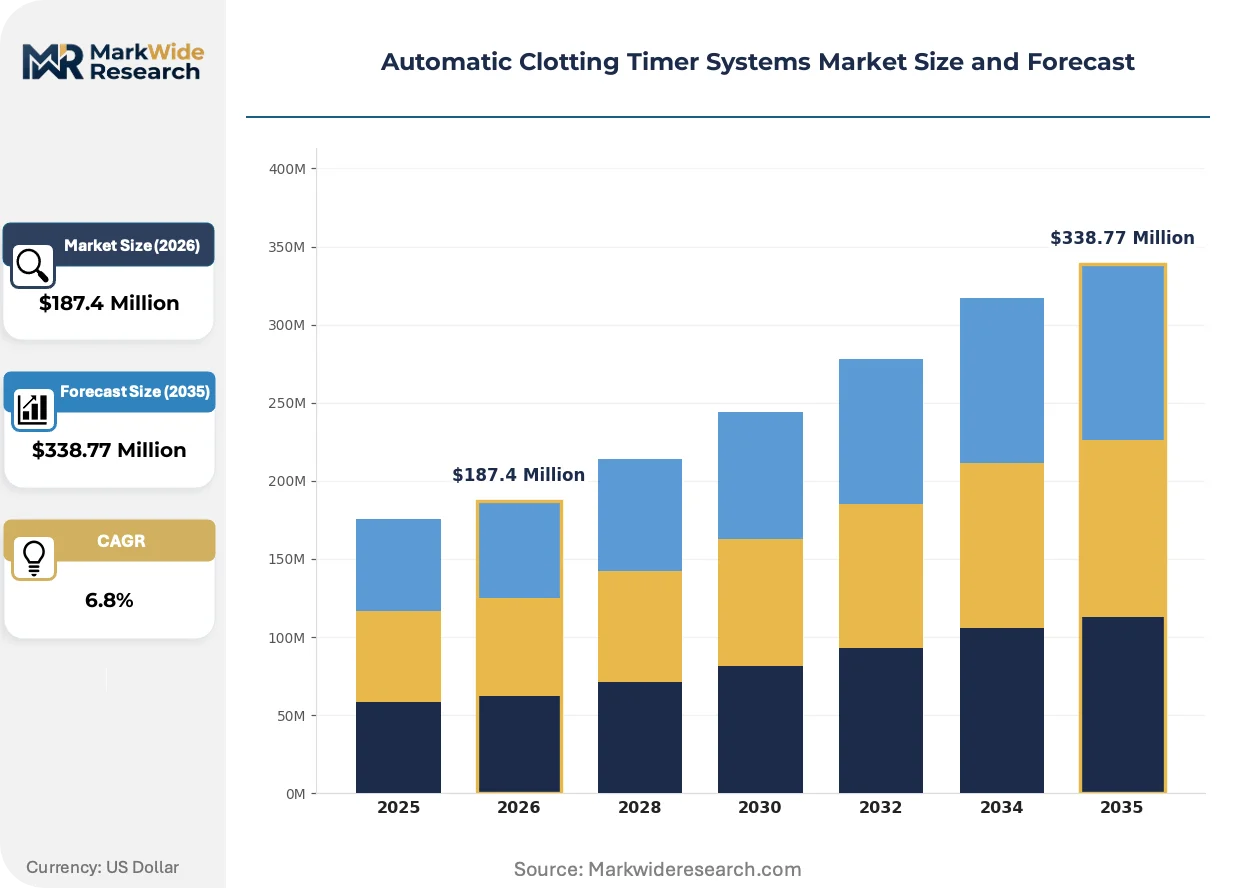
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Systems, Fully-Automated Systems, Semi-Automated Systems, Portable Devices Technology: Optical Technology, Electrical Impedance, Mechanical Method, Magnetic Resonance End User: Hospitals, Blood Banks, Diagnostic Laboratories, Research Institutions Application: Surgical Procedures, Blood Testing, Clinical Research, Patient Monitoring |
| Companies Covered | Siemens Healthineers, Sysmex Corporation, Werfen, F. Hoffmann-La Roche Ltd, Nihon Kohden Corporation, Diagnostica Stago, Helena Laboratories, International Technidyne Corporation, Instrumentation Laboratory, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Clotting Timer Systems Market Strategic Shifts
Automation architecture is reshaping competitive positioning as instrument manufacturers compete on workflow integration rather than standalone analytical performance, with software-defined assay protocols displacing hardware-locked methodologies.
Electrical impedance detection is converging with disposable microfluidic cartridges to enable clotting time measurement without optical path maintenance or ambient light shielding. Emergency departments in United States trauma centers are piloting these compact platforms for rapid INR determination prior to neurosurgical intervention. The structural consequence is compressing the addressable market for conventional benchtop analyzers in settings below fifty tests per day.
The FDA's updated Class II medical device guidance for hematology and pathology instruments is tightening predicate device equivalence standards for 510(k) submissions. Manufacturers must now demonstrate substantial equivalence through clinical performance studies rather than analytical method comparisons alone. High-throughput coagulation analyzers targeting reference laboratory segments are absorbing the compliance burden through dedicated regulatory affairs infrastructure.
Consolidated procurement across integrated delivery networks is displacing individual hospital purchasing autonomy with enterprise-wide capital equipment contracts. Multi-year reagent supply agreements bundled with analyzer placement are replacing traditional equipment sales in United States health systems. This concentration is most visible in tertiary hospital networks where standardization committees mandate single-vendor coagulation platforms across twelve-to-fifteen facility footprints.
Automatic Clotting Timer Systems Market Segmentation
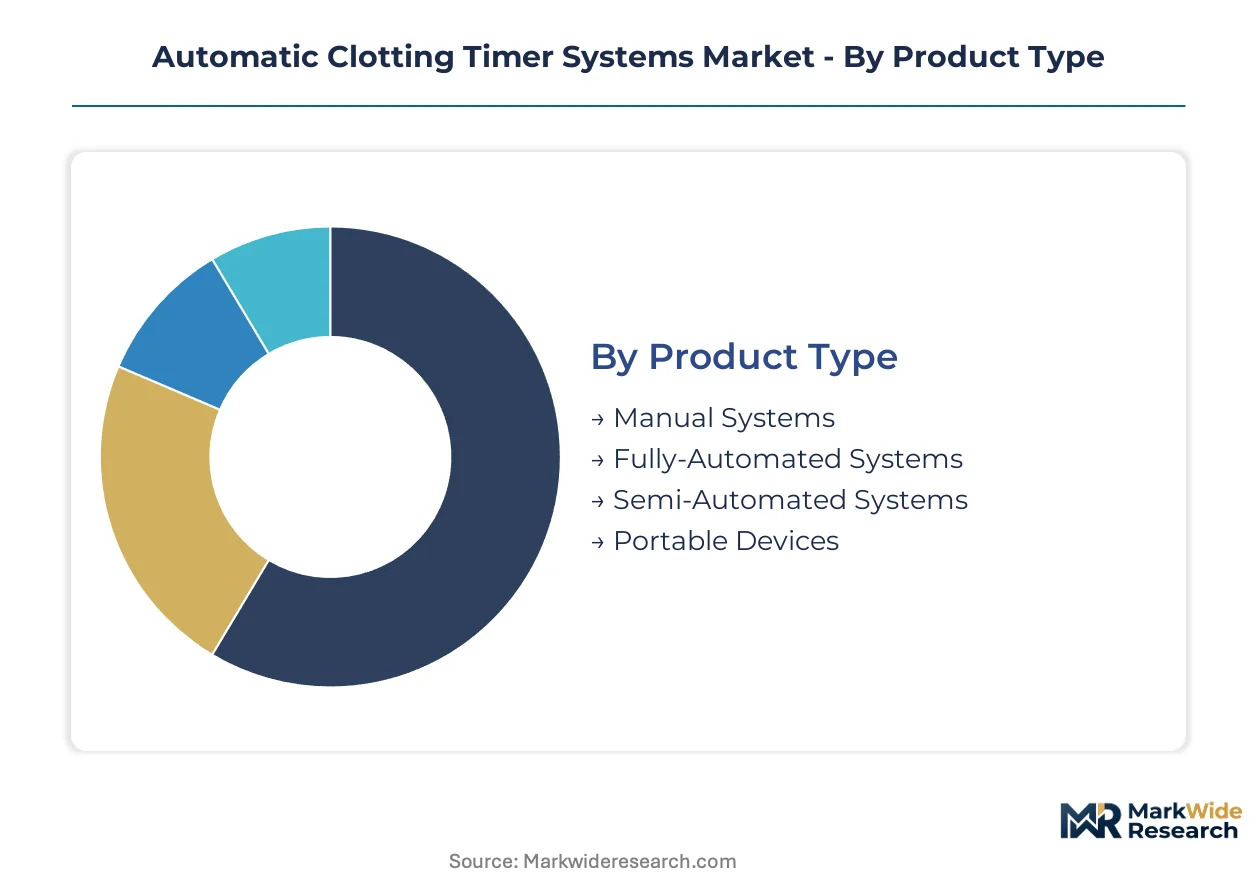
Hospital procurement committees evaluate automatic clotting timer systems through four intersecting dimensions: automation level, detection physics, care setting, and clinical use case. Each segmentation axis carries distinct regulatory, reimbursement, and workflow implications that shape vendor selection criteria.
Product Type:
Laboratory directors weigh capital depreciation schedules against staffing economics when selecting automation tiers.
- Fully-Automated Systems:These electromechanical platforms execute sample handling, reagent dispensing, and turbidimetric detection without technician intervention. Tertiary hospital networks in Germany, France, and the United States concentrate procurement here, driven by CLIA personnel cost containment and overnight unattended operation requirements.
- Portable Devices:Battery-operated or mains-powered compact units deliver point-of-care prothrombin time and activated partial thromboplastin time results within minutes. Emergency departments in United States trauma centers and ambulatory surgical centers in Japan are expanding deployment fastest, spurred by same-day discharge protocols and neurosurgical bleeding risk assessment windows.
- Manual Systems:Benchtop stopwatch-dependent methods requiring visual clot detection persist in resource-constrained settings with intermittent test volumes.
- Semi-Automated Systems:Hybrid platforms automate sample aspiration while retaining manual reagent preparation steps, occupying a narrowing niche in mid-sized diagnostic laboratories.
Volume sits with fully-automated systems; growth tilts toward portable devices.
Technology:
Detection physics determines reagent stability, maintenance burden, and environmental tolerance.
- Optical Technology:Turbidimetric and nephelometric methods measure light scatter as fibrin polymers form, offering mature assay menus and established reference ranges. Hospital laboratories in the United States and Germany standardize on these platforms for high-throughput surgical coagulation panels, though optical path cleaning and ambient light shielding impose infrastructure demands.
- Electrical Impedance:Solid-state electrodes detect clot formation through conductivity changes without optical components. Compact emergency department deployments in Japan and military field medical units favor this approach for temperature tolerance and mechanical durability.
- Mechanical Method:Physical probe movement or cup oscillation detects viscosity changes, retaining relevance in legacy analyzer installed bases.
- Magnetic Resonance:Emerging magnetic bead displacement techniques enable cartridge-based testing with minimal sample volume, currently concentrated in research institution pilot programs.
Optical technology commands the largest installed base; electrical impedance gains share fastest in point-of-care expansion.
End User:
Facility type dictates throughput requirements, regulatory complexity, and integration architecture.
- Hospitals:Integrated delivery networks consolidate procurement around multi-parameter hematology platforms that unify coagulation, chemistry, and immunoassay workflows on single automation tracks.
- Diagnostic Laboratories:Independent reference laboratories and hospital-affiliated central labs prioritize throughput scalability and LIS interoperability for moderate-complexity CLIA testing.
- Blood Banks:Transfusion services require specialized fibrinogen and factor assays with rapid turnaround for massive transfusion protocols.
- Research Institutions:Academic medical centers and contract research organizations drive demand for novel assay development platforms and custom protocol flexibility.
Procurement concentration favors hospital networks; diagnostic laboratories represent the most price-sensitive segment.
Application:
Clinical indication shapes test menu breadth, frequency, and urgency requirements.
- Surgical Procedures:Perioperative bleeding risk protocols in cardiac and trauma surgery mandate continuous coagulation monitoring with rapid turnaround, driving analyzer utilization rates in tertiary hospital operating suites.
- Patient Monitoring:Anticoagulation management services and direct oral anticoagulant monitoring guidelines create recurring demand in cardiology clinics and outpatient anticoagulation programs.
- Blood Testing:Routine preoperative screening and transfusion compatibility testing constitute high-volume, lower-margin workflow segments.
- Clinical Research:Pharmaceutical trials and biomarker discovery programs require specialized assay customization and regulatory documentation support.
Surgical applications absorb the highest capital investment; patient monitoring exhibits the steepest expansion trajectory as anticoagulant therapy broadens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity reagent manufacturing clusters in Germany and Japan anchor supply security for coagulation diagnostics, while tertiary hospital procurement networks in the United States and France concentrate demand for automated testing platforms.
United States
Tertiary hospital networks in Texas and the Northeast Corridor drive demand for high-throughput surgical coagulation monitoring. FDA Class II medical device guidance tightens 510(k) predicate equivalence standards for hematology instruments. The Mayo Clinic Rochester campus and Cleveland Clinic anchor multi-site standardization contracts that bundle analyzer placement with multi-year reagent supply agreements.
Germany
University hospital chains in Bavaria and North Rhine-Westphalia mandate continuous perioperative bleeding risk assessment for cardiac procedures. EU Medical Device Regulation notified body involvement extends certification timelines for new platform introductions. The Rhine-Main cluster around Frankfurt concentrates reference laboratory capacity serving cross-border diagnostic networks into Switzerland and Austria.
Japan
Ambulatory surgical centers in Tokyo and Osaka prefectures expand same-day discharge protocols requiring rapid point-of-care INR determination. PMDA pharmaceutical and medical device agency harmonization with IVD standards accelerates product registration for electrical impedance-based compact platforms. The Kansai region around Osaka anchors localized service infrastructure for coagulation analyzer maintenance networks.
France
Public hospital groups in Île-de-France and Auvergne-Rhône-Alpes consolidate procurement around multi-parameter hematology automation tracks. ANSM national drug and health product safety agency oversight aligns with EU MDR quality management requirements for moderate-complexity testing equipment. The Lyon-Grenoble corridor concentrates transfusion service demand for specialized fibrinogen assays supporting massive transfusion protocols.
United Kingdom
NHS trust consolidation in London and the Midlands shifts purchasing autonomy toward enterprise-wide capital equipment contracts. MHRA medical device regulation post-Brexit divergence creates parallel conformity assessment pathways for analyzer manufacturers. The Cambridge-Oxford-London triangle drives research institution demand for novel assay development platforms in pharmaceutical trial settings.
Automatic Clotting Timer Systems Market Competitive Environment
Global majors compete with regional champions across reagent supply infrastructure and service network density. The market structure tilts toward consolidated procurement relationships where multi-year consumable agreements lock in analyzer placement across integrated delivery networks. Three archetypes dominate: diversified laboratory conglomerates leveraging installed base economics, specialized hemostasis diagnostics firms competing on assay breadth, and point-of-care compact platform specialists penetrating emergency department settings. Competitive moves center on backward integration into reagent manufacturing and geographic expansion through distributor partnerships in Asia-Pacific growth corridors.
Within the diversified conglomerate tier, Siemens Healthineers and Sysmex Corporation exemplify scale-driven positioning anchored in recurring consumable revenue streams. Werfen occupies a specialist position focused on hemostasis diagnostics depth rather than broad laboratory automation. These three entities represent distinct strategic postures: European-installed base leverage, Asia-Pacific service infrastructure density, and therapeutic-area specialization respectively.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Sysmex Corporation |
| Werfen |
| F. Hoffmann-La Roche Ltd |
| Nihon Kohden Corporation |
| Diagnostica Stago |
| Helena Laboratories |
| International Technidyne Corporation |
| Instrumentation Laboratory |
| Others |
Value Chain & Pricing Dynamics
Electrical impedance miniaturization in compact coagulation platforms simultaneously compresses manufacturing cost structures and concentrates component sourcing around specialized German and Japanese sensor foundries. This technology transition rewards early movers with captive reagent supply chains while forcing late adopters into unfavorable long-term consumable contracts.
Pricing Analysis
Service-bundling separates premium-tier analyzer placements with multi-year preventive maintenance agreements from economy-tier capital sales with à la carte technical support. Three-tier pricing structure across premium, standard, and economy levels reflects CLIA certification grade, installed base scale, and geographic service network density. Pricing pressure stems from integrated delivery network procurement consolidation mandating enterprise-wide standardization. Diagnostic laboratories exhibit highest price sensitivity due to thin margins on moderate-complexity testing, while tertiary hospital networks absorb premium pricing for uninterrupted surgical workflow support.
Supply Chain Analysis
Dual-sourcing requirements from FDA and EU MDR notified bodies mandate qualified secondary suppliers for optical detectors, microfluidic cartridges, and lyophilized reagent matrices. Manufacturing concentrates in Germany, Japan, and the United States for precision electromechanical components and high-purity reagent formulation. Supply chain risk centers on single-source vulnerability for specialized turbidimetric cuvettes and impedance electrodes. Distribution runs through hematology-focused distributor networks serving integrated delivery networks and independent reference laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EU Medical Device Regulation recertification burdens create a barrier-to-entry moat favoring manufacturers with established quality management infrastructure and notified body relationships.
For Market Incumbents: Anchor recurring revenue streams through captive reagent supply agreements locked to analyzer placements across twelve-to-fifteen facility integrated delivery networks. Deepen backward integration into lyophilized reagent manufacturing to defend margin position against emerging electrical impedance platform specialists. Prioritize CLIA personnel training programs as a channel control mechanism that raises switching costs for hospital laboratory customers. For New Entrants and Emerging Players: Launch via emergency department point-of-care distribution partnerships in United States trauma centers and Japanese ambulatory surgical centers where same-day discharge protocols create urgent demand for rapid INR determination. Target portable device segments underserved by optical technology incumbents with temperature-tolerant electrical impedance platforms. Pursue military and disaster medical response procurement channels where battery-operated field deployment requirements favor compact solid-state designs. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified laboratory conglomerates seeking hemostasis diagnostics depth. Long-term viability hinges on recurring consumable revenue ratios exceeding capital equipment depreciation cycles. Monitor FDA 510(k) predicate equivalence standard tightening as the inflection signal that accelerates consolidation toward regulatory affairs-capable platforms.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR notified body engagement accelerates hospital upgrade cycles from legacy manual systems. |
| Hospital System Partnership | Multi-year reagent supply agreements with Mayo Clinic and Cleveland Clinic standardize analyzer placement. |
| Backward Integration into Reagents | In-house lyophilized reagent production captures margin from proprietary consumable lock-in economics. |
| Software Companion Development | LIS interoperability middleware resolves multi-vendor data protocol fragmentation in consolidated networks. |
| Reimbursement Strategy | Anticoagulation management service billing codes expand addressable market for outpatient coagulation monitoring. |
Study Parameters
Independent corroboration across hospital laboratory directors, hematology instrument procurement managers, biomedical engineers, and GPO contracts administrators underwrites the qualitative findings. Secondary validation draws from FDA 510(k) filings, EU MDR notified body certificates, hospital procurement databases, and CMS Medicare laboratory fee schedule data. Bottom-up analyzer placement counts triangulate against top-down reagent revenue estimates from diversified laboratory conglomerate segment disclosures.
Rate-of-change decomposition across automation level, detection physics, care setting, and clinical use case dimensions structures the analytical framework. CAGRs derive from installed base replacement cycles, perioperative protocol expansion rates, and point-of-care decentralization trajectories. Forecast inputs incorporate CLIA personnel shortage constraints, EU MDR certification timeline extensions, and direct oral anticoagulant monitoring guideline adoption curves.
Regulatory harmonization delays, reagent supply disruptions, and integrated delivery network procurement consolidation are the dominant revision risks. Forecasts reflect assumptions about uninterrupted surgical volume growth and stable anticoagulant therapy expansion. A model refresh is warranted upon material change in FDA Class II predicate equivalence standards or EU MDR notified body capacity constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Prefilled Syringes Market
Medical Devices
Life Science Microscopy Devices Market
Medical Devices
Global Monopolar Electrosurgery Market
Medical Devices
Global Transradial Access Market
Medical Devices
North America Sperm Separation Devices Market
Medical Devices
SPG Microstimulator System Market
Medical Devices
Global Intraosseous Devices Market
Medical Devices
North America Smart Medical Devices Market
Medical Devices
Cervical Total Disc Replacement Device Market
Medical Devices
Autosamplers Market
Medical Devices
Interatrial Shunt Market
Medical Devices
Intrathecal Pumps Market
Medical Devices
Gracey Curette Market
Medical Devices
Global Micro Guide Catheters Market
Medical Devices
Global Surgical Robotics Market
Medical Devices
Transportable Ventilator Market