
 North America IVD Regulatory Affairs Outsourcing Market | 2026-2036
North America IVD Regulatory Affairs Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
North America IVD Regulatory Affairs Outsourcing Market Analytics
Buyer concentration among large diagnostic companies is restructuring how regulatory outsourcing contracts are negotiated and fulfilled. Freyr Solutions leverages its technology-enabled delivery model to serve multinational IVD sponsors with distributed product portfolios. ICON plc anchors its position through deep clinical trial regulatory capabilities that extend into post-market surveillance requirements. Emergo by UL differentiates through integrated compliance consulting tied to its testing and certification heritage.
IVD regulatory affairs outsourcing encompasses the delegation of premarket strategy, submission preparation, quality system maintenance, and post-market compliance activities to third-party specialists, typically governed by FDA 21 CFR Part 820 quality system requirements and international harmonization standards. The primary commercial purpose centers on accelerating time-to-market for diagnostic technologies while navigating multi-jurisdictional approval pathways. Consulting and submission management services capture the largest share of contract value due to their direct linkage to product authorization timelines. Cloud-based regulatory solutions represent the fastest-expanding technology segment as sponsors replace paper-based quality management systems with validated electronic platforms.
FDA oversight through 21 CFR Part 809 IVD regulations and the evolving transition to its Quality Management System Regulation shapes submission complexity and drives demand for specialized guidance. Health Canada and its Medical Devices Bureau maintain parallel but distinct premarket review pathways that Canadian-market entrants must address concurrently with US filings. Stakeholders must monitor how FDA's digital health pre-certification pilots and anticipated IVD-specific guidance documents reshape the skill requirements that outsourcing partners must maintain.
Market Dynamics
FDA's transition from the Quality System Regulation to the Quality Management System Regulation is forcing diagnostic sponsors to rebuild quality documentation and submission protocols, amplifying demand for external regulatory expertise.
Growth Catalysts
- 21 CFR Part 809 complexity:FDA's expanding IVD classification rules require specialized interpretation for premarket notification pathways, pulling sponsors toward external specialists.
- Digital health pre-certification pilots:FDA's evolving software-as-a-medical-device framework creates new compliance categories that internal teams struggle to operationalize without support.
- Canadian parallel filings:Health Canada's Medical Devices Bureau maintains distinct review timelines, compelling US sponsors to secure dual-jurisdiction expertise for synchronized market entry.
Market Restraints
- Specialized talent scarcity:The shallow pool of professionals holding dual FDA-Health Canada expertise concentrates in Boston and San Diego, inflating service rates.
- Validation cost rigidity:Cloud-based quality management systems require extensive 21 CFR Part 11 validation, locking mid-tier sponsors into higher fixed outsourcing minimums.
- Regulatory divergence friction:FDA's digital health initiatives proceed on timelines misaligned with Health Canada's software guidance, complicating unified submission strategies.
Strategic Opportunities
- Mexico regulatory alignment:COFEPRIS's accelerated medical device approval pathways for US-authorized products create nearshore expansion potential for outsourcing providers.
- Companion diagnostic convergence:The intersection of IVD and pharmaceutical development protocols opens integrated regulatory service bundles spanning CDER and CDRO coordination.
- Post-market surveillance automation:FDA's MDR electronic submission mandates drive demand for AI-assisted adverse event reporting platforms that outsourcing firms can white-label.
Industry Challenges
- Legacy system integration:Sponsors running paper-based quality systems face costly migrations to validated electronic platforms before outsourcing partnerships can activate.
- Skill bifurcation:The gap between traditional 510(k) preparation expertise and emerging software pre-certification knowledge forces providers to maintain redundant specialist teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America IVD Regulatory Affairs Outsourcing Market |
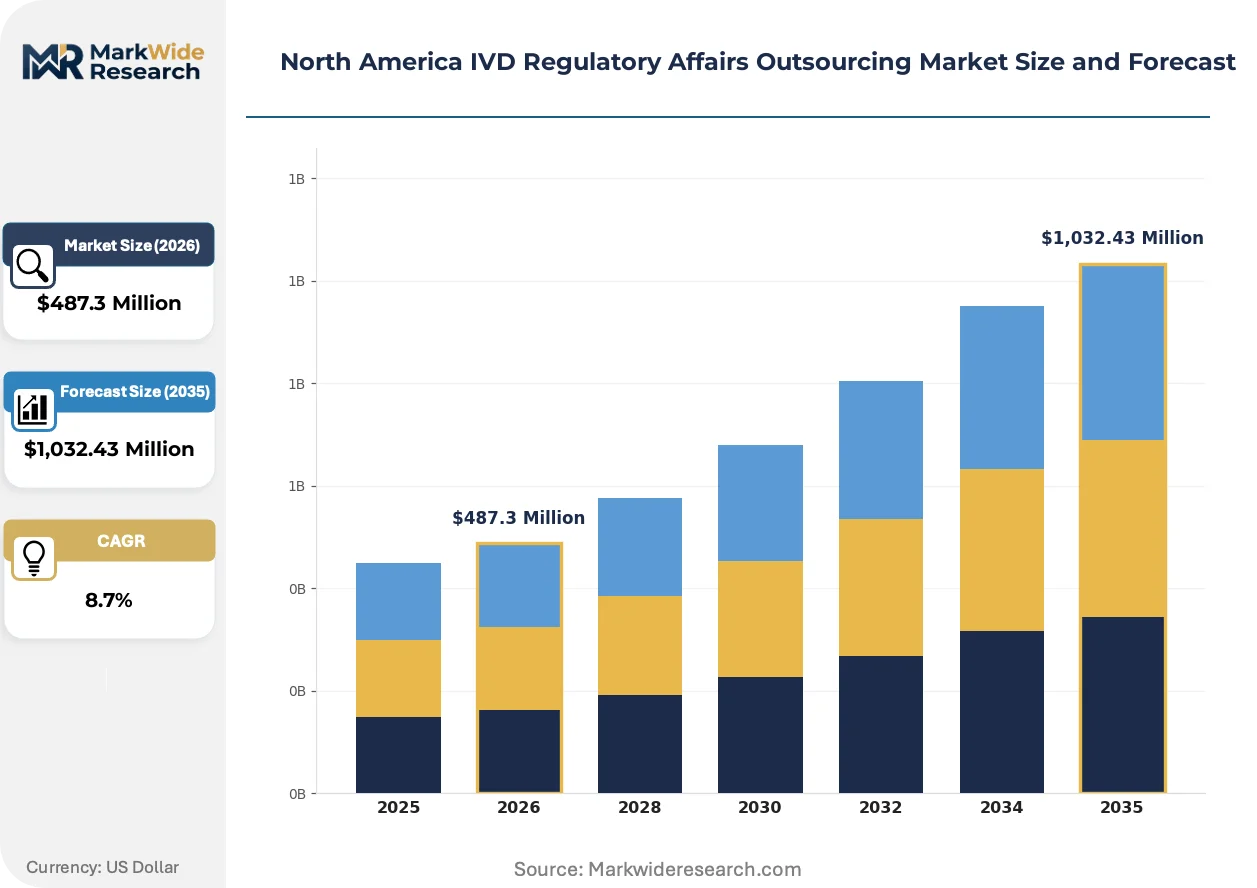
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Submission Management, Compliance Management, Market Authorization End User: Diagnostic Companies, Biotechnology Firms, Research Institutions, Contract Manufacturers Technology: Cloud-Based Solutions, On-Premises Solutions, Electronic Document Management Systems, Automated Regulatory Submissions Application: In Vitro Diagnostics, Medical Devices, Combination Products, Clinical Trials |
| Companies Covered | Freyr Solutions, Covance, ICON plc, Emergo by UL, LORENZ Life Sciences Group, AXSource Consulting Inc., Promedica International, MakroCare, RegIQ Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America IVD Regulatory Affairs Outsourcing Market Evolving Landscape
Technology-enabled delivery models are compressing project timelines while regulatory digitization is redefining the scope of outsourced activities beyond document preparation toward continuous compliance monitoring.
Cloud-native regulatory information management systems are consolidating sponsor quality data across distributed product portfolios into single validated repositories. Mid-cap diagnostic companies with limited IT infrastructure are adopting these platforms fastest, replacing fragmented spreadsheet-based submission tracking. This consolidation is compressing the traditional handoff cycles between sponsor and service provider, blurring the boundary between internal and external quality system ownership.
FDA's Quality Management System Regulation proposal is extending design controls into software lifecycle processes, forcing sponsors to revalidate existing automated systems. The rule's emphasis on risk-based post-market surveillance is expanding the scope of retained regulatory services beyond initial authorization. Canadian sponsors filing under the CMDCAS transition are simultaneously adapting to MDSAP audit requirements, creating dual-compliance workload spikes.
Diagnostic sponsors are unbundling regulatory affairs from full-service CRO relationships, establishing direct contracts with specialized IVD regulatory boutiques. Large reference laboratories and contract manufacturers are building captive regulatory teams for routine filings while outsourcing novel technology classifications. This bifurcation is most visible in California's molecular diagnostics cluster, where sponsors maintain internal 510(k) capabilities but delegate de novo pathway strategies.
North America IVD Regulatory Affairs Outsourcing Market Segmentation
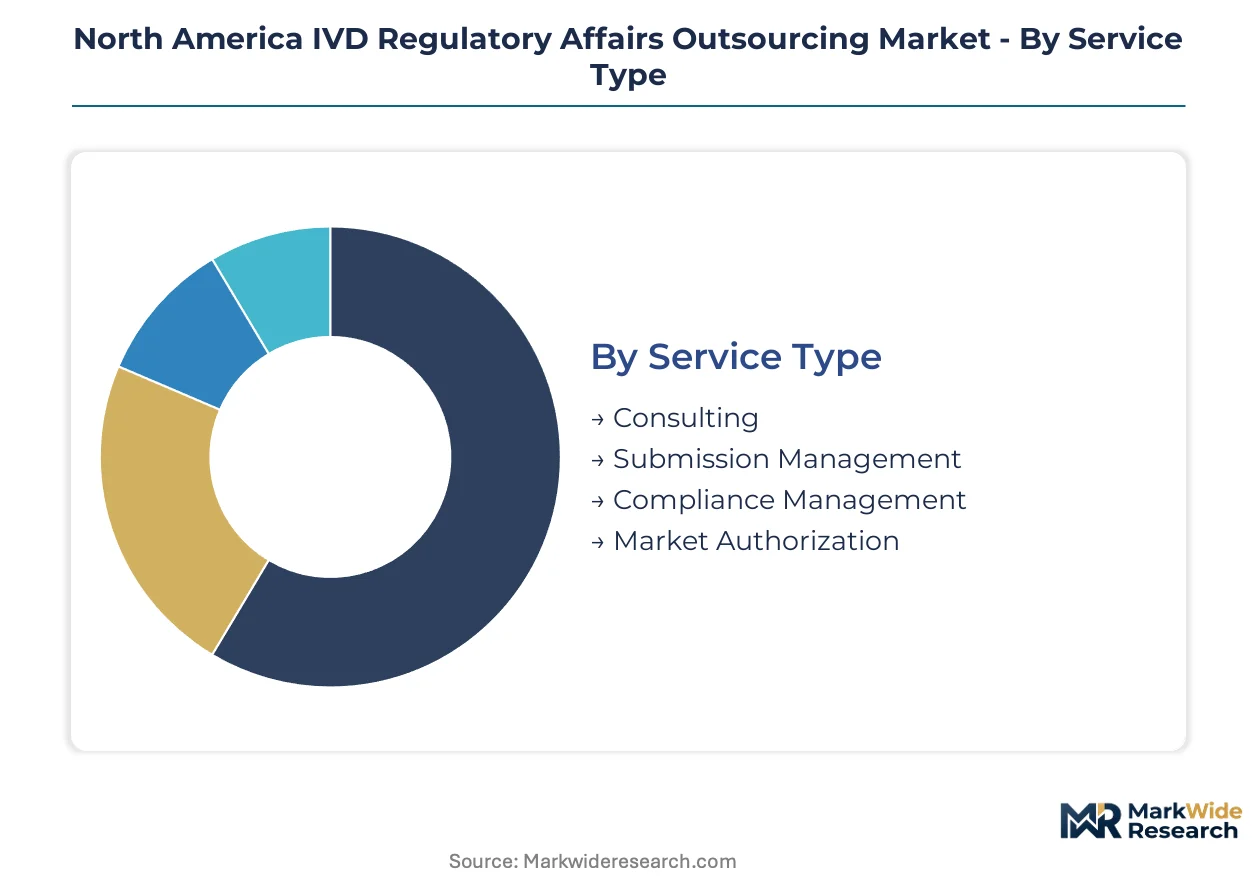
Regulatory outsourcing contracts fragment across service intensity tiers, from advisory retainers to full quality system delegation. Each segment commands distinct pricing structures and specialist skill profiles that reshape how diagnostic sponsors structure vendor relationships.
Service Type:
Customization intensity varies sharply across this category, with advisory services permitting flexible scope adjustments while managed compliance programs demand rigid protocol adherence.
- Consulting:Strategic advisory engagements covering premarket pathway selection, predicate device analysis, and FDA meeting preparation. Diagnostic companies in California's molecular diagnostics cluster deploy these services for novel technology classifications where internal expertise gaps exist. Hourly billing structures dominate, though outcome-based retainers are gaining traction for 510(k) clearance milestones.
- Submission Management:End-to-end preparation of 510(k), PMA, and de novo submissions including technical documentation assembly, biocompatibility summaries, and clinical data formatting. Boston-area IVD innovators rely heavily on these services for synchronized FDA-Health Canada filings. Fixed-fee arrangements predominate, with penalty clauses tied to acceptance review cycles.
- Compliance Management:Ongoing quality system maintenance, internal audit programs, and CAPA remediation support.
- Market Authorization:Jurisdiction-specific licensing and establishment registration activities spanning US, Canadian, and Mexican regulatory frameworks.
Leading the category by volume: Consulting. Expanding most quickly: Submission Management.
End User:
Contract sophistication tracks organizational scale, with large diagnostic enterprises negotiating master service agreements while emerging biotechnology firms purchase discrete project scopes.
- Diagnostic Companies:Established IVD manufacturers with distributed product portfolios requiring sustained regulatory partnership. These sponsors in San Diego and Minneapolis maintain captive teams for routine 510(k) filings while outsourcing novel platform technologies. Multi-year strategic relationships predominate, with preferred provider panels consolidating to three to five specialist firms.
- Contract Manufacturers:Third-party production facilities needing regulatory coverage for OEM labeling and quality system interface. Texas and North Carolina manufacturing hubs drive concentrated demand for FDA establishment registration and device listing support. These engagements typically bundle regulatory services with manufacturing contracts at compressed margins.
- Biotechnology Firms:Emerging developers transitioning research assays toward commercial IVD status.
- Research Institutions:Academic medical centers and national laboratories pursuing investigational device exemptions and pre-submission pathways.
Dominating contract value: Diagnostic Companies. Gaining share fastest: Contract Manufacturers.
Technology:
Deployment models diverge by IT infrastructure maturity, with cloud-native platforms displacing on-premises installations among mid-cap sponsors lacking dedicated validation teams.
- Cloud-Based Solutions:Validated software-as-a-service platforms for regulatory information management, submission tracking, and quality system documentation. Mid-tier diagnostic companies across the US Midwest adopt these fastest, replacing fragmented spreadsheet-based systems. 21 CFR Part 11 validation burdens shift to vendor responsibility, lowering entry barriers for resource-constrained sponsors.
- Automated Regulatory Submissions:AI-assisted document generation, eCTD formatting, and FDA gateway transmission tools. These solutions concentrate in California's digital health corridor where software-as-a-medical-device sponsors require rapid iteration cycles. Implementation costs and change control rigor limit penetration among traditional IVD manufacturers.
- Electronic Document Management Systems:On-premise or hybrid repositories for controlled document lifecycle management.
- On-Premises Solutions:Self-hosted regulatory platforms maintained within sponsor firewall environments.
Highest installed base: Electronic Document Management Systems. Steepest expansion trajectory: Cloud-Based Solutions.
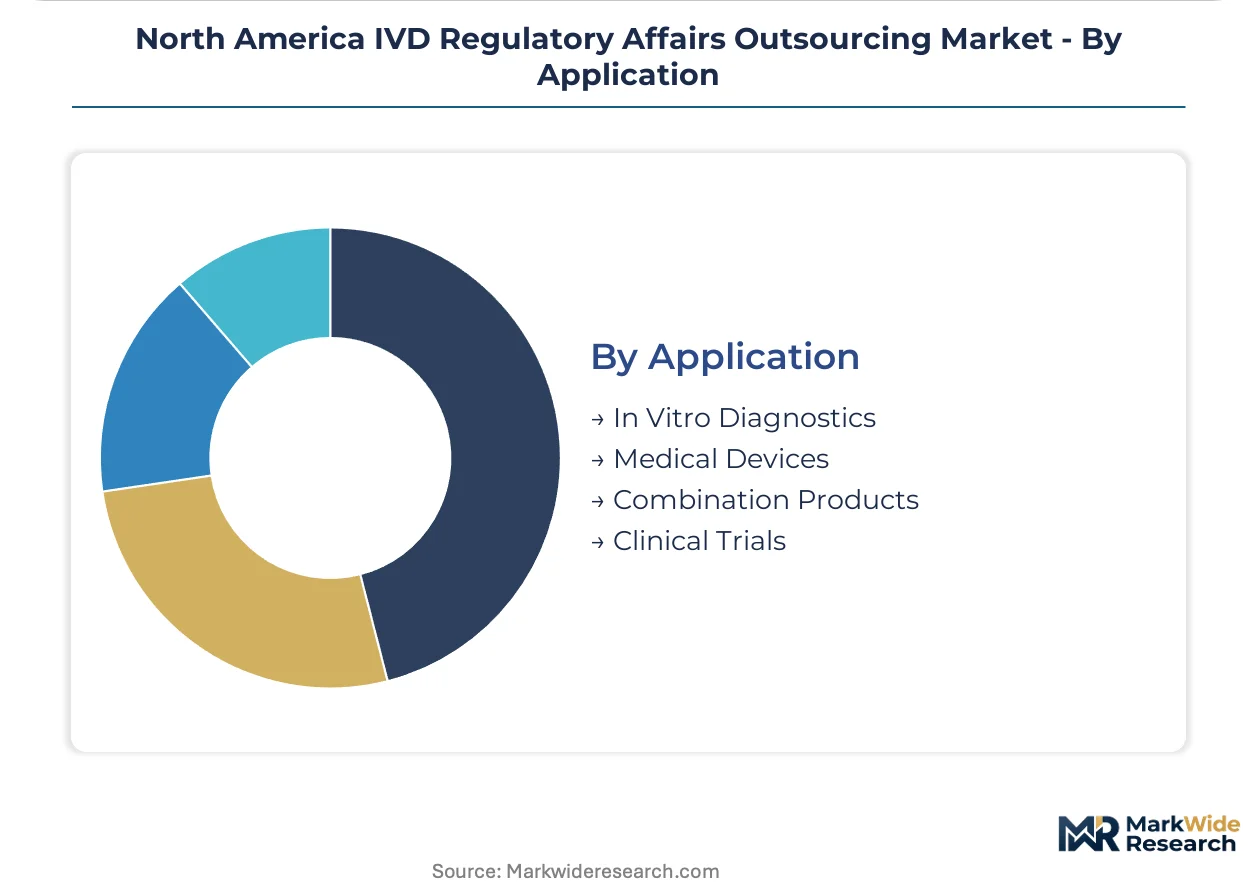
Application:
Regulatory complexity escalates with product classification risk, with combination products demanding cross-functional expertise spanning FDA centers.
- In Vitro Diagnostics:Traditional diagnostic reagents, instruments, and systems governed by 21 CFR Part 809. This segment captures the largest share of outsourcing demand, with molecular diagnostics and point-of-care platforms driving specialized submission requirements. FDA's evolving classification rules for multiplex assays and software-integrated devices amplify external guidance needs.
- Combination Products:Co-packaged or single-entity products combining IVD components with drug or device constituents. These engagements require coordination across CDER, CDRH, and OC offices, commanding premium service rates. Oncology companion diagnostics represent the fastest-growing subsegment as pharmaceutical sponsors seek synchronized therapeutic and diagnostic approvals.
- Medical Devices:Non-IVD devices with overlapping quality system requirements.
- Clinical Trials:Investigational device exemption support and premarket clinical study regulatory management.
Capturing largest contract volume: In Vitro Diagnostics. Climbing the fastest: Combination Products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic sponsors concentrate outsourcing demand in metropolitan clusters with dense FDA submission activity and specialized regulatory talent pools. United States hubs dominate contract value, though Canadian and Mexican pathways attract synchronized filing strategies.
United States
San Diego and Boston anchor the highest outsourcing contract density, driven by molecular diagnostic innovators and companion diagnostic developers. FDA's 21 CFR Part 809 framework and evolving Quality Management System Regulation force sponsors to rebuild submission protocols, amplifying external expertise demand. California's digital health corridor generates concentrated need for software-as-a-medical-device pre-certification guidance.
Canada
Health Canada's Medical Devices Bureau maintains distinct review timelines that US sponsors must address for synchronized North American market entry. The CMDCAS transition to MDSAP audit requirements creates dual-compliance workload spikes for Ontario and Quebec-based diagnostic operations. Toronto's emerging IVD manufacturing base drives demand for FDA-Health Canada parallel filing expertise.
Mexico
COFEPRIS accelerated approval pathways for US-authorized products create nearshore expansion potential for outsourcing providers serving multinational sponsors. The Bajío Region's medical device manufacturing growth generates establishment registration and quality system interface demand. Mexico City regulatory consultancies specialize in bridging FDA submissions with Latin American market authorization.
North America IVD Regulatory Affairs Outsourcing Market Competitive Landscape
United States-based specialists anchor the premium advisory tier; Canadian and European-owned subsidiaries hold compliance management scale. The vendor base fragments across technology-enabled boutiques and full-service CRO regulatory divisions. Three archetypes dominate: technology-platform aggregators, clinical trial regulatory extenders, and testing-heritage compliance integrators. Consolidation proceeds through diagnostic-specific boutique acquisitions and cloud platform licensing partnerships.
Within the technology-enabled tier, Freyr Solutions exemplifies platform-driven delivery models for distributed product portfolios. ICON plc occupies a position bridging clinical trial regulatory capabilities into post-market surveillance requirements. Emergo by UL anchors the testing-heritage integration archetype, leveraging certification infrastructure for compliance consulting bundling.
| Leading Market Players |
|---|
| Freyr Solutions |
| Covance |
| ICON plc |
| Emergo by UL |
| LORENZ Life Sciences Group |
| AXSource Consulting Inc. |
| Promedica International |
| MakroCare |
| RegIQ Solutions |
| Others |
Value Network & Pricing Analysis
Dual FDA-Health Canada expertise concentrated in Boston and San Diego creates labor-cost differentials that widen pricing-tier spreads between premium advisory retainers and standardized submission packages. These geographic talent clusters compress margins for mid-tier sponsors while amplifying rate premiums for boutique specialists holding cross-border regulatory credentials.
Pricing Analysis
Volume concentrates in fixed-fee submission management contracts while margins accrue to outcome-based consulting retainers tied to 510(k) clearance milestones. Pricing stratifies across premium, standard, and economy tiers based on certification depth (FDA 510(k) versus de novo pathway complexity) and customization intensity (template-driven versus novel predicate analysis). Cost compression in standard-tier submission preparation is intensifying because cloud-based regulatory platforms are commoditizing document assembly workflows. Biotechnology firms exhibit highest price sensitivity due to constrained capital reserves, while large diagnostic companies prioritize speed-to-clearance over rate negotiation.
Supply Chain Analysis
Certification and qualification gating through 21 CFR Part 11 validation requirements shapes vendor selection, concentrating service delivery among United States, Canada, and Ireland-based providers with established FDA gateway access. Raw material dependencies center on specialized regulatory talent pools, validated software infrastructure, and proprietary predicate device databases. Single-source vulnerability runs through Boston's concentrated expert labor market, where poaching between outsourcing firms disrupts project continuity. Distribution runs through direct enterprise sales to diagnostic sponsors, with master service agreements replacing transactional engagements among top-tier accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as incumbents pursue backward integration into proprietary regulatory technology platforms to defend margin erosion from SaaS-based competitors.
For Market Incumbents: Cement market position by acquiring cloud-native regulatory information management platforms to internalize recurring revenue streams and reduce talent dependency. Build captive Health Canada expertise in Toronto to preempt emerging competitors exploiting CMDCAS-MDSAP transition complexity. The threat of technology-enabled boutiques automating submission preparation demands defensive platform investments before pricing power erodes further.
For New Entrants and Emerging Players: Enter via Mexico's COFEPRIS accelerated approval pathways for US-authorized products, where established regulatory consultancies maintain limited presence. Target contract manufacturers in Texas and North Carolina manufacturing hubs with bundled FDA establishment registration and quality system interface services. A white-label AI-assisted adverse event reporting platform offers the most penetrable go-to-market angle, addressing FDA's MDR electronic submission mandates without requiring deep predicate device expertise.
For Investors and Strategic Acquirers: Re-rating potential sits with technology-enabled boutiques holding validated 21 CFR Part 11 platforms given FDA's Quality Management System Regulation transition forcing sponsor system migrations. Long-term viability favors providers spanning premarket submission through post-market surveillance automation, capturing recurring compliance revenue across product lifecycles. The signal to watch is Health Canada's software guidance alignment with FDA digital health pre-certification timelines, which would validate unified North American filing strategies and reward dual-jurisdiction capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Platform Acquisition | Consolidates fragmented sponsor quality data into single 21 CFR Part 11 validated repositories. |
| Companion Diagnostic Service Bundle | Integrates CDER and CDRH coordination for synchronized therapeutic and diagnostic approvals. |
| Post-Market Surveillance Automation | Addresses FDA's MDR electronic submission mandates through AI-assisted adverse event reporting. |
| Nearshore Mexico Expansion | Captures COFEPRIS accelerated pathway demand from multinational sponsors seeking Latin American entry. |
| Dual-Jurisdiction Talent Build | Positions providers for synchronized FDA-Health Canada filings as MDSAP audit requirements converge. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with regulatory affairs directors, quality system managers, FDA submission specialists, and diagnostic company procurement leads. FDA 510(k) clearance databases, Health Canada medical device licenses, and COFEPRIS registration records provided structured secondary validation. Bottom-up service provider revenue estimates triangulated against top-down diagnostic sponsor outsourcing expenditure surveys.
Data-stream reconciliation across service type, end user, technology deployment, and application segments shaped the analytical framework throughout the projection horizon. Modeled dimensions encompassed consulting intensity, submission pathway complexity, cloud versus on-premises infrastructure, and traditional IVD versus combination product regulatory requirements. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion patterns, with FDA regulatory timeline assumptions and Health Canada review cycle benchmarks serving as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated FDA digital health guidance or prolonged MDSAP transition disruption. Forecasts reflect assumptions regarding regulatory staffing availability and cloud platform adoption curves. A model refresh is warranted upon material change in FDA Quality Management System Regulation implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Neurodiagnostic and Monitoring Devices Market
Medical Devices
Seizure Detection Devices Market
Medical Devices
Water Bath Vaporizer Market
Medical Devices
Biologic Injectors Market
Medical Devices
Italy Contraceptive Devices Market
Medical Devices
Global Implantable Cardioverter Defibrillators (ICD) Market
Medical Devices
Platelet Concentration Systems Market
Medical Devices
Global Hydrogel Based Drug Delivery System Market
Medical Devices
Wearable Cardioverter Defibrillators Market
Medical Devices
Video-Guided Pericardial Access Device Market
Medical Devices
Permanent Artificial Skin Market
Medical Devices
Global Hemostasis Valves Market
Medical Devices
Veterinary Stereotactic Radiosurgery System Market
Medical Devices
Australia Respiratory Devices Market
Medical Devices
Diabetes Devices Market
Medical Devices
Surgical Integration Systems Market