
 Quantitative Pathology Imaging Market | 2026-2036
Quantitative Pathology Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Quantitative Pathology Imaging Market Analytics
North American scanner OEMs is expanding production capacity for high-throughput whole slide imaging systems to serve backlog in clinical laboratories. Leica Biosystems leverages its installed base of histology equipment to cross-sell integrated digital pathology workflows. Hamamatsu Photonics sustains technology leadership through proprietary sensor architectures that enable rapid scan speeds. Koninklijke Philips competes by bundling pathology informatics with enterprise imaging contracts across health systems.
Quantitative pathology imaging encompasses the digital acquisition, computational analysis, and standardized quantification of histopathological specimens using calibrated whole slide scanners and algorithmic software, typically achieving sub-micron spatial resolution across tissue sections spanning 20x to 40x optical magnification, with primary purpose of converting subjective visual interpretation into reproducible numerical outputs for diagnostic and research decision-making. Digital slide scanners anchor the hardware revenue pool given capital intensity and replacement cycles, while artificial intelligence represents the fastest-expanding technology layer as vendors embed predictive algorithms directly into analysis workflows. Image analysis software captures disproportionate margin contribution relative to hardware due to recurring license structures and lower incremental delivery costs.
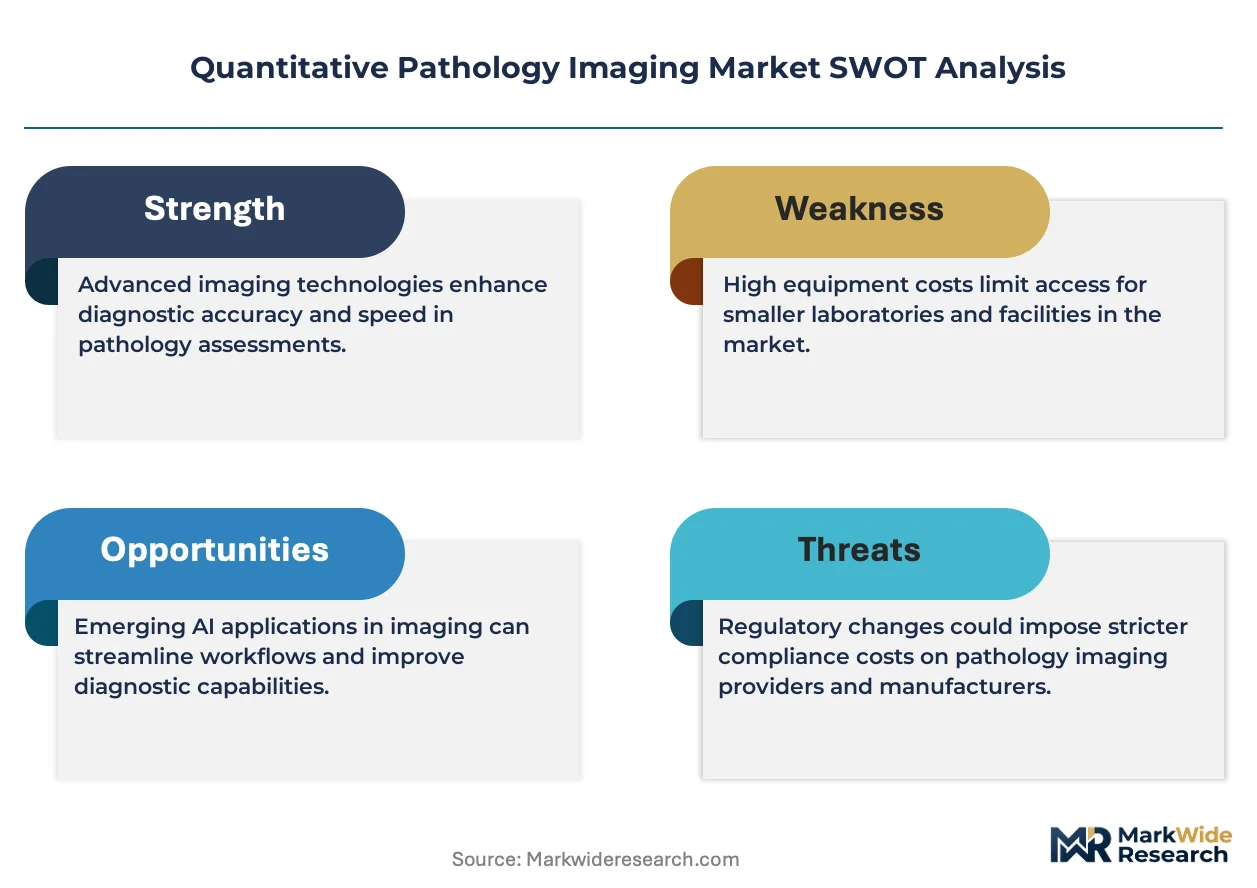
FDA software-as-medical-device oversight, EU MDR conformity requirements for diagnostic imaging systems, and HIPAA security rule provisions for cloud-based pathology data collectively elevate compliance expenditure for market participants while creating structural barriers to unvalidated algorithm deployment. ISO 15189 accreditation standards for medical laboratories further constrain instrument selection to validated platforms with established quality management systems. Stakeholders must monitor evolving premarket review pathways for machine learning-enabled diagnostic algorithms as regulatory clarity will determine competitive positioning in clinical versus research market segments.
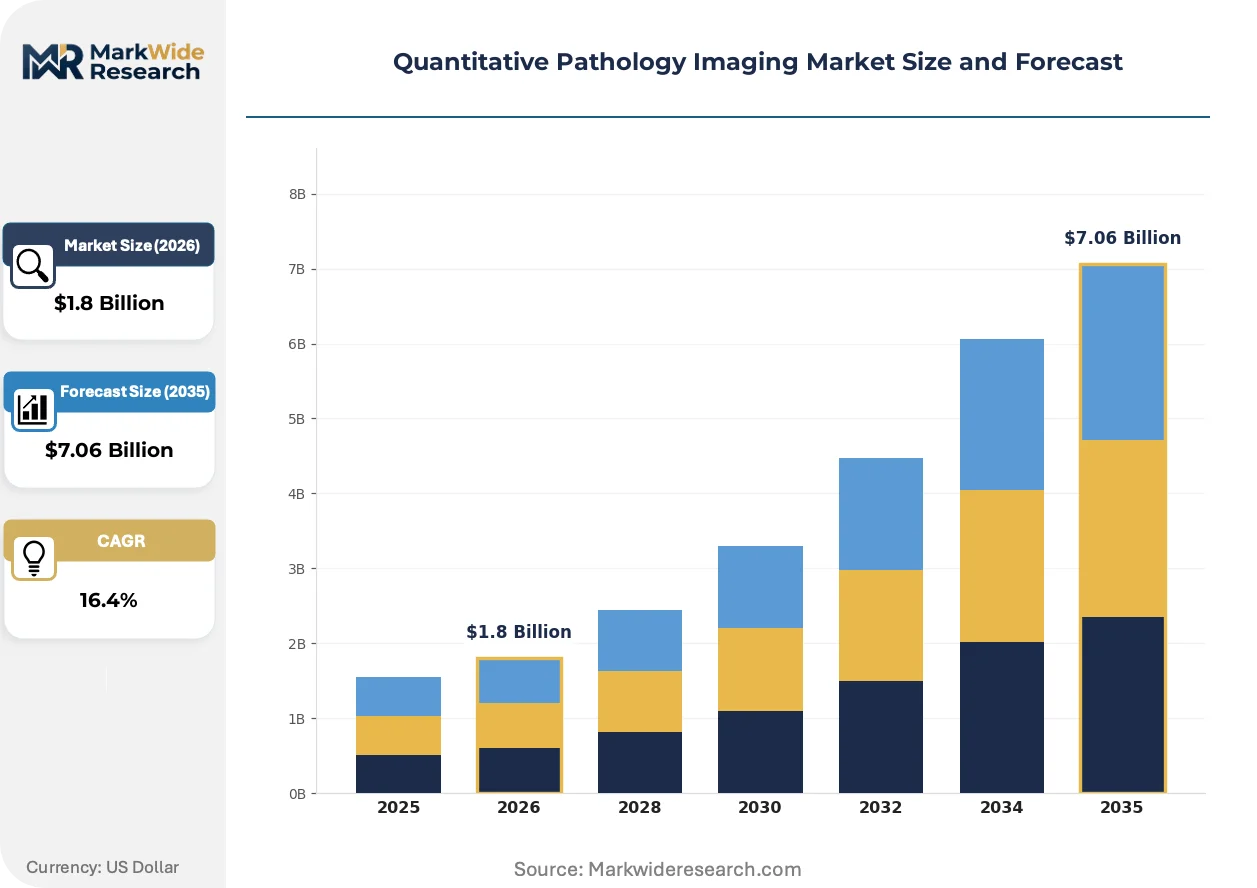
Market Dynamics
Hospital pathology departments are consolidating around digital-first diagnostic workflows as FDA software-as-medical-device enforcement compresses vendor compliance timelines and concentrates procurement authority within integrated delivery networks.
Growth Catalysts
- EU MDR Conformity Pathways:The Medical Device Regulation's classification of computational diagnostic algorithms as Class IIa/IIb devices is accelerating CE marking investment among European scanner OEMs and creating validated product differentiation.
- Cloud-Native Pathology Informatics:Health systems in the United States are migrating image archives to HIPAA-compliant cloud infrastructure, reducing on-premise storage capex and enabling multi-site diagnostic collaboration.
- AI-Enabled Workflow Automation:Machine learning algorithms for region-of-interest detection and biomarker quantification are compressing pathologist review time in high-volume clinical laboratories.
Market Restraints
- Capital Intensity of Scanner Hardware:High-throughput whole slide imaging systems require substantial upfront investment, constraining adoption among independent pathology practices and smaller hospital networks.
- Sensor Supply Concentration:Proprietary CMOS and CCD sensor architectures for sub-micron resolution scanning remain concentrated among Japanese and German component suppliers, creating input bottlenecks.
- Interoperability Friction:DICOM Whole Slide Imaging standard adoption remains uneven across vendor platforms, complicating multi-scanner deployments and data portability.
Strategic Opportunities
- Pharmaceutical Contract Research:Drug developers are expanding computational pathology partnerships for biomarker validation in immuno-oncology trials, creating high-margin service revenue streams.
- Decentralized Diagnostic Networks:Telepathology platforms enabling remote specialist consultation are penetrating rural and underserved regions within the United States.
- ISO 15189 Accreditation Tailwinds:Medical laboratory quality management mandates are disqualifying non-validated imaging platforms and consolidating demand around enterprise-grade vendors.
Industry Challenges
- Computational Pathology Talent Scarcity:The intersection of histopathology expertise and machine learning engineering remains undersupplied, lengthening algorithm development cycles.
- Legacy System Integration Complexity:Hospital information systems and laboratory information management platforms require costly middleware development to accommodate digital pathology data formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quantitative Pathology Imaging Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Slide Scanners, Image Analysis Software, Viewer Software, Accessories End User: Hospitals, Research Laboratories, Diagnostic Laboratories, Academic Institutions Technology: Whole Slide Imaging, Artificial Intelligence, Machine Learning, Cloud-Based Solutions Application: Cancer Diagnosis, Disease Research, Molecular Pathology, Education |
| Companies Covered | Leica Biosystems, Hamamatsu Photonics, Koninklijke Philips, Olympus Corporation, F. Hoffmann-La Roche, 3DHISTECH, Visiopharm, Mikroscan Technologies, Huron Technologies International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quantitative Pathology Imaging Market Evolving Landscape
Multiplexed imaging modalities and federated learning architectures are converging to transform quantitative pathology from static image capture into dynamic, AI-augmented diagnostic decision support.
Multiplex immunofluorescence and spatial transcriptomics platforms are expanding into routine clinical workflows, enabling simultaneous visualization of protein expression and RNA localization across tissue microenvironments. Academic medical centers in the United States and Germany are deploying these systems for precision oncology diagnostics. This capability expansion is compressing the timeline from tissue acquisition to actionable biomarker reporting.
FDA's evolving premarket review framework for machine learning-enabled diagnostic devices is elevating clinical validation requirements for algorithm developers. The agency's predetermined change control plans are forcing vendors to lock algorithm update protocols prior to clearance. High-risk pathology AI applications in cancer diagnosis face the steepest compliance burden, with developers responding through prospective clinical trials and real-world performance monitoring infrastructure.
Integrated delivery networks are consolidating scanner procurement under enterprise imaging contracts that bundle hardware, software licenses, and professional services. Health systems are displacing point solutions in favor of multi-departmental platforms serving radiology, cardiology, and pathology from unified data architectures. This concentration is most visible in the United States, where IDN mergers have reduced the number of independent purchasing entities by over one-third since 2020.
Quantitative Pathology Imaging Market Segmentation
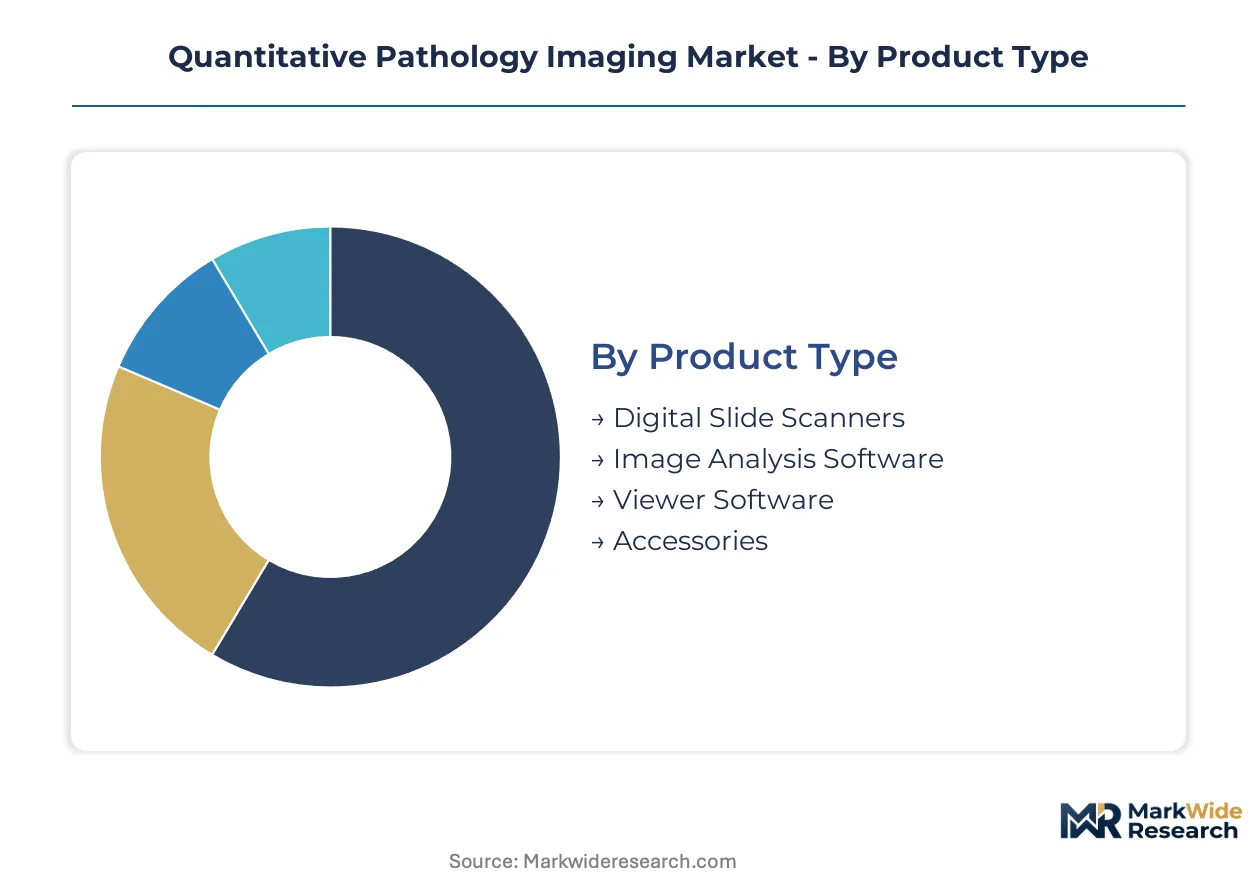
Quantitative pathology imaging segments reflect divergent capital deployment cycles and regulatory exposure across hardware, software, and service layers. Procurement patterns vary sharply between clinical diagnostic settings and research environments, with FDA software-as-medical-device oversight creating distinct compliance burdens by product category.
Product Type:
Capital intensity and replacement cadence separate institutional buyers from cost-constrained adopters across hardware and software tiers.
- Digital Slide Scanners:High-throughput whole slide imaging systems with sub-micron resolution sensors dominate hospital capital budgets. Demand concentrates in United States integrated delivery networks consolidating procurement under enterprise imaging contracts.
- Image Analysis Software:Algorithmic platforms for biomarker quantification and region-of-interest detection command recurring license structures with disproportionate margin contribution. FDA premarket review pathways for AI-enabled diagnostic tools are elevating validation investment among developers targeting clinical laboratories.
- Viewer Software:Visualization and annotation tools enable remote pathologist consultation across distributed diagnostic networks.
- Accessories:Slide loaders, calibration standards, and storage peripherals complete validated workflow configurations for ISO 15189-accredited laboratories.
Volume sits with Digital Slide Scanners; growth tilts toward Image Analysis Software.
End User:
Regulatory maturity and reimbursement pathways determine technology adoption velocity across clinical and non-clinical settings.
- Hospitals:Pathology departments within acute care facilities are consolidating around digital-first diagnostic workflows. United States health systems drive demand as IDN mergers compress vendor selection to multi-departmental enterprise platforms.
- Research Laboratories:Pharmaceutical contract research organizations deploy computational pathology for immuno-oncology biomarker validation. Academic medical centers in Germany and the United States are expanding multiplexed imaging capabilities for precision oncology studies.
- Diagnostic Laboratories:Independent reference labs face capital constraints from scanner hardware costs while competing for high-volume clinical contracts.
- Academic Institutions:Medical schools and teaching hospitals leverage digital pathology for resident education and remote specialist training programs.
Procurement authority concentrates in Hospitals; expansion rates are steepest in Research Laboratories.
Technology:
Integration architecture and data sovereignty requirements shape platform selection between on-premise and cloud-native deployments.
- Whole Slide Imaging:Calibrated scanner hardware producing standardized digital slide formats remains the foundational data capture layer. Japanese and German sensor suppliers maintain proprietary control over sub-micron resolution CMOS and CCD architectures.
- Artificial Intelligence:Predictive algorithms for cancer diagnosis and biomarker detection face the steepest FDA premarket compliance burden. Developers are locking algorithm update protocols through predetermined change control plans prior to clearance.
- Machine Learning:Pattern recognition systems for region-of-interest detection compress pathologist review time in high-volume clinical workflows.
- Cloud-Based Solutions:HIPAA-compliant image archives enable multi-site diagnostic collaboration while reducing on-premise storage capital expenditure for United States health systems.
Installed base concentrates in Whole Slide Imaging; capability investment flows fastest into Artificial Intelligence.
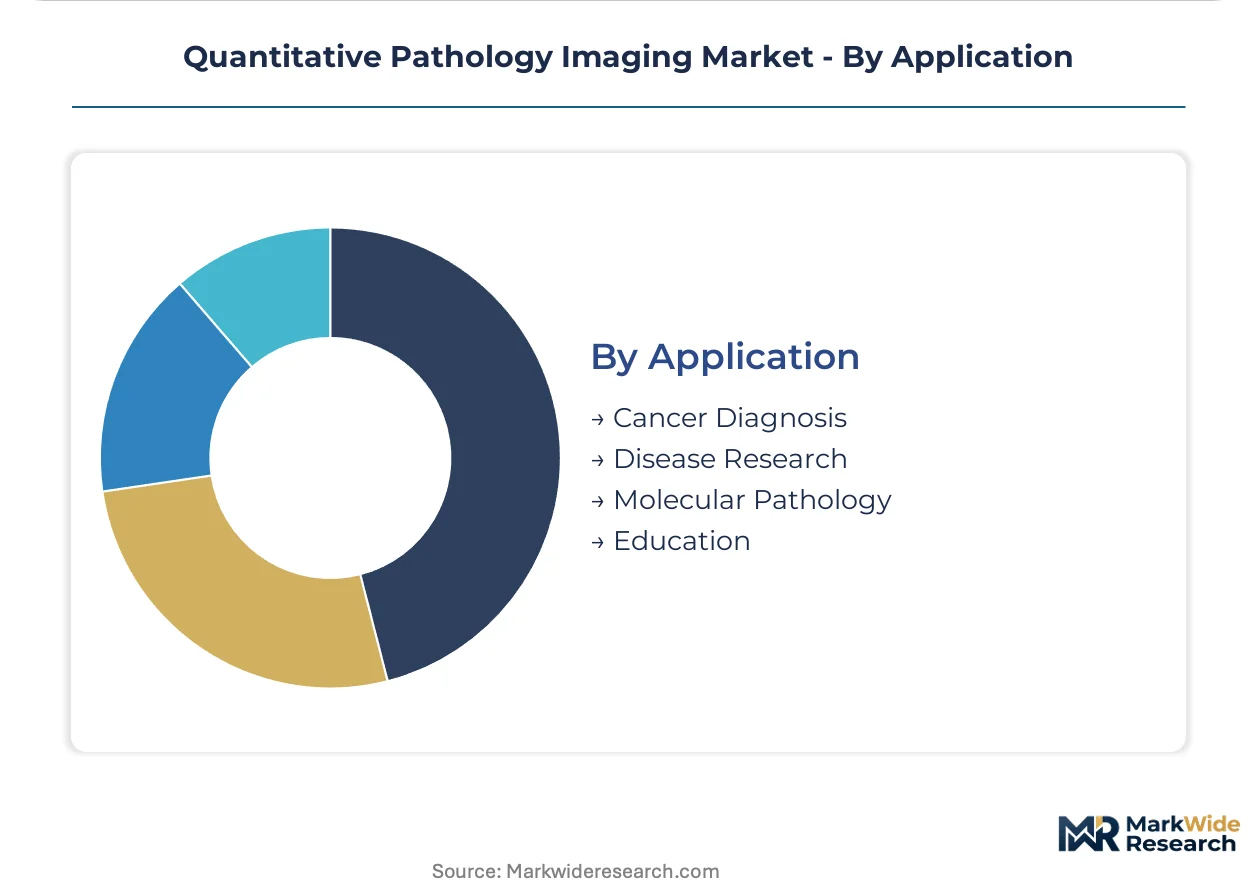
Application:
Reimbursement coding and clinical utility evidence separate commercially viable deployments from research-stage investigations.
- Cancer Diagnosis:Computational pathology for oncology applications commands the highest regulatory scrutiny and the largest addressable clinical volume. FDA enforcement of software-as-medical-device classifications is accelerating vendor investment in prospective clinical trials for high-risk diagnostic algorithms.
- Disease Research:Exploratory histopathological studies in academic and pharmaceutical settings generate demand for multiplexed imaging and spatial transcriptomics platforms. German research institutes are deploying these systems for tissue microenvironment analysis.
- Molecular Pathology:RNA and protein localization workflows require specialized fluorescence imaging capabilities with extended dynamic range.
- Education:Digital slide libraries and telepathology platforms support remote pathology training and specialist certification programs.
Revenue concentration rests with Cancer Diagnosis; capability expansion is most rapid in Disease Research.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon sensor fabrication concentrates in Japan and Germany, anchoring supply chains for sub-micron resolution imaging hardware. Clinical demand clusters in the United States, Germany, and Japan where integrated health systems and academic medical centers drive procurement. Regulatory divergence across FDA, EU MDR, and PMDA jurisdictions is fragmentating vendor compliance strategies.
United States
Integrated delivery networks in Texas, California, and the Northeast Corridor are consolidating pathology procurement under enterprise imaging contracts spanning radiology and cardiology. FDA software-as-medical-device enforcement is compressing vendor timelines for AI-enabled diagnostic algorithm clearance. The Boston-Cambridge cluster anchors pharmaceutical contract research demand for computational pathology in immuno-oncology trials.
Germany
Academic medical centers in Munich and Heidelberg are deploying multiplexed imaging and spatial transcriptomics for precision oncology diagnostics. EU MDR conformity requirements for Class IIa/IIb computational diagnostic algorithms are accelerating CE marking investment among scanner OEMs. The Baden-Württemberg industrial corridor sustains proprietary sensor architecture production for high-throughput whole slide systems.
Japan
Hamamatsu and Nagoya manufacturing clusters maintain captive production of proprietary CMOS and CCD sensors for sub-micron resolution scanning. PMDA premarket review pathways for machine learning-enabled medical devices are elevating clinical validation requirements for domestic algorithm developers. Tokyo-Osaka health systems are migrating image archives to cloud-native infrastructure under revised data sovereignty guidelines.
China
NMPA medical device classification rules for AI-enabled diagnostic software are creating compliance bottlenecks for multinational scanner vendors seeking market entry. Shanghai and Beijing academic hospitals are expanding digital pathology adoption for resident education and remote specialist consultation. Domestic sensor suppliers in Shenzhen are challenging Japanese and German component dominance in mid-tier scanner segments.
United Kingdom
NHS England pathology network consolidation is centralizing procurement authority for whole slide imaging platforms across regional diagnostic hubs. MHRA post-Brexit medical device regulations are diverging from EU MDR timelines, creating dual compliance burdens for vendors. The Cambridge-London corridor generates demand for research-grade multiplexed imaging in pharmaceutical biomarker validation partnerships.
Quantitative Pathology Imaging Market Competitive Landscape
Global majors compete with regional champions across scanner hardware and algorithmic software layers. The vendor base separates into three tiers: integrated imaging conglomerates with multi-departmental enterprise contracts, specialized scanner OEMs with proprietary sensor architectures, and algorithm developers pursuing FDA software-as-medical-device clearance. Strategic moves concentrate on cross-selling integrated digital pathology workflows and locking algorithm update protocols through predetermined change control plans.
Among diversified imaging conglomerates, Koninklijke Philips and F. Hoffmann-La Roche occupy positions bundling pathology informatics with broader enterprise health system contracts. Specialized scanner manufacturers include Leica Biosystems, Hamamatsu Photonics, and Olympus Corporation, with the first two representing archetypes of installed-base leverage and proprietary sensor technology respectively. Algorithm-focused developers such as Visiopharm and 3DHISTECH exemplify the compliance-intensive path toward clinical diagnostic deployment.
| Leading Market Players |
|---|
| Leica Biosystems |
| Hamamatsu Photonics |
| Koninklijke Philips |
| Olympus Corporation |
| F. Hoffmann-La Roche |
| 3DHISTECH |
| Visiopharm |
| Mikroscan Technologies |
| Huron Technologies International |
| Others |
Value Network & Pricing Analysis
Cloud-native pathology informatics migration is compressing total cost of ownership while redistributing margin pools from capital hardware toward recurring software licenses, concentrating pricing power among vendors with validated FDA clearance pathways.
Pricing Analysis
Extended warranty and professional service bundles separate enterprise-grade scanner contracts from unbundled equipment-only transactions. Three-tier pricing structure across premium, standard, and economy levels reflects FDA software-as-medical-device certification status and ISO 15189 accreditation compatibility. Cost compression in mid-tier scanner segments is intensifying because domestic sensor suppliers in China are challenging Japanese and German component dominance. Independent pathology practices exhibit highest price sensitivity, while United States integrated delivery networks prioritize total workflow integration over unit cost.
Supply Chain Analysis
Freight costs for precision optical components and calibrated sensor modules elevate landed costs for non-regional scanner assembly. Proprietary CMOS and CCD sensor architectures concentrate in Japan and Germany, with secondary component sourcing from South Korea and Taiwan. Raw material dependencies include rare-earth optical glass, high-purity silicon wafers, and precision stepper motors. Single-source vulnerability persists for sub-micron resolution sensor suppliers. Distribution runs through authorized dealer networks serving hospital procurement committees and laboratory capital equipment planners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quantitative pathology imaging sits in a technology-transition phase as AI-enabled diagnostic algorithms displace static image capture workflows, replacing legacy visual interpretation with computational decision support.
For Market Incumbents: Deepen proprietary sensor architecture control through captive production investments in Baden-Württemberg and Hamamatsu manufacturing clusters. Expand predetermined change control plan capabilities to lock algorithm update protocols ahead of FDA premarket review. Emerging algorithm developers with faster regulatory pathways threaten established scanner OEM margins. For New Entrants and Emerging Players: The price-point gap between premium enterprise contracts and economy-tier independent laboratory equipment creates white-space opportunity in mid-market diagnostic laboratories facing capital constraints. Telepathology platforms for rural United States regions and pharmaceutical contract research biomarker validation services offer penetrable entry vectors. Pursue cloud-native deployment models to bypass hardware-intensive capital barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified imaging conglomerates seeking algorithmic software capabilities. Long-term viability favors developers with locked FDA clearance protocols and installed base leverage through histology equipment cross-selling. Watch FDA premarket review timeline acceleration as the inflection signal for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Predetermined Change Control Plan Lock | FDA software-as-medical-device enforcement elevates algorithm update protocol rigidity for diagnostic clearance. |
| Enterprise Imaging Contract Bundling | Koninklijke Philips and F. Hoffmann-La Roche leverage multi-departmental health system relationships for pathology platform consolidation. |
| Proprietary Sensor Architecture Investment | Hamamatsu Photonics and German OEMs defend rapid scan speed leadership through captive CMOS and CCD production. |
| Pharmaceutical CRO Partnership Expansion | Immuno-oncology biomarker validation demand from Boston-Cambridge drug developers creates high-margin service revenue. |
| ISO 15189 Accreditation Alignment | Medical laboratory quality mandates disqualify non-validated platforms and consolidate demand around enterprise-grade vendors. |
Research Methodology
Multi-period observation of scanner procurement volumes, algorithm clearance timelines, and cloud migration patterns anchored the trend analysis, supplemented by interviews with pathology department directors, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at scanner OEMs. Secondary validation drew from FDA 510(k) and De Novo filings, EU MDR notified body documentation, hospital procurement databases, GPO contract disclosures, and CMS Medicare laboratory reimbursement data. Bottom-up unit economics triangulated against top-down health system capital expenditure patterns.
Input-output matrices modeled scanner hardware replacement cycles, software license renewal rates, and service contract attach ratios across product type, end user, technology, and application dimensions. CAGRs were derived from segmented growth rate differentials weighted by revenue concentration. Forecast inputs included FDA premarket review queue velocity, EU MDR CE marking investment flows, and integrated delivery network merger activity.
Inputs from regulatory filing databases and hospital procurement systems were available through the study window; gaps in real-time algorithm performance monitoring data introduce uncertainty bands around AI-enabled diagnostic adoption curves. Forecasts reflect documented assumptions regarding clearance timeline stability and reimbursement pathway evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
SPECT Scanning Services Market
Medical Imaging
Breast MRI Screening Market
Medical Imaging
Remanufactured Medical Imaging Devices Market
Medical Imaging
United States Computed Tomography Market
Medical Imaging
Global Picture Archiving Communications System Market
Medical Imaging
Specimen Radiography Systems Market
Medical Imaging
Global Veterinary X-Ray Market
Medical Imaging
United Kingdom Nuclear Imaging Market
Medical Imaging
Radiology As a Service Market
Medical Imaging
Perfusion Imaging Market
Medical Imaging
Brazil Digital Radiology Market
Medical Imaging
Europe Nuclear Imaging Devices Market
Medical Imaging
Digital X-Ray Imaging Market
Medical Imaging
United States Diagnostic Imaging Market
Medical Imaging
Dual and Multi-Energy Computed Tomography (CT) Market
Medical Imaging
Orthopedic Radiology Equipment Market