
 Interlock Vials Market | 2026-2036
Interlock Vials Market Size, Share, and Industry Trends Forecast 2026-2036
Interlock Vials Market Foresight
Glass is expanding its share in interlock vial construction as borosilicate formulations displace lower-grade soda-lime alternatives in parenteral packaging. Gerresheimer AG leverages its tubular glass expertise to anchor supply contracts with European biotechnology firms. Schott AG sustains technology leadership through FIOLAX borosilicate platforms optimized for autoclave resistance. West Pharmaceutical Services differentiates via integrated elastomer closure systems paired with its vial offerings.
Interlock vials are precision-molded containers featuring mechanically interlocking neck geometries that create tamper-evident, hermetic seals with matched closures, typically manufactured from Type I borosilicate glass or cyclic olefin polymers with dimensional tolerances below 0.1 millimeters to ensure syringeability and container closure integrity for sterile injectables. Glass vials dominate current volume due to regulatory familiarity and chemical inertness requirements for biologics, while plastic vials represent the fastest-growing product category as pharmaceutical sponsors adopt cyclic olefin polymer alternatives for protein-based therapies requiring reduced surface interaction. Small and medium sizes command the majority of revenue given the prevalence of single-dose biologic formulations, though large vials capture expanding share in cell and gene therapy applications requiring higher fill volumes.
FDA container closure integrity guidelines and EMA Annex 1 sterile manufacturing revisions compel pharmaceutical sponsors to validate interlock seal performance against microbial ingress and oxygen permeation thresholds. USP Chapter 1207 and ISO 11607-1 establish deterministic testing protocols that vial manufacturers must document for market access. Stakeholders should monitor evolving pharmacopeial standards for extractables and leachables, as these specifications will determine material substitution timelines and qualification costs across supplier portfolios.
Market Dynamics
FDA container closure integrity guidelines and EMA Annex 1 sterile manufacturing revisions are forcing pharmaceutical sponsors to requalify entire vial portfolios, compressing supplier selection timelines and elevating technical documentation burdens.
Growth Catalysts
- EMA Annex 1 revisions:Mandatory sterile manufacturing upgrades across European biologics facilities are accelerating replacement cycles for legacy vial-closure systems that cannot demonstrate validated seal integrity under revised protocols.
- Cell and gene therapy expansion:Higher fill-volume requirements in autologous cell therapies are pulling demand toward large-format interlock vials with enhanced dimensional stability.
- Borosilicate glass chemistry:Type I glass formulations with reduced alkali leachability are displacing soda-lime alternatives in parenteral applications where protein stability is critical.
Market Restraints
- Raw material concentration:High-purity borosilicate glass feedstock production concentrates in Germany and the United States, creating geographic supply vulnerability for Asian packaging converters.
- Qualification timeline friction:USP Chapter 1207 deterministic testing protocols require 18-24 month validation cycles that delay new supplier entry and lock incumbents into long-term contracts.
- Cyclic olefin polymer substitution:Plastic vial alternatives with reduced protein adsorption are capturing share in temperature-sensitive biologics, pressuring glass volume growth.
Strategic Opportunities
- India biologics manufacturing:CDSCO's expanding biosimilar approval pathways and PLI scheme incentives for domestic pharmaceutical packaging are creating demand for qualified interlock vial supply.
- Ready-to-use (RTU) format convergence:Pre-sterilized, pre-capped vial-nest configurations are enabling fill-finish line automation that reduces contamination risk and labor intensity.
- Single-use system integration:Interlock vials designed for seamless compatibility with disposable bioreactor and fluid transfer manifolds are capturing value in continuous manufacturing deployments.
Industry Challenges
- Container closure integrity validation:Demonstrating microbial ingress resistance across temperature cycling and transport stress conditions requires specialized metrology capabilities that contract manufacturers struggle to maintain in-house.
- Extractables and leachables documentation:Evolving pharmacopeial standards for glass delamination and elastomer additive migration are extending regulatory submission timelines and increasing analytical chemistry costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interlock Vials Market |
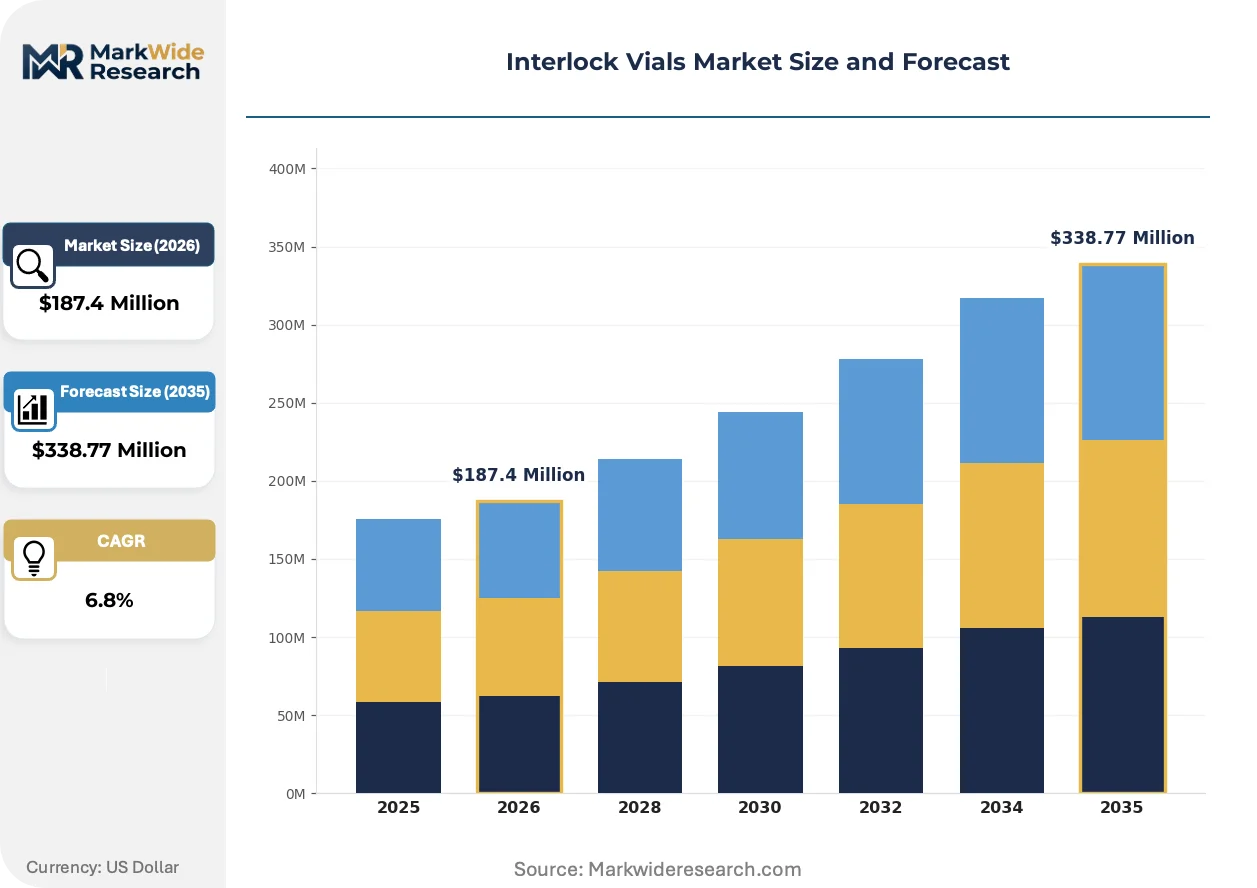
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Vials, Plastic Vials, Metal Vials, Composite Vials Size: Small, Medium, Large, Extra Large Closure System: Snap-on, Screw Cap, Dropper, Sealing End User: Pharmaceuticals, Biotechnology, Research Laboratories, Healthcare |
| Companies Covered | Gerresheimer AG, Schott AG, Berry Global, West Pharmaceutical Services, Nipro Pharma Packaging, SGD Pharma, Restek Corporation, J.G. Finneran Associates, Stevanato Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interlock Vials Market Shifts & Advancements
Precision molding technologies and integrated closure systems are compressing the traditional separation between primary container and delivery device manufacturing. Material science advances are enabling vial formats that reduce surface interaction with sensitive biologics.
Cyclic olefin polymer formulations are modularizing interlock vial construction by enabling thinner-walled, higher-clarity containers with reduced protein adsorption characteristics. Biologics manufacturers with temperature-sensitive portfolios are adopting these platforms for subcutaneous injection formulations. This material shift is compressing the historical glass dominance in parenteral packaging by creating functional differentiation around thermal and mechanical performance.
REACH regulatory expansions in the European Union are restricting certain elastomer curing agents and glass surface treatments used in legacy vial-closure combinations. Pharmaceutical sponsors must now requalify alternative formulations or face supply discontinuation. Small and medium-sized biotechnology firms without dedicated regulatory affairs capacity are outsourcing this compliance burden to full-service packaging suppliers.
Consolidated procurement through central laboratory services organizations is displacing direct purchasing relationships between biopharmaceutical developers and vial manufacturers. Large contract development and manufacturing organizations are negotiating multi-program supply agreements that lock in volume commitments and technical specifications. This channel concentration is most visible in the United States, where three major CDMOs control a significant share of commercial biologics fill-finish capacity.
Interlock Vials Market Segmentation
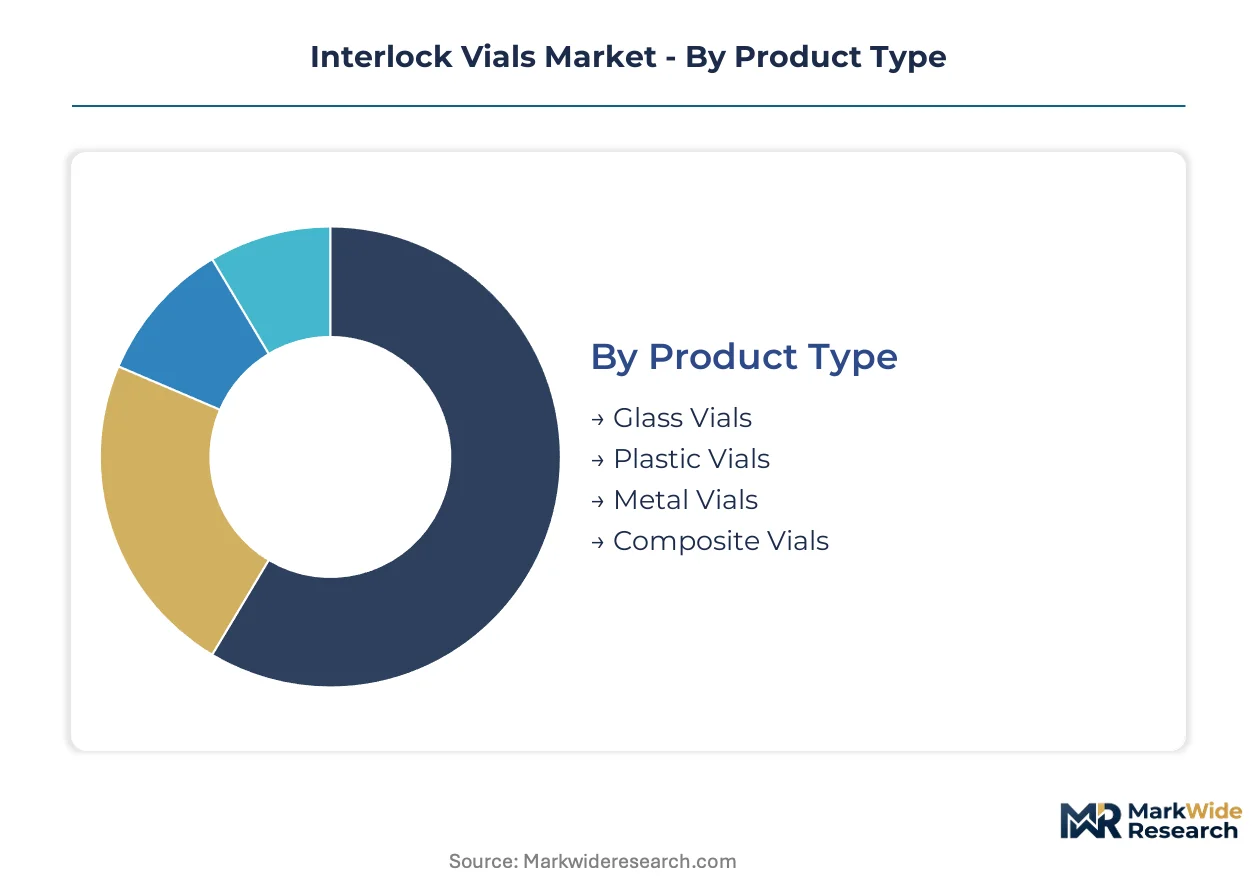
Interlock vial purchasing patterns diverge sharply between high-volume generic injectables and premium biologic containment, with material selection and closure geometry serving as the primary axes of supplier differentiation. Pharmaceutical sponsors structure procurement around validated container closure integrity rather than unit economics alone.
Product Type:
Glass dominates volume shipments while plastics command premium positioning in protein-based therapies.
- Glass Vials:Type I borosilicate formulations deliver chemical inertness and autoclave resistance required for parenteral biologics. Demand concentrates in Germany and the United States where Gerresheimer AG and West Pharmaceutical Services maintain tubular glass production. FDA container closure integrity guidelines compel sponsors to retain glass for high-value injectable portfolios despite longer lead times.
- Plastic Vials:Cyclic olefin polymer alternatives reduce protein adsorption and enable thinner-walled geometries for temperature-sensitive formulations. Biotechnology firms in Switzerland and Massachusetts are adopting these platforms for subcutaneous delivery systems where surface interaction minimization outweighs regulatory familiarity premiums.
- Metal Vials:Stainless steel containment for specialized radiopharmaceutical and diagnostic applications requiring magnetic shielding properties.
- Composite Vials:Hybrid constructions combining polymer barriers with structural reinforcement for niche cell therapy transport applications.
Today's leader: Glass Vials. Tomorrow's challenger: Plastic Vials.
Size:
Fill volume requirements track directly with therapeutic modality—single-dose biologics versus multi-dose cell therapies.
- Small:Sub-5mL formats for potent peptide and oligonucleotide injections where dosing precision limits fill tolerance.
- Medium:5-20mL standard for monoclonal antibody presentations; this tier captures the majority of commercial biologics revenue.
- Large:20-100mL configurations for cell therapy harvest volumes and extended-infusion oncology products. Autologous CAR-T manufacturing in Pennsylvania and Bavaria is pulling demand toward enhanced dimensional stability at this scale.
- Extra Large:Above 100mL for bulk API storage and specialized gene therapy vector containment.
Medium formats anchor current procurement; Large vials are climbing the fastest as cell therapy manufacturing scales.
Closure System:
Seal geometry determines automation compatibility and tamper-evidence strength across fill-finish line configurations.
- Snap-on:Rapid assembly for high-speed generic injectable production where throughput outweighs resealability.
- Screw Cap:Reversible closure for multi-dose vials in clinical trial settings and compounding pharmacies.
- Dropper:Integrated delivery for ophthalmic and nasal formulations requiring controlled dispensing.
- Sealing:Permanent crimped aluminum seals for commercial biologics where EMA Annex 1 sterile manufacturing revisions mandate validated hermetic integrity. West Pharmaceutical Services pairs these with elastomer formulations optimized for oxygen ingress resistance.
Sealing systems dominate commercial biologics; Screw Cap retains flexibility in research-phase procurement.
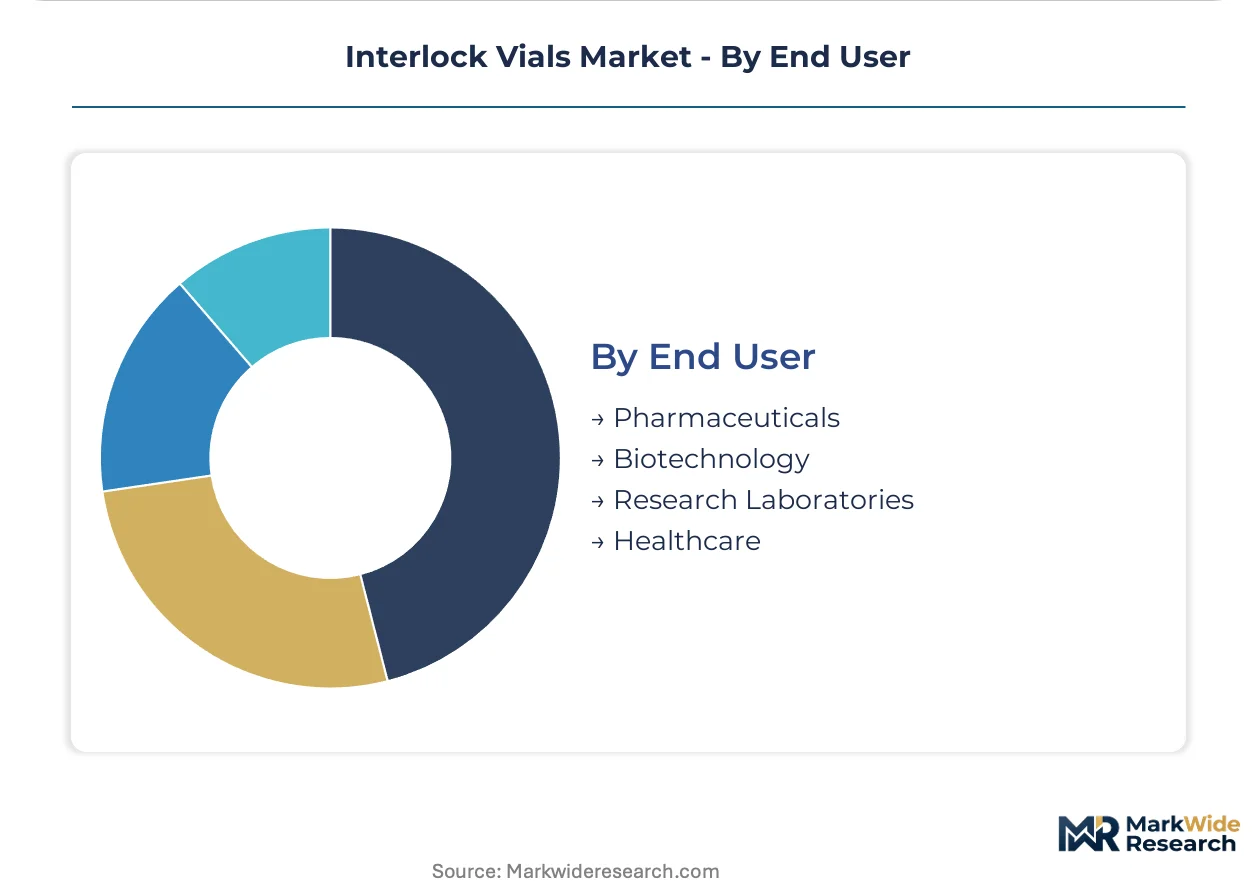
End User:
Regulatory burden intensity separates pharmaceutical sponsors from research-phase buyers.
- Pharmaceuticals:Large-scale manufacturers of small-molecule and biologic injectables. CDSCO's biosimilar approval pathways in India are expanding qualified supplier demand for this segment.
- Biotechnology:Development-stage firms and commercial cell therapy producers. REACH regulatory expansions in the European Union are forcing requalification of elastomer curing agents for this user category.
- Research Laboratories:Academic and CRO settings with lower validation requirements but higher SKU fragmentation.
- Healthcare:Hospital pharmacy and compounding operations purchasing through group purchasing organizations.
Pharmaceuticals drive volume standardization; Biotechnology is expanding most quickly as gene therapy programs advance to commercial scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Philadelphia-Wilmington biopharmaceutical corridor anchors North American interlock vial procurement through concentrated fill-finish capacity and proximity to FDA headquarters. Demand concentrates in jurisdictions with stringent container closure integrity mandates and established biologics manufacturing infrastructure.
United States
Massachusetts and Pennsylvania biotech clusters drive specification-setting for large-format vials in cell therapy applications. FDA container closure integrity guidelines compel sponsors to maintain validated supplier relationships through extended qualification cycles. Greater Boston hosts development-stage firms adopting cyclic olefin polymer alternatives for protein-based subcutaneous formulations.
Germany
Bavaria and North Rhine-Westphalia house tubular glass production facilities serving European biotechnology sponsors. EMA Annex 1 sterile manufacturing revisions accelerate replacement cycles for legacy vial-closure systems that fail validated seal integrity protocols. The Rhine-Main region concentrates elastomer formulation expertise for oxygen ingress-resistant closures.
India
Maharashtra and Gujarat pharmaceutical manufacturing zones expand qualified interlock vial demand through CDSCO biosimilar approval pathways. The PLI scheme for domestic pharmaceutical packaging incentivizes local converter investment in borosilicate glass processing. Hyderabad's vaccine production complex sources pre-sterilized vial-nest configurations for automated fill-finish lines.
Switzerland
Basel-area biologics manufacturers specify high-clarity vial formats for monoclonal antibody presentations requiring visual inspection compatibility. Swissmedic pharmacovigilance standards exceed baseline EMA requirements, extending analytical documentation burdens for extractables and leachables. The Lake Geneva corridor attracts specialized suppliers for temperature-sensitive biologics packaging.
Japan
Kanto region pharmaceutical sponsors adopt interlock vials for oncology and autoimmune biologics requiring hermetic integrity across distribution temperature excursions. PMDA quality management system inspections emphasize deterministic testing protocols aligned with USP Chapter 1207. Osaka-based packaging converters serve domestic generic injectable manufacturers with high-throughput snap-on closure systems.
Interlock Vials Market Competitive Landscape
Global majors compete with regional champions across regulatory qualification depth and material science specialization. The vendor base separates into three tiers: integrated primary packaging suppliers with captive glass production, specialized vial converters sourcing tubular feedstock, and polymer-focused entrants displacing glass in temperature-sensitive segments. Dominant competitive moves include backward integration into borosilicate glass melting capacity and strategic partnerships with contract development and manufacturing organizations for multi-program supply agreements.
Among Germany-based integrated suppliers, Gerresheimer AG and Schott AG exemplify the glass-centric archetype through tubular production expertise and FIOLAX platform chemistry. West Pharmaceutical Services occupies a differentiated position pairing vial offerings with integrated elastomer closure systems. These three entities anchor the premium tier where validated container closure integrity documentation commands procurement preference over unit economics.
| Leading Market Players |
|---|
| Gerresheimer AG |
| Schott AG |
| Berry Global |
| West Pharmaceutical Services |
| Nipro Pharma Packaging |
| SGD Pharma |
| Restek Corporation |
| J.G. Finneran Associates |
| Stevanato Group |
| Others |
Supply & Pricing Matrix
Precision glassblowing expertise concentrated in Bavaria and North Rhine-Westphalia creates labor-cost differentials that widen spreads between premium certified and standard-grade interlock vial tiers. Pharmaceutical sponsors absorb these premiums to secure validated container closure integrity documentation required by FDA and EMA protocols.
Pricing Analysis
Input-cost pass-through from high-purity borosilicate glass feedstock anchors contract-based long-term offtake agreements between tubular glass producers and biologics manufacturers. Price differentiation separates USP Chapter 1207-validated premium tiers from standard clinical-grade offerings, with certification level and volume scale as primary drivers. Pricing pressure stems from cyclic olefin polymer substitution in temperature-sensitive protein formulations, compressing glass volume premiums. Generic injectable manufacturers exhibit highest price sensitivity, while commercial biologics sponsors prioritize seal integrity validation over unit economics.
Supply Chain Analysis
Certification and qualification gating through USP Chapter 1207 deterministic testing protocols restricts supplier entry and concentrates validated production in Germany, the United States, and Switzerland. Raw material dependencies center on high-purity borosilicate glass feedstock, elastomer formulation expertise, and precision molding equipment. Single-source vulnerability from geographic concentration of tubular glass melting capacity creates exposure to energy cost volatility and trade restriction risk. Distribution runs through contract development and manufacturing organizations negotiating multi-program supply agreements that lock in technical specifications and volume commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The interlock vials market functions as a stable compounder, with tightening FDA and EMA container closure integrity mandates generating sustained replacement demand across biologics manufacturing infrastructure.
For Market Incumbents: Anticipate cyclic olefin polymer substitution pressure by deepening captive borosilicate glass melting capacity and securing long-term elastomer formulation partnerships. Lock CDMOs into multi-program supply agreements before qualification timeline friction delays competitor entry. Prioritize investment in ready-to-use format capabilities to capture fill-finish line automation demand. For New Entrants and Emerging Players: Contract development and manufacturing organizations represent the most accessible channel for qualified supplier penetration without bearing full USP Chapter 1207 validation burden. Target India's expanding biosimilar manufacturing base through CDSCO pathway alignment and PLI scheme qualification. White-space exists in pre-sterilized vial-nest configurations for cell therapy applications requiring enhanced dimensional stability at large formats. For Investors and Strategic Acquirers: Pharmaceutical packaging conglomerates are the most active acquirer in this space, seeking validated supplier relationships to anchor biologics containment portfolios. Five-to-ten year viability rests on regulatory qualification depth rather than manufacturing scale alone. Watch for EMA Annex 1 enforcement acceleration as inflection indicator for replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Glass Melting | Gerresheimer AG and Schott AG secure captive feedstock supply against raw material concentration risk. |
| Ready-to-Use Format Development | Pre-sterilized vial-nest configurations enable fill-finish automation that reduces contamination risk. |
| Elastomer Closure System Integration | West Pharmaceutical Services pairs validated seal geometries with oxygen ingress-resistant formulations. |
| CDSCO Pathway Alignment for India Market | PLI scheme incentives attract domestic pharmaceutical packaging investment in Maharashtra and Gujarat. |
| Cyclic Olefin Polymer Platform Expansion | Biotechnology firms in Massachusetts adopt reduced-protein-adsorption alternatives for subcutaneous delivery. |
Research Methodology
Bottom-up biologics manufacturing demand modeling reconciled against top-down tubular glass production tracking forms the analytical core of this study. Primary interviews with regulatory affairs leads, fill-finish operations directors, CDMO procurement managers, and elastomer formulation scientists combined with secondary validation against FDA 483 inspection observations, EMA Annex 1 revision commentaries, USP Chapter 1207 guidance documents, and pharmaceutical packaging trade association statistics. Triangulation between sponsor-level demand signals and converter capacity disclosures ensures cross-verified volume and value estimates.
Input-output matrices mapping Type I borosilicate glass feedstock availability to vial conversion capacity and closure system integration yield segment-level projections across the analysis window. Segmentation dimensions include material chemistry, fill volume tier, closure geometry, therapeutic modality, and regional regulatory cluster. CAGRs derive from fitted growth curves against qualification timeline constraints and replacement cycle patterns. Forecast inputs incorporate EMA Annex 1 implementation pace and CDSCO biosimilar approval velocity as demand drivers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to cyclic olefin polymer substitution rates and REACH regulatory expansion scope. Model assumptions reflect documented qualification timelines, validated supplier concentration, and pharmacopeial standard evolution trajectories. A model refresh is warranted upon material change in FDA container closure integrity enforcement posture or EMA Annex 1 revision implementation deadlines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Vial Adaptors for Reconstitution Drug Market
Pharmaceutical Equipment
Europe Formulation Development Outsourcing Market
Pharmaceutical Equipment
Asia-Pacific Pharmacy Automation Market
Pharmaceutical Equipment
Global Pharmaceutical Contract Manufacturing and Contract Research Market
Pharmaceutical Equipment
Asia-Pacific Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Pharmaceutical Stability and Storage Services Market
Pharmaceutical Equipment
Closed Funnel Ampoules Market
Pharmaceutical Equipment
Pharmaceutical Continuous Manufacturing Market
Pharmaceutical Equipment
Pharmaceutical Storage and Material Handling Equipment Market
Pharmaceutical Equipment
Sterile Injectable Contract Manufacturing Market
Pharmaceutical Equipment
Radiochemical Synthesizers Market
Pharmaceutical Equipment
Asia-Pacific CDMO Market
Pharmaceutical Equipment
Pharmaceutical Equipment Testing Market
Pharmaceutical Equipment
Pharmaceutical Filtration Market
Pharmaceutical Equipment
Pharmaceutical Incubators Market
Pharmaceutical Equipment
North America Pharmaceutical Isolator Market