
 Medical Mobility Aid Market | 2026-2036
Medical Mobility Aid Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Mobility Aid Market Foresight
Buyer concentration among home care agencies and long-term care networks is realigning procurement leverage toward larger distributors. Invacare Corporation leverages its North American manufacturing footprint to sustain institutional contracts. Sunrise Medical anchors European demand through specialized seating and positioning systems. Permobil competes on premium powered mobility with advanced suspension and control technologies.
Medical mobility aids encompass wheeled and ambulatory assistive devices engineered to transport or support individuals with impaired gait, balance, or endurance, typically fabricated from aluminum tubing, carbon fiber composites, or high-impact polymers and rated for specific load capacities and terrain grades. Their primary commercial purpose is to restore functional independence and reduce caregiver burden across acute, post-acute, and community settings. Wheelchairs and walkers command the largest revenue pools, while smart technology variants with sensor-integrated feedback represent the fastest-expanding margin segment. Electric mobility systems carry premium positioning due to battery and motor subsystem complexity, whereas manual devices dominate volume through lightweight aluminum construction.
FDA 510(k) clearance requirements, EU MDR conformity assessment, and ISO 7176 technical standards collectively govern product safety, electromagnetic compatibility, and clinical performance claims for mobility devices. These frameworks elevate engineering costs for market entry while creating compliance-based differentiation among established manufacturers. Stakeholders must monitor reimbursement code revisions and durability testing protocols as gatekeepers for category expansion.
Market Dynamics
Reimbursement code compression is forcing manufacturers to absorb clinical validation costs while home care networks consolidate purchasing power through group procurement organizations.
Growth Catalysts
- Aging-in-place mandates:CMS Medicare Advantage supplemental benefits in the US now cover powered mobility for home-bound beneficiaries, expanding addressable demand beyond institutional settings.
- ISO 7176 durability testing:Standardized performance benchmarks enable cross-border tender participation, reducing market fragmentation for certified manufacturers.
- Lithium-ion battery chemistry:Energy density improvements extend electric wheelchair range above 25 kilometers, satisfying community mobility requirements without overnight charging infrastructure.
Market Restraints
- Aluminum alloy price volatility:Manual wheelchair frame costs fluctuate with London Metal Exchange pricing, compressing margin on high-volume SKUs.
- EU MDR conformity assessment:Notified body bottlenecks extend Class II device approval timelines to 18-24 months, freezing pipeline launches for mid-tier manufacturers.
- Refurbished device circulation:Secondary markets in Eastern Europe absorb price-sensitive demand, cannibalizing new equipment sales in adjacent geographies.
Strategic Opportunities
- German DiPA digitization incentive:The Digitale Pflegeanwendungen program subsidizes sensor-integrated mobility aids for outpatient care, creating reimbursement precedent.
- Telehealth-integrated diagnostics:Remote pressure mapping and gait analysis enable pre-authorized custom seating configurations without clinical site visits.
- Rental-subscription hybrid models:Post-acute facilities in the Netherlands pilot outcome-based device leasing tied to functional recovery milestones.
Industry Challenges
- Seating and positioning specialist scarcity:Certified ATP (Assistive Technology Professional) credential holders concentrate in urban hospital systems, leaving rural service gaps.
- Legacy ERP integration:Durable medical equipment distributors struggle to reconcile FDA UDI tracking requirements with 1990s-era inventory systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Mobility Aid Market |
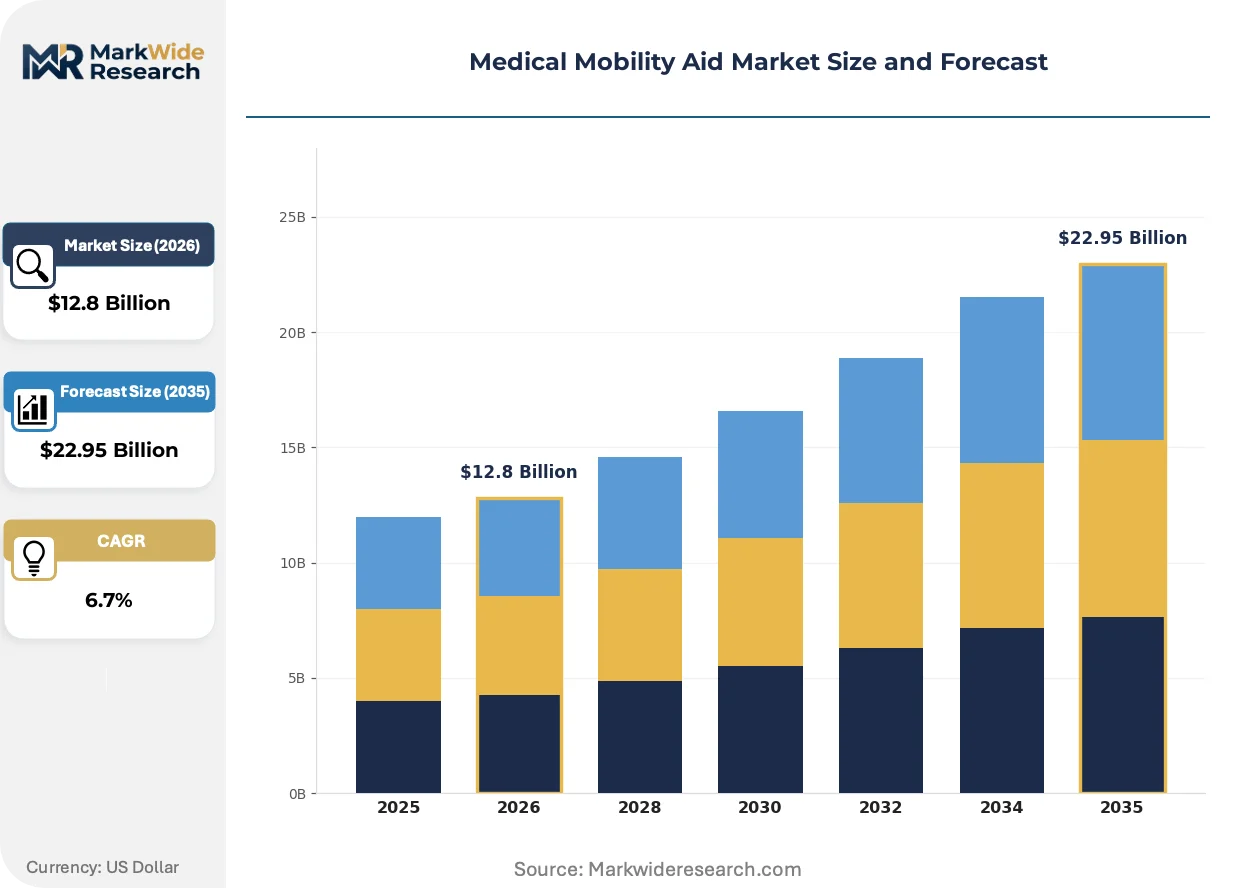
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wheelchairs, Walkers, Canes, Crutches End User: Hospitals, Rehabilitation Centers, Home Care, Elderly Care Technology: Manual, Electric, Smart, Hybrid Material: Aluminum, Steel, Plastic, Carbon Fiber |
| Companies Covered | Invacare Corporation, Sunrise Medical, Permobil, Ottobock, Pride Mobility Products, Drive DeVilbiss Healthcare, Medline Industries, GF Health Products, NOVA Medical Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Mobility Aid Market Shifts & Advancements
Sensor fusion and predictive maintenance algorithms are migrating from industrial automation into personal mobility, redefining device lifecycle economics and service attachment rates.
Carbon fiber monocoque frames are consolidating high-performance manual wheelchair construction. Paralympic athletes and active daily users drive adoption despite 40% price premiums over aluminum. The material shift is compressing repair revenue pools as frame fatigue failure rates decline.
EU MDR post-market surveillance requirements now mandate systematic complaint trending and PMCF (Post-Market Clinical Follow-up) studies for Class II mobility devices. Manufacturers must maintain clinical evidence registries or risk certificate suspension. German notified bodies lead enforcement, pressuring smaller OEMs to outsource quality management.
Hospital-at-home programs are fragmenting traditional durable medical equipment channels. Health systems in the US and UK now contract directly with manufacturers for episode-based device provisioning, bypassing regional distributors. This disintermediation concentrates volume with suppliers offering logistics integration and clinical training bundles.
Medical Mobility Aid Market Segmentation
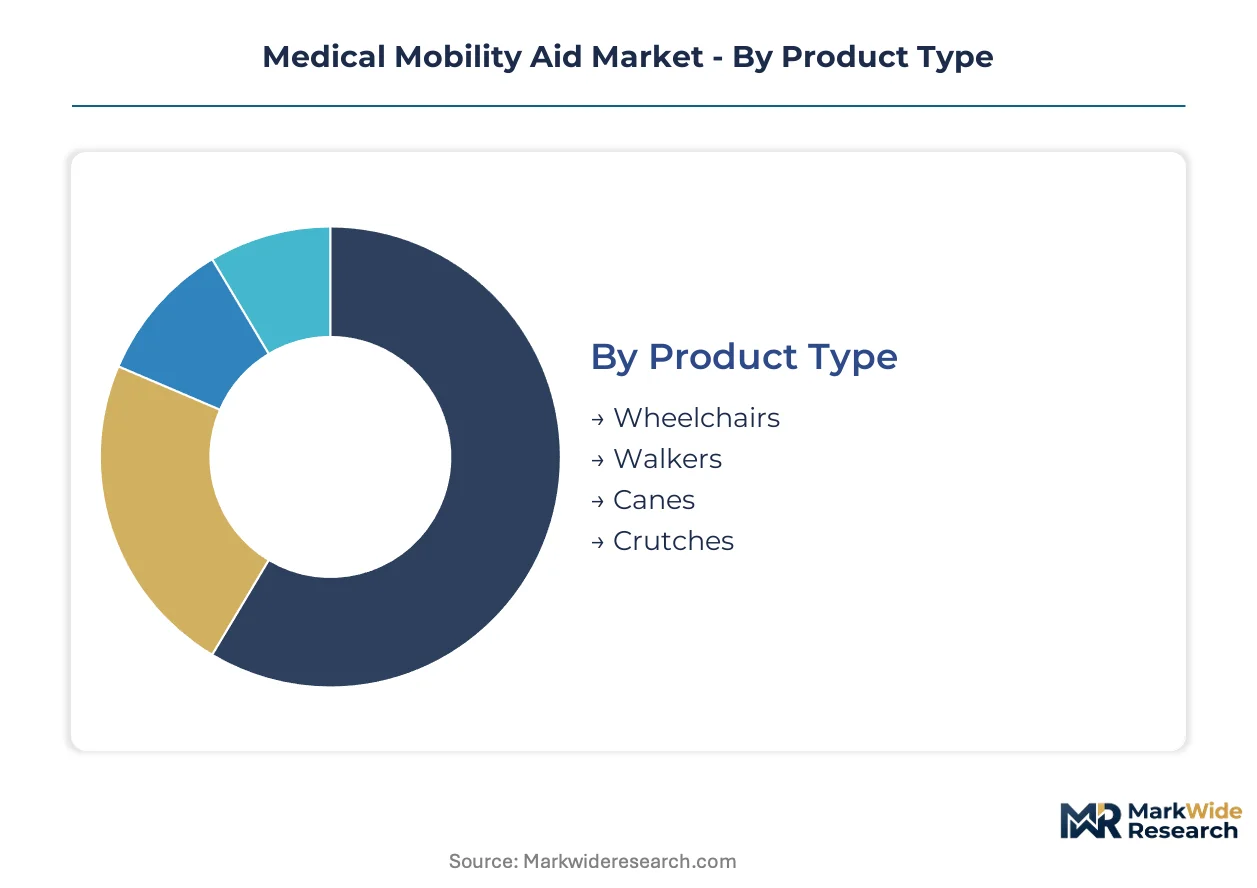
Segmentation in medical mobility aids reveals how reimbursement frameworks, material science advances, and care setting migration reshape procurement patterns. Each axis—product configuration, user environment, propulsion technology, and construction material—carries distinct margin profiles and regulatory exposure that manufacturers must navigate.
Product Type:
Frame geometry and load-bearing architecture differentiate commercial positioning across ambulatory and seated mobility categories.
- Wheelchairs:Seated mobility systems span manual folding frames to powered base units with programmable drive controls. CMS Medicare Advantage supplemental benefits in the US now cover powered configurations for home-bound beneficiaries, expanding addressable demand beyond institutional procurement.
- Walkers:Ambulatory support frames with two- or four-wheel configurations incorporate height-adjustable aluminum tubing rated for specific load capacities. German outpatient care networks concentrate procurement of rollator variants with seat and storage integration under DiPA digitization incentives.
- Canes:Single-point balance aids fabricated from aluminum or carbon fiber composites address gait instability in community-dwelling populations.
- Crutches:Axillary and forearm variants provide temporary weight-bearing relief during post-acute recovery protocols.
Mature deployment sits with wheelchairs. Newer deployment is concentrated in walkers with sensor-integrated variants.
End User:
Care setting economics determine device specification tiers and service attachment rates.
- Hospitals:Acute care facilities prioritize bariatric-rated frames and rapid-sanitization surfaces for short-stay patient transport. Episode-based device provisioning contracts in US and UK health systems now bypass regional distributors, concentrating volume with logistics-integrated suppliers.
- Home Care:Community-based providers source lightweight manual devices and powered mobility for aging-in-place beneficiaries. Reimbursement code compression forces manufacturers to absorb clinical validation costs while group procurement organizations consolidate purchasing leverage.
- Rehabilitation Centers:Post-acute facilities demand adjustable seating systems and gait training equipment for functional recovery protocols.
- Elderly Care:Long-term care networks balance durability requirements with fall-prevention specifications in residential settings.
Volume concentration rests with hospitals. Margin expansion is climbing the fastest in home care networks.
Technology:
Propulsion and control architectures stratify across energy density, maintenance burden, and user autonomy spectra.
- Electric:Battery-powered base units with brushless motor subsystems and programmable drive profiles extend community mobility range above 25 kilometers. Lithium-ion chemistry improvements satisfy daily use without overnight charging infrastructure.
- Smart:Sensor-integrated platforms with pressure mapping, predictive maintenance algorithms, and telehealth connectivity redefine lifecycle economics. German DiPA subsidies specifically target these configurations for outpatient digitization.
- Manual:Human-propelled frames dominate unit volume through lightweight aluminum construction and minimal maintenance requirements.
- Hybrid:Dual-mode systems combining manual propulsion with electric assist address terrain variability and user fatigue.
Installed base dominance belongs to manual systems. Steepest expansion trajectory is gaining share fastest in smart technology variants.
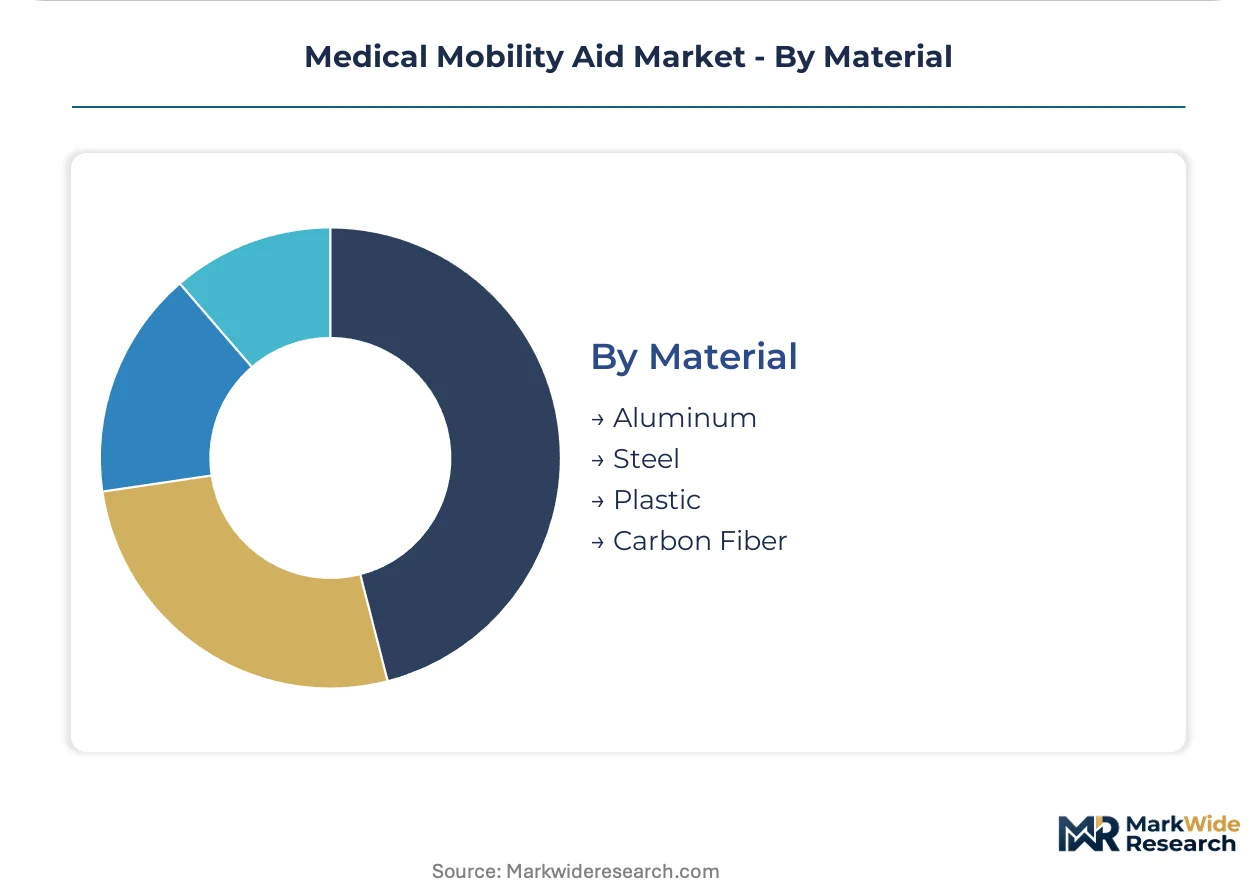
Material:
Construction substrate selection trades off weight reduction, fatigue resistance, and cost structure against reimbursement ceilings.
- Aluminum:6061-T6 alloy tubing dominates manual wheelchair and walker fabrication, though London Metal Exchange price volatility compresses margin on high-volume SKUs.
- Carbon Fiber:Monocoque frame construction consolidates high-performance manual wheelchair segments despite 40% price premiums over aluminum. Paralympic athletes and active daily users drive adoption as frame fatigue failure rates decline.
- Steel:Chromoly and mild steel variants serve institutional bariatric applications and cost-sensitive procurement tiers.
- Plastic:High-impact polymers form handgrips, seat shells, and accessory components with mold-cycle cost advantages.
Volume manufacturing anchors with aluminum. Technology migration is accelerating most quickly toward carbon fiber in performance segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum alloy supply from Chinese smelters and German precision manufacturing clusters anchor production geography for medical mobility aids. Battery cell assembly in South Korea and Japan feeds electric propulsion demand. Regulatory divergence between FDA clearance pathways and EU MDR conformity assessment shapes competitive access.
United States
CMS Medicare Advantage supplemental benefits now cover powered mobility for home-bound beneficiaries, expanding addressable demand beyond institutional procurement. FDA 510(k) clearance requirements for Class II devices elevate engineering costs for market entry. North Carolina and Ohio host durable medical equipment distribution clusters serving hospital-at-home programs.
Germany
The Digitale Pflegeanwendungen program subsidizes sensor-integrated mobility aids for outpatient care, creating reimbursement precedent for smart technology variants. EU MDR post-market surveillance mandates systematic complaint trending through German notified bodies. Reutlingen and Berlin concentrate seating and positioning specialist networks serving long-term care digitization.
Japan
Super-aged society demographics drive procurement of lightweight manual devices and powered mobility for community-dwelling elderly. METI standards for lithium-ion battery safety govern electric wheelchair import certification. Osaka and Nagoya anchor precision motor and control subsystem manufacturing for regional supply.
United Kingdom
NHS England episode-based device provisioning contracts now bypass regional distributors, concentrating volume with logistics-integrated suppliers. MHRA alignment with EU MDR technical standards maintains cross-border tender participation for certified manufacturers. West Midlands hosts rehabilitation equipment distribution networks serving hospital-at-home expansion.
China
NMPA Class II medical device registration requirements tighten compliance timelines for domestic and imported mobility products. Dual carbon goals accelerate lithium-ion battery chemistry investment for electric mobility range extension. Jiangsu and Zhejiang provinces concentrate aluminum tubing fabrication and carbon fiber composite processing for export manufacturing.
Medical Mobility Aid Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue sensor-integrated smart technology and rental-subscription hybrid models. The vendor base stratifies across three tiers: multinational institutional suppliers with North American manufacturing footprints, European specialists in seating and positioning systems, and Asian fabricators serving cost-sensitive procurement. Competitive moves center on M&A for distribution network consolidation and vertical integration into battery and motor subsystems to capture electric mobility margins.
Within the premium-powered tier, Permobil exemplifies advanced suspension and control technology positioning. Among North American institutional suppliers, Invacare Corporation anchors durable medical equipment distribution through manufacturing footprint scale. Sunrise Medical occupies a specialist position in European demand through seating and positioning system concentration. These three represent distinct competitive archetypes: technology-premium, scale-driven institutional, and European clinical-specialist.
| Leading Market Players |
|---|
| Invacare Corporation |
| Sunrise Medical |
| Permobil |
| Ottobock |
| Pride Mobility Products |
| Drive DeVilbiss Healthcare |
| Medline Industries |
| GF Health Products |
| NOVA Medical Products |
| Others |
Supply & Pricing Matrix
Captive battery and motor subsystem production anchors pricing power for electric mobility specialists while compressing margin exposure to lithium-ion commodity swings. Outsourced aluminum tubing fabrication for manual frames leaves manufacturers tethered to London Metal Exchange volatility, eroding price-setting leverage on high-volume SKUs.
Pricing Analysis
Service bundling separates premium powered mobility from unbundled manual frame procurement, with extended warranty and ATP seating support commanding 15-25% price premiums. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and customization depth. Cost compression in manual aluminum frames is intensifying because group procurement organizations consolidate hospital-at-home purchasing leverage. Home care networks exhibit highest price sensitivity, while rehabilitation centers tolerate premium positioning for adjustable seating systems.
Supply Chain Analysis
Reverse-logistics flows for refurbished device refurbishment and component recovery channel secondary market supply into Eastern Europe, cannibalizing new equipment sales in adjacent geographies. Component assembly draws from China, Germany, and South Korea for aluminum smelting, precision manufacturing clusters, and battery cell production respectively. Raw material dependencies rest on 6061-T6 aluminum alloy, lithium-ion cathode chemistry, and carbon fiber prepreg. Single-source vulnerability concentrates in German notified body certification capacity. Distribution runs through durable medical equipment distributors reconciling FDA UDI tracking with legacy ERP systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR conformity assessment bottlenecks and reimbursement code compression are forcing weaker players toward exit or acquisition, consolidating viable vendor count. Surviving participants must secure notified body relationships and captive subsystem supply.
For Market Incumbents: Deepen backward integration into battery and motor subsystems to capture electric mobility margins and insulate against Korean cell supplier pricing power. Fortify German notified body relationships to preempt certificate suspension under PMCF study mandates. Defend institutional contract volume through logistics integration and clinical training bundles that hospital-at-home programs now require. For New Entrants and Emerging Players: Launch via rental-subscription hybrid models in Dutch post-acute facilities piloting outcome-based device leasing tied to functional recovery milestones. Target sensor-integrated walker variants under German DiPA digitization incentives where reimbursement precedent exists. Penetrate rural home care networks where ATP seating specialist scarcity leaves service gaps unaddressed by urban hospital system incumbents. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multinational institutional suppliers seeking European seating and positioning capabilities. Five-to-ten year viability hinges on MDR certificate maintenance and DiPA reimbursement capture. Acquisition targets should display captive subsystem supply or certified quality management outsourcing relationships. Monitor German notified body enforcement intensity as inflection indicator for certificate suspension risk.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessment through German notified bodies enables cross-border tender participation. |
| Hospital System Partnership | Episode-based device provisioning contracts in NHS England and US health systems bypass regional distributors. |
| Software Companion Development | Telehealth-integrated pressure mapping and gait analysis enables pre-authorized custom seating configurations. |
| Reimbursement Strategy | DiPA digitization incentive targeting in Germany creates subsidy precedent for sensor-integrated variants. |
| Backward Integration | In-house production of battery and motor subsystems captures electric mobility margins and reduces supplier pricing exposure. |
Research Methodology
Document review covered FDA 510(k) clearance databases, EU MDR notified body registers, CMS Medicare reimbursement code revisions, and German DiPA program documentation, complemented by interviews with durable medical equipment procurement directors, ATP seating specialists, GPO contracts managers, and biomedical engineers. Secondary validation drew from ISO 7176 technical standards, hospital procurement databases, and aluminum trade flow data. Bottom-up unit demand modeling and top-down market sizing triangulated volume estimates.
Segment-level projections across product configuration, propulsion technology, care setting, and construction material dimensions fed aggregate market value outputs over the projection horizon. CAGRs were derived from regression analysis against aging demographic trajectories and reimbursement policy shift timelines. Forecast inputs incorporated lithium-ion energy density improvement curves and notified body capacity constraints.
Regulatory enforcement intensity, aluminum alloy price volatility, and reimbursement code compression are the dominant revision risks to baseline projections. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Electric Heated Eye Mask Market
Medical Devices
Implantable Drug Eluting Devices Market
Medical Devices
Canada Ultrasound Devices Market
Medical Devices
Incubator Devices Market
Medical Devices
Self-Sampling Blood Collection and Storage Devices Market
Medical Devices
Pocket Ventilation Systems Market
Medical Devices
Spine Positioning Devices Market
Medical Devices
Peri-Implantitis Market
Medical Devices
Microneedling Cartridges Market
Medical Devices
Kidney Stone Management Devices Market
Medical Devices
Intravenous Stopcock Market
Medical Devices
Spinal Non-Fusion Technologies Market
Medical Devices
Positive Air Pressure Devices Market
Medical Devices
Lactation Massager Market
Medical Devices
Pressotherapy Systems Market
Medical Devices
Speech Generating Devices Market