
 Digital BTE Market | 2026-2036
Digital BTE Market Size, Share, and Industry Trends Forecast 2026-2036
Digital BTE Market Insights
Geriatric patients are redrawing demand patterns in the Digital BTE Market as aging populations in developed economies seek programmable, connected hearing solutions. Sonova leverages its audiology clinic network to sustain direct-to-patient channel control across European markets. WS Audiology anchors its position through R&D intensity in rechargeable battery architectures. Demant A/S competes by specializing in pediatric fitting protocols that differentiate its clinical brand.
Digital BTE (Behind-the-Ear) hearing instruments house microphones, amplifiers, and digital signal processors in a compact casing worn behind the pinna, with sound delivered via tubing or thin wire to an earpiece; these devices process audio through multi-channel compression algorithms to restore speech intelligibility for sensorineural hearing loss. Receiver-in-Canal configurations now lead volume shipments due to their acoustic advantages in high-frequency amplification. Bluetooth-enabled models represent the fastest-growing technology segment as smartphone integration becomes standard. Artificial Intelligence integration sits at the premium margin pool, where adaptive noise classification commands price premiums.
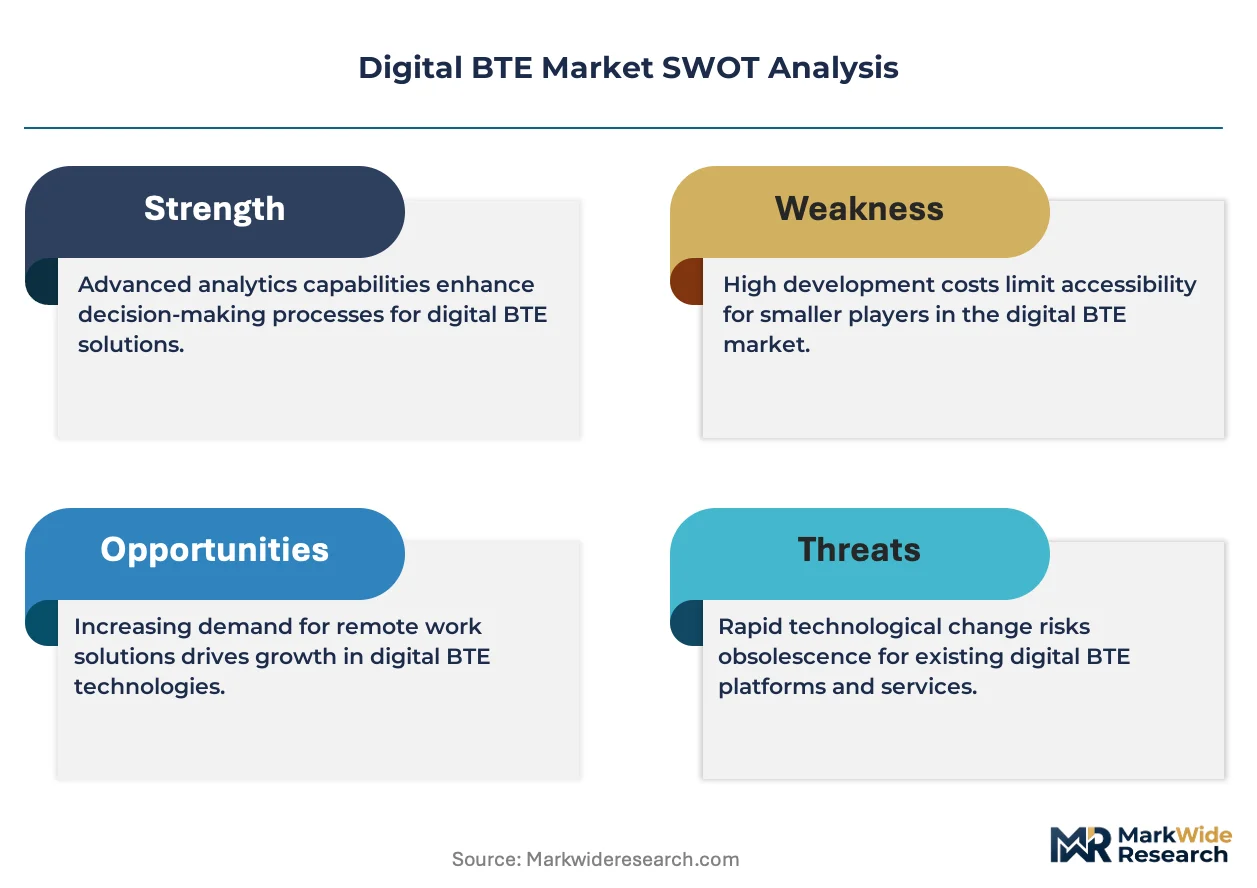
FDA 510(k) clearance requirements and CE marking under the EU Medical Device Regulation shape product development timelines and market access conditions for manufacturers. The FCC governs wireless transmission protocols for Bluetooth and telehealth connectivity in US-sold devices. EMA-aligned notified bodies enforce clinical evidence standards that determine which digital BTE platforms gain European commercial authorization. Stakeholders must monitor regulatory divergence between FDA software-as-medical-device guidance and EU AI Act risk classifications for algorithmic hearing aids.
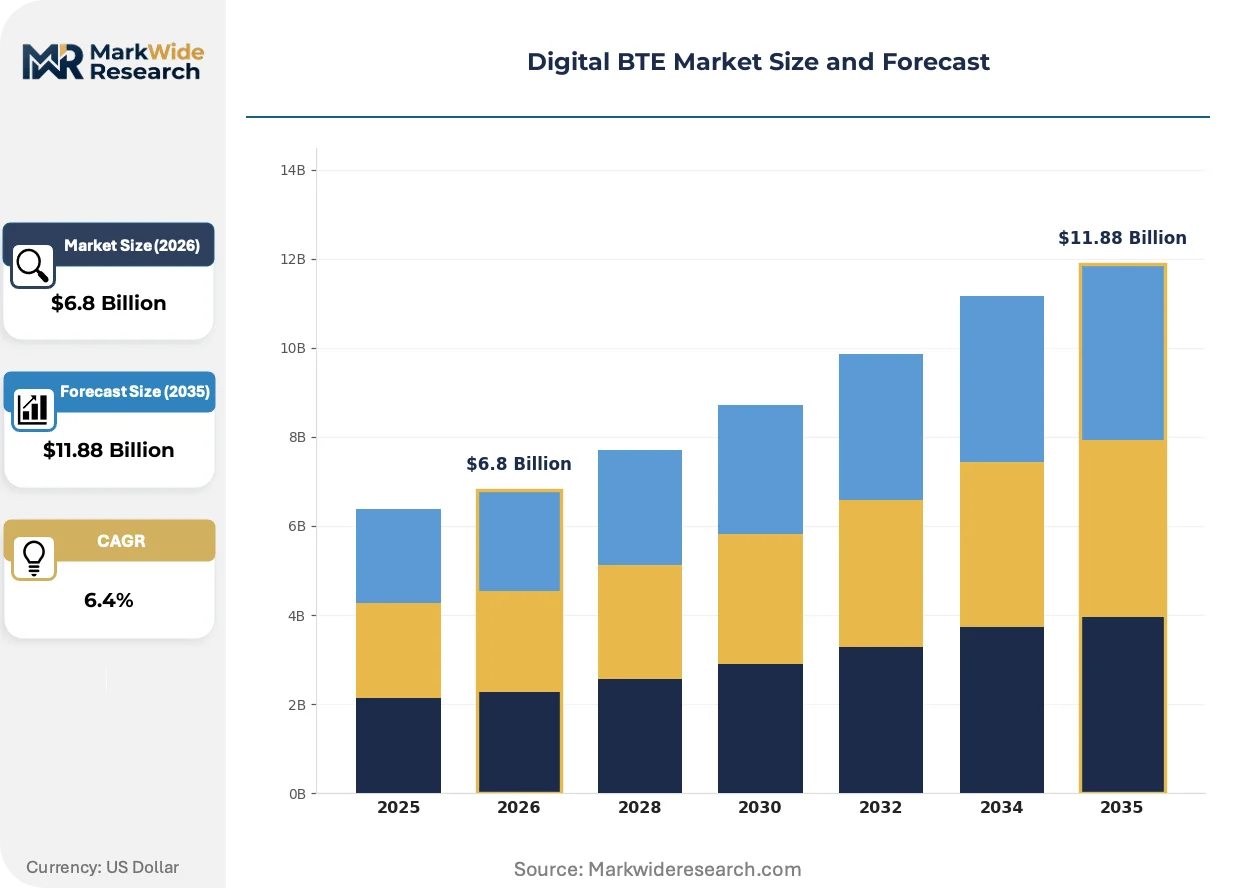
Market Dynamics
Bluetooth Low Energy and Auracast broadcast audio are compressing traditional telecoil infrastructure while FDA software-as-medical-device guidance accelerates algorithmic hearing aid approvals. These forces are restructuring how manufacturers allocate R&D capital and which channel partners control patient access.
Growth Catalysts
- FDA OTC Hearing Aid Rule:The 2022 over-the-counter classification unlocks direct-to-consumer channels, expanding addressable populations beyond clinical fitting workflows.
- Silver Economy Expansion:Japan, Germany, and the United States concentrate the fastest-aging demographic cohorts, generating concentrated demand for programmable amplification.
- Rechargeable Lithium-Ion Architectures:Elimination of zinc-air battery dependence reduces lifetime cost burden and improves water-resistance ratings for active users.
Market Restraints
- Semiconductor Supply Concentration:Taiwan and South Korea dominate MEMS microphone and DSP chip fabrication, creating single-source vulnerability for multi-channel compression engines.
- Clinical Fitting Bottleneck:Audiologist appointment scarcity in rural United States counties delays device activation and dampens replacement cycle velocity.
- Cochlear Implant Substitution:Severe-to-profound loss patients in tertiary care centers migrate toward surgical intervention, capping BTE addressable share at moderate-to-severe thresholds.
Strategic Opportunities
- India Tier-II City Penetration:Underdeveloped audiology infrastructure in Lucknow, Jaipur, and Kochi creates whitespace for tele-audiology-enabled direct distribution.
- EU AI Act Alignment:Early compliance with high-risk system documentation requirements positions premium manufacturers for accelerated CE marking under harmonized standards.
- Workplace Hearing Conservation Mandates:OSHA occupational noise regulations in manufacturing and construction sectors institutionalize employer-funded preventive amplification programs.
Industry Challenges
- Real-Ear Measurement Skill Scarcity:Precise probe-microphone verification requires specialized clinical training that vocational programs are failing to replenish at replacement rates.
- Firmware Validation Timelines:FDA 510(k) software modification protocols extend release cycles for AI-driven noise classification updates, compressing competitive responsiveness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital BTE Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Behind-the-Ear, Receiver-in-Canal, Open-Fit, Custom Molded Technology: Bluetooth, Digital Signal Processing, Artificial Intelligence, Telehealth End User: Adults, Pediatrics, Geriatrics, Hearing Impaired Distribution Channel: Online Retailers, Hospitals, Audiology Clinics, Specialty Stores |
| Companies Covered | Sonova, WS Audiology, Demant A/S, Starkey Laboratories, GN Store Nord A/S, RION Co., Siemens, Resound, NewEar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital BTE Market Trends and Innovations
Auracast broadcast audio and on-device machine learning are dismantling legacy assistive listening infrastructure while regulatory frameworks struggle to synchronize approval pathways for algorithmic medical devices.
Receiver-in-Canal architectures with thin-wire acoustic delivery are supplanting traditional tubing-based BTE configurations in premium and mid-tier segments. Geriatric users with dexterity limitations favor the reduced occlusion and improved high-frequency response. This shift is compressing demand for standard-tube BTE housings and reallocating manufacturing capacity toward miniaturized receiver modules.
EMA's Medical Device Regulation and the EU AI Act are converging on clinical evidence requirements for adaptive hearing algorithms. Manufacturers must now submit prospective validation data for noise-classification neural networks before CE marking authorization. German notified bodies are enforcing the strictest interpretation, delaying market entry for platforms lacking pre-market clinical studies.
Audiologist-owned retail chains are consolidating procurement leverage through group purchasing organizations, squeezing manufacturer margins on standard-tier devices. Independent practices in the United States are ceding volume to Costco and managed care networks. This concentration is most visible in California and Texas, where regional buying cooperatives now negotiate exclusive firmware customization rights.
Digital BTE Market Segmentation
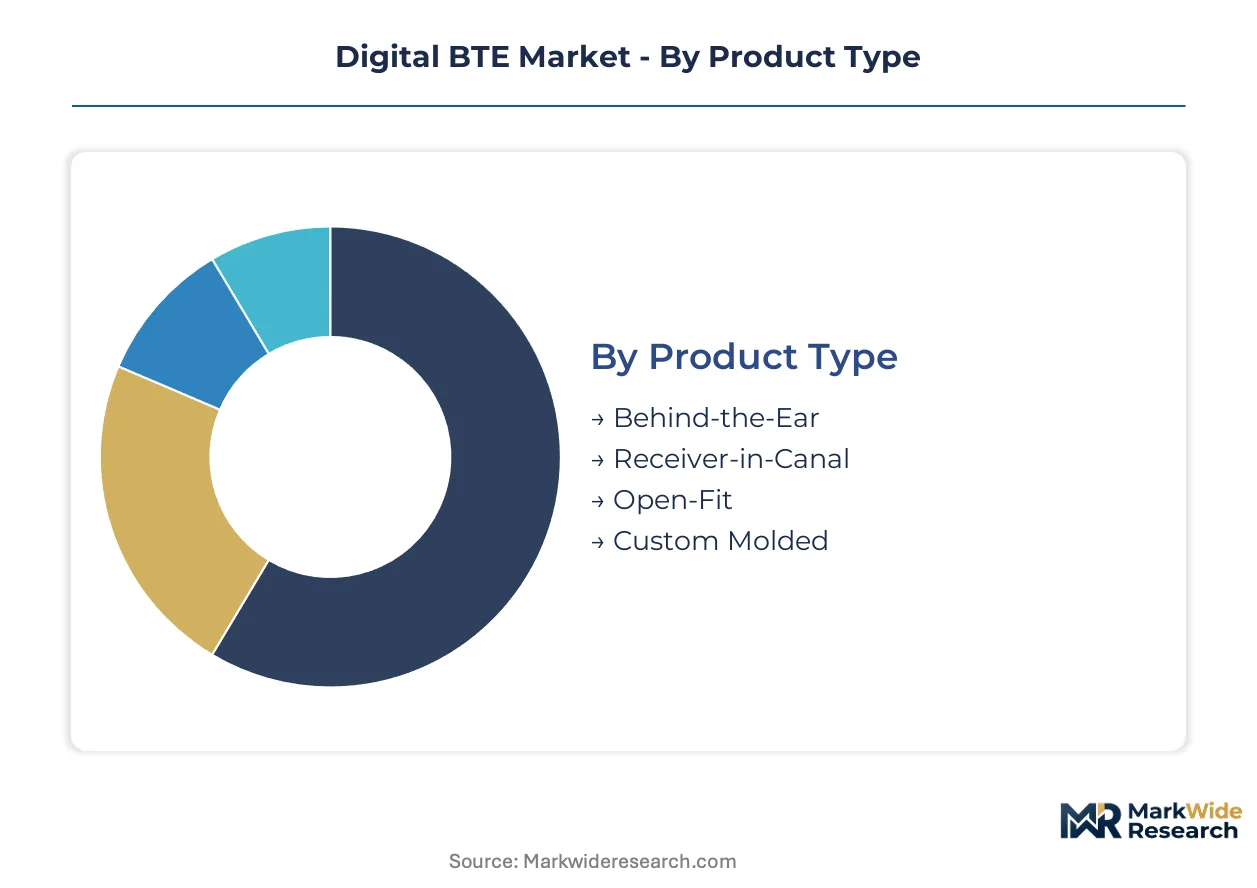
Digital BTE segmentation reveals how clinical workflows, connectivity standards, and patient demographics partition procurement budgets. Manufacturers align R&D pipelines and channel partnerships around these divides to capture margin pools.
Product Type:
Behind-the-Ear configurations dominate domestic markets in Germany and the United States where established audiology infrastructure supports traditional fitting protocols. Export demand concentrates on miniaturized variants for Asian markets with cosmetic sensitivity.
- Behind-the-Ear:Standard BTE housings enclose microphones, amplifiers, and DSP chips in a single casing behind the pinna, with sound delivered through tubing to custom earmolds. Demand concentrates in Medicare-funded US dispensing offices where reimbursement familiarity sustains volume despite newer alternatives.
- Receiver-in-Canal:Thin-wire acoustic delivery positions the receiver directly in the ear canal, improving high-frequency response and reducing occlusion. German and Japanese geriatric patients favor this configuration for its cosmetic discretion and comfort during extended wear.
- Open-Fit:Non-occluding dome tips preserve natural low-frequency hearing while amplifying speech bands. Popular among first-time adult users in urban US markets seeking immediate adaptation without blocked-ear sensation.
- Custom Molded:Patient-specific shell fabrication from ear impressions delivers maximum retention for pediatric and severe-loss fittings. Requires longer fulfillment timelines that limit penetration in direct-to-consumer channels.
Behind-the-Ear holds the largest share; momentum sits with Receiver-in-Canal.
Technology:
Technology tiers stratify by cost and clinical integration depth, with premium Bluetooth and AI platforms commanding hospital system contracts while basic DSP serves retail price points.
- Bluetooth:Low-energy wireless protocols enable smartphone streaming and remote control via manufacturer apps. US audiologist practices report patient demand for iOS and Android compatibility as a non-negotiable selection criterion.
- Digital Signal Processing:Multi-channel compression algorithms restore speech intelligibility through real-time frequency analysis. Forms the baseline technology layer across all price tiers, with channel count differentiating premium from standard offerings.
- Artificial Intelligence:On-device neural networks classify acoustic environments and auto-adjust processing parameters. Japanese and German regulators now require prospective clinical validation for CE marking of adaptive algorithms.
- Telehealth:Cloud-connected firmware enables remote fitting adjustments and diagnostic data transmission. Expanding fastest in rural US counties where audiologist appointment scarcity delays traditional activation workflows.
Digital Signal Processing anchors volume; Bluetooth climbs the fastest.
End User:
User segments diverge by loss severity, dexterity requirements, and third-party payment sources, shaping everything from industrial design to channel strategy.
- Adults:Working-age users aged 18-64 with noise-induced or early-onset sensorineural loss. US occupational health mandates in manufacturing sectors drive employer-funded procurement for this cohort.
- Pediatrics:Congenital or early-acquired loss patients requiring durable housings and tamper-resistant battery compartments. Demant A/S and regional specialists dominate through school-based screening partnerships.
- Geriatrics:Adults over 65 with age-related presbycusis represent the dominant demand source across all developed economies. Japan's super-aged demographic concentrates the highest per-capita penetration rates globally.
- Hearing Impaired:Severe-to-profound loss patients at the boundary between amplification and surgical intervention. Cochlear implant candidacy evaluations in tertiary US medical centers siphon some candidates from maximum-gain BTE configurations.
Geriatrics commands the largest share; Telehealth-enabled remote fitting expands Adult access fastest.
Distribution Channel:
Channel structure determines pricing transparency, fitting quality, and manufacturer margin capture, with independent audiology consolidating while retail fragments.
- Online Retailers:Direct-to-consumer platforms accelerated by FDA OTC rule enable self-fitting without clinical intermediation. Amazon and manufacturer-direct sites capture growing volume from price-sensitive US consumers.
- Hospitals:Tertiary medical centers handle complex pediatric and severe-loss cases requiring multidisciplinary evaluation. German university hospitals anchor premium procurement through research partnerships with manufacturers.
- Audiology Clinics:Independent and chain-affiliated practices provide probe-microphone verification and real-ear measurement. US consolidation into buying cooperatives in California and Texas squeezes manufacturer margins on standard-tier devices.
- Specialty Stores:Costco and optical chain hearing aid departments offer bundled pricing and basic fitting services. Volume concentration here pressures independent practices in suburban US markets.
Audiology Clinics retain the largest share; Online Retailers gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European distribution for digital BTE components, while Japan's Kansai International Airport corridor handles precision MEMS microphone imports for East Asian assembly networks. These logistics nodes determine regional procurement velocity and manufacturer inventory positioning.
United States
Medicare reimbursement stability and the FDA OTC Hearing Aid Rule sustain domestic demand for programmable amplification. OSHA workplace hearing conservation mandates in manufacturing sectors institutionalize employer-funded preventive device procurement. The Austin-San Antonio corridor concentrates tele-audiology platform development for rural access expansion.
Germany
German university hospitals anchor premium procurement through research partnerships with manufacturers, while statutory health insurance covers standard-tier fittings. EMA Medical Device Regulation and EU AI Act enforcement through Berlin-based notified bodies impose stringent clinical evidence requirements for adaptive algorithms. The Munich-Stuttgart axis houses precision receiver-in-canal module fabrication.
Japan
Super-aged demographic concentration generates the highest per-capita penetration rates globally for geriatric-targeted devices. METI industrial standards and PMDA device classification frameworks govern software-as-medical-device approvals for AI-integrated platforms. The Osaka-Kobe manufacturing belt specializes in miniaturized digital signal processor chip packaging.
India
Tier-II city audiology infrastructure gaps in Lucknow, Jaipur, and Kochi create whitespace for direct distribution models bypassing clinical bottlenecks. CDSCO medical device registration requirements and BIS quality certification shape import timelines for multinational manufacturers. The Delhi-NCR cluster concentrates domestic assembly operations for economy-tier digital BTE housings.
South Korea
MFDS regulatory alignment with international standards accelerates CE marking reciprocity for export-oriented manufacturers. Government-funded senior welfare programs in Seoul and Busan subsidize hearing aid procurement for low-income elderly populations. The Suwon-Gwangmyeong electronics corridor supplies lithium-ion rechargeable battery architectures to regional device assemblers.
Digital BTE Market Competitive Landscape
Concentration sits with vertically integrated audiology conglomerates controlling clinic networks, component fabrication, and firmware development under unified ownership. The vendor base stratifies across three tiers: premium specialists commanding hospital system contracts, mid-scale manufacturers serving retail chains, and regional assemblers targeting price-sensitive emerging markets. Dominant competitive moves include audiology clinic chain acquisitions for channel control and rechargeable battery architecture R&D partnerships with East Asian cell suppliers.
Within the premium-tier vector, Sonova and WS Audiology occupy positions exemplifying integrated clinic-network strategies, while Demant A/S represents specialization in pediatric fitting protocols. Among these, Sonova anchors European direct-to-patient channel control, WS Audiology exemplifies rechargeable battery architecture intensity, and Demant A/S sits within the clinical-brand differentiation archetype through school-based screening partnerships.
| Leading Market Players |
|---|
| Sonova |
| WS Audiology |
| Demant A/S |
| Starkey Laboratories |
| GN Store Nord A/S |
| RION Co. |
| Siemens |
| Resound |
| NewEar |
| Others |
Pricing and Supply Chain Analysis
Lithium-ion rechargeable architectures displacing zinc-air batteries redraw procurement economics for hearing aid manufacturers, compressing lifetime cost structures while tethering supply chains to East Asian cell fabrication corridors. This substitution simultaneously elevates upfront device pricing for rechargeable tiers and concentrates component sourcing leverage within South Korean and Chinese battery suppliers.
Pricing Analysis
Volume-discount tiering structures separate premium AI-enabled platforms from standard Bluetooth models from economy DSP-only devices. Price differentiation rests on channel certification depth and after-sales bundling intensity. Cost compression in standard tiers is intensifying because Costco and managed care networks consolidate procurement leverage. Employer-funded occupational health programs exhibit lowest price sensitivity; direct-to-consumer online buyers demonstrate highest elasticity.
Supply Chain Analysis
Taiwan Strait transit vulnerability underwrites supply security for MEMS microphone and DSP chip shipments into final assembly facilities. Component fabrication draws from Taiwan, South Korea, and Japan for precision acoustic processors and miniature receivers. Single-source vulnerability concentrates in multi-channel compression engine supply. Distribution runs through audiology clinic networks, hospital procurement systems, and direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through audiology clinic chain consolidation and group purchasing organization formation in California and Texas, fragmenting manufacturer pricing control. This shift elevates procurement leverage for mid-tier device categories.
For Market Incumbents: Fortify channel control through exclusive firmware customization partnerships with consolidated buying cooperatives. Deepen backward integration into lithium-ion cell supply through joint development agreements with Suwon-Gwangmyeong corridor suppliers. Priority defensive investments sit in tele-audiology platform development to preempt direct-to-consumer substitution.
For New Entrants and Emerging Players: Rural audiology service gaps in United States counties with appointment scarcity present the most penetrable whitespace. Target telehealth-enabled remote fitting workflows for Medicare-funded populations seeking activation without clinical travel. Go-to-market execution should anchor on FDA OTC pathway compliance for self-fitting device categories.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed audiology clinic roll-ups seeking manufacturing partnerships. Long-term viability framing centers on algorithmic differentiation sustainability under EU AI Act documentation requirements. Acquisition target archetypes include rechargeable battery architecture specialists and pediatric fitting protocol developers. The signal to watch is FDA software-as-medical-device guidance evolution for AI-driven noise classification platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Rechargeable Battery Architecture Partnership | East Asian cell supplier alliances secure lithium-ion supply for next-generation device portfolios. |
| Tele-audiology Platform Development | FDA-cleared remote fitting software expands rural access beyond clinical infrastructure constraints. |
| EU AI Act Compliance Investment | Prospective clinical validation for adaptive algorithms accelerates CE marking through German notified bodies. |
| Pediatric Fitting Protocol Specialization | School-based screening partnerships differentiate clinical brand positioning for congenital loss segments. |
| Audiology Clinic Network Acquisition | Direct-to-patient channel control in European markets defends margin capture against retail consolidation. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with audiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) filings, EMA Medical Device Regulation submissions, CMS Medicare reimbursement databases, and audiology clinic procurement records. Bottom-up volume estimates triangulated against top-down manufacturer capacity assessments.
Across the analysis window, forecasts model product type segmentation by configuration architecture, technology tier by connectivity standard, end user by age cohort and loss severity, and distribution channel by access modality. CAGRs were derived from regression analysis of historical shipment velocity against demographic penetration curves and reimbursement policy trajectories. Forecast inputs incorporated audiologist appointment availability indices and semiconductor fab capacity utilization trends.
Forecasts assume regulatory continuity in FDA software-as-medical-device guidance and EU AI Act risk classification frameworks; material policy shifts would require re-modeling algorithmic approval timelines and clinical evidence requirements. Specific risk factors include Taiwan semiconductor supply disruption and Medicare reimbursement rate revision. Practitioners should keep alternative scenarios live as Bluetooth Low Energy protocol adoption and Auracast infrastructure deployment evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Supraglottic Device Market
Medical Devices
Global Body Contouring Devices Market
Medical Devices
US Mechanical Ventilator Market
Medical Devices
Brazil Clear Aligners Market
Medical Devices
Europe Minimally Invasive Surgery Devices Market
Medical Devices
Global Surgical Power Tools Market
Medical Devices
Ventricle Assist Device Market
Medical Devices
South America Single-Use Medical Device Reprocessing Market
Medical Devices
Medical Device Technologies Market
Medical Devices
Direct Energy Medical Devices Market
Medical Devices
Global Self Care Medical Devices Market
Medical Devices
Colon Hydrotherapy Units Market
Medical Devices
Asia-Pacific Ambulatory Infusion Pumps Market
Medical Devices
Veterinary Procedure Lights Market
Medical Devices
Endodontic Devices Market
Medical Devices
Medical Bionic Implant Market