
 Medical Device and Accessories Market | 2026-2036
Medical Device and Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Device and Accessories Market Outlook
Hospital procurement consolidation is realigning vendor relationships across the medical device supply chain. Medtronic leverages its integrated portfolio to secure multi-year contracts with purchasing networks. Johnson & Johnson MedTech anchors its position through sustained R&D investment in robotic surgery platforms. Siemens Healthineers differentiates via diagnostic imaging technology leadership and direct hospital service agreements.
Medical devices and accessories encompass instruments, apparatus, implants, and consumables engineered to specific biocompatibility standards such as ISO 10993 for material safety evaluation, serving therapeutic monitoring, diagnosis, or surgical intervention purposes. Diagnostic equipment and surgical instruments command established revenue pools, while AI-enabled devices and robotics represent the fastest-expanding technology segments as hospitals prioritize automation and predictive analytics. Wearable devices gain traction in home care settings where remote patient monitoring reduces readmission exposure.
FDA premarket clearance pathways, EU MDR conformity requirements, and China's NMPA registration standards collectively shape product development timelines and market access costs for device manufacturers. These frameworks intensify documentation burdens but simultaneously filter out lower-compliance competitors, concentrating commercial opportunity among firms with dedicated regulatory affairs capabilities. Stakeholders must weigh certification investments against the narrowing window for first-mover positioning in AI-integrated device categories.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while elevating compliance requirements under FDA premarket notification and EU MDR frameworks. Manufacturers now compete on integrated service portfolios rather than standalone device pricing.
Growth Catalysts
- Aging Demographics:Germany, Japan, and the United States face expanding chronic disease burdens that sustain demand for cardiac monitors, insulin pumps, and continuous glucose monitoring systems in home care environments.
- EU MDR Harmonization:The Medical Device Regulation's unified conformity assessment pathway reduces fragmentation across European national markets, accelerating cross-border commercialization for certified manufacturers.
- Remote Patient Monitoring:Wearable biosensors and connected inhalers are penetrating post-acute care settings as hospitals seek to reduce thirty-day readmission penalties through real-time physiological tracking.
Market Restraints
- Supply Concentration:Specialty polymer and precision sensor production clusters in Germany and Japan create single-source vulnerability for implantable device manufacturers during geopolitical disruptions.
- Regulatory Friction:China's NMPA registration timeline extends eighteen to thirty-six months for Class III devices, delaying revenue recognition and inflating pre-market capital requirements.
- Technical Limitation:Battery energy density constraints restrict continuous monitoring duration for ambulatory cardiac devices, forcing trade-offs between form factor and functional autonomy.
Strategic Opportunities
- Underpenetrated Geographies:India's hospital infrastructure expansion under Ayushman Bharat creates procurement windows for affordable diagnostic imaging and surgical instrumentation.
- Technology Convergence:Artificial intelligence integration with endoscopic visualization systems enables real-time polyp detection, differentiating vendors in colonoscopy and laparoscopy segments.
- Regulatory Tailwind:The United States FDA's Breakthrough Devices Program accelerates review timelines for technologies addressing life-threatening conditions, compressing time-to-market for qualifying innovations.
Industry Challenges
- Biocompatibility Assessment Bottleneck:ISO 10993 testing capacity constraints extend material qualification timelines, delaying product launches and inflating regulatory affairs headcount requirements.
- Cybersecurity Certification Burden:FDA premarket guidance on device software security demands specialized engineering talent that commands premium compensation, compressing R&D efficiency ratios.
- Legacy System Integration:New AI-enabled diagnostic platforms face interoperability friction with hospital electronic health record architectures, complicating pilot-to-scale transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Device and Accessories Market |
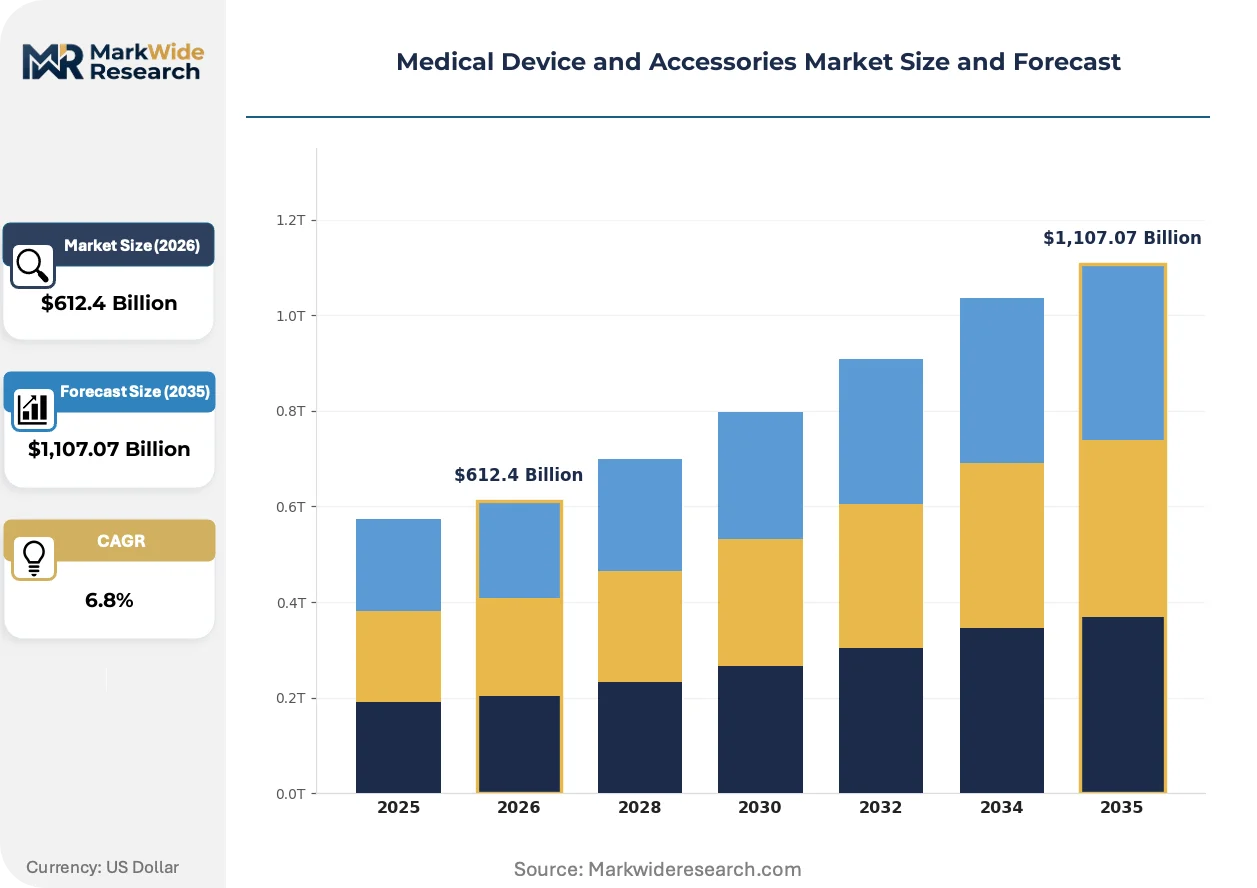
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $1,107.07 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implants, Wearable Devices, Diagnostic Equipment, Surgical Instruments Application: Cardiology, Orthopedics, Neurology, Dentistry End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Technology: Biomaterials, Robotics, AI-Enabled Devices, Telemedicine |
| Companies Covered | Medtronic, Johnson & Johnson MedTech, Siemens Healthineers, Abbott Laboratories, Stryker, GE HealthCare, Royal Philips, Boston Scientific, Medline Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Device and Accessories Market Strategic Shifts
Digital health integration is dissolving traditional boundaries between acute and ambulatory care, forcing device manufacturers to architect connectivity-first product platforms. Software-enabled functionality now determines competitive differentiation as hardware commoditizes.
Robotic surgical platforms are modularizing across procedure types, enabling hospitals to configure capital equipment for orthopedic, cardiovascular, or general surgery applications through interchangeable instrument arms and software modules. Academic medical centers in the United States and Germany are standardizing on these flexible configurations to maximize utilization rates across subspecialty rotations. This architecture is modularizing vendor revenue models from perpetual licenses toward recurring software and consumable streams.
The EU AI Act's risk-based classification framework is imposing conformity assessment requirements on diagnostic algorithms that influence clinical decisions. Manufacturers must now maintain quality management systems spanning both hardware production and machine learning model lifecycle governance. High-risk AI-integrated imaging devices face notified body scrutiny of training data representativeness and performance validation protocols, particularly affecting radiology and pathology applications.
Hospital purchasing networks are consolidating vendor panels around integrated service agreements that bundle device supply, maintenance, and staff training. Third-party distributors are losing shelf space as manufacturers establish direct field service organizations to capture lifetime value. This pattern is most pronounced in the United States, where health system mergers have created super-regional entities with centralized procurement authority and stringent supplier qualification criteria.
Medical Device and Accessories Market Segmentation
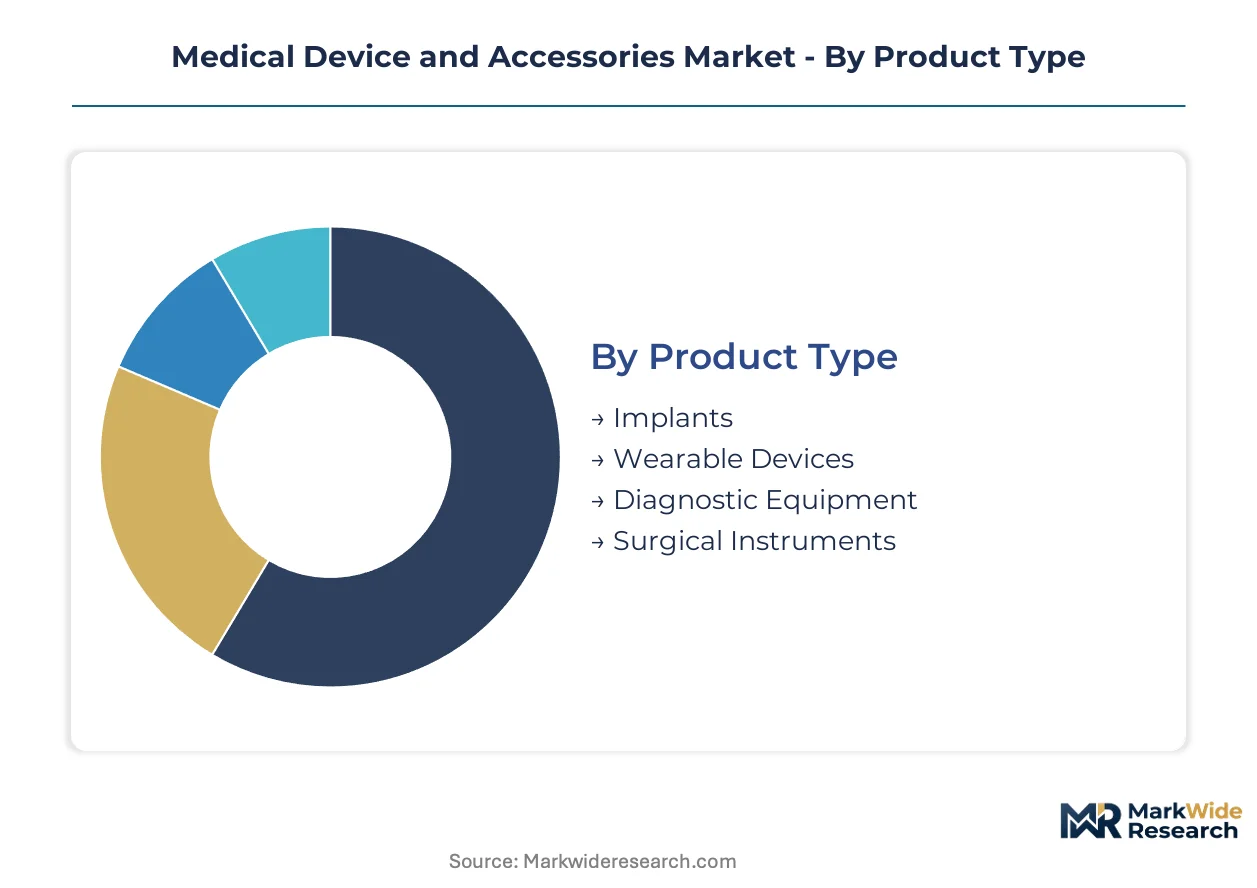
Device manufacturers configure product portfolios around four distinct segmentation axes that determine pricing architecture, regulatory pathway selection, and channel strategy. Each axis reflects divergent buyer priorities across acute care procurement networks and ambulatory service lines.
Product Type:
Hospital procurement committees weight capital intensity against utilization rates when allocating budget across device categories.
- Implants:Metallic and polymeric constructs designed for permanent or long-term tissue integration, subject to ISO 10993 biocompatibility validation. Demand concentrates in German orthopedic centers and US cardiac catheterization labs where aging demographics sustain hip replacement and stent placement volumes.
- Diagnostic Equipment:Imaging modalities and in-vitro analyzers requiring FDA 510(k) or EU MDR conformity assessment. Siemens Healthineers and GE HealthCare anchor hospital purchasing decisions in the United States and Germany through service bundling and uptime guarantees.
- Wearable Devices:Ambulatory biosensors for glucose, cardiac rhythm, and respiratory monitoring. Dexcom and Abbott capture home care prescriptions through pharmacy benefit integration.
- Surgical Instruments:Reusable and single-use tools for open and minimally invasive procedures. Stainless steel and advanced ceramic compositions dominate instrument tray configurations.
Diagnostic equipment leads on scale; wearable devices lead on momentum.
Application:
Clinical outcome metrics and reimbursement codes shape segment profitability across therapeutic areas.
- Cardiology:Interventional devices and electrophysiology systems addressing coronary artery disease and arrhythmia. US hospitals prioritize robotic-assisted PCI platforms to reduce radiation exposure and procedure variability.
- Orthopedics:Joint reconstruction, spine fixation, and sports medicine implants. Zimmer Biomet and Stryker compete on robotic navigation integration for knee arthroplasty.
- Neurology:Deep brain stimulation systems and cerebrospinal fluid management devices. Medtronic maintains installed base leadership in movement disorder therapy.
- Dentistry:Implantology systems and digital intraoral scanners. Straumann and Dentsply Sirona drive chairside CAD/CAM adoption in German and US private practices.
Orthopedics leads on scale; neurology leads on momentum.
End User:
Capital availability and regulatory risk tolerance differentiate procurement behavior across care settings.
- Hospitals:Integrated delivery networks with centralized sourcing authority and multi-year capital planning cycles. US health system consolidation favors vendors with national service coverage and EHR interoperability.
- Home Care:Patients and family caregivers acquiring devices through durable medical equipment suppliers and direct-to-consumer channels. Continuous glucose monitors and pulse oximeters penetrate this segment fastest.
- Clinics:Physician-owned ambulatory surgery centers and specialty practices with limited capital budgets. Leasing and pay-per-use models predominate for imaging and surgical equipment.
- Rehabilitation Centers:Post-acute facilities prioritizing mobility assistance and respiratory therapy devices. Medicare reimbursement rates constrain equipment refresh cycles.
Hospitals lead on scale; home care leads on momentum.
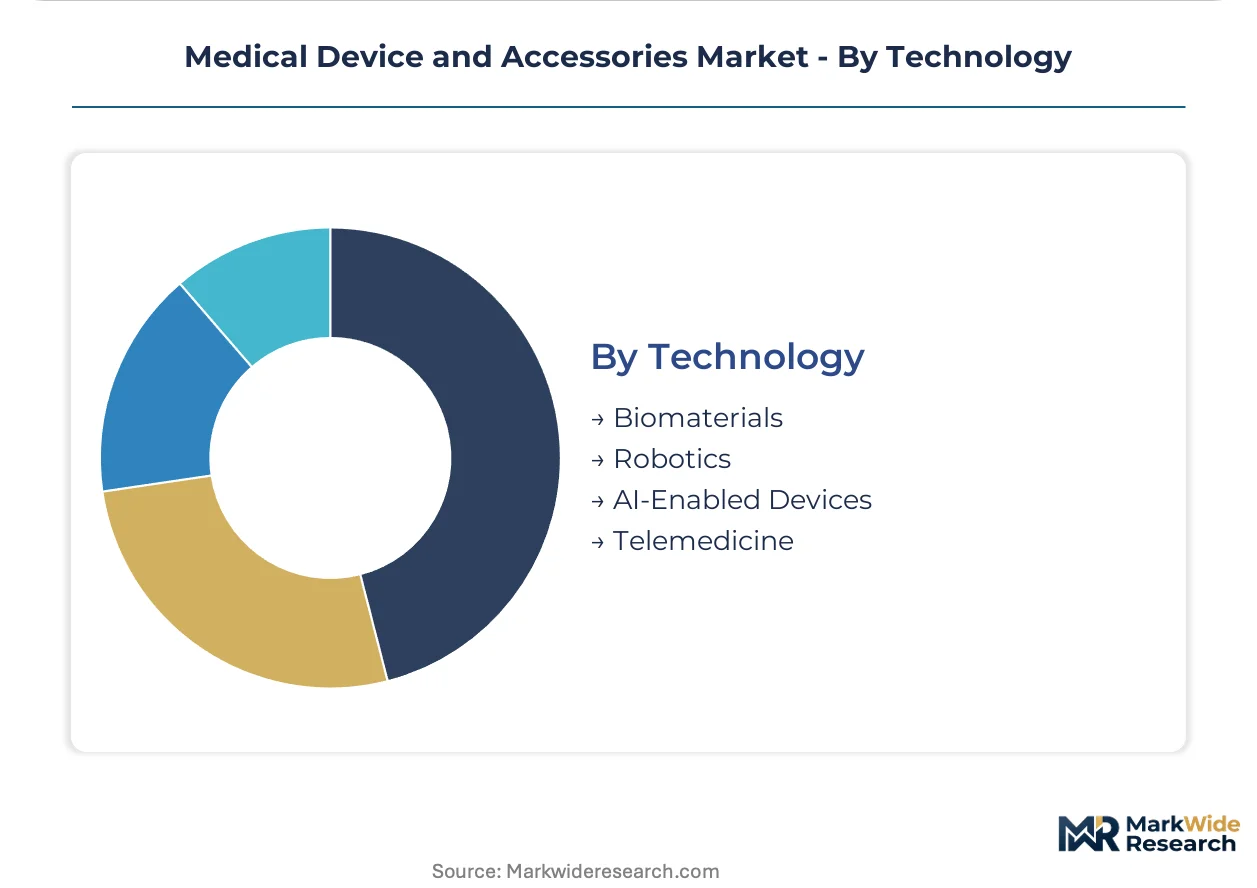
Technology:
Intellectual property density and software validation burdens determine competitive moats and time-to-market.
- AI-Enabled Devices:Machine learning algorithms for image analysis, risk stratification, and workflow optimization. FDA Breakthrough Device designation accelerates review for qualifying radiology and pathology applications.
- Robotics:Surgical and rehabilitation platforms with haptic feedback and autonomous instrument control. Intuitive Surgical and Johnson & Johnson MedTech compete on procedure-specific instrument ecosystems.
- Biomaterials:Surface-modified metals, absorbable polymers, and tissue-engineered scaffolds. ISO 10993 testing capacity constraints delay material qualification timelines.
- Telemedicine:Remote diagnostic peripherals and connected care platforms. COVID-19 emergency waivers expanded reimbursement, though parity regulations vary by US state.
Biomaterials leads on scale; AI-enabled devices lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's orthopedic implant production clusters contrast with India's hospital infrastructure buildout under public health expansion programs. Both markets illustrate divergent pathways for medical device commercialization.
United States
Hospital system consolidation into super-regional networks concentrates procurement authority among fewer buyers with stringent supplier qualification criteria. FDA's Breakthrough Devices Program accelerates review timelines for qualifying AI-integrated diagnostics. The Minneapolis-St. Paul corridor anchors cardiac rhythm management device engineering.
Germany
Aging demographics sustain hip replacement and stent placement volumes across university hospital networks. EU MDR harmonization reduces fragmentation across national markets for certified manufacturers. The Tuttlingen surgical instrument cluster maintains precision manufacturing dominance through multi-generational tooling expertise.
China
NMPA registration timelines extending eighteen to thirty-six months for Class III devices delay revenue recognition for foreign entrants. Dual carbon goals pressure manufacturers toward energy-efficient production processes. The Suzhou industrial park concentrates foreign-invested medical device assembly operations serving domestic distribution.
India
Ayushman Bharat hospital infrastructure expansion creates procurement windows for affordable diagnostic imaging and surgical instrumentation. CDSCO regulatory harmonization with IMDRF standards accelerates approval pathways for established multinationals. The Hyderabad medical technology corridor clusters contract research organizations supporting clinical validation studies.
Japan
PMDA's Sakigake designation system fast-tracks innovative devices addressing unmet medical needs. METI industrial policy prioritizes robotic surgery platform development through public-private partnerships. The Kobe biomedical innovation cluster integrates university research hospitals with device prototyping facilities.
Medical Device and Accessories Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across product categories. The vendor base organizes into three tiers: integrated health technology conglomerates with diagnostic-to-therapeutic portfolios, mid-scale specialists commanding procedure-specific ecosystems, and regional fabricators serving price-sensitive procurement segments. Dominant competitive moves include strategic partnerships for AI algorithm licensing and backward integration into biocompatible material production.
Within the integrated health technology tier, Medtronic and Johnson & Johnson MedTech exemplify portfolio breadth spanning cardiac rhythm management through robotic surgery platforms. Siemens Healthineers occupies a position representing diagnostic imaging technology leadership. These three entities anchor competitive dynamics through multi-year service agreements with consolidated hospital purchasing networks.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson MedTech |
| Siemens Healthineers |
| Abbott Laboratories |
| Stryker |
| GE HealthCare |
| Royal Philips |
| Boston Scientific |
| Medline Industries |
| Others |
Value Chain & Pricing Dynamics
AI-enabled diagnostic software integration is compressing hardware margins while elevating recurring revenue streams, simultaneously concentrating procurement leverage among integrated health technology conglomerates and fragmenting component sourcing across specialized biopolymer producers. This dual transformation rewards manufacturers with captive regulatory affairs capabilities and penalizes pure-play hardware vendors.
Pricing Analysis
Capacity additions in China's Suzhou industrial park are reshaping price floors for Class II diagnostic equipment, forcing incumbent multinationals toward three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on FDA Breakthrough Device designation and ISO 10993 certification tier, with US hospital purchasing networks commanding steepest discounts through multi-year service bundling. Cost compression in the economy tier intensifies because domestic Chinese manufacturers exploit NMPA fast-track pathways. Ambulatory surgery centers exhibit highest price sensitivity; academic medical centers prioritize clinical outcome guarantees over unit economics.
Supply Chain Analysis
Specialty polymer feedstock for implantable devices rests on German and Japanese chemical producers, with precision sensor substrates drawing from Taiwanese semiconductor foundries. Raw material dependencies span medical-grade silicone elastomers, platinum-iridium electrode alloys, and bioresorbable polylactic acid. Single-source vulnerability concentrates in Tuttlingen's surgical instrument steel forging capacity. Distribution runs through direct field service organizations as hospital purchasing networks disintermediate third-party distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Medical Device and Accessories Market functions as a stable compounder underpinned by irreversible demographic aging across developed economies, with chronic disease prevalence sustaining replacement demand cycles regardless of macroeconomic volatility.
For Market Incumbents: Anchor market position through backward integration into biocompatible material production and captive ISO 10993 testing capacity, insulating against qualification timeline bottlenecks that delay product launches. Prioritize software companion development for existing hardware installed bases to capture recurring revenue streams as robotic surgery platforms modularize. Defend against emerging pure-play AI diagnostic vendors by embedding machine learning algorithms directly into imaging hardware at the point of data capture. For New Entrants and Emerging Players: Rural Indian district hospitals under Ayushman Bharat procurement windows represent the most penetrable buyer archetype, with price points and service requirements unmet by incumbent multinationals. Target affordable diagnostic imaging and surgical instrumentation segments where CDSCO harmonization with IMDRF standards accelerates approval timelines for established quality systems. Pursue contract manufacturing partnerships with Hyderabad medical technology corridor CROs to access clinical validation infrastructure without captive capital deployment. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale specialists commanding procedure-specific instrument ecosystems but lacking integrated diagnostic-to-therapeutic portfolios. Long-term viability over a five-to-ten year horizon favors targets with FDA Breakthrough Device designations in pipeline and direct hospital service agreements in force. Monitor EU AI Act notified body backlog as an inflection indicator for AI-integrated device category entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerated review compresses time-to-market for qualifying AI-integrated diagnostics addressing life-threatening conditions. |
| EU MDR Notified Body Certification | Unified conformity assessment reduces fragmentation across European national markets for certified manufacturers. |
| Hospital System Direct Partnership | Integrated service agreements bundle device supply, maintenance, and staff training, capturing lifetime value. |
| Software Companion Development | Recurring revenue streams from algorithm updates offset hardware commoditization in robotic surgery platforms. |
| Reimbursement Strategy Alignment | Medicare remote patient monitoring codes determine commercial viability for wearable biosensor launches. |
Study Parameters
Direct dialogue with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs directors informed primary intelligence, cross-referenced against FDA 510(k) filings, EU MDR notified body certificates, CMS Medicare reimbursement databases, and hospital procurement contract records. Bottom-up and top-down triangulation validated segment-level demand estimates.
Bottom-up modeling anchored volume projections on installed base replacement cycles and procedure volume growth, while top-down analysis cross-checked aggregate market sizing against capital expenditure disclosures from integrated delivery networks. Segmentation across product type, application, end user, and technology dimensions incorporated AI integration intensity and robotic platform modularity as industry-specific forecast inputs. CAGRs derived from weighted average of historical trajectory and forward-looking adoption curve analysis across the projection horizon.
Underlying measurement precision varies by segment; diagnostic equipment and surgical instruments carry tighter precision than emerging AI-enabled device categories where regulatory pathways remain unsettled. Forecasts reflect documented assumptions regarding NMPA registration timeline normalization and EU AI Act implementation pacing. Regulatory backlog accumulation, biocompatibility testing capacity constraints, and hospital merger activity constitute primary revision triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Wearable Medical Devices Market
Medical Devices
Photopheresis Products Market
Medical Devices
Global Digital Dose Inhaler Market
Medical Devices
Vitrectomy Devices Market
Medical Devices
Needle-Free Drug Delivery Devices Market
Medical Devices
Wearable Cardioverter Defibrillators Market
Medical Devices
Asia-Pacific Digital Dentistry Market
Medical Devices
Argentina Respiratory Devices Market
Medical Devices
Global Bone Cement Delivery System Market
Medical Devices
Mobile Healthcare Devices Market
Medical Devices
Medical Coatings for Implants Market
Medical Devices
Organ-On-A-Chip Systems Market
Medical Devices
Transcutaneous Electrical Nerve Stimulation Market
Medical Devices
Neurovascular Devices Market
Medical Devices
Genitourinary Prosthetics Market
Medical Devices
North America Vagus Nerve Stimulation Market