
 Global Capnography Market | 2026-2036
Global Capnography Market Size, Share, and Industry Trends Forecast 2026-2036
Global Capnography Market Foresight
Microstream infrared technology is rewriting capnography device architecture by enabling lower sample volumes and faster response times for non-intubated patients. Medtronic leverages its integrated critical care portfolio to bundle capnography with ventilator platforms across hospital networks. Masimo anchors its position through advanced signal processing algorithms that reduce motion artifact in ambulatory settings. Nihon Kohden competes in Asia-Pacific markets with localized manufacturing and region-specific regulatory dossiers.
Capnography measures the concentration of carbon dioxide in exhaled breath, typically expressed as end-tidal CO2 in millimeters of mercury, using infrared light absorption at specific wavelengths to quantify gas composition. The technology serves as a standard-of-care monitor for verifying endotracheal tube placement, assessing ventilation adequacy, and detecting respiratory depression during sedation. Mainstream capnographs dominate high-acuity hospital settings where real-time waveform analysis supports anesthesia workflows, while portable capnography devices represent the fastest-expanding category as home healthcare providers and emergency medical services adopt point-of-care respiratory assessment tools. Multiparameter monitors with integrated EtCO2 modules capture premium margin pools by consolidating monitoring infrastructure in intensive care units.
FDA premarket notification requirements under 21 CFR 870.1900 classify capnography as a Class II medical device with specific performance testing for accuracy and alarm functionality, while EMA MDR compliance demands enhanced clinical evidence and post-market surveillance for devices distributed across European Union member states. ISO 80601-2-55 establishes international safety and performance standards for respiratory gas monitors, creating harmonization pressure for manufacturers seeking multi-regional approval. Stakeholders must monitor evolving reimbursement policies for capnography in outpatient procedural settings, as payor decisions will determine whether portable and disposable sensor formats achieve scalable adoption beyond traditional hospital environments.
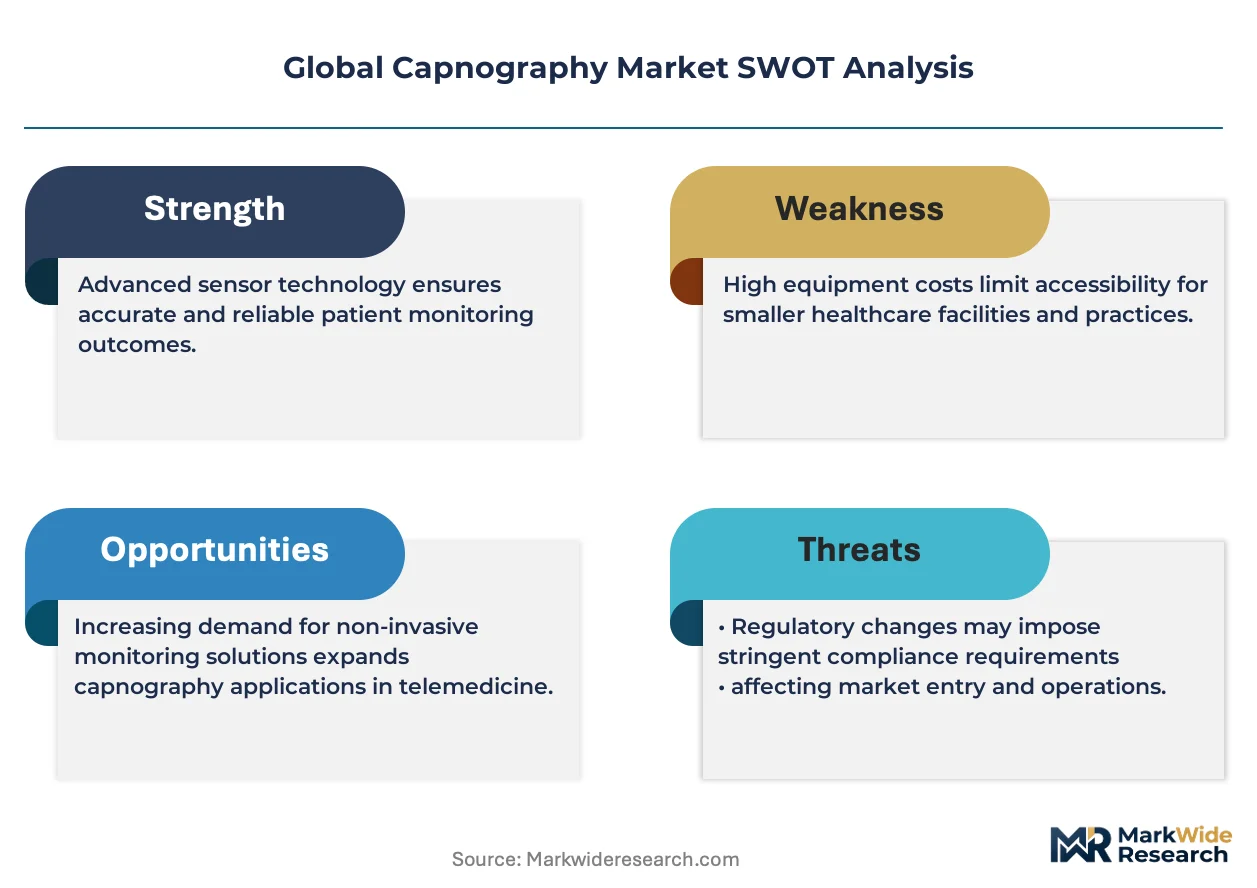
Market Dynamics
Microstream infrared technology is compressing sensor size requirements while tightening accuracy tolerances, forcing manufacturers to rebuild device architectures around lower sample volumes and faster response curves. This single technical shift cascades through FDA 510(k) clearance pathways, procurement specifications at integrated delivery networks, and competitive positioning across both hospital and pre-hospital segments.
Growth Catalysts
- CMS reimbursement mandates:United States federal payor requirements for EtCO2 monitoring during moderate sedation procedures lock in device utilization across ambulatory surgery centers.
- Japan's anesthesia safety protocols:PMDA-aligned clinical guidelines mandating continuous respiratory monitoring expand installed base requirements in tertiary hospitals.
- Microstream infrared miniaturization:Reduced sample volume requirements enable reliable capnography in non-intubated patients, opening procedural sedation and emergency medicine applications.
Market Restraints
- Disposable sensor cost concentration:Single-use nasal cannulas and airway adapters represent 60-70% of lifetime device costs, constraining adoption in cost-sensitive home healthcare settings.
- EMA MDR clinical evidence requirements:Enhanced post-market surveillance obligations for Class IIa respiratory monitors extend regulatory timelines and documentation burdens for EU market entry.
- Pulse oximetry substitution threat:Low-cost SpO2 monitoring with pleth variability index claims overlaps with capnography's respiratory depression detection function in some sedation workflows.
Strategic Opportunities
- Germany's outpatient procedural expansion:Ambulatory surgery center licensing growth under national healthcare efficiency reforms creates demand for portable monitoring configurations.
- AI-integrated waveform analysis:Machine learning algorithms for automated respiratory pattern recognition converge with capnography hardware to differentiate device offerings.
- India's critical care infrastructure buildout:Government hospital modernization programs under the PLI scheme for medical devices incentivize localized manufacturing partnerships.
Industry Challenges
- ISO 80601-2-55 electromagnetic compatibility testing:Revised international safety standards for respiratory gas monitors require hardware redesigns and extended certification cycles.
- Biomedical engineering talent scarcity:Specialized expertise in infrared spectroscopy and clinical algorithm development concentrates at a handful of academic medical centers and incumbent manufacturers.
- Legacy monitor integration complexity:Proprietary data protocols from established multiparameter monitor vendors complicate third-party capnography module connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Capnography Market |
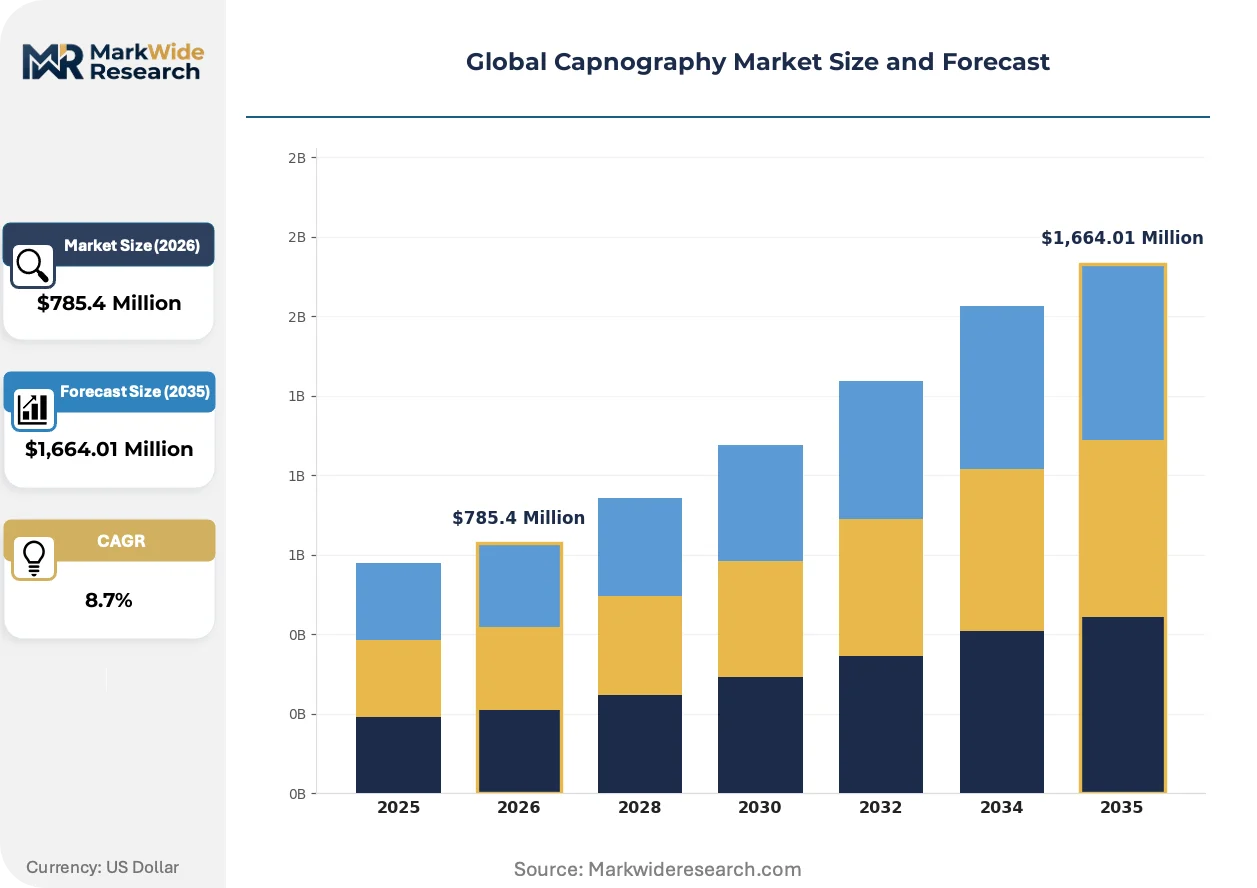
| Market Size in 2026 | $785.4 Million |
| Market Size in 2035 | $1,664.01 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mainstream Capnographs, Sidestream Capnographs, Microstream Capnographs, Portable Capnography Devices, Multiparameter Monitors Application: Perioperative Monitoring, Critical Care, Emergency Medicine, Sleep Studies, Neonatal Monitoring End User: Hospitals, Ambulatory Surgery Centers, Diagnostic Laboratories, Home Healthcare Providers, Research Institutes Technology: Infrared Sensor Technology, Raman Spectroscopy, Photoacoustic Spectroscopy, Electrochemical Sensors, Ultrasonic Sensors |
| Companies Covered | Medtronic, Masimo, Koninklijke Philips N.V., Drägerwerk AG & Co. KGaA, Becton, Dickinson and Company, GE Healthcare, Nihon Kohden Corporation, Hamilton Medical, ICU Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Capnography Market Shifts & Advancements
Capnography device architecture is splitting into two divergent optimization paths: hospital-grade systems pursuing deeper integration with electronic health records and ventilator platforms, while portable formats prioritize battery efficiency and wireless telemetry for point-of-care deployment outside traditional clinical settings.
Solid-state infrared sources are replacing traditional filament-based emitters in next-generation capnography sensors. Ambulance services and emergency medical technician fleets in North America and Western Europe are piloting these configurations for field durability. The shift is rendering obsolete the frequent calibration cycles and thermal stabilization delays that constrained pre-hospital adoption.
EMA MDR Article 10 post-market clinical follow-up requirements are tightening evidence standards for respiratory gas monitors distributed across European Union member states. Manufacturers must now maintain active surveillance registries tracking device performance in clinical use. High-acuity hospital settings face the steepest compliance burden, with some vendors withdrawing legacy product lines rather than absorbing documentation costs.
Hospital procurement committees are unbundling capnography modules from mandatory ventilator purchase bundles. Integrated delivery networks in the United States now separately negotiate EtCO2 sensor contracts, pressuring original equipment manufacturers to open proprietary connector specifications. This pattern is most visible in multi-hospital systems across Texas, Florida, and California where standardization mandates span dozens of facilities.
Global Capnography Market Segmentation
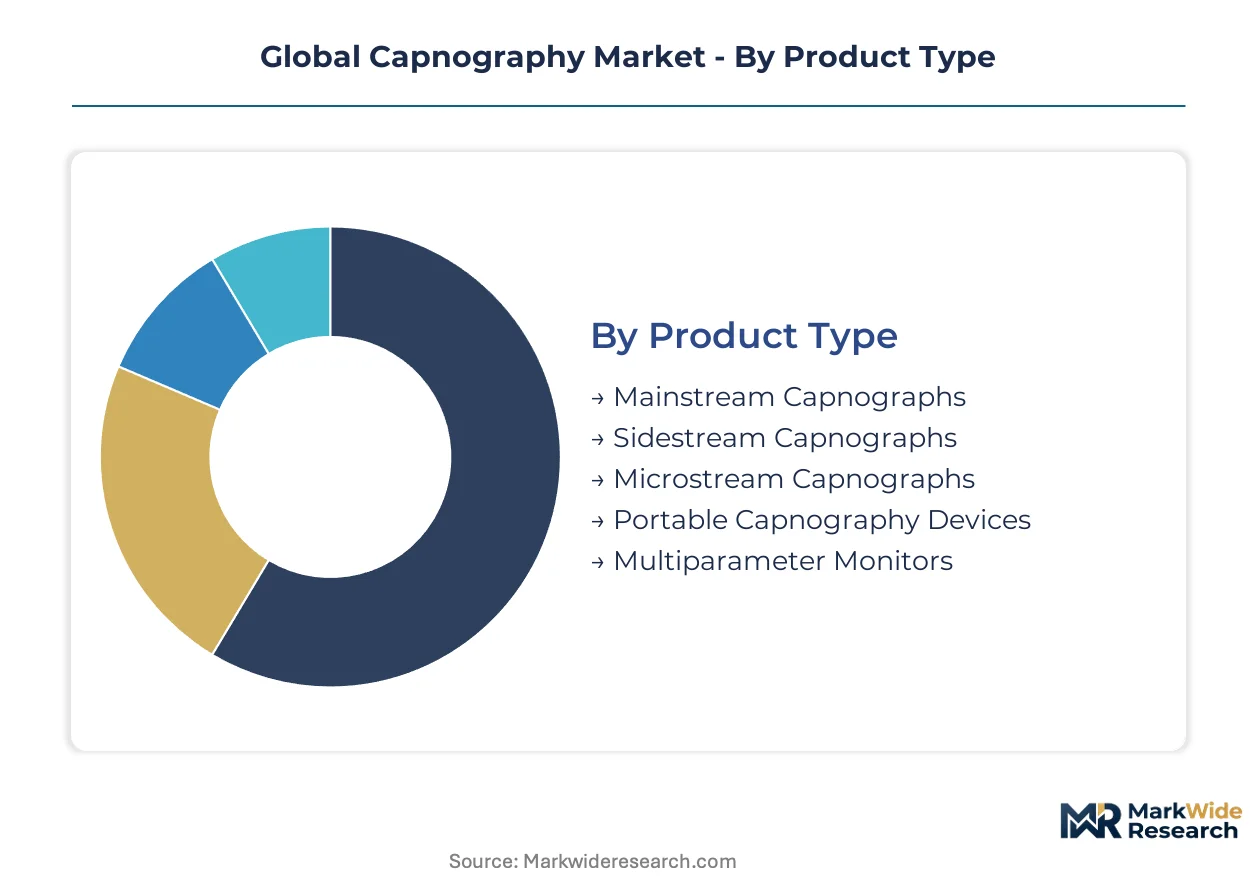
Capnography market segmentation reveals divergent technology maturities and clinical workflows driving procurement decisions. Product architecture, application setting, and end-user infrastructure requirements create distinct competitive arenas with specialized performance thresholds.
Product Type:
Mature hospital-integrated systems anchor revenue while emerging portable formats reshape point-of-care deployment economics.
- Mainstream Capnographs:These devices measure CO2 directly at the airway interface through infrared absorption cells integrated into breathing circuits. Tertiary hospitals in the United States and Germany deploy these systems for real-time waveform analysis during mechanical ventilation. FDA 510(k) clearance pathways for mainstream devices demand rigorous accuracy validation across temperature and humidity ranges.
- Portable Capnography Devices:Battery-powered units with solid-state infrared sources enable respiratory assessment outside traditional clinical settings. Emergency medical services in Texas and Florida are standardizing these configurations for field intubation verification. Reduced calibration requirements and wireless telemetry integration accelerate replacement cycles for legacy filament-based designs.
- Sidestream Capnographs:Gas sampling through nasal cannulas or airway adapters transported to remote sensors.
- Microstream Capnographs:Low-flow sampling technology optimized for non-intubated patients with minimal dead space.
- Multiparameter Monitors:Integrated EtCO2 modules consolidated with SpO2, ECG, and blood pressure on single platforms.
Mainstream capnographs retain volume leadership; portable devices hold the steepest expansion curve.
Application:
Application segmentation tracks how clinical risk profiles determine monitoring intensity and reimbursement eligibility.
- Perioperative Monitoring:Continuous EtCO2 surveillance during anesthesia administration represents the original and most standardized capnography application. CMS reimbursement mandates in the United States lock device utilization into ambulatory surgery center workflows. Waveform interpretation training for anesthesiologists creates institutional stickiness for specific monitor brands.
- Emergency Medicine:Pre-hospital and emergency department settings demand rapid endotracheal tube placement confirmation under suboptimal conditions. Solid-state sensor durability addresses vibration and temperature extremes encountered in ambulance transport. PMDA-aligned protocols in Japan are extending continuous respiratory monitoring requirements to emergency department sedation procedures.
- Critical Care:ICU ventilator integration with trend analysis for weaning assessment.
- Sleep Studies:Nocturnal respiratory pattern monitoring for sleep-disordered breathing diagnosis.
- Neonatal Monitoring:Specialized low-volume sampling for premature infant ventilation management.
Perioperative monitoring commands installed base dominance; emergency medicine applications are climbing the fastest.
End User:
End user segmentation reflects divergent procurement authority and total cost-of-ownership sensitivity across care settings.
- Hospitals:Integrated delivery networks negotiate enterprise capnography contracts spanning dozens of facilities. Biomedical engineering departments prioritize interoperability with existing electronic health record infrastructure. Texas and California health systems are unbundling EtCO2 modules from mandatory ventilator purchase agreements.
- Ambulatory Surgery Centers:Outpatient procedural settings face CMS-mandated EtCO2 monitoring requirements with constrained capital budgets. Disposable sensor costs concentrate lifetime expenditure, driving interest in reusable airway adapter designs. Germany's ambulatory surgery center licensing expansion under national healthcare efficiency reforms is creating procurement opportunities.
- Home Healthcare Providers:Remote patient monitoring programs for chronic respiratory conditions.
- Diagnostic Laboratories:Pulmonary function testing with capnography adjunct diagnostics.
- Research Institutes:Physiological monitoring for clinical trial respiratory endpoints.
Hospitals retain volume leadership; ambulatory surgery centers hold the steepest expansion curve.
Technology:
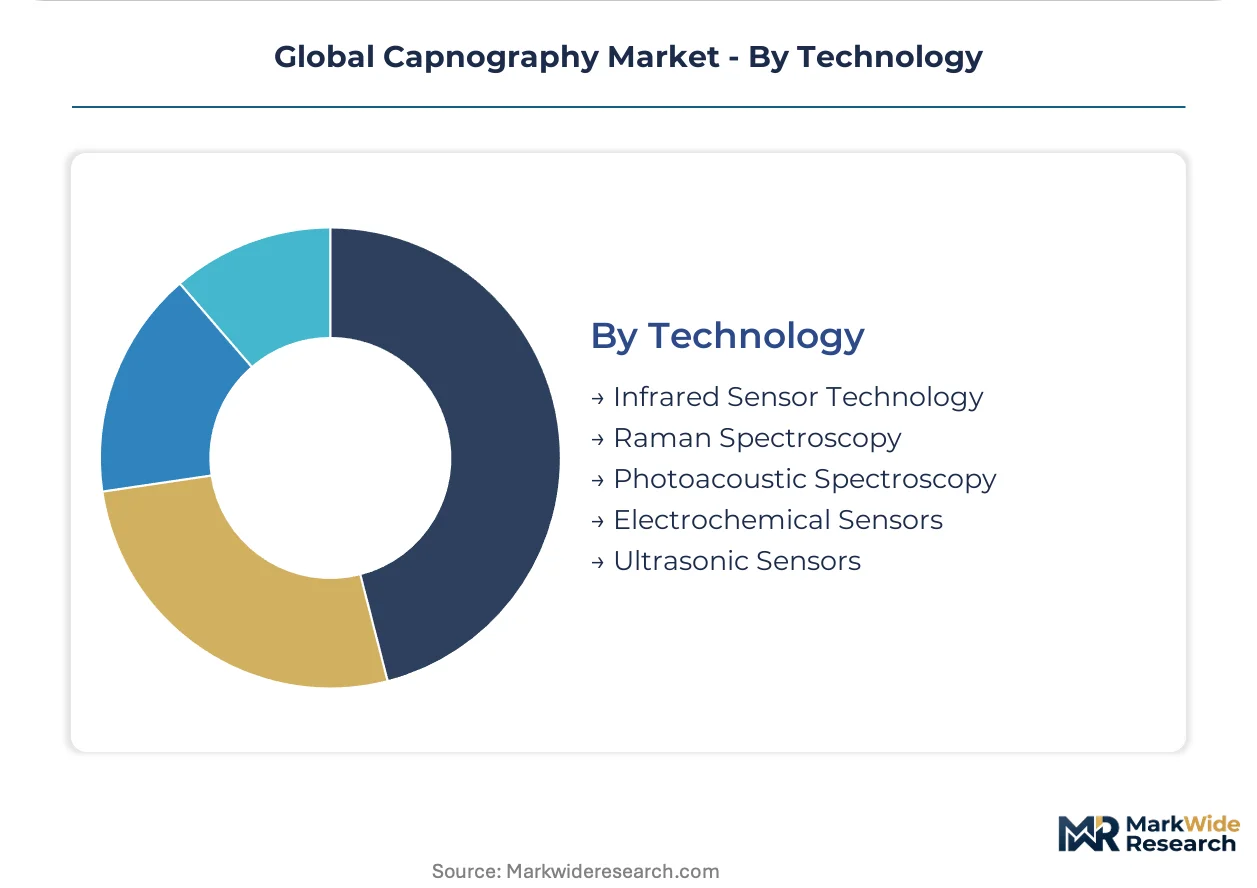
Technology segmentation tracks the displacement of legacy sensing modalities by solid-state and spectroscopic advances.
- Infrared Sensor Technology:Non-dispersive infrared absorption at specific CO2 wavelengths remains the dominant detection principle. Microstream implementations reduce sample volume requirements below 50 microliters for non-intubated patient monitoring. ISO 80601-2-55 electromagnetic compatibility testing requirements are forcing hardware redesigns for next-generation infrared platforms.
- Photoacoustic Spectroscopy:Laser-induced acoustic signal detection eliminates moving parts and enables miniaturization. Research-stage devices are targeting wearable respiratory monitoring applications with battery-constrained power budgets. EMA MDR clinical evidence requirements for novel sensing modalities extend regulatory timelines for commercial deployment.
- Raman Spectroscopy:Molecular fingerprinting through inelastic light scattering for multi-gas analysis.
- Electrochemical Sensors:Amperometric CO2 detection with liquid electrolyte cells.
- Ultrasonic Sensors:Acoustic transit time measurement for gas concentration determination.
Infrared sensor technology retains volume leadership; photoacoustic spectroscopy holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in tertiary care systems drive capnography demand concentration across North America, Western Europe, and East Asia. FDA, EMA, and PMDA regulatory frameworks shape device clearance timelines and reimbursement eligibility in each jurisdiction. Manufacturing and R&D clusters align with anesthesia safety protocol adoption rates in specific metropolitan hospital networks.
United States
CMS reimbursement mandates for EtCO2 monitoring during moderate sedation procedures lock device utilization into ambulatory surgery center workflows across Texas, Florida, and California health systems. FDA 510(k) clearance pathways under 21 CFR 870.1900 enforce Class II medical device performance standards for accuracy and alarm functionality. The Dallas-Fort Worth metroplex anchors procurement standardization initiatives across multi-hospital integrated delivery networks unbundling capnography modules from ventilator purchase agreements.
Germany
Ambulatory surgery center licensing expansion under national healthcare efficiency reforms creates demand for portable monitoring configurations in outpatient procedural settings. EMA MDR compliance demands enhanced clinical evidence and post-market surveillance for respiratory monitors distributed across European Union member states. The Baden-Württemberg region concentrates medical device engineering talent and infrared spectroscopy expertise at academic medical centers in Stuttgart and Heidelberg.
Japan
PMDA-aligned clinical guidelines mandating continuous respiratory monitoring expand installed base requirements in tertiary hospitals throughout Tokyo and Osaka metropolitan areas. METI industrial policy supports domestic manufacturing of critical care equipment through targeted R&D subsidies and regulatory harmonization initiatives. The Kanto region surrounding Tokyo anchors Nihon Kohden's localized production and region-specific regulatory dossier development for Asia-Pacific market penetration.
India
Government hospital modernization programs under the PLI scheme for medical devices incentivize localized manufacturing partnerships for critical care infrastructure buildout. CDSCO medical device registration requirements are converging with international standards to streamline import substitution for respiratory monitors. The Maharashtra-Gujarat industrial corridor attracts contract manufacturing investments targeting cost-sensitive hospital procurement in tier-2 and tier-3 cities.
United Kingdom
NHS procurement frameworks for anesthesia and critical care equipment standardize EtCO2 monitoring specifications across acute trusts in London, Birmingham, and Manchester. MHRA post-Brexit regulatory autonomy maintains alignment with ISO 80601-2-55 international safety standards while adapting EU MDR transition timelines. The Oxford-Cambridge-London golden triangle concentrates biomedical engineering research partnerships advancing signal processing algorithms for motion artifact reduction.
Global Capnography Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent technology maturities and clinical workflow integrations. The vendor base organizes around three strategic archetypes: diversified critical care conglomerates bundling capnography with ventilator platforms, standalone monitoring specialists leveraging proprietary signal processing algorithms, and regional manufacturers exploiting localized regulatory dossiers and cost-advantaged production. Dominant competitive moves include strategic partnerships for EHR interoperability and portfolio diversification into disposable sensor formats to capture recurring revenue streams.
Among diversified medical technology conglomerates, Medtronic and Koninklijke Philips N.V. occupy positions exemplifying integrated critical care portfolio strategies. Masimo represents the standalone monitoring specialist archetype with emphasis on advanced algorithm development. Nihon Kohden Corporation anchors the Asia-Pacific regional specialist tier through localized manufacturing and market-specific regulatory navigation. Drägerwerk AG & Co. KGaA exemplifies the European engineering-focused fabricator with deep anesthesia workstation integration. These five entities collectively illustrate the competitive tension between scale-driven platform bundling and precision-focused technology differentiation.
| Leading Market Players |
|---|
| Medtronic |
| Masimo |
| Koninklijke Philips N.V. |
| Drägerwerk AG & Co. KGaA |
| Becton, Dickinson and Company |
| GE Healthcare |
| Nihon Kohden Corporation |
| Hamilton Medical |
| ICU Medical |
| Others |
Supply & Pricing Matrix
Baden-Württemberg's precision engineering cluster concentrates infrared spectroscopy component fabrication, concentrating supply-side leverage among German sensor manufacturers who dictate terms to downstream device assemblers. This geographic concentration cascades through disposable sensor pricing, where single-use nasal cannula costs dominate lifetime ownership economics and amplify procurement committee bargaining power.
Pricing Analysis
Cost-plus contracts with medical-grade polymer indexation dominate disposable sensor procurement between ambulatory surgery centers and contract manufacturers. Three-tier pricing structure across premium FDA-cleared, standard CE-marked, and economy non-certified tiers separates institutional buyers from cost-sensitive home healthcare providers. Pricing pressure stems from integrated delivery networks unbundling EtCO2 modules from mandatory ventilator agreements. Ambulatory surgery centers exhibit highest price sensitivity due to constrained capital budgets; tertiary hospital systems demonstrate lowest sensitivity given CMS reimbursement lock-in.
Supply Chain Analysis
Upstream feedstock for infrared absorption cells draws from germanium substrate suppliers concentrated in Germany, Japan, and the United States. Solid-state emitter fabrication rests on indium gallium arsenide wafer processing and precision optical coating capabilities. Single-source vulnerability persists for micro-electromechanical system gas sampling valves sourced from specialized Taiwanese foundries. Distribution runs through group purchasing organizations consolidating hospital procurement across multi-facility networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Disposable sensor replacement cycles represent a service-attach opportunity expanding faster than hardware unit sales, as single-use nasal cannulas and airway adapters generate recurring revenue streams tethered to installed monitor bases.
For Market Incumbents: Pre-empt pulse oximetry substitution threats by deepening algorithm differentiation for respiratory depression detection in procedural sedation workflows. Lock in integrated delivery network contracts through open-protocol EHR connectivity investments. Prioritize backward integration into solid-state infrared emitter production to defend margin position against component cost volatility. For New Entrants and Emerging Players: India's tier-2 and tier-3 city hospital modernization under PLI scheme incentives offers the most penetrable white-space for localized manufacturing partnerships. Target emergency medical services in Texas and Florida with solid-state portable configurations optimized for field durability. Pursue CDSCO registration convergence with ISO 80601-2-55 standards as the primary go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue medical device play because disposable sensor attach rates and replacement frequency generate predictable cash flows decoupled from hardware replacement cycles. Target acquisition candidates with proprietary signal processing algorithms and established GPO contracts. Monitor CMS reimbursement policy shifts for outpatient procedural settings as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Disposable Sensor Format Expansion | Captures recurring revenue streams from installed monitor bases across ambulatory surgery centers. |
| FDA 510(k) Clearance Pathway Acceleration | Compresses time-to-market for Microstream infrared platforms targeting non-intubated patient segments. |
| Hospital System Partnership | Secures enterprise contracts with Texas and California integrated delivery networks unbundling EtCO2 modules. |
| Software Companion Development | Integrates AI-embedded waveform analysis for automated respiratory pattern recognition in critical care. |
| Reimbursement Strategy | Aligns device positioning with CMS mandates for EtCO2 monitoring in moderate sedation procedures. |
Research Methodology
A spread of perspectives from anesthesiologists, hospital procurement managers, biomedical engineers, and GPO contracts managers converged on the working assumptions driving this analysis. Primary fieldwork with integrated delivery network standardization committees and secondary validation against FDA 510(k) clearance databases, CMS reimbursement bulletins, EMA MDR guidance documents, and hospital procurement contract registries anchored the evidence base. Bottom-up unit economics modeling triangulated against top-down market sizing from regulatory filing volumes.
Demand-supply-balance framing structured the analytical approach across the analysis window, with segmentation dimensions spanning product architecture, application setting, end-user infrastructure, and technology modality. CAGRs derived from installed base expansion rates, replacement cycle compression, and disposable sensor attach rate trajectories. Forecast inputs incorporated PMDA-aligned protocol adoption timelines and ambulatory surgery center licensing expansion patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified critical care conglomerates or standalone algorithm specialists would shift outcomes beyond modeled ranges. Cross-checking against CMS Medicare claims data for EtCO2 procedure coding is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Stent Delivery Systems Market
Medical Devices
Global Hydrogel Based Drug Delivery System Market
Medical Devices
Bionic Devices Market
Medical Devices
Brain-On-Chip Model Market
Medical Devices
Global Medical Laser Systems Market
Medical Devices
Robotic Angiography Systems Market
Medical Devices
Global MRI Safe Cardiac Resynchronization Therapy Device Market
Medical Devices
Prosthetic Liners Market
Medical Devices
Self-Injections Market
Medical Devices
Life Science and Chemical Instruments Market
Medical Devices
Hybrid Grafts Market
Medical Devices
Massage Equipment Market
Medical Devices
Nerve Locator Stimulator Market
Medical Devices
Nano Healthcare Technology Market
Medical Devices
Global Blood Warmer Devices Market
Medical Devices
Spinal Fusion Market