
 Canola Protein Market | 2026-2036
Canola Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Canola Protein Market Intelligence
The capability gap in proprietary protein isolation and purification technology is bifurcating the market between large-scale producers and specialized innovators. Large agribusinesses like Archer Daniels Midland Company leverage extensive canola crushing infrastructure for commodity-grade concentrates. In contrast, specialists such as Burcon NutraScience Corporation and Merit Functional Foods differentiate through high-purity isolates developed for specific, high-value food and beverage applications.
Canola protein is a plant-based ingredient derived from the meal left after oil extraction from specific cultivars of rapeseed (Brassica napus). It is processed into forms with varying protein content; isolates typically achieve purity levels above 90% through advanced fractionation techniques. While concentrates dominate volume due to their established use in animal feed, high-purity isolates command a premium in the nutritional supplements and meat alternatives sectors. The beverages application represents a key growth frontier, contingent on overcoming persistent solubility and flavor challenges.
Market access is governed by food safety and novel food regulations, such as the FDA's Generally Recognized as Safe (GRAS) notifications in the United States. In Europe, producers must navigate the European Food Safety Authority's rigorous approval process for novel ingredients, while Health Canada sets standards for domestic production. Future success for participants depends on securing regulatory approvals while advancing processing technologies to improve sensory profiles for consumer-facing products.
Market Dynamics
The technical divide between commodity and specialty processing is the central force shaping the canola protein market. This bifurcation stems from the high-capital, proprietary nature of protein isolation technologies, creating distinct competitive arenas for large-scale crushers and specialized ingredient innovators.
Growth Catalysts
- Clean Label Demand:Consumer preference for plant-based, non-GMO, and allergen-free ingredients in the meat alternatives and nutritional supplement sectors accelerates the specification of canola protein over other plant sources.
- Extraction Technology:Advances in non-solvent, cold-press extraction methods are improving the functional and sensory properties of canola protein, making it more viable for applications in beverages and dairy alternatives.
- Regulatory Pathways:The establishment of clear regulatory frameworks, such as the Generally Recognized as Safe (GRAS) notification process by the FDA in the United States, provides producers with a defined path to commercialization.
Market Restraints
- Sensory and Functional Hurdles:Persistent challenges related to bitter taste, dark color, and poor solubility in certain pH ranges limit the application of canola protein, particularly in the high-growth beverage and dairy alternative segments.
- Regulatory Scrutiny:The European Food Safety Authority's rigorous and lengthy approval process for novel foods creates a significant barrier to entry and slows market penetration for new canola protein ingredients within the EU.
- Supply Chain Concentration:The geographic concentration of canola cultivation and primary processing in regions like Western Canada exposes the global supply chain to risks from localized climate events, logistical disruptions, or policy changes.
Strategic Opportunities
- Beverage Formulation:Overcoming solubility and off-flavor issues presents a major opportunity to penetrate the dairy alternative and ready-to-drink protein beverage markets, which command premium pricing for functional ingredients.
- Specialized Nutrition:Development of high-purity isolates with specific functional or hypoallergenic properties opens avenues in niche, high-value markets such as infant formula, clinical nutrition, and sports performance products.
- Geographic Expansion:Targeting consumer markets in Asia-Pacific countries with rising incomes and increasing interest in plant-based diets offers significant growth potential beyond the established markets of North America and Europe.
Industry Challenges
- Capital-Intensive Processing:Constructing and operating facilities with the advanced fractionation and purification technologies required for high-purity isolates demands substantial capital investment, creating a high barrier for new entrants.
- Multi-Jurisdictional Compliance:Navigating disparate food safety and novel food regulations across key markets, including the US, EU, and Canada, creates significant operational complexity and extends product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canola Protein Market |
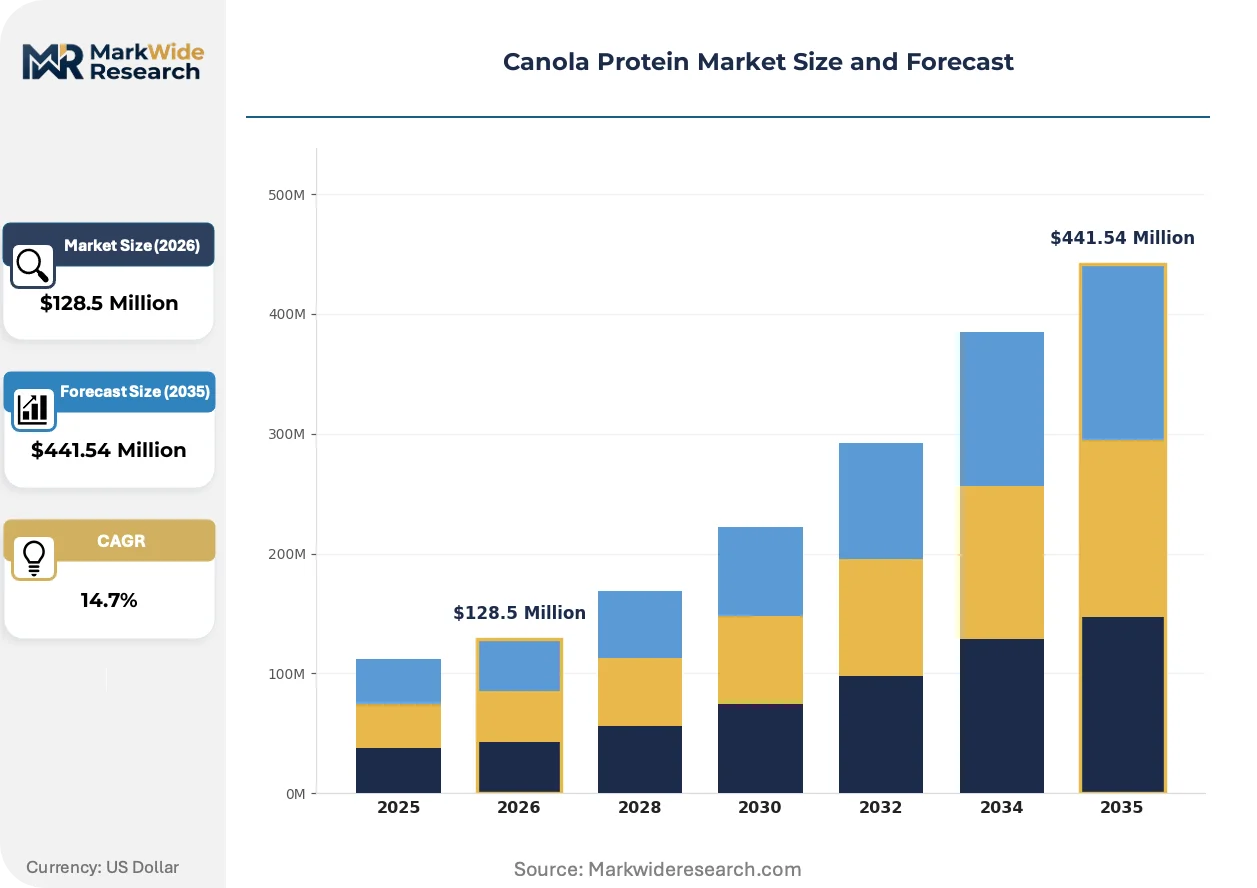
| Market Size in 2026 | $128.5 Million |
| Market Size in 2035 | $441.54 Million |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolates, Concentrates, Flour, Textured Protein, Hydrolysates Application: Bakery, Beverages, Nutritional Supplements, Meat Alternatives, Dairy Alternatives End Use Industry: Food Processing, Sports Nutrition, Personal Care, Animal Feed, Nutraceuticals Packaging Type: Pouches, Bulk Bags, Rigid Containers, Vacuum Packaging, Sachets |
| Companies Covered | Burcon NutraScience Corporation, Archer Daniels Midland Company, Bunge Limited, Cargill, Inc., Tate & Lyle, Roquette Frères, Koninklijke DSM N.V., CHS Inc., Merit Functional Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canola Protein Market Strategic Shifts & Innovations
The market's evolution is defined by processing innovations aimed at unlocking specific functionalities from the protein, moving it beyond a simple nutritional ingredient. This shift is supported by regulatory frameworks adapting to novel food sources and changing procurement behaviors among food formulators.
Advanced fractionation using methods like membrane filtration and chromatography allows for the precise separation of protein components. Food technology firms are adopting these techniques to produce high-purity isolates. This precision processing is miniaturizing the target of extraction from bulk canola meal to specific protein sub-fractions, enabling the creation of ingredients with tailored emulsifying or gelling properties for high-value applications.
Europe's Novel Food Regulation (EU) 2015/2283 sets a high bar for market access. The regulation mandates a comprehensive pre-market safety assessment by the European Food Safety Authority (EFSA) for ingredients without a significant history of consumption in the region. This process directly affects ingredient innovators targeting the European Union, requiring substantial investment in toxicological and allergenicity data to support their applications.
A notable shift in purchasing criteria is occurring among food product developers. Formulators are moving away from sourcing based purely on protein content and price, now prioritizing specific functional attributes such as water-binding capacity for meat analogs or foaming ability for dairy-free toppings. This trend is most visible in the plant-based cheese and baked goods categories, where ingredient functionality directly determines final product texture and quality.
Canola Protein Market Segmentation
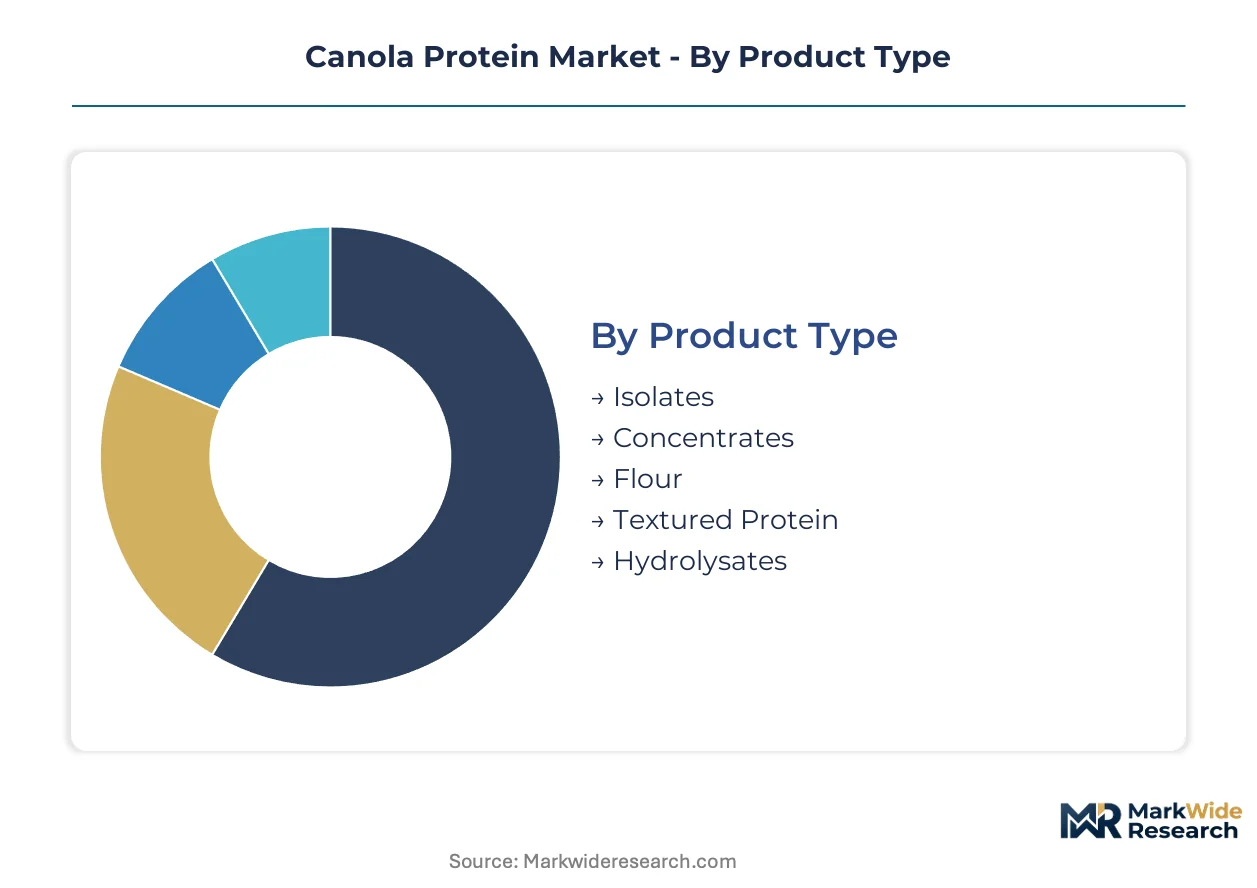
Market segmentation for canola protein clarifies how diverse product forms meet varied industrial and consumer needs. This analysis highlights the distinct functional requirements across different applications and end-use sectors. Understanding these divisions is essential for strategic product development and market penetration.
Product Type:
The market for canola protein is largely characterized by the channel mix through which different product types are distributed, influencing their adoption rates across industries.
- Isolates:These highly purified forms of canola protein typically achieve purity levels exceeding 90% through advanced fractionation techniques. Demand is concentrating in the nutritional supplements and meat alternatives sectors, driven by their superior functional properties and neutral flavor profile.
- Concentrates:Canola protein concentrates contain 60-90% protein, often produced through simpler extraction methods like aqueous extraction. Their established use in animal feed and cost-effectiveness drive significant volume, particularly in regions with large livestock industries.
- Flour:This minimally processed form retains more of the original meal components, offering a cost-effective protein enrichment for baked goods.
- Textured Protein:Produced via extrusion, this form provides fibrous texture suitable for meat analog applications.
- Hydrolysates:Enzymatic treatment breaks down proteins into smaller peptides, enhancing digestibility and solubility for specialized nutrition products.
By volume, Concentrates lead. By growth pace, Isolates are ahead.
Application:
Segmentation by application reveals distinct functional requirements for canola protein, shaping product innovation and formulation strategies across various food and beverage categories.
- Meat Alternatives:Canola protein provides essential amino acids and functional properties like emulsification and water binding for plant-based burgers and sausages. This sector drives significant demand for high-purity isolates, requiring specific textural and sensory attributes.
- Beverages:Inclusion in ready-to-drink protein shakes and dairy alternatives requires canola protein with excellent solubility and minimal off-flavors. Overcoming these challenges is critical for market expansion in this premium segment.
- Bakery:Canola protein enhances nutritional value and texture in breads, pastries, and gluten-free products.
- Nutritional Supplements:Used in protein powders and bars, canola protein offers a plant-based source for muscle recovery and general wellness.
- Dairy Alternatives:Canola protein contributes to the protein content and mouthfeel of plant-based milks, yogurts, and cheeses.
The Meat Alternatives segment is expanding most quickly. Beverages also show significant potential for future growth.
End Use Industry:
The varied end-use industries define the primary customer types and their specific procurement criteria for canola protein, from large-scale industrial buyers to niche specialty formulators.
- Food Processing:This broad category encompasses the use of canola protein in a wide array of consumer food products, including processed foods and snacks. Demand here is driven by cost-effectiveness and the ability to enhance nutritional profiles without significantly altering sensory characteristics.
- Animal Feed:Canola protein concentrates are widely incorporated into livestock, poultry, and aquaculture feeds as a cost-efficient protein source. This segment represents a foundational volume driver for commodity-grade canola protein.
- Sports Nutrition:High-purity canola protein isolates are utilized in products targeting athletes for muscle building and recovery.
- Personal Care:Canola protein finds applications in cosmetics and hair care products for its conditioning and moisturizing properties.
- Nutraceuticals:This segment uses canola protein in functional foods and supplements for specific health benefits beyond basic nutrition.
Food Processing maintains the largest share. Nutraceuticals are climbing the fastest in terms of adoption.
Packaging Type:
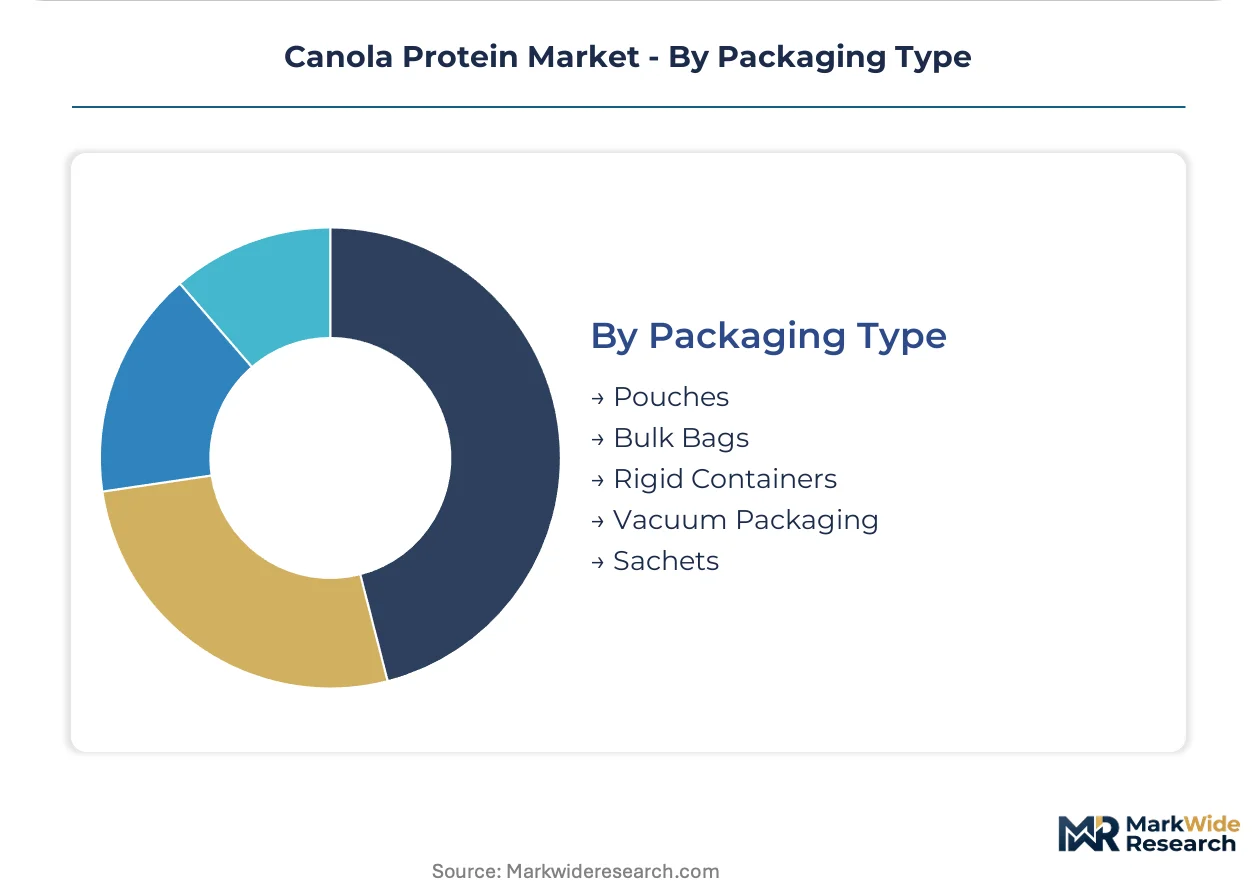
Segmentation by packaging type reflects the typical volume requirements and distribution logistics across the canola protein supply chain, from bulk industrial use to consumer-ready formats.
- Bulk Bags:Large industrial quantities of canola protein, often concentrates or flours, are transported and stored in bulk bags. This packaging is essential for large-scale food manufacturers and animal feed producers, optimizing logistics and reducing costs.
- Pouches:Flexible pouches are increasingly used for consumer-facing protein powders and smaller ingredient packs due to their convenience and reduced material usage. This format appeals to individual consumers and smaller-scale food formulators.
- Rigid Containers:Plastic tubs or drums are used for specialized protein isolates or for smaller industrial batches requiring robust protection.
- Vacuum Packaging:This method extends shelf life for sensitive protein products by removing oxygen, preventing degradation and maintaining freshness.
- Sachets:Single-serving sachets cater to convenience and portion control, popular in nutritional supplements and instant beverage mixes.
Bulk Bags account for the majority of volume. Pouches are on the steepest expansion trajectory for consumer products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The export-import balance for canola protein reflects differing regional strengths in cultivation, processing, and consumer demand. Key producing nations often supply specialized ingredients to markets with advanced food processing capabilities. Regulatory frameworks significantly influence market access and product development across these diverse geographies.
Canada
Demand for plant-based proteins drives canola protein consumption in North America, particularly in meat alternatives. Health Canada's food regulations provide a clear pathway for novel ingredient approval. Saskatchewan remains a central hub for canola cultivation and primary processing, supporting a robust supply chain.
United States
The United States market is a significant consumer of canola protein, with demand stemming from the nutritional supplements and functional food sectors. The FDA's Generally Recognized as Safe (GRAS) notification process facilitates commercialization for new ingredients. Food technology clusters in California are actively integrating canola protein into innovative product formulations.
Netherlands
The Netherlands serves as a critical entry point for canola protein into the European market, driven by its advanced food innovation ecosystem. Producers must navigate the European Food Safety Authority's (EFSA) rigorous novel food approval process. Food tech valleys around Wageningen are pioneering new applications for high-purity canola isolates.
China
China's large population and growing interest in plant-based diets present substantial demand for alternative protein sources like canola. The country's national food safety standards govern ingredient approval and market entry. Major food processing zones in the Yangtze River Delta are exploring canola protein for diverse food applications.
Germany
Germany represents a major European market for food ingredients, with demand for canola protein driven by its use in bakery and dairy alternatives. German food regulations align with broader EU standards for novel food ingredients. Industrial food clusters in North Rhine-Westphalia are actively incorporating canola protein into new product lines.
Canola Protein Market Key Industry Players
Concentration sits with large agribusinesses leveraging existing infrastructure, while specialized innovators focus on high-purity applications. The market exhibits a tiered structure, with commodity-grade concentrates and high-value isolates serving distinct customer segments. Competitive moves often involve capacity expansion for commodity players and technology licensing for specialty ingredient developers.
At the scale-driven end, Archer Daniels Midland Company and Bunge Limited exemplify the integration of canola protein production within extensive agricultural processing operations. These entities focus on volume and cost-effectiveness for commodity-grade concentrates. In contrast, Burcon NutraScience Corporation anchors the high-purity segment, representing specialized innovators developing advanced isolation technologies for specific functional attributes. Merit Functional Foods also operates in this space, focusing on high-purity isolates for premium food and beverage applications.
| Leading Market Players |
|---|
| Burcon NutraScience Corporation |
| Archer Daniels Midland Company |
| Bunge Limited |
| Cargill, Inc. |
| Tate & Lyle |
| Roquette Frères |
| Koninklijke DSM N.V. |
| CHS Inc. |
| Merit Functional Foods |
| Others |
Cost & Logistics Intelligence
Canola crushing infrastructure scale economies underpin the market's pricing dynamics, creating a distinct bifurcation between commodity and specialty protein segments. This scale dictates the investment required for advanced protein isolation, influencing both supply concentration and product pricing.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake agreements for canola protein concentrates. Price differentiation stems from protein purity levels and specific functional attributes like solubility or emulsification. Pricing softness reflects the availability of alternative plant proteins in the commodity segment. Food processors purchasing high-purity isolates demonstrate lower price sensitivity due to specific formulation requirements.
Supply Chain Analysis
Western Canadian climate vulnerability underwrites the geographic concentration of canola cultivation and primary crushing. The supply chain draws from rapeseed meal as the primary raw material, which then undergoes various extraction and fractionation processes. Single-source vulnerability to localized climate events represents a significant structural risk. Distribution runs through a hybrid model, combining direct sales to large food manufacturers with specialized ingredient distributors for niche applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The canola protein market represents a high-growth disruption, driven by advanced cold-press extraction technology improving protein functionality. This technological inflection unlocks new applications in premium food and beverage segments, demanding strategic foresight.
For Market Incumbents: Shield existing market share through strategic investments in next-generation processing technologies, particularly advanced fractionation. This counters the threat from specialized innovators offering superior functional isolates to food formulators. Expand capacity in key regions like Saskatchewan to maintain cost leadership for commodity-grade concentrates, securing raw material supply. Invest in regulatory expertise to navigate complex global approval processes efficiently.
For New Entrants and Emerging Players: Differentiate on novel functional properties, targeting specific gaps in the beverage and dairy alternative segments. The most penetrable segment remains high-purity isolates for specialized nutrition products, including infant formula. A go-to-market angle emphasizing superior sensory profiles and clean label credentials offers a strong competitive entry in health-conscious consumer markets. Focus on niche applications requiring unique textural attributes.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized ingredient innovators with proprietary isolation technologies and established regulatory approvals. This market offers long-term viability, underpinned by sustained consumer shifts towards plant-based diets and nutritional supplements. The signal to watch is the successful commercialization of canola protein in mainstream ready-to-drink beverages across multiple geographies. Target firms with robust intellectual property portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Western Canada | Ensures stable supply of raw material for protein extraction, supporting volume growth for concentrates. |
| Advanced Fractionation R&D | Unlocks superior functional properties for isolates, enabling penetration into premium food applications. |
| Regulatory Approval Acceleration | Secures market access in key regions like the EU, reducing time-to-market for novel ingredients. |
| Partnerships with Food Tech Innovators | Co-develops tailored canola protein solutions for emerging plant-based product categories. |
| Targeted Beverage Formulation | Addresses solubility and flavor challenges, opening significant growth in the premium dairy alternative sector. |
Research Approach
Operator-level perspectives from food scientists, R&D directors, procurement managers, and regulatory specialists anchored the qualitative base of this analysis. Primary interviews were conducted with industry experts across North America and Europe, validated through extensive secondary research. This approach enabled comprehensive bottom-up and top-down triangulation of market trends.
Sensitivity analysis informed the analytical framework used to project market trajectories across the analysis window. The model integrated segmentation dimensions such as product type, application, end-use industry, and geographic region. Compound annual growth rates were derived from historical data and projected forward using a multi-variable regression approach. Key forecast inputs included plant-based food adoption rates and regulatory approval timelines.
Material uncertainties — such as unforeseen regulatory shifts or rapid technological breakthroughs — sit outside the modeled envelope, influencing future market dynamics. Forecasts reflect assumptions documented regarding current market conditions and anticipated developments. Practitioners should keep alternative scenarios live as consumer preferences and supply chain resilience evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Europe Dairy Ingredients Market
Ingredients
Pomegranate Peel Polyphenol Complex Market
Ingredients
Farnesene Market
Ingredients
Asia-Pacific Gelatin Market
Ingredients
Soybean Oil Market
Ingredients
North America Carrageenan Market
Ingredients
Encapsulated Salt Market
Ingredients
Lupin Flour Market
Ingredients
Wheat Malt Market
Ingredients
Chlorella Ingredients Market
Ingredients
Sodium Reduction Ingredients Market
Ingredients
Asia-Pacific Lipids Market
Ingredients
PDO/PGI-Linked Mediterranean Ingredient Collections Market
Ingredients
Starch-Derived Fiber Market
Ingredients
Non-GMO Soya Market
Ingredients
Polydextrose Ingredients Market