
 Soybean Oil Market | 2026-2036
Soybean Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Soybean Oil Market Analysis
Foodservice buyers are unwinding long-term contracts with traditional packagers as biofuel blenders capture larger procurement slots. Bunge Limited leverages its crush footprint across the US Gulf and Paraná River corridors to secure origination premiums. Cargill, Incorporated anchors its position through direct farmer relationships and inland elevator networks. Archer Daniels Midland Company dominates export logistics with terminal assets at Santos and New Orleans.
Soybean oil is a triglyceride vegetable oil extracted from Glycine max seeds through mechanical pressing or solvent extraction with hexane, yielding a pale yellow liquid with a smoke point of 230°C for refined grades and a fatty acid profile dominated by linoleic and oleic acids. Its primary commercial purpose spans frying and baking mediums, industrial lubricant feedstocks, and biodiesel methyl ester production. Refined product type commands the largest volume share due to neutral flavor and extended fry-life specifications demanded by quick-service restaurant chains, while biofuels application generates the fastest value growth as renewable diesel hydrotreaters expand capacity. Organic product type occupies a narrow but defensible margin pool anchored by infant formula and clean-label food manufacturers in Western Europe and North America.
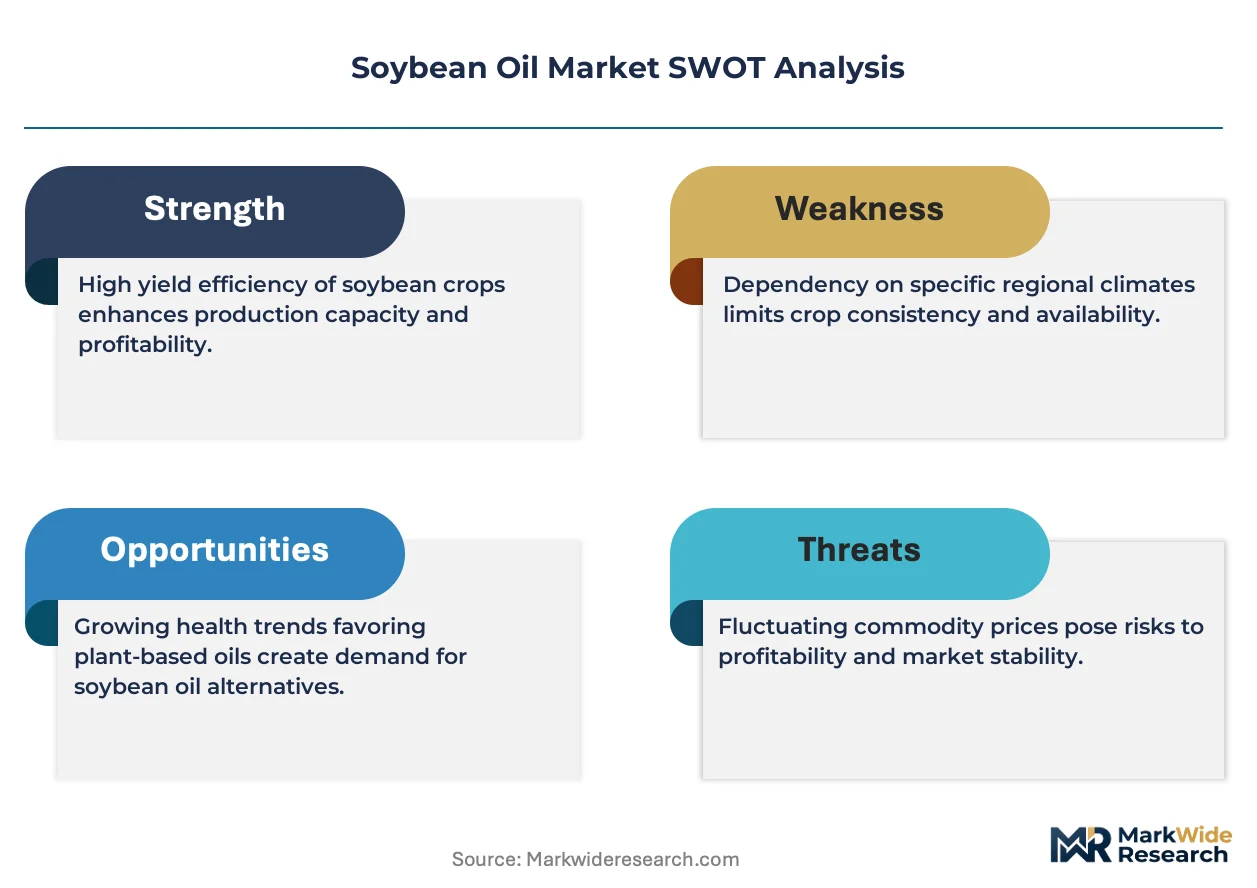
The EPA Renewable Fuel Standard and California Air Resources Board LCFS program shape US demand by mandating biomass-based diesel volumes and assigning carbon intensity scores that favor domestic crush over imported palm oil alternatives. REACH registration requirements in Europe and EUDR traceability rules constrain market access for non-compliant South American exporters. Stakeholders must monitor crush margin spreads between soybean oil, meal, and biodiesel RIN values to time capacity commitments.
Market Dynamics
Renewable diesel hydrotreater capacity expansion is redirecting soybean crush volumes away from food applications toward fuel markets, tightening edible oil supply chains and compressing foodservice contract tenors.
Growth Catalysts
- California LCFS Carbon Intensity Scoring:The program assigns favorable carbon scores to domestic soybean oil over imported palm oil alternatives, pulling crush capacity toward West Coast renewable diesel refiners.
- Biofuel Blender Procurement Slots:Large renewable fuel producers are capturing multi-year origination contracts that previously anchored foodservice supply chains, creating guaranteed offtake for crush operators.
- Paraná River Infrastructure:Expanded barge loading terminals and export elevators in Rosario and San Lorenzo accelerate South American soybean oil movement to Atlantic markets.
Market Restraints
- Soybean Input Cost Volatility:Weather-driven yield variability in US Midwest and Brazilian Cerrado regions transmits directly into crush margin compression and oil price instability.
- Indonesian and Malaysian Palm Oil Substitution:Lower-cost tropical oil alternatives capture baking and frying applications where carbon intensity regulations do not apply, capping soybean oil price ceilings.
- EUDR Traceability Compliance Burden:European Union Deforestation Regulation geolocation and chain-of-custody requirements impose documentation costs that disadvantage smaller South American exporters.
Strategic Opportunities
- High-Oleic Soybean Varieties:Seed technology delivering improved oxidative stability opens extended fry-life applications in quick-service restaurant chains and industrial snack manufacturing.
- India Edible Oil Deficit:The country's structural shortfall in domestic oilseed production creates import dependency that soybean oil suppliers can address through direct bulk vessel contracts.
- Renewable Diesel Tax Credit Stacking:Blenders capturing IRA biomass-based diesel credits alongside state-level low-carbon fuel programs generate margin pools that support premium crush origination pricing.
Industry Challenges
- Hydrotreater Feedstock Specification Tightening:Renewable diesel refiners impose increasingly stringent free fatty acid and moisture limits, requiring crush operators to upgrade degumming and refining infrastructure.
- Cross-Sector Talent Competition:Crush facilities and biofuel plants compete for the same process engineering and refinery operations skill sets, elevating compensation costs and extending hiring timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soybean Oil Market |
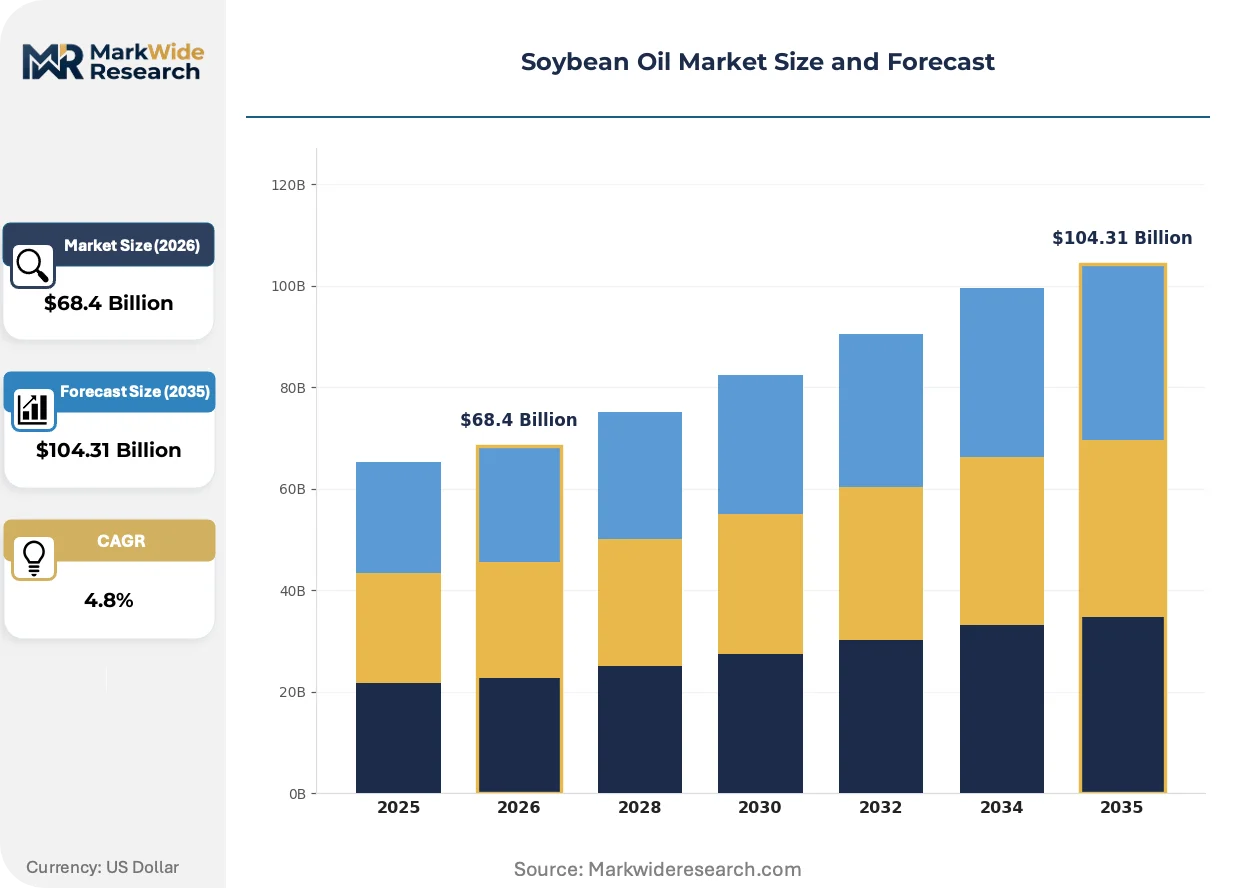
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $104.31 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined, Crude, Organic, Non-GMO Application: Food Processing, Biofuels, Cosmetics, Pharmaceuticals Distribution Channel: Retail, E-commerce, Wholesale, Direct Sales Ingredient Form: Liquid, Solid, Emulsified, Blended |
| Companies Covered | Archer Daniels Midland Company, Bunge Limited, Cargill, Incorporated, Louis Dreyfus Company B.V., Wilmar International Limited, COFCO Corporation, Richardson International Limited, CHS Inc., Fuji Oil Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soybean Oil Market Emerging Trajectories
Processing technology and regulatory frameworks are converging to transform how soybean oil moves from farm gate to end-use, with implications for asset deployment and contract structures across the value chain.
Enzymatic interesterification systems are replacing chemical catalysts in refined oil modification, enabling processors to tailor melting profiles and crystallization behavior for specific bakery and confectionery applications. North American and European margarine manufacturers are adopting these systems to eliminate trans-fat labeling requirements and simplify ingredient declarations. This enzymatic approach is miniaturizing the scale of modification equipment needed, allowing mid-size refiners to enter premium shortening markets previously dominated by integrated multinationals.
EPA's Renewable Fuel Standard volume obligations and California's LCFS carbon intensity benchmarks are tightening in parallel, creating overlapping compliance obligations for fuel producers that favor domestic crush over imported alternatives. Refiners are responding by securing direct origination relationships with Iowa, Illinois, and Indiana crush facilities, bypassing traditional merchant oil channels. The biofuel application segment bears the greatest compliance burden, with blenders building dedicated supply chains that lock out foodservice buyers from preferred origination zones.
Food manufacturers are compressing supplier qualification cycles and unbundling long-term contracts into shorter, index-linked agreements with multiple-origin flexibility clauses. Quick-service restaurant chains and industrial bakeries are driving this restructuring, seeking to avoid stranded volume commitments when biofuel blenders bid crush capacity away from edible markets. The United States foodservice sector exhibits the most pronounced contract tenor compression, with annual procurement cycles replacing three- to five-year supply agreements.
Soybean Oil Market Segmentation
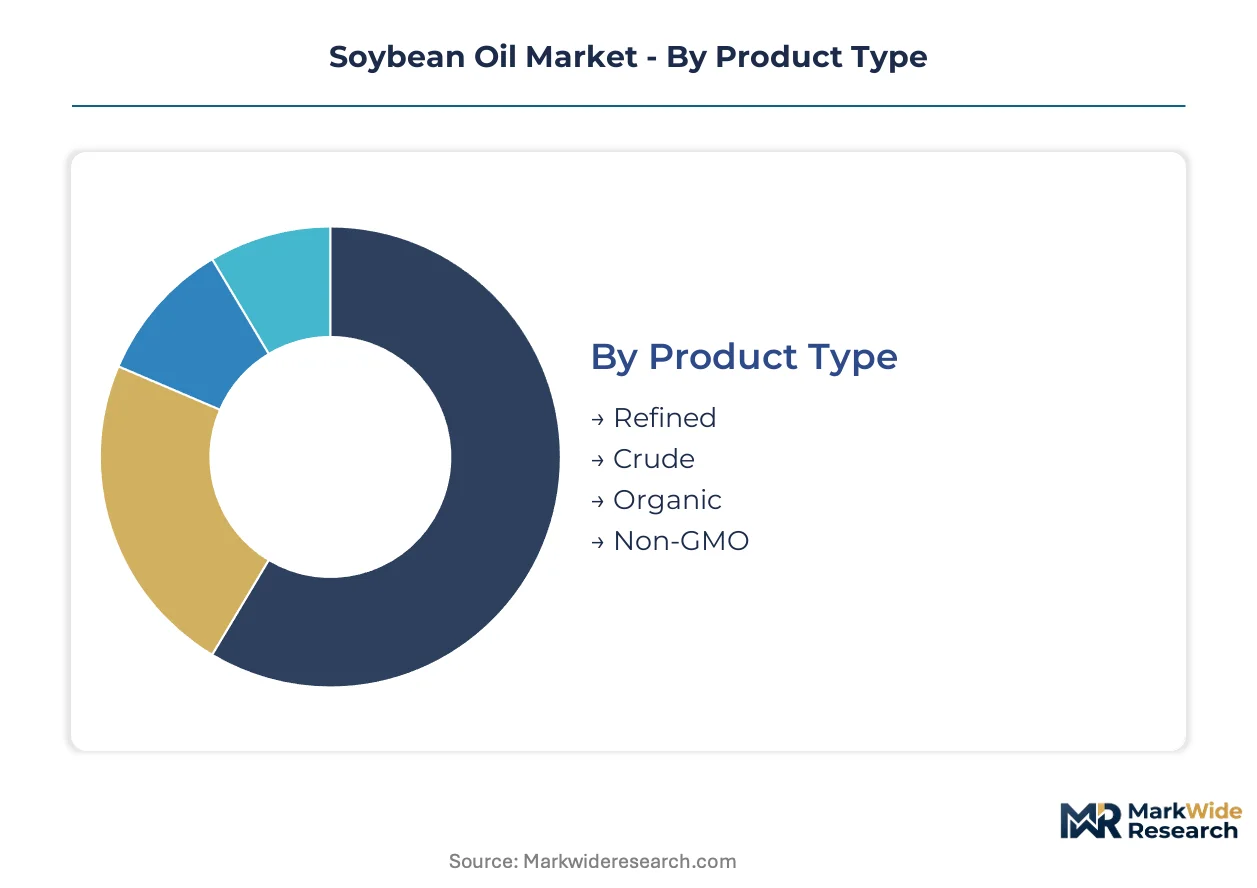
Soybean oil segmentation reveals divergent margin architectures across processing grades and end-use applications. Crush operators allocate capacity between food-grade premiums and biofuel volume plays based on RIN value spreads and carbon intensity scoring differentials.
Product Type:
Margin pools concentrate in certified grades where regulatory compliance creates pricing power, while commodity refined products compete on scale economies and crush efficiency.
- Refined:Degummed, neutralized, bleached, and deodorized oil meeting smoke point specifications above 230°C. Quick-service restaurant chains in the United States specify this grade for extended fry-life performance, though biofuel blenders now capture equivalent procurement volumes through renewable diesel offtake agreements.
- Organic:Crush derived from certified non-GMO seed stock with full traceability documentation. Infant formula manufacturers in Western Europe and North American clean-label food producers sustain premium pricing through supply scarcity and EUDR-compliant chain-of-custody systems.
- Crude:Degummed oil retaining phospholipids and free fatty acids above food-grade thresholds. Industrial lubricant compounders and early-stage biodiesel methyl ester producers absorb this tier at crush-parity pricing.
- Non-GMO:Identity-preserved crush from certified seed varieties. Japanese and South Korean food manufacturers specify this grade for consumer labeling requirements, with premiums sustained by IP handling costs and limited origination zones.
The dominant share belongs to Refined, while Organic is closing the gap fastest.
Application:
Volume concentration tracks regulatory mandate intensity, with compliance-driven segments commanding origination priority over discretionary foodservice procurement.
- Biofuels:Renewable diesel hydrotreater feedstock and biodiesel methyl ester production. California LCFS carbon intensity scoring and EPA Renewable Fuel Standard obligations pull crush capacity toward West Coast refiners, with blenders securing multi-year origination contracts that displace traditional foodservice supply chains.
- Food Processing:Frying mediums, bakery shortenings, and margarine bases. Quick-service restaurant chains and industrial bakeries are compressing contract tenors to annual cycles as biofuel procurement captures preferred crush windows.
- Cosmetics:Emollient and surfactant feedstocks for personal care formulations. European REACH registration requirements constrain supplier qualification, limiting participation to integrated crush operators with dedicated cosmetic-grade refining trains.
- Pharmaceuticals:Excipient and active ingredient carrier applications. FDA drug master file requirements and USP-NF monograph compliance create narrow qualified supplier lists with extended qualification timelines.
Biofuels commands origination priority through mandate-backed procurement, while Food Processing defends volume through reformulation flexibility and shorter contract structures.
Distribution Channel:
Channel economics reflect buyer scale and specification complexity, with direct relationships capturing margin through volume commitment and technical service integration.
- Wholesale:Bulk vessel and railcar movements to integrated food manufacturers and biofuel refiners. Bunge Limited and Cargill, Incorporated anchor this channel through captive elevator networks and export terminal assets at New Orleans and Santos.
- Direct Sales:Crush facility origination contracts with renewable diesel producers and multinational food manufacturers. EPA and California Air Resources Board compliance documentation travels through this channel exclusively.
- Retail:Branded bottled oils through supermarket and club store networks. Private label concentration in the United States limits branded margin expansion.
- E-commerce:Specialty organic and non-GMO grades for clean-label consumers and small-scale foodservice. Logistics costs constrain this channel to premium-priced certified grades.
Wholesale dominates volume movement, while Direct Sales is expanding most quickly as biofuel blenders bypass merchant intermediaries.
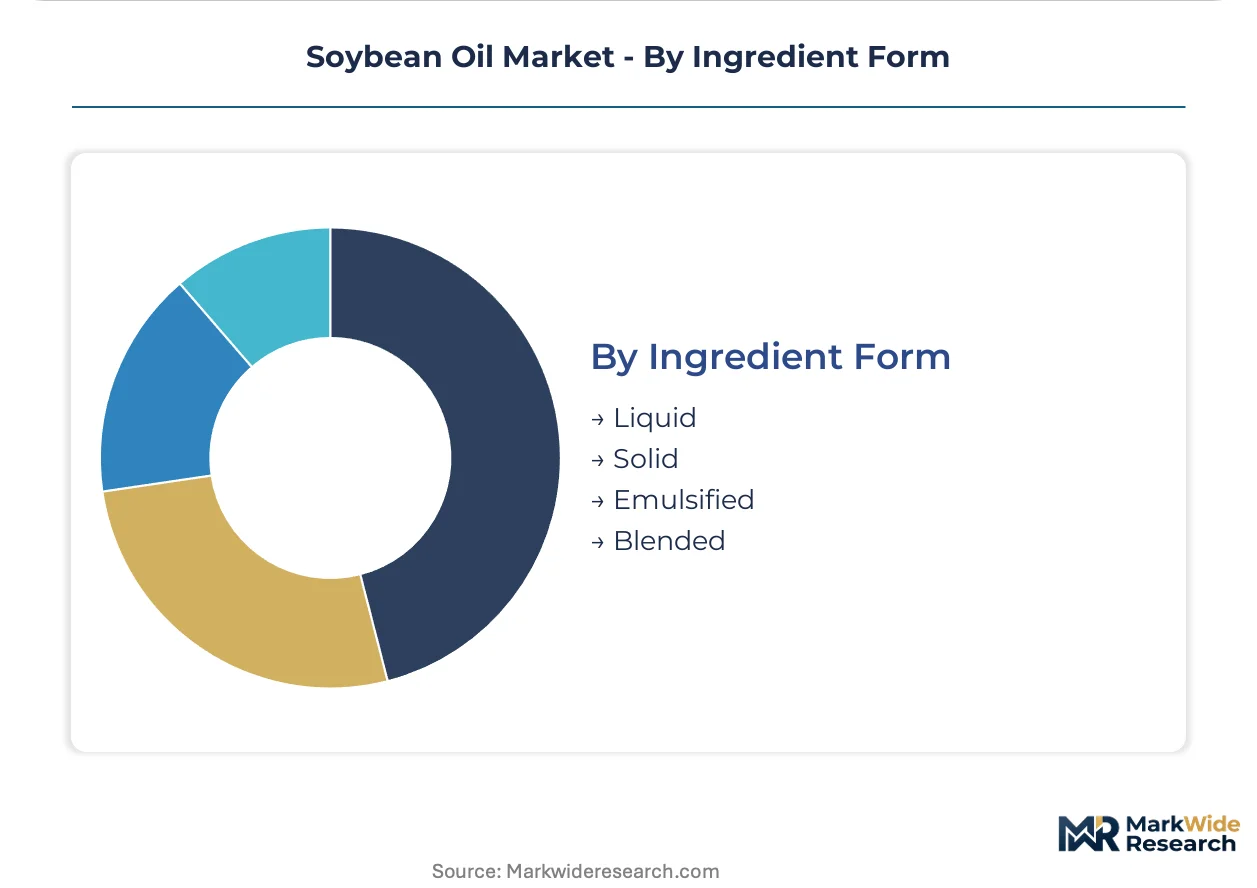
Ingredient Form:
Form selection correlates with processing intensity and end-use equipment compatibility, with liquid formats commanding scale advantages and solid forms capturing application-specific premiums.
- Liquid:Standard refined oil in bulk tankage and intermediate bulk containers. Foodservice distributors and biofuel refiners standardize on this form for pumping efficiency and blending uniformity.
- Solid:Fully hydrogenated flakes and interesterified shortening bases. North American and European margarine manufacturers specify enzymatic interesterification outputs for trans-fat elimination.
- Emulsified:Water-in-oil dispersions for bakery and confectionery applications. Industrial bakeries specify these systems for creaming consistency and shelf stability.
- Blended:Custom fatty acid profile mixtures with palm, canola, or sunflower oils. Quick-service restaurant chains specify these for fry-life extension and regional taste profile matching.
Liquid holds the volume majority, while Solid is gaining share fastest through enzymatic processing technology adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biofuel blenders and quick-service restaurant chains concentrate procurement in jurisdictions with renewable diesel mandates and established crush infrastructure. Regulatory programs in the United States, Brazil, and Argentina redirect origination volumes toward energy applications.
United States
Renewable diesel hydrotreater capacity expansion in Iowa, Illinois, and Indiana pulls crush volumes from foodservice channels. EPA Renewable Fuel Standard obligations and California Air Resources Board LCFS carbon intensity scoring favor domestic soybean oil over imported alternatives. The US Gulf Coast corridor anchors export logistics through New Orleans terminal assets.
Brazil
Paraná River barge terminals accelerate soybean oil movement to Atlantic markets for biodiesel methyl ester production. The country's national biofuel regulator, ANP, enforces biodiesel blending mandates that sustain crush operator margins. Rosario and San Lorenzo elevator clusters concentrate origination infrastructure for export-oriented processors.
Argentina
Crush facilities along the Paraná-Paraguay waterway system supply European and Asian biofuel refiners with degummed oil. EUDR traceability requirements constrain market access for non-compliant exporters. Buenos Aires province hosts the densest concentration of export-oriented crushing capacity.
China
Domestic soybean oil demand splits between food processing and industrial lubricant applications. SAMR food safety standards and GB quality specifications govern refined oil circulation. Shandong Peninsula crush clusters process imported soybeans for distribution to inland food manufacturers.
India
Structural edible oil deficits drive import dependency that soybean oil suppliers address through direct bulk vessel contracts. FSSAI packaging and labeling regulations govern retail distribution. Maharashtra and Gujarat port infrastructure handles majority inbound shipments for domestic refining.
Soybean Oil Market Vendor Landscape
Player mix skews toward integrated agricultural conglomerates with captive crush and export terminal assets. Market structure concentrates around three to five operators controlling origination corridors and hydrotreater offtake relationships. Strategic archetypes include: (1) river-system crush specialists leveraging barge logistics, (2) coastal export terminal operators capturing Atlantic and Pacific vessel economics, and (3) farmer-direct origination platforms securing identity-preserved seed flows. Dominant competitive moves encompass renewable diesel supply contract capture and enzymatic refining technology licensing.
Within the integrated agribusiness tier, Archer Daniels Midland Company, Bunge Limited, and Cargill, Incorporated exemplify scale-driven positioning. Archer Daniels Midland Company occupies a position anchored in US Midwest crush corridors and export terminal control. Bunge Limited represents river-system logistics specialization with Paraná River corridor dominance. Cargill, Incorporated exemplifies farmer-direct relationship models with inland elevator network density. These three operators collectively illustrate how origination infrastructure and regulatory compliance documentation capabilities determine competitive positioning in mandate-driven procurement environments.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Bunge Limited |
| Cargill, Incorporated |
| Louis Dreyfus Company B.V. |
| Wilmar International Limited |
| COFCO Corporation |
| Richardson International Limited |
| CHS Inc. |
| Fuji Oil Holdings Inc. |
| Others |
Supply Flow & Price Mechanics
Palm oil substitution in baking and frying applications is compressing soybean oil price ceilings while simultaneously redirecting crush capacity toward biofuel corridors in Iowa, Illinois, and Indiana. This input displacement dynamic concentrates pricing power with renewable diesel blenders capturing multi-year origination contracts, leaving foodservice buyers exposed to spot market volatility and shortened procurement tenors.
Pricing Analysis
Cost-plus contracts indexed to CBOT soybean futures and RIN value spreads dominate biofuel procurement, while foodservice buyers negotiate basis-plus agreements tied to Gulf Coast export parity. Price differentiation rests on carbon intensity scoring under California LCFS and certification tiers for organic and non-GMO grades. Pricing pressure intensifies as Indonesian and Malaysian palm oil alternatives capture cost-sensitive baking applications. Quick-service restaurant chains exhibit highest price sensitivity, whereas infant formula manufacturers absorb premiums for EUDR-compliant organic supply.
Supply Chain Analysis
Inventory cycles compress to 15-30 days for hydrotreater feedstock as renewable diesel refiners impose just-in-time delivery windows. Geographic supply concentrates in the United States, Brazil, and Argentina where Paraná River barge terminals and Gulf Coast export elevators cluster. Raw material dependencies center on soybean seed stock, hexane solvent for extraction, and caustic soda for refining. Single-source vulnerability runs through the US Midwest crush corridor during planting season weather events. Distribution runs through captive elevator networks controlled by integrated agribusiness conglomerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense as palm oil alternatives erode food-grade margins and biofuel mandates reallocate crush capacity. Incumbents must navigate tightening hydrotreater specifications and cross-sector talent competition while defending origination relationships.
For Market Incumbents: Fortify Paraná River corridor assets through barge terminal upgrades and direct farmer contracting platforms to secure identity-preserved seed flows. Invest in enzymatic interesterification licensing to capture premium shortening markets as trans-fat labeling requirements tighten. Prioritize EPA compliance documentation capabilities to defend renewable diesel supply relationships against merchant oil channel competitors.
For New Entrants and Emerging Players: Specialty organic certification services for South American exporters facing EUDR geolocation requirements represent an underserved advisory layer. Target Indian bulk vessel import coordination where structural edible oil deficits create procurement advisory demand. Deploy direct origination platforms connecting Maharashtra port infrastructure with Gujarat refiners to bypass established merchant channels.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed crush facility operators in Argentina's Buenos Aires province holding EUDR-compliant chain-of-custody systems. Five-to-ten year viability hinges on renewable diesel capacity expansion sustaining origination premiums. Monitor EPA Renewable Fuel Standard volume obligation announcements as inflection indicators for crush margin direction.
| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Diesel Supply Contract Capture | Multi-year offtake agreements with California LCFS-compliant refiners lock crush capacity away from foodservice competitors. |
| Enzymatic Interesterification Licensing | Technology adoption enables mid-size refiners to enter premium shortening markets previously dominated by integrated multinationals. |
| Paraná River Terminal Expansion | Rosario and San Lorenzo barge loading investments accelerate South American oil movement to Atlantic biofuel markets. |
| High-Oleic Seed Variety Development | Improved oxidative stability opens extended fry-life applications in quick-service restaurant chains and industrial snack manufacturing. |
| EUDR Compliance Infrastructure Buildout | Geolocation and chain-of-custody documentation capabilities determine market access for European-bound South American exporters. |
Methodological Framework
A spread of perspectives from crush facility operators, renewable diesel refinery procurement leads, foodservice distribution channel managers, and regulatory compliance officers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through EPA Renewable Fuel Standard filings, California Air Resources Board LCFS credit transaction data, ANP biodiesel mandate reports, and customs export records. Bottom-up volume modeling from individual crush facility capacity and top-down demand triangulation from end-use consumption patterns were cross-referenced for convergence.
Segmentation dimensions modeled include product grade tier, application end-use, distribution channel structure, and regional regulatory framework clusters. CAGRs were derived through regression analysis of historical crush margin spreads and forward projection of RIN value trajectories across the analysis window. Forecast inputs incorporated renewable diesel hydrotreater capacity buildout schedules and EUDR implementation compliance timelines.
Forecasts assume regulatory continuity in EPA Renewable Fuel Standard obligations, California LCFS carbon intensity benchmarks, and European Union Deforestation Regulation traceability requirements; material policy shifts would require re-modeling. Commodity price volatility in soybean futures and palm oil differentials represents primary revision risk. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Plant-Based API Market
Ingredients
Pea Fiber Market
Ingredients
Malted Barley Flour Market
Ingredients
Rose Hips Extract Market
Ingredients
Middle East and Africa Fermented Ingredients Market
Ingredients
Food Minerals Market
Ingredients
Waxy Maize Starch Market
Ingredients
Mediterranean Women’s Cycle Support Ingredient Systems Market
Ingredients
Europe Dairy Ingredients Market
Ingredients
Global Distillers Corn Oil Market
Ingredients
Drum to Hopper Blends Market
Ingredients
Glucuronolactone Market
Ingredients
Tapioca Pearls Market
Ingredients
Asia-Pacific Agar Market
Ingredients
Global Hydrolyzed Wheat Protein Market
Ingredients
Astragalus Root Extract Market