
 Farnesene Market | 2026-2036
Farnesene Market Size, Share, and Industry Trends Forecast 2026-2036
Farnesene Market Analysis
The capital-intensity divergence between precision fermentation specialists and traditional chemical producers is unwinding legacy supply hierarchies in farnesene manufacturing. Amyris, Inc. leverages its proprietary yeast strain platform to sustain continuous production at commercial scale. BASF SE anchors European supply through established oleochemical infrastructure and backward integration into terpene chemistry. Ginkgo Bioworks competes via automated foundry services that reduce strain development timelines for contract farnesene programs.
Farnesene denotes a sesquiterpene hydrocarbon with the molecular formula C15H24, existing primarily as alpha- and beta-isomers produced through plant extraction, chemical synthesis, or microbial fermentation using engineered Saccharomyces cerevisiae. The compound serves as a versatile building block for squalene analogs, polymer precursors, and high-value fragrance molecules across industrial biotechnology. Biotechnological source channels command expanding share as fermentation titers improve and downstream processing costs decline. Beta-Farnesene dominates volume flows due to its superior reactivity profile in polymerization pathways, while alpha-isomer variants occupy premium positions in pharmaceutical intermediate applications. Cosmetics application segments concentrate margin pools through clean-label positioning and replacement of petrochemical-derived emollients.
EPA biofuel pathway certifications and REACH substance registration requirements shape market access conditions for fermentation-derived farnesene in North America and Europe. FDA food contact substance notifications govern farnesene deployment in food additive applications, while EMA guidelines influence pharmaceutical-grade specifications. Brazil's national biofuel regulator ANP and environmental licensing frameworks under IBAMA determine expansion feasibility for sugarcane-based production clusters. Stakeholders must monitor regulatory divergence between jurisdictions governing genetically modified organism deployment in fermentation processes.
Market Dynamics
Fermentation-derived farnesene is compressing petrochemical terpene supply chains as sugarcane biorefineries in Brazil achieve continuous commercial production. This feedstock shift is redrawing procurement geography and forcing legacy oleochemical producers to reconfigure backward integration strategies.
Growth Catalysts
- REACH Registration Pathways:ECHA substance registration for fermentation-derived terpenes is unlocking European cosmetics formulation approvals, displacing synthetic emollient alternatives in clean-label product lines.
- Sugarcane Feedstock Abundance:Brazil's integrated milling infrastructure enables year-round farnesene production with captive sucrose supply, concentrating cost-competitive biorefinery operations in São Paulo state clusters.
- Polymer Precursor Demand:Beta-farnesene reactivity in polymerization pathways is pulling volume into synthetic rubber and adhesive applications, with tire manufacturers specifying bio-based feedstocks in procurement contracts.
Market Restraints
- Genetic Modification Licensing:GMO deployment restrictions under Brazil's CTNBio and EU Directive 2001/18/EC are fragmenting strain approval timelines, delaying facility commissioning in jurisdictions with stringent containment requirements.
- Downstream Processing Costs:Chromatographic separation and purification of sesquiterpene isomers requires energy-intensive distillation, compressing margins at fermentation titers below commercial viability thresholds.
- Petrochemical Substitution:Synthetic squalene and isoprene from naphtha cracking remain price-competitive in fragrance and polymer applications, capping farnesene penetration in cost-sensitive segments.
Strategic Opportunities
- Pharmaceutical-Grade Specifications:EMA guideline compliance for squalene adjuvant production is opening vaccine formulation channels, with fermentation-derived farnesene commanding premium positioning over shark liver extraction.
- Carbon Accounting Integration:EU Green Deal carbon border adjustment mechanisms are favoring bio-based terpenes in imported cosmetics, creating regulatory tailwinds for Brazilian and European fermentation producers with verified lifecycle assessments.
- Automated Strain Engineering:Convergence of machine learning-directed pathway optimization and high-throughput screening is collapsing development timelines for novel farnesene-producing yeast variants.
Industry Challenges
- Fermentation Scale-Up Expertise:Commercial-scale aerobic bioprocessing of sesquiterpenes requires specialized metabolic engineering talent scarce outside Amyris and established industrial biotechnology clusters.
- Food Contact Certification:FDA notification timelines for farnesene deployment in food additive applications extend 12-18 months, compressing product launch cycles for ingredient suppliers targeting CPG manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Farnesene Market |
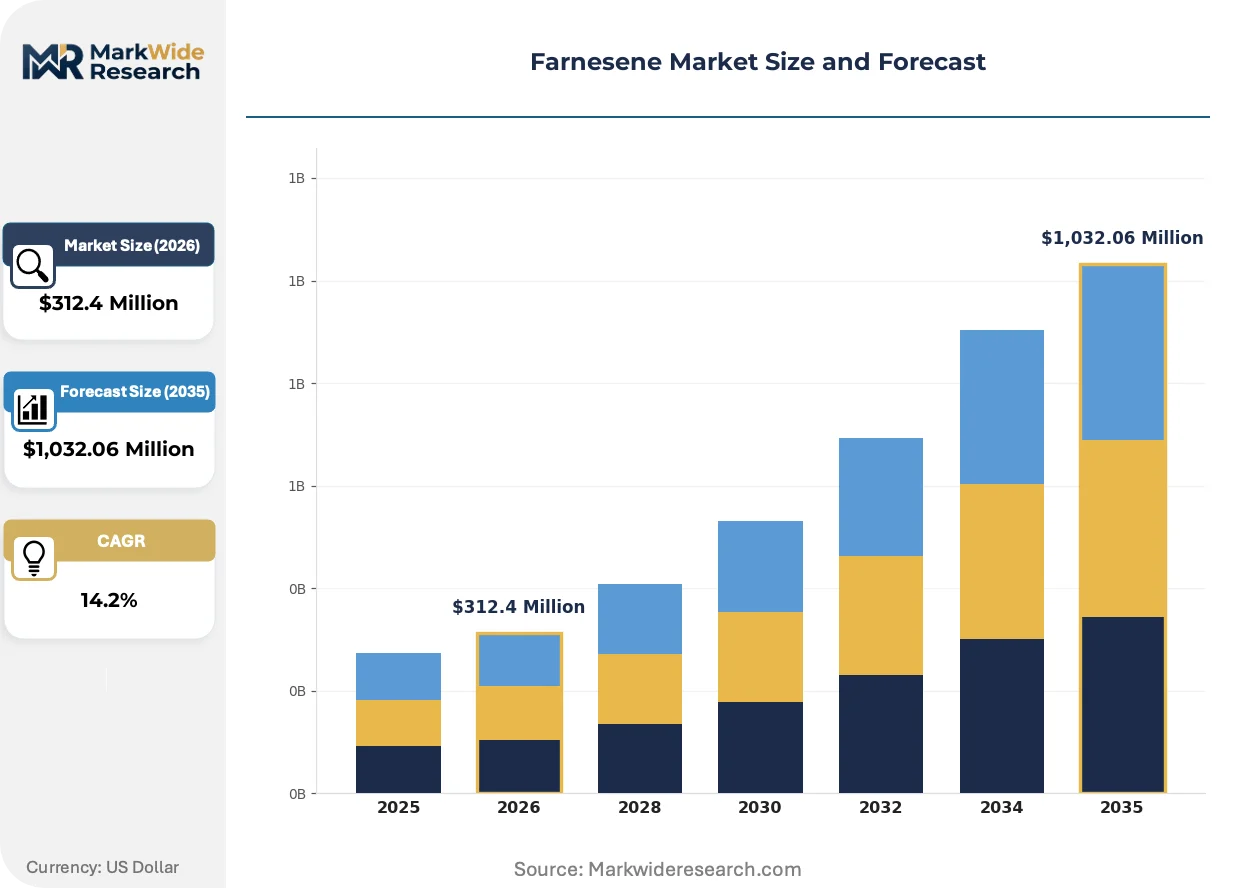
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,032.06 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alpha-Farnesene, Beta-Farnesene, Farnesene Blends, Others Application: Cosmetics, Pharmaceuticals, Food Additives, Fragrances Source: Natural, Synthetic, Biotechnological, Others End User: Food Industry, Personal Care, Pharmaceutical Companies, Cleaning Products |
| Companies Covered | BASF SE, Amyris, Inc., Merck, Biosynth, TCI (Tokyo Chemical Industry), Santa Cruz Biotechnology, Ginkgo Bioworks, Alfa Chemistry, Paraíso Bioenergia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Farnesene Market Emerging Trajectories
Continuous fermentation systems and modular biorefinery architectures are displacing batch production economics. These process innovations are compressing capital recovery periods and enabling distributed manufacturing closer to feedstock sources.
Engineered Saccharomyces cerevisiae strains with heterologous terpene synthase pathways are displacing plant extraction for high-purity alpha-farnesene. Pharmaceutical intermediate manufacturers are adopting these biocatalytic routes to secure squalene precursor supply chains independent of marine sourcing volatility. The displacement is compressing extraction-based margin pools in fragrance and vaccine adjuvant applications.
REACH authorization requirements for persistent, bioaccumulative, and toxic substances are tightening emollient ingredient specifications. Cosmetics formulators are responding by specifying fermentation-derived farnesene with full substance identity documentation. European contract manufacturers are most affected, with reformulation cycles accelerating to meet ECHA compliance deadlines.
Long-term offtake agreements with fixed volume commitments are displacing spot market purchasing in farnesene procurement. Specialty chemical distributors are ceding channel position to direct supplier relationships as cosmetics and polymer compounders seek supply security. This behavioral shift is most visible in German and French formulation houses, where backward integration into biorefinery equity stakes is emerging as a competitive defense mechanism.
Farnesene Market Segmentation
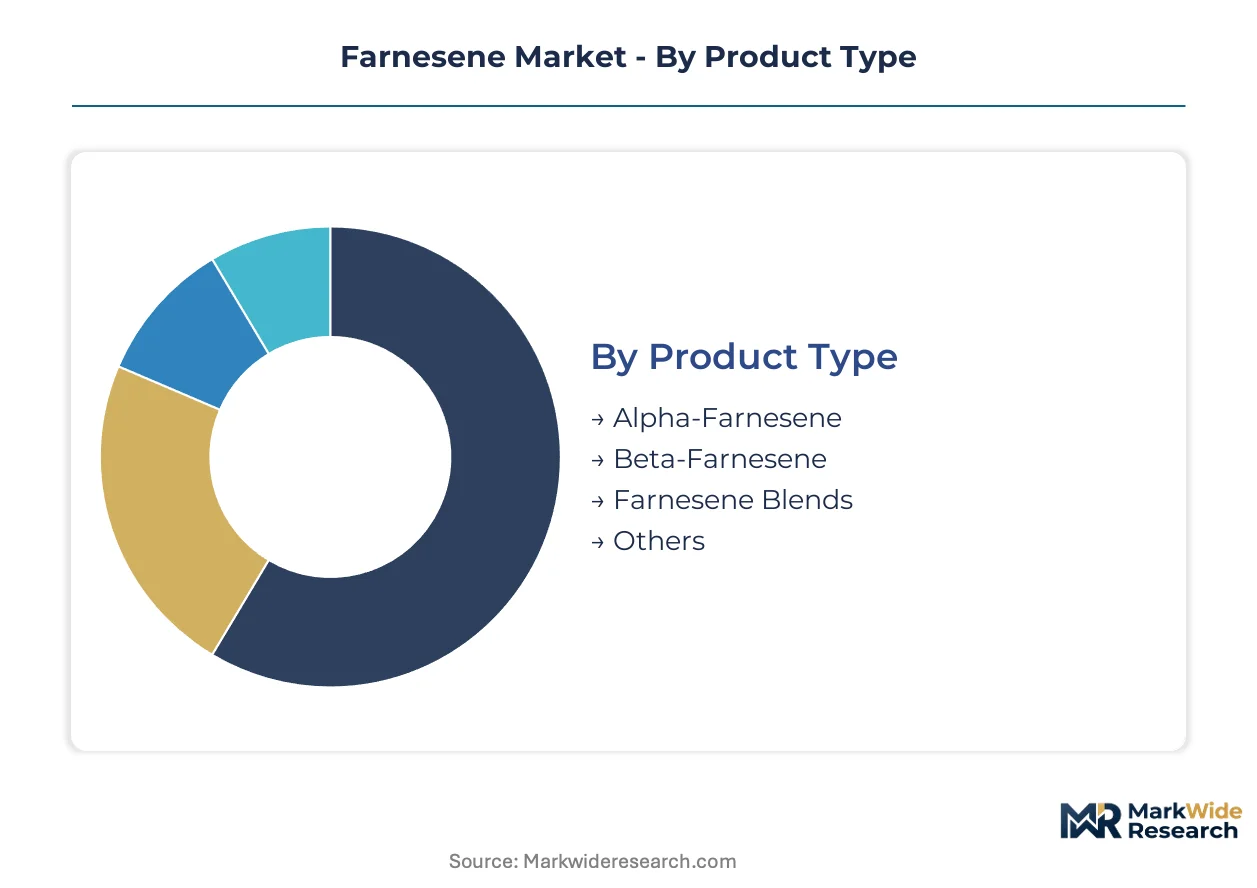
Farnesene market segmentation reveals divergent substitution pressures across molecular variants and sourcing pathways. Each dimension carries distinct regulatory exposure and margin structures that reshape supplier positioning.
Product Type:
Beta-farnesene faces the most acute petrochemical substitution pressure from synthetic isoprene, while alpha-isomer variants defend premium positioning through pharmaceutical-grade specifications.
- Beta-Farnesene:The C15H24 sesquiterpene exhibits superior reactivity in polymerization pathways, making it the preferred feedstock for synthetic rubber and adhesive manufacturers. Tire producers in Germany and Japan are specifying beta-farnesene in bio-based procurement contracts, though naphtha-derived isoprene from South Korean crackers remains price-competitive in cost-sensitive volume segments.
- Alpha-Farnesene:This stereoisomer commands pharmaceutical intermediate applications where EMA guideline compliance for squalene adjuvant production creates barrier-to-entry advantages. Vaccine formulators in Switzerland and the United States are adopting fermentation-derived alpha-farnesene to eliminate shark liver extraction volatility from their supply chains.
- Farnesene Blends:Mixed-isomer formulations optimize cost-performance ratios for fragrance compounders seeking consistent odor profiles.
- Others:Specialty isomer variants and modified terpene structures serve niche polymer research applications.
Beta-farnesene retains volume leadership; alpha-farnesene holds the steepest expansion curve.
Application:
Cost tier stratification separates premium pharmaceutical channels from commoditized fragrance applications, with cosmetics occupying the contested middle ground.
- Cosmetics:Clean-label emollient demand from French and German formulators is accelerating REACH-registered farnesene displacement of petrochemical-derived alternatives. ECHA substance identity requirements are compressing reformulation timelines for contract manufacturers serving European personal care brands.
- Pharmaceuticals:Squalene precursor applications for vaccine adjuvants command the highest purity premiums, with FDA notification pathways and EMA guideline compliance creating dual-jurisdiction qualification barriers. Swissmedic-registered suppliers capture margin concentration in this segment.
- Food Additives:FDA food contact substance notifications govern deployment timelines, extending 12-18 months for ingredient suppliers targeting CPG manufacturers.
- Fragrances:High-volume odorant applications compete directly with plant-extracted terpenes and synthetic substitutes from established oleochemical producers.
Pharmaceuticals command the premium tier; cosmetics is expanding most quickly through clean-label substitution.
Source:
Supply concentration in Brazilian sugarcane clusters favors biotechnological pathways, while synthetic producers defend residual positions through petrochemical integration.
- Biotechnological:Engineered Saccharomyces cerevisiae fermentation achieves continuous production at commercial scale in São Paulo state biorefineries, with ANP biofuel pathway certifications and IBAMA environmental licensing determining expansion feasibility. Amyris proprietary yeast strains sustain titers that compress downstream processing economics.
- Natural:Plant extraction from citrus and other botanical sources retains niche positioning for fragrance applications requiring specific geographic provenance claims.
- Synthetic:Chemical synthesis from petrochemical feedstocks defends cost-sensitive polymer segments through established naphtha cracking infrastructure.
- Others:Hybrid and emerging catalytic routes occupy pre-commercial development stages.
Biotechnological sourcing dominates forward capacity additions; natural extraction retains defensive positions in premium fragrance channels.
End User:
Customer type fragmentation creates divergent procurement behaviors, with pharmaceutical companies demanding supply security while food industry buyers prioritize cost containment.
- Pharmaceutical Companies:Long-term offtake agreements with fixed volume commitments are displacing spot purchasing as vaccine manufacturers secure squalene precursor supply chains. Direct supplier relationships are ceding distributor channel position in German and French formulation houses.
- Personal Care:Cosmetics compounders are acquiring backward integration stakes in biorefinery equity as competitive defense mechanisms against supply disruption.
- Food Industry:Additive applications face extended FDA notification timelines that compress product launch cycles for ingredient suppliers.
- Cleaning Products:Industrial surfactant and solvent applications represent volume opportunities with lower specification barriers.
Pharmaceutical companies anchor premium demand; personal care is gaining share fastest through clean-label reformulation cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. Brazil deploys farnesene primarily as a polymer feedstock integrated into sugarcane biorefineries. European formulators prioritize pharmaceutical-grade specifications for squalene adjuvant production. United States demand concentrates in cosmetics applications seeking clean-label emollient alternatives.
Brazil
São Paulo state clusters anchor biotechnological farnesene production through integrated sugarcane milling infrastructure. ANP biofuel pathway certifications and IBAMA environmental licensing frameworks determine facility expansion feasibility. Campinas and Piracicaba metropolitan areas concentrate engineered yeast fermentation capacity serving polymer precursor contracts.
Germany
Tire manufacturers in Cologne and Leverkusen specify beta-farnesene in bio-based procurement contracts for synthetic rubber applications. REACH substance registration requirements under ECHA govern cosmetics formulation approvals displacing petrochemical emollients. BASF SE anchors European supply through established oleochemical infrastructure in Ludwigshafen.
United States
Cosmetics compounders in New Jersey and California accelerate clean-label reformulation cycles targeting EWG-verified product lines. FDA food contact substance notifications extend 12-18 months for additive applications compressing supplier launch timelines. Amyris, Inc. maintains proprietary yeast strain production serving squalene analog demand.
Switzerland
Vaccine formulators in Basel adopt fermentation-derived alpha-farnesene to eliminate shark liver extraction supply volatility. Swissmedic registration requirements create barrier-to-entry advantages for pharmaceutical-grade specifications. Novartis and Roche supplier ecosystems concentrate squalene adjuvant procurement through long-term offtake agreements.
China
Fragrance compounders in Shanghai and Guangzhou integrate farnesene into high-volume odorant formulations competing with plant-extracted terpenes. NMPA cosmetic ingredient filing requirements reshape import documentation for fermentation-derived materials. Yangtze River Delta chemical parks host emerging biotechnological production trials.
Farnesene Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in farnesene manufacturing. Precision fermentation specialists compete against established oleochemical producers with backward integration into terpene chemistry. Three archetypes dominate: biotechnological platform companies, diversified chemical conglomerates, and automated strain engineering services. Capacity expansion in Brazilian sugarcane clusters and strategic partnerships for pharmaceutical-grade certification represent the primary competitive vectors.
Within the biotechnological platform tier, Amyris, Inc. and Ginkgo Bioworks occupy positions exemplifying divergent scale approaches. Amyris leverages proprietary yeast strain platforms for continuous commercial production. Ginkgo Bioworks competes via automated foundry services reducing development timelines. BASF SE anchors the diversified chemical conglomerate archetype through European oleochemical infrastructure.
| Leading Market Players |
|---|
| BASF SE |
| Amyris, Inc. |
| Merck |
| Biosynth |
| TCI (Tokyo Chemical Industry) |
| Santa Cruz Biotechnology |
| Ginkgo Bioworks |
| Alfa Chemistry |
| Paraíso Bioenergia |
| Others |
Supply Flow & Price Mechanics
Fermentation-derived farnesene displacement of petrochemical terpenes simultaneously redraws procurement geography toward Brazilian sugarcane clusters and compresses legacy pricing hierarchies that synthetic producers once controlled. This feedstock pivot concentrates cost-competitive supply in São Paulo state while forcing European and Asian oleochemical incumbents to reconfigure margin structures.
Pricing Analysis
Long-term offtake agreements with fixed volume commitments dominate farnesene procurement, displacing spot purchasing as cosmetics compounders and tire manufacturers seek supply security. Pricing stratifies across pharmaceutical-grade alpha-isomer specifications, standard polymer-grade beta-farnesene, and economy fragrance blends. Cost compression in beta-farnesene intensifies because naphtha-derived isoprene from South Korean crackers retains price competitiveness. Food additive buyers exhibit highest price sensitivity due to extended FDA notification timelines, while vaccine formulators show lowest sensitivity given squalene adjuvant supply security priorities.
Supply Chain Analysis
Chromatographic separation capacity for sesquiterpene isomer purification operates as a chokepoint constraining output expansion regardless of fermentation titer improvements. Supply concentrates in Brazil, Germany, and Switzerland, with Brazilian sugarcane biorefineries anchoring volume production. The chain draws from engineered yeast strains, sucrose feedstock, and specialized distillation equipment. Single-source vulnerability in Amyris proprietary strain licensing creates concentration risk for fermentation-derived supply. Distribution runs through direct supplier relationships that displace specialty chemical distributors in German and French formulation houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Farnesene sits at a high-growth disruption inflection where REACH registration pathways and automated strain engineering collapse development timelines simultaneously. This technological-regulatory convergence rewards early movers who secure pharmaceutical-grade certifications and biorefinery equity positions.
For Market Incumbents: Shield established margin pools in European cosmetics formulations by accelerating REACH substance identity documentation ahead of ECHA compliance deadlines. BASF SE and diversified oleochemical producers should deepen backward integration into Brazilian sugarcane clusters to match fermentation economics. Priority defensive investment centers on captive strain engineering capabilities that reduce dependency on external biotechnology platforms.
For New Entrants and Emerging Players: Pharmaceutical-grade alpha-farnesene specification gaps in vaccine adjuvant supply chains offer the most penetrable white-space target, with Swissmedic-registered suppliers commanding premium positioning. Automated foundry services for contract farnesene programs represent a second entry vector, reducing strain development timelines for specialty chemical distributors seeking biotechnology capabilities. Go-to-market execution should emphasize EMA guideline compliance as a barrier-to-entry credential.
For Investors and Strategic Acquirers: The market sits at a scale-up phase that favors precision fermentation specialists with proprietary yeast platforms and verified lifecycle assessments. Long-term viability over the next decade hinges on carbon accounting integration under EU Green Deal border adjustment mechanisms. Acquisition target archetypes include Brazilian biorefinery operators with ANP certifications and modular fermentation technology providers. The signal to watch is GMO deployment licensing velocity under Brazil's CTNBio and EU Directive 2001/18/EC as inflection indicators for capacity expansion feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Cosmetics compounders in New Jersey secure squalene analog supply chains through fixed volume commitments. |
| Backward Integration | German tire manufacturers acquire equity stakes in São Paulo biorefineries to control beta-farnesene feedstock access. |
| Green Manufacturing Transition | Fermentation-derived production achieves verified lifecycle assessments under EU carbon border adjustment mechanisms. |
| Capacity Expansion | Campinas and Piracicaba metropolitan areas add engineered yeast fermentation capacity serving polymer precursor contracts. |
| Regulatory Approval Pathway | FDA food contact substance notifications govern farnesene deployment timelines in CPG additive applications. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fermentation process engineers, cosmetics formulation chemists, pharmaceutical procurement managers, and sugarcane biorefinery plant managers. Secondary validation drew from ECHA substance registration databases, ANP biofuel pathway certifications, FDA food contact substance notifications, and SEC filings of listed industrial biotechnology companies. Bottom-up capacity modeling and top-down demand estimation were triangulated to cross-verify volume assumptions.
Across the projection horizon, the analytical framework modeled farnesene segmentation by isomer type, application tier, sourcing pathway, and end-user procurement behavior. CAGRs were derived from installed capacity expansion schedules, substitution elasticity estimates for petrochemical terpenes, and regulatory approval velocity assumptions. Industry-specific forecast inputs included fermentation titer improvement trajectories and REACH authorization timeline probabilities for persistent substance restrictions.
Material uncertainties — GMO licensing delays, downstream processing cost volatility, and petrochemical feedstock price swings — sit outside the modeled envelope. Forecasts reflect assumptions about strain engineering productivity gains and carbon accounting policy implementation. Practitioners should keep alternative scenarios live as CTNBio approval timelines and EU Green Deal border adjustment enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Konjac Flour Market
Ingredients
Europe Malt Ingredient Market
Ingredients
Protein Extracts from Single Cell Protein and Other Conventional Sources Market
Ingredients
Brazil Corn Syrup Market
Ingredients
North America Malt Ingredients Market
Ingredients
North America Cheese Powder Market
Ingredients
South America Algae Omega-3 Ingredients Market
Ingredients
Global Edible Oil Market
Ingredients
US Plant-Based Oils Market
Ingredients
Clean Label Flour Market
Ingredients
Agar Agar Flakes Market
Ingredients
Europe Malt Extract Market
Ingredients
Almond Ingredients Market
Ingredients
Hydrogenated Palm Oil Market
Ingredients
Cacao Extracts Market
Ingredients
Cheese Ingredients Market