
 Wheat Malt Market | 2026-2036
Wheat Malt Market Size, Share, and Industry Trends Forecast 2026-2036
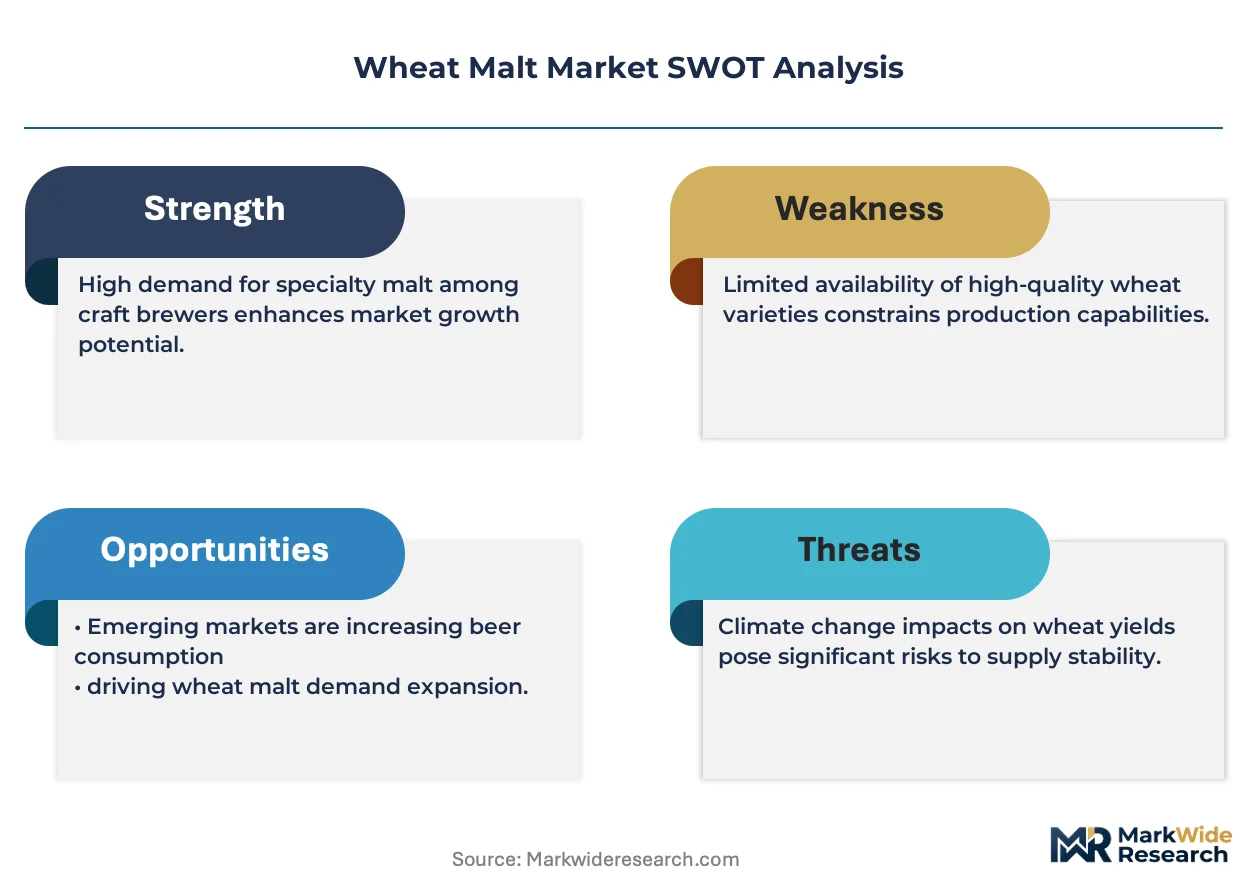
Wheat Malt Market Analysis
Europe is narrowing its wheat malt supply gap through capacity investments in France and Poland. Cargill leverages its grain origination network to secure premium wheat varieties for malting operations across the continent. Boortmalt sustains one of the largest specialized malt production footprints, with facilities optimized for wheat and specialty grains. Malteurop competes through integrated supply chains that connect farmer cooperatives directly to brewery customers.
Wheat malt consists of germinated wheat kernels dried in controlled kilning conditions, typically achieving diastatic power of 60–120 Lintner depending on modification targets, and serves primarily as a fermentable base for beer production and a flavor contributor in baked goods. Base malt occupies the largest volume share across brewing applications, while specialty malt commands stronger margins through roasted and caramelized variants that distillers prize for complexity. Crystal malt represents the fastest-growing product type as craft distilleries seek differentiated flavor profiles for premium spirits.
The EU Green Deal and F-Gas Regulation are reshaping malting energy standards, pushing kiln operators toward heat recovery systems and lower-emission fuels to maintain market access. Germany's KBA and state-level environmental agencies enforce compliance thresholds that directly affect production economics for malters supplying Bavarian breweries. Stakeholders must monitor evolving carbon border adjustments and brewing industry consolidation patterns that could reorder contract structures for wheat malt procurement.
Market Dynamics
The EU F-Gas Regulation and national emissions enforcement by Germany's KBA are forcing malting operators to reconfigure kiln energy systems, compressing margins for conventional fossil-fuel-dependent facilities while advantaging early adopters of heat recovery and biomass integration.
Growth Catalysts
- Craft Brewing Expansion:Small-scale breweries across Germany and Belgium are diversifying grain bills beyond barley, creating dedicated demand streams for wheat malt with specific enzymatic profiles. This segment now commands premium contract terms.
- EU Green Deal Compliance:Carbon border adjustment mechanisms are rewarding malters with verified low-emission production, channeling procurement toward facilities with renewable thermal energy and closed-loop water systems.
- Specialty Distilling:Premium spirits producers in Scotland and Ireland are specifying crystal and roasted wheat variants for flavor complexity, opening volume commitments previously reserved for traditional barley malts.
Market Restraints
- Input Cost Volatility:Wheat futures pricing tied to Black Sea supply disruptions creates margin unpredictability for malters lacking long-term origination contracts with cooperative grain networks.
- Supply Concentration Risk:Malting capacity clusters in France and Poland, creating geographic vulnerability to regional weather events and transportation bottlenecks across the Rhine corridor.
- Technical Limitation:Wheat malt's lower husk content compared to barley restricts lautering efficiency in traditional brewery equipment, limiting substitution rates without capital-intensive system modifications.
Strategic Opportunities
- Underpenetrated Eastern Europe:Poland's developing craft sector and Baltic states' emerging brewing clusters present first-mover advantages for specialty wheat malt distribution before supply contracts solidify.
- Regulatory Tailwind:France's national low-carbon label certification offers preferential positioning in public procurement and supermarket private-label beer supply chains.
- Technology Convergence:Integration of AI-driven kiln control with biomass gasification systems enables real-time moisture and color optimization while meeting tightening emissions thresholds.
Industry Challenges
- Skill Gap in Thermal Engineering:Malting facilities struggle to recruit technicians capable of operating hybrid kiln systems combining traditional germination expertise with automated heat recovery infrastructure.
- Certification Timeline Compression:Brewery customers are demanding simultaneous organic, carbon-neutral, and heritage-grain certifications, stretching quality assurance departments across overlapping audit schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wheat Malt Market |
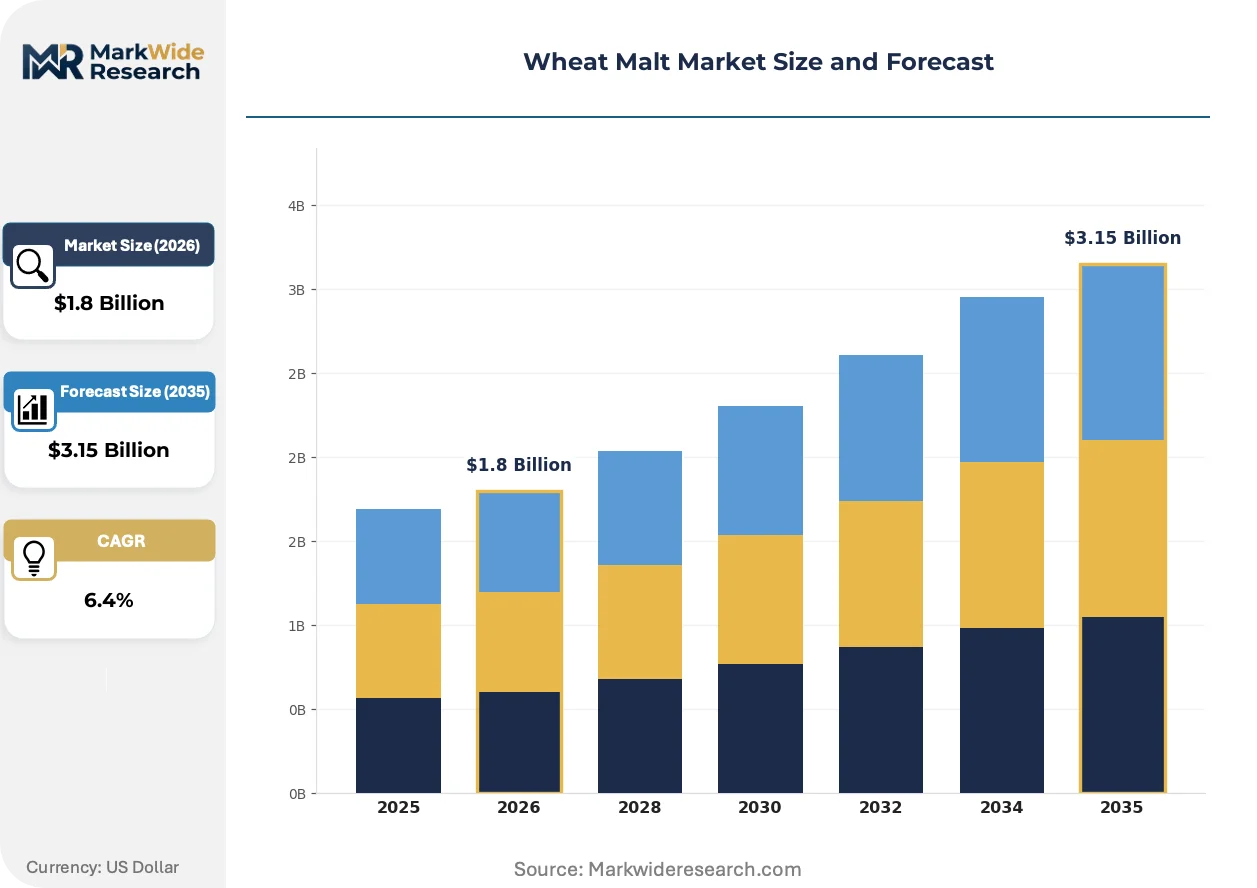
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Base Malt, Specialty Malt, Flour Malt, Crystal Malt Application: Craft Brewing, Industrial Brewing, Baking, Distilling End User: Breweries, Bakeries, Distilleries, Food Manufacturers Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Cargill, Boortmalt, Malteurop, Viking Malt, Briess Malt & Ingredients, Richardson International Limited, Great Western Malting, Muntons, Crisp Malting, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wheat Malt Market Emerging Trajectories
Electrification of malting kilns and predictive process control are converging with tightening emissions mandates, compressing the viable technology window for conventional fossil-fuel operations.
Electromagnetic heating systems for malt kilns are rendering obsolete the natural gas-fired batch dryers that dominated European malting for decades. Mid-sized craft malters in Denmark and the Netherlands are piloting these installations to secure carbon-neutral brewery contracts. The technology is rendering obsolete the 20-year depreciation schedules that malters previously used to justify delayed capital replacement.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon-based refrigeration is forcing malting facilities to adopt ammonia or CO2-based cooling for germination temperature control. This transition adds retrofit complexity for aging plants in Germany's traditional malting belt. Facilities in Bavaria face particular pressure from state environmental agencies accelerating compliance timelines beyond the EU baseline.
Brewery procurement teams are consolidating supplier relationships from transactional spot-buying to multi-year partnership agreements with traceability requirements. This consolidation favors malters with integrated grain origination and laboratory verification capabilities. The shift is most pronounced in Belgium, where abbey and Trappist breweries are locking in decade-long wheat malt supply contracts with single-source accountability.
Wheat Malt Market Segmentation
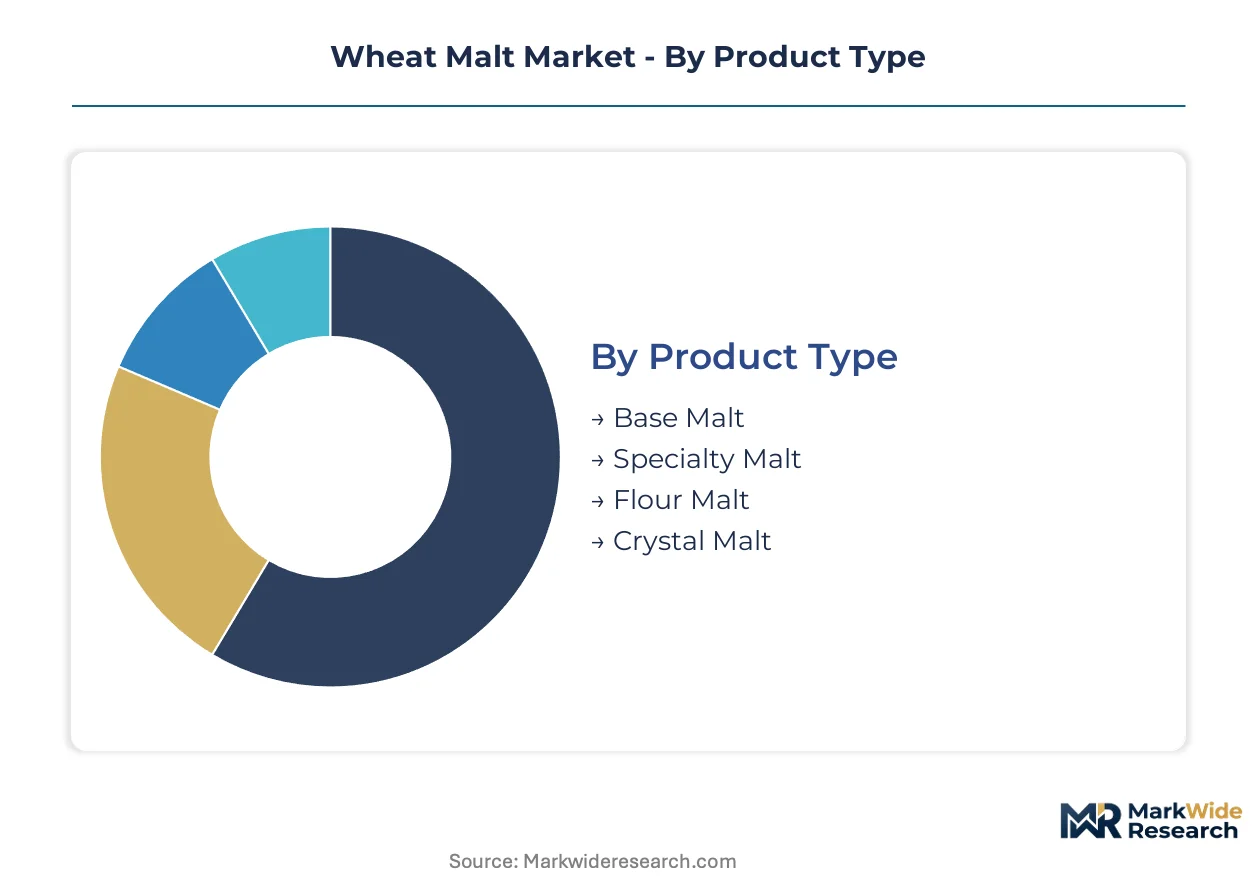
Wheat malt segmentation reveals how enzymatic specifications, thermal modification levels, and end-use processing requirements create distinct commercial tiers. Product type and application dimensions drive the most significant pricing and contract structure variations across European supply chains.
Product Type:
Cost tier differentiation separates commodity base malts from premium specialty variants with distinct thermal processing intensities and margin profiles.
- Base Malt:Standard-modification wheat malt achieving 60–80 Lintner diastatic power serves as the fermentable foundation for lager and wheat beer production. German and Belgian industrial brewers contract for this grade in bulk volumes, prioritizing enzymatic consistency over flavor complexity.
- Specialty Malt:Roasted and caramelized variants undergo extended kilning to develop Maillard reaction compounds prized by craft distilleries. Scotland's premium spirits producers now specify these wheat malts for flavor layering previously achieved through barley alternatives.
- Flour Malt:Finely milled wheat malt integrates into industrial bakery formulations for enzymatic dough conditioning and crust color development.
- Crystal Malt:Glassy-endosperm wheat malt produced through stewing and roasting cycles contributes caramel sweetness and body to specialty beers.
Base Malt holds installed capacity. Crystal Malt is rotating up the share rankings.
Application:
Volume concentration varies dramatically across brewing scales, with craft operators demanding smaller batches of specified enzymatic profiles than industrial facilities.
- Craft Brewing:Small-scale German and Belgian breweries diversify grain bills beyond traditional barley, creating dedicated demand streams for wheat malt with specific modification targets. These customers accept premium pricing for traceable heritage varieties and low-carbon production verification.
- Industrial Brewing:High-volume lager and wheat beer producers in Poland and the Czech Republic optimize for cost-efficient base malt with standardized diastatic power, sourcing through long-term origination contracts.
- Baking:Artisan and industrial bakeries employ wheat malt flour for natural dough improvement, replacing chemical additives in clean-label product lines.
- Distilling:Premium spirits producers leverage roasted wheat variants for flavor complexity, opening volume commitments previously reserved for traditional barley malts.
Industrial Brewing maintains volume leadership. Craft Brewing is climbing the fastest among application tiers.
End User:
Customer type determines contract structure complexity, with breweries demanding the most stringent certification and traceability protocols.
- Breweries:Range from abbey and Trappist operations in Belgium locking in decade-long supply agreements to emerging craft operators in Poland seeking flexible procurement terms.
- Bakeries:Industrial and artisan baking operations prioritize enzymatic activity consistency for dough processing efficiency.
- Distilleries:Premium spirits producers in Scotland and Ireland drive specialty malt specifications for differentiated flavor profiles.
- Food Manufacturers:Processed food companies incorporate wheat malt extracts for natural coloring and flavor enhancement applications.
Breweries anchor demand concentration. Distilleries are gaining share fastest among end-user categories.
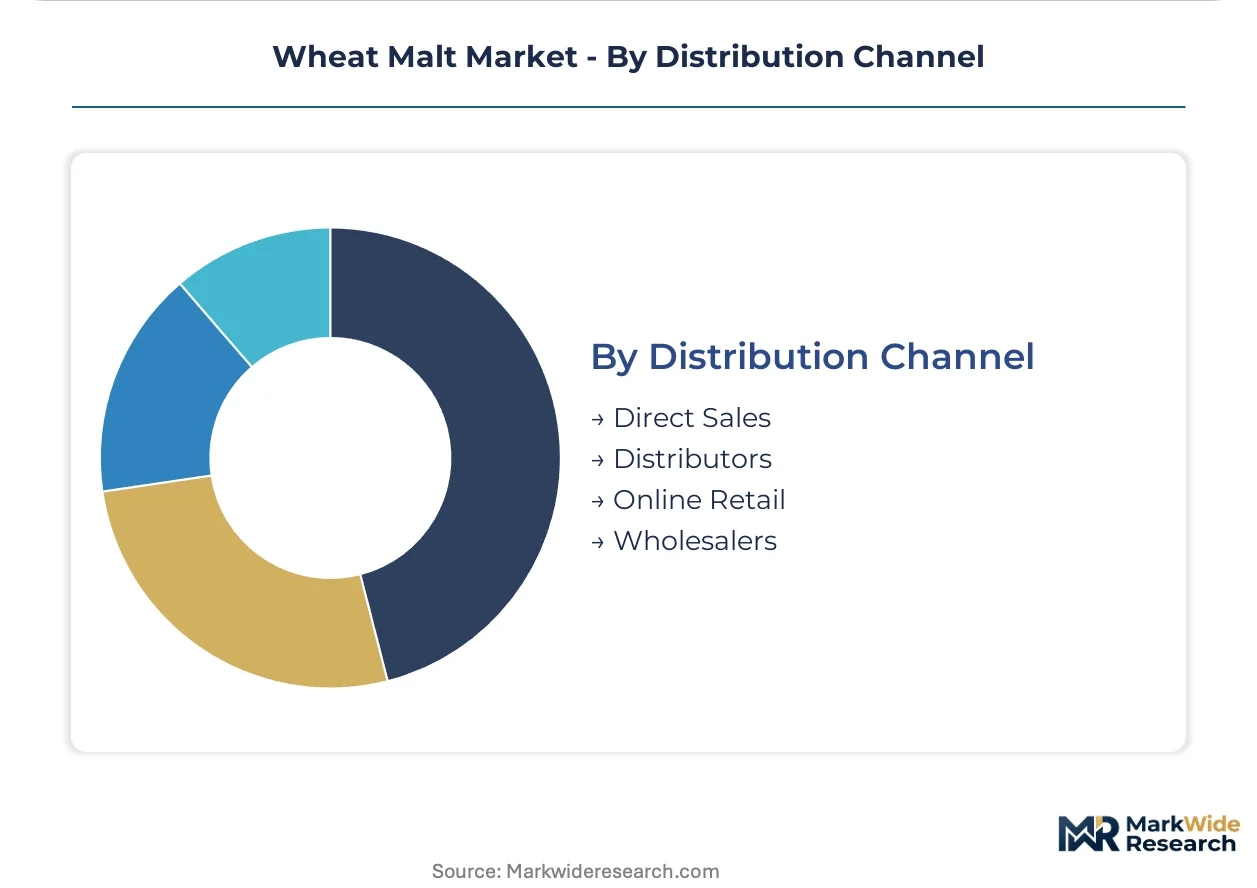
Distribution Channel:
Supply concentration shapes channel economics, with direct relationships favoring large-volume accounts and distributor networks serving fragmented craft segments.
- Direct Sales:Malteurop and Boortmalt leverage integrated supply chains to connect farmer cooperatives directly to major brewery customers, eliminating intermediary margins.
- Distributors:Specialized beverage ingredient distributors serve mid-sized craft breweries across France, Germany, and the Netherlands with smaller batch flexibility.
- Online Retail:E-commerce platforms enable homebrewers and micro-distilleries to access specialty wheat malt varieties with minimal order quantities.
- Wholesalers:Regional grain wholesalers aggregate demand from smaller bakeries and food manufacturers across Eastern European markets.
Direct Sales commands the largest contract value. Online Retail is expanding most quickly as craft segments proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes wheat malt differently than other markets, prioritizing heritage-grain specifications for traditional wheat beer styles while Poland and the Czech Republic optimize for cost-efficient base malt in high-volume lager production. This consumption-mix differential shapes regional supply chain configurations and malting investment patterns across Europe.
Germany
Bavarian breweries anchor demand for premium wheat malt with specific enzymatic profiles tied to Reinheitsgebot-adjacent brewing traditions. The KBA enforces emissions thresholds for malting kilns that exceed EU F-Gas Regulation baselines, compressing compliance timelines for aging facilities. Production clusters concentrate in Lower Bavaria and Upper Franconia, where Boortmalt operates specialized facilities serving abbey and Trappist contract customers.
France
Industrial baking applications drive wheat malt flour consumption alongside emerging craft brewery demand in the Île-de-France and Hauts-de-France regions. The national low-carbon label certification creates preferential procurement positioning for malters with verified renewable thermal energy. Malteurop leverages integrated farmer cooperative networks across the Paris Basin to secure premium wheat varieties for malting operations.
Poland
Developing craft brewing clusters in Warsaw and Krakow diversify grain bills beyond traditional barley, creating new demand streams for specialty wheat malt specifications. EU Green Deal carbon border adjustment mechanisms channel brewery procurement toward facilities with closed-loop water systems and biomass integration. Malting capacity investments in the Greater Poland Voivodeship narrow regional supply gaps previously filled by German imports.
Belgium
Abbey and Trappist breweries lock in decade-long wheat malt supply contracts with single-source accountability requirements and heritage-grain traceability protocols. REACH compliance for thermal processing additives shapes malting chemistry specifications for color and flavor development. Production concentrates in West Flanders and the Kempen region, where specialty malt roasting capabilities serve differentiated craft spirits producers.
United Kingdom
Premium spirits producers in Scotland specify roasted wheat variants for flavor complexity previously achieved through barley alternatives alone. EMA-aligned food contact material regulations govern malt extract applications in processed food manufacturing. Malting operations cluster in East Anglia and the Scottish Lowlands, connecting grain origination networks to distillery customers through direct sales contracts.
Wheat Malt Market Vendor Landscape
Capability concentration sits with specialized maltsters possessing heritage-grain sourcing relationships and laboratory verification infrastructure; scale advantage sits with integrated agribusiness operators with captive grain origination networks. The market structures around three tiers: global agribusiness conglomerates with backward integration into wheat farming, continental malt specialists with optimized kilning technology, and regional craft malters serving fragmented brewery demand. Dominant competitive moves include capacity expansion in Eastern European markets and strategic partnerships linking farmer cooperatives directly to brewery procurement teams.
Within the integrated agribusiness tier, Cargill leverages its grain origination network to secure premium wheat varieties across European malting operations. Boortmalt occupies a position among specialized continental maltsters with facilities optimized for wheat and specialty grain production. Malteurop represents the partnership-model archetype, connecting farmer cooperatives directly to brewery customers through integrated supply chain structures.
| Leading Market Players |
|---|
| Cargill |
| Boortmalt |
| Malteurop |
| Viking Malt |
| Briess Malt & Ingredients |
| Richardson International Limited |
| Great Western Malting |
| Muntons |
| Crisp Malting |
| Others |
Supply Flow & Price Mechanics
The Rhine corridor freight differential compresses margins for malters serving Bavarian breweries while amplifying price spreads between French origination points and Polish craft destinations, forcing procurement teams to weigh transport economics against heritage-grain premiums.
Pricing Analysis
Geographic price spreads between German premium contracts and Eastern European base malt quotations have widened as carbon border adjustments reward verified low-emission production. Pricing stratifies across heritage-grain premiums, organic certification tiers, and volume-scale discounts, with craft breweries least sensitive to cost and industrial lager producers most responsive to input fluctuations. Cost compression in standard-modification grades is intensifying because Black Sea wheat futures volatility disrupts origination planning. Industrial brewers in Poland and the Czech Republic exhibit the highest price elasticity, while Belgian abbey operations accept sustained premiums for single-source traceability.
Supply Chain Analysis
Extended payment terms from distillery customers in Scotland and Ireland are forcing malters to restructure working capital around 90-day receivables cycles. Supply concentrates in France, Poland, and Germany, with raw material dependencies on Paris Basin soft wheat varieties, Ukrainian milling wheat (subject to origination substitution), and specialized nitrogen fertilizer grades for protein content management. Single-source vulnerability runs through the Rhine waterway corridor connecting malting facilities to Rotterdam export terminals. Distribution runs through integrated direct sales for bulk brewery accounts and specialized beverage ingredient distributors serving fragmented craft segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barley malt substitution threatens wheat malt volume growth as brewers seek husk-efficient alternatives for legacy lautering equipment, compelling incumbents to defend position through enzymatic performance differentiation.
For Market Incumbents: Insulate contract structures by embedding heat recovery infrastructure investments into decade-long supply agreements with Bavarian and Belgian abbey breweries. Deepen upstream control over heritage wheat varieties through exclusive farmer cooperative partnerships in the Paris Basin, neutralizing origination cost volatility that erodes margin stability against barley malt alternatives. For New Entrants and Emerging Players: Establish a beachhead in Poland's developing craft sector before supply contracts solidify around German and French incumbents. Target Baltic states' emerging brewing clusters with specialty crystal malt offerings for premium spirits producers, leveraging e-commerce platforms to bypass distributor margin capture and build direct relationships with micro-distilleries seeking flavor differentiation. For Investors and Strategic Acquirers: The EU F-Gas Regulation's 2030 phasedown completion reshapes the acquisition landscape toward malters with ammonia-based cooling retrofits already deployed. Long-term viability centers on facilities combining biomass gasification with AI kiln control, with the inflection signal being brewery procurement teams' simultaneous demands for organic, carbon-neutral, and heritage-grain certifications compressing quality assurance timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Kiln Electrification Retrofit | Secures carbon-neutral brewery contracts in Denmark and the Netherlands ahead of regulatory deadlines. |
| Heritage-Grain Sourcing Partnership | Locks in exclusive Paris Basin soft wheat varieties for Reinheitsgebot-adjacent Bavarian brewers. |
| AI-Driven Moisture Optimization | Enables real-time color control while meeting KBA emissions thresholds exceeding EU baselines. |
| Eastern European Capacity Expansion | Captures Polish craft demand before German import dependencies solidify into long-term contracts. |
| Supply-Chain Finance Facility | Absorbs extended receivables cycles from Scottish and Irish distillery customers without margin erosion. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across malting facility managers, brewery procurement directors, distillery sourcing leads, and farmer cooperative representatives. Secondary validation drew from EU F-Gas Regulation implementation filings, German KBA emissions compliance records, customs trade data for wheat and malt flows, and agricultural cooperative production disclosures. Bottom-up volume estimates from individual facility capacities were triangulated against top-down consumption projections derived from brewery production statistics.
Calibration against historical capacity utilization rates and documented contract structures anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product modification level, end-use application, thermal energy source, and regional regulatory cluster. CAGRs were derived from slope analysis of volume trajectories adjusted for carbon border adjustment mechanism phase-in effects and craft brewery formation rates.
Sensitivities concentrate around Black Sea supply disruption persistence, EU Green Deal enforcement acceleration, and brewery consolidation patterns altering contract structures. Forecasts reflect documented assumptions regarding emissions compliance timelines and heritage-grain adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Wort Concentrate Market
Ingredients
Europe Edible Oil Market
Ingredients
Shortening Fats Market
Ingredients
Malted Barley Flour Market
Ingredients
Industrial Sugar Market
Ingredients
Potato Protein Market
Ingredients
Tannin Market
Ingredients
United States Whey Protein Ingredients Market
Ingredients
United States Soy Protein Market
Ingredients
Insect-Based Ingredients Market
Ingredients
Salt Market
Ingredients
South America Insoluble Dietary Fibers Market
Ingredients
Oyster Shell Powder Market
Ingredients
India Protein Market
Ingredients
Codonopsis Extract Market
Ingredients
Global Tomato Powder Market