
 South America Dairy Based Beverages Market | 2026-2036
South America Dairy Based Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
South America Dairy Based Beverages Market Analytics
Clean-label processing technology is fragmenting traditional production architectures across the South America dairy beverages sector. FrieslandCampina leverages its whey protein isolation capabilities to dominate functional drink formulations in the Andean zone. Grupo Lala anchors its position through extensive cold-chain distribution across Mexican and Central American corridors, while Danone SA differentiates via fermented beverage expertise tailored to local palate preferences.
Dairy based beverages constitute fluid milk products incorporating additional ingredients such as fruit purees, sweeteners, or probiotic cultures, typically processed through ultra-high temperature treatment or cold aseptic filling to achieve shelf stability or refrigerated distribution. Their primary commercial purpose centers on delivering convenient nutrition formats that bridge gaps between traditional liquid milk consumption and evolving on-the-go lifestyle patterns. Flavored milk captures the largest volume pool due to its penetration across school nutrition programs and retail channels, while probiotic beverages represent the fastest-expanding margin segment as health-conscious consumers in urban Brazil and Argentina prioritize gut wellness claims. Yogurt drinks occupy a mature position with established household penetration, though innovation in reduced-sugar formulations is reactivating interest among regulatory-sensitive buyers.
ANVISA governs dairy beverage safety standards and nutritional claim verification across Brazil, while Argentina's national food code enforces compositional thresholds that constrain imported formulation variability. The Mercosur technical regulation on dairy product harmonization is reshaping cross-border manufacturing decisions for multinational suppliers. Stakeholders must monitor how evolving front-of-pack labeling mandates across the region will force reformulation investments or channel repositioning.
Market Dynamics
ANVISA's updated front-of-pack labeling mandates are forcing accelerated reformulation timelines across Brazilian dairy beverage manufacturers, compressing product development cycles while simultaneously opening premium positioning for compliant brands.
Growth Catalysts
- Protein fortification protocols:Health clubs in São Paulo's metropolitan corridor are expanding procurement of whey-isolated dairy drinks, creating institutional demand anchors for functional beverage lines.
- ANVISA nutritional transparency frameworks:Brazil's revised labeling requirements are accelerating clean-label investments, rewarding early movers with shelf-space advantages in retail channels.
- Andean cold-chain expansion:Infrastructure investments across Peru and Colombia are extending refrigerated distribution reach for probiotic and fresh dairy beverages into secondary urban markets.
Market Restraints
- Feed cost volatility:Argentine dairy processors face margin compression from soybean meal price fluctuations, the primary protein input for regional cattle operations.
- Import formulation constraints:Argentina's national food code enforces compositional thresholds that restrict formulation variability for multinational suppliers seeking cross-border harmonization.
- Plant-based substitution acceleration:Oat and almond milk alternatives are capturing trial among urban Brazilian consumers aged 18-34, particularly in Rio de Janeiro's coastal districts.
Strategic Opportunities
- Uruguayan export corridor development:Mercosur technical regulation harmonization is enabling Uruguayan processors to supply Brazilian retailers with tariff-advantaged UHT milk bases.
- School nutrition program expansion:Chile's subsidized breakfast initiatives are creating institutional volume anchors for vitamin-fortified flavored milk formats.
- Fermented beverage microbiome positioning:Argentine urban consumers are demonstrating willingness to pay premium prices for clinically validated probiotic strain claims in drinkable yogurt.
Industry Challenges
- Clean-label technician scarcity:Brazilian manufacturers report difficulty recruiting formulation chemists experienced in natural stabilizer substitution for synthetic additive removal.
- Refrigerated last-mile capex intensity:Cold-chain extension into Brazil's northeastern states requires substantial fleet and depot investment with extended payback periods.
- Mercosur cross-border certification complexity:Divergent national interpretations of harmonized dairy standards are creating customs delays for multi-country supply networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Dairy Based Beverages Market |
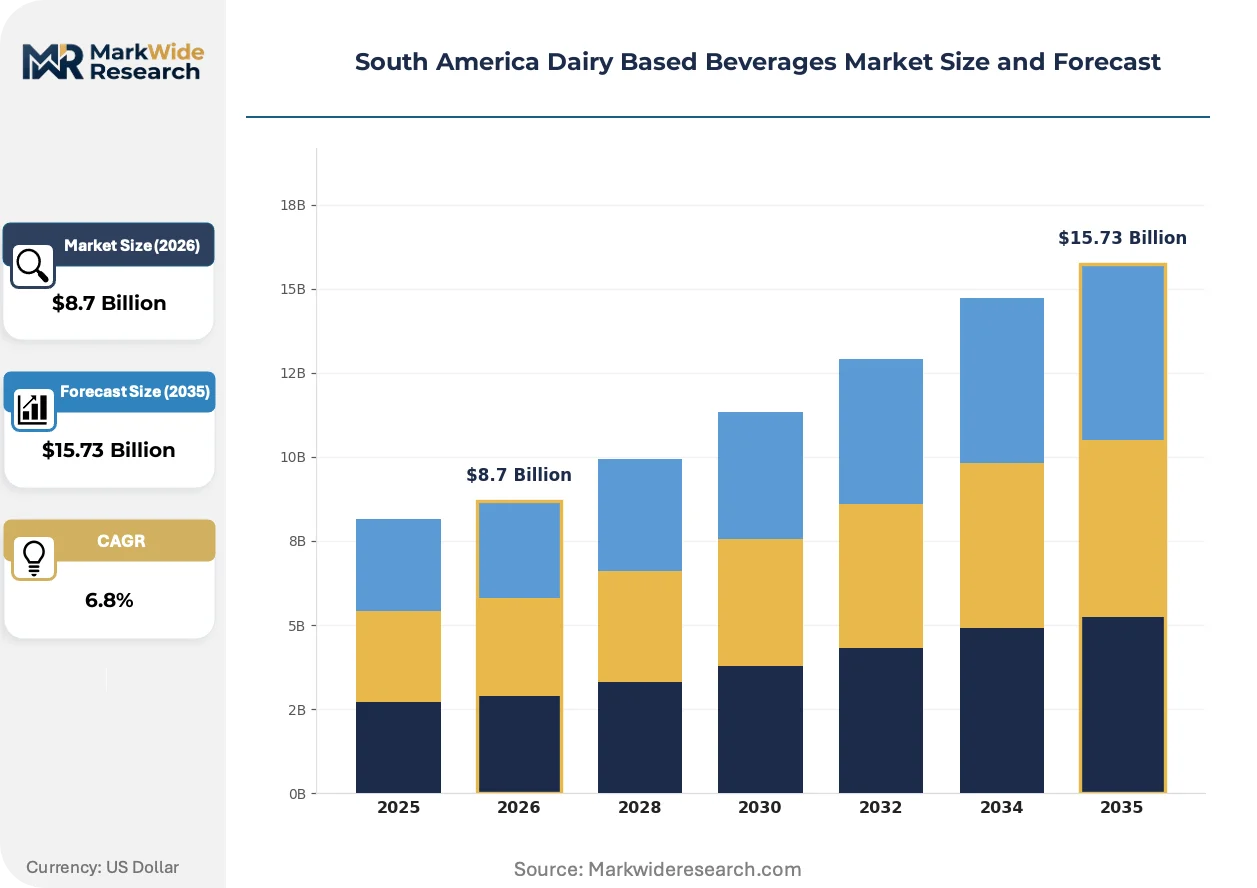
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yogurt Drinks, Flavored Milk, Milkshakes, Probiotic Beverages End User: Retail Consumers, Cafés, Restaurants, Health Clubs Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Direct Sales Ingredient Type: Fruit, Sweeteners, Nutritional Additives, Others |
| Companies Covered | FrieslandCampina, Grupo Lala, Nestlé SA, SanCor Cooperativas Unidas Limitada, Mastellone Hermanos, Danone SA, Alpina Productos Alimenticios, Laticinios Bela Vista, Groupe Lactalis, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Dairy Based Beverages Market Evolving Landscape
Processing architectures across South American dairy beverages are fragmenting as clean-label imperatives collide with shelf-stability requirements, forcing equipment and formulation investments that favor flexible manufacturing footprints over traditional scale economies.
Membrane filtration technology is hybridizing traditional thermal processing workflows. Ultra and nanofiltration systems now enable whey protein concentration at lower temperatures, preserving bioactive fractions for functional drink applications. Brazilian processors in Minas Gerais are retrofitting existing UHT lines with modular membrane skids, compressing capital requirements for premium protein beverage entry while maintaining base milk output capacity.
ANVISA's front-of-pack octagonal warning label system is reshaping formulation priorities across Brazil's dairy sector. The regulation triggers mandatory warning symbols for products exceeding sugar, sodium, or saturated fat thresholds, effectively disqualifying traditional flavored milk formulations from health-positioned marketing. Manufacturers are responding with stevia and monk fruit sweetener conversions, though taste acceptance testing in São Paulo focus groups shows persistent palate adaptation challenges among core demographic segments.
Direct-to-gym distribution models are displacing traditional wholesale club procurement for protein-fortified dairy beverages. Brazilian fitness chains are negotiating exclusive supply arrangements with regional processors, bypassing retail markup structures while capturing consumption data for flavor optimization. This channel compression is most visible in Rio de Janeiro and São Paulo states, where premium health club density supports dedicated delivery logistics and rotating SKU experimentation.
South America Dairy Based Beverages Market Segmentation
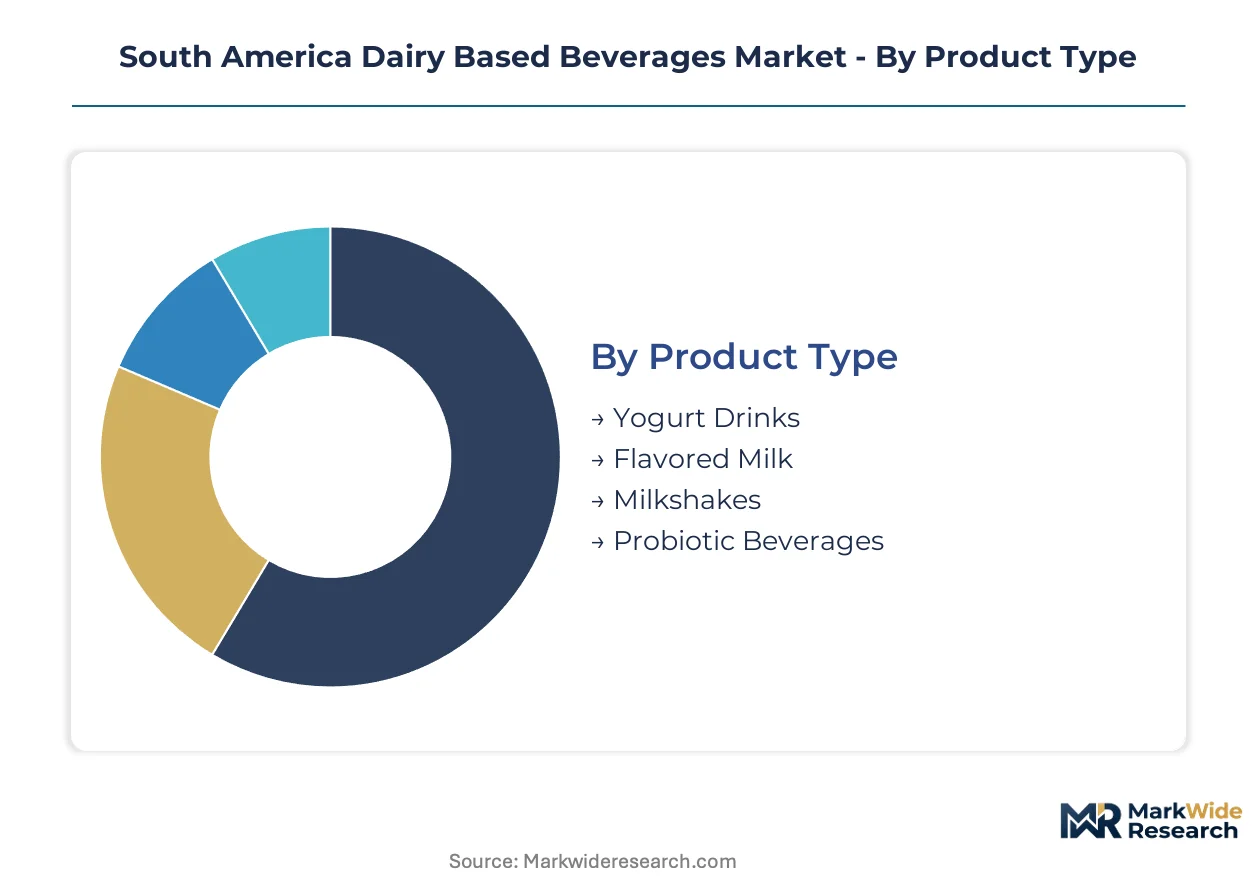
Segmentation across South America's dairy beverage sector reveals divergent growth mechanics between mature volume anchors and emerging premium formats. Understanding these fault lines enables suppliers to allocate reformulation investment and channel resources against shifting consumption patterns.
Product Type:
Maturity gradients separate established household staples from nascent functional categories with divergent margin profiles.
- Flavored Milk:UHT-treated milk incorporating cocoa, strawberry, or vanilla flavoring systems, typically packaged in Tetra Pak or PET formats for ambient distribution. Demand concentrates in Brazil's school nutrition programs and São Paulo's metropolitan retail corridor, driven by institutional procurement volumes and parental familiarity with fortified formats.
- Probiotic Beverages:Fermented dairy drinks containing live Lactobacillus or Bifidobacterium cultures, processed through controlled fermentation and cold-chain distribution. Argentine urban consumers in Buenos Aires demonstrate willingness to pay premium prices for clinically validated strain claims, particularly following ANVISA's front-of-pack labeling mandates that disadvantage conventional sugary alternatives.
- Yogurt Drinks:Drinkable fermented milk with standardized viscosity, ranging from traditional thin consistency to Greek-style protein concentrates.
- Milkshakes:High-viscosity dairy blends incorporating ice cream bases or thickeners, positioned as indulgence or meal-replacement formats.
Flavored milk handles the majority of throughput; probiotic beverages are expanding most quickly on share.
End User:
Channel concentration patterns reflect divergent service requirements and procurement sophistication across consumer and institutional buyers.
- Retail Consumers:Individual households purchasing through supermarkets, convenience stores, and e-commerce platforms for at-home consumption. Brazil's southeastern states, particularly Rio de Janeiro's coastal districts, show accelerating trial of reduced-sugar formulations among health-conscious demographics.
- Health Clubs:Fitness facilities procuring protein-fortified dairy drinks for member consumption and retail resale. São Paulo's metropolitan corridor anchors institutional demand for whey-isolated formulations, with Brazilian chains negotiating exclusive supply arrangements that bypass traditional wholesale markups.
- Cafés:Coffee shop operators incorporating dairy beverages into blended drink menus or standalone offerings.
- Restaurants:Foodservice establishments sourcing bulk dairy beverages for children's menus or beverage programs.
Retail consumers dominate absolute volume; health clubs are climbing the fastest as a procurement channel.
Distribution Channel:
Physical retail maintains grip on immediate consumption needs while digital infrastructure captures replenishment and specialty purchasing.
- Supermarkets:Full-format grocery retailers with refrigerated dairy cases and ambient UHT shelving across Brazil, Argentina, and Chile. ANVISA's octagonal warning label requirements are compressing shelf-space advantages for compliant reformulations in São Paulo and Minas Gerais retail networks.
- Online Retail:E-commerce platforms and direct-to-consumer fulfillment operations, expanding rapidly for subscription-based probiotic and protein beverage replenishment. Cold-chain logistics investments in Peru and Colombia are extending refrigerated delivery reach into secondary urban markets.
- Convenience Stores:Small-format retailers emphasizing grab-and-go flavored milk and single-serve yogurt drinks for immediate consumption.
- Direct Sales:Manufacturer-to-institution supply arrangements, particularly for health club and school nutrition program volumes.
Supermarkets handle the majority of throughput; online retail is gaining share fastest among premium functional formats.
Ingredient Type:
Clean-label substitution pressures are fragmenting formulation architectures across natural and synthetic input categories.
- Sweeteners:Caloric and non-caloric sweetening systems including sucrose, stevia, and monk fruit extracts. Brazilian manufacturers face persistent palate adaptation challenges in São Paulo focus groups when converting traditional flavored milk to natural alternatives.
- Nutritional Additives:Protein concentrates, vitamin premixes, and mineral fortificants targeting specific health claims. Whey protein isolation capabilities anchor functional drink formulations in the Andean zone, with FrieslandCampina leveraging technical expertise for premium positioning.
- Fruit:Purees, juices, and flavoring systems derived from strawberry, banana, mango, and other regional produce.
- Others:Stabilizers, emulsifiers, and texturizing agents including both synthetic and natural alternatives.
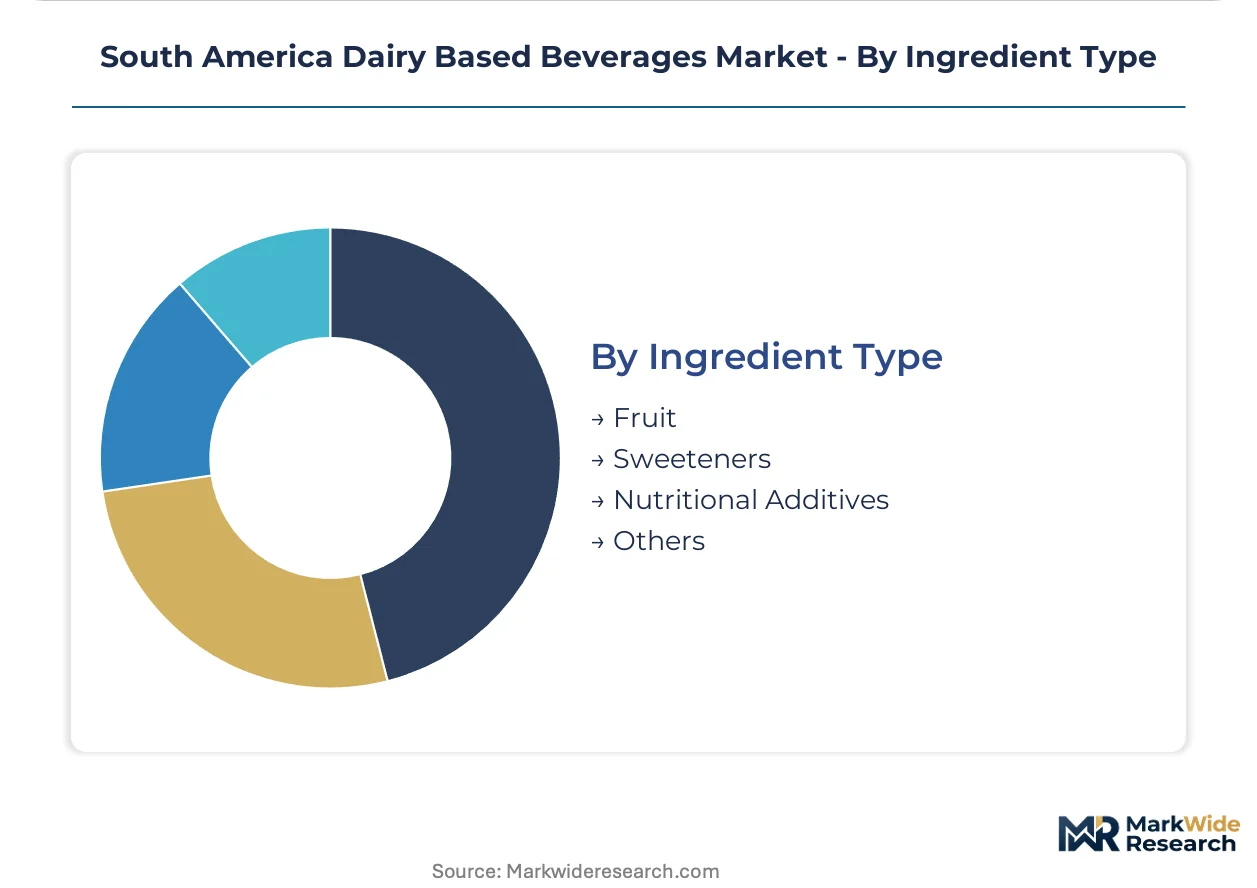
Sweeteners handle the majority of formulation volume; nutritional additives are the fastest mover on share as protein fortification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Uruguayan processors leverage Mercosur technical regulation harmonization to supply Brazilian retailers with tariff-advantaged UHT milk bases, redirecting traditional Argentine-Brazil trade flows through Montevideo's expanding dairy corridor.
Brazil
São Paulo's metropolitan corridor anchors institutional demand for protein-fortified dairy drinks through exclusive health club supply arrangements. ANVISA's front-of-pack octagonal warning label system compresses reformulation timelines for flavored milk manufacturers. Minas Gerais processors retrofit existing UHT lines with modular membrane filtration skids to preserve bioactive whey fractions.
Argentina
Buenos Aires urban consumers demonstrate willingness to pay premium prices for clinically validated probiotic strain claims in drinkable yogurt formats. The national food code enforces compositional thresholds that restrict formulation variability for multinational suppliers seeking cross-border harmonization. Córdoba's dairy belt faces margin compression from soybean meal price volatility affecting cattle feed inputs.
Chile
Santiago's subsidized breakfast initiatives create institutional volume anchors for vitamin-fortified flavored milk distribution through school nutrition programs. Cold-chain infrastructure investments extend refrigerated probiotic beverage reach into Valparaíso's secondary urban markets. The country's technical standards align with Mercosur harmonization protocols, enabling cross-border manufacturing flexibility.
Colombia
Bogotá's metropolitan retail networks show accelerating trial of reduced-sugar dairy formulations among health-conscious demographics aged 25-40. Andean cold-chain expansion enables refrigerated distribution of fresh probiotic beverages into Medellín's secondary markets. Regional processors leverage membrane filtration technology to compress capital requirements for premium protein beverage entry.
Peru
Lima's coastal districts capture oat and almond milk substitution trial among urban consumers aged 18-34, pressuring traditional dairy beverage positioning. Infrastructure investments in refrigerated logistics extend probiotic drink distribution into Arequipa's emerging urban corridors. Local manufacturers respond to clean-label imperatives with natural stabilizer substitution for synthetic additive removal.
South America Dairy Based Beverages Market Competitive Landscape
Channel-controlling players compete with product-specialist players across South America's dairy beverage sector, creating a tiered structure where cold-chain reach and formulation expertise determine positioning. The market consolidates around multinational dairy conglomerates with whey protein isolation capabilities and regional cooperatives with established procurement networks. Three archetypes dominate: scale-driven UHT processors, functional beverage specialists, and fermented dairy experts. Competitive moves center on exclusive health club distribution arrangements and membrane filtration technology licensing for clean-label reformulation.
Among Netherlands-based dairy conglomerates, FrieslandCampina occupies a position exemplifying whey protein isolation capabilities for functional drink formulations. Mexican and Central American corridor specialists include Grupo Lala, which anchors its presence through extensive cold-chain distribution infrastructure. French multinational Danone SA represents the fermented beverage expertise archetype, with positioning tailored to local palate preferences across Brazilian and Argentine urban markets.
| Leading Market Players |
|---|
| FrieslandCampina |
| Grupo Lala |
| Nestlé SA |
| SanCor Cooperativas Unidas Limitada |
| Mastellone Hermanos |
| Danone SA |
| Alpina Productos Alimenticios |
| Laticinios Bela Vista |
| Groupe Lactalis |
| Others |
Value Network & Pricing Analysis
ANVISA's front-of-pack octagonal warning label mandates compress reformulation timelines and force dual-tier pricing spreads between compliant premium formulations and legacy sugary alternatives. This regulatory chokepoint simultaneously widens margin spreads and redirects procurement toward membrane filtration-equipped processors capable of clean-label conversion.
Pricing Analysis
Current-generation membrane filtration-enabled protein beverages command substantial premiums over legacy UHT thermal processing formats, while next-generation fermented microbiome-positioned products are establishing ultra-premium tiers. Three-tier pricing structure across premium functional, standard fortified, and economy flavored milk levels dominates Brazilian retail channels. Price differentiation stems from certification grade under ANVISA's nutritional transparency frameworks and cold-chain delivery cost to secondary markets. Cost compression in economy flavored milk is intensifying because soybean meal feed volatility transmits through Argentine dairy belts. Institutional buyers in São Paulo's health club corridor demonstrate lowest price sensitivity, while northeastern Brazil retail consumers exhibit highest elasticity.
Supply Chain Analysis
Extended payment terms from Brazilian supermarket chains are forcing Uruguayan and Argentine processors to absorb working capital strain or seek supply-chain finance facilities. Geographic supply concentration centers on Brazil, Argentina, and Uruguay within Mercosur's harmonized trade zone. Raw material dependencies include whey protein concentrates, natural stabilizers, and probiotic culture strains. Single-source vulnerability pervades membrane filtration equipment supply, with Brazilian retrofit projects competing for limited technician availability. Distribution runs through refrigerated depot networks anchored in São Paulo and Minas Gerais, extending via cold-chain fleets into secondary urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where ANVISA's regulatory entrenchment creates substantial switching costs for reformulation-compliant incumbents. Network effects consolidate around cold-chain density and exclusive health club distribution arrangements.
For Market Incumbents: Harden membrane filtration capabilities through backward integration into whey protein isolation or captive supply agreements with Andean zone specialists. Defensive consolidation should prioritize exclusive health club distribution lockups in Rio de Janeiro and São Paulo states before plant-based substitutes erode institutional channel loyalty. Regulatory shift toward expanded front-of-pack labeling across Mercosur jurisdictions threatens margin recovery timelines for laggard reformulators. For New Entrants and Emerging Players: Colombian Andean cities with nascent cold-chain infrastructure represent the most penetrable entry point for probiotic beverage specialists seeking whitespace before incumbent network effects crystallize. Peruvian coastal districts among oat-milk-curious urban demographics aged 18-34 offer secondary beachhead for hybrid dairy-plant positioning. Direct-to-gym distribution partnerships bypassing traditional wholesale markups provide the decisive go-to-market angle for protein-fortified launches. For Investors and Strategic Acquirers: ANVISA's expanded nutritional transparency mandates reshape the acquisition landscape toward processors with demonstrated clean-label reformulation track records. Long-term viability across the projection horizon favors targets with membrane filtration retrofit completion and established health club channel relationships. Acquisition target archetype: mid-cap Brazilian processors in Minas Gerais with UHT line flexibility and pending ANVISA compliance certification. Signal to monitor: Mercosur technical regulation harmonization progress on cross-border dairy standard convergence.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Retrofit | Enables whey protein concentration at lower temperatures for functional beverage premiumization. |
| Exclusive Health Club Distribution | Bypasses retail markup structures while capturing consumption data for flavor optimization. |
| Natural Stabilizer Substitution | Removes synthetic additives to achieve ANVISA octagonal warning label compliance. |
| Andean Cold-Chain Expansion | Extends refrigerated probiotic reach into secondary Colombian and Peruvian urban markets. |
| Mercosur Harmonization Alignment | Enables Uruguayan processors to supply Brazilian retailers with tariff-advantaged UHT bases. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with Brazilian dairy formulation chemists, Argentine probiotic strain researchers, Chilean school nutrition program procurement officers, and Colombian cold-chain logistics directors. Secondary validation drew from ANVISA regulatory filings, Mercosur technical regulation harmonization documents, Brazilian supermarket scanner data, and Argentine agricultural commodity price indices. Bottom-up volume modeling triangulated against top-down category expenditure estimates.
Calibration across the analysis window employed scenario-weighted projections reflecting reformulation compliance timelines and health club channel penetration trajectories. Segmentation dimensions modeled include product type, end user archetype, distribution channel, and ingredient technology tier. CAGRs were derived from trend extrapolation moderated by regulatory inflection assumptions. Industry-specific forecast inputs incorporated membrane filtration adoption curves and natural sweetener palate acceptance testing results from São Paulo focus groups.
Practitioners should monitor ANVISA enforcement intensity, Mercosur harmonization implementation delays, and feed cost volatility indices for early signals of forecast deviation. Forecasts reflect documented assumptions regarding regulatory timeline adherence and cold-chain infrastructure investment continuity. Macroeconomic contraction, regulatory rollback, or breakthrough plant-based formulation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Packaged Cactus Water Market
Beverages
Asia-Pacific Spring Water Market
Beverages
South America Mate Market
Beverages
North America Fruits and Vegetables Juice Market
Beverages
Mixers Market
Beverages
Sparkling Juice Drinks Market
Beverages
Global Soft Drinks Concentrate Market
Beverages
Baby Drinking Water Market
Beverages
Oat Based Beverages Market
Beverages
Sparkling Soda Market
Beverages
Reconstituted Juice Market
Beverages
Caffeine-Based Drinks Market
Beverages
India Cafes & Bars Market
Beverages
Fusion Beverages Market
Beverages
Packaged Natural Mineral Water Market
Beverages
Powdered Soft Drinks Market