
 North America Yerba Mate Market | 2026-2036
North America Yerba Mate Market Size, Share, and Industry Trends Forecast 2026-2036
North America Yerba Mate Market Analytics
Aftermarket service revenue from equipment maintenance and brewing-system leasing is fragmenting as direct-to-consumer brands bypass traditional café supply chains. Guayaki Yerba Mate leverages its vertically integrated sourcing model to control quality from Argentine estates through U.S. bottling facilities. ECOTEAS Organic Yerba Mate sustains its position through certified organic supply chains that appeal to environmentally selective buyers. Herboflora specializes in botanical-infused formulations that differentiate its portfolio from commodity-grade competitors.
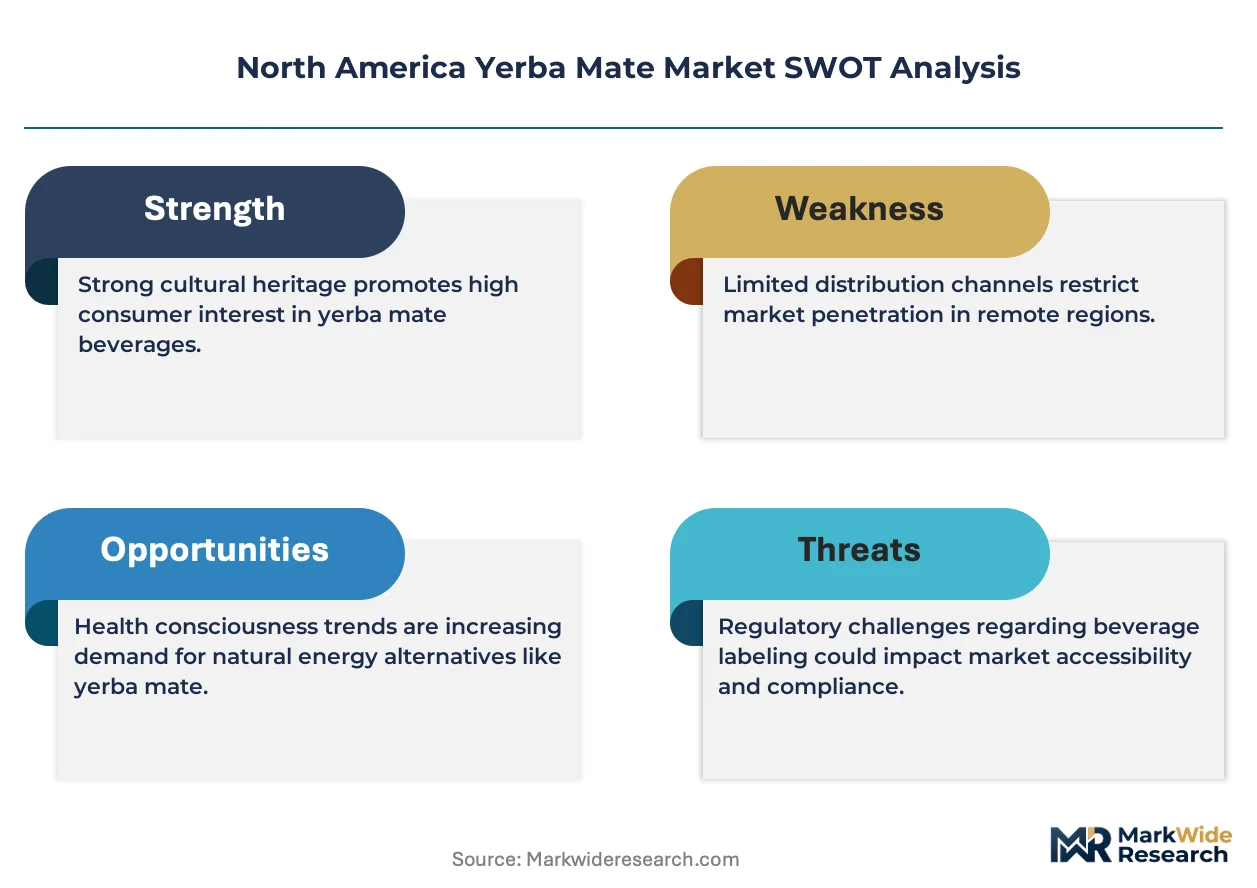
Yerba mate comprises dried leaves and stems of Ilex paraguariensis, a holly species native to subtropical South America, typically containing 1-2% caffeine by dry weight along with polyphenols and saponins that produce its characteristic bitter, earthy profile. The plant undergoes a multi-stage processing sequence of harvesting, blanching, drying, aging, and milling before commercial packaging for infusion or ready-to-drink formulation. Its primary commercial purpose centers on delivering sustained energy and cognitive alertness without the jitter effects commonly associated with coffee consumption. Organic and flavored product types command premium shelf positioning as health-conscious consumers migrate toward clean-label botanical beverages. Online retail distribution channels exhibit the fastest expansion trajectory, though supermarkets retain dominant volume throughput through established beverage aisle placement.
The U.S. FDA oversees food additive safety and labeling requirements for yerba mate imports, while USDA Organic certification governs premium-tier product eligibility and price positioning. Health Canada and the PMRA regulate pesticide residue thresholds and natural health product claims for Canadian market entry, creating compliance complexity for cross-border suppliers. Stakeholders must monitor evolving caffeine-content disclosure mandates and adapt formulation strategies as regulatory scrutiny of energy-positioned beverages intensifies across both jurisdictions.
Market Dynamics
The North America yerba mate market is being reshaped by direct-to-consumer brands bypassing traditional café supply chains, fragmenting aftermarket service revenue and forcing incumbent suppliers to rebuild distribution architectures around e-commerce fulfillment and subscription models.
Growth Catalysts
- USDA Organic certification:Premium-tier eligibility under this program commands shelf positioning and price premiums that accelerate margin expansion for certified importers targeting wellness-oriented retail channels.
- Specialty beverage cafes:Menu expansion across United States and Canadian urban centers creates dedicated consumption occasions that build habitual demand among coffee-alternative seekers.
- California's urban wellness corridors:Concentrated Latin American cultural influence overlapping with health-conscious retail density produces the continent's highest per-capita consumption rates and brand trial velocity.
Market Restraints
- Argentine supply concentration:Estate-level sourcing dependency creates climate and currency exposure that compresses margin predictability for brands without captive cultivation relationships.
- Health Canada PMRA residue thresholds:Pesticide compliance complexity for cross-border suppliers extends Canadian market entry timelines and elevates testing costs relative to domestic distribution.
- Coffee substitution economics:Established roast-and-brew infrastructure and consumer habit formation present durable switching costs that limit penetration in conventional beverage occasions.
Strategic Opportunities
- Pacific Northwest functional beverage corridor:Underpenetrated metropolitan markets in Oregon and Washington offer whitespace for yerba mate positioning against kombucha and adaptogenic drink incumbents.
- Ready-to-drink formulation innovation:Shelf-stable canned and bottled formats unlock convenience-store and gas-station distribution channels previously inaccessible to loose-leaf and traditional preparation methods.
- US FDA evolving caffeine disclosure mandates:Anticipatory compliance with forthcoming labeling requirements positions early adopters for regulatory preference and retail partnership security.
Industry Challenges
- Botanical sourcing expertise scarcity:Qualified procurement professionals capable of evaluating Ilex paraguariensis quality grades and aging protocols command premium compensation that elevates fixed costs for emerging brands.
- Multi-jurisdictional label compliance:Simultaneous satisfaction of US FDA food additive rules, USDA Organic standards, and Health Canada natural health product claims creates documentation overhead that slows product launch velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Yerba Mate Market |
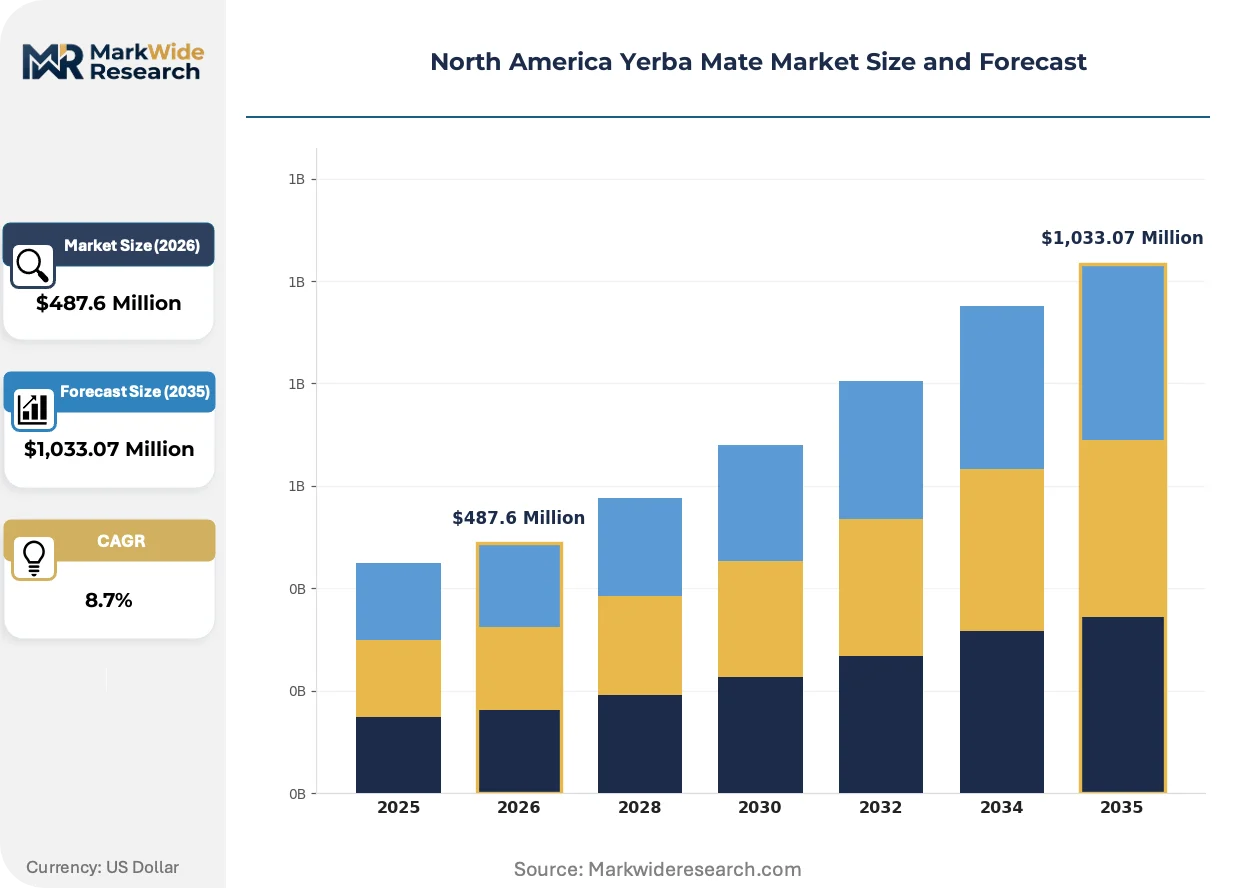
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Flavored, Organic, Instant Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops Package Type: Bags, Loose Leaf, Cans, Bottles Customer Type: Health Conscious, Millennials, Traditionalists, Casual Drinkers |
| Companies Covered | Vita Forte Inc., Mate Factor, EOCTEAS, Guayaki Yerba Mate, ECOTEAS Organic Yerba Mate, Herboflora, Darka Company s.r.o, La Hoja, pajarito powder, llc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Yerba Mate Market Evolving Landscape
Digital infrastructure is compressing traditional beverage distribution hierarchies, enabling direct relationships between South American estates and North American consumers that bypass import intermediaries and reshape quality verification mechanisms.
Cold-brew extraction technology is virtualizing the traditional thermos-and-bombilla preparation ritual, enabling shelf-stable concentrates that deliver polyphenol retention and flavor consistency without consumer equipment investment. Functional beverage startups in Austin and Denver are adopting this format at accelerated pace, compressing the addressable market for loose-leaf preparation systems and redirecting capital toward co-packing facility expansion.
Health Canada's evolving guidance on natural health product caffeine thresholds is tightening permissible positioning claims for energy-focused yerba mate marketing, forcing reformulation toward adaptogenic and nootropic co-ingredient strategies that satisfy amended disclosure requirements. Canadian importers are responding by front-loading clinical substantiation investments that exceed current compliance minima, creating defensive moats against retrospective enforcement actions.
Subscription-based replenishment models are displacing supermarket aisle discovery as the primary customer acquisition channel, with direct-to-consumer brands capturing lifetime value through automated shipment cadences that lock in pantry share. This behavioral pivot concentrates marketing spend on digital performance channels rather than slotting fees, with highest visibility in California's metropolitan wellness corridors where trial-to-subscription conversion rates exceed conventional retail benchmarks.
North America Yerba Mate Market Segmentation
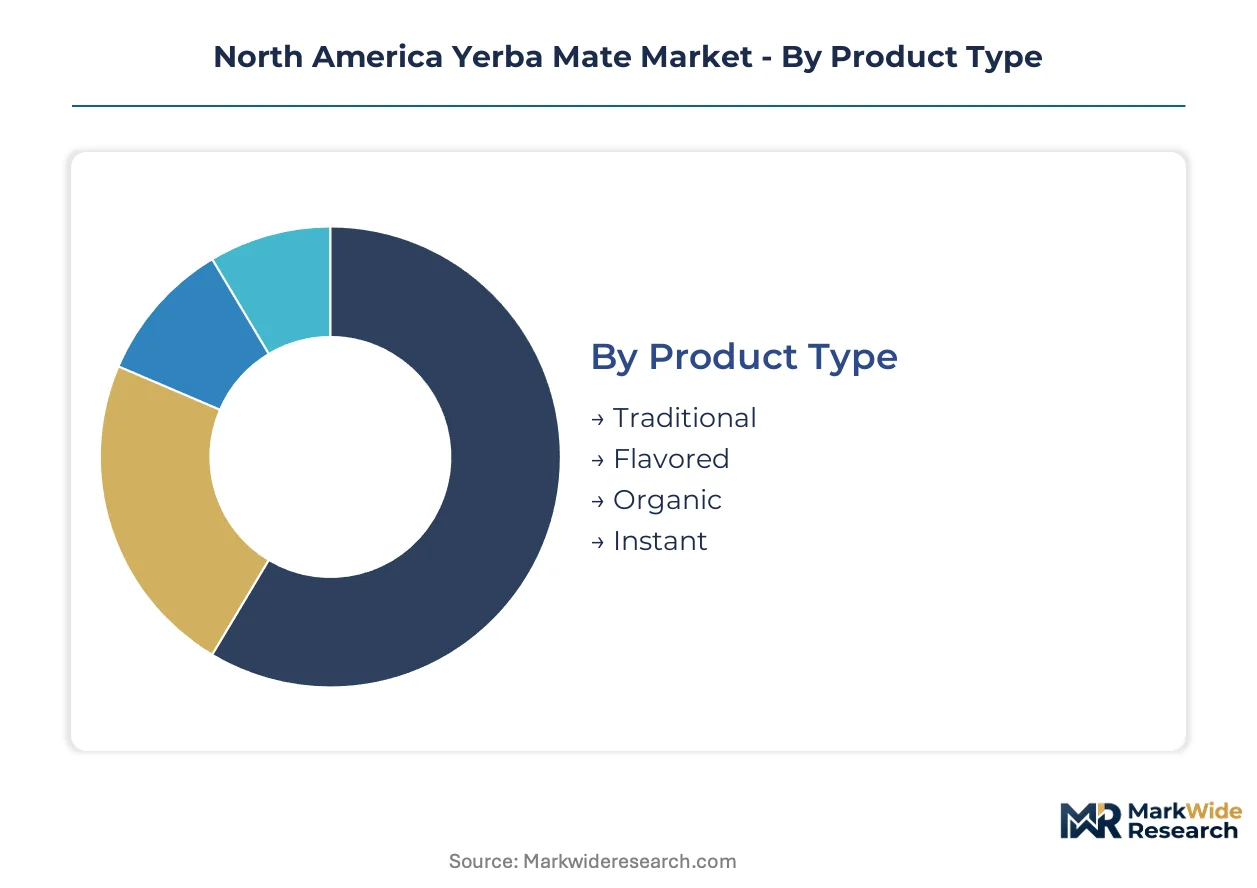
Yerba mate's North American penetration depends on matching preparation format to consumption occasion and aligning certification credentials with retail channel requirements. Segmentation reveals where margin concentrates and which customer acquisition pathways scale efficiently.
Product Type:
Cost tier differentiation separates commodity-grade offerings from certified organic and functional-positioned products, with formulation complexity determining price realization and shelf placement.
- Traditional:Unflavored dried leaf and stem preparations containing standard caffeine and polyphenol profiles. Demand concentrates in California's Latin American heritage communities and specialty café channels where authentic preparation rituals sustain loyalty.
- Organic:USDA-certified cultivation meeting residue thresholds for premium retail eligibility. Health-conscious consumers in Pacific Northwest metropolitan corridors drive trial velocity, with certification unlocking placement in Whole Foods and independent co-op networks.
- Flavored:Botanical and fruit infusions masking characteristic bitterness for new-user accessibility. Citrus and mint variants perform strongest in ready-to-drink canned formats targeting convenience-store distribution.
- Instant:Soluble powder extracts enabling hot and cold reconstitution without traditional equipment. Travel and workplace consumption occasions favor this format despite polyphenol degradation relative to loose-leaf preparation.
Traditional formulations command the established base. The steepest expansion runs through Organic certification tiers.
Distribution Channel:
Application context dictates channel selection, with ritual preparation favoring specialty retailers and convenience seeking driving digital and mass-market growth.
- Online Retail:Direct-to-consumer subscriptions and marketplace fulfillment capturing pantry share through automated replenishment. California wellness corridors exhibit highest conversion rates from trial to recurring shipment.
- Supermarkets:Dominant volume throughput via beverage aisle placement in Kroger, Safeway, and Publix banners. Slotting fee requirements and promotional calendar alignment favor established brands with trade marketing budgets.
- Health Stores:Independent co-ops and natural grocers prioritizing certified organic and fair-trade credentials. Staff recommendation influence drives brand discovery among supplement-adjacent shoppers.
- Specialty Shops:Latin American grocers and dedicated tea retailers serving heritage consumers and preparation-equipment purchasers. Bombilla and thermos bundling sustains higher basket values.
Supermarkets anchor volume throughput. Digital channels gain share fastest through subscription lock-in mechanics.
Package Type:
Volume scale and preparation investment separate formats, with single-serve convenience commanding premium pricing against bulk loose-leaf economy.
- Bags:Filter-paper sachets enabling steeping without gourd or bombilla equipment. Office and travel occasions favor this accessible entry point for coffee-alternative seekers.
- Loose Leaf:Traditional cut leaf requiring gourd preparation and temperature-controlled water. Enthusiast segments in Austin and Denver sustain demand despite equipment barriers to trial.
- Cans:Shelf-stable ready-to-drink formats with nitrogen flushing for oxidation control. Cold-brew processing preserves polyphenol content while unlocking gas station and convenience store distribution.
- Bottles:Refrigerated premium concentrates and multi-serve formats. Higher per-unit pricing targets specialty café and direct-to-consumer channels with functional positioning claims.
Loose leaf retains the heritage core. Canned formats expand most quickly through convenience retail penetration.
Customer Type:
Customer maturity and wellness orientation determine price sensitivity and preparation tolerance, with behavioral segmentation guiding channel and messaging allocation.
- Health Conscious:Supplement-adjacent consumers prioritizing polyphenol content and clean-label positioning. USDA Organic and adaptogenic co-ingredient claims drive purchase decisions in natural retail.
- Millennials:Digital-native cohort discovering yerba mate through social media and influencer recommendation. Subscription models and flavored RTD formats reduce friction for this segment.
- Traditionalists:Heritage consumers maintaining cultural preparation practices. Argentine and Brazilian immigrant communities in Miami and Los Angeles sustain demand for unflavored loose-leaf grades.
- Casual Drinkers:Occasional purchasers seeking energy alternatives without coffee commitment. Supermarket promotional pricing and bagged formats serve this price-sensitive, low-loyalty segment.
Traditionalists anchor the core consumption base. Millennial adoption shows the steepest trajectory through digital-native brand building.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the continent. The United States favors ready-to-drink convenience formats, while Canada maintains stricter residue thresholds that elevate organic certification premiums. Mexico's heritage preparation rituals sustain loose-leaf demand in border-adjacent markets.
United States
California's wellness corridors and Austin's functional beverage startup density drive premium-tier adoption. The FDA's evolving caffeine-content disclosure mandates force anticipatory label reformulation. Guayaki Yerba Mate's vertically integrated model anchors supply chain control from Argentine estates through U.S. bottling facilities.
Canada
Health-conscious consumers in Toronto and Vancouver prioritize USDA Organic and fair-trade credentials. Health Canada and the PMRA enforce pesticide residue thresholds that extend cross-border supplier testing timelines. ECOTEAS Organic Yerba Mate sustains positioning through certified organic supply chains that satisfy these elevated compliance requirements.
Mexico
Heritage preparation rituals in Mexico City and Monterrey sustain demand for traditional loose-leaf grades. Mexican food safety regulators apply NOM standards for imported botanical ingredients that parallel U.S. FDA frameworks. Border-adjacent metropolitan markets in Tijuana and Ciudad Juárez bridge consumption occasions between heritage ritual and U.S.-influenced convenience formats.
North America Yerba Mate Market Competitive Landscape
Capability concentration sits with vertically integrated specialists; scale advantage sits with direct-to-consumer platforms. The vendor base splits between estate-level sourcing operators and digital-native subscription brands. Three archetypes dominate: heritage importers with Argentine cultivation relationships, organic-certified specialists, and functional-positioned formulation innovators. Competitive moves center on co-packing facility expansion and anticipatory regulatory compliance investments.
Within the organic-certified tier, ECOTEAS Organic Yerba Mate exemplifies supply chain transparency positioning. Guayaki Yerba Mate occupies the scale-driven end with captive sourcing infrastructure. Herboflora represents botanical-infused formulation specialization that differentiates from commodity-grade competitors.
| Leading Market Players |
|---|
| Vita Forte Inc. |
| Mate Factor |
| EOCTEAS |
| Guayaki Yerba Mate |
| ECOTEAS Organic Yerba Mate |
| Herboflora |
| Darka Company s.r.o |
| La Hoja |
| pajarito powder, llc |
| Others |
Value Network & Pricing Analysis
Misiones Province estate capacity dynamics govern downstream pricing power for North American importers, with Argentine harvest variability transmitting directly into contract renegotiation leverage. USD-ARS exchange rate volatility compounds input cost unpredictability, forcing brands to absorb margin compression or pass through via subscription pricing adjustments.
Pricing Analysis
Long-term offtake contracts dominate procurement between established importers and Argentine cooperatives, locking in volume commitments that insulate against spot-market caffeine-commodity swings. Price differentiation rests on USDA Organic certification tier and vertical integration depth, with captive-estate brands commanding shelf placement premiums. Cost compression in commodity-grade tiers intensifies as direct-to-consumer entrants bypass traditional markup structures. Health-conscious subscribers in California wellness corridors exhibit lowest price sensitivity; casual supermarket purchasers in price-promotional channels show highest elasticity.
Supply Chain Analysis
Extended payment terms from North American distributors to Argentine growers strain working capital at estate level, accelerating consolidation toward cooperatives with supply-chain finance facilities. Cultivation concentrates in Argentina, with secondary sourcing from Paraguay and Brazil for varietal diversification. Raw material dependencies span Ilex paraguariensis leaf stock, nitrogen-flush packaging films, and cold-brew processing equipment. Single-source vulnerability runs through Buenos Aires port logistics, where customs delays cascade into subscription fulfillment disruptions. Distribution runs through captive bottling facilities in California and Texas, then splits between direct-to-consumer fulfillment centers and third-party retail logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as subscription platforms aggregate consumer demand, fragmenting traditional retail gatekeeper influence over brand discovery and shelf access.
For Market Incumbents: Harden supply chain control through backward integration into Argentine estate operations or exclusive multi-year cultivation agreements. Defend against direct-to-consumer disintermediation by locking in co-packing capacity expansion ahead of competitor facility construction. Prioritize anticipatory FDA caffeine disclosure compliance as a regulatory moat against retrospective enforcement exposure. For New Entrants and Emerging Players: Pacific Northwest metropolitan corridors in Oregon and Washington offer whitespace penetration against entrenched kombucha and adaptogenic beverage incumbents. Target ready-to-drink canned formats for convenience-store distribution, where heritage brands maintain weakest shelf presence. Deploy influencer-native digital acquisition through TikTok and Instagram wellness creators to compress trial-to-subscription conversion timelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated specialists with captive Argentine sourcing and California bottling infrastructure over asset-light digital brands. Long-term viability across the analysis window hinges on climate-adaptive cultivation partnerships and regulatory compliance anticipation. Monitor Health Canada PMRA residue threshold tightening as an inflection signal for cross-border supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Argentine Estates | Captive leaf supply insulates Guayaki and ECOTEAS from currency-driven cost volatility. |
| Direct-to-Consumer Subscription Launch | Automated replenishment locks pantry share and displaces supermarket discovery in California corridors. |
| Ready-to-Drink Canned Format Expansion | Nitrogen-flush cold-brew unlocks gas station and convenience store distribution previously inaccessible. |
| USDA Organic Certification Investment | Premium retail eligibility at Whole Foods and independent co-ops commands price realization above commodity tiers. |
| Anticipatory FDA Compliance Front-Loading | Early caffeine disclosure adaptation positions brands for regulatory preference and retail partnership security. |
Research Methodology
Desk research of customs import records, USDA organic certification databases, and FDA guidance documents preceded structured interviews with yerba mate brand executives, Argentine estate cooperative managers, and specialty beverage café procurement leads. Primary fieldwork with direct-to-consumer subscription operators and health store category buyers validated demand-side segmentation assumptions. Secondary triangulation incorporated Health Canada PMRA residue threshold filings and cold-brew processing equipment manufacturer specifications. Bottom-up volume modeling across product type, distribution channel, and customer segments converged with top-down trade flow analysis.
The forecast framework holds Argentine peso depreciation trajectory and FDA regulatory evolution within observed patterns, varying subscription adoption rates and ready-to-drink format penetration across sensitivity scenarios. Segmentation dimensions span preparation format, certification tier, package type, and regional consumption cluster. CAGRs derive from logistic adoption curve fitting against historical coffee-alternative beverage substitution patterns, with inputs from caffeine-content disclosure mandate timelines and Pacific Northwest market development indicators.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by emerging direct-to-consumer brands would shift outcomes through supply chain control acceleration. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Global Soda Maker Market
Beverages
Fruit and Vegetable Juice Market
Beverages
Ready to Drink Shakes Market
Beverages
United Kingdom Energy Drink Market
Beverages
Low Calorie RTD Beverages Market
Beverages
Grape Juice Concentrate for Wine Making Market
Beverages
Freezer & Beverage and Wine Cooler Market
Beverages
Extra Neutral Alcohol (ENA) Market
Beverages
Sparkling Juice Drinks Market
Beverages
Premium Water Market
Beverages
Europe Bottled Water Processing Market
Beverages
Bottled Water Processing Market
Beverages
Indonesia Bottled Water Market
Beverages
India Cafes & Bars Market
Beverages
Packaged Turmeric-Based Beverage Market
Beverages
Reconstituted Juice Market