
 Starch-Derived Fiber Market | 2026-2036
Starch-Derived Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Starch-Derived Fiber Market Analytics
Pharmaceutical companies are unwinding legacy reliance on synthetic excipients and redirecting procurement toward plant-based soluble fiber alternatives. Cargill Incorporated leverages backward integration into corn wet milling to secure raw material throughput across North American facilities. Ingredion Incorporated anchors its position through R&D intensity in resistant starch modification for glycemic control applications. Roquette Frères dominates European pharmaceutical-grade supply with specialized pea and wheat starch fractionation capabilities.
Starch-derived fiber encompasses carbohydrate polymers extracted from cereal, legume, or tuber sources through enzymatic or physical processing, yielding fractions with beta-glucan, amylose, or retrograded starch contents exceeding established dietary fiber thresholds. These materials function as bulking agents, prebiotic substrates, or viscosity modifiers in formulated products. Soluble fiber commands premium positioning in clinical nutrition and diabetes management formulations where viscosity and fermentability parameters determine reimbursement eligibility. Resistant starch competes on cost efficiency in large-scale bakery and extruded snack applications, though margin pools concentrate in pharmaceutical-grade resistant starch with documented clinical outcomes. Modified starch occupies a mature trajectory in conventional food processing, with differentiation shifting toward clean-label positioning and organic certification tiers.
FDA dietary fiber definition updates and EFSA health claim authorization processes shape product development roadmaps and market access timelines for novel starch fractions. REACH chemical registration requirements and EU MDR medical device regulations impose compliance burdens on suppliers targeting pharmaceutical and clinical nutrition channels. Stakeholders must monitor evolving prebiotic qualification criteria across FDA, EFSA, and Health Canada frameworks, as these determinations will unlock or constrain health claim substantiation investments and reformulation commitments.
Market Dynamics
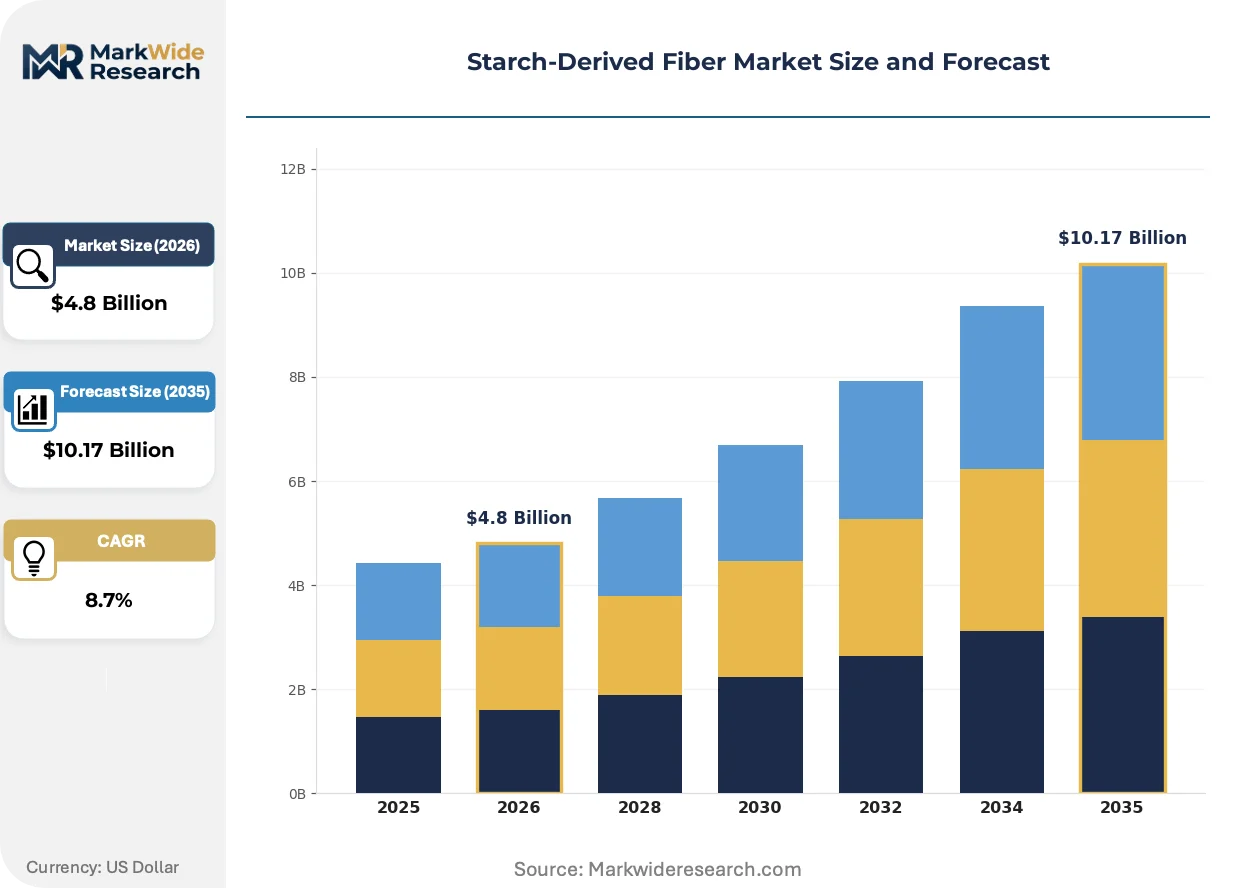
Pharmaceutical-grade resistant starch procurement is concentrating around wet-milling clusters with validated clinical documentation, as FDA dietary fiber definition updates force reformulation roadmaps and EFSA health claim processes extend market access timelines.
Growth Catalysts
- Controlled-Release Formulation Demand:Pharmaceutical manufacturers are expanding procurement of resistant starch grades for tablet matrix systems and colon-targeted delivery mechanisms.
- REACH Chemical Registration:ECHA compliance frameworks for novel starch fractions are unlocking pharmaceutical channel access for suppliers with pre-registered polymer modifications.
- Rotterdam Processing Clusters:Integrated maize-wheat fractionation infrastructure near Dutch port facilities is reducing logistics costs for clinical nutrition ingredient supply.
Market Restraints
- Corn Wet-Milling Input Volatility:Maize price sensitivity and energy intensity of steeping operations compress margins for unintegrated processors.
- EU F-Gas Regulation Compliance:Wet-processing facility emissions standards in Belgium and Germany are forcing capital upgrades or production rationalization.
- Synthetic Excipient Substitution Threat:Hydroxypropyl methylcellulose and polyvinylpyrrolidone retain cost advantages in immediate-release oral solid dosage forms.
Strategic Opportunities
- Prebiotic Qualification Pathways:Health Canada and FDA converging frameworks for fermentable fiber substantiation create first-mover advantages for documented resistant starch clinical trials.
- Pea Starch Fractionation:Legume-derived amylose concentrates offer non-GMO positioning and allergen-free claims for pediatric and clean-label nutrition applications.
- Direct-to-Formulator Digital Channels:B2B ingredient platforms are disintermediating traditional distributor networks for pharmaceutical and clinical nutrition procurement.
Industry Challenges
- Modified Starch IP Licensing Complexity:Enzymatic treatment patents and retrogradation process know-how create negotiation friction for new market entrants.
- Dual Certification Timeline Compression:Simultaneous EU MDR medical device and EFSA novel food authorization processes strain regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Starch-Derived Fiber Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soluble Fiber, Insoluble Fiber, Resistant Starch, Modified Starch Application: Food & Beverage, Pharmaceuticals, Nutraceuticals, Animal Feed End User: Food Manufacturers, Dietary Supplement Providers, Pharmaceutical Companies, Animal Nutritionists Distribution Channel: Online Retailers, Grocery Stores, Health Food Shops, Wholesalers |
| Companies Covered | Cargill Incorporated, Ingredion Incorporated, Archer Daniels Midland, Ixtlera, BENEO, Roquette Frères, AGRANA Beteiligungs-AG, Alliance Grain Traders, Dadtco Phil Africa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Starch-Derived Fiber Market Evolving Landscape
Enzymatic modification technologies and clinical documentation requirements are splitting competitive positioning between commodity-resistant starch and premium pharmaceutical grades. Formulation science advances are reshaping where value accumulates across the supply chain.
Resistant starch modification technology is bifurcating between cost-optimized bakery applications and clinical-grade fractions with documented glycemic response data. Pharmaceutical formulators are adopting high-amylose maize starches with proven colon fermentation profiles at accelerating pace. This technical split is compressing margin pools in conventional food processing while concentrating value capture in certified pharmaceutical supply tiers.
EFSA health claim authorization processes are extending development timelines for novel starch-derived fiber submissions. The industrial consequence is delayed market access for innovative fractions and accelerated investment in legacy ingredient repositioning. Soluble fiber segments targeting diabetes management reimbursement eligibility are most affected, with suppliers prioritizing existing authorized health claims over novel substantiation pathways.
Buyer concentration among multinational pharmaceutical and clinical nutrition formulators is compressing supplier negotiation leverage. Direct strategic sourcing agreements with wet-milling operators are displacing traditional ingredient distributor relationships. This procurement restructuring is most visible in the Netherlands and Germany, where integrated processors are capturing volume commitments through backward integration into crop origination.
Starch-Derived Fiber Market Segmentation
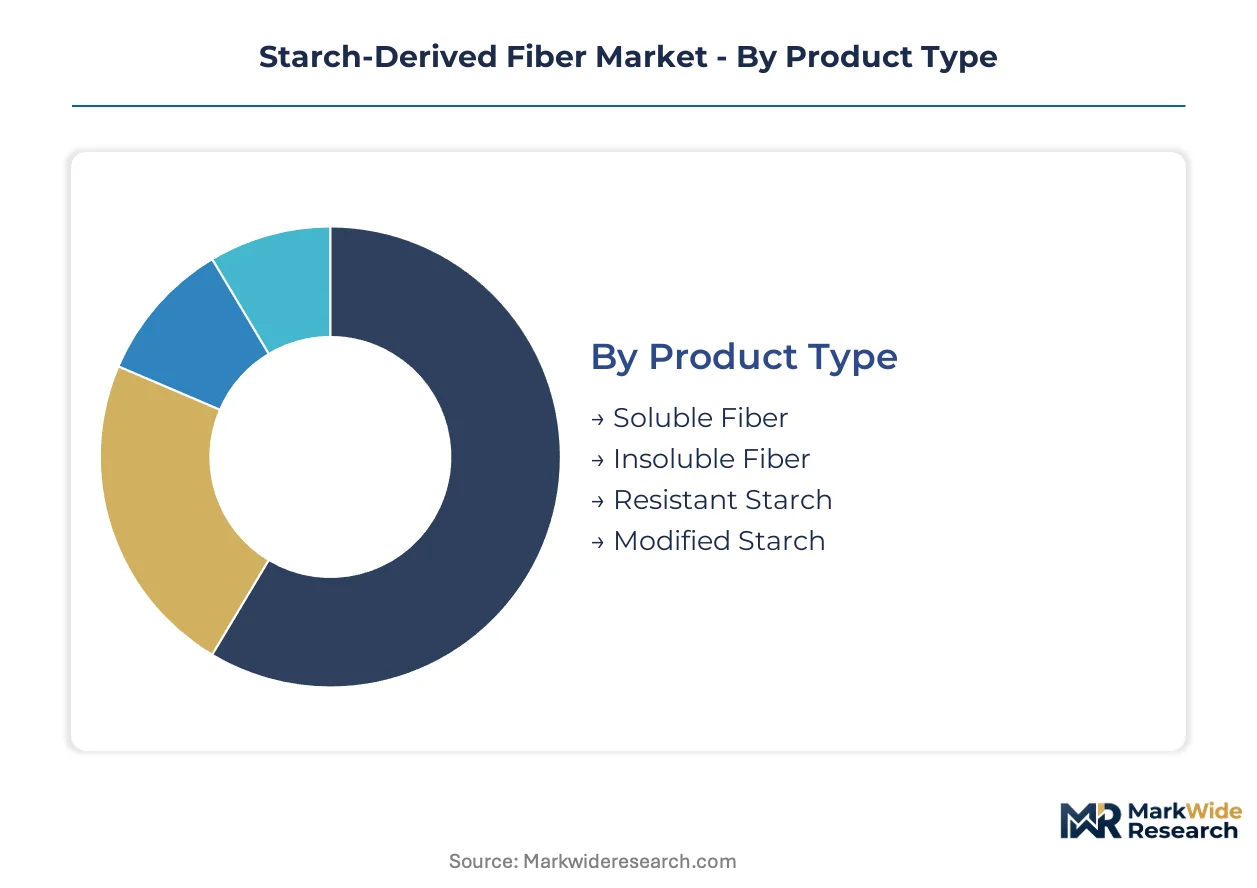
Starch-derived fiber markets fragment across functional chemistry, regulatory pathway, and customer procurement sophistication. Margin capture concentrates where clinical documentation meets controlled-release pharmaceutical specifications, while commodity applications compete on wet-milling scale and agricultural input costs.
Product Type:
Margin pools concentrate in pharmaceutical-grade resistant starch with validated clinical outcomes, while soluble fiber commands premium positioning in diabetes management reimbursement pathways.
- Soluble Fiber:Beta-glucan and arabinoxylan concentrates extracted through enzymatic hydrolysis achieve viscosity thresholds required for glycemic control health claims. Demand clusters in clinical nutrition formulations seeking FDA dietary fiber definition compliance and EFSA Article 13.5 authorization, though reimbursement eligibility timelines extend development cycles.
- Resistant Starch:High-amylose maize and retrograded wheat fractions with documented colon fermentation profiles anchor controlled-release tablet matrices and prebiotic positioning. Pharmaceutical procurement is accelerating around Rotterdam and German wet-milling clusters with integrated clinical trial documentation, displacing synthetic excipient reliance.
- Insoluble Fiber:Retrograded starch and cellulose-rich cereal fractions function as bulking agents in reduced-calorie bakery applications. Cost-sensitive food manufacturers prioritize this grade for clean-label fiber fortification without viscosity modification requirements.
- Modified Starch:Enzymatically or physically treated starches occupy mature trajectories in conventional food processing. Differentiation has shifted toward organic certification tiers and clean-label positioning as commodity margins compress.
The dominant share belongs to Resistant Starch, while Soluble Fiber is gaining share fastest through reimbursement-linked clinical nutrition expansion.
Application:
Application segmentation reflects divergent regulatory burden and documentation requirements, with pharmaceutical channels demanding multi-year substantiation investments that lock out unintegrated suppliers.
- Food & Beverage:Bakery, extruded snacks, and dairy applications consume volume-resistant starch for texture modification and fiber fortification. Cost efficiency drives procurement toward integrated wet-milling operations with captive corn origination, particularly across North American facilities.
- Pharmaceuticals:Tablet matrix systems and colon-targeted delivery mechanisms require pharmaceutical-grade resistant starch with batch-specific fermentation documentation. FDA dietary fiber definition updates and EU MDR compliance are extending supplier qualification timelines and concentrating procurement around pre-registered polymer modifications.
- Nutraceuticals:Prebiotic supplements and diabetes management formulations prioritize soluble fiber with established health claims. EFSA authorization processes favor legacy ingredient repositioning over novel fraction substantiation, compressing innovation returns.
- Animal Feed:Digestive health and growth promotion applications in poultry and swine operations utilize cost-optimized resistant starch grades. Price sensitivity limits penetration of clinically documented fractions in this channel.
Food & Beverage retains volume leadership, though Pharmaceuticals is climbing the fastest as controlled-release formulation demand accelerates.
End User:
Customer type segmentation reveals procurement restructuring, with direct strategic sourcing agreements displacing traditional distributor relationships among multinational formulators.
- Pharmaceutical Companies:Multinational oral solid dosage manufacturers are consolidating procurement around wet-milling operators with validated clinical documentation. REACH pre-registration and EU MDR compliance have become non-negotiable qualification criteria, compressing viable supplier pools.
- Dietary Supplement Providers:Prebiotic and glycemic control supplement brands prioritize EFSA-authorized health claims over novel fraction innovation. Regulatory affairs capacity constraints favor established soluble fiber suppliers with existing substantiation packages.
- Food Manufacturers:Large-scale bakery and snack producers negotiate volume commitments with backward-integrated processors. Clean-label positioning and organic certification tiers increasingly determine supplier selection beyond functional performance.
- Animal Nutritionists:Feed compounders and integrators specify resistant starch for gut health applications in monogastric species. Cost optimization dominates procurement, limiting adoption of premium-grade fractions.
Pharmaceutical Companies command the steepest margin premiums, while Dietary Supplement Providers are expanding procurement fastest through direct-to-formulator digital channels.
Distribution Channel:
Channel segmentation tracks disintermediation pressure, with B2B ingredient platforms eroding traditional distributor leverage in pharmaceutical and clinical nutrition procurement.
- Wholesalers:Traditional ingredient distributors retain relevance in mid-scale food manufacturing and regional animal feed supply. Consolidation among multinational formulators is compressing negotiation leverage and margin capture.
- Online Retailers:B2B ingredient platforms are capturing pharmaceutical and nutraceutical procurement through technical documentation transparency and direct supplier connectivity. Rotterdam-based processors have established dedicated digital channels for clinical nutrition customers.
- Health Food Shops:Specialty retail channels serve small-scale dietary supplement brands and clean-label food startups. Limited volume scale constrains supplier engagement and technical support allocation.
- Grocery Stores:Mass retail procurement of finished consumer products containing starch-derived fiber remains indirect, with formulation decisions upstream at food manufacturer level.
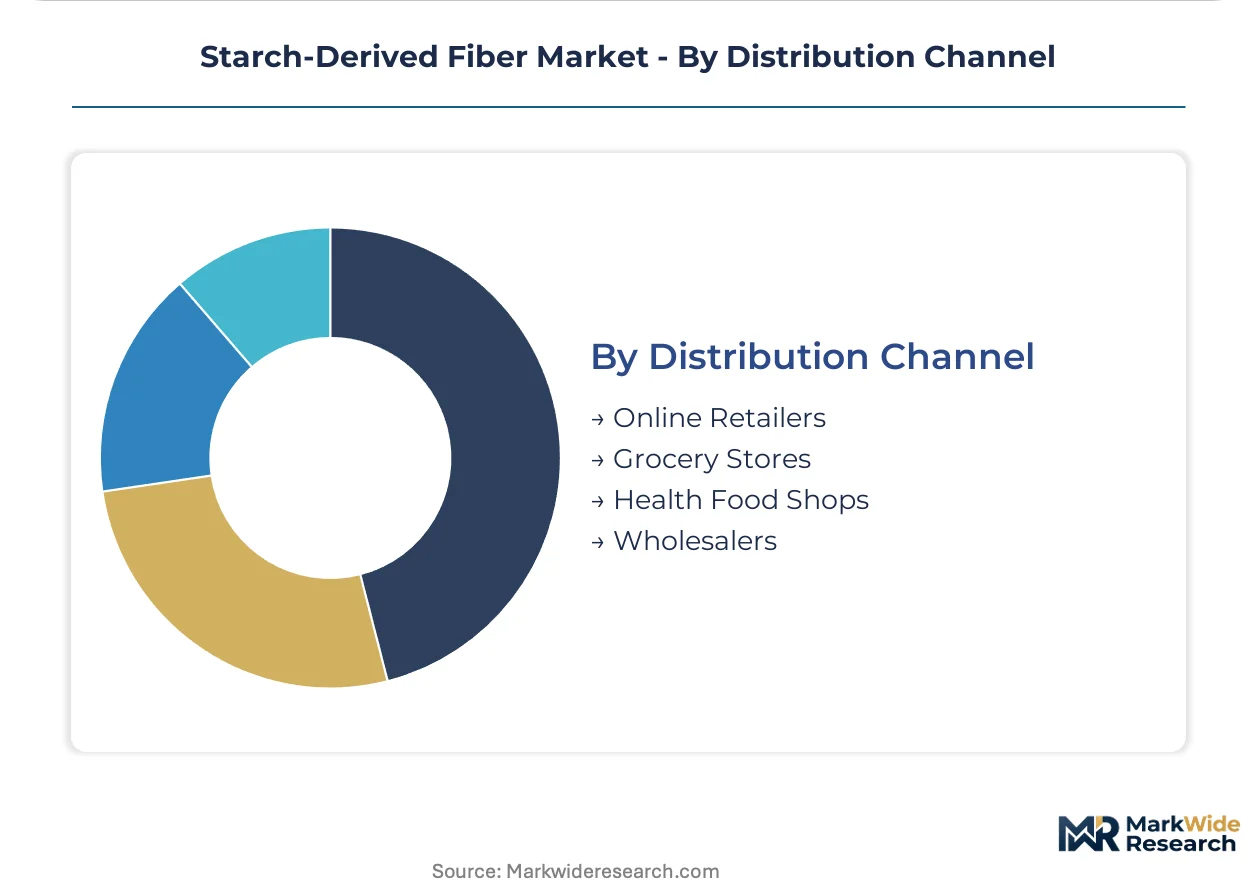
Wholesalers retain the largest transaction volume, though Online Retailers are expanding fastest through B2B platform disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's integrated bulk handling infrastructure underwrites European starch-derived fiber supply security, connecting North American maize shipments to wet-milling clusters in the Netherlands and Germany.
United States
Corn wet-milling capacity in Iowa and Illinois supplies pharmaceutical-grade resistant starch to domestic tablet manufacturers. FDA dietary fiber definition updates are forcing reformulation roadmaps among oral solid dosage producers. Cargill's backward integration into captive corn origination secures raw material throughput across Midwest processing facilities.
Netherlands
Rotterdam-based maize-wheat fractionation clusters serve clinical nutrition formulators seeking EFSA-authorized health claims. EU Green Deal emissions standards are accelerating capital upgrades at wet-processing facilities near the port. Roquette Frères and BENEO operate integrated supply chains linking crop origination to pharmaceutical-grade starch isolation.
Germany
Pharmaceutical procurement concentrates around specialized pea and wheat starch fractionators in North Rhine-Westphalia. EU F-Gas Regulation compliance is forcing production rationalization at legacy wet-milling sites. German processors are capturing volume commitments through direct strategic sourcing agreements with multinational formulators.
Belgium
Clinical nutrition ingredient demand drives resistant starch imports through Antwerp port infrastructure. ECHA REACH pre-registration requirements are compressing viable supplier pools for pharmaceutical channel access. Belgian wet-processing facilities face emissions compliance deadlines under tightening EU environmental standards.
India
Cost-optimized resistant starch production serves regional bakery and extruded snack manufacturers. FSSAI regulatory frameworks are evolving toward alignment with international dietary fiber definitions. Gujarat and Maharashtra processing hubs are expanding fractionation capacity for export-oriented pharmaceutical ingredient supply.
Starch-Derived Fiber Market Competitive Landscape
Concentration sits with backward-integrated agricultural processors possessing captive crop origination and clinical documentation capabilities. The competitive structure divides between multinational wet-milling operators with pharmaceutical-grade certification and regional specialists competing on cost efficiency. Three archetypes dominate: integrated agribusiness conglomerates, European specialty starch fractionators, and emerging legume-derived fiber innovators. Capacity expansion and strategic partnerships represent the dominant competitive moves, with processors securing volume commitments through direct formulator relationships.
Within the integrated agribusiness tier, Cargill Incorporated and Ingredion Incorporated exemplify scale-driven positioning through North American corn wet-milling infrastructure. Roquette Frères occupies a position among European specialty fractionators leveraging Rotterdam port access for clinical nutrition supply. These three anchors represent divergent strategic postures: captive agricultural input control versus pharmaceutical-grade certification depth versus integrated port-proximate processing clusters.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Ingredion Incorporated |
| Archer Daniels Midland |
| Ixtlera |
| BENEO |
| Roquette Frères |
| AGRANA Beteiligungs-AG |
| Alliance Grain Traders |
| Dadtco Phil Africa |
| Others |
Value Network & Pricing Analysis
Corn wet-milling capacity utilization above 85% at Iowa and Illinois facilities compresses margin pools for unintegrated processors while anchoring price floors through captive origination economics. Rotterdam port-proximate clusters leverage bulk handling scale to undercut inland European competitors on delivered cost to pharmaceutical formulators.
Pricing Analysis
Volume-discount tiering separates pharmaceutical-grade resistant starch with EFSA-authorized health claims from commodity bakery grades and economy animal feed fractions. Price differentiation rests on certification depth—REACH pre-registration and EU MDR compliance command 40-60% premiums over standard food-grade material. Pricing pressure stems from synthetic excipient substitution in immediate-release tablet formulations, where hydroxypropyl methylcellulose retains cost advantages. Animal feed compounders exhibit highest price sensitivity, while multinational pharmaceutical manufacturers prioritize batch documentation over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate pharmaceutical procurement, with Rotterdam and North Rhine-Westphalia processors maintaining 15-20 day safety stocks against maize shipment delays. Geographic supply concentrates in the United States, the Netherlands, and Germany, where integrated wet-milling infrastructure feeds from North American maize and regional wheat origination. Raw material dependencies center on high-amylose maize cultivars, enzymatic processing agents, and pharmaceutical-grade packaging materials. Single-source vulnerability runs through Rotterdam port bulk handling, where congestion propagates through European clinical nutrition supply. Distribution runs through direct strategic sourcing agreements displacing traditional wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Starch-derived fiber markets are recovering from input cost cyclicality as maize prices normalize and energy intensity premiums compress. Pharmaceutical procurement acceleration provides the cyclical uplift, with controlled-release formulation demand expanding at double-digit rates.
For Market Incumbents: Shield margin pools through backward integration into high-amylose maize origination and enzymatic modification IP licensing. Synthetic excipient substitution in immediate-release tablets threatens volume in commodity grades; prioritize REACH pre-registration investments to lock pharmaceutical channel access against emerging legume-fraction competitors. For New Entrants and Emerging Players: Lead with pea starch fractionation targeting pediatric nutrition and allergen-free positioning where Roquette Frères and BENEO maintain limited penetration. Direct-to-formulator digital channels offer disintermediation leverage against established distributor relationships in clinical nutrition procurement. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors European specialty fractionators with Rotterdam port access and existing EFSA health claim portfolios. Five-to-ten year viability hinges on prebiotic qualification convergence across FDA, EFSA, and Health Canada frameworks. Watch for fermentation documentation standardization as the inflection signal separating pharmaceutical-grade suppliers from commodity processors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Amylose Maize Origination | Cargill's captive corn supply secures raw material throughput against price volatility at Iowa wet-milling facilities. |
| REACH Pre-Registration for Novel Starch Fractions | ECHA compliance unlocks pharmaceutical channel access for suppliers targeting EU MDR medical device regulations. |
| Direct-to-Formulator Digital Platform Launch | B2B ingredient transparency disintermediates traditional distributor networks for clinical nutrition procurement. |
| Pea Starch Fractionation Capacity Expansion | Legume-derived amylose concentrates capture non-GMO and allergen-free positioning in pediatric applications. |
| Clinical Trial Documentation Investment | Validated colon fermentation profiles differentiate pharmaceutical-grade resistant starch from commodity bakery grades. |
Research Methodology
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings on starch-derived fiber procurement patterns. Conversations with pharmaceutical formulation scientists, wet-milling plant managers, clinical nutrition procurement leads, and regulatory affairs directors at EFSA and FDA were synthesized with trade data from customs authorities, EU REACH registration databases, and SEC 10-K disclosures from listed agribusiness conglomerates. Bottom-up volume modeling from individual facility throughput was triangulated against top-down market sizing from ingredient distributor channel checks.
Sensitivity analysis across maize price scenarios, energy cost assumptions, and pharmaceutical procurement elasticity informs the projection framework. Segmentation dimensions modeled include product chemistry (soluble fiber, resistant starch, insoluble fiber, modified starch), application channel (food and beverage, pharmaceuticals, nutraceuticals, animal feed), and customer procurement sophistication (multinational formulator, regional manufacturer, feed compounder). CAGRs were derived from regression analysis of historical volume relationships to pharmaceutical tablet production and clinical nutrition shipment data. Forecast inputs incorporate EFSA health claim authorization timelines and FDA dietary fiber definition compliance deadlines.
The analysis sits within stated boundaries; outcomes outside sustained pharmaceutical procurement acceleration or regulatory harmonization across FDA, EFSA, and Health Canada would require recalibration. Forecasts reflect assumptions on wet-milling capacity expansion rates, maize cultivar availability, and emissions compliance costs under EU Green Deal implementation. Revision becomes warranted when prebiotic qualification criteria divergence crosses thresholds that fragment health claim substantiation investments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Sesame Seed Extract Market
Ingredients
Avocado Powder Market
Ingredients
North America Dairy Ingredients Market
Ingredients
Europe Fruit and Vegetable Ingredients Market
Ingredients
Industrial Starch Market
Ingredients
Chickpea Flour Market
Ingredients
Encapsulated Salt Market
Ingredients
High Oleic Oil Market
Ingredients
Bakery Ingredients Market
Ingredients
Pea Starch Market
Ingredients
USA Yeast Extracts Market
Ingredients
Soy Derivatives Market
Ingredients
Oat Ingredients Market
Ingredients
Baobab Powder Market
Ingredients
Wheat Starch Market
Ingredients
Starches/Glucose Market