
 Global Alternative Protein Market | 2026-2036
Global Alternative Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Global Alternative Protein Market Analysis
Foodservice operators is rotating toward alternative proteins as quick-service chains and institutional caterers rewrite procurement specifications to reduce Scope 3 emissions. Impossible Foods Inc. anchors this shift through its heme-based platform that replicates meat sensory profiles at commercial scale. Roquette Frères dominates pea protein isolate supply through backward integration into European and North American crop origination. ADM competes across multiple feedstocks, leveraging its oilseed processing infrastructure to extract soy and canola proteins for ingredient customers.
Alternative proteins comprise non-animal-derived nutritional sources manufactured through mechanical extraction, fermentation, or cell cultivation to deliver amino acid profiles comparable to conventional meat, dairy, or egg proteins. Plant-based proteins typically require 60-80% less land and water inputs than animal agriculture per kilogram of protein output, positioning them as functional ingredients for reformulated foods. Mycoprotein fermentation occupies the fastest-growing margin pool within the product type taxonomy, as precision bioreactor control yields texture properties that command premium positioning in ready-to-eat formats. Powder formulations lead the form dimension by volume, though ingredients for further processing capture disproportionate value through technical service relationships with food manufacturers.
The FDA oversees novel protein safety assessments through its Generally Recognized as Safe notification pathway, while the EU EFSA mandates pre-market authorization for insect proteins and cultured meat under novel food regulations. REACH compliance in Europe further constrains extraction solvent residues and processing aid chemistry, elevating compliance costs for imported concentrates. Stakeholders must monitor divergence between the USDA's bioengineered food disclosure standard and the EU's stricter labeling thresholds for precision fermentation products, as this regulatory gap will determine where capacity investments flow and which technologies achieve transatlantic scale.
Market Dynamics
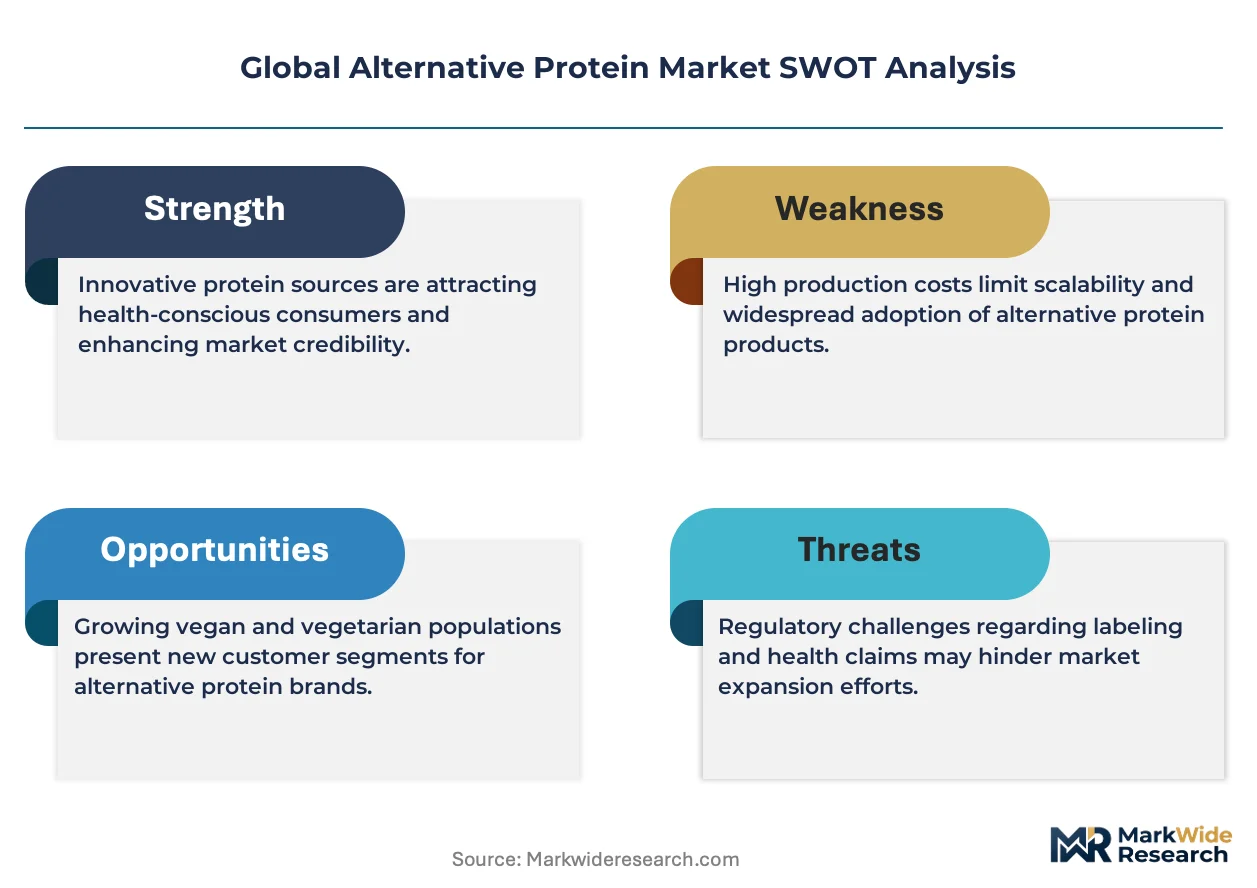
Fermentation-derived protein platforms are compressing capital cycles for novel ingredient commercialization, forcing legacy extraction infrastructure into accelerated retrofit decisions.
Growth Catalysts
- EU Green Deal Farm to Fork mandates:Binding sustainability benchmarks for protein procurement across member state institutional catering contracts are redirecting volume toward certified alternative suppliers.
- Precision bioreactor control:Automated mycoprotein fermentation systems now achieve texture parity with animal muscle fibers at industrial scale, unlocking ready-to-eat premium positioning.
- German food technology clusters:Berlin and Munich host concentrated pilot-to-commercial facilities that reduce scale-up timelines for fermentation startups seeking technical validation.
Market Restraints
- Pea protein isolate concentration:Roquette Frères and a handful of processors control European and North American crop origination, creating single-source vulnerability for formulators.
- EFSA novel food authorization timelines:Pre-market approval processes for insect proteins and cultured meat extend 18-24 months, freezing product launch schedules.
- Conventional dairy price volatility:Whey and casein spot markets periodically compress alternative protein price premiums, eroding reformulation incentives for cost-sensitive manufacturers.
Strategic Opportunities
- India FSSAI regulatory pathway development:Emerging clarity on plant protein and fermentation ingredient standards creates first-mover positioning for supply chain localization.
- Quick-service chain Scope 3 commitments:Hard procurement targets for emissions reduction are rewriting ingredient specifications, opening technical partnership slots for novel protein suppliers.
- Hybrid meat-alternative formulations:Blending fermentation-derived proteins with plant isolates addresses cost and sensory gaps simultaneously, creating intermediate price-performance tiers.
Industry Challenges
- Bioprocess engineering talent scarcity:Industrial-scale fermentation operation requires hybrid skill sets spanning metabolic engineering and food safety compliance that outstrip current training pipeline output.
- USDA-EU labeling divergence:Misaligned thresholds for precision fermentation product disclosure force dual formulation strategies, fragmenting production scale economics.
- Downstream processing capex intensity:Chromatography and membrane filtration systems for protein purification demand dedicated capital commitments that strain venture-backed balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Alternative Protein Market |
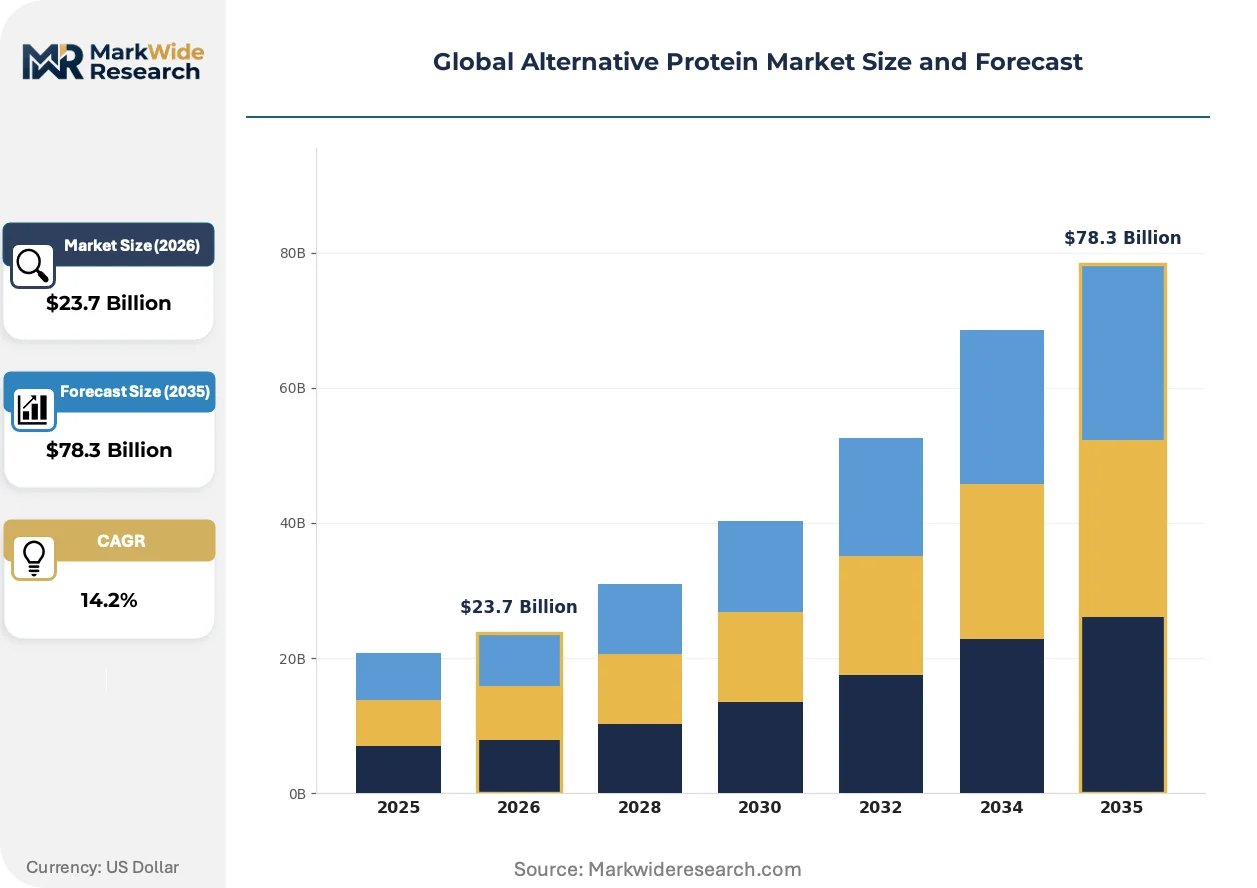
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $78.3 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plant-based, Mycoprotein, Insect protein, Cultured meat End User: Food industry, Nutraceuticals, Animal feed, Sports nutrition Form: Powder, Ready-to-eat, Ingredients, Snacks Distribution Channel: Online, Offline, Supermarkets, Health food stores |
| Companies Covered | ADM, Cargill Inc., International Flavors & Fragrances Inc., Kerry Group, Ingredion Inc., Tate & Lyle PLC, Impossible Foods Inc., Roquette Frères, DSM Firmenich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Alternative Protein Market Emerging Trajectories
Biomanufacturing platforms are collapsing traditional boundaries between ingredient production and finished food formulation, enabling direct-to-brand supply relationships that bypass conventional ingredient trading structures.
Precision fermentation for dairy-identical proteins is decomposing the whey and casein supply chain by enabling functional equivalence without lactose or allergen carryover. Sports nutrition brands in North America and Western Europe are accelerating adoption, locking in multi-year offtake agreements ahead of capacity ramp. This technology is compressing margin pools for commodity dairy processors while creating captive supply advantages for integrated biomanufacturers.
REACH compliance enforcement in Europe is tightening residual solvent limits for protein extraction processes, elevating compliance costs for imported concentrates and redirecting sourcing toward EU-verified suppliers. The industrial consequence is accelerated investment in supercritical CO2 and aqueous extraction systems that eliminate petrochemical processing aids. Ingredient customers in Germany and France are now mandating REACH-compliant certificates as standard procurement documentation.
Foodservice operators are consolidating alternative protein procurement through direct technical partnerships rather than distributor-mediated spot purchasing. Large institutional caterers in the United Kingdom and Netherlands are embedding food scientists within supplier development programs, co-developing application-specific protein systems. This behavior compresses traditional ingredient broker margins while rewarding suppliers with integrated formulation capabilities and rapid pilot-scale iteration capacity.
Global Alternative Protein Market Segmentation
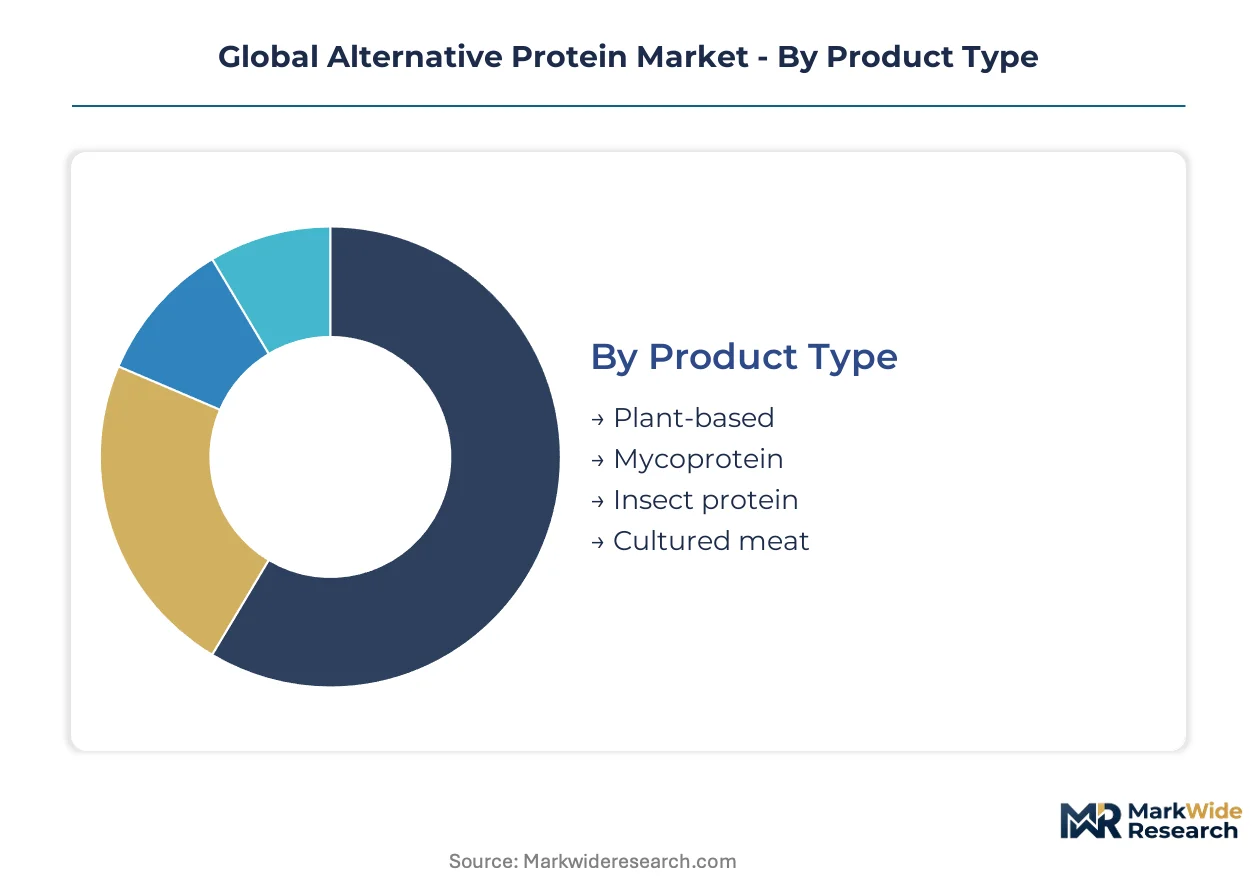
Alternative protein segmentation reveals where value capture concentrates across production technologies and go-to-market pathways. Manufacturers configure product portfolios around margin architecture rather than volume alone.
Product Type:
Margin pools concentrate in fermentation platforms where bioreactor control yields texture premiums that plant extraction cannot replicate.
- Plant-based:Mechanical and aqueous extraction of soy, pea, and canola proteins delivers functional isolates for meat and dairy analogues. Demand clusters in North American and European retail channels where sustainability claims drive shelf placement negotiations with Kroger, Tesco, and Carrefour buyers.
- Mycoprotein:Fungal biomass cultivated in submerged fermentation achieves fibrous structures that mimic animal muscle tissue without texturizing additives. German and Dutch foodservice operators are locking in multi-year supply contracts for mycoprotein-based ready meals as institutional catering contracts adopt EU Green Deal procurement standards.
- Insect protein:Black soldier fly and mealworm meals processed into defatted powders for aquaculture and pet nutrition applications.
- Cultured meat:Animal cell cultivation in bioreactors producing skeletal muscle tissue without slaughter; regulatory authorization timelines constrain commercial availability.
Plant-based holds installed capacity. Mycoprotein is rotating up the share rankings.
End User:
Application mix determines pricing power, with sports nutrition commanding formulation premiums that commodity animal feed cannot support.
- Food industry:Ingredient supply for meat alternatives, dairy analogues, and bakery applications where protein fortification replaces conventional binders and emulsifiers. Quick-service chains in the United States and United Kingdom are embedding alternative proteins into core menu items as Scope 3 emissions targets harden.
- Sports nutrition:Powder and ready-to-drink formulations targeting amino acid completeness and digestibility scores that match or exceed whey benchmarks. North American brands are accelerating precision fermentation of dairy-identical proteins to secure supply chains ahead of capacity constraints.
- Nutraceuticals:Capsule and tablet applications emphasizing protein bioavailability for aging populations and clinical nutrition protocols.
- Animal feed:Cost-competitive protein meals for aquaculture, poultry, and pet nutrition where amino acid density justifies inclusion rates.
Food industry maintains volume leadership. Sports nutrition is climbing the fastest as premium positioning accelerates.
Form:
Processing intensity creates margin stratification, with purified ingredients capturing value through technical service relationships that finished formats cannot replicate.
- Ingredients:Protein isolates, concentrates, and texturized vegetable proteins supplied to food manufacturers for further formulation. German and French procurement teams now mandate REACH-compliant extraction certificates, redirecting sourcing toward EU-verified suppliers with aqueous and supercritical CO2 processing capabilities.
- Powder:Bulk packaged proteins for beverage, bar, and supplement manufacturing where solubility and dispersibility specifications determine supplier selection.
- Ready-to-eat:Chilled and shelf-stable prepared meals where mycoprotein fermentation enables clean-label texture without methylcellulose or modified starch.
- Snacks:Extruded and baked protein-fortified formats targeting convenience consumption occasions.
Ingredients command technical premiums. Ready-to-eat is gaining share fastest through foodservice partnerships.
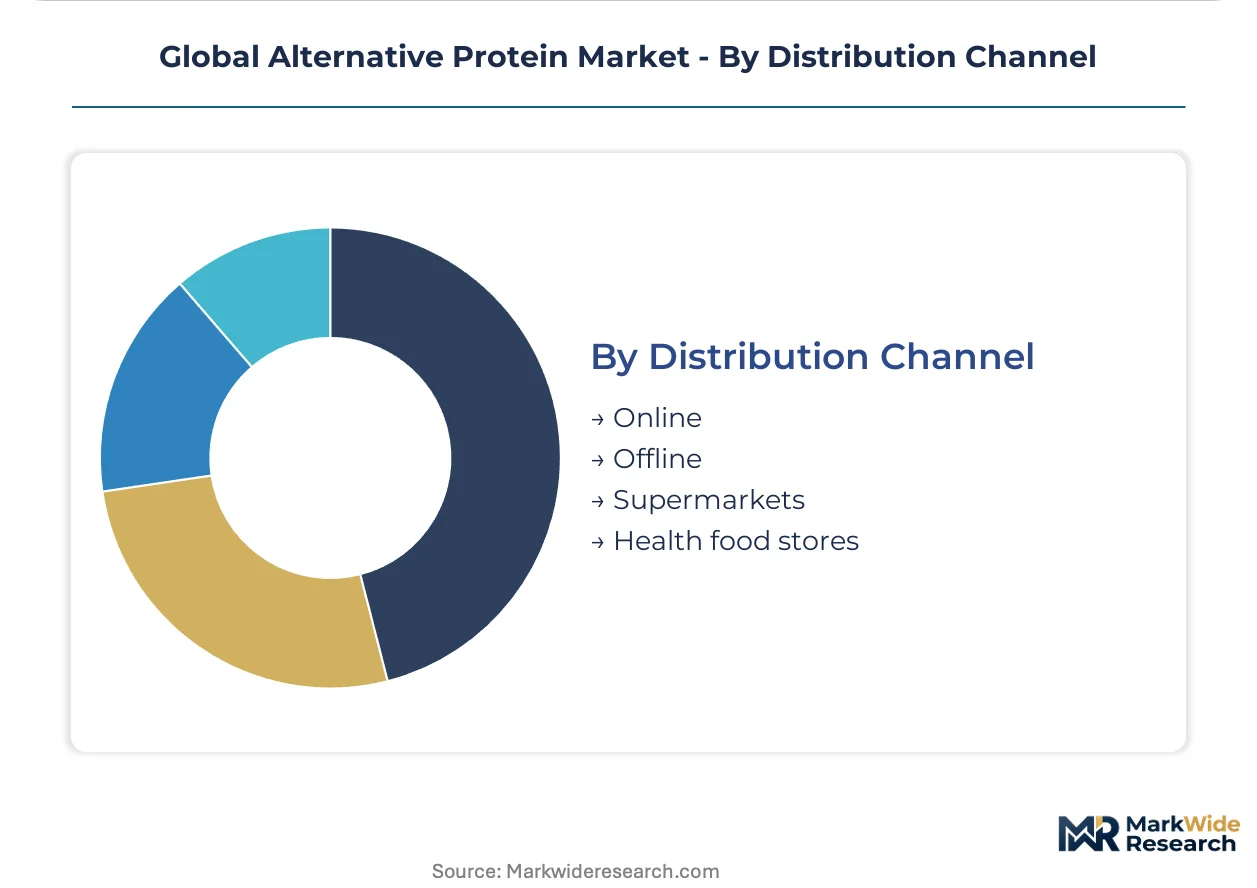
Distribution Channel:
Channel selection determines customer acquisition economics, with direct technical partnerships displacing distributor-mediated spot purchasing in institutional segments.
- Online:Direct-to-consumer and B2B platform sales enabling ingredient sampling, formulation support, and subscription replenishment for small and mid-sized manufacturers.
- Supermarkets:Mass retail placement for branded finished products where shelf space negotiations hinge on scan velocity and sustainability credentials.
- Offline:Traditional foodservice and industrial distributor networks for volume contract fulfillment.
- Health food stores:Specialty retail positioning for premium-priced organic and non-GMO certified protein products.
Supermarkets anchor volume throughput. Online is rotating up the share rankings as formulation services digitize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain infrastructure underwrites Europe's position as the primary consolidation point for alternative protein ingredient flows into food manufacturing networks.
United States
Sports nutrition brands and quick-service chains drive procurement volumes. The FDA's GRAS notification pathway governs novel protein safety assessments. Chicago and Minneapolis host concentrated oilseed processing infrastructure that supplies soy and canola protein isolates to North American formulators.
Germany
Institutional catering contracts under EU Green Deal procurement standards redirect volume toward certified alternative suppliers. EFSA novel food regulations mandate pre-market authorization for insect proteins and cultured meat. Berlin and Munich clusters accelerate pilot-to-commercial scale-up for fermentation-derived proteins.
Netherlands
Foodservice operators and ingredient traders concentrate demand for mycoprotein and plant-based isolates. REACH compliance enforcement tightens residual solvent limits for imported concentrates. Wageningen University's food technology corridor anchors R&D partnerships between startups and established processors.
India
Domestic food manufacturers and export-oriented ingredient suppliers expand capacity. FSSAI regulatory pathway development on plant protein and fermentation standards creates localization incentives. Maharashtra and Gujarat host emerging extrusion and isolation facilities serving South Asian and Middle Eastern markets.
United Kingdom
Large institutional caterers embed food scientists within supplier development programs. The Food Standards Agency applies novel food regulations aligned with EFSA frameworks. London and the Midlands concentrate co-manufacturing capacity for ready-to-eat alternative protein formats.
Global Alternative Protein Market Vendor Landscape
Concentration sits with diversified ingredient conglomerates and specialized fermentation platforms. Roquette Frères dominates European and North American pea protein origination through backward integration into crop supply. Three archetypes define competitive positioning: oilseed processors leveraging existing crushing infrastructure, precision fermentation specialists building captive biomanufacturing capacity, and hybrid meat-alternative brands integrating formulation with ingredient supply. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as players secure multi-year offtake agreements ahead of bioreactor ramp.
Within the diversified processor tier, ADM and Cargill Inc. represent scale-driven archetypes that compete across multiple feedstocks. Impossible Foods Inc. occupies a position exemplifying integrated brand-platform models that bypass conventional ingredient trading structures. Roquette Frères anchors the specialized isolate segment. These three entities collectively illustrate how competitive advantage flows from upstream control over crop origination, bioprocess engineering capabilities, or direct-to-foodservice technical relationships.
| Leading Market Players |
|---|
| ADM |
| Cargill Inc. |
| International Flavors & Fragrances Inc. |
| Kerry Group |
| Ingredion Inc. |
| Tate & Lyle PLC |
| Impossible Foods Inc. |
| Roquette Frères |
| DSM Firmenich |
| Others |
Supply Flow & Price Mechanics
REACH compliance enforcement gates both supply qualification and price differentiation simultaneously, as German and French procurement teams now mandate EU-verified extraction certificates that eliminate low-cost petrochemical-processed imports from consideration pools.
Pricing Analysis
Volume-discount tiering structures separate fermentation-derived mycoprotein premiums from commodity plant isolate benchmarks, with texture parity commanding three-to-five-fold spreads over mechanical extraction alternatives. Certification grade under REACH and organic non-GMO status drive secondary differentiation layers, while cost compression in pea protein isolates intensifies as Roquette Frères and ADM expand North American crushing capacity. Foodservice operators show least price sensitivity due to Scope 3 emissions procurement mandates, whereas animal feed formulators remain most exposed to whey spot market volatility.
Supply Chain Analysis
Strategic stockpile preferences dominate mycoprotein and precision fermentation inputs where bioreactor uptime depends on sterile media continuity, contrasting with just-in-time plant protein flows through Rotterdam cold chain consolidation. Supply concentrates in Germany, the Netherlands, and the United States, drawing from soy and pea origination in North America plus fungal biomass cultivation in European pilot-to-commercial clusters. Chromatography resins and bioreactor vessel fabrication create single-source vulnerability, while distribution runs through direct technical partnerships that displace traditional ingredient broker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among quick-service chains and institutional caterers with hard Scope 3 targets, fragmenting supplier margins as procurement teams embed food scientists within direct development programs.
For Market Incumbents: Compound formulation service capabilities to defend against precision fermentation specialists bypassing conventional ingredient trading structures. Lock multi-year offtake agreements with sports nutrition brands before dairy-identical protein capacity saturates North American premiums. Prioritize backward integration into European crop origination to offset Roquette Frères' origination control.
For New Entrants and Emerging Players: FSSAI regulatory fast-tracks in India create first-mover positioning for supply chain localization ahead of clarified plant protein and fermentation standards. Target aquaculture feed applications where insect protein faces lower novel food authorization barriers than human nutrition channels. Pursue hybrid meat-alternative formulations that blend fermentation-derived textures with plant isolate cost bases.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision fermentation sub-segments as chromatography and membrane filtration capex demands strain venture-backed balance sheets. Five-to-ten year viability favors integrated biomanufacturers with captive bioreactor capacity over pure-play extraction processors. Watch EFSA novel food authorization timelines as the signal—accelerated approvals would trigger capacity investment waves, while extended freezes would strand fermentation assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-year Offtake Agreement | Sports nutrition brands lock dairy-identical protein supply ahead of capacity constraints. |
| Backward Integration into Crop Origination | ADM and Cargill leverage oilseed crushing infrastructure to control isolate feedstock costs. |
| REACH-Compliant Extraction Certification | EU-verified suppliers capture procurement mandates from German and French food manufacturers. |
| Direct Technical Partnership | UK institutional caterers embed food scientists to co-develop application-specific protein systems. |
| Hybrid Formulation Development | Blending fermentation textures with plant isolates addresses cost and sensory gaps simultaneously. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fermentation platform engineers, procurement leads at quick-service chains, foodservice R&D directors, and regulatory affairs specialists navigating EFSA novel food pathways. Secondary validation drew from FDA GRAS notifications, EFSA scientific opinions, EU Green Deal procurement documentation, and trade flow data through Rotterdam port authorities. Bottom-up capacity assessments triangulated against top-down protein demand modeling across the analysis window.
Across the projection horizon, the analytical framework segmented volume and value outputs by production technology, end-use application, form factor, and distribution channel. CAGRs were derived from regression analysis against protein price spreads, regulatory authorization velocity, and foodservice procurement contract tenors. Fermentation scale-up timelines and REACH compliance cost curves served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of stable EU Green Deal procurement enforcement and no radical compression in conventional dairy spot markets; material deviation would warrant model refresh. Revision becomes warranted when EFSA novel food authorization timelines or FSSAI regulatory clarity crosses thresholds that alter capacity investment economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
North America Insect Protein Market
Alternative Food Sources
Africa Fat Replacers Market
Alternative Food Sources
Soy Leghemoglobin Market
Alternative Food Sources
Fat Replacers Market
Alternative Food Sources
Vegan Caviar Market
Alternative Food Sources
Food Cultures Market
Alternative Food Sources
Insect Protein Market
Alternative Food Sources
Edible Packaging Market
Alternative Food Sources
Corn-Based Protein Market
Alternative Food Sources
Vegan Eggs Market
Alternative Food Sources
Africa Protein Market
Alternative Food Sources
Algal Protein Market
Alternative Food Sources
Upcycled Food Products Market
Alternative Food Sources
Artificial Meat Market
Alternative Food Sources
North America Meal Products Replacement Market
Alternative Food Sources
Vegetable Waste Products Market