

PDO/PGI-Linked Mediterranean Ingredient Collections Market Size, Share, and Industry Trends Forecast 2026-2036
PDO/PGI-Linked Mediterranean Ingredient Collections Market Insights
Premium restaurant chains is bifurcating from mass-market foodservice as the dominant buyer archetype for certified Mediterranean ingredients. DSM-Firmenich leverages its extraction capabilities to supply standardized oleoresins from PDO olive varietals. Indena anchors its botanical sourcing network around Sicilian and Calabrian citrus terroirs with protected status. Euromed competes through vertical integration into Andalusian olive processing, controlling quality from harvest to concentrate.
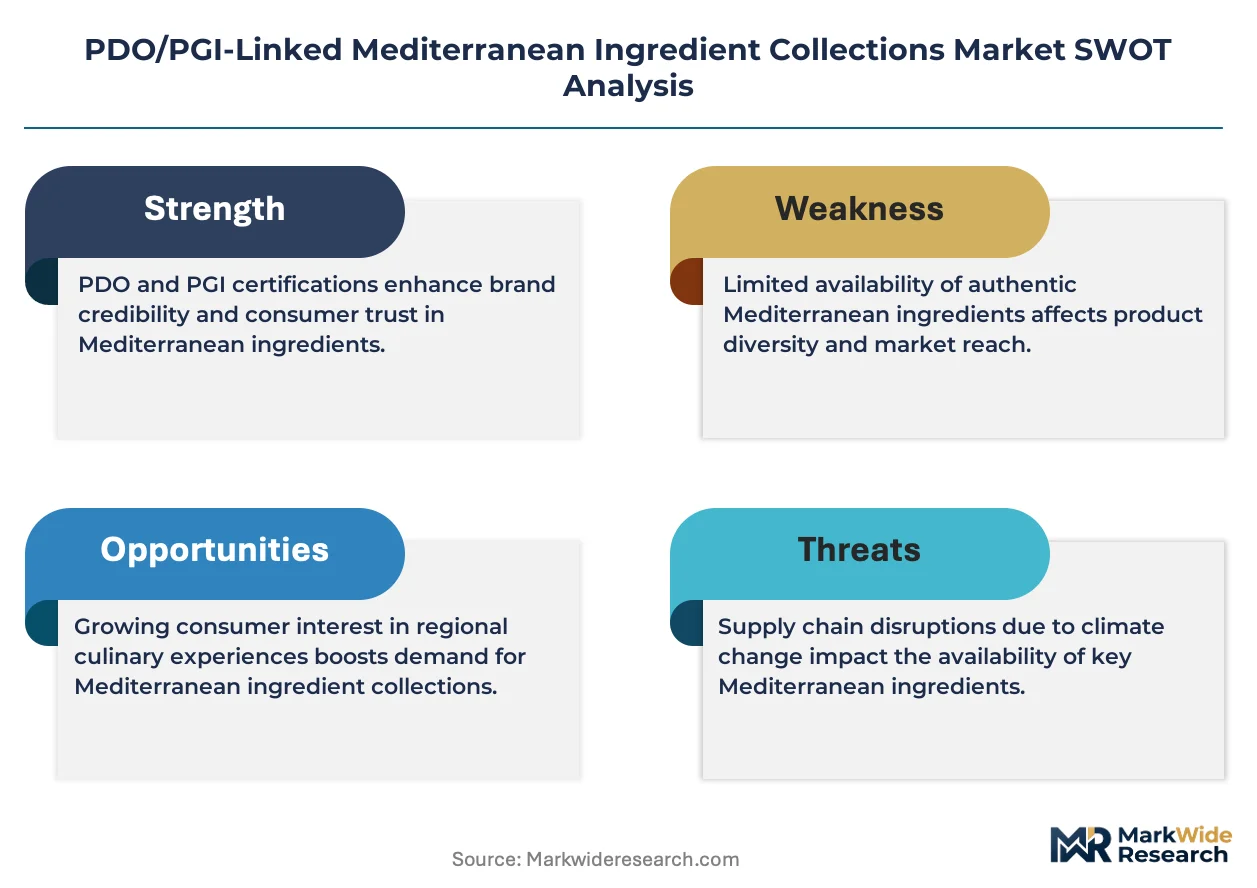
PDO/PGI-linked Mediterranean ingredient collections comprise geographically designated agricultural outputs and their derived extracts, governed by EU Regulation 1151/2012 and equivalent frameworks, with specifications mandating cultivar provenance, traditional processing methods, and chemical fingerprinting for authenticity verification; these collections serve commercial food manufacturing, premium culinary channels, and nutraceutical formulation where provenance commands measurable price premiums. Extra virgin olive oil dominates value pools due to entrenched health positioning and cosmetic dual-use applications, while cured meats and Mediterranean cheese capture margin through limited production volumes and seasonal scarcity. Specialty sauces and artisan bakery applications represent the fastest-expanding demand vector as clean-label formulation requirements intensify.
EU Geographical Indications Regulation enforcement through EFSA and member-state agricultural ministries defines compositional thresholds and traceability protocols that determine market access for labeled products. REACH compliance through ECHA additionally governs extract solvents and residue limits for ingredient derivatives entering cosmetic and pharmaceutical channels. Stakeholders must monitor evolving bilateral recognition agreements between the EU and non-European trade partners, as mutual GI protection clauses will determine competitive territory for established Mediterranean suppliers.
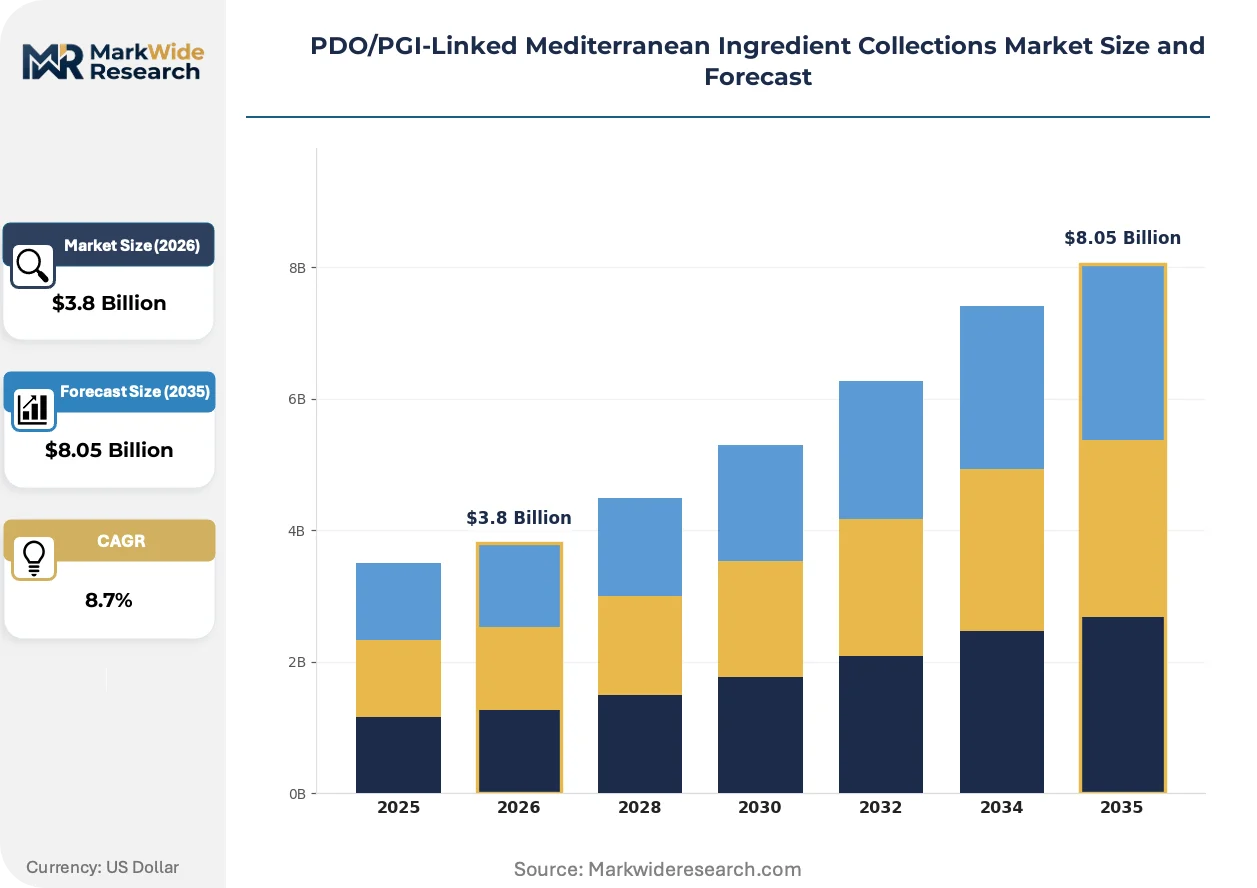
Market Dynamics
EU Geographical Indications Regulation enforcement is compressing market access windows for uncertified suppliers while concentrating procurement power among vertically integrated processors with in-house laboratory authentication capabilities.
Growth Catalysts
- EFSA traceability mandates:Tighter chemical fingerprinting requirements for PDO-labeled olive oils are accelerating investment in isotope-ratio mass spectrometry infrastructure across Italian and Spanish processing cooperatives.
- Clean-label formulation:Premium sauce manufacturers are substituting synthetic preservatives with PGI-certified citrus extracts and herb oleoresins to meet retailer ingredient blacklists.
- Cosmetic dual-use demand:Marseille and Barcelona-based formulators are expanding offtake of Sicilian citrus terpenes for fragrance and active botanical applications.
Market Restraints
- Input cost volatility:Adverse weather patterns in Andalusia and Calabria are compressing olive and citrus harvest yields, amplifying raw material price swings for concentrate processors.
- Supply concentration risk:Over half of certified Iberian ham curing capacity clusters in Extremadura and Salamanca provinces, creating geographic single-point vulnerability.
- Substitution threat:Non-PDO olive oils from Tunisia and Morocco are capturing mid-tier foodservice accounts through aggressive pricing and improved organoleptic profiles.
Strategic Opportunities
- Underpenetrated geography:Greek PDO cheese and honey designations remain underdeveloped in Northern European retail channels relative to Italian and Spanish equivalents.
- Regulatory tailwind:EU-China bilateral GI recognition agreements are opening protected status enforcement mechanisms for Mediterranean suppliers in premium Chinese urban markets.
- Distribution innovation:Direct-to-chef platforms in London, Paris, and Amsterdam are bypassing traditional wholesale tiers for time-sensitive cured meat and fresh cheese collections.
Industry Challenges
- Analytical talent scarcity:Shortage of technicians proficient in gas chromatography-isotope ratio mass spectrometry is extending authentication laboratory turnaround times.
- Certification timeline compression:EU member-state agricultural ministries are backlogging PDO application reviews, delaying new product launches by 18-24 months.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PDO/PGI-Linked Mediterranean Ingredient Collections Market Trends and Innovations
Authentication technology deployment and procurement model restructuring are reconfiguring competitive advantage around provenance verification speed and supply chain transparency depth.
Blockchain-enabled batch tracking is miniaturizing from enterprise ERP systems to cooperative-level implementations. Spanish olive oil cooperatives in Jaén and Córdoba provinces are piloting distributed ledger integration for real-time harvest-to-bottle provenance queries. This compression of verification infrastructure is lowering entry barriers for smaller PGI-designated producers to access premium retail channels previously gated by traceability audit costs.
REACH compliance through ECHA is tightening residue limits for solvent-extracted oleoresins entering cosmetic and pharmaceutical channels. The regulation mandates sub-ppm thresholds for hexane and acetone traces in botanical concentrates. Italian citrus processors in Sicily and Calabria are retrofitting extraction lines with supercritical CO2 systems to maintain EU market access for terpene-derived cosmetic actives.
Buyer concentration among specialty food distributors is consolidating procurement decisions into fewer hands with stricter certification requirements. Premium restaurant groups in Copenhagen, Milan, and San Sebastian are contracting directly with designated-origin consortia, disintermediating traditional import brokers. This channel shift is most visible in the cured meat segment, where whole-ham aging contracts now specify individual producer farms rather than regional pooling.
PDO/PGI-Linked Mediterranean Ingredient Collections Market Segmentation
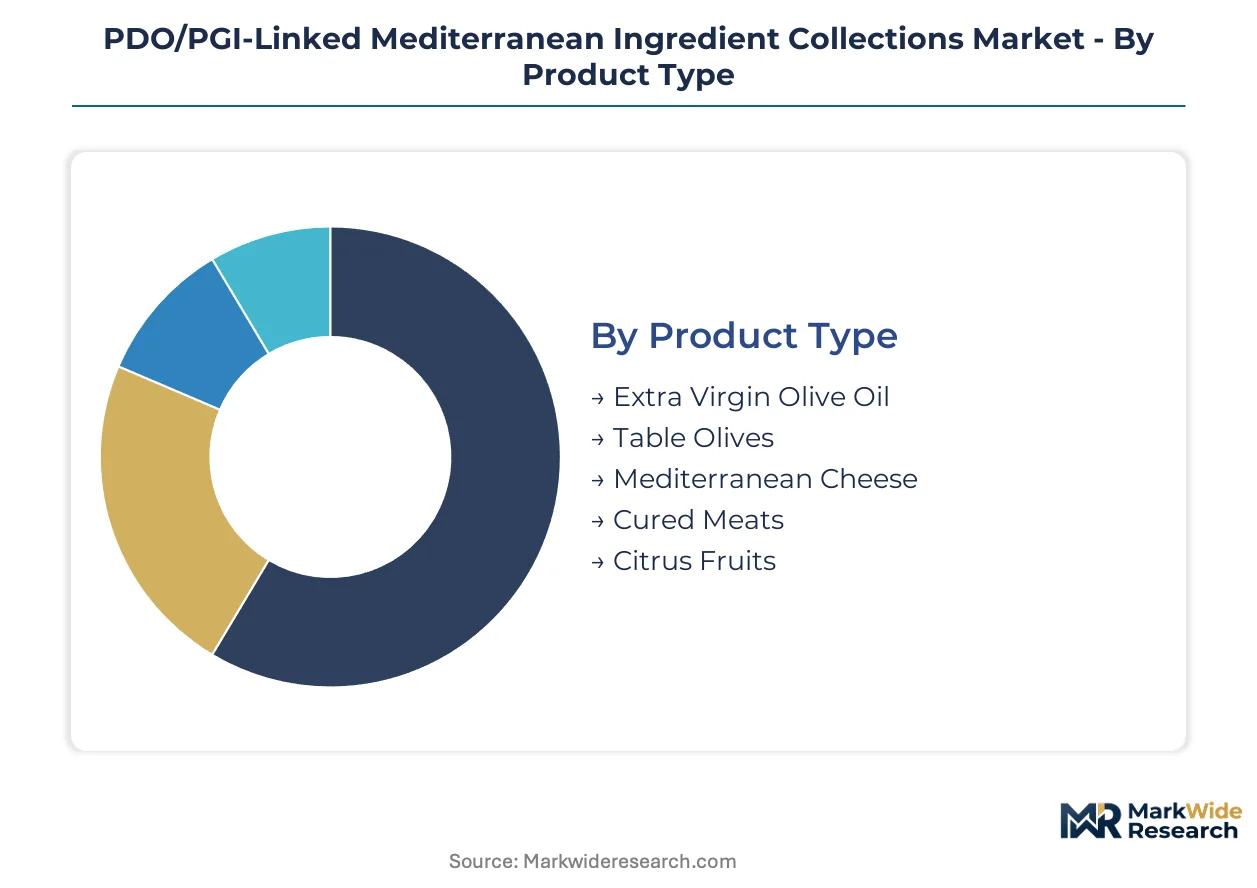
PDO/PGI-linked Mediterranean ingredient collections fragment across four dimensions that each determine authentication burden, margin capture, and channel access. Provenance verification costs vary sharply by product physics and harvest seasonality, reshaping where processors invest in laboratory infrastructure versus cooperative pooling.
Product Type:
Extra virgin olive oil commands the deepest margin pools due to dual-use cosmetic applications and established health premium positioning, while cured meats and cheese capture scarcity rents through volume-constrained traditional processing.
- Extra Virgin Olive Oil:Cold-pressed extraction from designated cultivars with free acidity below 0.8% and specific polyphenol profiles mandated by EU Regulation 1151/2012. Demand concentrates in Barcelona and Marseille cosmetic formulators seeking Sicilian and Calabrian terpene derivatives for active botanical applications, constrained by supercritical CO2 retrofit costs for REACH compliance.
- Cured Meats:Whole-muscle aging from Iberian or Italian swine breeds with minimum curing periods specified in PGI protocols. Procurement is tightening around direct-to-chef platforms in Copenhagen and Milan, where premium restaurant chains now specify individual producer farms rather than regional pooling.
- Table Olives:Fermented or brined fruit from designated groves with cultivar-specific size and oil content thresholds.
- Mediterranean Cheese:Raw milk production with animal breed and grazing area restrictions, including Parmigiano-Reggiano and Manchego type-protections.
- Citrus Fruits:Fresh and processed varieties from Sicilian and Calabrian terroirs with protected status for essential oil extraction.
The dominant share belongs to Extra Virgin Olive Oil, while Cured Meats is closing the gap fastest through restaurant channel disintermediation.
Ingredient Source:
Volume flows concentrate in coastal and highland terroirs where microclimate specificity supports chemical fingerprint differentiation, while organic certification叠加 adds audit layers that smaller cooperatives struggle to absorb.
- Organic Farms:Cultivation units with EU organic regulation compliance and prohibited synthetic input histories, requiring dual certification maintenance.
- Traditional Villages:Settlement-clustered production with documented generational processing continuity specified in PDO application dossiers.
- Coastal Orchards:Maritime-influenced groves in Liguria, Andalusia, and Provence where salt spray and temperature moderation create distinctive organoleptic profiles.
- Highland Groves:Elevated cultivation in Sierra de Cazorla, Calabrian Aspromonte, and Greek Peloponnese mountains with frost-risk harvest compression.
- Traditional Ranches:Extensive livestock systems with breed purity and feed restrictions for Iberian ham and Italian salumi designations.
Coastal Orchards anchor current supply volumes, though Highland Groves is expanding most quickly as temperature stress shifts viable cultivation zones.
Application:
Clean-label formulation mandates in retail channels are accelerating substitution of synthetic preservatives with PGI-certified extracts, compressing development cycles for sauce manufacturers.
- Gourmet Food Production:Premium packaged goods with ingredient blacklists excluding artificial additives.
- Artisan Bakery:Small-batch producers sourcing designated-origin fats and flavoring agents.
- Specialty Sauces:Manufacturer demand for citrus extracts and herb oleoresins with verified provenance chains.
- Premium Catering:Event and hospitality procurement with menu transparency requirements.
- Ethnic Culinary Uses:Diaspora community retail channels maintaining traditional preparation methods.
Specialty Sauces holds the largest application share, with Artisan Bakery gaining ground fastest as sourdough and heritage grain trends intensify.
End User:
Procurement power is consolidating among vertically integrated distributors with in-house authentication capabilities, while direct sourcing fragments traditional wholesale hierarchies.
- Gourmet Retailers:Premium supermarket banners and independent delicatessens with consumer-facing provenance storytelling.
- Specialty Food Distributors:Western European wholesalers expanding certified origin collections with laboratory verification infrastructure.
- Premium Restaurant Chains:Copenhagen, Milan, and San Sebastian-based groups contracting directly with designated-origin consortia.
- Culinary Schools:Training institutions sourcing authentic materials for technique instruction.
- Exporters:Traders leveraging EU-China bilateral GI recognition agreements for protected status enforcement in premium Chinese urban markets.
Specialty Food Distributors retain the dominant procurement position, though Premium Restaurant Chains is climbing fastest through disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Valencia anchors Mediterranean ingredient export flows, with specialized reefer terminals handling olive oil and cured meat consignments bound for Northern European and Asian markets.
Italy
Premium restaurant procurement in Milan and Rome drives concentrated demand for Parmigiano-Reggiano and Tuscan olive oil designations. EFSA traceability mandates enforce isotope-ratio mass spectrometry verification at processing cooperatives in Emilia-Romagna. The Parma food cluster coordinates aging facility investments for protected ham and cheese consortia.
Spain
Barcelona cosmetic formulators expand offtake of Andalusian olive-derived terpenes for active botanical applications. REACH compliance through ECHA tightens residue limits for solvent-extracted oleoresins entering pharmaceutical channels. Jaén province cooperatives pilot blockchain-enabled batch tracking for real-time harvest-to-bottle provenance.
Greece
Northern European retail channels underpenetrate Greek PDO cheese and honey designations relative to Italian equivalents. The country's agricultural ministry processes backlogged PDO applications, delaying new product launches. Peloponnese highland groves expand cultivation as temperature stress shifts viable zones northward.
France
Marseille fragrance houses source Sicilian citrus terpenes for cosmetic dual-use applications. ANSM enforces cosmetic ingredient safety standards for botanical actives entering personal care formulations. Provence coastal orchards maintain distinctive organoleptic profiles from maritime microclimate influence.
China
EU-China bilateral GI recognition agreements open protected status enforcement mechanisms in premium urban markets. SAMR coordinates with EU counterparts on mutual authentication protocols for imported designated-origin goods. Shanghai and Beijing specialty retailers expand shelf space for certified Mediterranean collections.
PDO/PGI-Linked Mediterranean Ingredient Collections Market Competitive Landscape
Concentration sits with vertically integrated processors possessing in-house laboratory authentication capabilities. Italian and Spanish cooperatives dominate raw material sourcing, while multinational ingredient houses control extraction and standardization. Three archetypes define competitive positioning: designated-origin consortia with terroir control, extraction specialists with supercritical CO2 infrastructure, and distributor-integrators with direct chef relationships. Competitive moves center on backward integration into Andalusian and Calabrian processing assets, plus disintermediation of traditional wholesale tiers through direct-to-restaurant platforms.
Within the extraction-specialist tier, DSM-Firmenich, Indena, and Euromed occupy distinct positions. DSM-Firmenich leverages standardized oleoresin supply from PDO olive varietals. Indena anchors botanical sourcing networks around Sicilian and Calabrian citrus terroirs. Euromed competes through upstream control over Andalusian olive processing, commanding quality parameters from harvest to concentrate output.
| Leading Market Players |
|---|
| DSM-Firmenich |
| Indena |
| Euromed |
| ADM |
| IFF |
| Glanbia Nutritionals |
| Pharmactive Biotech Products |
| Bionap |
| Soria Natural |
| Others |
Pricing and Supply Chain Analysis
Ninety-day inventory cycles for cured meat aging facilities compress working capital requirements while amplifying price volatility when Iberian ham supply tightens. EFSA authentication mandates add fixed laboratory costs that processors recover through premium tier markups, concentrating margin capture among cooperatives with in-house isotope-ratio mass spectrometry.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by PDO certification depth and chemical fingerprint verification completeness. Price differentiation hinges on cultivar provenance documentation and REACH-compliant extraction infrastructure ownership. Pricing pressure stems from Tunisian and Moroccan non-PDO olive oils capturing mid-tier foodservice accounts through improved organoleptic profiles at lower cost points. Mass-market foodservice buyers exhibit highest price sensitivity, while premium restaurant chains contracting directly with designated-origin consortia absorb authentication premiums with minimal elasticity.
Supply Chain Analysis
Just-in-time harvest scheduling dominates olive oil processing, though strategic stockpiling of aged ham inventory buffers seasonal supply gaps. Raw material flows concentrate in Spain, Italy, and Greece, with coastal orchards in Andalusia and Liguria anchoring volume. Production draws from designated cultivar groves, traditional livestock ranches, and supercritical CO2 extraction lines. Single-source vulnerability clusters in Extremadura and Salamanca provinces where over half of certified Iberian ham curing capacity resides. Distribution runs through specialty food distributors with laboratory verification infrastructure, though direct-to-chef platforms in Copenhagen and Milan are disintermediating traditional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PDO/PGI-linked Mediterranean ingredient collections sit in early-cycle expansion as EU-China bilateral GI recognition agreements unlock protected status enforcement in premium Chinese urban markets, accelerating penetration beyond traditional Western European channels.
For Market Incumbents: Consolidate authentication infrastructure investments to defend against laboratory talent scarcity extending verification turnaround times. Deepen backward integration into Andalusian and Calabrian processing assets to control quality parameters from harvest to concentrate output. Lock in direct-to-chef platform relationships in Milan and San Sebastian before emerging distributors replicate disintermediation capabilities.
For New Entrants and Emerging Players: Anchor in Greek PDO cheese and honey designations where Northern European retail channels remain underpenetrated relative to Italian and Spanish equivalents. Target artisan bakery applications as clean-label formulation mandates intensify demand for heritage grain and designated-origin fat sourcing. Enter through specialty sauce manufacturers seeking PGI-certified citrus extracts to substitute synthetic preservatives on retailer ingredient blacklists.
For Investors and Strategic Acquirers: Long-term, this sits as a provenance-premium play because regulatory enforcement of EU Geographical Indications Regulation compresses market access for uncertified competitors while concentrating procurement power among verified suppliers. Acquisition candidates include extraction specialists with supercritical CO2 infrastructure for REACH compliance and cooperatives with blockchain-enabled batch tracking pilots. Watch EU-China mutual authentication protocol implementation velocity as the inflection signal for Asian market penetration acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Retrofit | Ensures REACH compliance through ECHA for cosmetic and pharmaceutical channel access. |
| Blockchain-Enabled Batch Tracking | Spanish Jaén cooperatives pilot distributed ledger integration for real-time provenance queries. |
| Direct-to-Chef Platform Launch | London and Amsterdam premium restaurant chains bypass traditional wholesale tiers for time-sensitive collections. |
| PDO Certification Investment | EU member-state agricultural ministry backlogs delay launches by 18-24 months without early filing. |
| EU-China GI Recognition Leverage | SAMR coordination on mutual authentication protocols opens protected status enforcement in Shanghai and Beijing. |
Research Methodology
The analysis maps extra virgin olive oil, cured meats, Mediterranean cheese, and citrus extract sub-sectors, each validated through procurement directors at specialty food distributors, quality assurance leads at extraction processors, and regulatory affairs managers at designated-origin consortia. Primary interviews combined with secondary validation from EFSA guidance documents, EU Regulation 1151/2012 implementation reports, and customs trade data for certified origin goods. Bottom-up volume estimates from cooperative production records triangulated against top-down demand aggregation from premium restaurant chain purchasing data.
Consistency checks validated volume and value outputs against ECHA REACH compliance cost disclosures and bilateral GI recognition agreement implementation timelines. The analytical framework modeled product type, ingredient source terroir, application channel, and end-user procurement archetype across the projection horizon. CAGRs derived from segment-level adoption curves incorporating clean-label formulation mandate intensity and cosmetic dual-use demand expansion. Forecast inputs included supercritical CO2 retrofit investment cycles and blockchain tracking technology diffusion rates among cooperative-level producers.
Material uncertainties — adverse weather patterns compressing olive and citrus harvest yields, EU member-state agricultural ministry certification backlogs, and substitution acceleration from improved non-PDO organoleptic profiles — sit outside the modeled envelope. Forecasts reflect assumptions on regulatory enforcement continuity and bilateral agreement implementation velocity. Revision becomes warranted when authentication laboratory capacity constraints cross thresholds that extend verification turnaround beyond buyer contract specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.