
 Lupin Flour Market | 2026-2036
Lupin Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Lupin Flour Market Insights
EU Regulation 1169/2011 on food information to consumers is pivoting the cost-of-entry calculus for lupin flour suppliers seeking shelf space in European retail. Prolupin GmbH leverages its German processing infrastructure to sustain organic certification across defatted flour lines. Lupin Foods Australia Pty Ltd anchors supply through vertically integrated lupin breeding programs in Western Australia. Wide Open Agriculture competes on regenerative agriculture credentials that differentiate its premium positioning in Asian export channels.
Lupin flour consists of milled seed from Lupinus angustifolius or L. albus species, typically containing 40-45% protein and 25-30% dietary fiber by dry weight, produced through dehulling, milling, and optional air classification or solvent defatting for functional food applications. Sweet lupin flour dominates volume throughput due to negligible alkaloid content and minimal debittering requirements, while gluten-free flour commands margin premiums from coeliac-safe bakery and pasta segments where Albus varieties provide superior emulsification. Defatted flour is gaining share in meat extender applications where protein concentration above 50% enables competitive texturization against soy and pea isolates.
Food Standards Australia New Zealand enforces maximum alkaloid thresholds for lupin ingredients, while the USDA Organic seal and EU Organic Regulation 2018/848 govern premium tier access in North American and European retail. FSANZ testing protocols shape export readiness for Australian processors, and EU novel food authorizations under EFSA jurisdiction still constrain certain bitter lupin applications despite traditional consumption histories. Stakeholders must monitor evolving protein content labeling thresholds and emerging genome-edited cultivar approval pathways that could reshape varietal sourcing decisions.
Market Dynamics
EU Regulation 1169/2011's allergen labeling mandates are compressing shelf-access timelines for lupin flour suppliers, forcing rapid reformulation cycles in gluten-free bakery supply chains and accelerating varietal segregation at processing facilities.
Growth Catalysts
- EU Novel Food Framework:EFSA authorization pathways for genome-edited cultivars are shortening variety-to-market cycles, enabling protein-optimized lupin lines to reach food manufacturers faster than conventional breeding permits.
- Plant-Based Meat Extenders:Australian sweet lupin cultivars with 50%+ protein concentration are displacing soy isolates in texturized vegetable protein applications, driven by clean-label imperatives in European and North American retail.
- Regenerative Agriculture Certification:Western Australian producers leveraging carbon-negative lupin cultivation are capturing premium positioning in Asian export channels where Scope 3 emissions reporting is tightening.
Market Restraints
- Alkaloid Threshold Compliance:FSANZ maximum alkaloid standards impose costly testing burdens on Australian processors exporting to Asian markets, with batch rejection rates concentrated in bitter lupin heritage varieties.
- Input Cost Volatility:Energy-intensive air classification and solvent defatting processes expose margins to natural gas price swings, particularly at German organic-certified facilities.
- Pea Protein Substitution:Established pea isolate supply chains with decade-long customer relationships and lower alkaloid regulatory burdens are constraining lupin flour penetration in meat extender formulations.
Strategic Opportunities
- Underpenetrated Japanese Functional Foods:METI's Foods with Function Claims system offers a regulatory pathway for lupin protein isolates targeting sarcopenia-prevention products in an aging demographic.
- Pasta Application White Space:Albus variety emulsification properties enable egg-free fresh pasta formulations that meet EU organic standards while delivering superior mouthfeel to rice or corn alternatives.
- Direct-to-Baker Distribution:Specialty millers are bypassing ingredient distributors to supply artisan gluten-free bakeries in Berlin and Melbourne with small-batch defatted flour, capturing margin normally allocated to wholesale intermediaries.
Industry Challenges
- Cross-Contamination Protocol Gaps:Coeliac-safe certification requires dedicated milling lines that many mid-scale processors lack, forcing capital allocation decisions between organic and gluten-free audit streams.
- Debittering Skill Scarcity:Wet-processing expertise for alkaloid reduction in bitter lupin varieties is concentrated among aging technicians in Mediterranean traditional-use regions, constraining workforce expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lupin Flour Market |
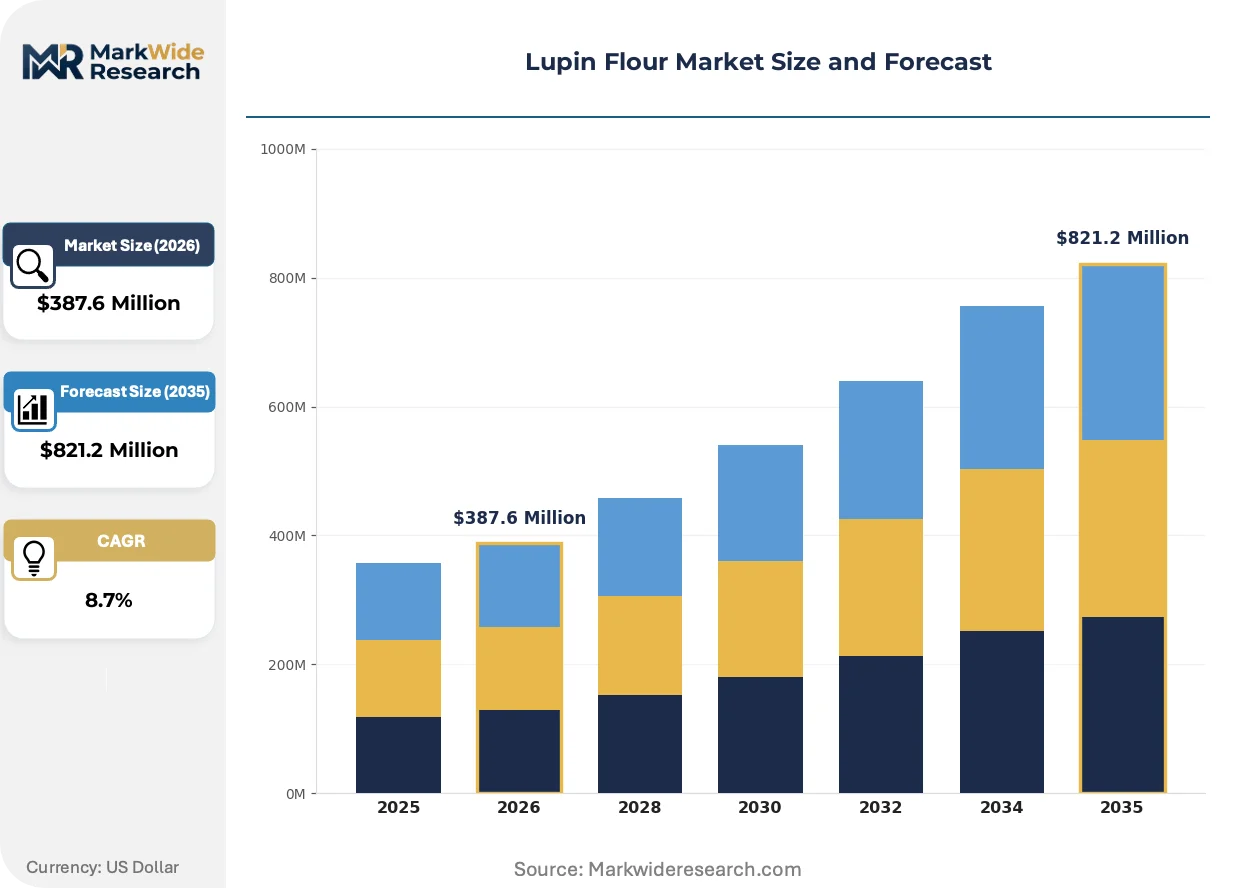
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweet Lupin Flour, Bitter Lupin Flour, Albus Lupin Flour, Others Application: Bakery Products, Pasta Production, Meat Extenders, Dairy Alternatives, Confectionery Processing Form: Raw Flour, Defatted Flour, Gluten-Free Flour, Instant Flour, Organic Flour End User: Food & Beverage Manufacturers, Nutraceutical Companies, Animal Feed Producers, Retail Consumers |
| Companies Covered | The Lupin Co, Lupins for Life, Lupina LLC, Prolupin GmbH, Wide Open Agriculture, Lupin Foods Australia Pty Ltd, Australian Lupin Processing, Golden West Foods Pty Ltd, Barentz International B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lupin Flour Market Trends and Innovations
Processing technology convergence with precision fermentation infrastructure is compressing protein isolation economics, while regulatory clarity on novel foods is unlocking varietal innovation pipelines previously stalled by authorization uncertainty.
Air classification systems integrated with near-infrared protein monitoring are rewriting the cost structure of high-protein flour production. German organic processors are retrofitting dehulling lines with real-time composition sensors, enabling 50%+ protein concentration without solvent defatting. This technology is compressing the price gap between defatted and full-fat lupin flour, reshaping competitive positioning in meat extender supply chains.
REACH registration requirements for novel protein isolates are tightening purity documentation standards for European food ingredient suppliers. EFSA's evolving guidance on genome-edited crops is creating regulatory friction for CRISPR-optimized lupin lines, delaying variety approvals despite technical readiness. German and French processors are responding by accelerating traditional breeding program investments to maintain supply security.
Certification-driven procurement is fragmenting buyer-seller relationships in North American specialty flour distribution. Large gluten-free bakery chains are mandating third-party coeliac-safe audits that smaller Australian exporters cannot resource, consolidating supply relationships around vertically integrated processors with captive laboratory testing. This pattern is most visible in Pacific Northwest retail channels where consumer liability sensitivity exceeds national averages.
Lupin Flour Market Segmentation
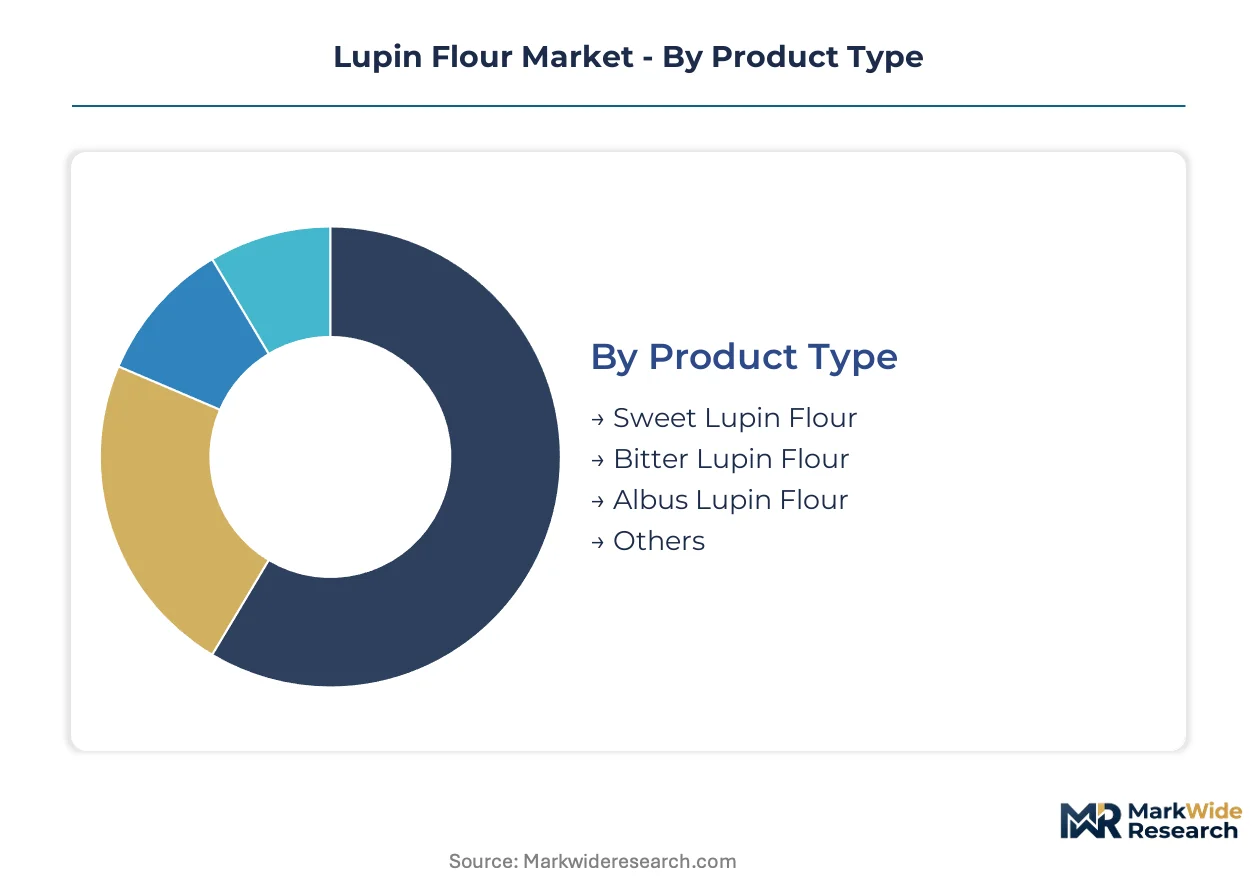
Segmentation in lupin flour tracks the tension between commodity-grade supply and premium-certified tiers. Buyers sort across alkaloid content, protein concentration, and allergen compliance thresholds that reshape procurement economics.
Product Type:
Standardization dominates at the commodity end where alkaloid thresholds are preset, while premium tiers demand varietal traceability and organic certification.
- Sweet Lupin Flour:Negligible alkaloid content eliminates debittering costs. German gluten-free bakeries and Australian meat extender manufacturers absorb the majority of volume, driven by EU Regulation 1169/2011 allergen labeling mandates that favor clean-label ingredients.
- Albus Lupin Flour:Superior emulsification properties from Lupinus albus species enable egg-free pasta formulations. Italian fresh pasta producers and French organic food manufacturers concentrate demand here, leveraging its 40-45% protein content for premium positioning in EU retail channels.
- Bitter Lupin Flour:Requires wet-processing debittering that concentrates expertise in Mediterranean traditional-use regions. Heritage variety preservation and niche nutraceutical applications sustain limited commercial volumes.
- Others:Includes experimental hybrids and genome-edited cultivars awaiting EFSA novel food authorization.
Leading the category by volume: Sweet Lupin Flour. Expanding most quickly: Albus Lupin Flour.
Application:
Cost tier separation runs from mass-market bakery substitution to high-margin functional food positioning.
- Bakery Products:Gluten-free bread and cake formulations absorb the largest volume share. Coeliac-safe certification requirements in Germany and Australia drive supplier consolidation around dedicated milling lines.
- Meat Extenders:Texturized vegetable protein applications favor defatted sweet lupin with 50%+ protein concentration. North American plant-based meat manufacturers displace soy isolates where clean-label imperatives outweigh cost premiums.
- Pasta Production:Albus variety emulsification enables egg-free fresh pasta with superior mouthfeel versus rice or corn alternatives.
- Dairy Alternatives:Emerging application in fermented beverages and protein-fortified milk substitutes.
- Confectionery:Limited penetration due to flavor profile constraints and alkaloid sensitivity in high-heat processing.
Dominant by revenue: Bakery Products. Steepest expansion trajectory: Meat Extenders.
Processing Form:
Volume scale separates commodity raw flour from premium tiers requiring energy-intensive refinement.
- Defatted Flour:Solvent or mechanical fat removal achieves 50%+ protein concentration. Meat extender manufacturers in Germany and Australia prioritize this grade for competitive texturization against pea and soy isolates.
- Gluten-Free Flour:Dedicated milling lines and batch testing command 15-25% price premiums. Coeliac-safe certification from third-party auditors gates access to North American retail chains.
- Raw Flour:Full-fat composition for traditional Mediterranean applications and animal feed compounding.
- Instant Flour:Pre-gelatinized for convenience food manufacturing.
- Organic Flour:EU Organic Regulation 2018/848 and USDA Organic seal compliance required for premium tier access.
Highest throughput: Raw Flour. Fastest margin expansion: Gluten-Free Flour.
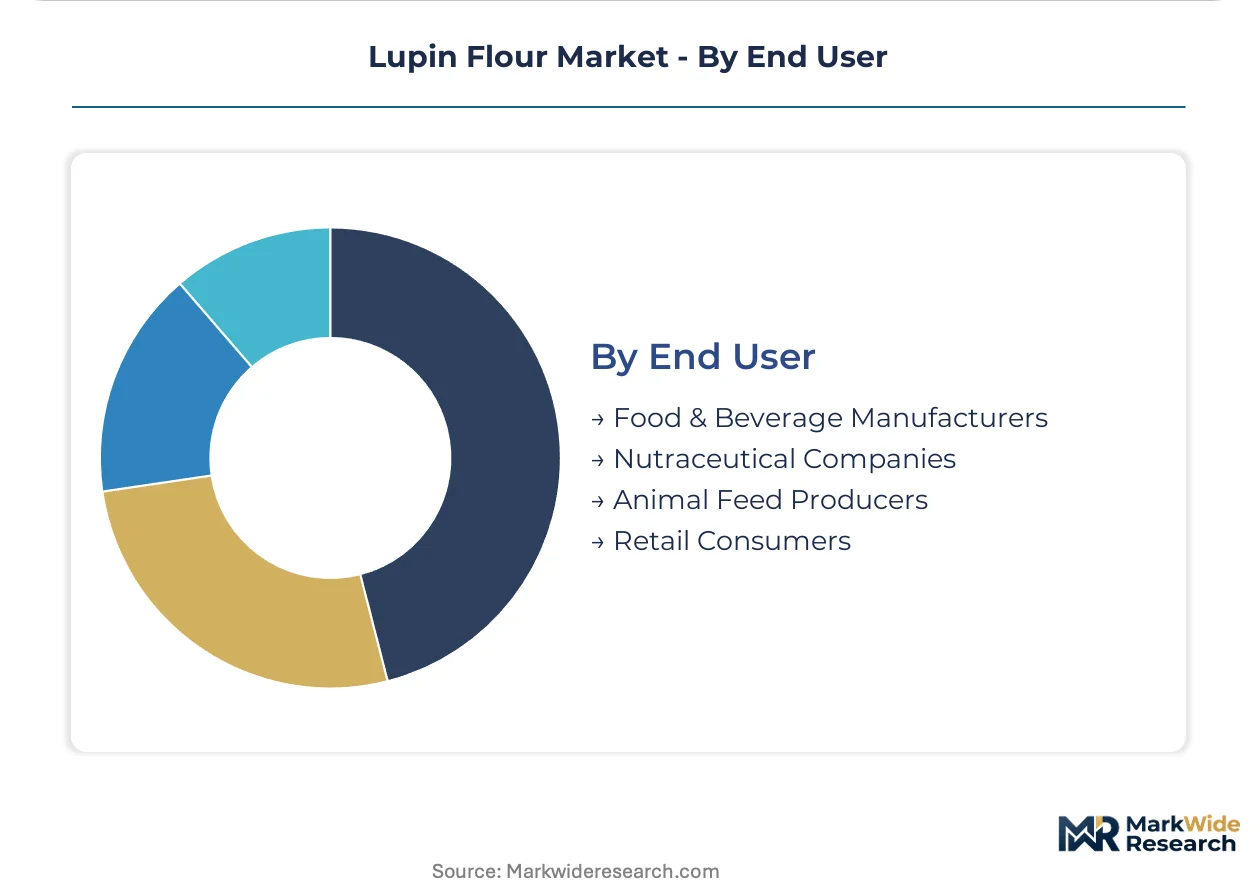
End User:
Customer type determines specification stringency from bulk commodity to retail-branded finished goods.
- Food & Beverage Manufacturers:Account for majority volume absorption across bakery, pasta, and meat substitute applications. German and Australian processors dominate supply relationships through vertically integrated breeding programs.
- Nutraceutical Companies:Protein isolate and dietary fiber extraction for functional food and supplement formulations. FSANZ maximum alkaloid thresholds shape Australian export readiness.
- Animal Feed Producers:Bitter lupin varieties bypass food-grade debittering costs for livestock protein supplementation.
- Retail Consumers:Direct-to-baker distribution in Berlin and Melbourne bypasses wholesale intermediaries for artisan gluten-free segments.
Controlling volume share: Food & Beverage Manufacturers. Gaining share fastest: Nutraceutical Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western Australia's Wheatbelt region concentrates lupin breeding infrastructure through state-sponsored agricultural zones that incentivize varietal development. German organic processing clusters benefit from Bavarian tax incentives for sustainable food manufacturing. These spatial advantages anchor supply-side capacity in both hemispheres.
Germany
Gluten-free bakery manufacturers in Berlin and Munich absorb defatted sweet lupin volumes as EU Regulation 1169/2011 tightens allergen disclosure timelines. EFSA novel food pathways for genome-edited cultivars accelerate variety approvals from Bavarian breeding programs. Prolupin GmbH operates organic-certified processing lines in Brandenburg that supply coeliac-safe flour to pan-European retail chains.
Australia
Meat extender manufacturers prioritize Western Australian sweet lupin cultivars with 50%+ protein concentration for clean-label formulations. FSANZ maximum alkaloid thresholds shape export batch testing protocols at Perth-area processing facilities. Lupin Foods Australia Pty Ltd maintains vertically integrated breeding operations across the Wheatbelt that anchor supply security for Asian export channels.
Italy
Fresh pasta producers in Emilia-Romagna leverage Albus variety emulsification properties for egg-free formulations targeting EU organic retail. REACH registration requirements for protein isolates tighten purity documentation standards at Bologna-area ingredient distributors. Reggio Emilia processing clusters specialize in small-batch defatted flour for artisan gluten-free pasta brands.
United States
North American plant-based meat manufacturers displace soy isolates with Australian-sourced lupin protein where USDA Organic seal compliance enables premium positioning. FDA food allergen labeling guidance shapes reformulation cycles at Pacific Northwest bakery chains. Seattle and Portland distribution hubs consolidate supply relationships around vertically integrated processors with captive laboratory testing.
Japan
METI's Foods with Function Claims system offers regulatory pathways for lupin protein isolates targeting sarcopenia-prevention products in an aging demographic. Tokyo-area functional food manufacturers trial Albus variety formulations for senior nutrition applications. Osaka processing clusters import Australian defatted flour for protein-fortified beverage development.
Lupin Flour Market Competitive Landscape
Australian producers anchor the varietal supply tier; German specialists hold organic processing capabilities that command premium positioning. The market structures around three distinct player configurations: vertically integrated breeders with captive milling infrastructure, regional organic processors with third-party certification relationships, and specialty distributors bridging export channels to food manufacturers. Consolidation pressures concentrate around dedicated gluten-free milling lines and coeliac-safe audit capabilities. Competitive moves center on backward integration into breeding programs and geographic expansion through Asian export channel partnerships.
Within the vertically integrated tier, Lupin Foods Australia Pty Ltd and Wide Open Agriculture exemplify producers combining Western Australian cultivation with captive processing infrastructure. Prolupin GmbH occupies a position among European organic specialists leveraging German certification standards for pan-European distribution. Among ingredient distributors, Barentz International B.V. represents the trading-house archetype facilitating cross-border supply relationships without captive production assets. These three configurations capture distinct margin pools across the value chain.
| Leading Market Players |
|---|
| The Lupin Co |
| Lupins for Life |
| Lupina LLC |
| Prolupin GmbH |
| Wide Open Agriculture |
| Lupin Foods Australia Pty Ltd |
| Australian Lupin Processing |
| Golden West Foods Pty Ltd |
| Barentz International B.V. |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between organic-defatted and commodity raw flour manifests in dual supply chain configurations: EU Organic Regulation 2018/848 compliance commands dedicated milling lines in Brandenburg while spot-market sweet lupin flows through Perth bulk handlers. This bifurcation concentrates pricing power with processors maintaining captive laboratory testing for coeliac-safe certification, compressing margins for undifferentiated exporters.
Pricing Analysis
Short lead-time premiums attach to defatted flour from German organic-certified facilities serving Berlin gluten-free bakeries facing EU Regulation 1169/2011 compliance deadlines. Three-tier pricing structure across premium, standard, and economy levels separates dedicated gluten-free milling lines from shared equipment commodity grades. Pricing pressure stems from energy-intensive air classification costs at solvent-defatting facilities exposed to natural gas volatility. Artisan bakeries in Melbourne and Berlin exhibit lowest price sensitivity, while North American meat extender manufacturers negotiate aggressively against established pea isolate benchmarks.
Supply Chain Analysis
Direct-to-baker channels handle artisan demand in Berlin and Melbourne, bypassing wholesale intermediaries that consolidate commodity flows. Geographic supply concentration centers on Western Australia's Wheatbelt breeding programs, Brandenburg organic processing clusters, and Emilia-Romagna pasta ingredient distributors. Raw material dependencies include lupin seed stocks, natural gas for thermal processing, and food-grade solvents for defatting operations. Single-source vulnerability concentrates in Mediterranean debittering expertise for bitter lupin heritage varieties. Distribution runs through vertically integrated processors with captive testing, regional organic specialists with third-party certification, and trading houses facilitating Asian export channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dedicated gluten-free milling line scarcity props pricing premiums, constraining supply expansion faster than demand absorption across EU and North American retail channels.
For Market Incumbents: Lock in coeliac-safe certification audits before third-party laboratory capacity saturates, and anchor supply security through backward integration into Western Australian breeding programs. Pea protein substitution threats intensify margin pressure in meat extender formulations. Channel control through direct-to-baker relationships in Berlin and Melbourne defends premium positioning against trading-house intermediaries. For New Entrants and Emerging Players: METI's Foods with Function Claims system in Japan opens a window for sarcopenia-prevention protein isolates targeting senior nutrition applications. Underpenetrated Japanese functional foods and egg-free fresh pasta formulations in Italian organic retail represent the most penetrable white spaces. A go-to-market angle leveraging regenerative agriculture credentials unlocks premium positioning in Asian export channels where Scope 3 emissions reporting tightens. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by vertically integrated food manufacturers seeking captive supply security. Long-term viability hinges on genome-edited cultivar approval velocity through EFSA novel food pathways. Acquisition target archetype: regional organic processors with established EU Organic Regulation 2018/848 certification and dedicated gluten-free milling infrastructure. The signal to watch is batch rejection rates at FSANZ alkaloid testing protocols, indicating varietal sourcing flexibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Breeding Programs | Captive supply of protein-optimized sweet lupin cultivars reduces FSANZ batch rejection exposure. |
| Coeliac-Safe Certification Investment | Dedicated gluten-free milling lines unlock 15-25% price premiums from North American retail chains. |
| Regenerative Agriculture Certification | Carbon-negative cultivation credentials differentiate premium positioning in Asian export channels. |
| Direct-to-Baker Distribution Expansion | Bypassing wholesale intermediaries captures margin normally allocated to ingredient distributors in Berlin and Melbourne. |
| Genome-Edited Cultivar Development | EFSA novel food authorization for CRISPR-optimized lines shortens variety-to-market cycles versus conventional breeding. |
Research Methodology
Independent corroboration across primary interviews with plant-based meat procurement leads, organic certification auditors, and gluten-free bakery operations managers, alongside secondary validation through FSANZ alkaloid testing protocols, EU Organic Regulation 2018/848 compliance databases, and EFSA novel food submission records, underwrites the qualitative findings. Bottom-up triangulation from processor capacity assessments and top-down validation against trade flow data ensures analytical robustness.
Comparable-period anchoring to historical supply constraints and demand inflection points structures the projection horizon across the analysis window. Segmentation dimensions modeled include product type tier, application end-use, processing form grade, and geographic regulatory cluster. CAGRs derive from varietal adoption velocity, certification penetration rates, and substitution elasticity against pea and soy isolates. Forecast inputs incorporate energy cost trajectories for air classification and solvent defatting, plus EFSA genome-edited cultivar approval timelines.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation protein isolation would alter the outlook. Forecasts reflect assumptions on regulatory clarity for novel foods, alkaloid threshold enforcement consistency, and plant-based meat formulation substitution rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Pine Needle Oil Market
Ingredients
Seaweed Extracts Market
Ingredients
Pig Protein Concentrate Market
Ingredients
Middle East and Africa Fruit and Vegetable Ingredients Market
Ingredients
Fonio Flour Market
Ingredients
Oyster Peptide Market
Ingredients
Horehound Extract Market
Ingredients
Plant-Based API Market
Ingredients
Potato Starch Market
Ingredients
Confectionery Ingredients Market
Ingredients
Asia-Pacific Yeast Market
Ingredients
Medium Chain Triglyceride (MCT) Oil Market
Ingredients
Pea Flour Market
Ingredients
Brewer's Yeast Market
Ingredients
Feed Ingredients Market
Ingredients
Elecampane Root Market