
 Vegan Protein Blend Market | 2026-2036
Vegan Protein Blend Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Protein Blend Market Analytics
Asset-light contract manufacturing is tilting competitive dynamics toward brands that outsource production rather than build captive facilities. Garden of Life LLC leverages vertical integration into organic certification to sustain premium positioning. Orgain Inc. anchors its portfolio in ready-to-drink formats that dominate pharmacy and club channels. Sunwarrior LLC differentiates through raw, sprouted protein processing that commands shelf space in specialty shops.
A vegan protein blend combines two or more plant-derived protein isolates—typically pea, rice, hemp, or soy—to achieve a complete amino acid profile with protein concentrations ranging from 70% to 90% by dry weight, primarily serving nutritional supplementation and functional food formulation. Pea protein dominates volume due to its neutral flavor and superior emulsification properties in powder and ready-to-drink applications. Hemp protein occupies a smaller but defensible premium tier where omega fatty acid content justifies higher price points in health food stores.
The FDA governs protein content claims and allergen labeling for plant-based supplements sold in the United States, while USDA Organic certification shapes premium tier eligibility and channel access. The EPA oversees agricultural input standards that affect upstream pea and soy sourcing sustainability credentials. Stakeholders must monitor evolving protein digestibility scoring methods and organic supply chain integrity as dual determinants of competitive positioning.
Market Dynamics
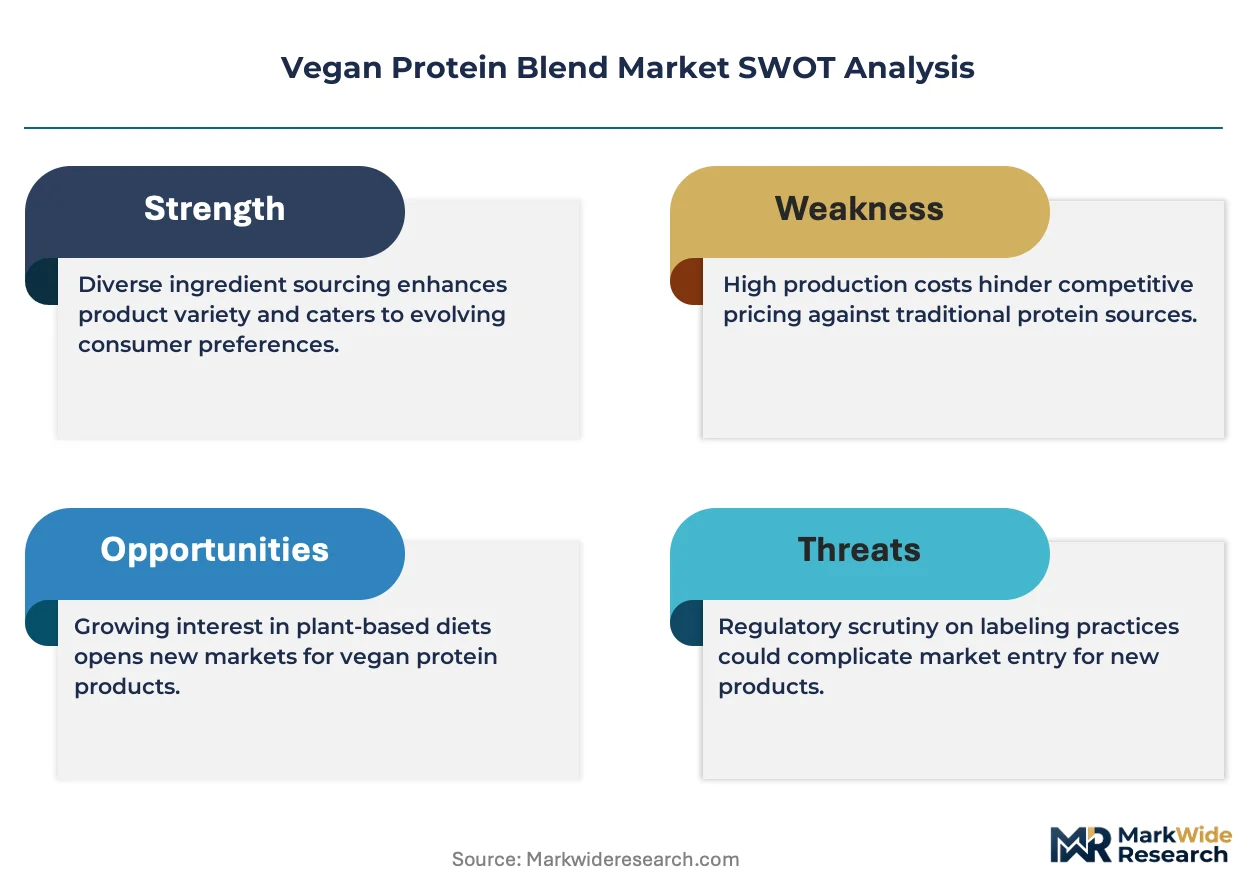
The FDA's tightened substantiation requirements for protein content claims are forcing reformulation cycles across the vegan protein blend supply chain, compressing time-to-market for new entrants while advantaging incumbent brands with established analytical capabilities.
Growth Catalysts
- Clean-label gym culture:United States consumers prioritize ingredient transparency, driving pharmacy and club channel expansion for certified organic blends.
- REACH-aligned sustainability mandates:European formulators now require deforestation-free soy and pea sourcing credentials to maintain retail access.
- Sprouted protein processing:Raw, enzymatically activated blends command specialty shelf space and price premiums in health food retail.
Market Restraints
- Organic supply concentration:USDA Organic-certified pea protein originates from a narrow corridor of North American and European growers, creating procurement bottlenecks.
- Allergen cross-contamination risk:Shared processing equipment for soy and tree nut proteins triggers FDA allergen labeling requirements that limit contract manufacturer flexibility.
- Digestibility scoring uncertainty:Evolving PDCAAS and DIAAS methodologies create formulation instability as brands await final FDA guidance on claim substantiation.
Strategic Opportunities
- Ready-to-drink pharmacy penetration:Orgain-style RTD formats remain underdeveloped in European and Asian retail pharmacies relative to powder saturation.
- Dual carbon goal alignment:China's MEE agricultural input standards create premium positioning for verified low-carbon pea and hemp protein imports.
- Sports nutrition institutional procurement:Collegiate and professional athletic programs represent concentrated volume contracts with limited incumbent penetration.
Industry Challenges
- Organic certification timeline compression:Three-year transition periods for conventional acreage constrain rapid scaling of certified supply.
- Emulsification technical debt:Legacy powder formulations require redevelopment to match next-generation ready-to-drink stability standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Protein Blend Market |
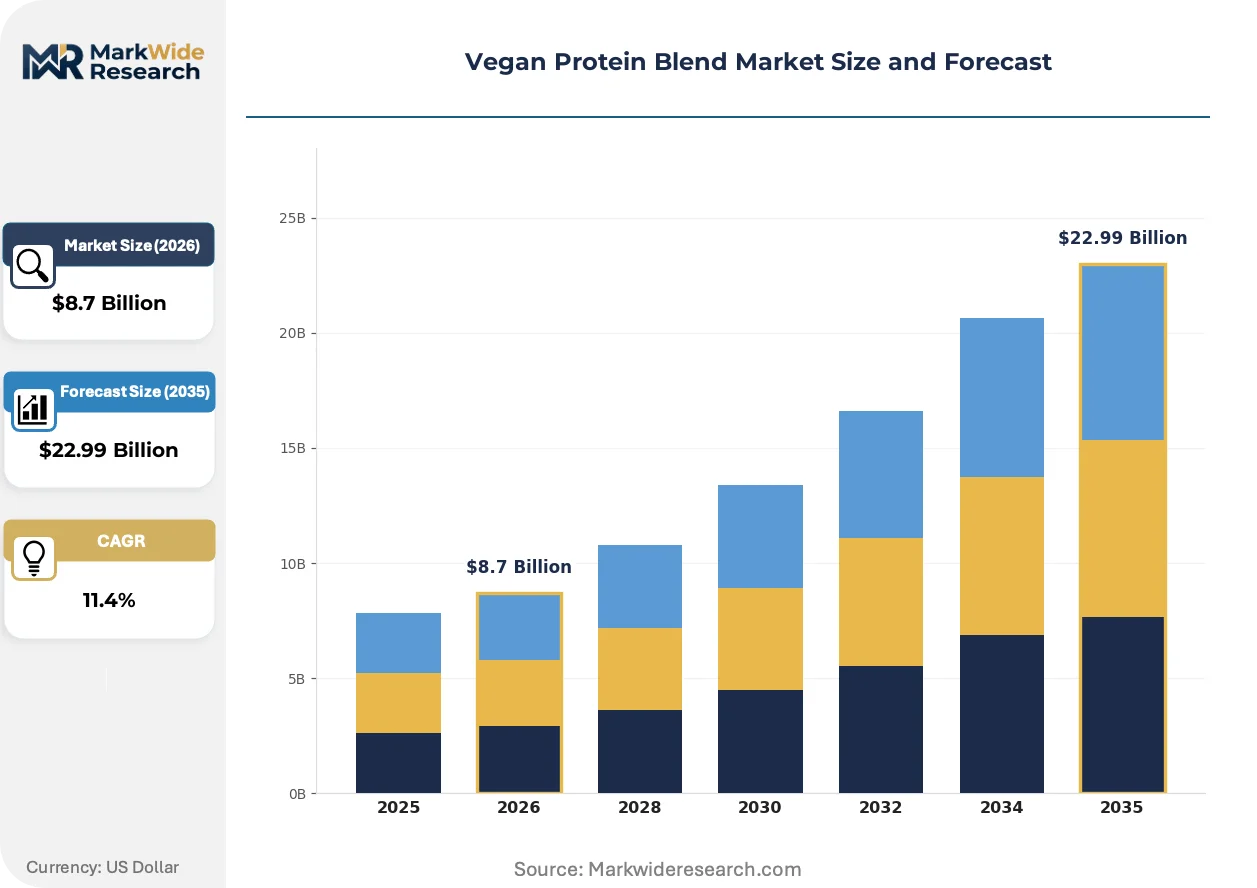
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pea Protein, Rice Protein, Hemp Protein, Soy Protein Form: Powder, Bar, Ready-to-Drink, Supplement End User: Athletes, Fitness Enthusiasts, Vegans, Health-Conscious Consumers Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Garden of Life LLC, Sunwarrior LLC, Orgain Inc., AMCO Proteins, Glanbia plc, Kerry Group plc, Roquette Frères, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Protein Blend Market Evolving Landscape
Processing technology and regulatory precision are converging to reshape competitive differentiation, with brands racing to capture shelf space through substantiated functional claims rather than marketing positioning alone.
Precision fermentation-derived proteins are migrating from niche ingredient status to mainstream blend components. Sports nutrition formulators in the United States and Germany are integrating microbial proteins at 10-30% inclusion rates. This technology is compressing the cost-performance gap between plant and animal-derived proteins while enabling novel amino acid profiles.
EFSA's updated guidance on protein quality claims is forcing European brands to invest in clinical substantiation studies. The industrial consequence is a bifurcation between premium tier products with dossier-backed claims and commodity blends restricted to generic positioning. German and Dutch manufacturers are responding fastest, leveraging existing clinical trial infrastructure from pharmaceutical adjacencies.
Direct-to-consumer subscription models are displacing traditional retail replenishment cycles for vegan protein blends. United States millennials and Gen Z buyers now expect personalized formulation and flavor rotation delivered on 30-day cycles. This behavioral shift concentrates customer lifetime value with digitally native brands while eroding pharmacy and club channel loyalty.
Vegan Protein Blend Market Segmentation
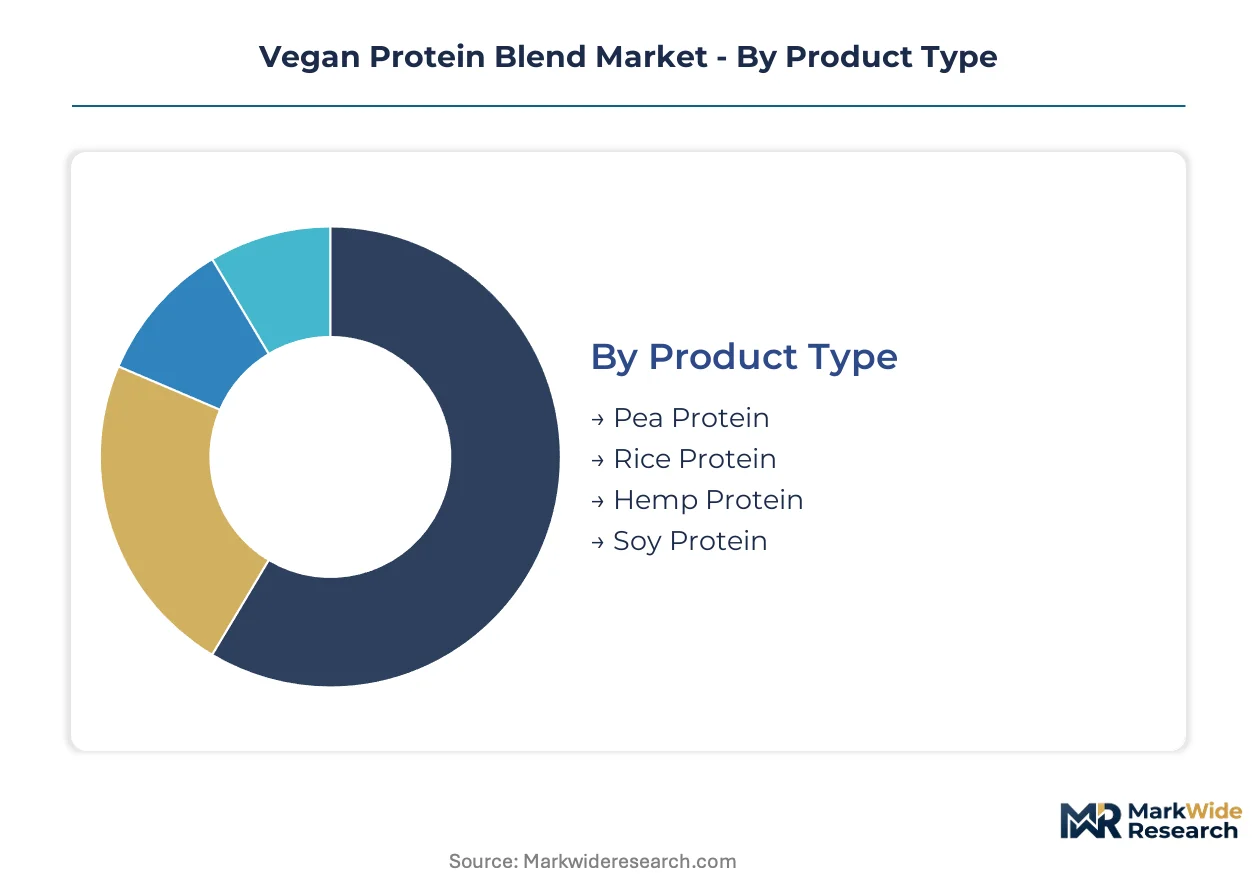
Vegan protein blend manufacturers configure product portfolios around protein source synergies, format stability requirements, and channel-specific packaging economics. Segmentation decisions directly determine sourcing geography, regulatory compliance burden, and margin structure across the value chain.
Product Type:
The use-case spectrum spans neutral-flavor mass-market formulations to omega-fatty-acid-positioned premium tiers, with emulsification properties and amino acid completeness driving formulation choices.
- Pea Protein:Yellow split pea isolates deliver 80-90% protein concentration with superior emulsification in powder and ready-to-drink matrices. United States gym culture concentrates demand for this neutral-flavor workhorse in pharmacy and club channels where clean-label transparency dominates purchase decisions.
- Rice Protein:Brown rice concentrates provide hypoallergenic alternatives with lighter texture profiles but require lysine fortification to achieve complete amino acid scores. European formulators under REACH-aligned sustainability mandates favor rice protein for deforestation-free credentialing in retail-accessible blends.
- Hemp Protein:Cold-pressed hemp seed delivers 50-70% protein with retained omega-3 and omega-6 fatty acids, commanding specialty health food store placement.
- Soy Protein:Isolated soy protein maintains cost leadership with 90%+ concentration and established supply infrastructure, though allergen labeling requirements constrain contract manufacturing flexibility.
Established volume favors pea protein; emerging adoption favors hemp protein.
Form:
Format selection determines manufacturing asset requirements, with powder dominating capital-light contract manufacturing and ready-to-drink demanding in-house aseptic filling capabilities.
- Powder:Dry-blended isolates in bulk canisters and single-serve sachets constitute the manufacturing baseline, with shelf stability exceeding 24 months and minimal cold-chain dependency.
- Ready-to-Drink:Aseptically processed beverages in tetra or bottle formats capture pharmacy channel expansion but require emulsion stability investments that compress new entrant margins.
- Bar:Extruded protein bars with binding systems and moisture control occupy convenience retail with higher per-unit margins but complex co-manufacturing relationships.
- Supplement:Capsule and tablet formats serve precision-dosing segments in clinical and sports nutrition institutional procurement with exacting dissolution specifications.
Volume concentration sits with powder; steepest expansion trajectory belongs to ready-to-drink.
End User:
Customer archetypes differentiate by performance claim requirements, with athletes demanding batch-tested certification and vegans prioritizing ethical sourcing verification.
- Athletes:Collegiate and professional programs require NSF Certified for Sport or Informed Sport batch testing, creating concentrated volume contracts with limited supplier pools.
- Fitness Enthusiasts:Recreational gym-goers in United States metro markets drive subscription-model replenishment cycles with flavor rotation expectations.
- Vegans:Ethical purity seekers demand third-party vegan certification and supply chain transparency, accepting price premiums for verified animal-free processing.
- Health-Conscious Consumers:Mainstream wellness buyers respond to organic certification and clean-label positioning in supermarket and online retail environments.
Contract concentration favors athletes; digital-native acquisition favors fitness enthusiasts.
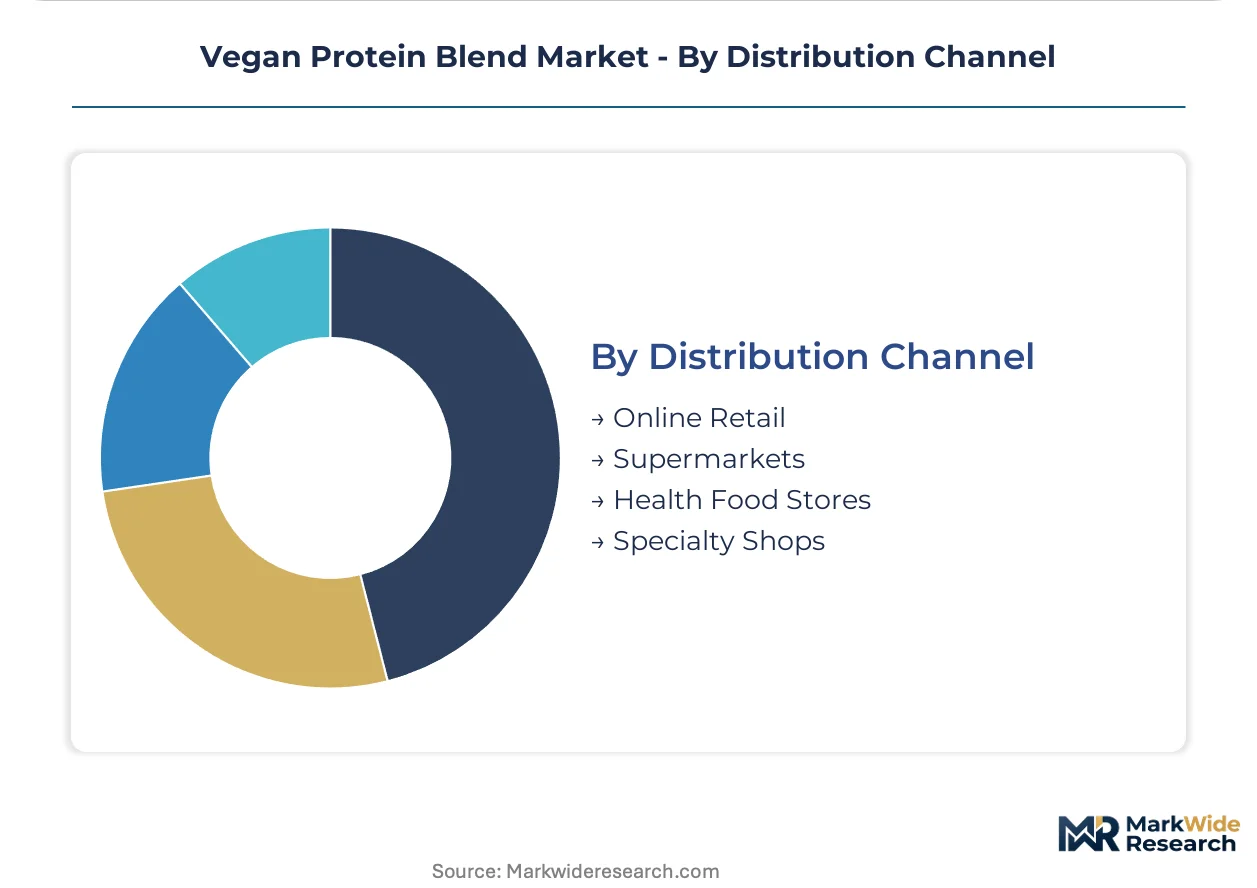
Distribution Channel:
Channel configuration determines packaging format, margin structure, and promotional investment requirements, with online retail compressing traditional retail replenishment cycles.
- Online Retail:Direct-to-consumer and marketplace platforms enable personalized formulation and 30-day subscription models that concentrate customer lifetime value with digitally native brands.
- Supermarkets:Mass-market placement requires slotting fee investments and conventional flavor profiles, with organic certification gating premium tier access.
- Health Food Stores:Independent and chain specialty retailers provide shelf space for sprouted, raw, and small-batch positioned blends with educated staff recommendation dynamics.
- Specialty Shops:Vitamin shops, CrossFit boxes, and yoga studios serve high-touch environments where staff expertise justifies price premiums and drives trial conversion.
Customer lifetime value concentrates in online retail; margin per unit peaks in specialty shops.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net export balances in plant protein isolates favor North American and European suppliers, while Asian markets absorb inbound shipments to feed expanding domestic formulation capacity. Trade flows concentrate in pea and rice protein fractions where processing infrastructure gaps persist in import-dependent economies.
United States
Pharmacy channel expansion for ready-to-drink formats and CrossFit-affiliated specialty shops drive procurement volumes. FDA Nutrition Facts labeling enforcement tightens substantiation requirements for protein content claims. Austin and Denver metro clusters host sprouted-protein processing facilities serving subscription-model brands.
Germany
REACH-aligned sustainability mandates require deforestation-free soy and pea sourcing credentials for retail access. EFSA protein quality claim guidance forces clinical substantiation investments. Cologne-Düsseldorf corridor manufacturers leverage pharmaceutical-adjacent trial infrastructure for dossier-backed premium positioning.
China
Dual carbon goals under MEE agricultural input standards create premium import positioning for verified low-carbon pea and hemp proteins. Sports nutrition institutional procurement concentrates volume in tier-one cities. Yangtze River Delta processing hubs integrate precision fermentation-derived proteins into mainstream blend formulations.
Brazil
Domestic soy protein isolate production supplies cost-competitive base materials for regional formulators. ANVISA supplement regulations govern protein content claim thresholds. São Paulo state industrial clusters export deforestation-free certified fractions to European buyers under supply chain traceability protocols.
India
FSSAI labeling requirements and PLI scheme incentives for food processing infrastructure attract contract manufacturing investment. Health-conscious urban consumers in Maharashtra and Karnataka drive pharmacy channel penetration for powder formats. Gujarat processing zones specialize in rice protein concentrates for hypoallergenic export blends.
Vegan Protein Blend Market Competitive Landscape
On the supply side, the industry is bifurcating between asset-light contract manufacturers and vertically integrated brands with captive organic certification. Strategic archetypes include sprouted-processing specialists, ready-to-drink format leaders, and commodity-scale ingredient suppliers. Competitive moves center on pharmacy channel slotting fee investments and precision fermentation technology licensing partnerships.
Among North American positioned players, Garden of Life LLC exemplifies organic-certified vertical integration, while Orgain Inc. anchors the ready-to-drink pharmacy expansion archetype. Sunwarrior LLC occupies the sprouted-protein specialty tier. European ingredient giants Roquette Frères and Kerry Group plc represent scale-driven supply-side concentration with multi-source protein portfolios.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Garden of Life LLC |
| Sunwarrior LLC |
| Orgain Inc. |
| AMCO Proteins |
| Glanbia plc |
| Kerry Group plc |
| Roquette Frères |
| Others |
Value Network & Pricing Analysis
North American organic pea protein cultivation concentrates in a narrow corridor of Canadian prairie provinces and upper Midwest US states, tethering margin capture to processors with multi-year grower contracts and certified handling infrastructure. This upstream bottleneck translates pricing power downstream to brands commanding USDA Organic certification and pharmacy channel shelf space.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates certified organic blends with deforestation-free credentials from commodity-grade isolates and private-label contract manufacturing outputs. Pricing pressure stems from precision fermentation-derived proteins compressing the cost-performance gap in sports nutrition formulations. Athletes and institutional procurement programs demonstrate lowest price sensitivity, while mass-market supermarket buyers exhibit highest elasticity.
Supply Chain Analysis
Asset-light contract manufacturers including AMCO Proteins and captive facilities at Kerry Group plc hold dominant processing capacity for powder and ready-to-drink formats. Geographic supply concentrates in the United States, Canada, and Germany for organic-certified inputs, with Brazil and India supplying conventional soy and rice protein fractions. Raw material dependencies include yellow split pea isolates, brown rice concentrates, and hemp seed cake. Single-source vulnerability runs through USDA Organic-certified acreage transition timelines. Distribution runs through direct-to-consumer subscription platforms, pharmacy chains, and specialty health food retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation-derived proteins pose a credible substitution threat to plant-based isolates, forcing incumbents to defend positioning through certification depth and clinical substantiation rather than cost parity alone.
For Market Incumbents: Entrench pharmacy channel relationships through exclusive ready-to-drink slotting agreements that block precision fermentation entrants from shelf access. Deepen backward integration into organic certification infrastructure to secure constrained North American pea protein supply against new entrant procurement.
For New Entrants and Emerging Players: Pursue collegiate and professional athletic program procurement contracts where NSF Certified for Sport requirements limit incumbent supplier pools. Target European pharmacy channels with deforestation-free credentialing under REACH-aligned mandates as the most penetrable white space.
For Investors and Strategic Acquirers: Capital is best deployed toward sprouted-processing specialists with raw enzymatic activation capabilities and established specialty retail shelf relationships. Long-term viability hinges on brands capturing subscription-model customer lifetime value against eroding retail loyalty. Watch for FDA final guidance on DIAAS protein digestibility scoring as an inflection signal for reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Certification | Captures constrained North American pea protein supply against procurement bottlenecks. |
| Ready-to-Drink Pharmacy Channel Expansion | Orgain-style RTD formats remain underdeveloped in European and Asian retail pharmacies. |
| Precision Fermentation Technology Licensing | Microbial protein inclusion at 10-30% rates compresses plant-animal cost gaps. |
| Clinical Substantiation Investment | EFSA protein quality claim guidance forces dossier-backed premium tier positioning. |
| Direct-to-Consumer Subscription Launch | 30-day personalized formulation cycles concentrate customer lifetime value digitally. |
Research Methodology
A standing panel of sports nutrition formulators, pharmacy category buyers, organic certification auditors, and contract manufacturing procurement leads provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA Nutrition Facts labeling enforcement records, USDA Organic certification databases, EFSA guidance documents, and REACH-aligned supply chain traceability protocols. Bottom-up volume modeling triangulated against top-down macroeconomic demand projections.
Scenario bracketing anchored projections across base, upside, and downside cases throughout the forecast period. Segmentation dimensions modeled include protein source synergy, format stability requirements, end-user archetype performance claims, and channel-specific packaging economics. CAGRs derived from historical volume trajectories adjusted for regulatory inflection points and technology substitution curves. Industry-specific inputs encompassed precision fermentation capacity buildouts and organic acreage transition timelines.
Sensitivities concentrate around FDA final DIAAS guidance timing, precision fermentation cost curves, and organic supply chain integrity disruptions. Forecasts reflect assumptions on certification penetration rates and subscription-model adoption velocity. Quarterly review of pharmacy channel slotting fee investments and precision fermentation partnership announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant Based Food Colors Market
Plant Based Food
Vegan Dips Market
Plant Based Food
Vegan Protein Concentrate Market
Plant Based Food
Canada Plant Protein Market
Plant Based Food
North America Rice Protein Market
Plant Based Food
Europe Meat Substitutes Market
Plant Based Food
Plant Based Collagen Market
Plant Based Food
Indoor Leafy Green Precision Nutrition Program Market
Plant Based Food
Middle East and Africa Meat Substitute Market
Plant Based Food
Fermented Plant Extracts Market
Plant Based Food
Textured Pea Protein Market
Plant Based Food
Global Plant Based Milk Market
Plant Based Food
Global Plant Based Food Market
Plant Based Food
Plant-Based Chicken Market
Plant Based Food
Kava Root Extract Market
Plant Based Food
Veggie Burger Market