
 Encapsulated Salt Market | 2026-2036
Encapsulated Salt Market Size, Share, and Industry Trends Forecast 2026-2036
Encapsulated Salt Market Foresight
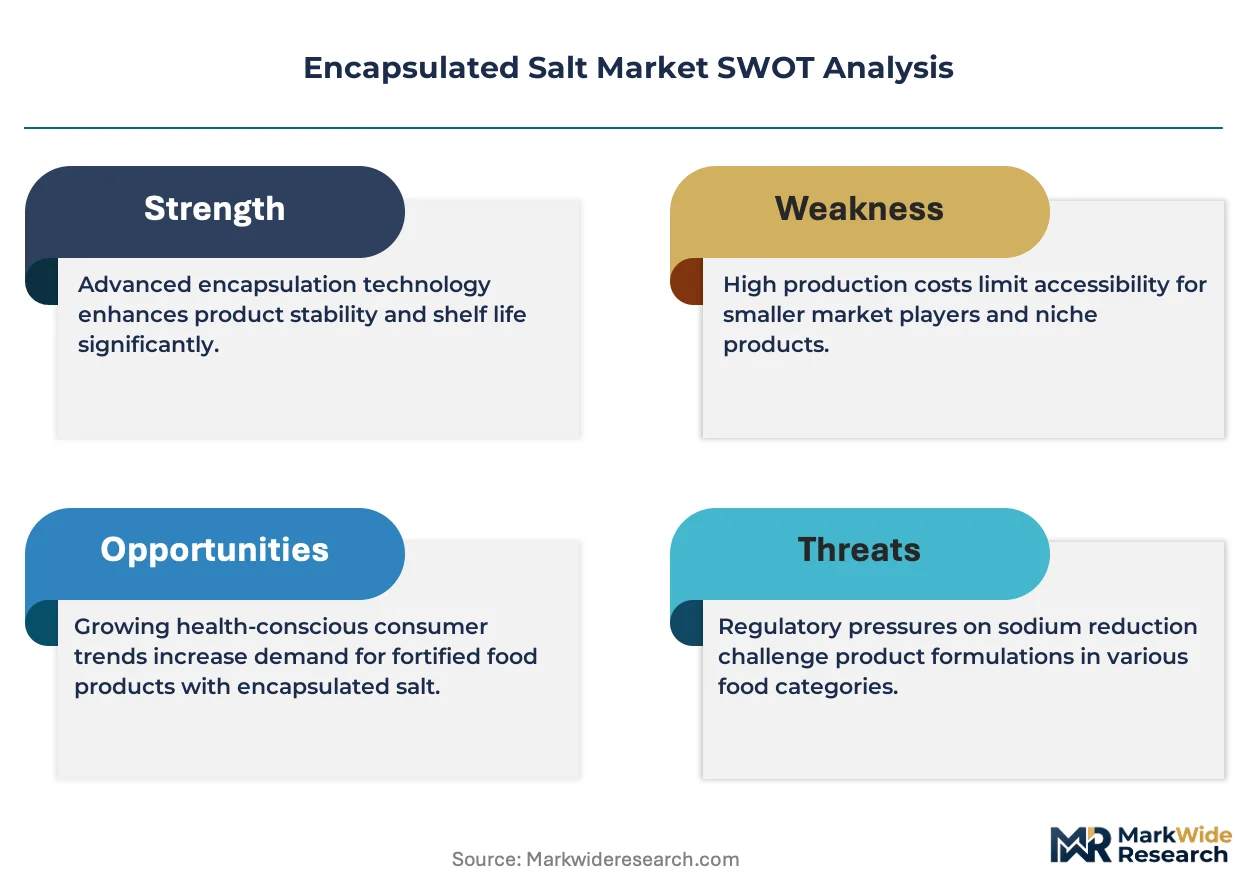
Capital-intensity divergence between spray-drying specialists and fluid-bed coating operators is unwinding competitive stability in the encapsulated salt sector. Balchem leverages its integrated choline and mineral encapsulation infrastructure to sustain pricing power across North American food accounts. BASF competes through synthetic polymer coating chemistry that anchors industrial-grade contracts with European pharmaceutical buyers.
Encapsulated salt refers to sodium chloride particles coated with lipid, polymer, or protein barriers to control dissolution kinetics, moisture release, and taste perception in finished goods. The coating thickness typically ranges from 10 to 200 microns depending on hydrophobicity requirements and target release profiles in processed foods or tablet matrices. Powder formats dominate pharmaceutical nutrient supplement applications where uniform dispersal in effervescent systems commands premium positioning, while granular encapsulation leads seasoning applications for savory snack manufacturers seeking localized burst release. Tablets and capsules represent the fastest-expanding packaging configuration in agriculture, where controlled-release salt licks for livestock nutrition are displacing unprotected mineral blocks.
The FDA's sodium reduction targets for processed foods and the EU's Food Information to Consumers regulation are tightening compositional disclosure standards, forcing reformulation toward precision-encapsulated sodium delivery systems. REACH compliance for coating polymers and EFSA's evolving stance on novel food additives further constrain material selection and supplier qualification timelines. Stakeholders must monitor regulatory divergence between FDA voluntary targets and binding EU sodium limits when allocating R&D budgets across coating platforms.
Market Dynamics
Processed meat manufacturers are accelerating sodium-reduction formulations as regulatory disclosure requirements tighten across multiple jurisdictions, forcing coating technology upgrades and supplier consolidation.
Growth Catalysts
- FDA Sodium Reduction Targets:Voluntary guidelines for processed foods are compelling CPG manufacturers to adopt precision-encapsulated sodium delivery systems that maintain taste profiles while cutting overall salt content.
- Fluid-Bed Coating Technology:Continuous processing methods are replacing batch spray-drying in high-volume savory snack operations, improving coating uniformity and reducing manufacturing waste.
- Germany's Industrial Food Processing Corridor:Concentrated demand from Central European meat processors is driving capacity expansion for lipid-based encapsulation systems serving reformulation mandates.
Market Restraints
- Hydrogenated Palm Oil Input Volatility:Primary lipid coating feedstock faces price instability linked to Malaysian and Indonesian export policy fluctuations and sustainability certification costs.
- REACH Compliance Burden:ECHA registration requirements for synthetic polymer coatings extend supplier qualification timelines to 18-24 months, freezing new material adoption.
- Unprotected Mineral Block Substitution:Traditional salt licks in livestock nutrition retain cost advantage in price-sensitive agricultural segments, slowing controlled-release tablet penetration.
Strategic Opportunities
- Effervescent Pharmaceutical Systems:Powder-format encapsulated salt for nutrient supplements commands premium positioning in effervescent tablet applications where uniform dispersal is critical.
- EU Green Deal Chemicals Strategy:Bio-based coating polymer incentives are creating qualification pathways for protein-barrier alternatives to synthetic lipid systems.
- Livestock Nutrition Tablets:Controlled-release salt licks are displacing unprotected mineral blocks in precision animal husbandry operations across Denmark and the Netherlands.
Industry Challenges
- Coating Thickness Calibration Expertise:10-200 micron specification ranges require specialized process engineers scarce in regional food technology programs.
- EFSA Novel Food Additive Pathways:Evolving safety assessment protocols for new encapsulation materials create 36-48 month approval timelines that outpace product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Encapsulated Salt Market |
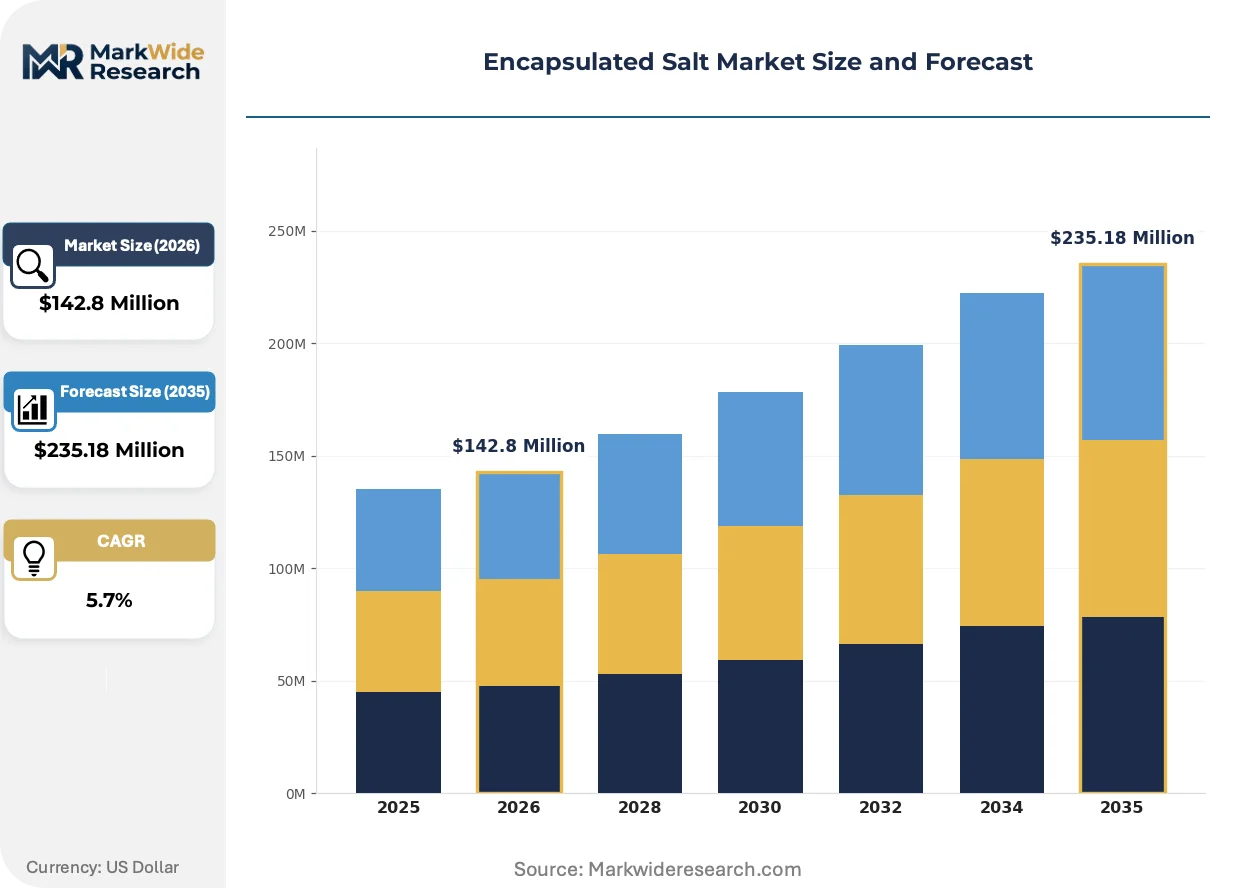
| Market Size in 2026 | $142.8 Million |
| Market Size in 2035 | $235.18 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
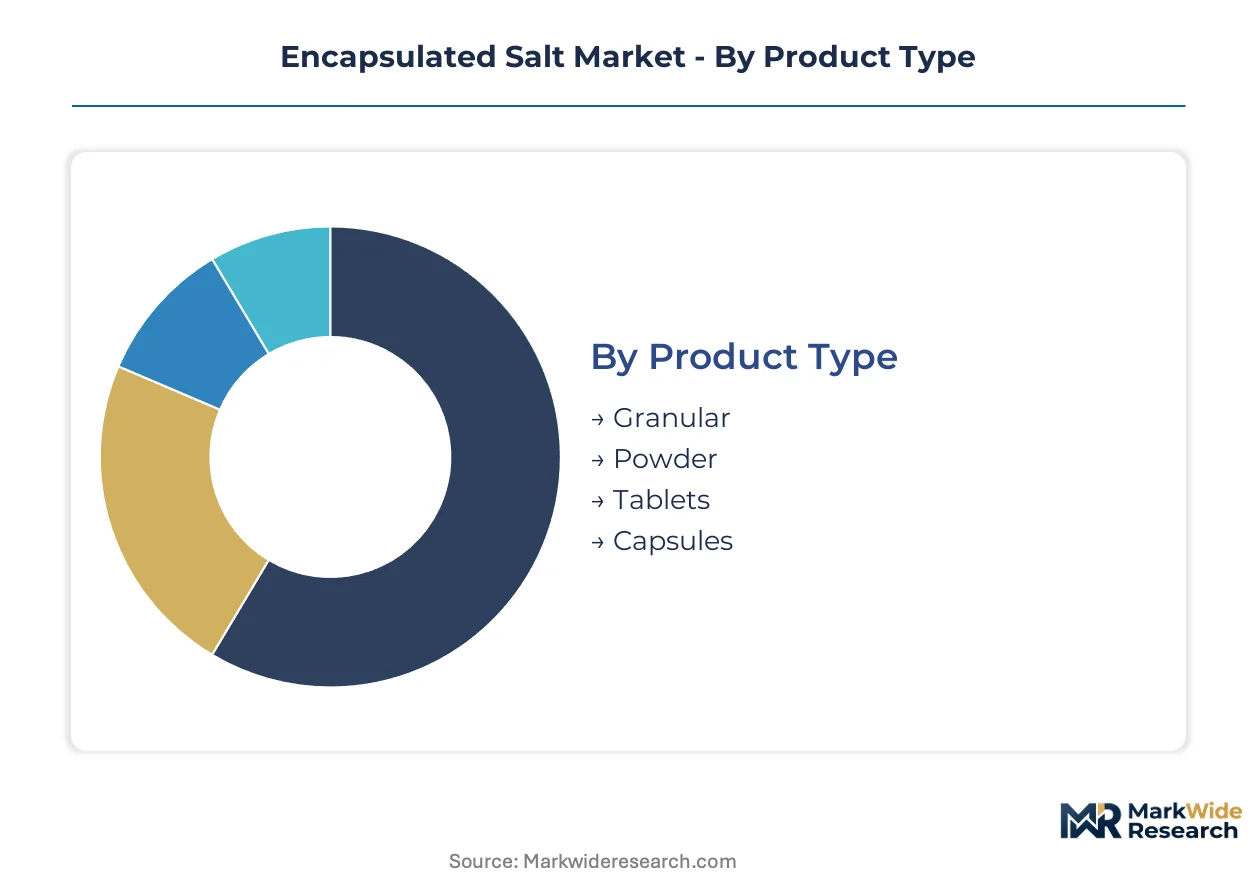
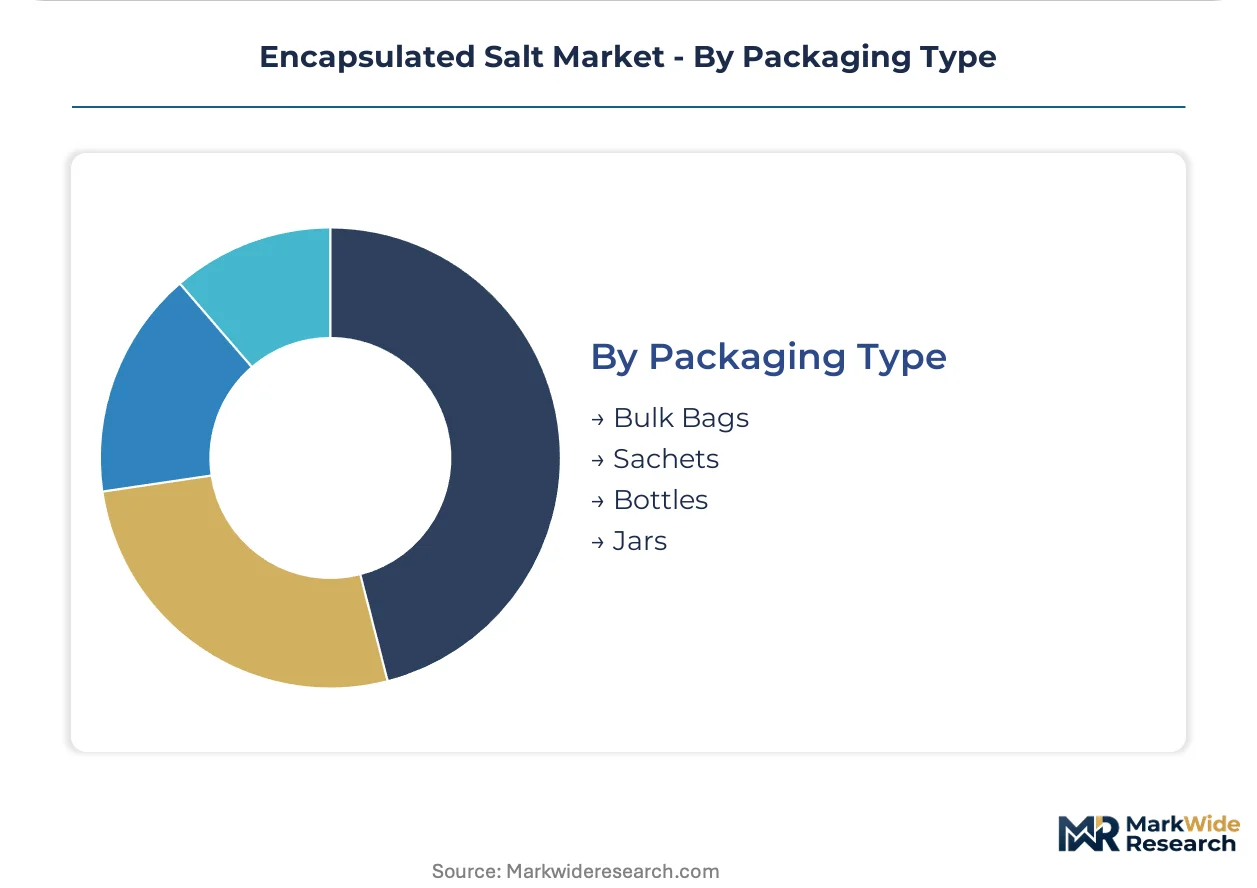
| Segmentation | Product Type: Granular, Powder, Tablets, Capsules End User: Food Industry, Pharmaceuticals, Cosmetics, Agriculture Application: Seasoning, Preservative, Nutrient Supplement, Industrial Use Packaging Type: Bulk Bags, Sachets, Bottles, Jars |
| Companies Covered | Balchem, Danisco, BASF, Symrise, Tate & Lyle, Cargill, Compass Minerals, Avebe, K+S Aktiengesellschaft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Encapsulated Salt Market Shifts & Advancements
Coating chemistry convergence and regulatory disclosure mandates are restructuring supplier-buyer relationships across food, pharmaceutical, and agricultural end-uses.
Protein-based encapsulation barriers derived from whey and zein are supplanting hydrogenated lipid coatings in clean-label savory applications. European snack manufacturers are adopting these systems at pilot scale ahead of anticipated EFSA favorable opinions. The shift is compressing synthetic polymer coating margins while opening premium pricing tiers for bio-derived alternatives.
REACH authorization requirements for persistent organic pollutants in coating polymers are forcing reformulation of established encapsulation platforms. Industrial consequence includes mandatory substitution of certain phthalate-based plasticizers in pharmaceutical-grade coatings. German and Swiss contract manufacturers are responding with accelerated bio-polymer validation programs to maintain EU market access.
Direct technical partnerships between coating technology providers and processed meat R&D teams are shortening formulation development cycles. Traditional ingredient distributor networks are losing share to embedded application laboratories offering joint development agreements. This restructuring is most visible in the Netherlands and Belgium, where sodium-reduction commitments have compressed supplier selection timelines to under six months.
Encapsulated Salt Market Segmentation
Encapsulated salt segmentation reflects divergent technical requirements across regulatory jurisdictions. Coating thickness specifications and dissolution kinetics vary sharply between FDA-monitored processed foods and EFSA-regulated novel food additives, fragmenting supplier qualification pathways.
Product Type:
REACH authorization timelines and FDA GRAS determinations create divergent commercialization windows for each physical format, concentrating investment in pre-qualified coating platforms.
- Granular:Lipid-coated salt crystals ranging 10-200 microns enable localized burst release in savory snack manufacturing. German meat processors dominate procurement volumes under tightened sodium disclosure mandates.
- Powder:Uniform particle dispersion below 50 microns serves effervescent pharmaceutical systems where rapid dissolution kinetics command premium positioning. EFSA novel food additive pathways constrain European adoption timelines.
- Tablets:Compressed matrices with controlled-release barriers displace unprotected mineral blocks in precision livestock nutrition across Denmark and the Netherlands.
- Capsules:Gelatin or HPMC shells encapsulate salt for targeted delivery in dietary supplement formulations facing USP dissolution testing requirements.
Established volume favors Granular; emerging adoption favors Tablets.
End User:
Customer procurement sophistication separates specification-driven pharmaceutical buyers from price-sensitive agricultural purchasers.
- Food Industry:Processed meat manufacturers accelerate sodium-reduction reformulations as EU Food Information to Consumers regulation tightens compositional disclosure. Fluid-bed coating technology upgrades dominate capital allocation.
- Pharmaceuticals:Synthetic polymer coating chemistry anchors industrial-grade contracts with European buyers facing REACH compliance burdens extending supplier qualification to 18-24 months.
- Cosmetics:Microencapsulated salt enables controlled exfoliation in personal care formulations requiring dermatological safety testing under EU Cosmetics Regulation.
- Agriculture:Traditional salt licks retain cost advantage in price-sensitive segments, slowing controlled-release tablet penetration outside precision animal husbandry operations.
Contract value concentrates in Pharmaceuticals; reformulation velocity peaks in Food Industry.
Application:
Functional performance requirements separate taste-masking seasoning applications from preservation chemistry demanding moisture control.
- Seasoning:Localized burst release in savory snacks demands precise coating thickness calibration scarce in regional food technology programs.
- Preservative:Hydrophobic barriers extend shelf stability in processed meats where FDA sodium reduction targets compel precision-encapsulated delivery systems.
- Nutrient Supplement:Uniform dispersal in effervescent tablets commands premium positioning for powder-format encapsulated salt in pharmaceutical applications.
- Industrial Use:Synthetic polymer coatings serve non-food applications with less stringent EFSA safety assessment protocols.
Technical complexity peaks in Seasoning; margin expansion concentrates in Nutrient Supplement.
Packaging Type:
Supply chain configuration separates bulk industrial procurement from retail-facing unit-dose formats.
- Bulk Bags:Food manufacturers source tonnage quantities through direct technical partnerships with coating providers, bypassing traditional distributor networks.
- Sachets:Single-serve seasoning packets for foodservice and retail channels require moisture-barrier laminates to preserve encapsulation integrity.
- Bottles:Pharmaceutical and supplement applications demand child-resistant closures and desiccant integration under USP packaging standards.
- Jars:Wide-mouth containers serve institutional foodservice accounts with high-throughput dispensing requirements.
Procurement consolidation favors Bulk Bags; premium positioning concentrates in Bottles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial food processing corridor drives granular encapsulation demand for sodium-reduction reformulations, while the United States and China pursue divergent coating chemistry strategies shaped by distinct regulatory disclosure frameworks.
Germany
Processed meat manufacturers in Lower Saxony and Bavaria dominate procurement volumes for lipid-based encapsulation systems. REACH compliance for synthetic polymer coatings extends supplier qualification timelines to 18-24 months, freezing new material adoption. The Emsland starch processing cluster anchors bio-based coating polymer development ahead of EU Green Deal Chemicals Strategy incentives.
United States
FDA sodium reduction targets for processed foods compel CPG manufacturers toward precision-encapsulated delivery systems. Fluid-bed coating technology upgrades dominate capital allocation in high-volume savory snack operations. Chicago's ingredient technology corridor hosts embedded application laboratories that shorten formulation development cycles through direct technical partnerships.
China
Domestic seasoning manufacturers accelerate sodium-reduction adoption under SAMR disclosure tightening. GB standards for food additive coatings create divergent qualification pathways from FDA GRAS determinations. Yangtze River Delta flavor houses pilot protein-barrier encapsulation for clean-label export formulations targeting European retail channels.
Netherlands
Precision animal husbandry operations in Gelderland and Overijssel displace unprotected mineral blocks with controlled-release salt lick tablets. EFSA novel food additive assessment protocols for bio-derived coatings compress supplier selection timelines to under six months. Wageningen University's food technology programs address coating thickness calibration expertise scarcity.
Denmark
Livestock nutrition tablet demand concentrates in Jutland's dairy and pork production regions. National veterinary regulations favor controlled-release mineral delivery over traditional salt licks in intensive operations. Aarhus University's agricultural engineering faculty validates bio-polymer encapsulation performance in field trials.
Encapsulated Salt Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational chemical conglomerates controlling synthetic polymer coating chemistry while regional food technology houses dominate lipid-based systems. The market structure favors backward integration into choline and mineral encapsulation infrastructure for pricing power retention. Three archetypes define competitive positioning: integrated nutrition ingredient platforms, synthetic coating chemistry specialists, and agricultural mineral processors. Dominant competitive moves include direct technical partnerships with processed meat R&D teams and accelerated bio-polymer validation programs to maintain EU market access.
Within the integrated nutrition tier, Balchem and Tate & Lyle exemplify platform players with cross-category encapsulation infrastructure spanning food and pharmaceutical applications. BASF anchors the synthetic polymer chemistry vector, serving industrial-grade contracts with European pharmaceutical buyers facing REACH compliance burdens. Cargill occupies a position bridging agricultural mineral supply with food-grade coating capabilities, while Danisco represents the enzyme and culture house archetype extending into bio-derived barrier systems. Symrise exemplifies flavor house vertical integration into precision sodium delivery for savory seasoning applications.
| Leading Market Players |
|---|
| Balchem |
| Danisco |
| BASF |
| Symrise |
| Tate & Lyle |
| Cargill |
| Compass Minerals |
| Avebe |
| K+S Aktiengesellschaft |
| Others |
Supply & Pricing Matrix
Protein-barrier encapsulation replacing hydrogenated palm oil coatings simultaneously shifts supplier geography toward European bio-polymer clusters and compresses synthetic coating margins while opening premium tiers for bio-derived alternatives.
Pricing Analysis
After-sales technical service and joint formulation development contracts drive lifetime value in this market. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade levels separates EFSA-compliant coatings from FDA GRAS tiers from unregistered commodity grades. Cost compression in synthetic polymer segments is intensifying because REACH authorization timelines extend supplier qualification to 18-24 months. Agricultural mineral processors exhibit highest price sensitivity, while pharmaceutical buyers facing USP dissolution testing requirements show lowest sensitivity.
Supply Chain Analysis
Inventory buffers for hydrogenated palm oil feedstock have tightened to 6-8 weeks as Malaysian and Indonesian export policies fluctuate. Manufacturing concentration centers on Germany, the United States, and China, with coating technology providers anchoring in Chicago's ingredient corridor and the Yangtze River Delta. Raw material sourcing draws from Southeast Asian lipid processors, European starch derivatives clusters, and domestic salt refiners. Single-source vulnerability in hydrogenated palm oil certification creates supply chain risk. Distribution runs through direct technical partnerships with processed meat R&D teams, bypassing traditional ingredient distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in regulatory entrenchment: EFSA novel food additive pathways and REACH compliance burdens create 36-48 month approval timelines that freeze new material adoption and protect qualified incumbents.
For Market Incumbents: Consolidate backward integration into choline and mineral encapsulation infrastructure to sustain pricing power across North American food accounts. Add capacity in Germany's industrial food processing corridor to capture sodium-reduction reformulation demand. Invest in bio-polymer validation programs ahead of EU Green Deal Chemicals Strategy incentives to defend against protein-barrier substitution threats.
For New Entrants and Emerging Players: Embedded application laboratory services represent a service-layer gap where incumbents under-serve regional meat processors with compressed supplier selection timelines. Target the Netherlands and Belgium precision animal husbandry segments with controlled-release salt lick tablet formulations. Enter through direct technical partnerships offering joint development agreements with processed meat R&D teams.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed flavor houses that have vertically integrated into precision sodium delivery for savory seasoning applications. Five-to-ten year viability hinges on coating chemistry convergence and regulatory disclosure mandate expansion. Watch for EFSA favorable opinions on protein-based encapsulation barriers as the inflection signal indicating bio-derived tier margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Encapsulation Infrastructure | Balchem-style captive supply of choline and mineral coating capacity sustains pricing power across FDA-regulated food accounts. |
| Bio-Polymer Validation Program Acceleration | German and Swiss contract manufacturers maintain EU market access ahead of REACH authorization requirements for persistent organic pollutants. |
| Direct Technical Partnership Formation | Embedded application laboratories in the Netherlands and Belgium shorten supplier selection timelines to under six months for sodium-reduction commitments. |
| Fluid-Bed Coating Technology Upgrade | Continuous processing methods in high-volume savory snack operations improve coating uniformity and reduce manufacturing waste. |
| Controlled-Release Tablet Capacity Expansion | Precision livestock nutrition operations in Denmark and the Netherlands displace unprotected mineral blocks with compressed matrix formulations. |
Research Methodology
A spread of perspectives from coating technology providers, processed meat R&D directors, pharmaceutical formulation scientists, and agricultural mineral procurement managers converged on the working assumptions driving this analysis. Primary interviews combined with secondary validation from EFSA novel food additive databases, REACH registration filings, FDA GRAS notices, and EU Food Information to Consumers regulatory texts. Bottom-up segment sizing triangulated against top-down industry association data from food ingredient and animal nutrition trade bodies.
Segmentation dimensions modeled include coating chemistry type, physical format, end-use industry, application function, and regional regulatory cluster across the analysis window. CAGRs derived from historical volume trajectories and forward-looking capacity announcements by integrated nutrition platforms and synthetic coating specialists. Forecast inputs incorporated fluid-bed coating adoption curves in savory snack manufacturing and protein-barrier pilot scale validation timelines in European clean-label applications.
Forecasts assume regulatory continuity in FDA sodium reduction targets and EU REACH authorization frameworks; material policy shifts would require re-modeling. Revision becomes warranted when hydrogenated palm oil sustainability certification costs or EFSA novel food additive assessment protocol changes cross thresholds that alter coating platform economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
United States Protein Market
Ingredients
Multi-Grain Premixes Market
Ingredients
South America Fermented Ingredients Market
Ingredients
Hydrolysed Vegetable Protein (HVP) Market
Ingredients
China Protein Market
Ingredients
Europe Vanilla Beans and Extract Market
Ingredients
Flaxseed Derivatives Market
Ingredients
Passion Fruit Powder Market
Ingredients
Soy Protein Concentrate Market
Ingredients
Encapsulated Ingredients Market
Ingredients
Feed Premix Market
Ingredients
Beef Concentrate Market
Ingredients
Codonopsis Extract Market
Ingredients
Malted Wheat Flour Market
Ingredients
Sunflower Oil Market
Ingredients
North America Bioactive Ingredients Market