
 Non-GMO Soya Market | 2026-2036
Non-GMO Soya Market Size, Share, and Industry Trends Forecast 2026-2036
Non-GMO Soya Market Analytics
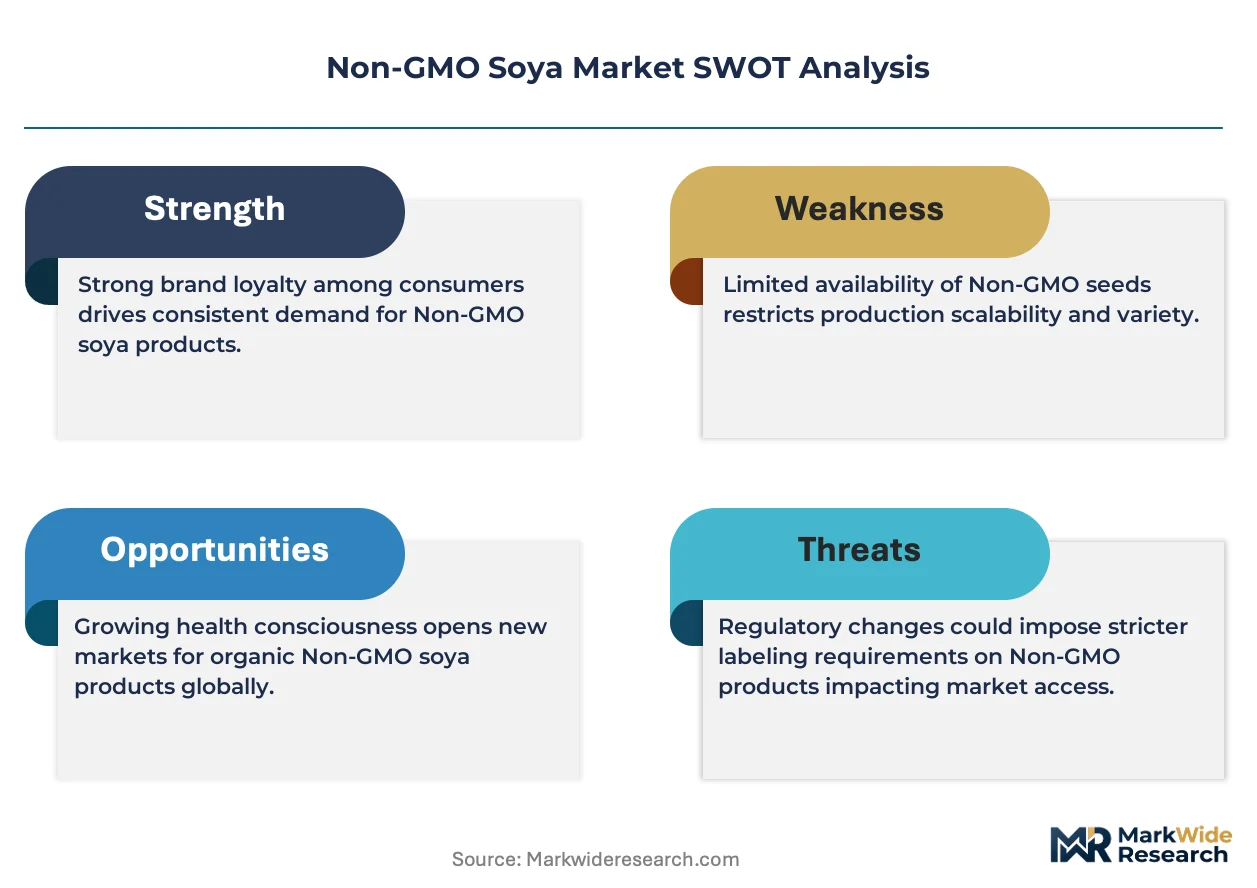
A capital-intensity divergence between integrated processors and merchant traders is unwinding competitive stability in the Non-GMO Soya space. Cargill leverages its origination networks across North American farm belts to secure identity-preserved supply chains. Zeeland Farm Services sustains regional dominance through backward integration into seed conditioning and farmer certification programs.
Non-GMO soya denotes glycine max varieties bred without recombinant DNA techniques, typically achieving protein content of 38-42% on a dry-matter basis and requiring segregated handling from farm to crush to maintain genetic integrity. The crop serves primarily as a high-value protein input for human food systems, aquaculture diets, and specialty feed formulations where label claims command premium positioning. Whole beans and textured protein currently anchor volume throughput, while soya oil extracts targeted at cold-pressed food applications capture disproportionate margin pools. Flour segments serving gluten-free bakery and meat analog applications are expanding fastest, though from a smaller base than commodity-adjacent categories.
USDA oversight of organic and non-GMO labeling, coupled with FDA enforcement of food identity standards, creates compliance cost barriers that favor scaled operators with dedicated quality systems. The EU Green Deal and REACH-aligned import protocols are extending documentation requirements to deforestation-free sourcing claims, reshaping market access conditions for South American exporters. Stakeholders must monitor evolving certification interoperability between Non-GMO Project verification and emerging government-backed traceability systems.
Market Dynamics
Identity-preserved supply chains are fragmenting procurement power as crushers and food manufacturers compete for limited certified acreage, while traceability mandates from the EU Green Deal force infrastructure investments that favor scaled operators with dedicated logistics networks.
Growth Catalysts
- EU F-Gas Regulation:Tightening traceability requirements for imported protein crops are accelerating investment in certified crushing capacity and segregated handling infrastructure across Brazilian port terminals.
- Plant-based meat sector:Manufacturers in the food and beverage industry are expanding long-term procurement contracts for identity-preserved soya to secure non-GMO label claims for retail positioning.
- Brazilian crusher expansion:Certified non-GMO crushing capacity is concentrating in Mato Grosso and Paraná states, drawing demand from European and North American food manufacturers.
Market Restraints
- Segregated logistics costs:Identity-preserved handling from farm to crush requires dedicated storage, transport, and documentation systems that add 15-25% to base commodity logistics expenditure.
- South American supply concentration:Certified non-GMO soya production clusters in specific Brazilian and Argentinian farm belts, creating weather and political risk exposure for buyers.
- Protein content variability:Non-GMO varieties typically achieve 38-42% protein on dry-matter basis versus 44-48% for select GMO cultivars, limiting substitution in high-performance feed formulations.
Strategic Opportunities
- EU deforestation-free sourcing mandates:The EU Green Deal's extension of documentation requirements to land-use claims creates first-mover advantage for crushers with satellite-verified supply chains.
- Gluten-free bakery segment:Soya flour applications in allergen-free baked goods and meat analog formulations are expanding faster than commodity-adjacent categories, albeit from a smaller volume base.
- Cold-pressed soya oil channel:Direct-to-food-manufacturer distribution is bypassing traditional commodity brokers, capturing disproportionate margin pools in specialty food applications.
Industry Challenges
- Certification interoperability gaps:Misalignment between Non-GMO Project verification protocols and emerging government-backed traceability systems is creating duplicate audit burdens for exporters.
- Identity-preservation talent scarcity:Qualified agronomists and supply chain managers capable of managing segregated handling protocols are concentrated among established processors.
- Seed conditioning capex requirements:Backward integration into farmer certification and seed conditioning programs demands sustained capital deployment that merchant traders struggle to match.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-GMO Soya Market |
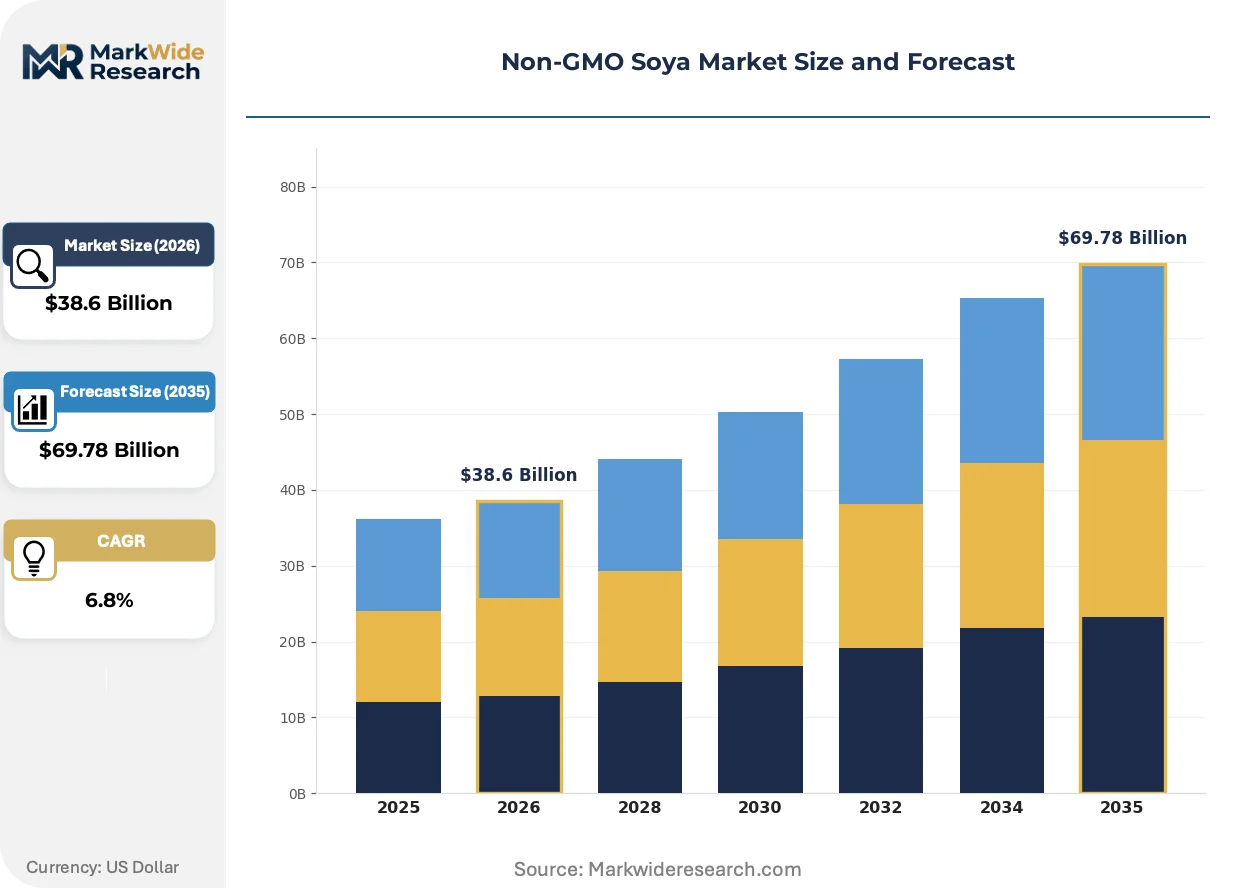
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Beans, Oil, Flour, Textured Protein End Use Industry: Food & Beverage, Animal Feed, Nutraceuticals, Personal Care Distribution Channel: Online Retail, Supermarkets, Wholesale, Export Grade: Food Grade, Feed Grade, Organic, Non-Organic |
| Companies Covered | Archer-Daniels-Midland Company, Cargill, Grain Millers, Zeeland Farm Services, World Food Processing, Laura Soybeans, Sans, Divine Soya & Agro Food, Scoular, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-GMO Soya Market Evolving Landscape
Near-infrared spectroscopy and blockchain-based provenance tracking are compressing verification timelines and reshaping competitive advantage toward data-integrated supply chain operators.
Blockchain-enabled provenance platforms are recording genetic integrity, handling custody, and sustainability metrics at each supply chain node. Large food manufacturers in Germany and the Netherlands are mandating these systems for supplier qualification. This distributed ledger infrastructure is supplanting paper-based certification chains that previously required 45-90 day document reconciliation periods.
The EU Green Deal's deforestation-free import requirements are extending REACH-aligned documentation to protein crop sourcing. Crushers must now provide geolocated farm-level data verified against satellite imagery. South American exporters with established traceability systems are capturing preferential access to Rotterdam and Hamburg port terminals.
Long-term offtake agreements are displacing spot-market procurement for identity-preserved soya. Plant-based meat manufacturers in California and Illinois are signing multi-year contracts directly with Brazilian crushers. This contract manufacturing model is most visible in North American food processing corridors where label-claim security outweighs price flexibility.
Non-GMO Soya Market Segmentation
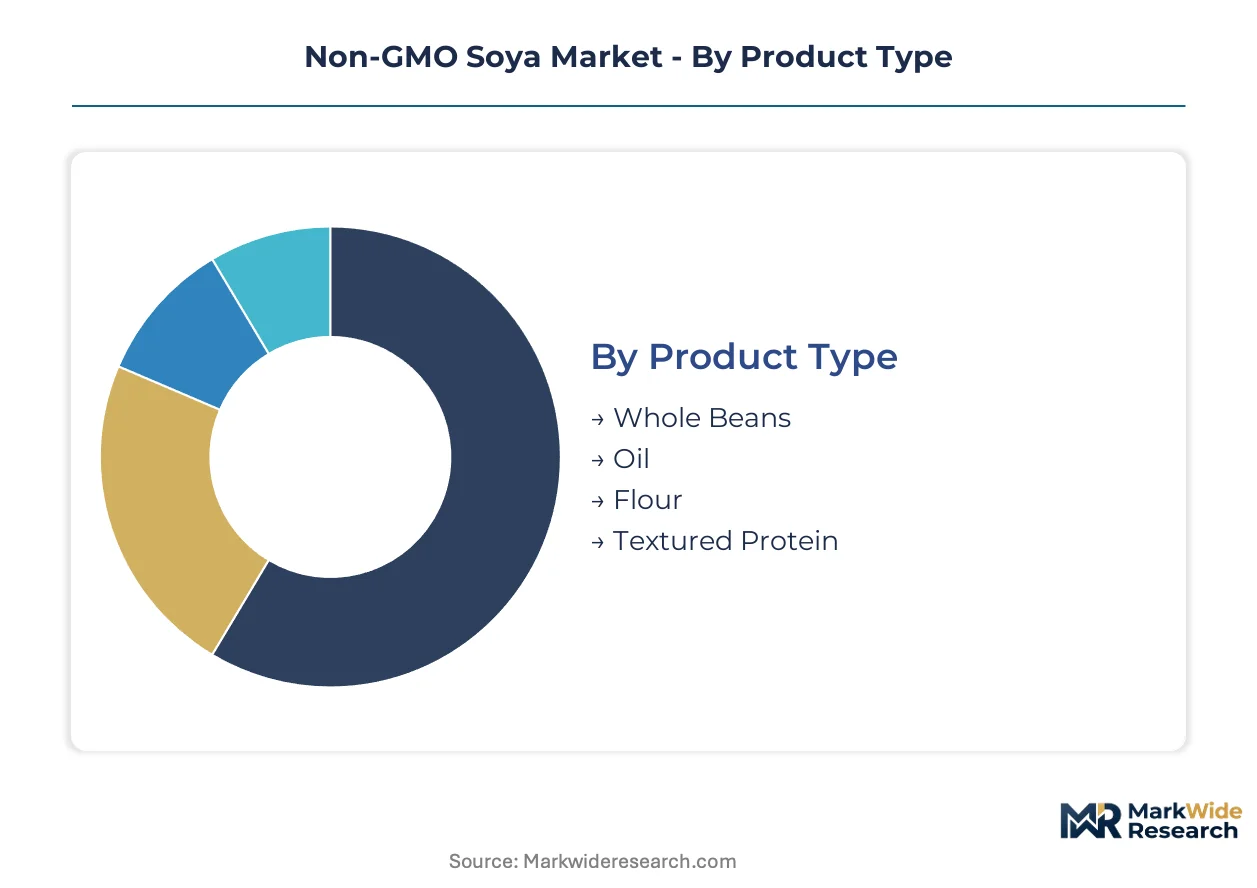
Channel configuration varies sharply across product forms in the Non-GMO Soya Market. Whole beans and bulk oil flow through export and wholesale networks, while flour and textured protein penetrate retail and food-service channels directly.
Product Type:
Whole beans and oil concentrates dominate export terminals and crusher procurement, whereas flour and textured protein access food manufacturers through specialized distribution.
- Whole Beans:Identity-preserved varieties requiring segregated storage and handling from farm to crush. Demand concentrates in Brazilian export corridors serving Rotterdam and Hamburg terminals, driven by EU Green Deal traceability mandates for deforestation-free sourcing verification.
- Oil:Cold-pressed extracts for food applications and refined grades for industrial use. California and Illinois plant-based meat manufacturers are contracting directly with Paraná state crushers to secure non-GMO label claims for retail positioning.
- Flour:Gluten-free bakery applications and meat analog formulations.
- Textured Protein:High-moisture extruded products for meat alternatives.
By volume, Whole Beans leads. By growth pace, Flour is expanding most quickly.
End Use Industry:
Cost tier differentiation separates premium food-grade applications from commodity feed formulations, with nutraceuticals and personal care commanding the steepest premiums.
- Food & Beverage:Plant-based meat analogs, dairy alternatives, and specialty bakery applications. German and Dutch food manufacturers mandate blockchain-enabled provenance tracking for supplier qualification, displacing spot-market procurement with multi-year offtake agreements.
- Animal Feed:Aquaculture diets and specialty livestock formulations where non-GMO claims support premium protein positioning.
- Nutraceuticals:Isolated protein concentrates and functional ingredients for dietary supplements.
- Personal Care:Soya-derived emollients and surfactants for cosmetic formulations.
Food & Beverage generates the largest revenue pool. Nutraceuticals shows the steepest margin expansion trajectory.
Distribution Channel:
Volume concentration favors export and wholesale for bulk commodities, while margin capture shifts toward direct manufacturer relationships bypassing traditional brokers.
- Online Retail:Direct-to-consumer flour and specialty oil products.
- Supermarkets:Packaged textured protein and branded soya ingredients.
- Wholesale:Bulk whole beans and unrefined oil to food processors.
- Export:Containerized shipments from Santos and Paranaguá to European and North American ports.
Export channels move the greatest tonnage. Online Retail is gaining share fastest in consumer-facing segments.
Grade:
Certification tier creates price stratification across food safety and organic standards, with identity-preserved organic commanding the widest premium over conventional non-GMO.
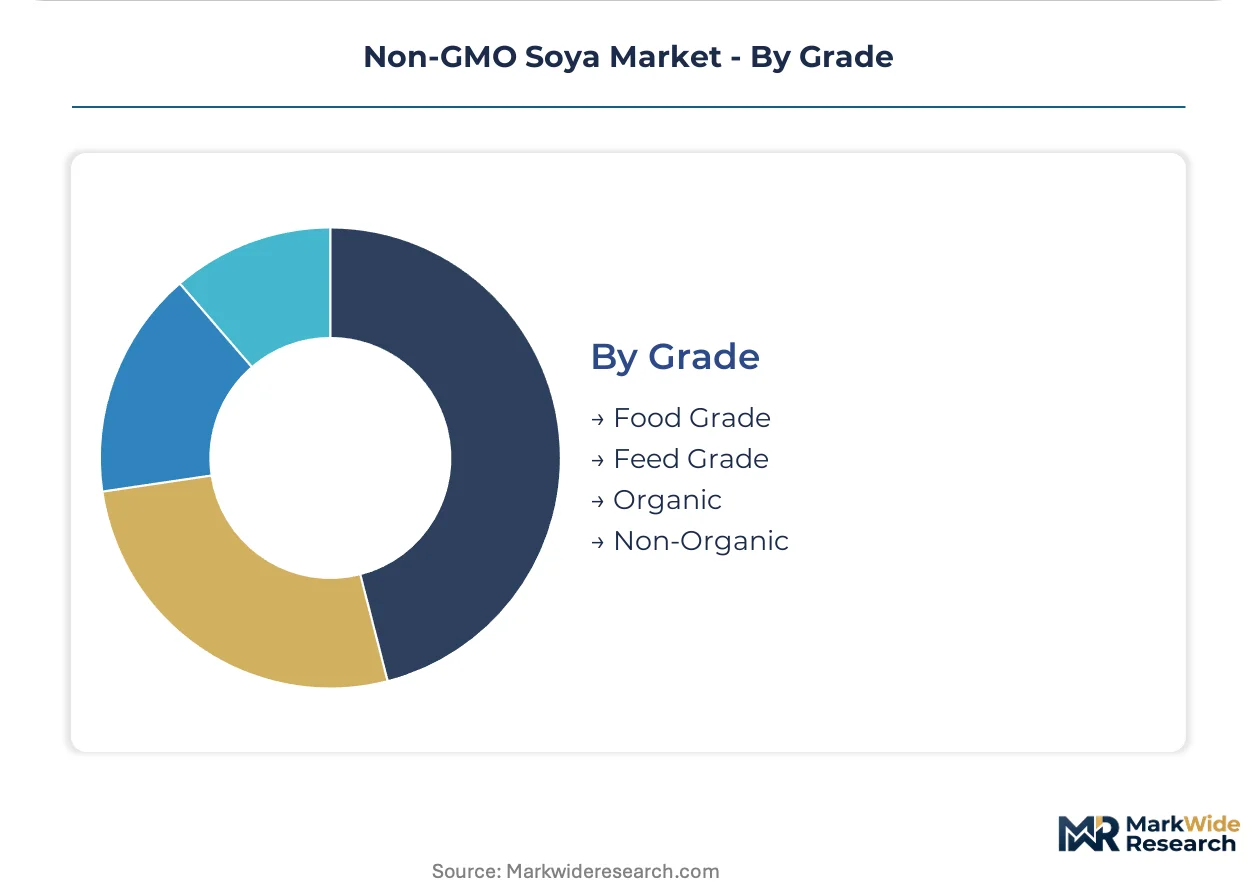
- Food Grade:Meets FDA food identity standards and USDA labeling requirements for human consumption. Compliance cost barriers favor scaled operators with dedicated quality systems and satellite-verified supply chains.
- Feed Grade:Specifications for aquaculture and livestock formulations with lower protein content thresholds.
- Organic:Dual-certified non-GMO and organic under USDA National Organic Program.
- Non-Organic:Identity-preserved conventional non-GMO without organic certification.
Non-Organic grade dominates acreage planted. Organic certification is climbing the fastest as EU import protocols tighten residue and sustainability requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Rotterdam and Hamburg terminals while Brazilian crushers capture volume leverage through certified capacity expansion in Mato Grosso and Paraná.
United States
Illinois and California plant-based meat manufacturers drive contract demand for identity-preserved supply chains. USDA oversight of non-GMO labeling creates compliance barriers favoring scaled operators with dedicated quality systems. Zeeland Farm Services anchors regional dominance through backward integration into Michigan farm belts.
Brazil
European food manufacturers source certified non-GMO whole beans through Santos and Paranaguá export corridors. EU Green Deal deforestation-free mandates force geolocated farm-level verification against satellite imagery. Crushers in Mato Grosso state expand segregated handling infrastructure to capture preferential Rotterdam terminal access.
Germany
Food manufacturers in Hamburg and Frankfurt mandate blockchain-enabled provenance tracking for supplier qualification. REACH-aligned import protocols extend documentation requirements to protein crop sustainability metrics. German crushers invest in near-infrared spectroscopy systems to compress genetic integrity verification timelines.
Netherlands
Rotterdam port terminals serve as the primary European entry point for Brazilian non-GMO soya shipments. EU F-Gas Regulation tightens traceability requirements for imported protein crops. Dutch food processors sign multi-year offtake agreements directly with Paraná state crushers to secure label-claim security.
Argentina
Specialized farm belts in Buenos Aires province supply high-protein non-GMO varieties for aquaculture feed formulations. The country's national agricultural regulator enforces identity-preserved handling documentation for export certification. Rosario crushing clusters compete with Brazilian terminals for European market share through differentiated logistics offerings.
Non-GMO Soya Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics across the Non-GMO Soya space. Integrated processors with captive origination networks command premium positioning through identity-preserved supply chain control. Merchant traders compete on volume throughput but struggle to match backward integration investments. Dominant competitive moves include capacity expansion in certified crushing infrastructure and strategic partnerships with plant-based meat manufacturers for long-term offtake security.
Among North American agribusiness conglomerates, Archer-Daniels-Midland Company and Cargill occupy positions exemplifying scale-driven integrated processing archetypes with origination networks spanning multiple farm belts. Zeeland Farm Services represents the regional specialist model, anchoring competitive positioning through farmer certification programs and seed conditioning capabilities that larger traders struggle to replicate at comparable cost efficiency.
| Leading Market Players |
|---|
| Archer-Daniels-Midland Company |
| Cargill |
| Grain Millers |
| Zeeland Farm Services |
| World Food Processing |
| Laura Soybeans |
| Sans |
| Divine Soya & Agro Food |
| Scoular |
| Others |
Value Network & Pricing Analysis
Plant-based meat manufacturers substituting identity-preserved soya for commodity GMO varieties are simultaneously shifting procurement geography toward Brazilian crushers and compressing pricing flexibility through multi-year offtake structures.
Pricing Analysis
The customization-premium spread between identity-preserved contract pricing and spot commodity benchmarks reflects certification grade and volume scale as primary differentiation drivers. Contract-based long-term offtake dominates as plant-based meat manufacturers prioritize label-claim security over price flexibility. Cost compression in standard non-GMO tiers is intensifying because Brazilian crushers are expanding certified capacity. Food-grade buyers show least price sensitivity, while feed-grade aquaculture formulations remain most responsive to protein content variability discounts.
Supply Chain Analysis
Brazil and Argentina anchor certified non-GMO soya production, with Mato Grosso and Paraná states expanding segregated handling infrastructure. Crushing capacity draws from identity-preserved seed conditioning, geolocated farm verification, and satellite-validated deforestation-free documentation. Single-source vulnerability concentrates in Rotterdam and Hamburg port terminals as primary European entry points. Distribution runs through containerized export corridors from Santos and Paranaguá direct to food manufacturer processing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among plant-based meat manufacturers signing multi-year offtake agreements, fragmenting procurement leverage among smaller food processors and feed compounders.
For Market Incumbents: Secure backward integration into farmer certification programs to defend against merchant traders expanding spot-market sourcing. Anchor capacity in Mato Grosso and Paraná states to capture EU Green Deal preferential terminal access. Invest in near-infrared spectroscopy systems to compress genetic integrity verification timelines against competitors relying on slower laboratory protocols.
For New Entrants and Emerging Players: EU deforestation-free certification fast-tracks offer entry into Rotterdam and Hamburg terminal queues ahead of established exporters lacking satellite-verified supply chains. Target gluten-free bakery soya flour applications as the most penetrable segment with less incumbent concentration than whole bean export channels. Pursue direct-to-food-manufacturer distribution bypassing commodity brokers to capture cold-pressed soya oil margin pools.
For Investors and Strategic Acquirers: The market sits at a certification-infrastructure buildout phase that favors processors with captive origination networks over merchant trading archetypes. Long-term viability over the next decade hinges on interoperability between Non-GMO Project verification and government-backed traceability systems. Watch for EU F-Gas Regulation enforcement tightening as the inflection signal for preferential market access consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Conditioning | Zeeland Farm Services anchors Michigan farm belt control through farmer certification programs. |
| Certified Crushing Capacity Expansion | Paraná state crushers capture California and Illinois plant-based meat contract demand. |
| Blockchain-Enabled Provenance Tracking | German and Dutch food manufacturers mandate distributed ledger systems for supplier qualification. |
| Long-Term Offtake Agreements | Direct contracts displace spot-market procurement for identity-preserved label-claim security. |
| Satellite-Verified Deforestation-Free Sourcing | EU Green Deal geolocation requirements reshape Rotterdam terminal access for Brazilian exporters. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with crushing facility operators, plant-based meat procurement directors, and EU regulatory affairs specialists; and secondary validation against USDA organic certification databases, EU F-Gas Regulation implementation guidance, and Brazilian export terminal throughput records. Bottom-up acreage and capacity modeling triangulated against top-down trade flow analysis.
Across the projection horizon, segmentation dimensions encompassed product form, end-use industry tier, distribution channel structure, and certification grade. CAGRs derived from volume trajectory modeling anchored in crusher capacity expansion timelines and contract procurement patterns. Industry-specific inputs included EU deforestation-free mandate compliance rates and near-infrared spectroscopy adoption curves among verification laboratories.
Underlying assumptions cover sustained EU Green Deal enforcement, Brazilian political stability for agricultural export policy, and plant-based meat manufacturer procurement consolidation, with deviation risk concentrated in certification interoperability delays and South American weather volatility. Recalibration cycles align with material shifts in EU import protocol implementation and crushing capacity commissioning schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Food Colors Market
Ingredients
Vegetable Extract Market
Ingredients
Virginiamycin Market
Ingredients
Europe Fats and Oil Market
Ingredients
Global Tomato Powder Market
Ingredients
Hydrolysed Vegetable Protein (HVP) Market
Ingredients
Fruit Concentrate Market
Ingredients
Asia-Pacific Whey Protein Ingredients Market
Ingredients
France Sodium Reduction Ingredients Market
Ingredients
Edible Animal Fat Market
Ingredients
Food Grade L-Arabinose Market
Ingredients
Vegetable Concentrates Market
Ingredients
High Protein Flour Market
Ingredients
US Ingredients Market
Ingredients
Hydrogenated Palm Oil Market
Ingredients
Grape Skin Extract Market