
 Heart Health Supplement Market | 2026-2036
Heart Health Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
Heart Health Supplement Market Analytics
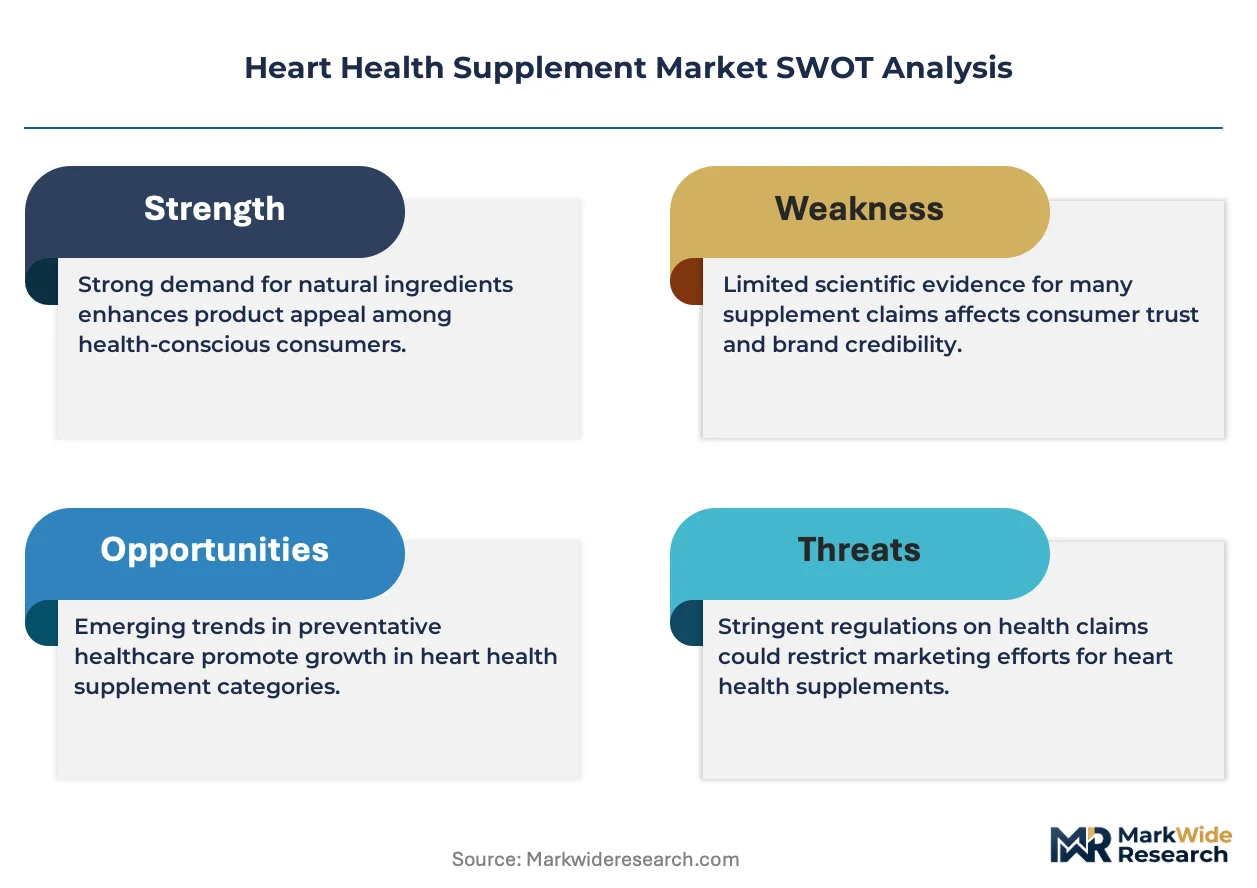
NSF International's Certified for Sport program is collapsing the field of credible suppliers as retailers demand verified label claims. Abbott Laboratories leverages its pharmaceutical heritage to anchor clinical credibility in CoQ10 positioning. Bayer AG competes through pharmacy channel dominance and physician-adjacent marketing. NOW Foods sustains manufacturing scale across multiple delivery modes to control cost structures.
Heart health supplements comprise bioactive compounds—omega-3 fatty acids, coenzyme Q10, red yeast rice, and garlic-derived allicin—formulated to modulate lipid profiles, endothelial function, and oxidative stress markers. These products serve consumers seeking non-prescription cardiovascular risk reduction alongside standard care. Omega-3 fatty acids dominate value pools due to prescription-strength EPA consolidation and retail commoditization of fish oil. Gummies capture the fastest-growing delivery mode as palatability drives compliance among younger demographics. Natural ingredient sourcing leads positioning, though fermented red yeast rice commands premium tiers for statin-intolerant users.
FDA's Current Good Manufacturing Practice regulations and NDI notifications govern market entry, while EFSA health claims authorization shapes European formulation strategies. The FTC actively polices substantiation for cholesterol-reduction claims, forcing reformulation or label revision. Stakeholders must monitor evolving FDA guidance on structure-function claims versus disease-state language, as enforcement thresholds determine competitive viability for new entrants.
Market Dynamics
The FDA's evolving New Dietary Ingredient notification requirements are reshaping competitive entry barriers, forcing smaller formulators to abandon novel bioactive development while consolidating innovation capacity among established pharmaceutical-adjacent players with dedicated regulatory affairs infrastructure.
Growth Catalysts
- Preventive Cardiovascular Protocols:Cardiologist-adjacent wellness programs in the United States are normalizing supplement co-prescription alongside statin therapy, expanding addressable patient populations beyond traditional self-directed users.
- Aging Demographic Concentration:Senior consumers in Japan and Germany are driving demand for endothelial function modulators as healthcare systems shift toward outpatient chronic disease management.
- EPA Prescription Consolidation:FDA-approved icosapent ethyl formulations are validating omega-3 lipid management claims, creating downstream credibility effects for retail-strength fish oil positioning.
Market Restraints
- Anchovy and Sardine Supply Volatility:Peruvian and Chilean fishery quotas constrain omega-3 raw material availability, concentrating input risk among coastal South American extraction operations.
- NDI Notification Friction:FDA's 75-day pre-market safety evaluation for novel ingredients delays fermented red yeast rice variant launches, compressing innovation timelines for statin-alternative formulations.
- Plant-Based Omega Substitution:Algal DHA extraction technologies are displacing marine sources in vegan-positioned products, threatening traditional fish oil value pools.
Strategic Opportunities
- Gummy Delivery Mode Expansion:Palatability-driven compliance among younger demographics in the United States is opening format innovation white space previously dominated by softgel incumbents.
- EFSA Health Claims Authorization:European Union regulatory pathways for cholesterol reduction substantiation are enabling premium positioning for clinically validated garlic-derived allicin formulations.
- Direct-to-Consumer Channel Maturation:Subscription-based replenishment models are capturing recurring revenue streams outside pharmacy and mass retail gatekeepers.
Industry Challenges
- Regulatory Affairs Talent Scarcity:Structure-function claim drafting expertise sits concentrated among former FDA staffers, inflating compliance costs for mid-tier formulators navigating FTC enforcement thresholds.
- Certification Timeline Compression:NSF International's Certified for Sport program demands are extending third-party verification cycles, delaying product launches for retailers demanding verified label claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heart Health Supplement Market |
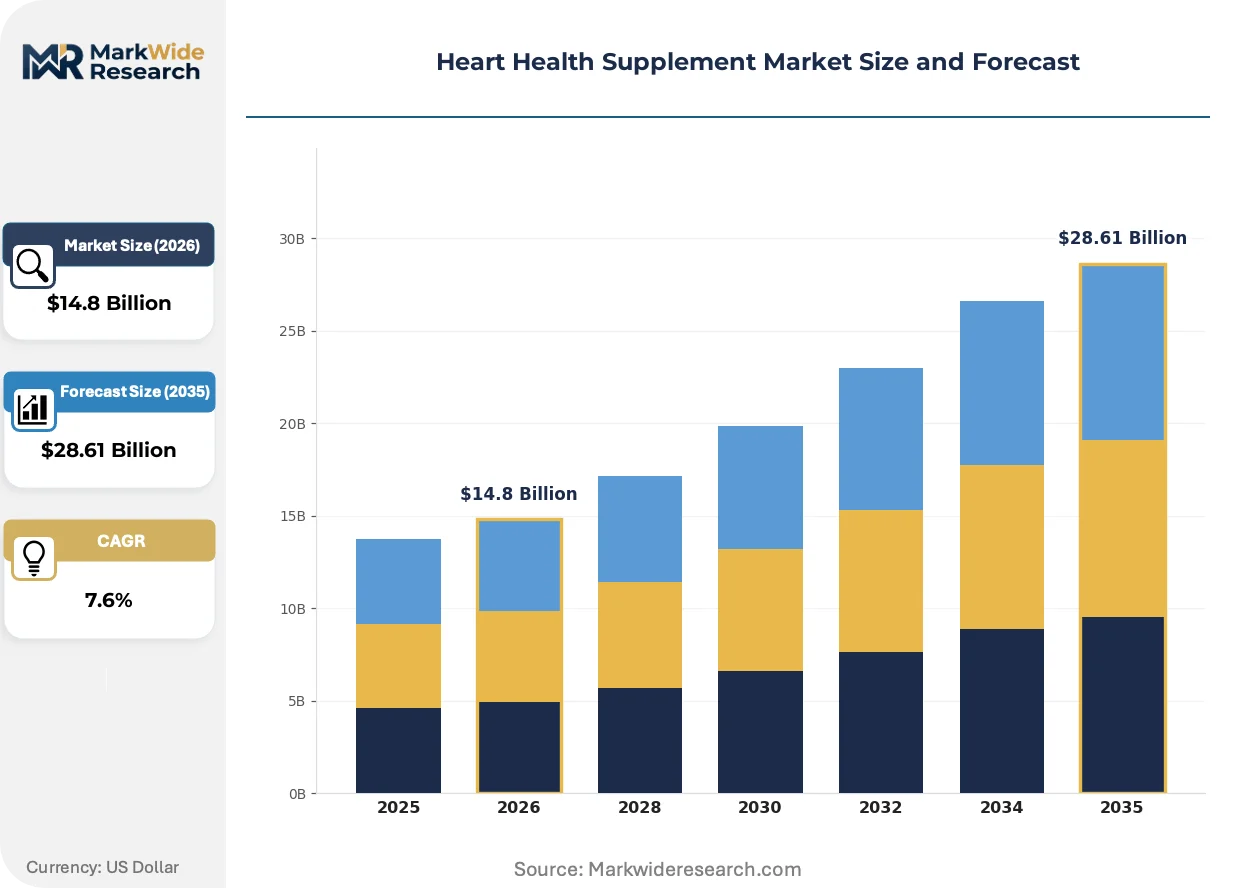
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $28.61 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CoQ10, Omega-3 Fatty Acids, Red Yeast Rice, Garlic Extract Delivery Mode: Capsules, Powders, Gummies, Liquids End User: Adults, Seniors, Athletes, Health-Conscious Individuals Ingredient Source: Natural, Synthetic, Organic, Fermented |
| Companies Covered | Abbott Laboratories, Bayer AG, Nestlé Health Science, NOW Foods, Amway Corp., Thorne HealthTech Inc., Nordic Naturals, Herbalife Nutrition Ltd., Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heart Health Supplement Market Evolving Landscape
Delivery format innovation and regulatory claim substantiation are converging to reshape competitive differentiation, as palatability engineering and clinical validation protocols displace commodity positioning in cardiovascular wellness.
Liposomal encapsulation technology is bifurcating the CoQ10 segment between premium bioavailability-positioned offerings and standard oil-based formulations. Cardiologist-recommended protocols in the United States are accelerating adoption of enhanced-absorption variants. This technological divide is compressing margin structures for legacy softgel manufacturers while enabling premium tier pricing for liposome-equipped suppliers.
EFSA's ongoing evaluation of Article 13.1 health claims for polyphenol-rich extracts is forcing European formulators to abandon general cardiovascular wellness language in favor of specific endothelial function endpoints. The regulatory tightening is redirecting R&D investment toward mechanistic clinical trials. Fermented red yeast rice producers in Italy and Spain are responding with statin-content standardization protocols that exceed current pharmacopeial requirements.
Cardiologist-influenced purchasing is displacing self-directed retail selection in the United States, as physician-adjacent wellness protocols normalize professional recommendation as a prerequisite for premium supplement adoption. This channel migration is compressing traditional mass-market volume while expanding specialty pharmacy and clinician-dispensed segments. The behavioral shift is most visible in metropolitan healthcare systems with integrated preventive cardiology programs.
Heart Health Supplement Market Segmentation
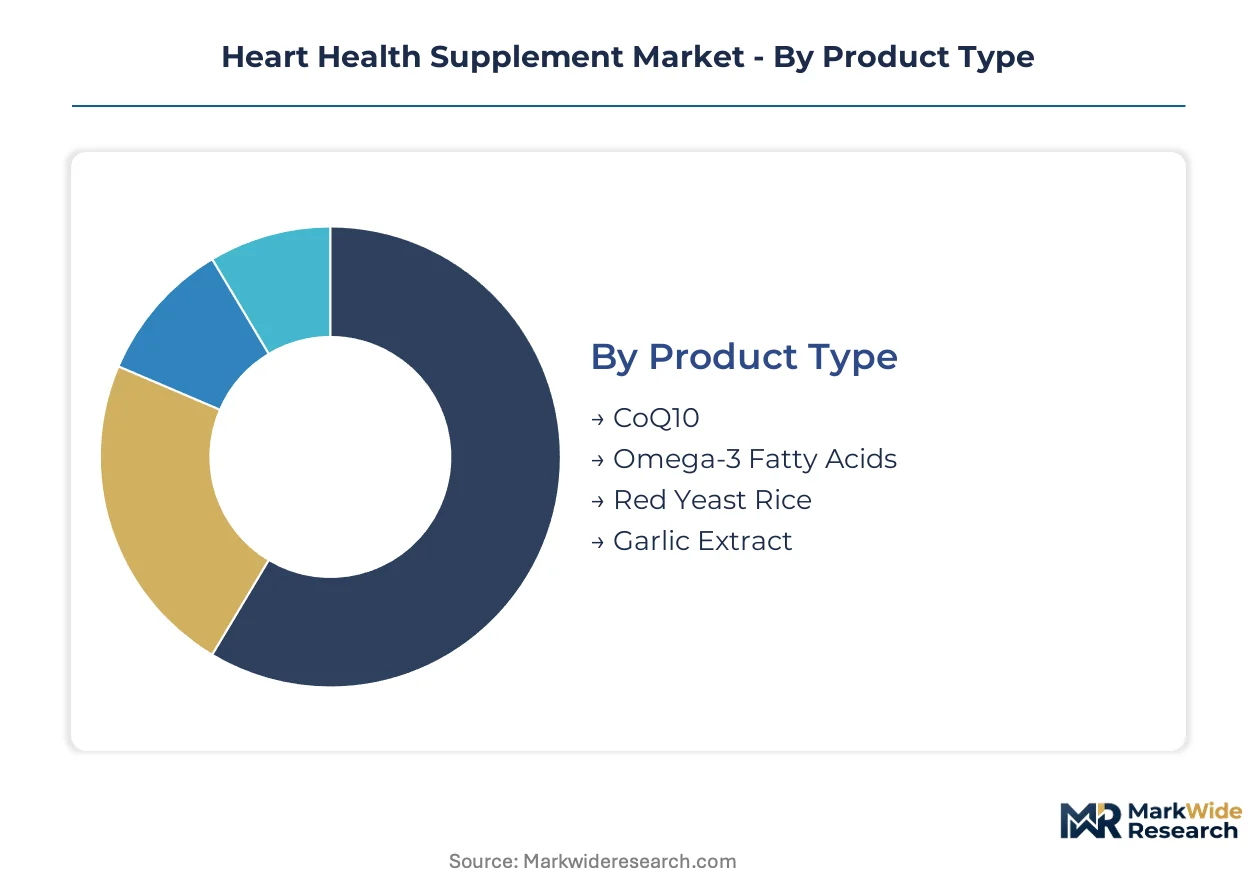
Channel dynamics in heart health supplements diverge sharply by segment—omega-3 concentrates flow through pharmacy chains, gummies capture direct-to-consumer velocity, and fermented botanicals concentrate in specialty clinician networks. Understanding these pathway distinctions enables targeted distribution investment and margin defense.
Product Type:
Pharmacy-adjacent channels favor clinically credentialed formats, while mass retail commoditizes standard fish oils and direct-to-consumer subscriptions capture novel bioactives.
- Omega-3 Fatty Acids:EPA and DHA concentrates derived from anchovy, sardine, and algal biomass dominate prescription-adjacent positioning. United States pharmacy chains and cardiologist-dispensed protocols drive volume concentration, though Peruvian fishery quotas constrain raw material security.
- CoQ10:Ubiquinone and ubiquinol variants serve statin-associated myopathy management and mitochondrial support applications. Liposomal encapsulation variants command premium tiers through enhanced bioavailability claims, with cardiologist-recommended absorption protocols accelerating adoption in integrated preventive cardiology programs.
- Red Yeast Rice:Monacolin K-containing fermented botanicals target statin-intolerant patient populations seeking non-prescription lipid management. FDA NDI notification friction delays novel variant launches.
- Garlic Extract:Allicin-standardized formulations pursue EFSA Article 13.1 health claim authorization for endothelial function endpoints. European formulators redirect R&D toward mechanistic clinical trials.
By volume, Omega-3 Fatty Acids leads. By growth pace, Red Yeast Rice is climbing the fastest amid statin intolerance prevalence.
Delivery Mode:
Cost tier stratification separates premium absorption-engineered formats from commodity softgels, with palatability premiums capturing younger demographics.
- Capsules:Softgel and hard-shell formats remain the volume backbone, with enteric-coated variants commanding margin premiums for gastric bypass patients and sensitive digestive systems. Standard oil-based softgels face compression as liposomal and emulsified alternatives capture clinical recommendation share.
- Gummies:Palatability-engineered compliance formats capture subscription-model velocity among demographics averse to pill burden. United States direct-to-consumer channels and mass retail placement drive expansion, though sugar content limits cardiologist endorsement.
- Powders:Bulk active concentrates serve compounding pharmacies and functional food integration. Sports nutrition crossover applications expand addressable use cases.
- Liquids:Emulsified and liposomal suspensions target pediatric and geriatric populations with swallowing difficulties. Unit economics constrain mass-market penetration.
Capsules maintain volume leadership. Gummies gain share fastest through palatability-driven compliance expansion.
End User:
Application severity determines channel selection—acute risk management flows through clinical recommendation, while wellness maintenance concentrates in self-directed retail.
- Seniors:Polypharmacy-aware populations seeking endothelial function and oxidative stress modulation drive demand for standardized, drug-interaction-tested formulations. Japan and Germany outpatient chronic disease management protocols accelerate adoption.
- Adults:Primary prevention-focused consumers with moderate cardiovascular risk profiles populate mass retail and pharmacy self-selection aisles. Price sensitivity constrains premium tier penetration.
- Health-Conscious Individuals:Wellness-optimization seekers without diagnosed conditions pursue preventive protocols through subscription and specialty retail. Algal omega-3 sourcing satisfies vegan positioning requirements.
- Athletes:NSF Certified for Sport program compliance gates entry for competitive use cases. Cardiac output optimization and recovery positioning expand beyond traditional cardiovascular risk framing.
Seniors dominate current volume. Health-Conscious Individuals expand most quickly through subscription channel maturation.
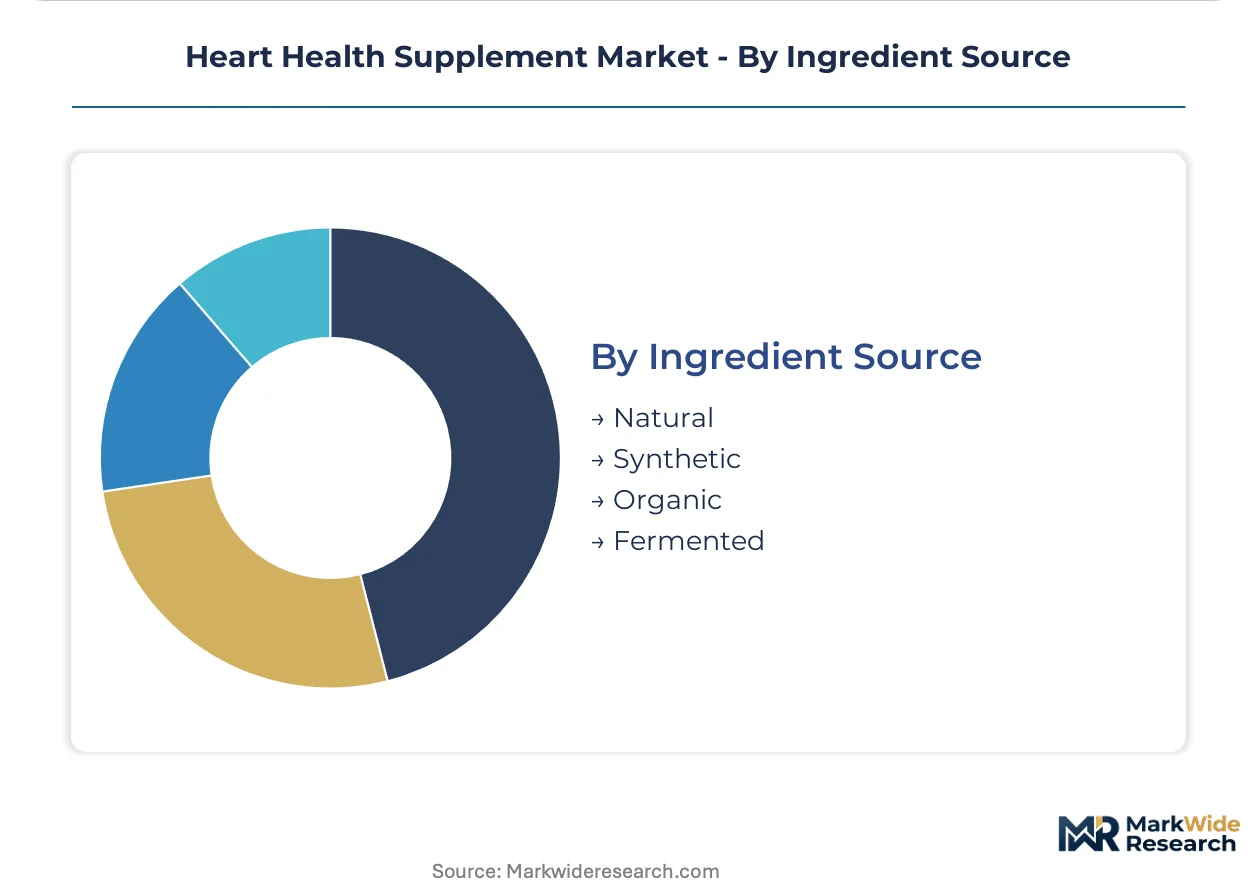
Ingredient Source:
Supply concentration and certification tier differentiate positioning—marine extraction clusters concentrate in South America, while fermentation capacity localizes in European and Asian biotechnology hubs.
- Natural:Marine-derived omega-3 and botanical extracts anchor clean-label positioning, though fishery quota volatility and climate stress concentrate input risk. Third-party sustainability certification commands retail placement.
- Fermented:Red yeast rice and precision-fermented bioactives enable statin-content standardization exceeding pharmacopeial minimums. Italian and Spanish producers lead quality tier consolidation.
- Organic:Certified supply chains satisfy premium channel gatekeeping requirements, with algal cultivation expanding certified DHA availability beyond marine dependence.
- Synthetic:Cost-optimized ubiquinone and standardized actives serve price-sensitive mass-market positioning, though clinical credibility gaps constrain cardiologist recommendation.
Natural sources lead by volume. Fermented ingredients gain fastest through statin-alternative formulation demand and standardization protocol advancement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's evolving New Dietary Ingredient notification requirements are reshaping compliance burdens for novel formulations. Demand concentrates in the United States, where direct-to-consumer supplement channels and cardiologist-adjacent wellness protocols drive category penetration. Senior consumers represent the fastest-expanding end-user cohort as preventive cardiovascular care gains traction among aging populations.
United States
Cardiologist-adjacent wellness programs are normalizing supplement co-prescription alongside statin therapy. The FDA's Current Good Manufacturing Practice regulations and NDI notifications govern market entry. Metropolitan healthcare systems with integrated preventive cardiology programs in Boston and Minneapolis accelerate professional recommendation as a prerequisite for premium adoption.
Germany
Outpatient chronic disease management protocols shift healthcare systems toward endothelial function modulators for senior populations. EFSA health claims authorization shapes European formulation strategies for cholesterol reduction substantiation. The Baden-Württemberg biotechnology cluster hosts precision-fermented red yeast rice producers advancing statin-content standardization protocols.
Japan
Aging demographic concentration drives demand for oxidative stress modulation among polypharmacy-aware populations. METI standards influence quality tier consolidation for mitochondrial support applications. The Kanto region around Tokyo anchors manufacturing scale for liposomal encapsulation variants targeting enhanced bioavailability positioning.
Italy
EFSA's ongoing evaluation of Article 13.1 health claims for polyphenol-rich extracts forces abandonment of general cardiovascular wellness language. Fermented red yeast rice producers respond with mechanistic clinical trial investments exceeding pharmacopeial requirements. The Emilia-Romagna fermentation hub concentrates statin-alternative formulation capacity for European export.
Australia
Health-conscious individuals pursue preventive protocols through subscription channel maturation outside pharmacy gatekeepers. The TGA's complementary medicine regulations govern label claim substantiation for algal omega-3 sourcing. Sydney and Melbourne direct-to-consumer brands capture recurring revenue streams through palatability-engineered gummy formats.
Heart Health Supplement Market Competitive Landscape
Listed leaders compete with private specialists across regulatory affairs infrastructure and manufacturing scale dimensions. The vendor base fragments across pharmaceutical-adjacent conglomerates, dedicated supplement formulators, and direct-to-consumer specialists. Three archetypes dominate: clinical credibility anchors leveraging pharmaceutical heritage, manufacturing scale players controlling cost structures across delivery modes, and subscription-native brands capturing younger demographics through palatability innovation. Competitive moves concentrate on certification timeline navigation and liposomal technology licensing.
Within the clinical credibility tier, Abbott Laboratories and Bayer AG exemplify pharmaceutical heritage deployment for cardiologist recommendation capture. NOW Foods occupies a position among manufacturing scale specialists sustaining multi-format production. Nordic Naturals anchors the marine-sourced omega-3 segment. These three represent distinct competitive vectors: prescription-adjacent positioning, cost structure control, and raw material supply security.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Bayer AG |
| Nestlé Health Science |
| NOW Foods |
| Amway Corp. |
| Thorne HealthTech Inc. |
| Nordic Naturals |
| Herbalife Nutrition Ltd. |
| Pfizer Inc. |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Peruvian fishery operators and omega-3 concentrate processors lock in both anchovy supply access and eighteen-month price visibility against quota volatility. These arrangements cascade downstream through pharmacy chain procurement, where volume commitments secure preferential tier placement for clinically credentialed formulations.
Pricing Analysis
Certification level creates the primary spread between NSF Certified for Sport premiums and standard softgel economy tiers. Three-tier pricing structure across premium, standard, and economy levels segments by bioavailability engineering and third-party verification. Pricing pressure stems from algal DHA substitution threatening marine-source value pools. Price-sensitive mass retail consumers drive commoditization, while cardiologist-recommended absorption protocols sustain premium tier inelasticity.
Supply Chain Analysis
Strategic stockpile preferences dominate red yeast rice procurement, with Italian and Spanish fermentation hubs maintaining six-month monacolin K inventories against FDA NDI notification delays. Raw material sourcing concentrates in Peru, Chile, and coastal China for marine and algal biomass extraction. Supply chain risk centers on single-source vulnerability for liposomal phospholipid inputs. Distribution runs through pharmacy chains, direct-to-consumer subscriptions, and specialty clinician networks in tiered channel access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cardiologist-adjacent wellness protocols are creating platform-economics inflection, where professional recommendation engines interoperate with pharmacy dispensing systems and subscription replenishment platforms to capture recurring patient relationships.
For Market Incumbents: Shield manufacturing scale advantages by securing backward integration into Peruvian fishery quota allocations and liposomal phospholipid supply. Prioritize NSF International certification timeline compression to outpace mid-tier formulators facing verification delays. Defend against algal DHA substitution by anchoring clinical credibility in prescription-adjacent EPA validation.
For New Entrants and Emerging Players: Lead with palatability-engineered gummy formats in direct-to-consumer subscription channels, where younger demographics exhibit lowest pill burden tolerance. Target health-conscious individuals seeking vegan-positioned algal omega-3 alternatives. Capture cardiologist attention through enhanced bioavailability clinical data packages.
For Investors and Strategic Acquirers: Fermentation-capable botanical specialists with EFSA health claim authorization progress represent the highest-conviction acquisition archetype. Long-term viability hinges on regulatory affairs infrastructure depth and mechanistic clinical trial investment. Watch for FDA guidance on structure-function claim enforcement thresholds as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Liposomal Technology Licensing | CoQ10 bioavailability claims capture cardiologist recommendation share from oil-based incumbents. |
| EFSA Health Claim Authorization | Garlic-derived allicin formulations unlock premium European positioning through endothelial function substantiation. |
| Direct-to-Consumer Channel Expansion | Subscription replenishment models bypass pharmacy gatekeepers to capture recurring revenue streams. |
| Precision Fermentation Scale-Up | Red yeast rice producers in Italy advance statin-content standardization exceeding pharmacopeial minimums. |
| Regulatory Affairs Infrastructure Buildout | Former FDA staffer expertise concentration enables faster NDI notification navigation for novel bioactives. |
Research Methodology
A spread of perspectives from regulatory affairs directors at pharmaceutical-adjacent supplement firms, cardiologists in integrated preventive cardiology programs, procurement managers at pharmacy chains, and direct-to-consumer brand operators converged on the working assumptions. These primary insights combined with secondary validation from FDA NDI notification databases, EFSA Article 13.1 health claim submissions, NSF International certification records, and Peruvian fishery quota disclosures. Bottom-up volume modeling and top-down value reconciliation triangulated market sizing.
Segmentation dimensions modeled include product type, delivery mode, end user cohort, and ingredient source across the analysis window. CAGRs derived from regression analysis against demographic aging trajectories and preventive cardiology protocol adoption curves. Forecast inputs incorporated EPA prescription consolidation effects and algal DHA technology cost curves.
The analysis sits within stated boundaries; outcomes outside sustained FDA enforcement continuity or Peruvian fishery quota stability would require recalibration. Forecasts reflect assumptions on cardiologist recommendation normalization and subscription channel maturation velocity. Revision becomes warranted when NDI notification processing timelines or EFSA health claim authorization throughput crosses material threshold shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Global Docosahexaenoic Acid (DHA) Market
Nutritional Supplements
Italy Whey Protein Market
Nutritional Supplements
Europe Amino Acid in Dietary Supplements Market
Nutritional Supplements
Global Nutraceutical Ingredients Market
Nutritional Supplements
Bovine Lactoferrin Market
Nutritional Supplements
Global Beta Glucan Market
Nutritional Supplements
Hydroxymethylbutyrate (HMB) Market
Nutritional Supplements
Nicotine Gum Market
Nutritional Supplements
Spirulina Powder Market
Nutritional Supplements
Botanical Supplements Market
Nutritional Supplements
Testosterone Booster Market
Nutritional Supplements
Diet Shakes Market
Nutritional Supplements
Global Nootropics Brain Supplements Market
Nutritional Supplements
Australia Nutraceuticals Market
Nutritional Supplements
Garlic Supplements Market
Nutritional Supplements
Asia-Pacific Dietary Supplement Market