
 Pomegranate Peel Polyphenol Complex Market | 2026-2036
Pomegranate Peel Polyphenol Complex Market Size, Share, and Industry Trends Forecast 2026-2036
Pomegranate Peel Polyphenol Complex Market Insights
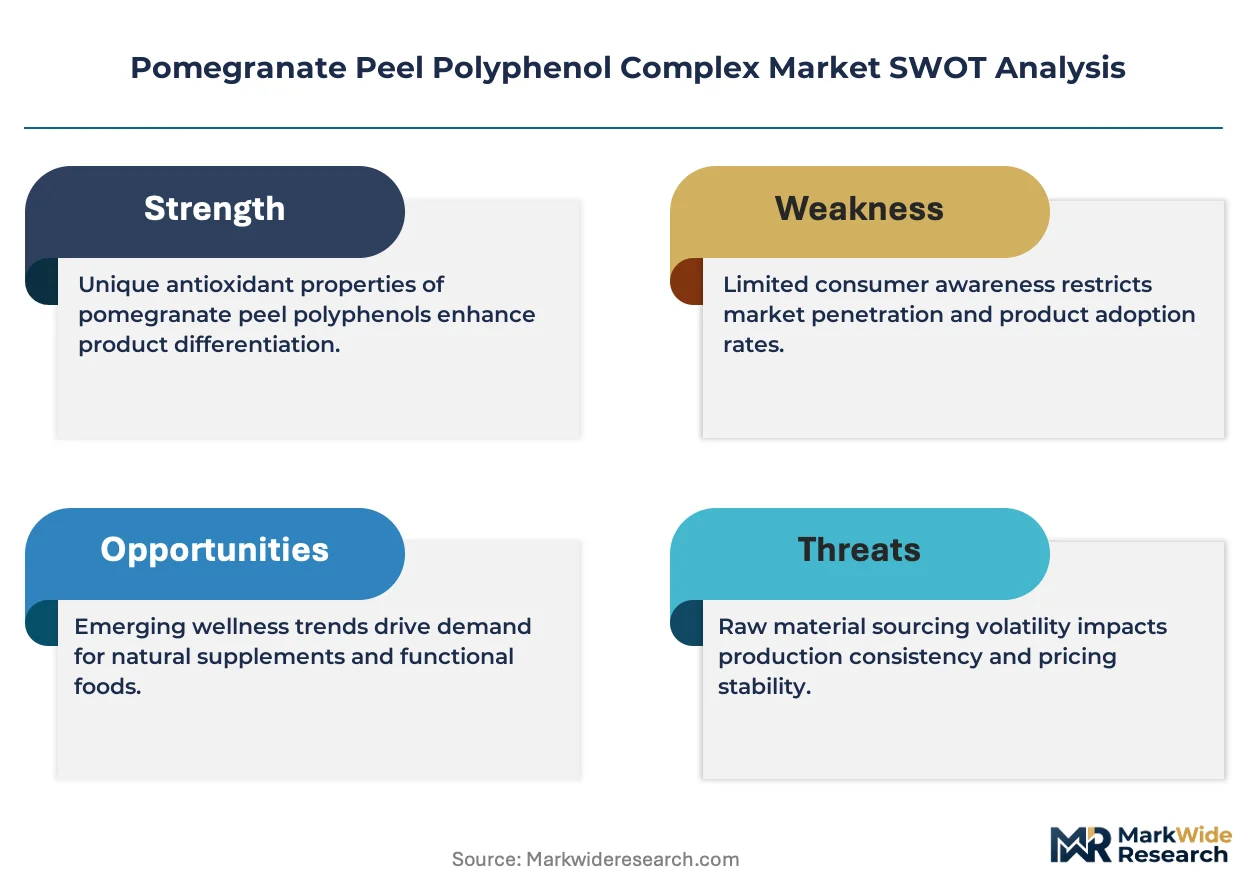
Ingredient value capture is reconfiguring from commodity extract supply toward finished-formulation partnerships. Sabinsa leverages vertically integrated cultivation in India to secure raw material consistency. Euromed anchors Mediterranean sourcing networks for hydroxytyrosol-adjacent polyphenol portfolios. Indena specializes in phytosome delivery systems that enhance bioavailability for nutraceutical clients.
Pomegranate peel polyphenol complex comprises ellagitannins, punicalagins, and ellagic acid extracted from discarded pericarp tissue, typically standardized to 40-90% total polyphenol content via solvent or supercritical CO2 processing for antioxidant, anti-inflammatory, and antimicrobial applications in consumer products. Extract Powder commands the largest revenue share among product types due to stability and dosing precision in capsule and tablet formats. Dietary Supplements represents the fastest-growing application segment as consumers shift from synthetic vitamins toward plant-derived alternatives with clinically traceable actives.
EFSA Novel Food authorization requirements and EU REACH compliance on extract solvent residues determine market access for European suppliers, while FDA GRAS self-affirmation and New Dietary Ingredient notifications govern US commercialization pathways. India's FSSAI and CDSCO regulate ingredient imports and health claim substantiation for domestic nutraceutical and pharmaceutical use. Stakeholders must monitor evolving extraction solvent restrictions and adapt substantiation dossiers to jurisdiction-specific safety and efficacy thresholds.
Market Dynamics
Clean-label formulation mandates from EFSA and FDA are compressing synthetic antioxidant substitution timelines, forcing extract suppliers to validate polyphenol stability under accelerated shelf-life protocols before securing finished-product partnerships.
Growth Catalysts
- EFSA Novel Food pathway streamlining:Accelerated safety dossier templates for botanical extracts reduce authorization timelines from thirty-six to eighteen months, enabling faster European market entry for standardized pomegranate peel formulations.
- Cosmeceutical anti-aging applications:Dermatology brands in Germany incorporate punicalagin-rich complexes into topical serums, driving demand for cosmetic-grade extract specifications with sub-50ppm solvent residues.
- Supercritical CO2 processing diffusion:Equipment cost reductions below 2M EUR per production line enable mid-scale Indian processors to achieve pharmaceutical-grade extraction without thermal degradation of ellagitannins.
Market Restraints
- Raw material seasonality:Indian pomegranate harvest concentration between October and January creates six-month supply windows requiring working capital-intensive inventory buildups.
- EU REACH solvent residue thresholds:Methanol and acetone limits below 10ppm in final extracts force processors to deploy costly ethanol-only extraction trains with 15-20% yield penalties.
- Synthetic antioxidant price floors:Butylated hydroxytoluene and tertiary butylhydroquinone maintain 60-70% cost advantages over botanical alternatives in mass-market food preservation applications.
Strategic Opportunities
- US GRAS self-affirmation pathway:FDA's notification-exempt structure for ingredients with documented consumption history allows rapid commercialization without pre-market approval delays.
- Pharmaceutical drug-interaction studies:CYP450 enzyme inhibition profiling opens prescription adjuvant positioning for polyphenol complexes in oncology supportive care protocols.
- Direct-to-practitioner distribution:Functional medicine clinics bypass traditional supplement retail markup structures, capturing 40-50% higher per-unit economics for clinically dosed extract protocols.
Industry Challenges
- Bioanalytical method standardization:Punicalagin quantification protocols vary between HPLC-UV and UPLC-MS platforms, creating inter-laboratory certificate-of-analysis disputes that delay batch releases.
- Phytosome formulation scale-up:Phospholipid complex manufacturing requires sterile processing environments with 10,000-class cleanroom specifications that extract-only suppliers lack in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pomegranate Peel Polyphenol Complex Market |
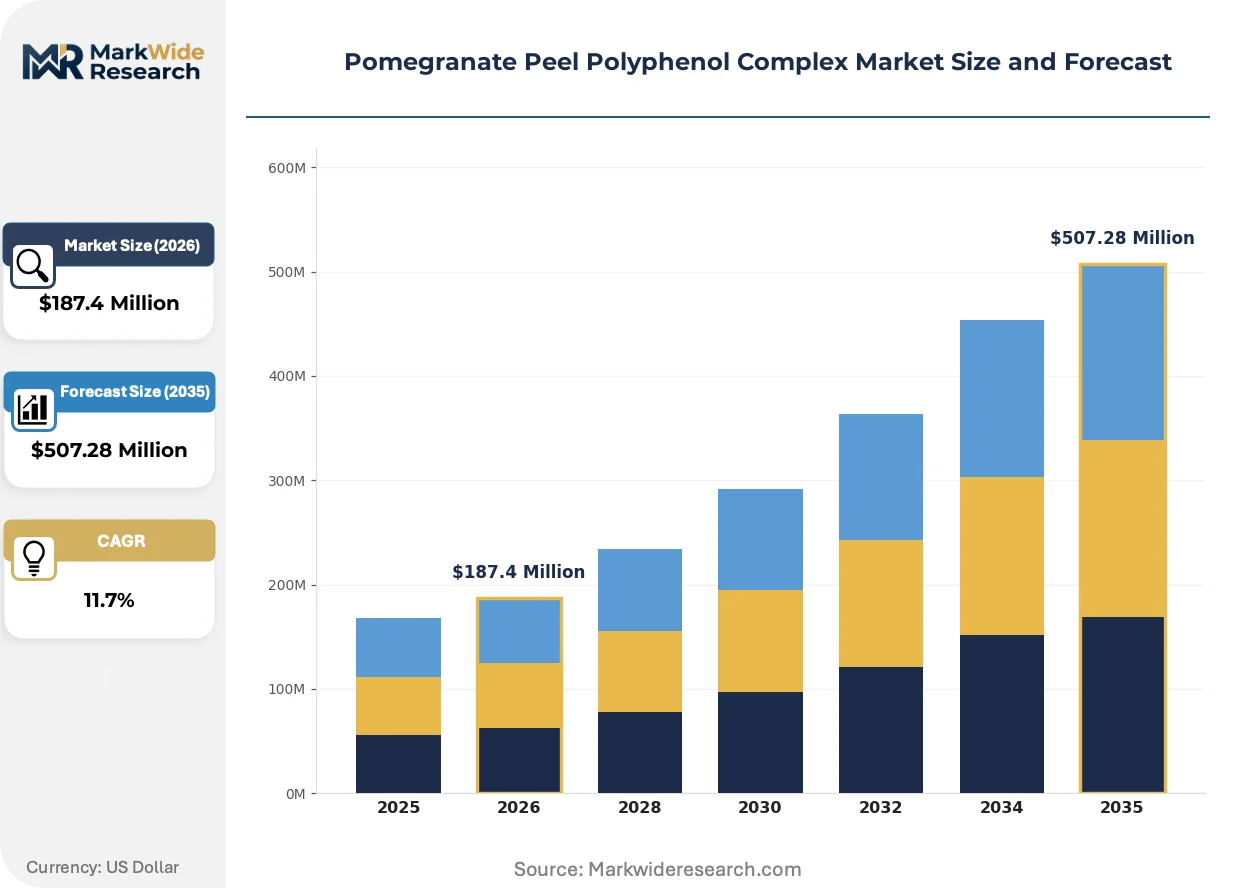
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extract Powder, Liquid Concentrate, Standardized Powder, Granules Application: Cosmetics, Nutraceuticals, Functional Beverages, Dietary Supplements End User: Personal Care Manufacturers, Food Processors, Pharmaceutical Firms, Beverage Producers Packaging Type: Multi-layer Bags, Bottles, Sachets, Bulk Containers |
| Companies Covered | Layn Natural Ingredients, Sabinsa, Euromed, Arjuna Natural, Botanic Healthcare, Indena, Verdure Sciences, Symrise, Croda Beauty, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pomegranate Peel Polyphenol Complex Market Trends and Innovations
Digital twin modeling of extraction kinetics is compressing process development cycles while regulatory pre-submission platforms are virtualizing compliance workflows. These shifts are reconfiguring how botanical suppliers validate and commercialize standardized actives.
Supercritical CO2 extraction with integrated in-line NIR spectroscopy is virtualizing real-time polyphenol monitoring during processing. Nutraceutical contract manufacturers in Germany and India adopt these systems to eliminate offline HPLC bottlenecks. The technology is virtualizing quality assurance labor costs while enabling continuous rather than batch production economics.
EFSA's 2023 updated guidance on botanical safety assessment requires extended ninety-day subchronic toxicity studies for novel delivery formats. European extract suppliers now front-load toxicology investment before formulation partnerships. Dietary supplement brands targeting EU member states delay launch timelines by twelve to eighteen months to accommodate revised dossier requirements.
Practitioner-channel purchasing concentrates demand among integrative medicine networks that bypass traditional retail distribution. North American naturopathic clinics and European pharmacy-affiliated nutritionists now specify third-party tested extracts with published pharmacokinetic data. This channel rotation is most pronounced in California and Bavaria where licensed practitioner density exceeds national averages by 3:1.
Pomegranate Peel Polyphenol Complex Market Segmentation
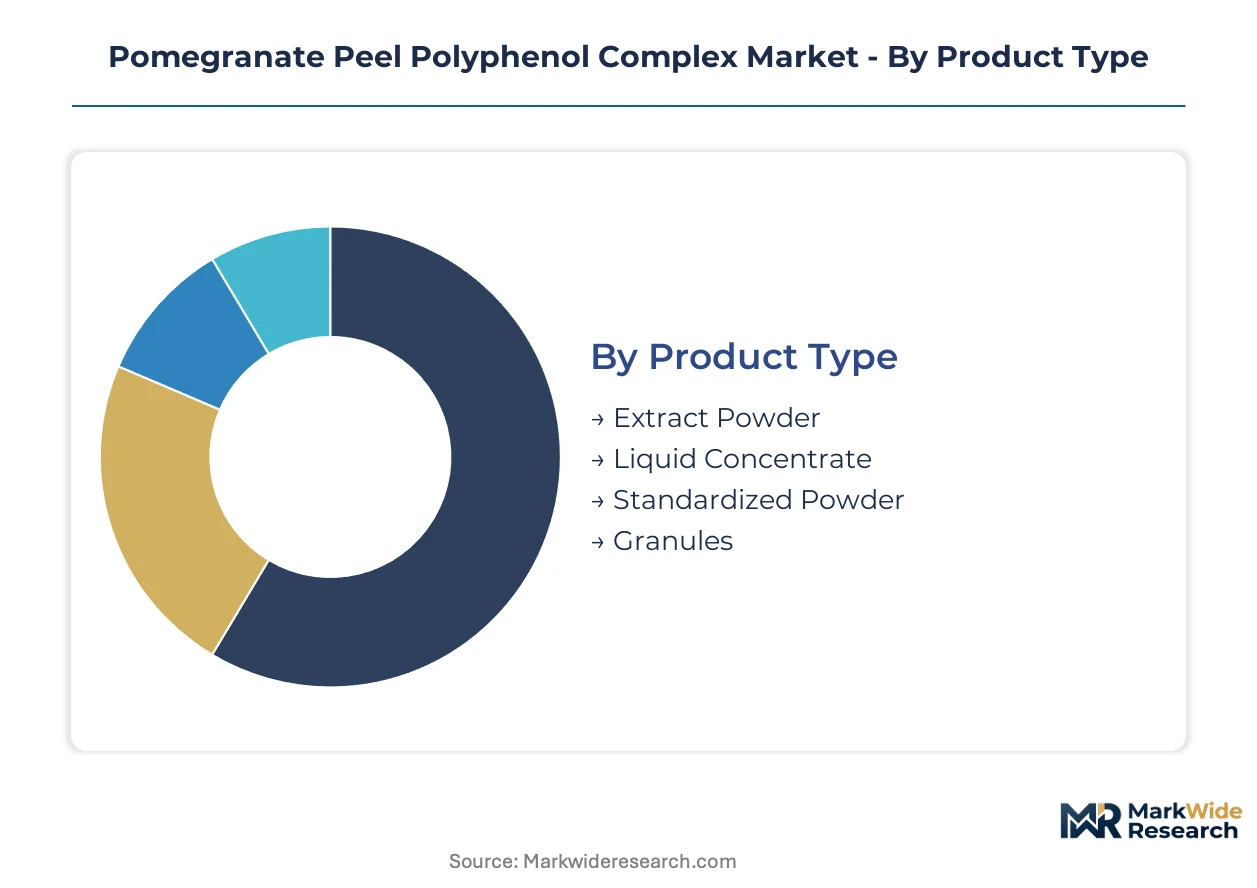
Pomegranate peel polyphenol complex markets fragment across extraction formats, end-use applications, and customer procurement patterns. Each segment carries distinct specification requirements, regulatory burdens, and margin profiles that determine supplier positioning strategies.
Product Type:
Inventory velocity varies dramatically across formats, with liquid concentrates turning every 45-60 days while standardized powders sit 90-120 days awaiting pharmaceutical qualification batches.
- Extract Powder:Spray-dried or vacuum-dried matrices containing 40-90% total polyphenols by spectrophotometric assay. German nutraceutical contract manufacturers and Indian export processors dominate procurement, driven by capsule-filling line compatibility and 24-month ambient stability.
- Liquid Concentrate:Aqueous or hydroalcoholic solutions standardized to 20-40% punicalagin content with potassium sorbate preservation. Functional beverage formulators in California and Bavaria favor this format for direct tank addition without reconstitution steps.
- Standardized Powder:Chromatographically calibrated batches with certificate-of-analysis traceability to reference standards. Pharmaceutical firms specify this grade for investigational new drug applications requiring batch-to-batch consistency.
- Granules:Agglomerated particles with improved flow properties for high-speed tableting operations. Direct-compression supplement manufacturers in Mumbai and Chicago procurement clusters specify this format to eliminate pre-blending steps.
Extract Powder anchors the volume base while Liquid Concentrate gains share at the steepest rate.
Application:
Margin structures diverge sharply across end-use categories, with pharmaceutical-adjacent positioning capturing 3-4x the per-kilogram realization of commodity food preservation.
- Dietary Supplements:Hard-shell capsules, softgels, and tablet formats delivering 200-500mg polyphenol equivalents per serving. US practitioner-channel brands and EU pharmacy-affiliated networks drive specification toward USP-verified and TGA-registered ingredient grades.
- Cosmetics:Topical serums, creams, and mask formulations leveraging punicalagin's collagenase inhibition and UV-protective properties. German dermatology brands and South Korean K-beauty manufacturers specify cosmetic-grade extracts with sub-50ppm solvent residues and heavy metal screening.
- Nutraceuticals:Positioned between food and pharmaceutical regulatory classifications, encompassing medical foods and functional ingredients for metabolic health protocols. EFSA health claim substantiation requirements shape formulation partnerships.
- Functional Beverages:Ready-to-drink shots, enhanced waters, and fermented bases incorporating polyphenol complexes for antioxidant positioning. Shelf-life stability challenges limit adoption to aseptic or high-acid systems.
Dietary Supplements command the highest absolute volumes while Cosmetics deliver the strongest margin expansion trajectory.
End User:
Procurement sophistication scales with regulatory exposure, with pharmaceutical and personal care manufacturers imposing quality systems that exclude commodity-grade suppliers.
- Pharmaceutical Firms:Require DMF-available extracts with documented CYP450 interaction profiles and cGMP manufacturing site audits. Oncology supportive care and metabolic syndrome adjuvant protocols represent the primary demand concentration.
- Personal Care Manufacturers:Specify cosmetic-grade materials with ISO 16128 natural origin certification and preservative-free options for clean-label positioning. German and French formulators lead specification complexity.
- Food Processors:Natural antioxidant replacement for synthetic BHT and TBHQ in lipid-rich products. Price sensitivity limits penetration to premium-positioned organic and clean-label lines.
- Beverage Producers:Demand water-soluble, flavor-neutral extracts compatible with high-speed aseptic filling. Heat stability requirements exclude standard tannin-rich preparations.
Personal Care Manufacturers anchor premium pricing while Pharmaceutical Firms are expanding most quickly as drug-interaction databases mature.
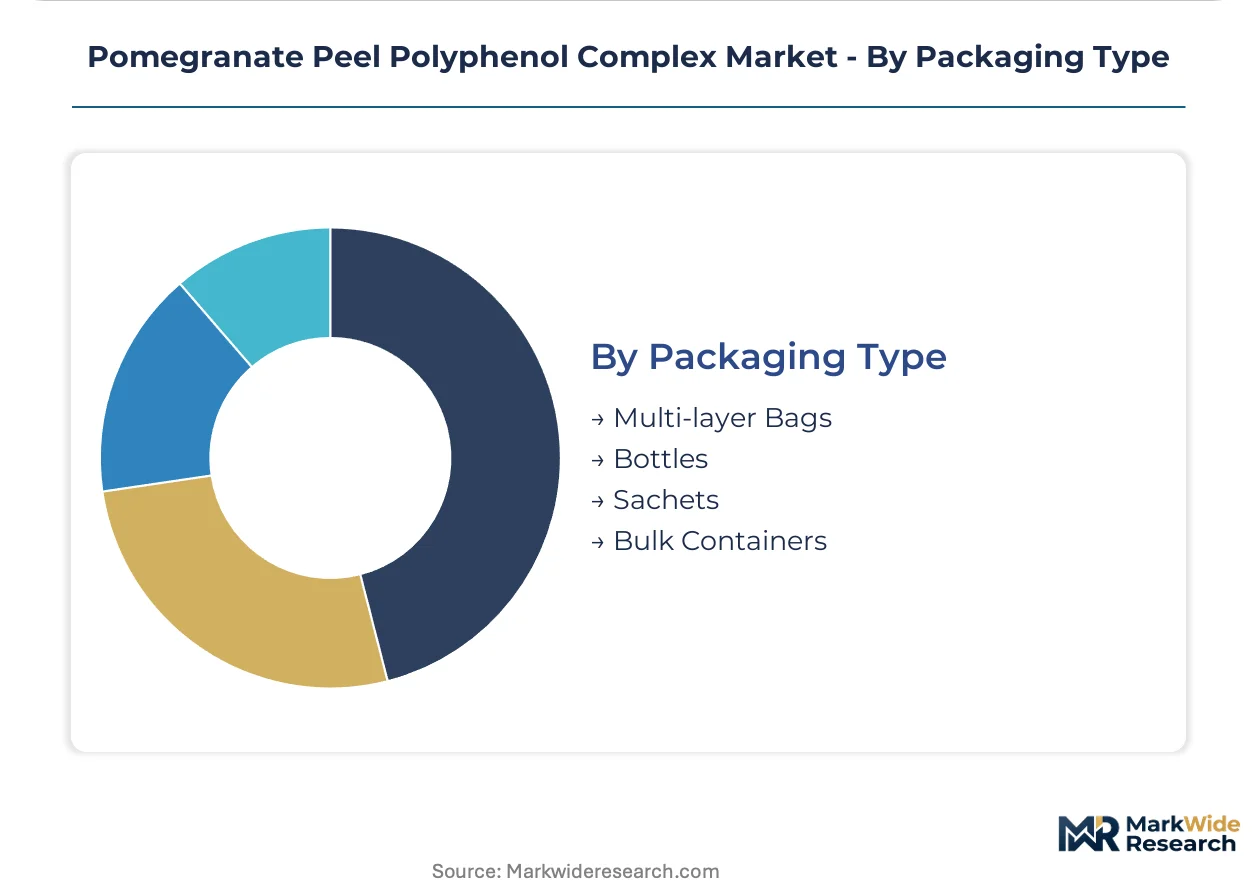
Packaging Type:
Packaging selection tracks customer scale and contamination sensitivity, with bulk formats dominating industrial procurement and unit-dose formats serving formulation laboratories.
- Multi-layer Bags:Aluminum-laminated constructions with nitrogen flushing provide 24-month stability for ambient warehouse storage. Indian and Chinese export processors standardize on 25kg formats for ocean freight efficiency.
- Bulk Containers:Fiber drums and lined totes for pharmaceutical and large-scale beverage manufacturing. Just-in-time delivery contracts with German and US contract manufacturers minimize working capital requirements.
- Sachets:Single-use 5-50g portions for laboratory-scale formulation development and clinical trial material preparation. Sampling programs and R&D procurement drive this segment.
- Bottles:HDPE or amber glass containers with desiccant inserts for liquid concentrates and hygroscopic powders. Practitioner-channel and direct-to-consumer brands specify this format.
Multi-layer Bags carry the dominant shipment volumes while Sachets are climbing the fastest on sampling program expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian procurement clusters exhibit acute price sensitivity to raw material harvest cycles, while German pharmaceutical buyers absorb premium specifications without volume elasticity. This demand-elasticity contrast shapes supplier investment priorities across origin markets.
Germany
Cosmeceutical formulators in Bavaria drive punicalagin-rich extract demand for topical anti-aging serums. EFSA Novel Food authorization timelines compress from thirty-six to eighteen months under streamlined botanical extract pathways. Frankfurt-Rhine-Main logistics clusters enable just-in-time delivery to pharmaceutical contract manufacturers.
United States
Practitioner-channel brands in California specify third-party tested extracts with published pharmacokinetic data for functional medicine protocols. FDA GRAS self-affirmation allows rapid commercialization without pre-market approval delays for ingredients with documented consumption history. Greater Boston biotech corridors incubate oncology supportive care adjuvant applications.
India
Export processors in Maharashtra and Gujarat concentrate spray-dried extract production for European and North American nutraceutical contract manufacturers. FSSAI and CDSCO regulate ingredient imports and health claim substantiation for domestic pharmaceutical use. Working capital intensity spikes during October-January harvest windows requiring six-month inventory buildups.
China
Supercritical CO2 equipment manufacturers serve mid-scale processors seeking pharmaceutical-grade extraction capabilities. NMPA botanical drug regulations and GB standards on extract solvent residues determine market access for finished formulations. Yangtze River Delta chemical processing clusters integrate in-line NIR spectroscopy for real-time polyphenol monitoring.
France
Personal care manufacturers in Île-de-France specify ISO 16128 natural origin certification for clean-label cosmetic positioning. ANSM cosmetic ingredient safety assessments impose extended toxicology requirements on novel delivery formats. Lyon-based dermatology brands anchor demand for sub-50ppm solvent residue specifications.
Pomegranate Peel Polyphenol Complex Market Competitive Landscape
Capability concentration sits with phytosome delivery specialists; scale advantage sits with vertically integrated cultivation operators. The market structures around three tiers: botanical extract pure-plays, diversified ingredient houses, and captive pharmaceutical supply divisions. Strategic archetypes include Mediterranean-sourcing network anchors, Indian cultivation-backward integrators, and phospholipid complex formulation specialists. Dominant competitive moves encompass ethanol-only extraction train upgrades to meet EU REACH thresholds and sterile processing environment investments for phytosome scale-up.
Among Indian cultivation-integrated suppliers, Sabinsa and Arjuna Natural exemplify backward integration archetypes securing raw material consistency through captive agricultural operations. Euromed occupies a position representing Mediterranean-sourcing network specialists with hydroxytyrosol-adjacent polyphenol portfolios. Indena sits within the delivery-system tier, anchoring phytosome technology capabilities that enhance bioavailability for nutraceutical clients. These three patterns—captive supply, regional sourcing networks, and formulation technology—capture the competitive positioning spectrum.
| Leading Market Players |
|---|
| Layn Natural Ingredients |
| Sabinsa |
| Euromed |
| Arjuna Natural |
| Botanic Healthcare |
| Indena |
| Verdure Sciences |
| Symrise |
| Croda Beauty |
| Others |
Pricing and Supply Chain Analysis
Indian pomegranate harvest concentration between October and January concentrates raw material bargaining power among Maharashtra and Gujarat processors, pushing margin capture downstream toward German pharmaceutical buyers and California practitioner-channel brands that absorb premium specifications without volume elasticity.
Pricing Analysis
After-sales technical service and formulation partnership contracts drive lifetime value beyond commodity extract sales. Three-tier pricing structure across pharmaceutical-grade, nutraceutical-grade, and cosmetic-grade certifications anchors the market, with punicalagin content and solvent residue thresholds as primary differentiation levers. Cost compression in standard-grade powders is intensifying because mid-scale Indian processors deploy supercritical CO2 equipment to bypass ethanol-only yield penalties. Food processors exhibit acute price sensitivity, while oncology-supportive pharmaceutical firms show minimal elasticity.
Supply Chain Analysis
Pomegranate pericarp feedstock availability fluctuates with Indian agricultural cycles, drawing processors into six-month inventory accumulation patterns. Supply concentrates in India, Germany, and China, with extract production anchored in Maharashtra and Gujarat, formulation partnerships in Bavaria and Frankfurt-Rhine-Main, and supercritical equipment manufacturing in Yangtze River Delta clusters. Working capital intensity during harvest windows creates single-source vulnerability for European buyers dependent on October-January procurement. Distribution runs through nutraceutical contract manufacturers and direct-to-practitioner channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pomegranate peel polyphenol complex markets fragment across extraction format sophistication, creating niche entry points as EFSA Novel Food pathway streamlining accelerates botanical extract authorization timelines.
For Market Incumbents: Build formulation partnership moats through captive phytosome manufacturing capabilities and sterile processing environments with 10,000-class cleanroom specifications. Sabinsa and Euromed archetypes should deepen backward integration into Mediterranean and Indian cultivation networks to defend against mid-scale CO2 equipment adopters. Indena-type delivery-system specialists must lock in practitioner-channel exclusivity with published pharmacokinetic dossiers. For New Entrants and Emerging Players: Pursue white-space positioning in cosmetic-grade extracts with sub-50ppm solvent residue specifications, where German dermatology brands and South Korean K-beauty manufacturers face supply constraints. Functional beverage formulators in California and Bavaria represent the most penetrable application segment due to liquid concentrate format gaps. A direct-to-practitioner go-to-market angle bypasses retail markup compression and captures 40-50% higher per-unit economics. For Investors and Strategic Acquirers: Capital is best deployed toward Indian cultivation-backward integrators with captive agricultural operations and established FSSAI export credentials, positioned for multi-year horizon viability as EU REACH solvent restrictions tighten. The acquisition target archetype combines spray-dried extract production with existing EFSA Novel Food dossiers. Watch for inflection when supercritical CO2 equipment costs compress below 2M EUR per line, triggering mid-scale processor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Ethanol-Only Extraction Train Upgrade | EU REACH methanol and acetone thresholds below 10ppm force 15-20% yield trade-offs for market access. |
| Phytosome Manufacturing Scale-Up | Sterile processing environments with 10,000-class cleanroom specifications enable bioavailability-enhanced formulation partnerships. |
| Direct-to-Practitioner Channel Development | California and Bavaria integrative medicine networks bypass traditional retail markups for premium extract positioning. |
| Supercritical CO2 Equipment Deployment | Mid-scale Indian processors achieve pharmaceutical-grade extraction without thermal degradation of ellagitannins. |
| Novel Food Dossier Front-Loading | EFSA ninety-day subchronic toxicity requirements compress launch timelines for European market entry. |
Research Methodology
The analysis maps extraction format tiers, application segments, and regional procurement clusters, each validated through extraction technology directors, nutraceutical contract manufacturing procurement leads, EFSA regulatory affairs specialists, and functional medicine clinic formulators. Primary interviews with Indian export processors and German pharmaceutical buyers combined with secondary validation from CDSCO import records, EFSA Novel Food authorization databases, FSSAI regulatory filings, and customs trade data. Bottom-up segment sizing and top-down market triangulation cross-validated volume and value estimates.
Assumptions held fixed include EFSA Novel Food pathway streamlining timelines, EU REACH solvent residue thresholds, and FDA GRAS self-affirmation structures; variables tested across supercritical equipment cost curves, harvest yield volatility, and practitioner-channel penetration rates. Segmentation dimensions modeled encompass product type, application, end user, and packaging format across the projection horizon. CAGRs derived from segment-level demand elasticity and supply capacity buildout trajectories, with extract powder inventory velocity and liquid concentrate adoption curves as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity price cycles, ocean freight rate volatility, or currency fluctuation between INR and EUR would shift the trajectory. Forecasts reflect documented assumptions on regulatory pathway efficiency and equipment cost compression. Cross-checking against EFSA authorization database trends and Indian agricultural ministry harvest statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Carob Powder Market
Ingredients
Europe Edible Oil Market
Ingredients
Asia Pacific Vegetable Oil Market
Ingredients
United States Whey Protein Ingredients Market
Ingredients
North America Soy Protein Market
Ingredients
North America Rice Protein Ingredients Market
Ingredients
Asia Pacific Feed Yeast Market
Ingredients
Mussel Oil and Powder Market
Ingredients
Soy Protein Hydrolysate Market
Ingredients
Cosmetic Ingredients Market
Ingredients
Distiller's Dried Grains with Solubles (DDGS) Feed Market
Ingredients
North America Potato Protein Market
Ingredients
Yeast Peptide Market
Ingredients
Low-Fat Cocoa Powder Market
Ingredients
Hydrolysed Vegetable Protein (HVP) Market
Ingredients
Algae-Based Ingredients Market