
 Reduced Fat Dairy Market | 2026-2036
Reduced Fat Dairy Market Size, Share, and Industry Trends Forecast 2026-2036
Reduced Fat Dairy Market Analytics
Premium reduced fat dairy is decoupling from commodity-grade offerings on the basis of protein fortification, clean-label credentials, and grass-fed sourcing claims. Arla Foods leverages its cooperative farmer network to sustain consistent milk supply for value-added reduced fat cheese production. Danone differentiates through specialized fermentation protocols that preserve texture in low-fat yogurt formulations without artificial stabilizers.
Reduced fat dairy comprises milk, cream, cheese, and yogurt products processed to contain less than 2% milk fat through centrifugal separation, membrane filtration, or skimming, followed by standardization of protein and solids-not-fat content to maintain functional performance in cooking, baking, and direct consumption. The milk segment anchors volume throughput in supermarket and wholesale channels across North America and Europe, while yogurt leads margin generation through probiotic and high-protein premium extensions. The snacking application within dairy is expanding fastest as portable reduced fat cheese sticks and drinkable yogurts displace traditional confectionery in school and cafe environments.
The U.S. FDA enforces standardized identity requirements for reduced fat milk and cheese under 21 CFR 131 and 133, directly constraining formulation flexibility and label claims for domestic manufacturers. The European Commission's Farm to Fork Strategy and EFSA nutritional profiling criteria are reshaping permissible health claims and front-of-pack labeling across the EU-27, forcing reformulation investments. Stakeholders must monitor evolving divergence between FDA and EFSA fat-reduction thresholds as dual-market suppliers face escalating compliance complexity without harmonized standards.
Market Dynamics
The EU's Farm to Fork Strategy is compressing formulation timelines for reduced fat dairy manufacturers, forcing simultaneous compliance with tightening fat thresholds and front-of-pack nutritional labeling mandates across member states.
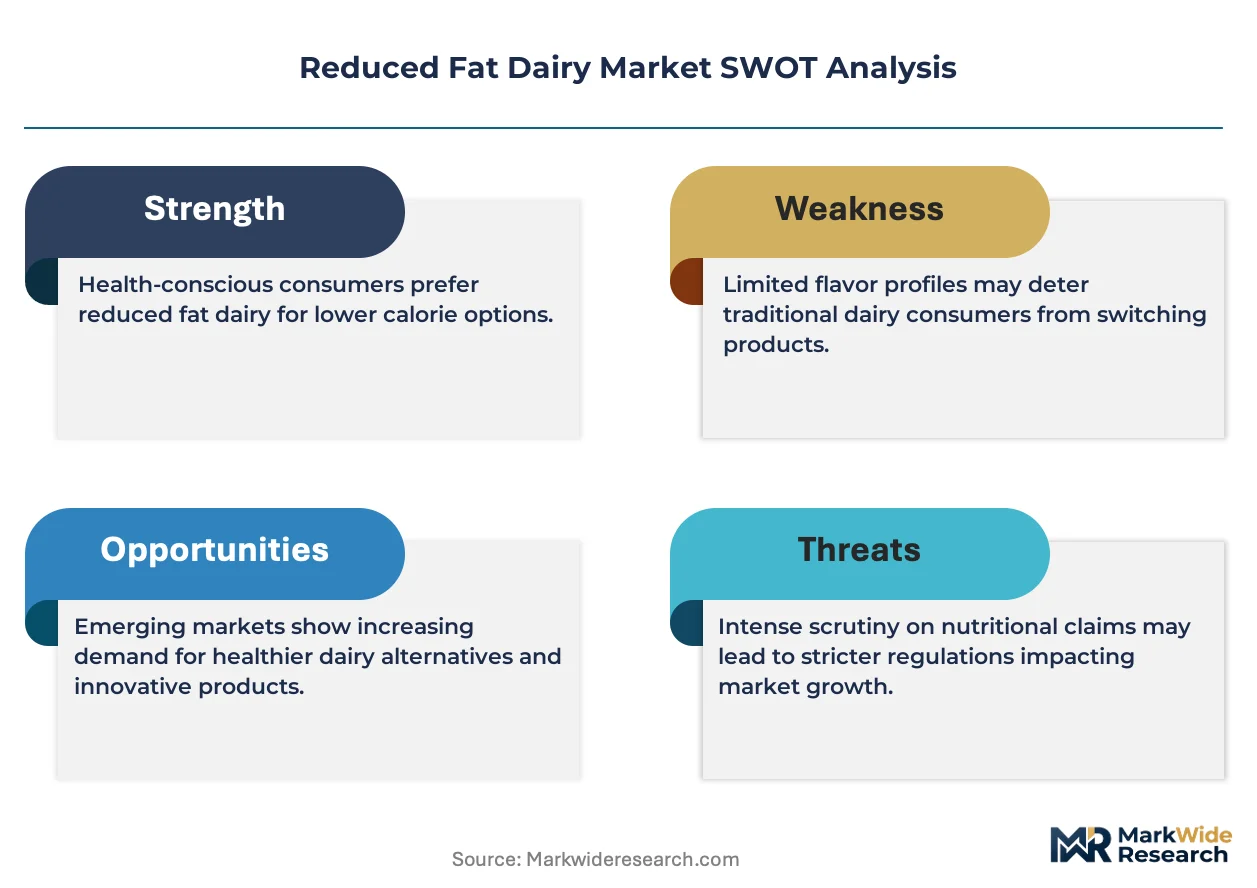
Growth Catalysts
- Protein Fortification Technology:Membrane filtration and ultrafiltration processes enable higher protein retention in low-fat formulations, preserving functional performance in cooking applications without artificial additives.
- EFSA Nutritional Profiling Criteria:The European Commission's evolving health claim permissions create competitive differentiation for products meeting stricter compositional standards.
- Germany:Health-conscious households in metropolitan clusters are elevating reduced fat yogurt and cheese to core dietary staples, driving private-label innovation in supermarket channels.
Market Restraints
- Skim Milk Powder Volatility:Input cost fluctuations for standardization ingredients compress margin predictability for value-added reduced fat cheese production.
- Cooperative Supply Concentration:Farmer-owned dairy networks in Denmark and the Netherlands control critical raw milk volumes, creating procurement bottlenecks for independent processors.
- Texture Degradation Limits:Current enzymatic modification protocols cannot fully replicate mouthfeel properties of full-fat equivalents in hard cheese categories.
Strategic Opportunities
- Drinkable Yogurt Formats:Portable reduced fat dairy beverages are displacing traditional confectionery in French and German school nutrition programs.
- Clean-Label Fermentation:Specialized bacterial cultures that preserve texture without stabilizers open premium positioning in organic retail channels.
- Grass-Fed Sourcing Claims:Pasture-based verification systems align with EU Green Deal sustainability metrics, unlocking green procurement contracts.
Industry Challenges
- Fermentation Specialist Scarcity:Dairy science expertise in low-fat culture development lags demand from expanding production lines.
- Dual Certification Complexity:Manufacturers supplying both FDA-regulated US markets and EFSA-governed EU channels face non-harmonized fat-reduction thresholds.
- Legacy Equipment Retrofit Costs:Centrifugal separation infrastructure requires substantial capital outlay to achieve membrane filtration compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reduced Fat Dairy Market |
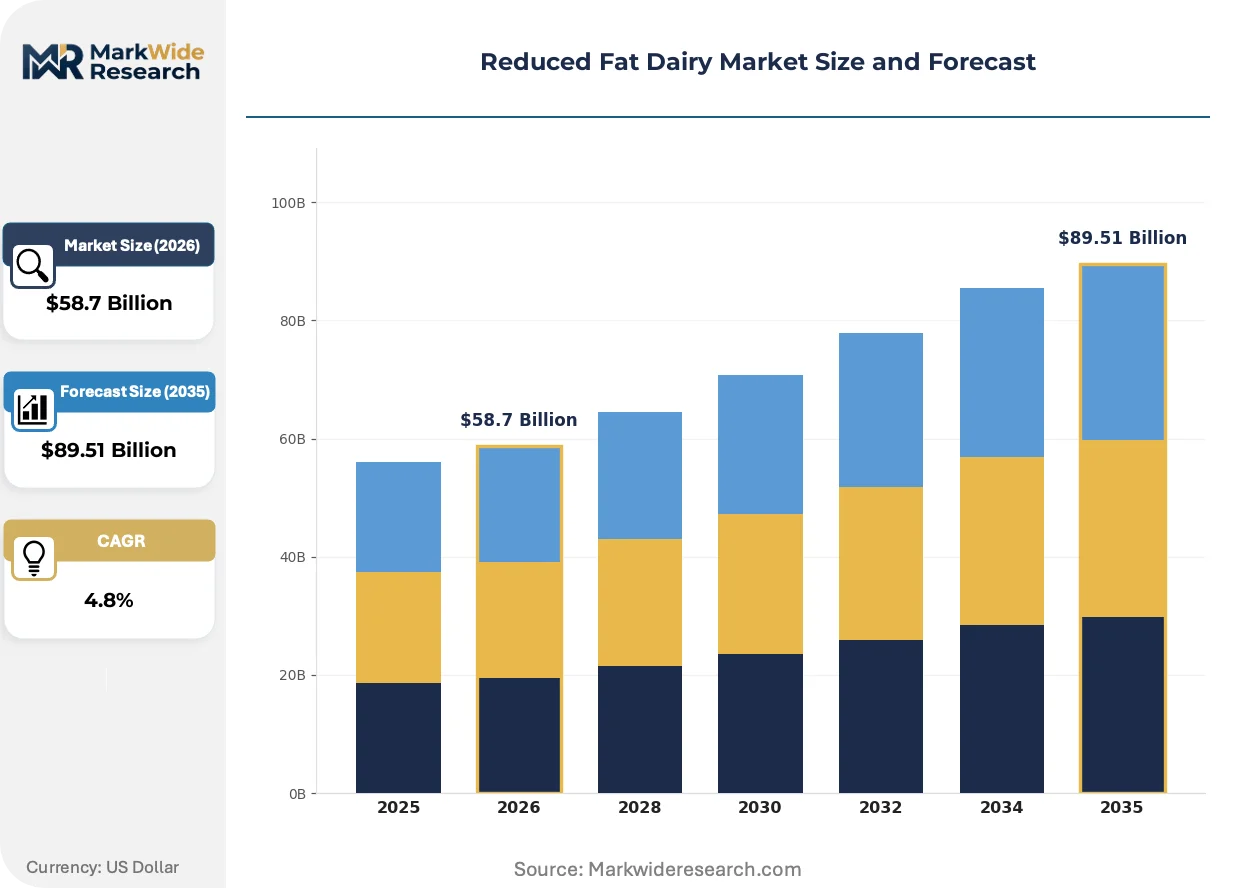
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $89.51 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cheese, Yogurt, Milk, Cream End User: Households, Restaurants, Cafes, Schools Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesale Application: Baking, Cooking, Snacking, Beverages |
| Companies Covered | Arla Foods, Dairy Farmers of America, Nestlé, Organic Valley, Saputo, Danone, Kraft Heinz, Lactalis, Fonterra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reduced Fat Dairy Market Evolving Landscape
Membrane filtration systems are rewriting the technical baseline for reduced fat dairy, enabling protein standardization that was previously unattainable through conventional skimming methods.
Ultrafiltration technology is integrating ceramic membrane modules into continuous processing lines, allowing simultaneous fat reduction and protein concentration. Mid-sized dairy cooperatives in France and the Netherlands are adopting these systems at accelerating rates. The technology is integrating premium reduced fat offerings with commodity-grade production economics, collapsing traditional tier boundaries.
REACH chemical safety protocols and the EU Green Deal's farm-level sustainability metrics are reshaping permissible processing aids and packaging materials for dairy products. Manufacturers must now document carbon intensity across the full milk supply chain to retain shelf placement in major retail banners. Organic reduced fat yogurt lines face the steepest compliance burden, driving consolidation among smaller processors.
School and workplace snacking channels are displacing traditional retail dominance for reduced fat cheese formats. Single-serve cheese sticks and drinkable yogurts are capturing share from chocolate and confectionery in German and French institutional procurement. This rotation is most visible in urban education districts where nutritional procurement mandates have tightened.
Reduced Fat Dairy Market Segmentation
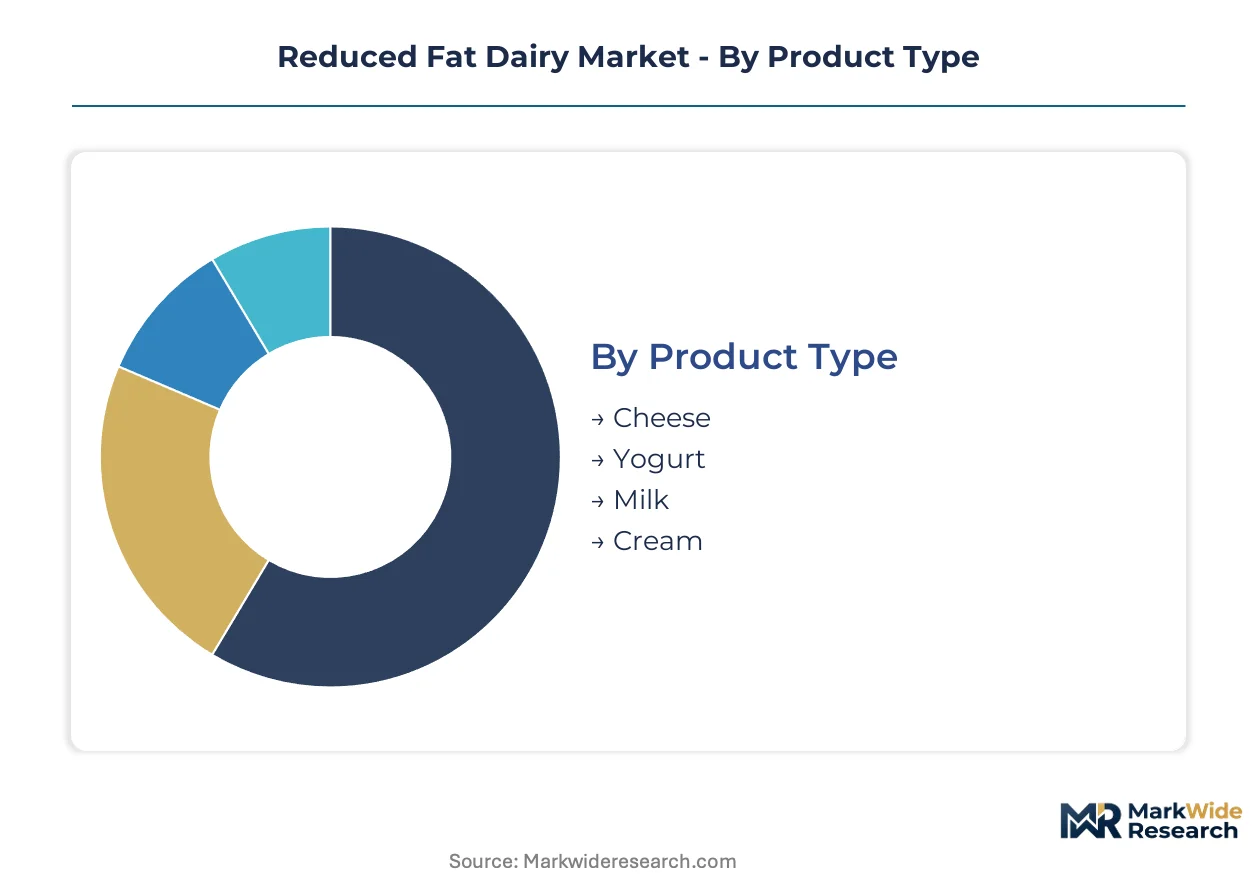
Reduced fat dairy markets fragment across four distinct axes that determine formulation priorities, margin structure, and channel access. Product type dictates processing technology investments. End user concentration shapes packaging formats and procurement relationships. Distribution channel selection governs shelf-life engineering and promotional spend. Application use cases drive protein fortification specifications and texture preservation requirements.
Product Type:
Milk anchors commodity throughput in retail and foodservice channels, while yogurt and cheese command premium positioning through functional claims and snacking convenience.
- Milk:Standardized to less than 2% milk fat through centrifugal separation or membrane filtration. Volume concentrates in North American and European supermarket private-label programs where EFSA nutritional profiling criteria constrain permissible health claims.
- Yogurt:Specialized fermentation protocols preserve texture without artificial stabilizers. Demand clusters in German and French metropolitan households elevating reduced fat variants to core dietary staples, with probiotic and high-protein extensions driving margin generation.
- Cheese:Enzymatic modification protocols attempt to replicate full-fat mouthfeel in hard cheese categories, though texture degradation limits persist in current technology.
- Cream:Functional performance in cooking and baking applications requires precise solids-not-fat standardization after fat reduction.
Volume placements concentrate in Milk; the faster expansion belongs to Yogurt.
End User:
Procurement patterns diverge sharply between institutional buyers with mandated nutritional standards and discretionary household purchasers responsive to clean-label positioning.
- Households:Health-conscious consumers in Germany and France drive private-label innovation in supermarket channels, with grass-fed sourcing claims unlocking green procurement contracts.
- Schools:Nutritional procurement mandates in urban education districts are tightening, displacing traditional confectionery with portable reduced fat cheese sticks and drinkable yogurts.
- Restaurants:Foodservice operators prioritize functional performance in cooking applications, demanding consistent protein retention across batch volumes.
- Cafes:Beverage-forward formats emphasize texture preservation in low-fat cream and milk applications for espresso-based drinks.
Institutional procurement in Schools is climbing the fastest; household discretionary spending maintains the revenue base.
Distribution Channel:
Channel selection determines packaging format, shelf-life requirements, and the feasibility of premium positioning through temperature-controlled logistics.
- Supermarkets:Private-label reduced fat lines compete directly with branded alternatives in Western European retail channels, with EFSA front-of-pack labeling mandates forcing simultaneous reformulation investments.
- Wholesale:Foodservice distributors require bulk formats with extended shelf-life specifications, constraining clean-label fermentation approaches that sacrifice stability.
- Online Retail:Direct-to-consumer channels enable subscription models for organic reduced fat yogurt lines, though cold-chain costs compress margins.
- Convenience Stores:Single-serve snacking formats capture impulse purchases, with drinkable yogurt displacing confectionery in grab-and-go occasions.
Supermarket placements dominate current volume; online subscription models show the steepest expansion trajectory.
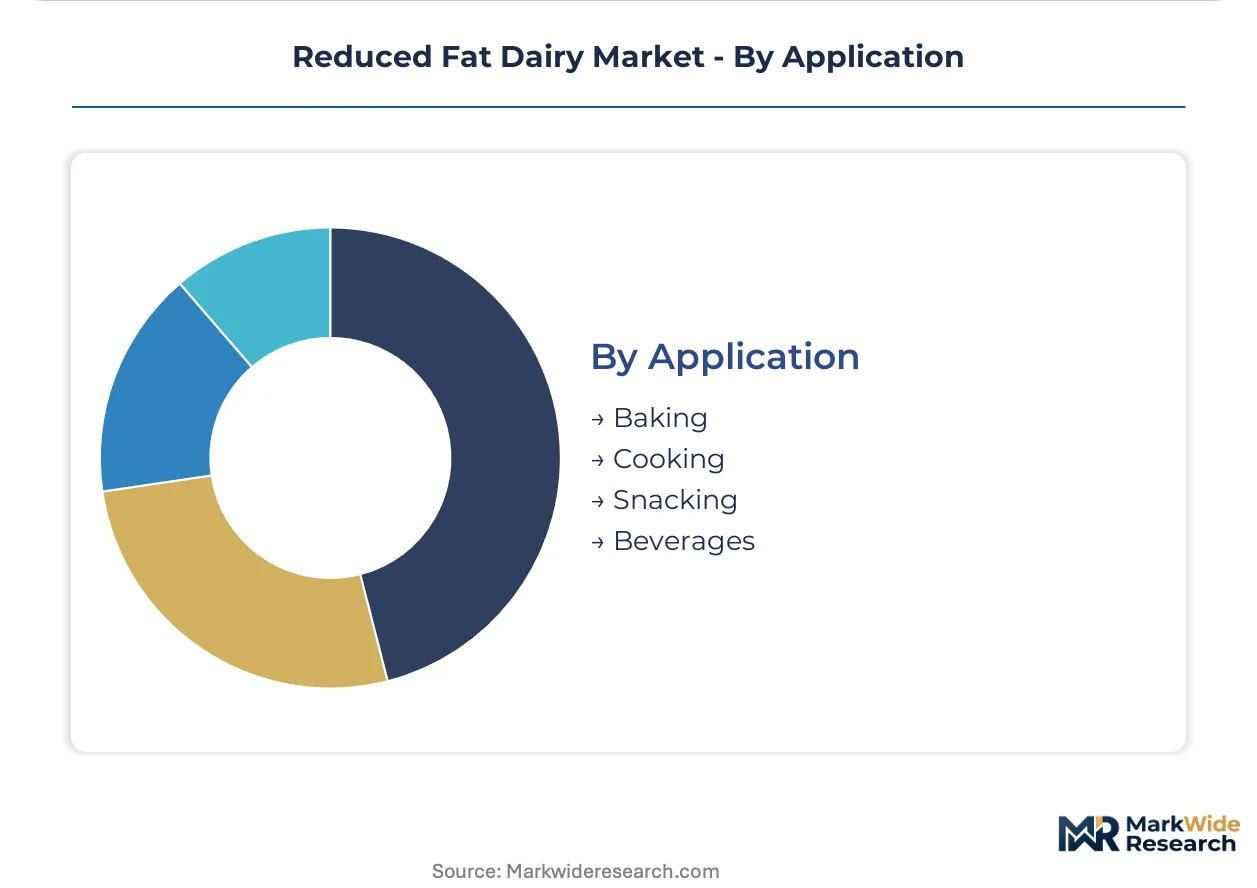
Application:
Use case determines the functional performance threshold for protein retention, emulsification stability, and thermal behavior under cooking stress.
- Snacking:Portable cheese sticks and drinkable yogurts displace traditional confectionery in school and workplace environments, with texture preservation critical to repeat purchase.
- Cooking:Sauce and soup applications demand heat-stable emulsification without fat-mediated mouthfeel, driving membrane filtration adoption for protein concentration.
- Baking:Maillard reaction performance and crumb structure depend on precise solids-not-fat standardization in reduced fat milk and cream inputs.
- Beverages:Coffee and smoothie applications require foaming stability and clean flavor profiles that challenge current low-fat cream formulations.
Cooking applications anchor industrial procurement volumes; snacking formats are gaining share fastest in retail channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan clusters in Germany's Rhine-Ruhr corridor anchor European reduced fat dairy demand, with health-conscious households driving private-label innovation in supermarket channels.
Germany
Urban households in Berlin, Munich, and Hamburg elevate reduced fat yogurt and cheese to dietary staples. The Federal Ministry of Food and Agriculture enforces strict nutritional labeling under the National Nutrition Strategy. Bavarian dairy cooperatives concentrate production of protein-fortified reduced fat variants for nationwide distribution.
France
Paris and Lyon metropolitan areas drive premium positioning for clean-label reduced fat offerings. ANSM and DGCCRF oversee compliance with EU Farm to Fork nutritional profiling criteria. The Brittany dairy belt supplies raw milk for value-added reduced fat cheese production serving Western European retail banners.
United States
Wisconsin and California dairy belts concentrate milk processing capacity for reduced fat standardization. The FDA enforces identity requirements under 21 CFR 131 and 133, constraining formulation flexibility. Midwestern cooperatives supply private-label reduced fat milk to national supermarket chains.
Netherlands
Randstad urban consumers demand grass-fed verification for reduced fat dairy procurement. The Netherlands Food and Consumer Product Safety Authority implements EU Green Deal sustainability metrics at farm level. Friesland-based cooperatives control critical raw milk volumes for cross-border supply.
Denmark
Copenhagen's institutional procurement mandates displace confectionery with reduced fat snacking formats in schools. The Danish Veterinary and Food Administration enforces EFSA-compliant front-of-pack labeling. Arla Foods' cooperative farmer network sustains consistent supply for value-added reduced fat cheese production.
Reduced Fat Dairy Market Competitive Landscape
Premium-margin players sit above commodity-margin players across protein fortification capability and clean-label fermentation expertise. Cooperative structures dominate raw milk procurement in Northern Europe, while multinational processors control branded distribution in North America. Three archetypes define competitive positioning: farmer-owned cooperatives with captive supply, diversified nutrition conglomerates with R&D scale, and specialist organic processors with certification depth. Capacity expansion and portfolio diversification toward drinkable formats represent the dominant competitive moves.
Within the cooperative archetype, Arla Foods and Dairy Farmers of America exemplify farmer-owned structures that anchor regional supply security. Danone occupies a position representing diversified nutrition specialists with fermentation protocol differentiation. These three entities collectively illustrate how governance structure shapes competitive capability across the reduced fat dairy value chain.
| Leading Market Players |
|---|
| Arla Foods |
| Dairy Farmers of America |
| Nestlé |
| Organic Valley |
| Saputo |
| Danone |
| Kraft Heinz |
| Lactalis |
| Fonterra |
| Others |
Value Network & Pricing Analysis
Western European supermarket private-label procurement teams concentrate purchasing power across Germany, France, and the Netherlands, compressing branded margins through volume-based contract negotiations and dual-sourcing requirements. This buyer concentration enforces commodity-plus pricing for standard reduced fat milk while preserving premium capture for protein-fortified yogurt and clean-label cheese lines.
Pricing Analysis
Value-based pricing anchors on protein retention performance and fermentation-derived texture quality rather than input fat content alone. Three-tier pricing structure across premium, standard, and economy levels separates grass-fed certified organic lines from conventional membrane-filtered products and commodity skim alternatives. Cost compression in economy-tier milk intensifies because skim milk powder standardization ingredient costs fluctuate with global dairy commodity cycles. Institutional buyers in German and French school nutrition programs exhibit lowest price sensitivity due to mandated nutritional procurement standards, while convenience store impulse purchasers drive hardest bargain for single-serve snacking formats.
Supply Chain Analysis
Cold-chain logistics costs for temperature-controlled distribution of fresh reduced fat yogurt constrain radius economics and reinforce regional production clustering. Raw milk supply concentrates in Denmark, the Netherlands, and northern Germany where farmer-owned cooperatives control critical volumes. Processing draws from membrane filtration equipment, specialized bacterial cultures, and sustainable packaging substrates. Single-source vulnerability runs through concentrated cooperative supply networks that limit independent processor access to standardized milk volumes. Distribution feeds from dairy cooperative processing hubs through wholesale foodservice channels and supermarket direct-store-delivery systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around compliance-capable processors as EU Farm to Fork nutritional profiling mandates and FDA identity standard divergence force subscale competitors toward exit. Stranded asset risk accumulates for processors lacking membrane filtration retrofit capital or dual-certification regulatory affairs depth.
For Market Incumbents: Lock in cooperative supply agreements through equity participation or long-term offtake guarantees to defend against raw milk procurement bottlenecks. Invest in parallel FDA and EFSA regulatory affairs capabilities to capture dual-market premiums as threshold divergence widens. Prioritize fermentation specialist recruitment and retention to preserve clean-label texture preservation advantages against enzyme-modification commodity competitors.
For New Entrants and Emerging Players: Begin with drinkable yogurt formats in French and German school nutrition procurement channels where mandated nutritional standards displace incumbent confectionery suppliers. Target organic reduced fat cheese segments where consolidation pressure has thinned specialist processor ranks. Pursue direct-to-consumer subscription models to bypass supermarket private-label gatekeeping and capture full margin on grass-fed verified products.
For Investors and Strategic Acquirers: The window for entry favors mid-cap processors with existing membrane filtration infrastructure and pending organic certification completion. Long-term viability hinges on regulatory affairs scalability across FDA and EFSA jurisdictions rather than commodity volume scale alone. Watch EFSA nutritional profiling criteria revision timing as inflection indicator for premium positioning eligibility and reformulation investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Capacity Expansion | Enables protein fortification that preserves cooking functionality without artificial additives under EFSA standards. |
| Dual Certification Investment | Captures premium positioning across FDA-regulated US markets and EFSA-governed EU channels simultaneously. |
| Clean-Label Fermentation Protocol Development | Unlocks organic retail placement through specialized bacterial cultures that eliminate stabilizer dependencies. |
| Grass-Fed Sourcing Verification System | Aligns with EU Green Deal sustainability metrics to secure green procurement contracts from institutional buyers. |
| School Nutrition Channel Penetration | Displaces traditional confectionery in French and German urban education districts through mandated procurement. |
Research Methodology
Document review covered EU Farm to Fork Strategy implementation guidance, FDA 21 CFR 131 and 133 identity standards, EFSA nutritional profiling technical documentation, and dairy cooperative annual disclosures, complemented by interviews with dairy processing executives, regulatory affairs specialists at multinational nutrition conglomerates, fermentation science researchers, supermarket category buyers in Germany and France, and school nutrition procurement officers. Secondary validation drew from customs trade data, dairy commodity price indices, and retail audit databases. Bottom-up volume modeling triangulated against top-down market sizing from production capacity and consumption surveys.
Cross-referencing historical protein fortification adoption curves against expert panel input on membrane filtration deployment timelines shaped projection parameters across the analysis window. Segmentation dimensions modeled include product type, end user procurement pattern, distribution channel logistics requirements, and application-specific functional performance thresholds. CAGRs derived from weighted average of technology diffusion rates and regulatory compliance investment cycles, with specific inputs from skim milk powder price volatility assumptions and school nutrition mandate expansion schedules.
Underlying measurement precision varies by segment; snacking application volumes carry tighter precision than emerging drinkable yogurt formats due to established retail audit coverage. Forecasts reflect documented assumptions on regulatory timeline adherence and technology cost reduction curves. Stakeholders should weight assumptions against their own operating context regarding cold-chain infrastructure access and cooperative supply relationship depth.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Mozzarella Cheese Market
Dairy Products
Nigeria Yogurt Drinks Market
Dairy Products
Fermented Milk Products Market
Dairy Products
Milk Fat Fractions Market
Dairy Products
Enzyme Modified Cheese Market
Dairy Products
Fat-Filled Milk Powder Market
Dairy Products
Fermented Dairy Ingredients Market
Dairy Products
UHT Whipping Cream Market
Dairy Products
Probiotic Dairy Products Market
Dairy Products
North America Cheese Market
Dairy Products
Asia-Pacific Dairy Market
Dairy Products
GCC Casein Market
Dairy Products
Parmesan Cheese Market
Dairy Products
Processed Cheese Market
Dairy Products
Lactic Butter Market
Dairy Products
North America Whole Milk Powder Market