
 Chlorella Ingredients Market | 2026-2036
Chlorella Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Chlorella Ingredients Market Outlook
Single-serve sachet and stick-pack bundling is shifting buyer choice away from bulk powder drums toward pre-portioned convenience formats. Sun Chlorella Corporation leverages its Japanese retail pharmacy network to anchor premium tablet positioning in aging-consumer segments. Taiwan Chlorella Manufacturing Company sustains cost-competitive powder output through integrated pond-to-dryer operations. Phycom BV differentiates via heterotrophic fermentation technology that delivers consistent protein concentration regardless of seasonal sunlight variation.
Chlorella ingredients comprise dried and processed biomass of the green microalga Chlorella vulgaris or Chlorella pyrenoidosa, typically containing 50-60% protein by dry weight together with chlorophyll, carotenoids, and cell-wall-bound polysaccharides; manufacturers employ either open-pond photosynthetic cultivation or closed heterotrophic fermentation followed by spray-drying and mechanical cell-wall disruption to enhance bioavailability of intracellular nutrients. Powder formulations dominate ingredient supply to food and beverage manufacturers seeking natural colorants and protein fortification, while extract grades command margin premiums in cosmetic applications where chlorophyll-derived compounds serve as antioxidant actives. Pharmaceutical-grade tablets and capsules represent the fastest-growing finished-form channel as nutraceutical brands target clinically positioned immune and detoxification claims.
The FDA regulates chlorella as a dietary supplement under DSHEA with New Dietary Ingredient notification requirements for novel extraction methods, while the EU EFSA evaluates Novel Food status for non-traditional cultivation variants under Regulation (EU) 2015/2283. Japan's Ministry of Health, Labour and Welfare administers FOSHU approval pathways that confer permitted health-claim status for chlorella products meeting randomized controlled trial evidence standards. China's National Health Commission maintains an approved list of microalgae species for food use that constrains import eligibility for strains outside domestic positive lists. Stakeholders must monitor evolving cell-wall disruption patent landscapes and jurisdiction-specific algae-source qualification protocols to secure formulation access in premium regulated channels.
Market Dynamics
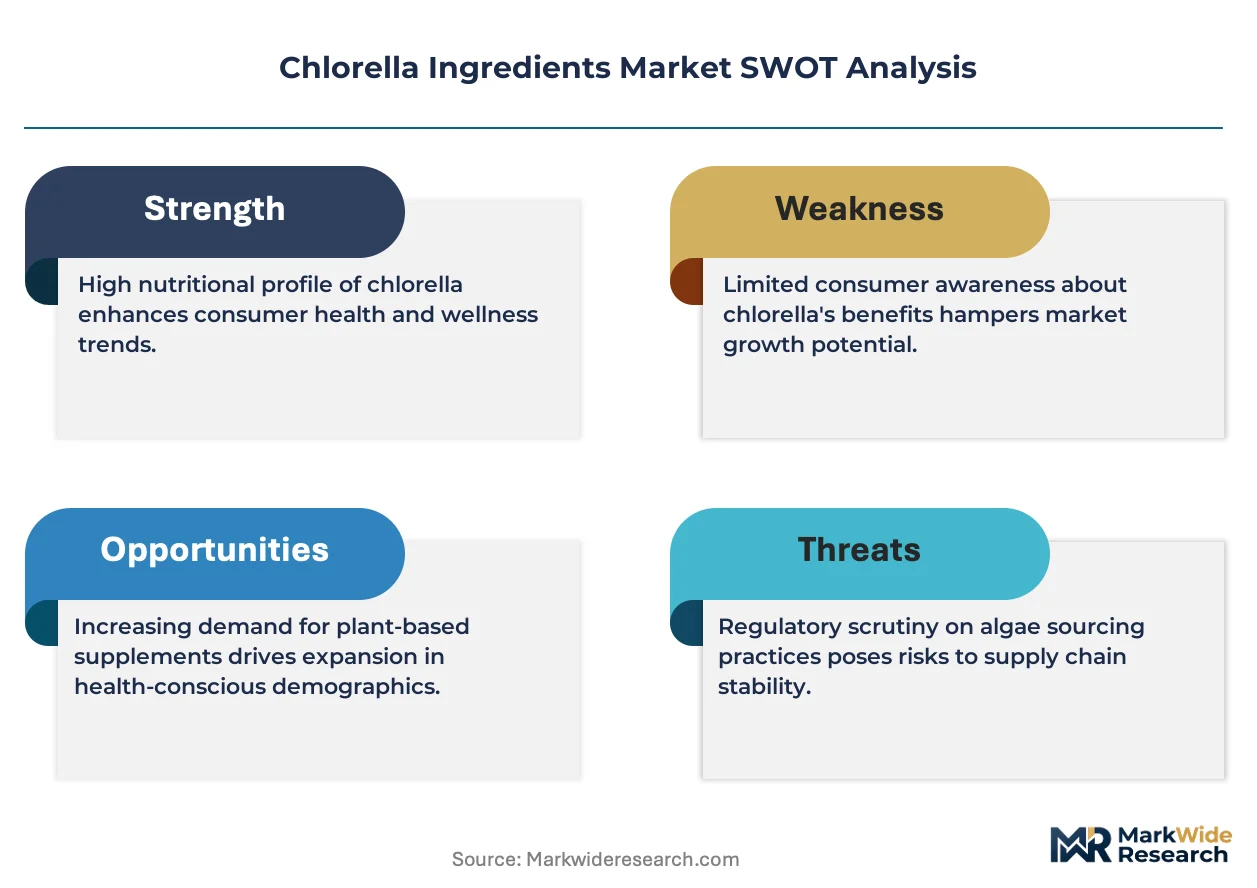
Pharmaceutical-grade certification requirements are fragmenting supplier eligibility across regulated nutraceutical channels, forcing manufacturers to choose between premium positioning and mass-market volume strategies.
Growth Catalysts
- FOSHU pathway expansion:Japan's Ministry of Health, Labour and Welfare is streamlining immune-support claim approvals for chlorella tablets, incentivizing clinical trial investment by domestic formulators.
- Heterotrophic fermentation scale-up:Closed bioreactor systems eliminate seasonal protein yield variation, attracting contract manufacturers seeking consistent raw material specifications.
- Stick-pack format adoption:Single-serve sachets are displacing bulk powder drums in convenience-oriented consumer segments across German pharmacy retail.
Market Restraints
- Glucose feedstock volatility:Heterotrophic cultivation depends on corn-derived glucose pricing, exposing fermenter operators to agricultural commodity swings.
- Taiwan-Japan supply concentration:Integrated pond-to-dryer operations in these two markets control the majority of pharmaceutical-grade powder output, creating single-source vulnerability.
- Cell-wall disruption patent thickets:Mechanical disruption technologies for bioavailability enhancement face overlapping IP claims that complicate equipment sourcing.
Strategic Opportunities
- EU Novel Food authorization gaps:Strains cultivated via heterotrophic methods remain underreviewed by EFSA, creating first-mover advantage for dossier-ready applicants.
- Cosmetic active extracts:Chlorophyll-derived antioxidant compounds command margin premiums in Korean skincare formulation, an application segment with limited incumbent supply.
- Direct-to-practitioner distribution:Functional medicine clinics represent an underdeveloped channel for detoxification-positioned tablet products in North American metropolitan markets.
Industry Challenges
- Phycology technician scarcity:Open-pond cultivation requires specialized algae strain management expertise that outpaces vocational training program output in major production regions.
- Dual certification timelines:Simultaneous pursuit of pharmaceutical-grade GMP and organic accreditation extends facility qualification periods by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chlorella Ingredients Market |
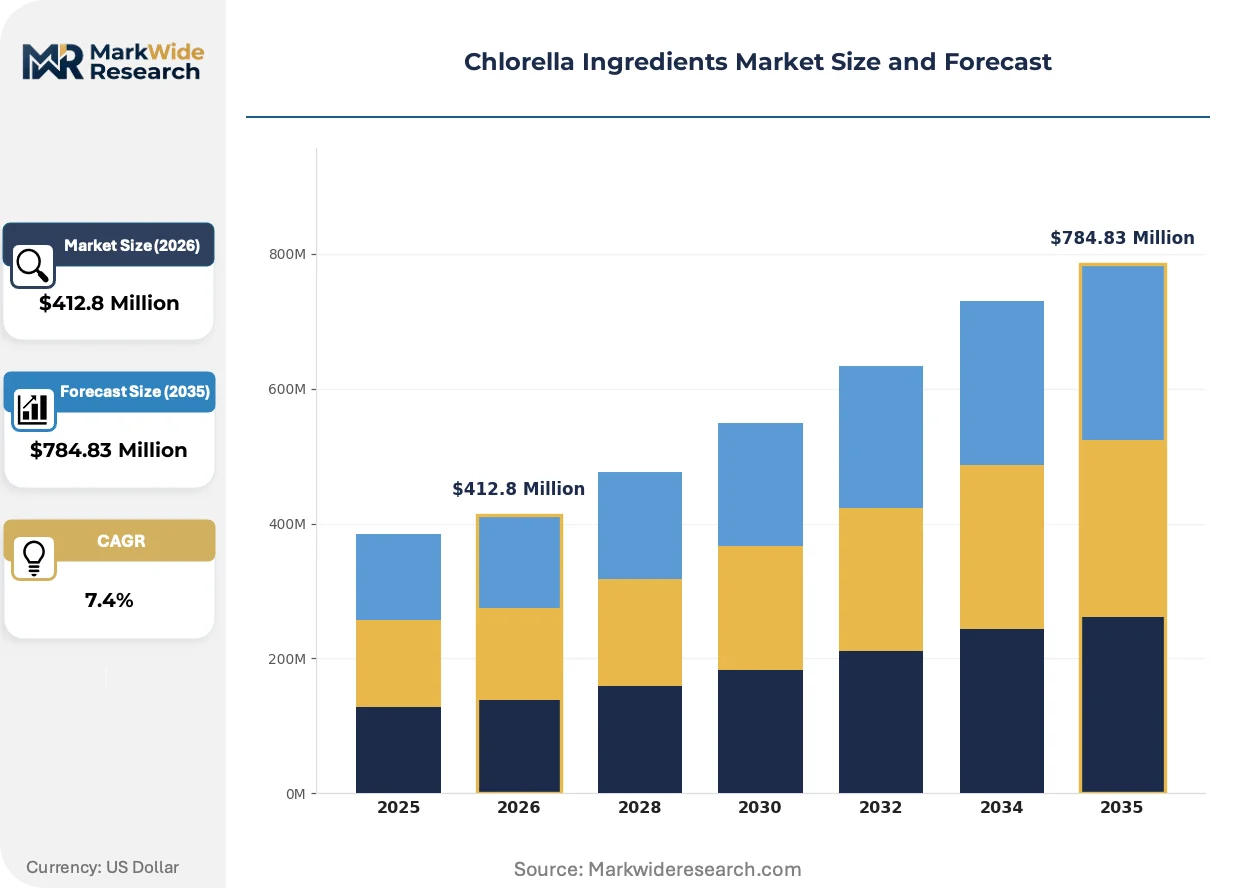
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $784.83 Million |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Tablets, Capsules, Extracts Application: Food & Beverage, Cosmetics, Nutraceuticals, Animal Feed Grade: Food Grade, Pharmaceutical Grade, Cosmetic Grade, Industrial Grade Form: Organic, Inorganic, Liquid, Dry |
| Companies Covered | Sun Chlorella Corporation, Taiwan Chlorella Manufacturing Company, Yaeyama Chlorella, Gong Bih Enterprise, Nutriphys, Phycom BV, Tianjin Norland Biotech, E.I.D. - Parry, Vedan Enterprise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chlorella Ingredients Market Strategic Shifts
Convergence of precision fermentation with automated cell-wall disruption is compressing the gap between raw biomass and finished tablet, reshaping where value capture occurs in the supply chain.
Closed heterotrophic fermentation using glucose-fed bioreactors is electrifying protein concentration consistency for nutraceutical manufacturers. German and Japanese formulators are adopting this technology rapidly to eliminate seasonal yield variation. The shift is compressing lead times for immune-support supplement production while reducing dependency on pond operators in climate-vulnerable regions.
EFSA's evolving interpretation of Regulation (EU) 2015/2283 is reclassifying certain heterotrophic chlorella strains as Novel Food candidates requiring full safety dossiers. This regulatory friction is delaying market entry for fermentation-based suppliers while favoring incumbent photosynthetic producers with grandfathered status. Tablet and capsule manufacturers are responding by dual-sourcing across cultivation methods to maintain formulation continuity.
Pre-portioned convenience formats are capturing preference share from bulk powder among aging-consumer segments in Japanese pharmacy retail. Stick-pack bundling is displacing traditional drum purchasing for household consumption, while single-serve sachets penetrate travel and workplace channels. This channel rotation is most visible in Tokyo and Osaka metropolitan pharmacy networks where Sun Chlorella Corporation anchors premium positioning.
Chlorella Ingredients Market Segmentation
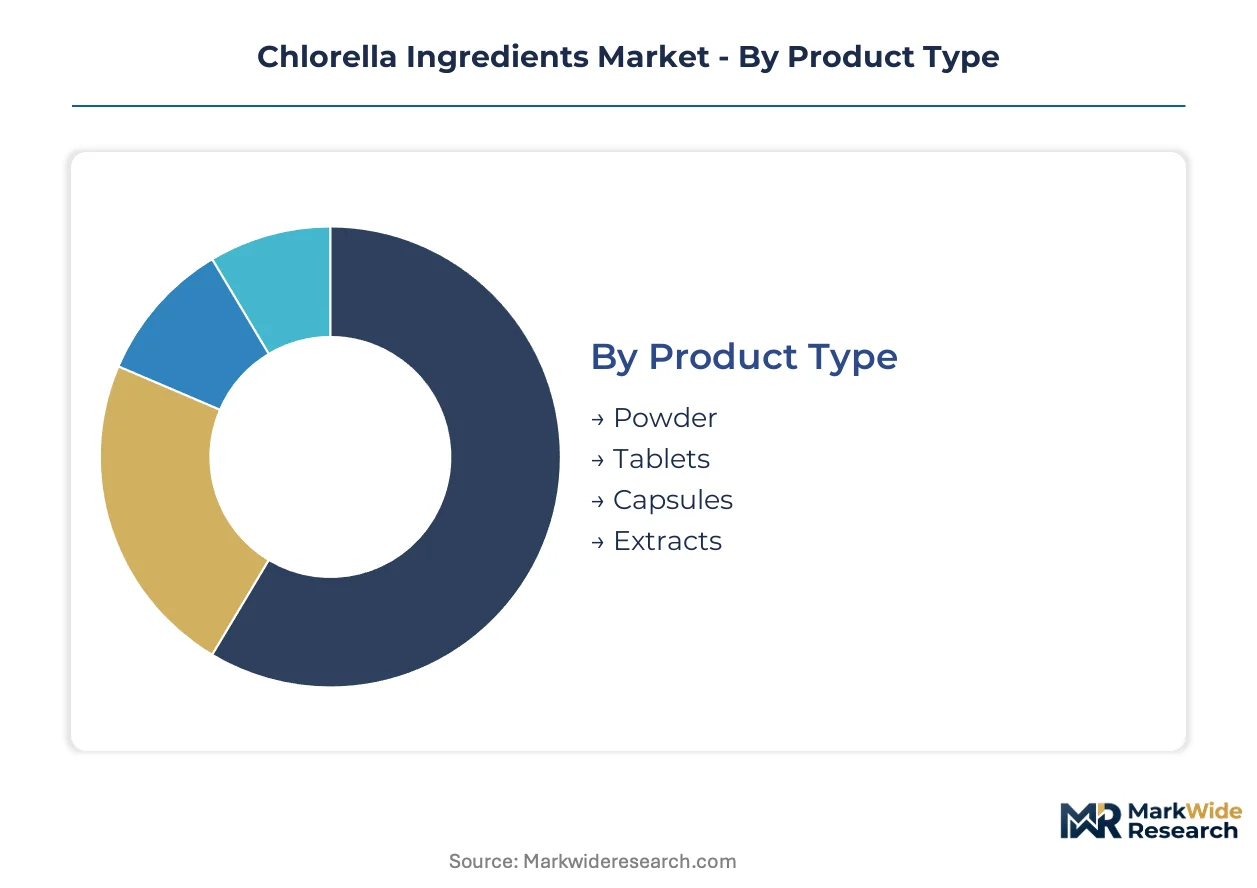
Chlorella ingredient buyers sort supply by certification tier and finished-form compatibility, not commodity protein content alone. Each segmentation axis reveals distinct margin pools and regulatory entry barriers that separate premium nutraceutical channels from mass-market food additive applications.
Product Type:
Powder dominates volume throughput while tablets command per-unit margin premiums in pharmacy retail.
- Powder:Spray-dried biomass with 50-60% protein concentration serves as the foundational input for food fortification and supplement manufacturing. German beverage formulators and Taiwanese contract manufacturers absorb the majority of pharmaceutical-grade powder output for downstream tablet pressing and encapsulation.
- Tablets:Compressed chlorella with standardized cell-wall disruption enables precise dosing for immune-support positioning in Japanese FOSHU-approved products. Sun Chlorella Corporation's pharmacy network distribution anchors premium tablet pricing in aging-consumer segments across Tokyo and Osaka metropolitan markets.
- Capsules:Gelatin and vegetable-shell encapsulation targets practitioner-channel distribution in North American functional medicine clinics.
- Extracts:Chlorophyll-derived antioxidant concentrates supply Korean skincare formulators seeking natural active ingredients.
Today's leader: Powder. Tomorrow's challenger: Tablets.
Application:
Nutraceutical claims drive regulatory investment while cosmetics extracts unlock margin expansion in beauty-active channels.
- Nutraceuticals:Immune-support and detoxification tablets with FOSHU approval in Japan and DSHEA compliance in the US represent the steepest expansion trajectory. Clinical trial investment by domestic Japanese formulators is streamlining health-claim pathways.
- Cosmetics:Chlorophyll-based antioxidant actives command premium positioning in Korean skincare formulations where natural ingredient sourcing differentiates premium product lines.
- Food & Beverage:Natural green colorant and protein fortification applications in bakery and beverage manufacturing emphasize cost-competitive powder sourcing.
- Animal Feed:Aquaculture and poultry nutrition applications absorb lower-grade biomass with reduced cell-wall processing requirements.
Nutraceuticals capture regulatory rents. Cosmetics bypass certification delays.
Grade:
Pharmaceutical certification fragments supplier eligibility while food grade sustains volume throughput.
- Pharmaceutical Grade:GMP-compliant production with full heavy metal and microbial documentation enables immune-support tablet positioning in regulated pharmacy channels. Dual certification timelines for organic and pharmaceutical standards extend facility qualification by 18-24 months.
- Food Grade:Standardized protein content and basic safety testing serves bakery, beverage, and casual supplement applications with shorter procurement cycles.
- Cosmetic Grade:Chlorophyll concentration and heavy metal limits tailored to topical application requirements in Korean and European skincare manufacturing.
- Industrial Grade:Unprocessed or minimally treated biomass for animal feed and agricultural applications with minimal regulatory documentation.
Pharmaceutical grade extracts margin premiums. Food grade defends volume base.
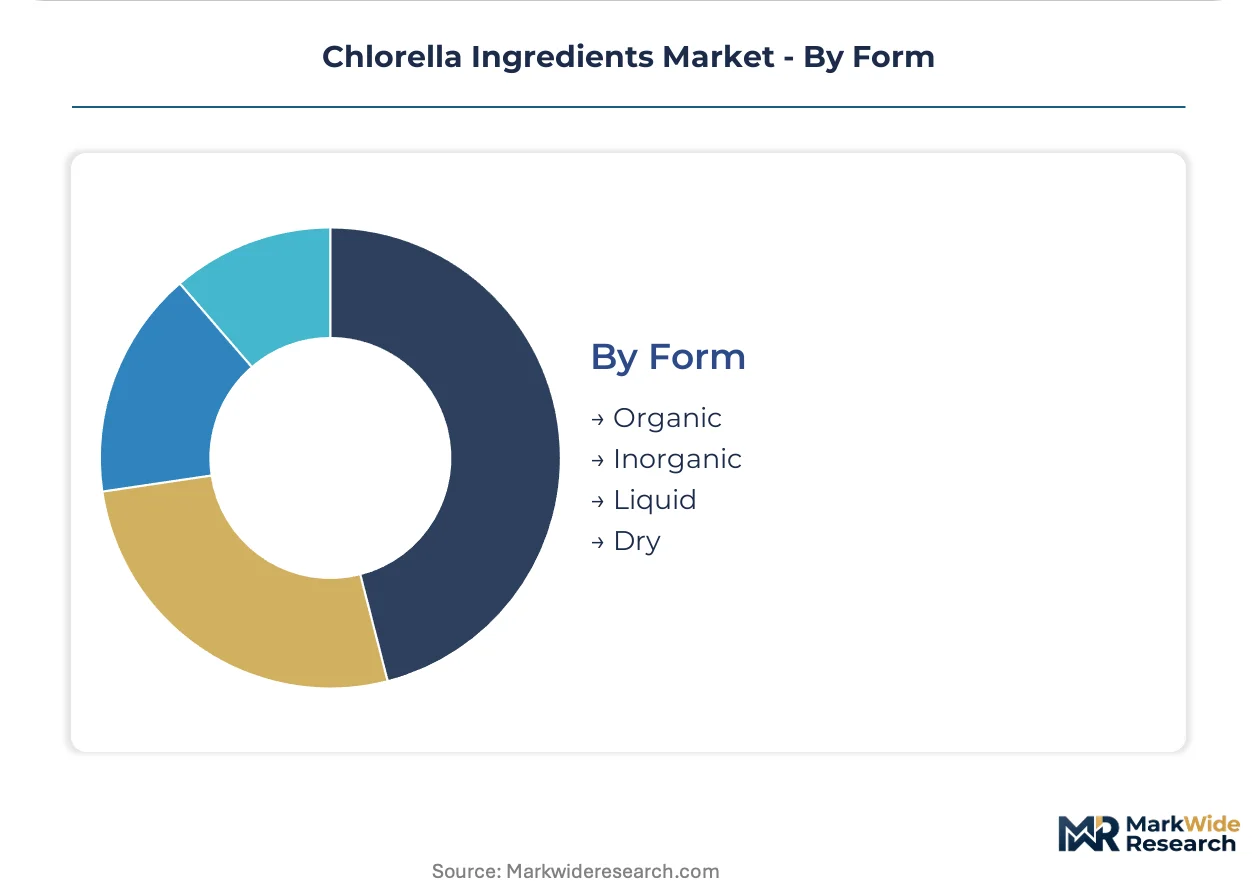
Form:
Organic certification opens premium channels while heterotrophic fermentation reshapes supply consistency.
- Organic:Third-party certified cultivation in open ponds targets premium positioning in European and North American natural product retail. EU EFSA Novel Food requirements and USDA organic standards constrain sourcing flexibility.
- Inorganic:Conventional photosynthetic or heterotrophic production without organic certification serves cost-sensitive food additive and feed applications.
- Dry:Spray-dried powder and granule formats dominate ingredient supply for manufacturing integration and extended shelf stability.
- Liquid:Suspensions and extracts for beverage fortification and cosmetic serum applications represent a niche but expanding format category.
Organic form secures shelf placement. Heterotrophic dry form compresses lead times.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan pioneered commercial chlorella cultivation in the 1950s, establishing the technical foundation that Taiwan and later Germany adapted for pharmaceutical-grade production. This historical lineage shapes today's geographic concentration of premium nutraceutical supply.
Japan
Japan's aging population drives sustained tablet consumption through pharmacy retail networks. The Ministry of Health, Labour and Welfare streamlines FOSHU immune-support claim approvals, incentivizing clinical trial investment by domestic formulators. Tokyo and Osaka metropolitan markets anchor premium positioning for finished tablet products.
Taiwan
Taiwanese contract manufacturers absorb pharmaceutical-grade powder for downstream tablet pressing and encapsulation. The Food and Drug Administration maintains strict import documentation for microalgae strains. Integrated pond-to-dryer operations in Taichung and Tainan control cost-competitive biomass output.
Germany
German nutraceutical formulators expand procurement of pharmaceutical-grade chlorella powder for immune-support supplements. EFSA evaluates Novel Food status for non-traditional cultivation variants under Regulation (EU) 2015/2283. Frankfurt and Munich pharmacy retail networks drive stick-pack format adoption.
China
China's National Health Commission maintains an approved list of microalgae species that constrains import eligibility for strains outside domestic positive lists. Heterotrophic fermentation scale-up attracts contract manufacturers seeking consistent raw material specifications. Tianjin and Qingdao clusters concentrate biomass processing capacity.
United States
North American functional medicine clinics represent an underdeveloped channel for detoxification-positioned tablet products. The FDA regulates chlorella as a dietary supplement under DSHEA with New Dietary Ingredient notification requirements. California and New York metropolitan markets concentrate practitioner-channel distribution trials.
Chlorella Ingredients Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification tier and finished-form sophistication. The vendor base stratifies between pharmaceutical-grade GMP operators and food-grade bulk suppliers. Three archetypes dominate: integrated pond-to-dryer operators, heterotrophic fermentation specialists, and pharmacy-network tablet brands. Capacity expansion and dual-certification pursuit constitute the dominant competitive moves.
Within the integrated cultivation tier, Taiwan Chlorella Manufacturing Company and Sun Chlorella Corporation exemplify contrasting geographic anchoring. Among fermentation-based specialists, Phycom BV occupies a position representing closed bioreactor technology adoption. These three entities represent the structural poles of the competitive landscape: pond-based volume, pharmacy-network premium positioning, and bioreactor consistency.
| Leading Market Players |
|---|
| Sun Chlorella Corporation |
| Taiwan Chlorella Manufacturing Company |
| Yaeyama Chlorella |
| Gong Bih Enterprise |
| Nutriphys |
| Phycom BV |
| Tianjin Norland Biotech |
| E.I.D. - Parry |
| Vedan Enterprise |
| Others |
Value Chain & Pricing Dynamics
EU EFSA Novel Food authorization requirements gate qualified supply and premium-tier pricing access for heterotrophic fermentation strains, forcing manufacturers to absorb extended dossier costs or retreat to photosynthetic sourcing. This regulatory filter concentrates margin capture among incumbent pond operators with grandfathered status while compressing price realization for fermentation entrants seeking pharmacy-channel positioning.
Pricing Analysis
Three-tier pricing structure across pharmaceutical, food, and feed grades separates margin pools by certification intensity. Price differentiation hinges on GMP compliance documentation and organic dual-certification status, with pharmaceutical-grade powder commanding substantial premiums over food-grade bulk. Pricing pressure stems from glucose feedstock volatility exposing heterotrophic operators to agricultural commodity swings. Feed-grade buyers exhibit highest price sensitivity, while Japanese pharmacy retailers absorb premium tablet pricing with minimal volume elasticity.
Supply Chain Analysis
Phycology technician scarcity in Taiwan and Japan constrains open-pond cultivation expansion despite sustained demand from German formulators. Raw material flows draw from corn-derived glucose for fermentation bioreactors, pond-cultivated biomass for organic-certified output, and specialized mechanical disruption equipment for bioavailability enhancement. Single-source vulnerability concentrates in Taiwan-Japan pharmaceutical-grade powder output. Distribution runs through East Asian contract manufacturing clusters for tablet pressing and encapsulation, with finished products flowing to German and Japanese pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as nutraceutical buyers shift procurement toward pharmaceutical-grade specifications with full heavy metal and microbial documentation. Premium-tier positioning now requires dual certification investment that extends facility qualification timelines substantially.
For Market Incumbents: Cement pharmacy-network relationships through exclusive FOSHU pathway partnerships with Japanese formulators. Deepen backward integration into pond-to-dryer operations in Taiwan to defend against heterotrophic fermentation scale-up by Phycom BV and emerging bioreactor specialists. Prioritize cell-wall disruption patent portfolio expansion to complicate equipment sourcing for potential entrants.
For New Entrants and Emerging Players: Launch via direct-to-practitioner distribution in North American functional medicine clinics, the most penetrable channel for detoxification-positioned tablet products. Target cosmetic active extracts for Korean skincare formulators, where chlorophyll-derived antioxidant compounds face limited incumbent supply and bypass pharmaceutical certification delays. Pursue EU Novel Food authorization for heterotrophic strains to capture first-mover advantage in underreviewed dossier categories.
For Investors and Strategic Acquirers: Roll-up economics work for integrated pond-to-dryer operators because pharmaceutical-grade certification fragments supplier eligibility and extends facility qualification timelines. Long-term viability centers on exposure to aging-consumer pharmacy retail in Japan and stick-pack format adoption in German metropolitan markets. Watch EFSA's evolving interpretation of Regulation (EU) 2015/2283 as the inflection signal for fermentation-based supplier reclassification.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Pursuit | Pharmaceutical-grade GMP plus organic accreditation opens premium pharmacy channels in Germany and Japan. |
| Heterotrophic Fermentation Scale-Up | Closed bioreactor systems eliminate seasonal protein yield variation for immune-support supplement manufacturers. |
| Stick-Pack Format Introduction | Single-serve sachets displace bulk powder drums in convenience-oriented German pharmacy retail segments. |
| Cell-Wall Disruption Patent Expansion | Mechanical disruption IP thickets complicate equipment sourcing for bioavailability enhancement competitors. |
| Direct-to-Practitioner Channel Development | Functional medicine clinics in North American metropolitan markets represent underdeveloped detoxification tablet distribution. |
Study Parameters
Direct dialogue with nutraceutical formulators, phycology technicians at pond cultivation facilities, regulatory affairs specialists navigating EFSA Novel Food pathways, and pharmacy procurement managers in Tokyo and Osaka grounded qualitative findings. Secondary validation drew from FDA DSHEA guidance documents, EFSA Novel Food opinions, Japan MHLW FOSHU approvals, customs trade data for microalgae biomass, and SEC filings from publicly traded supplement manufacturers. Bottom-up demand modeling across certification tiers triangulated against top-down market sizing from production capacity assessments.
Bottom-up volume builds aggregated pharmaceutical-grade, food-grade, and cosmetic-grade demand by application segment, while top-down checks calibrated against known production capacity at major pond and fermentation facilities across the analysis window. Segmentation dimensions modeled include product type, application, grade tier, and cultivation method. CAGRs derived from regression analysis of historical procurement patterns and projected FOSHU pathway expansion. Industry-specific inputs incorporated glucose feedstock pricing volatility and phycology technician training program output.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EFSA reclassification of heterotrophic strains or sustained glucose commodity spikes. Forecasts reflect assumptions regarding regulatory timeline continuity and pharmacy retail format stability. Material deviation in EU Novel Food authorization pacing or Japan FOSHU immune-support claim streamlining warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Industrial Sugar Market
Ingredients
Almond Ingredients Market
Ingredients
Corn Gluten Meal Market
Ingredients
Corn Oil Market
Ingredients
Smoked Yeast Market
Ingredients
Halal and Kosher Empty Capsules Market
Ingredients
Plant Based Premix Market
Ingredients
North America Soy Protein Concentrate Market
Ingredients
Seaweed Extracts Market
Ingredients
Global Pea Protein Ingredients Market
Ingredients
Guar Gum Market
Ingredients
Low Calorie Oil Market
Ingredients
Freeze-Dried Pea Isolates Market
Ingredients
Dried Distillers' Grains with Soluble Market
Ingredients
Cottonseed Oil Market
Ingredients
Wort Concentrate Market