
 Europe Dairy Ingredients Market | 2026-2036
Europe Dairy Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Dairy Ingredients Market Foresight
A capital-intensity divergence between spray-drying specialists and commodity milk powder operators is unwinding competitive stability across the sector. Fonterra Co-operative Group Limited leverages its New Zealand-origin supply chain to dominate whey protein isolate shipments into European ports. Kerry Group PLC anchors its position through backward integration into Irish dairy cooperative networks. Arla Foods amba sustains margin pools by controlling organic skim milk powder certification pathways.
Europe dairy ingredients comprise processed or fractionated milk-derived components—ranging from protein-standardized powders to anhydrous milk fat with defined fatty acid profiles—manufactured through centrifugal separation, membrane filtration, or thermal dehydration for use in formulated foods and nutrition products. Spray-dried whey permeate serves as a cost-effective bulking agent in bakery applications where water-binding capacity controls dough rheology. Milk powder retains volume leadership within the product type dimension, though infant nutrition end users drive fastest growth for demineralized whey fractions with specified mineral reduction levels. Powder form commands the largest share of trade flows, while concentrated liquid formats gain traction among beverage manufacturers seeking reduced reconstitution steps.
EMA food contact material rules, EU Green Deal methane benchmarks, and CE marking for dairy processing equipment collectively shape product standards and facility investment timelines across member states. EFSA novel food approvals constrain entry timelines for cell-cultured dairy protein alternatives, preserving incumbent ingredient demand. Stakeholders must monitor how the EU AI Act's quality control system classifications affect automated sorting and grading investments in fractionation plants.
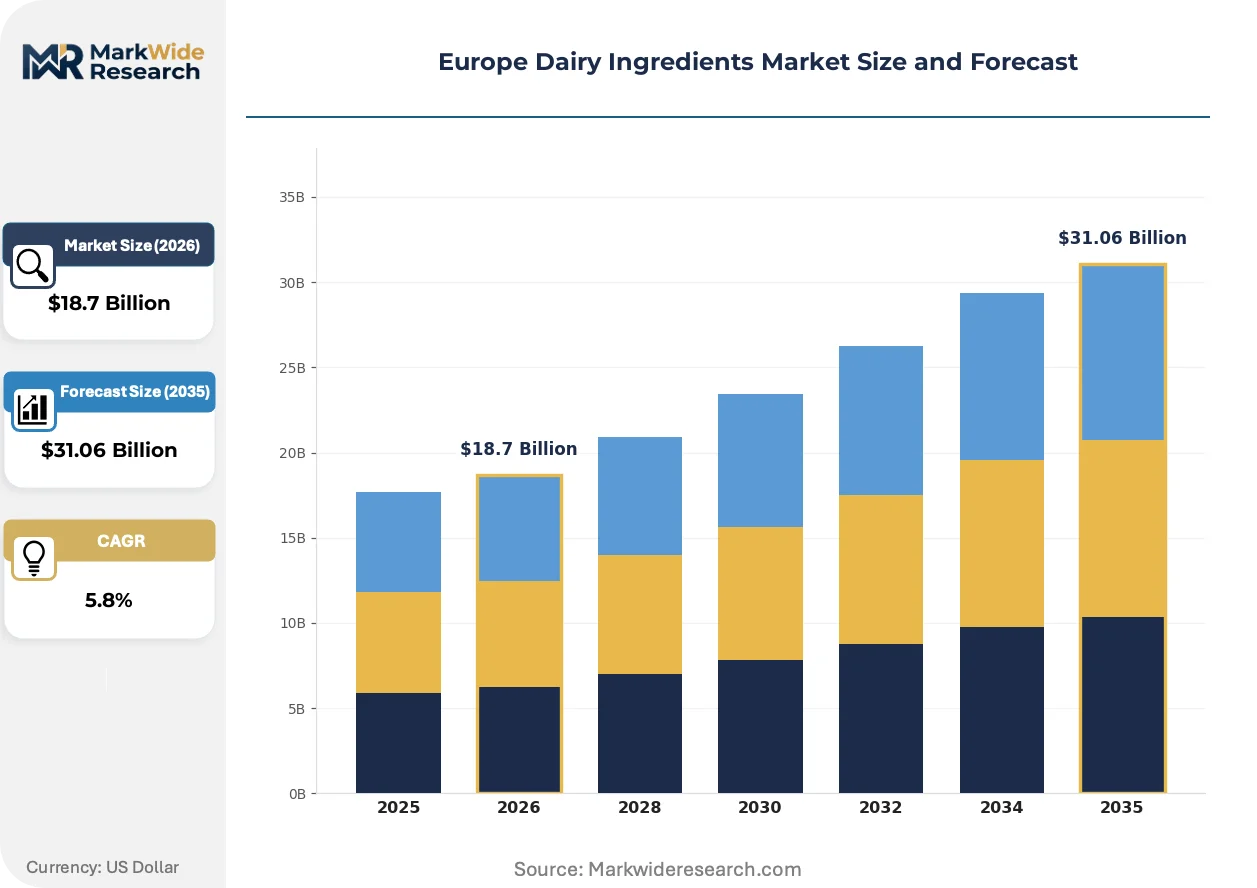
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing methane emission thresholds for dairy processors, forcing capital reallocation toward anaerobic digestion retrofits and low-carbon fractionation infrastructure across member states.
Growth Catalysts
- Infant nutrition demand:Formulators in Germany and France are expanding whey protein concentrate sourcing for specialized pediatric formulations.
- EMA food contact material rules:Updated compliance pathways for packaging migration limits are standardizing ingredient purity specifications across the supply base.
- Membrane filtration advances:Ceramic microfiltration systems are improving protein fractionation yields in Dutch processing clusters.
Market Restraints
- Feed cost volatility:Fodder price swings in Poland and Ireland transmit directly to milk solids input costs.
- Supply concentration risk:Fractionation capacity clusters in the Netherlands create single-point vulnerability for whey permeate availability.
- EFSA novel food timelines:Cell-cultured dairy protein approval delays extend competitive threat incubation periods for incumbent suppliers.
Strategic Opportunities
- Polish dairy cooperative networks:Underdeveloped whey valorization infrastructure presents brownfield retrofit potential for demineralized fraction output.
- EU AI Act quality classifications:Automated grading system mandates create equipment upgrade cycles for fractionation plants seeking competitive differentiation.
- Beverage manufacturer channel shift:Concentrated liquid dairy ingredient formats are bypassing traditional powder reconstitution steps in German bottling operations.
Industry Challenges
- Organic certification timelines:Skim milk powder pathway compliance under EU organic regulation creates 18-24 month product launch delays.
- Anaerobic digestion capex:Methane capture retrofits for existing spray-drying facilities require balance sheet restructuring for mid-scale processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Dairy Ingredients Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk Powder, Butter, Cheese, Yogurt End User: Beverage Manufacturers, Bakery, Confectionery, Infant Nutrition Form: Liquid, Powder, Concentrated, Spray-dried Application: Food Processing, Dietary Supplements, Animal Feed, Pharmaceuticals |
| Companies Covered | Fonterra Co-operative Group Limited, Kerry Group PLC, Arla Foods amba, Danone S.A., Glanbia PLC, Koninklijke FrieslandCampina N.V., Saputo Inc., Valio Group, Groupe Lactalis, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Dairy Ingredients Market Shifts & Advancements
Membrane technology maturation and regulatory carbon accounting are converging to restructure competitive advantage around energy-adjusted protein yields rather than nominal volume throughput.
Precision ceramic microfiltration is displacing traditional centrifugal separation for whey protein isolate recovery. Infant nutrition manufacturers in France and Germany are adopting these systems at pilot scale. The technology is displacing incumbent thermal processing methods by reducing protein denaturation rates and energy intensity per kilogram of isolate output.
EU Green Deal methane benchmarks are tightening facility-level emission ceilings for dairy processors. Operators must now account for enteric fermentation and manure management in scope 3 calculations. Dutch fractionation plants are responding by integrating biogas capture into existing spray-drying operations to maintain license-to-operate status.
Direct procurement from cooperative-owned fractionation facilities is consolidating buyer relationships previously mediated by trading houses. German bakery and confectionery manufacturers are establishing multi-year offtake agreements with Irish dairy processors. This pattern is most visible in the organic skim milk powder segment where certification chain-of-custody requirements favor disintermediated sourcing structures.
Europe Dairy Ingredients Market Segmentation
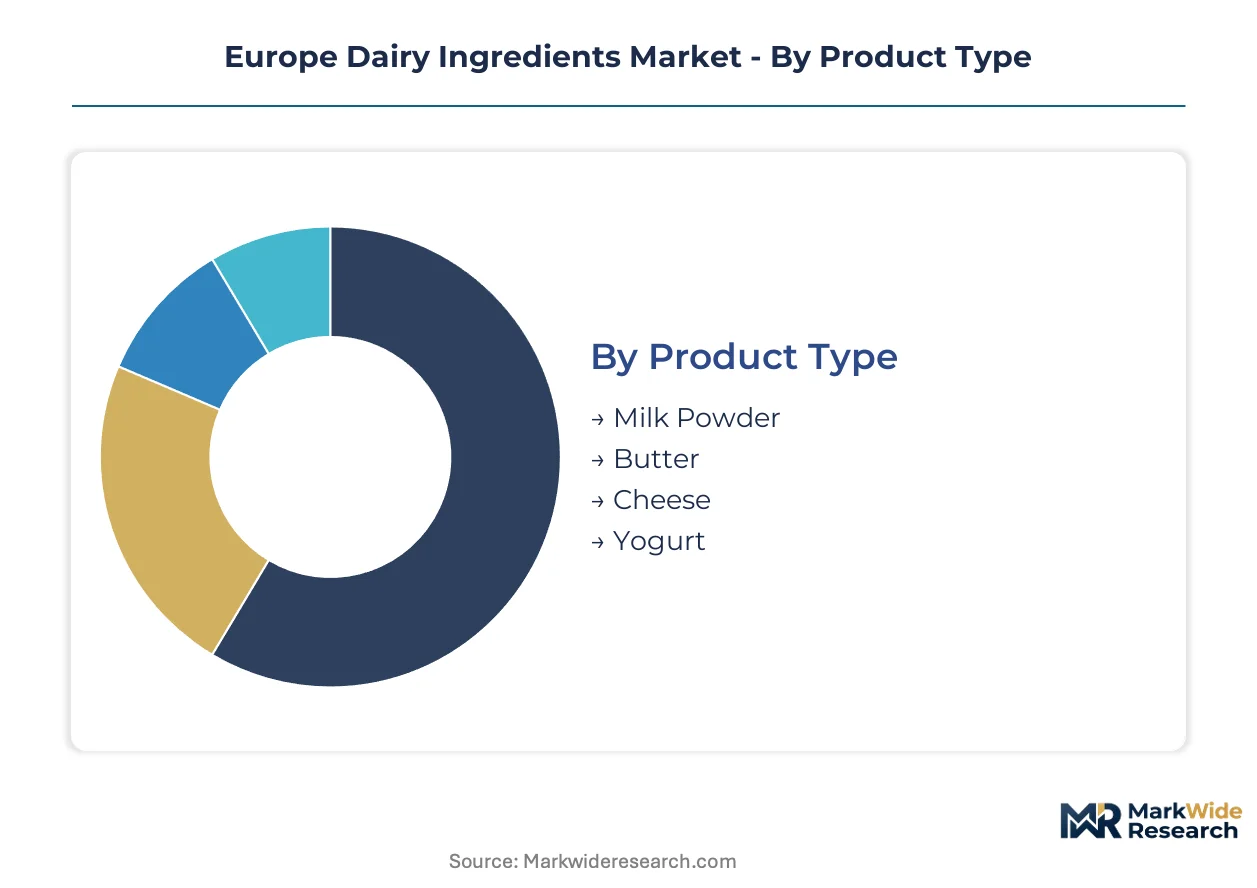
Ingredient specification tiers separate commodity milk powders from fractionated protein isolates with defined functional properties. Margin capture in European dairy ingredients hinges on certification pathways, application-specific purity grades, and format flexibility for downstream formulation.
Product Type:
Milk powder commands the deepest margin pools through organic certification premiums and infant-grade demineralization specifications.
- Milk Powder:Protein-standardized and fat-adjusted varieties serve as formulation bases for UHT beverages and recombined dairy. German and Dutch processors dominate volume through backward integration into cooperative milk collection networks. Skim milk powder with specified heat treatment profiles anchors margin structures for bakery and confectionery channels.
- Butter:Anhydrous milk fat with defined fatty acid profiles supplies chocolate manufacturing and premium bakery applications. French churning operations concentrate fractionation capacity for specified melting point grades demanded by industrial confectioners.
- Cheese:Rennet and enzyme-modified varieties provide flavor concentrates for savory processing and snack seasoning.
- Yogurt:Spray-dried and freeze-dried cultures deliver probiotic stability for dietary supplement compounding.
Milk powder holds installed capacity. Butter is rotating up the share rankings.
End User:
Infant nutrition formulators extract premium pricing through mineral-reduced whey fractions with EFSA-compliant novel food dossiers.
- Infant Nutrition:Demineralized whey protein concentrate with specified mineral reduction levels meets pediatric formulation standards. French and German manufacturers source through multi-year offtake agreements with Dutch fractionators to secure batch-to-batch consistency for hypoallergenic products.
- Beverage Manufacturers:Concentrated liquid dairy proteins bypass reconstitution steps in German bottling operations. Membrane-filtered micellar casein isolates enable high-protein drink positioning with reduced astringency.
- Bakery:Spray-dried whey permeate functions as cost-effective bulking agents where water-binding capacity controls dough rheology.
- Confectionery:Anhydrous milk fat with specified slip melting points supplies chocolate tempering and praline filling operations.
Infant nutrition holds installed capacity. Beverage manufacturers are rotating up the share rankings.
Form:
Powder formats dominate trade flows through shelf stability and containerized shipping economics, while liquid concentrates gain traction in proximity-served beverage corridors.
- Powder:Agglomerated and instantized varieties dissolve without lumping in cold reconstitution. Dutch spray-drying clusters serve pan-European distribution through Rotterdam port logistics.
- Liquid:Pasteurized and aseptically filled concentrates reduce reformulation steps for ready-to-drink manufacturers. German bottling corridors near Bavarian processing plants favor tanker-truck procurement over powder handling.
- Concentrated:Evaporated and membrane-concentrated proteins deliver reduced water content for freight efficiency in cross-border supply.
- Spray-dried:Rapid thermal dehydration preserves protein functionality for sensitive applications including pharmaceutical excipient grades.
Powder holds installed capacity. Liquid is rotating up the share rankings.
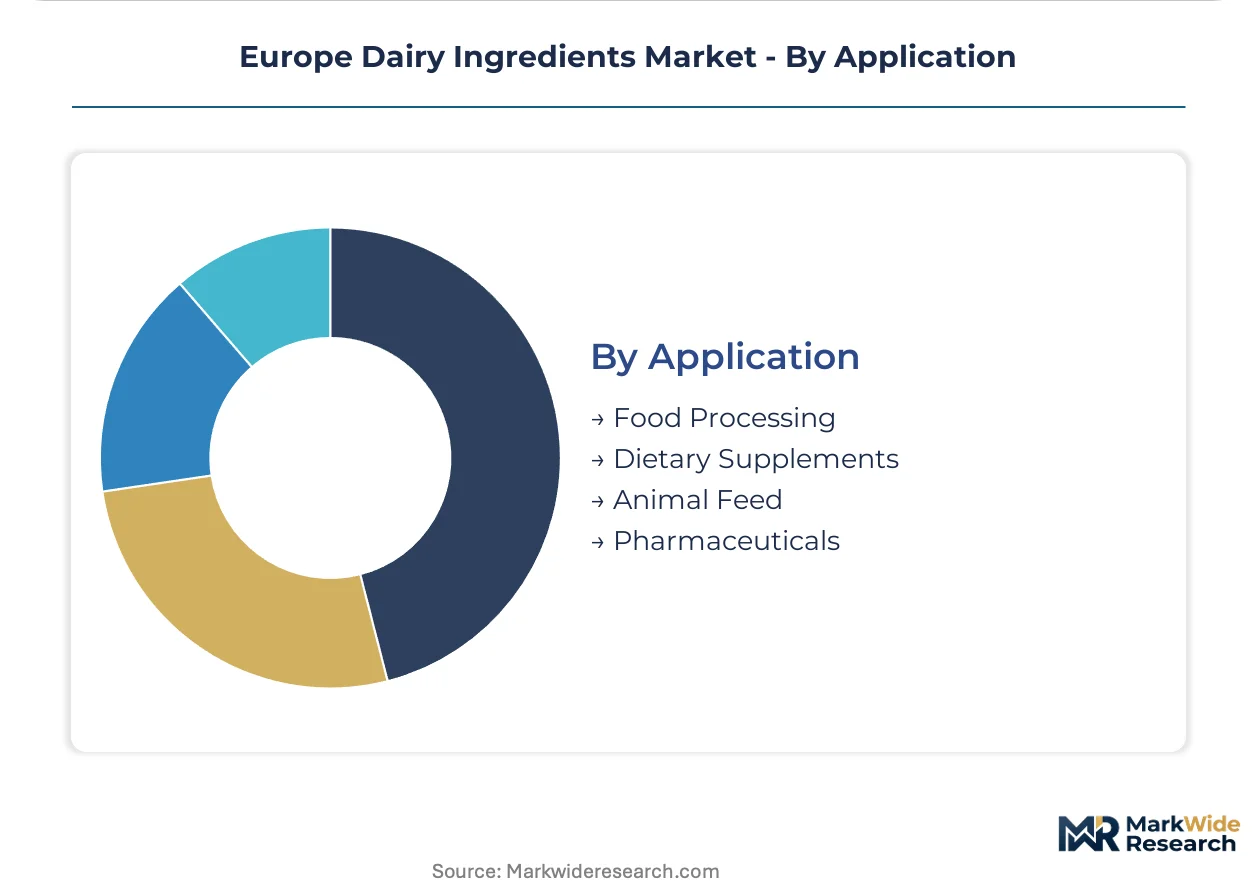
Application:
Food processing absorbs volume through standardized milk powders, while pharmaceutical-grade lactose and protein isolates command specification premiums.
- Food Processing:Recombined dairy, processed cheese, and bakery applications consume standardized milk powders and whey derivatives. Polish and Irish cooperatives supply cost-competitive base materials for private-label manufacturing.
- Dietary Supplements:Micellar casein and whey protein isolates with specified digestibility profiles serve sports nutrition and clinical nutrition positioning. EFSA health claim substantiation requirements filter supplier qualification.
- Animal Feed:Permeate and delactosed whey streams valorize lactose recovery residuals for calf milk replacer and pet food formulations.
- Pharmaceuticals:Crystalline lactose monohydrate and whey protein hydrolysates meet pharmacopeial standards for tablet excipients and enteral nutrition.
Food processing holds installed capacity. Dietary supplements are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Poland and Ireland exhibit acute price sensitivity to feed cost swings, while German and Dutch infant nutrition formulators absorb premium pricing for certified demineralized whey fractions without volume elasticity.
Germany
Bavarian bottling corridors drive concentrated liquid dairy protein procurement for ready-to-drink manufacturers. EFSA novel food dossier requirements constrain entry timelines for specialized pediatric formulations. Munich-area processors are retrofitting membrane filtration lines to serve hypoallergenic infant nutrition contracts.
Netherlands
Rotterdam port logistics anchor pan-European powder distribution through spray-drying clusters. EU Green Deal methane benchmarks force biogas capture integration into existing fractionation infrastructure. FrieslandCampina and Arla operate large-scale whey fractionation facilities in the northern dairy belt.
France
Industrial confectioners in Île-de-France demand anhydrous milk fat with specified slip melting points for chocolate tempering. ANSM food contact material compliance standardizes ingredient purity specifications for packaging migration limits. Auvergne-Rhône-Alpes churning operations concentrate fractionation capacity for premium bakery applications.
Poland
Cooperative milk collection networks supply cost-competitive base materials for private-label recombined dairy. Feed cost volatility transmits directly to milk solids input costs across the national herd. Underdeveloped whey valorization infrastructure in Mazovia presents brownfield retrofit potential for demineralized fraction output.
Ireland
Kerry Group anchors backward integration into cooperative networks supplying organic skim milk powder. Central Bank agricultural lending frameworks influence processor balance sheet capacity for anaerobic digestion capex. Cork and Limerick processing clusters serve German bakery and confectionery offtake agreements.
Europe Dairy Ingredients Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Europe dairy ingredients market. Cooperative-backed processors with captive milk supply dominate volume positions, while independent fractionators compete on application-specific purity grades. Strategic archetypes include New Zealand-origin exporters leveraging supply chain reach, Irish cooperative-integrated nutrition ingredient platforms, and Dutch-scale fractionation operators. Competitive moves center on multi-year offtake agreement consolidation and membrane filtration technology licensing.
Within the cooperative-integrated tier, Arla Foods amba and Fonterra Co-operative Group Limited exemplify divergent geographic anchoring strategies. Arla occupies a position tied to European organic certification pathways, while Fonterra represents the New Zealand-origin supply chain model serving European port demand. Kerry Group PLC sits within the nutrition ingredient platform archetype, leveraging Irish cooperative network integration.
| Leading Market Players |
|---|
| Fonterra Co-operative Group Limited |
| Kerry Group PLC |
| Arla Foods amba |
| Danone S.A. |
| Glanbia PLC |
| Koninklijke FrieslandCampina N.V. |
| Saputo Inc. |
| Valio Group |
| Groupe Lactalis |
| Others |
Supply & Pricing Matrix
Multi-year offtake agreements between German infant nutrition formulators and Dutch fractionators lock in supply access while providing 12-18 month price visibility against feed cost volatility. These contracts insulate premium whey protein concentrate volumes from spot market swings in Polish milk solids.
Pricing Analysis
Service and certification bundling drives lifetime value for organic skim milk powder grades. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-compliant infant-grade demineralized whey from commodity bakery permeate. Cost compression in standard milk powders is intensifying because Polish cooperative feed cost volatility transmits directly to base material pricing. German beverage manufacturers show lowest price sensitivity for liquid concentrate premiums, while Polish private-label recombined dairy processors absorb highest volume elasticity.
Supply Chain Analysis
Rotterdam port logistics chokepoint underwrites pan-European powder distribution economics for Dutch spray-drying clusters. Manufacturing gravity centers on the Netherlands, Germany, and Ireland, with raw material flows drawing from Bavarian bottling corridors and Irish cooperative collection networks. Single-source vulnerability concentrates in Dutch whey fractionation capacity for specialized pediatric formulations. Distribution runs through cooperative-owned facilities disintermediating traditional trading house relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as EU Green Deal methane benchmarks force capital reallocation toward low-carbon fractionation infrastructure, accelerating replacement demand for anaerobic digestion retrofits.
For Market Incumbents: Compound defensive positioning through backward integration into Irish and Polish cooperative milk collection networks to secure captive supply against Fonterra's New Zealand-origin import competition. Prioritize membrane filtration technology licensing to capture premium protein isolate yields ahead of ceramic microfiltration maturation. Defend margin pools by accelerating organic skim milk powder certification pathway investments before 18-24 month compliance timelines extend competitive gaps. For New Entrants and Emerging Players: Differentiate on precision fractionation technology for hypoallergenic pediatric formulations where EFSA novel food dossier requirements constrain incumbent response speed. Target Polish Mazovia whey valorization infrastructure brownfield retrofits as the most penetrable geography for demineralized fraction output. Pursue direct procurement relationships with German bakery and confectionery manufacturers seeking disintermediated organic certification chain-of-custody. For Investors and Strategic Acquirers: Capital is best deployed toward membrane technology specialists with pilot-scale ceramic microfiltration deployments in French and German infant nutrition corridors. Long-term viability across the analysis window hinges on energy-adjusted protein yield positioning rather than nominal volume throughput. Watch EU AI Act quality control system classification mandates as the inflection signal for automated grading equipment upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Technology Licensing | Ceramic microfiltration pilots in France and Germany displace thermal processing for protein isolate recovery. |
| Anaerobic Digestion Retrofit | Biogas capture integration maintains Dutch fractionation license-to-operate under EU Green Deal methane ceilings. |
| Direct Procurement Agreement | German bakery manufacturers bypass trading houses for Irish organic skim milk powder chain-of-custody assurance. |
| EFSA Novel Food Dossier Investment | Specialized pediatric formulation approvals constrain cell-cultured dairy protein competitive threat timelines. |
| Cooperative Network Integration | Polish and Irish backward integration secures cost-competitive base materials against New Zealand-origin imports. |
Research Methodology
Cross-validation between primary interviews with dairy processing executives, membrane technology R&D directors, and infant nutrition formulation scientists anchors the qualitative findings against secondary validation from EFSA novel food registers, EU Green Deal implementation trackers, and cooperative milk collection statistics. Bottom-up facility capacity modeling triangulates with top-down trade flow analysis through Rotterdam port customs data.
Sensitivity analysis across protein fractionation yield assumptions, feed cost volatility bands, and regulatory compliance timeline scenarios shapes the analytical framework. Segmentation dimensions span product type, end user, form, and application purity grades across the projection horizon. CAGRs derive from installed capacity utilization rates, technology substitution curves for ceramic microfiltration, and methane benchmark compliance cost pass-through elasticity.
The analysis sits within stated boundaries; outcomes outside EU Green Deal methane enforcement intensity or EFSA approval acceleration would require recalibration. Forecasts reflect documented assumptions on membrane technology adoption curves and cooperative network consolidation patterns. Practitioners should keep alternative scenarios live as EU AI Act quality control classifications and cell-cultured dairy protein approval timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
South America Lipid Market
Ingredients
Vegetable Extract Market
Ingredients
Europe Fermented Ingredients Market
Ingredients
Europe Alcohol Ingredients Market
Ingredients
North America Rice Bran Oil Market
Ingredients
Dry Mixes Market
Ingredients
Malted Barley Flour Market
Ingredients
Asia-Pacific Fats and Oil Market
Ingredients
Non Meat Ingredients Market
Ingredients
Middle East and Africa Lipids Market
Ingredients
Fermented Ingredients Market
Ingredients
China Soy Protein Market
Ingredients
Codonopsis Extract Market
Ingredients
Black Seed Oil Market
Ingredients
Global Amaranth Oil Market
Ingredients
Middle-East and Africa Vegetable Oil Market