
 Asia-Pacific Gelatin Market | 2026-2036
Asia-Pacific Gelatin Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Gelatin Market Outlook
Modular capsule-delivery formats are broadening buyer choice across pharmaceutical and nutraceutical channels. GELITA AG leverages its European-Australian raw material network to sustain halal-certified output for Southeast Asian buyers. Darling Ingredients anchors North American sourcing capabilities that compete with regional tanners for bovine hide supply. Nitta Gelatin dominates Japanese pharmaceutical-grade production, while Luohe Wulong Gelatin controls cost-sensitive powdered segments through Henan province manufacturing scale.
Gelatin denotes a collagen-derived protein hydrolysate produced through controlled acid or alkaline processing of animal connective tissues, yielding gels with Bloom strengths typically ranging from 50 to 300 grams. The material functions as a thermoreversible gelling agent, film former, and encapsulation matrix across food, pharmaceutical, and technical applications. Pharmaceutical applications lead value capture due to stringent endotoxin and purity requirements for hard and soft capsule production. Powdered gelatin occupies the highest volume tier, though specialty gelatin variants command superior margins in personalized nutrition and clean-label confectionery segments.
China's NMPA enforces GB standards for pharmaceutical gelatin heavy metal limits, while India's CDSCO mandates traceability documentation for bovine sourcing to prevent transmissible spongiform encephalopathy contamination. Japan's PMDA aligns with JIS standards for imported gelatin used in medical devices and oral dosage forms. Australia's TGA certification requirements for bovine-derived materials shape export eligibility across the region. Stakeholders must monitor evolving halal certification protocols and traceability mandates as procurement criteria harden across Indonesian, Malaysian, and Thai buyer networks.
Market Dynamics
Pharmaceutical purity mandates from CDSCO and NMPA are compressing supplier qualification timelines while fragmenting procurement across halal-certified and bovine-traceable sourcing tiers.
Growth Catalysts
- Hard capsule demand:Indian and Chinese pharmaceutical manufacturers expand gelatin offtake as oral solid dosage production scales to serve domestic and export markets.
- GB standards enforcement:NMPA's tightened heavy metal limits for pharmaceutical-grade material are accelerating replacement of non-compliant domestic suppliers with certified alternatives.
- Halal certification protocols:Indonesian, Malaysian, and Thai buyer networks now mandate third-party halal verification, creating preference pull for Australian and New Zealand-sourced bovine material.
Market Restraints
- Bovine hide supply concentration:Regional tanners in India and Brazil compete aggressively for hide inputs, squeezing gelatin processors' raw material access and elevating input cost volatility.
- Collagen peptide substitution:Hydrolyzed collagen powders with superior cold-water solubility are displacing standard gelatin in functional beverage and sports nutrition applications.
- TSE traceability documentation:CDSCO's bovine sourcing paperwork requirements extend procurement cycles by 40-60 days for cross-border material flows.
Strategic Opportunities
- Vietnamese pharmaceutical manufacturing:Greenfield capsule production facilities in Ho Chi Minh City and Hanoi create demand for imported pharmaceutical-grade gelatin with established regulatory dossiers.
- Personalized nutrition formats:Micro-dose sachets and stick-pack delivery systems favor low-Bloom gelatin variants with rapid dissolution profiles.
- Clean-label confectionery:Japanese and South Korean confectioners are reformulating with porcine-free and single-source bovine gelatin to meet retailer sustainability scorecards.
Industry Challenges
- Endotoxin testing capacity:Pharmaceutical-grade production requires LAL or rFC assay capabilities that remain concentrated among a limited supplier base, creating qualification bottlenecks.
- Halal audit fragmentation:Competing certification bodies across Indonesia's MUI, Malaysia's JAKIM, and Thailand's CICOT impose non-harmonized facility inspection protocols that multiply compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Gelatin Market |
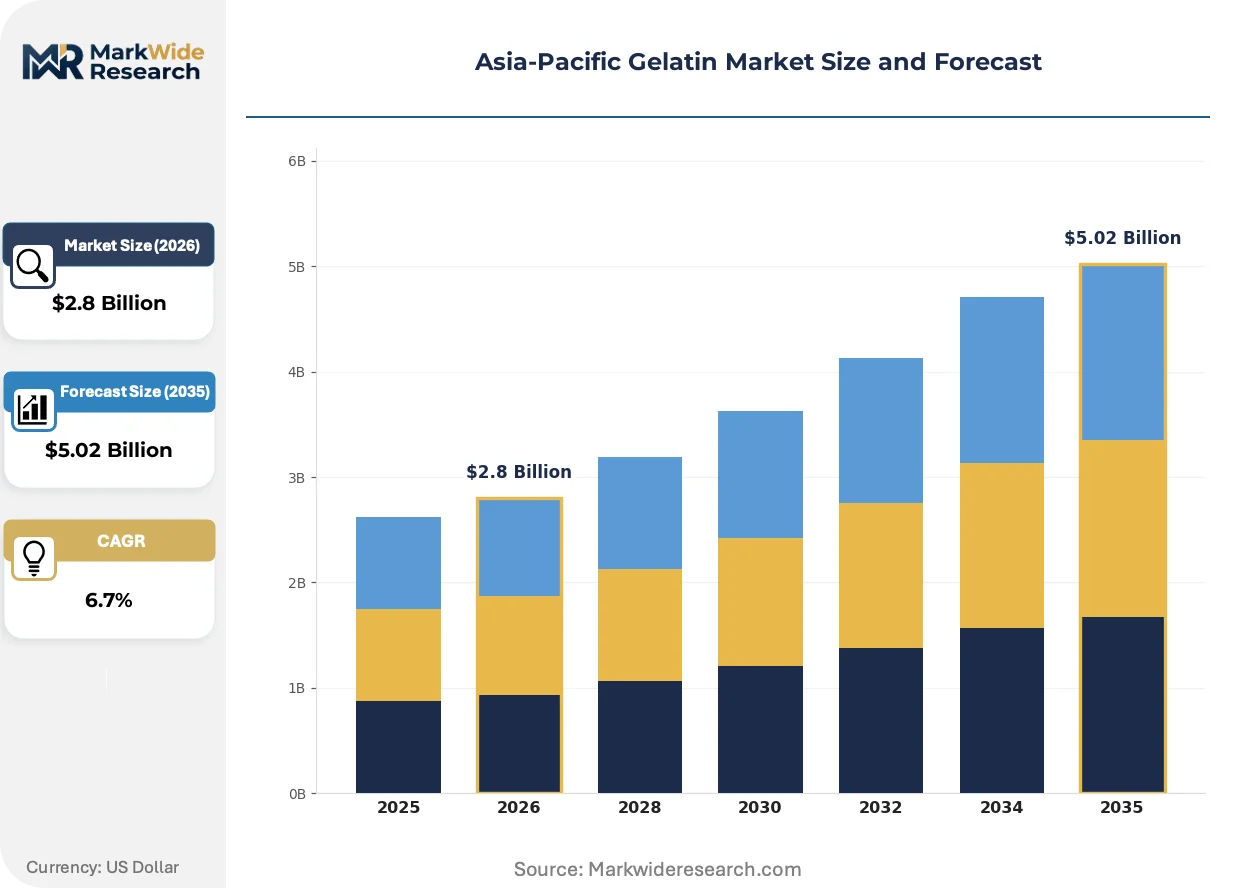
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Gelatin, Sheet Gelatin, Granular Gelatin, Capsule Gelatin, Specialty Gelatin Application: Pharmaceutical, Food & Beverage, Cosmetic, Photographic, Technical End User Industry: Nutrition, Personal Care, Imaging, Chemical Manufacturing, Animal Feed Form: Dry, Liquid, Gel, Semi-solid, Emulsion |
| Companies Covered | GELITA AG, Darling Ingredients Inc., Nitta Gelatin Inc., Jellice Group, Luohe Wulong Gelatin Co. Ltd, Asahi Gelatine Industrial Co Ltd, India Gelatine & Chemicals Ltd, Xiamen Hyfine Gelatin Co Ltd, Narmada Gelatines Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Gelatin Market Strategic Shifts
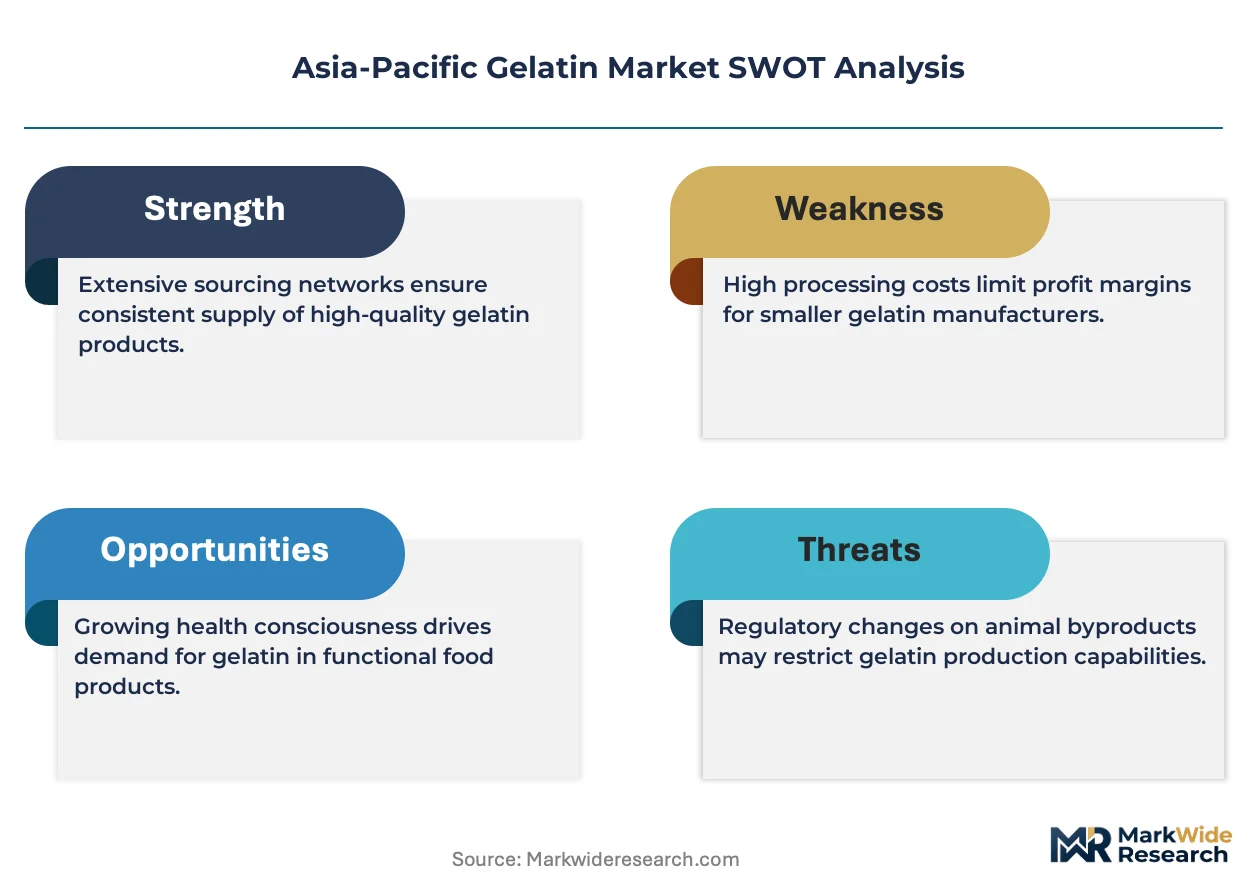
Processing technology and regulatory documentation requirements are restructuring competitive advantage around traceability infrastructure and modular manufacturing formats rather than scale alone.
Enzymatic hydrolysis protocols for gelatin extraction are modularizing production economics across Southeast Asian processors. Malaysian and Indonesian manufacturers deploy these systems to switch between food-grade and pharmaceutical-grade output within single facility footprints. This flexibility is compressing minimum viable scale thresholds and enabling mid-cap entrants to serve specialty nutraceutical contracts previously captured by integrated multinationals.
PMDA's alignment with JIS standards for imported gelatin used in medical devices is tightening documentation requirements for Australian and New Zealand exporters. Japanese pharmaceutical manufacturers now require batch-level certificates of analysis with endotoxin, heavy metal, and moisture specifications traceable to TGA-certified production lots. This regulatory convergence is favoring suppliers with pre-established multi-jurisdiction dossier libraries.
Direct procurement relationships between Japanese nutraceutical formulators and Australian bovine gelatin producers are displacing traditional trader-mediated supply chains. Large-volume buyers in Osaka and Tokyo pharmaceutical clusters now negotiate annual contracts with specified halal certification bodies and dedicated production runs. This channel compression is visible most acutely in premium capsule-grade segments where documentation transparency commands price premiums over spot-market material.
Asia-Pacific Gelatin Market Segmentation
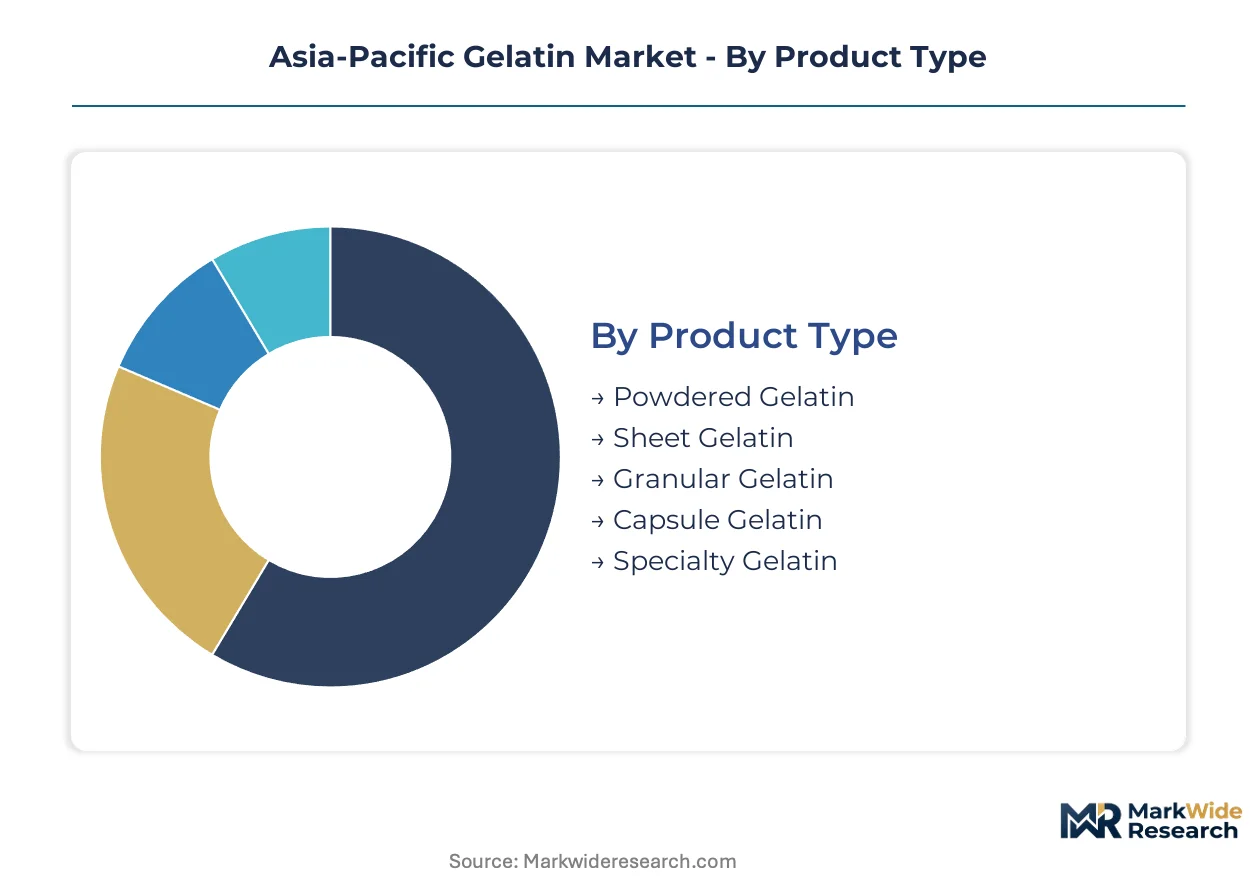
Asia-Pacific gelatin procurement decisions pivot on regulatory compliance grade, dissolution performance, and halal certification status. Buyers across pharmaceutical and nutraceutical channels segment suppliers by documentation depth rather than commodity pricing alone.
Product Type:
Powdered gelatin commands volume leadership through cost-efficient dosing in industrial food systems. Specialty variants extract margin premiums from personalized nutrition and medical device applications.
- Powdered Gelatin:Standardized 50-300 Bloom grades dominate mass-market confectionery and dairy stabilization across India and China. CDSCO-compliant documentation requirements now filter supplier pools for pharmaceutical contract manufacturers in Ahmedabad and Hyderabad.
- Capsule Gelatin:Hard and soft capsule grades require endotoxin testing below 10 EU/g and heavy metal thresholds per GB standards. NMPA-certified production lots from Henan and Shandong provinces capture expanding domestic pharmaceutical output.
- Sheet Gelatin:Bloom-standardized sheets serve premium confectionery artisans in Japan and South Korea seeking precise hydration control.
- Granular Gelatin:Rapid-dispersing granules address clean-label beverage applications across Southeast Asian functional drink formulators.
- Specialty Gelatin:Low-Bloom hydrolysates and modified gelation profiles target medical device coatings and microencapsulation systems.
Powdered gelatin leads on scale; specialty gelatin leads on momentum.
Application:
Regulatory stringency varies sharply across end-use channels, with pharmaceutical and food-grade specifications diverging on purity testing protocols.
- Pharmaceutical:Hard capsule production absorbs the highest-grade material with mandatory TSE traceability and LAL endotoxin verification. Indian CDSCO and Chinese NMPA documentation requirements compress qualified supplier lists to certified processors.
- Food & Beverage:Confectionery, dairy, and meat processing applications prioritize cost efficiency and halal certification over analytical depth. Malaysian and Indonesian buyers mandate JAKIM or MUI verification for bovine-derived inputs.
- Cosmetic:Film-forming and moisture-retention properties drive demand from South Korean skincare manufacturers.
- Photographic:Silver halide emulsion binding retains niche demand from Japanese and Chinese imaging chemical producers.
- Technical:Adhesive, match-head, and paper sizing applications absorb lower-grade material with minimal regulatory documentation.
Pharmaceutical commands value concentration; food and beverage maintains volume dominance.
End User Industry:
Customer procurement sophistication spans from commodity spot purchasing to multi-year contracted supply with dedicated production runs.
- Nutrition:Sports nutrition and dietary supplement brands in Japan and Australia specify halal-certified bovine gelatin for capsule and gummy formats. Direct sourcing relationships with Australian processors displace trader-mediated channels.
- Personal Care:South Korean and Japanese cosmetic formulators leverage gelatin-derived film formers in sheet masks and anti-aging topicals.
- Imaging:Analog photography supply chains in China sustain residual demand for silver halide emulsion-grade material.
- Chemical Manufacturing:Microencapsulation and adhesive applications absorb technical-grade output from cost-optimized processors.
- Animal Feed:Pet food palatants and livestock nutrition represent price-sensitive volume absorption for lower-grade material.
Nutrition leads on specification intensity; animal feed leads on raw tonnage.
Form:
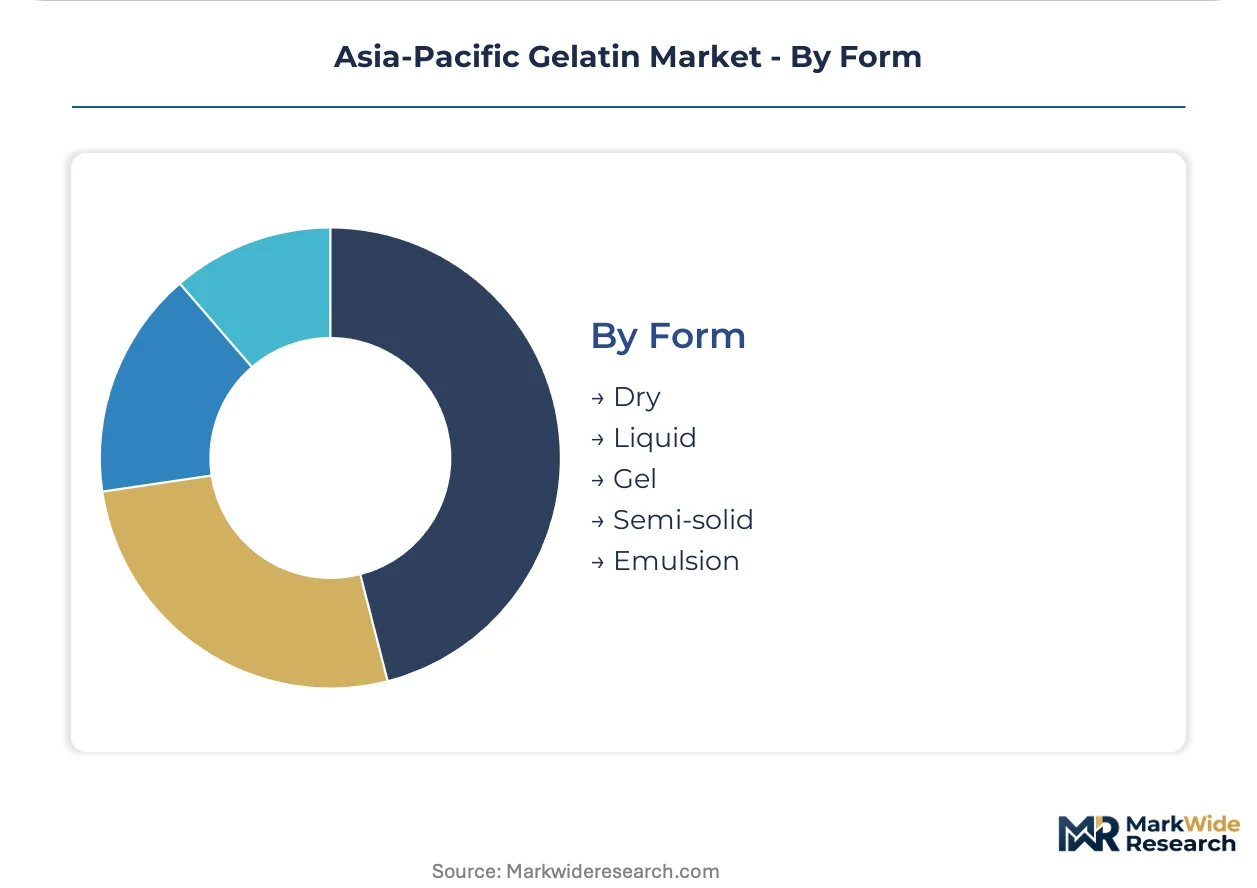
Physical state determines handling infrastructure requirements and dissolution kinetics across manufacturing environments.
- Dry:Powder and granule formats dominate warehouse-stable supply chains with extended shelf life. Japanese pharmaceutical clusters prefer pre-qualified dry stock with batch-level certificates of analysis.
- Liquid:Pre-hydrated concentrates serve food processors seeking elimination of dissolution stages. Vietnamese beverage manufacturers import liquid concentrates for streamlined production.
- Gel:Thermoreversible gel blocks target artisan confectionery and specialty dessert applications.
- Semi-solid:Intermediate hydration states facilitate controlled-release pharmaceutical formulations.
- Emulsion:Oil-in-water dispersions address cosmetic and technical coating applications requiring uniform particle distribution.
Dry form leads on logistical flexibility; liquid form climbs fastest on processing efficiency gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gelatin production in Asia-Pacific traces its industrial lineage to post-war Japan and post-reform China, where tannery-linked collagen processing scaled to serve pharmaceutical and food applications. Today regulatory divergence and halal certification requirements fragment procurement patterns across national markets.
China
Pharmaceutical-grade gelatin demand from NMPA-certified capsule manufacturers in Henan and Shandong provinces drives procurement volumes. GB standards enforcement for heavy metal limits is disqualifying domestic suppliers lacking analytical documentation. Shandong-based processors are upgrading endotoxin testing capacity to retain qualification for hard capsule contracts.
India
CDSCO-mandated TSE traceability documentation is extending procurement cycles for bovine-derived material by 40-60 days. Ahmedabad and Hyderabad pharmaceutical clusters are consolidating supplier relationships with certified processors capable of batch-level certificate provision. Regional tanneries in Tamil Nadu and West Bengal compete aggressively for hide inputs.
Japan
PMDA alignment with JIS standards for imported gelatin is tightening documentation requirements for medical device and oral dosage applications. Osaka and Tokyo pharmaceutical manufacturers now negotiate direct annual contracts with Australian bovine gelatin producers. Nitta Gelatin anchors domestic pharmaceutical-grade production from Kanto-based facilities.
Australia
TGA certification requirements for bovine-derived materials shape export eligibility across Southeast Asian buyer networks. Queensland and New South Wales processors supply halal-certified material to Indonesian, Malaysian, and Thai nutraceutical formulators. Direct procurement relationships with Japanese buyers are displacing traditional trader-mediated channels.
Vietnam
Greenfield capsule production facilities in Ho Chi Minh City and Hanoi are creating demand for imported pharmaceutical-grade gelatin with established regulatory dossiers. Local beverage manufacturers import liquid gelatin concentrates for streamlined production. Vietnamese pharmaceutical manufacturing remains dependent on certified foreign supply for high-purity material.
Asia-Pacific Gelatin Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification depth and documentation infrastructure. The vendor base organizes around three tiers: multinational integrated processors with multi-jurisdiction dossier libraries, regional specialists with halal-certified production lines, and cost-optimized domestic suppliers serving food-grade applications. Dominant competitive moves include backward integration into hide sourcing and strategic partnerships with pharmaceutical contract manufacturers for dedicated production runs.
Within the multinational integrated tier, GELITA AG and Darling Ingredients exemplify archetypes leveraging European-Australian raw material networks and North American sourcing capabilities respectively. Nitta Gelatin occupies a position representing Japanese pharmaceutical-grade specialization. These three entities anchor the premium-tier vector where batch-level traceability and multi-regulatory certification command price premiums over spot-market material.
| Leading Market Players |
|---|
| GELITA AG |
| Darling Ingredients Inc. |
| Nitta Gelatin Inc. |
| Jellice Group |
| Luohe Wulong Gelatin Co. Ltd |
| Asahi Gelatine Industrial Co Ltd |
| India Gelatine & Chemicals Ltd |
| Xiamen Hyfine Gelatin Co Ltd |
| Narmada Gelatines Limited |
| Others |
Value Chain & Pricing Dynamics
CDSCO-mandated TSE traceability documentation is forcing pharmaceutical capsule manufacturers in India and China to consolidate procurement around certified suppliers, compressing qualified vendor pools and elevating price premiums for batch-level certificate provision.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, food-grade, and technical-grade levels dominates Asia-Pacific gelatin procurement. Price differentiation rests on endotoxin testing capacity and halal certification depth, with NMPA-compliant material commanding substantial premiums over standard food-grade output. Cost compression in technical-grade segments is intensifying because regional tanners in Tamil Nadu and West Bengal compete aggressively for bovine hide inputs. Food and beverage manufacturers exhibit highest price sensitivity, while Japanese pharmaceutical clusters show least sensitivity due to documentation transparency requirements.
Supply Chain Analysis
Bovine hide supply rests on Australian, Indian, and Brazilian tannery networks competing for raw material access. Gelatin production draws from collagen-rich hide trimmings, bone chips, and acid-alkaline processing chemicals as core inputs. Single-source vulnerability concentrates around endotoxin testing capacity limited to LAL or rFC assay-equipped facilities. Distribution runs through direct annual contracts between Australian processors and Japanese pharmaceutical manufacturers, displacing traditional trader-mediated channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific gelatin procurement has shifted toward late-cycle quality concentration as PMDA and CDSCO documentation mandates harden buyer preference for certified supply chains with established multi-jurisdiction dossiers.
For Market Incumbents: Deploy backward integration into hide sourcing to secure raw material access against regional tanner competition. Anchor capacity addition in Queensland and New South Wales to serve halal-certified demand from Indonesian and Malaysian nutraceutical formulators. Deepen endotoxin testing infrastructure to defend qualification status as NMPA and CDSCO tighten purity thresholds. For New Entrants and Emerging Players: Begin with Vietnamese pharmaceutical manufacturing clusters in Ho Chi Minh City and Hanoi where greenfield capsule facilities create demand for imported pharmaceutical-grade gelatin with established regulatory dossiers. Target clean-label confectionery reformulation in Japan and South Korea as the most penetrable segment. Pursue direct sourcing relationships with Australian bovine processors as the go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap processors possessing enzymatic hydrolysis flexibility to switch between food-grade and pharmaceutical-grade output within single facility footprints. Long-term viability favors entities with pre-established TGA certification and halal audit capabilities across MUI, JAKIM, and CICOT protocols. Watch for CDSCO and NMPA documentation requirement harmonization as the inflection indicator for consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hide Sourcing | Captive supply of bovine raw materials insulates processors from Tamil Nadu and West Bengal tanner competition. |
| Halal Certification Multi-Body Coverage | Simultaneous MUI, JAKIM, and CICOT approval unlocks Indonesian, Malaysian, and Thai buyer networks. |
| Enzymatic Hydrolysis Deployment | Modular production systems enable mid-cap entrants to serve specialty nutraceutical contracts. |
| Direct Procurement Channel Establishment | Annual contracts with Osaka and Tokyo pharmaceutical clusters displace trader-mediated supply chains. |
| Endotoxin Testing Capacity Expansion | LAL or rFC assay capabilities address qualification bottlenecks for hard capsule production. |
Study Parameters
Direct dialogue with pharmaceutical procurement managers, gelatin plant operations directors, halal certification auditors, and nutraceutical formulators grounded this analysis in operational reality. Secondary validation drew from CDSCO regulatory filings, NMPA GB standards documentation, TGA certification registers, and Australian export trade records. Bottom-up demand modeling across capsule production facilities and top-down supply assessment across tannery-linked processors enabled triangulation.
Segmented outputs across pharmaceutical-grade, food-grade, and technical-grade tiers, coupled with halal certification status and regional production hub classification, structured the analytical framework. CAGRs derived from elasticity-adjusted demand projections and supply-side capacity constraints across the analysis window. Endotoxin testing capacity expansion timelines and CDSCO documentation cycle extensions served as key forecast inputs.
Several conditions sit outside the modeled scope, including abrupt bovine spongiform encephalopathy outbreaks, halal certification body recognition withdrawals, and collagen peptide substitution acceleration beyond functional beverage segments. Forecasts reflect documented assumptions on regulatory enforcement continuity and hide supply competition intensity. A small set of named triggers warrants ongoing watch: NMPA heavy metal limit revisions, JAKIM-MUI audit protocol harmonization, and Vietnamese pharmaceutical manufacturing investment acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
United States Protein Market
Ingredients
Hydroxytyrosol Market
Ingredients
Almond Flour Market
Ingredients
Cooking Oil Market
Ingredients
Global Organic Personal Care Ingredients Market
Ingredients
Global Yeast Market
Ingredients
United Kingdom Gelatin Market
Ingredients
Africa Soy Protein Ingredients Market
Ingredients
RTD/High Strength Premixes Market
Ingredients
Soy Derivatives Market
Ingredients
Dry Brewing Ingredients Market
Ingredients
North America Potato Protein Market
Ingredients
Egg Albumin Protein Market
Ingredients
Wort Concentrate Market
Ingredients
Marine Protein Market
Ingredients
Omega 9 Market