
 Polydextrose Ingredients Market | 2026-2036
Polydextrose Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Polydextrose Ingredients Market Analytics
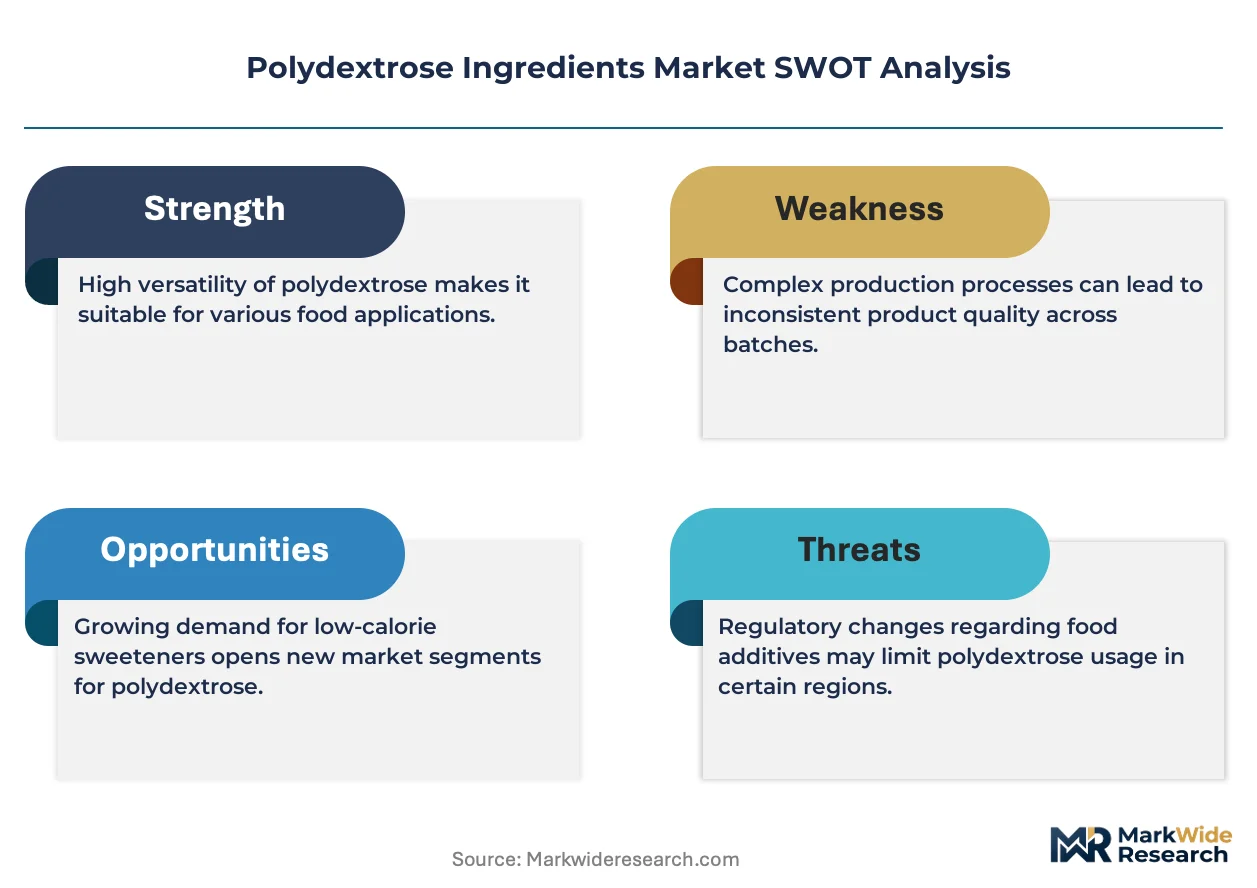
REACH compliance is rebalancing the cost-of-entry calculus for European polydextrose suppliers, forcing reformulation investments that favor established producers with dedicated regulatory teams. Tate & Lyle PLC leverages its London-based technical center to sustain EFSA-compliant fiber claims across multiple jurisdictions. Roquette Frères anchors its position through backward integration into sorbitol and citric acid feedstocks. CJ CheilJedang competes aggressively in Asian markets with specialized grades for reduced-sugar confectionery applications.
Polydextrose is a randomly bonded condensation polymer of glucose, containing minor amounts of bound sorbitol and citric acid, with a molecular weight range of approximately 2,000-22,000 daltons and minimal digestibility in the human small intestine; manufacturers synthesize it via melt-phase polymerization followed by purification to achieve specified fiber content for food-grade applications. The ingredient functions primarily as a bulking agent and soluble dietary fiber source in reduced-calorie and reduced-sugar formulations where it replaces sucrose or fat while maintaining texture and mouthfeel. Sweeteners occupy the dominant product category as polydextrose's humectant properties prove essential in sugar-free hard candies and chewing gums across European and North American markets. Bakery Goods represents the fastest-growing application segment as artisan and industrial bakers incorporate polydextrose to achieve clean-label fiber claims without compromising crumb structure or shelf stability.
The FDA maintains specific guidance on polydextrose's classification as a dietary fiber under the Nutrition Facts Label final rule, while EFSA evaluates novel fiber health claims through centralized scientific assessment procedures that determine market access across EU member states. China's NMPA and SAMR jointly oversee food additive approvals and GB standard compliance for polydextrose used in domestic functional foods and special dietary formulations. Stakeholders must monitor evolving fiber definition harmonization between Codex Alimentarius and national regulators, as divergence in analytical methodologies for total dietary fiber measurement threatens to fragment formulation strategies and complicate multi-territory product registrations.
Market Dynamics
Functional beverage manufacturers are accelerating polydextrose adoption for low-calorie fiber fortification, while the FDA's updated dietary fiber definition has clarified regulatory standing for North American product developers.
Growth Catalysts
- FDA Fiber Definition Clarity:The Nutrition Facts Label final rule removed formulation uncertainty for US product developers, enabling faster new product introductions.
- China's Aging Demographics:Domestic nutraceutical firms are expanding soluble fiber portfolios to serve health-conscious elderly consumers in tier-one cities.
- Reduced-Sugar Confectionery:Sugar-free hard candies and chewing gums across European markets require polydextrose's humectant properties for texture stability.
Market Restraints
- REACH Compliance Burden:European suppliers face reformulation investments that favor established producers with dedicated regulatory teams.
- Feedstock Concentration:Backward integration into sorbitol and citric acid feedstocks limits supplier flexibility and raises barriers for new entrants.
- Analytical Methodology Divergence:Non-harmonized total dietary fiber measurement between Codex Alimentarius and national regulators complicates multi-territory registrations.
Strategic Opportunities
- Clean-Label Bakery Positioning:Artisan and industrial bakers incorporate polydextrose to achieve fiber claims without compromising crumb structure or shelf stability.
- Asian Reduced-Sugar Applications:Specialized grades for confectionery applications show traction in South Korea and Japan as sugar reduction mandates tighten.
- EFSA Novel Fiber Pathway:Centralized scientific assessment procedures for health claims create a unified market access mechanism across EU member states.
Industry Challenges
- Regulatory Talent Scarcity:Multi-jurisdiction fiber claim navigation requires specialists fluent in FDA, EFSA, and NMPA submission protocols simultaneously.
- Purification Capex Intensity:Melt-phase polymerization followed by fiber-content purification demands continuous capital reinvestment for food-grade specification maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polydextrose Ingredients Market |
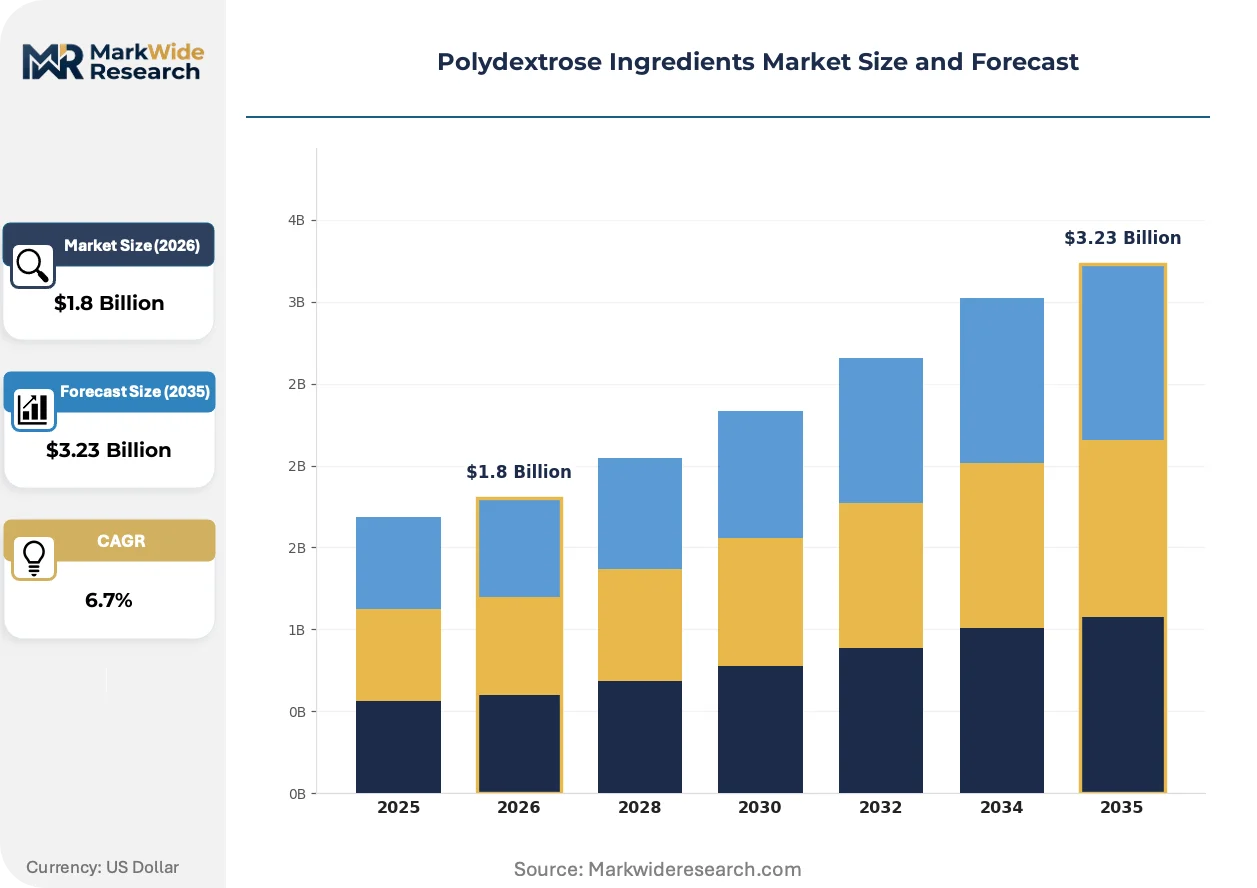
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweeteners, Stabilizers, Thickeners, Emulsifiers Application: Beverages, Confectionery, Dairy Products, Bakery Goods End User: Food Manufacturers, Pharmaceutical Companies, Nutraceutical Firms, Beverage Producers Distribution Channel: Online Retail, Direct Sales, Wholesale, Specialty Stores |
| Companies Covered | Tate & Lyle PLC, DuPont de Nemours, Inc., Henan Tailijie Biotech, Roquette Frères, Ingredion Incorporated, Cargill Incorporated, CJ CheilJedang, Samyang Corporation, Baolingbao Biology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polydextrose Ingredients Market Evolving Landscape
Enzymatic modification techniques are rewriting how polydextrose achieves specified molecular weight distributions, enabling tighter control over digestive resistance profiles.
Advanced enzymatic processing is rewriting the competitive landscape for premium-grade polydextrose production. Specialty ingredient houses in Germany and the Netherlands are adopting these systems to achieve narrower molecular weight ranges within the 2,000-22,000 dalton specification. This precision is compressing quality differentiation between established suppliers and specialized biotech entrants.
REACH registration deadlines for polymer additives are forcing European manufacturers to consolidate purification workflows or exit food-grade markets entirely. The ECHA evaluation process for existing substances has extended compliance timelines for smaller producers. Functional beverage formulators in France and Italy are accelerating supplier qualification audits to secure compliant material ahead of regulatory cutoffs.
Direct procurement from ingredient technology platforms is displacing traditional distributor relationships among mid-sized nutraceutical compounders. These buyers now specify fiber content, bound sorbitol ratios, and citric acid residuals through digital specification tools. The shift is most visible in China's Guangdong and Zhejiang provinces, where domestic brands bypass import agents to contract directly with polydextrose synthesis facilities.
Polydextrose Ingredients Market Segmentation
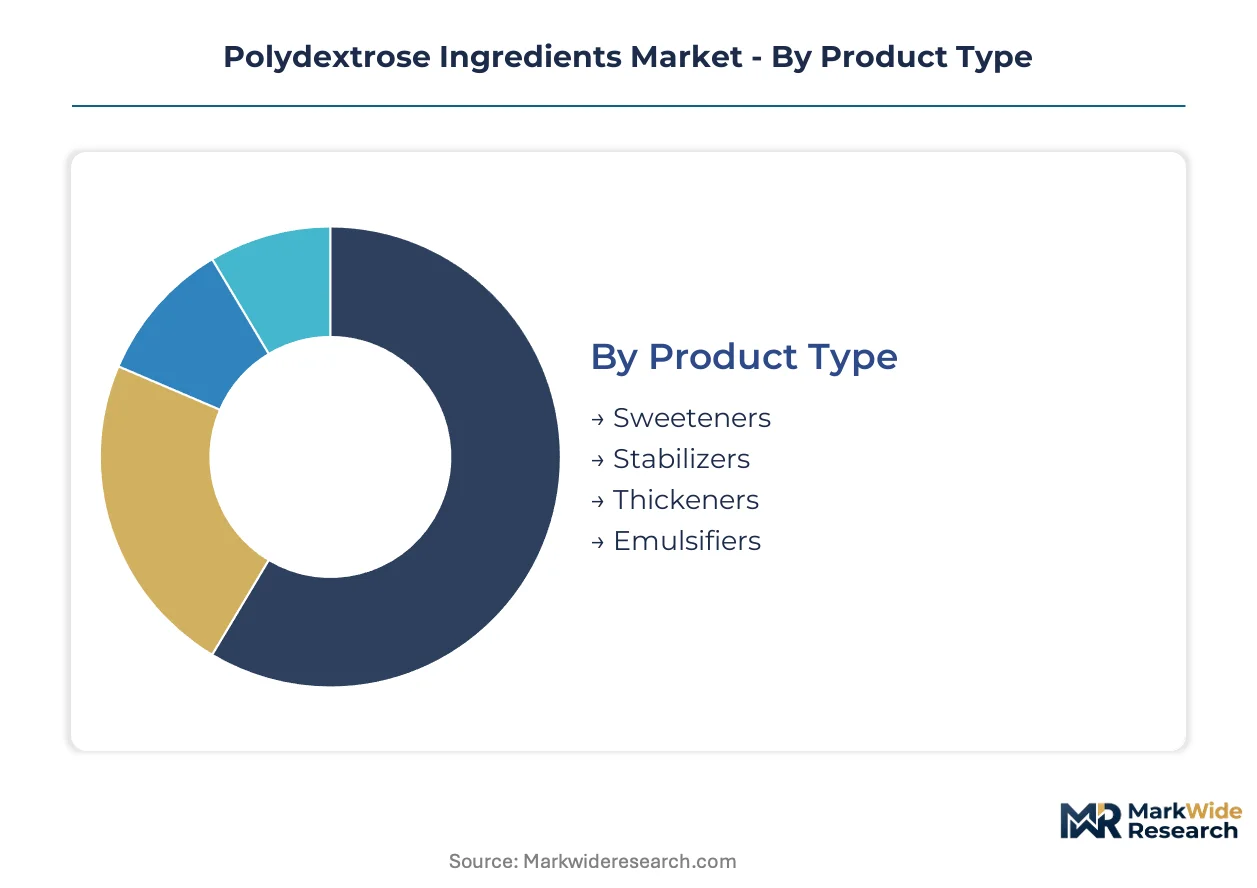
Polydextrose ingredient suppliers configure production assets around distinct functional specifications and end-use performance requirements. Capital deployment decisions hinge on which segments command premium pricing and which require specialized purification infrastructure.
Product Type:
Sweetener-grade polydextrose demands the heaviest upfront investment in melt-phase polymerization reactors and molecular weight control systems.
- Sweeteners:These grades contain tightly controlled glucose polymer chains with bound sorbitol ratios optimized for humectancy in sugar-free formulations. Functional beverage producers in China and the United States specify these grades for low-calorie fiber fortification where FDA fiber definition clarity has reduced regulatory uncertainty.
- Stabilizers:Modified molecular weight distributions enhance freeze-thaw stability in frozen dessert applications. European dairy processors favor these specifications for clean-label ice cream formulations where EFSA-compliant fiber claims support premium positioning.
- Thickeners:Higher molecular weight fractions provide viscosity building without caloric contribution.
- Emulsifiers:Specialized citric acid incorporation levels improve fat replacement functionality in reduced-calorie spreads.
Sweeteners absorb the bulk of installed capacity; stabilizers are expanding most quickly.
Application:
Volume concentration varies sharply by application, with beverage and bakery channels driving divergent specification requirements.
- Beverages:Ready-to-drink functional drinks require rapid-dissolving, low-viscosity polydextrose grades that integrate seamlessly into high-speed bottling lines. South Korean and Japanese manufacturers lead adoption here as sugar reduction mandates tighten across East Asian markets.
- Bakery Goods:Artisan and industrial bakers incorporate polydextrose to achieve fiber claims without compromising crumb structure or shelf stability. This segment demands precise moisture-binding characteristics that prevent staling in extended-distribution bread products.
- Confectionery:Hard candy and chewing gum applications depend on polydextrose's crystallization inhibition properties.
- Dairy Products:Yogurt and fermented milk applications require fermentation-compatible grades that resist microbial degradation.
Beverages dominate current procurement volumes; bakery goods show the steepest expansion trajectory.
End User:
Customer scale determines service intensity, with pharmaceutical buyers imposing the most stringent documentation and audit requirements.
- Food Manufacturers:Large-scale bakery and confectionery operations purchase polydextrose in bulk tote quantities with customized fiber content certifications. These buyers leverage direct procurement platforms to bypass traditional distribution markups.
- Nutraceutical Firms:China's domestic brands in Guangdong and Zhejiang provinces contract directly with synthesis facilities for specialized grades targeting aging consumers in tier-one cities.
- Beverage Producers:Functional drink specialists require just-in-time delivery and rapid specification adjustments.
- Pharmaceutical Companies:Excipient-grade polydextrose for tablet binders demands full regulatory dossiers and GMP compliance documentation.
Food manufacturers represent the largest addressable base; nutraceutical firms are gaining share fastest.
Distribution Channel:
Channel economics reflect buyer sophistication and order fragmentation patterns across customer tiers.
- Direct Sales:Major polydextrose producers maintain technical service teams for large food manufacturers requiring formulation support. This channel captures the highest margin realization through specification customization and long-term supply agreements.
- Online Retail:Digital procurement platforms enable mid-sized compounders to specify fiber content, bound sorbitol ratios, and citric acid residuals through automated specification tools.
- Wholesale:Regional distributors stock standard grades for smaller bakeries and confectionery operations with less complex technical requirements.
- Specialty Stores:Ingredient boutiques serve artisan producers seeking small-batch quantities with specialized certifications.
Direct sales command the greatest revenue concentration; online retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in China where domestic nutraceutical firms expand soluble fiber portfolios for aging consumers, while regulatory clarity in the United States accelerates new product introductions. European suppliers navigate REACH compliance deadlines that favor established producers with dedicated technical teams.
China
Functional beverage manufacturers in Guangdong and Zhejiang provinces contract directly with synthesis facilities for specialized grades targeting tier-one city consumers. SAMR and NMPA jointly oversee GB standard compliance for polydextrose used in functional foods and special dietary formulations. Shanghai and Shenzhen clusters host the fastest-growing procurement volumes as domestic brands bypass import agents.
United States
The FDA's Nutrition Facts Label final rule removed formulation uncertainty for product developers, enabling faster fiber fortification in reduced-calorie beverages. Tate & Lyle PLC leverages its technical center to sustain compliant fiber claims across multiple jurisdictions. Chicago and Minneapolis industrial corridors concentrate bulk purchasing from large-scale bakery and confectionery operations.
Germany
REACH registration deadlines for polymer additives force manufacturers to consolidate purification workflows or exit food-grade markets entirely. ECHA evaluation processes extend compliance timelines for smaller producers. Cologne and Hamburg clusters witness accelerated supplier qualification audits from functional beverage formulators securing compliant material ahead of regulatory cutoffs.
South Korea
Sugar reduction mandates tighten across East Asian markets, driving demand for rapid-dissolving, low-viscosity polydextrose grades in ready-to-drink functional drinks. MFDS oversees food additive approvals for domestic and imported fiber ingredients. Seoul and Busan manufacturing corridors lead adoption as CJ CheilJedang competes aggressively with specialized confectionery grades.
France
EFSA's centralized scientific assessment procedures for novel fiber health claims create unified market access across EU member states. Roquette Frères anchors its position through backward integration into sorbitol and citric acid feedstocks. Lille and Lyon industrial zones concentrate clean-label ice cream formulation activity where EFSA-compliant fiber claims support premium positioning.
Polydextrose Ingredients Market Competitive Landscape
European producers anchor the premium-tier segment; Asian specialists hold volume positions in reduced-sugar applications. The vendor base splits between consolidated multinational ingredient houses and regional biotech entrants with enzymatic processing capabilities. Three archetypes dominate: backward-integrated feedstock controllers, enzymatic modification specialists, and direct-procurement platform operators. Capacity expansion and regulatory dossier accumulation constitute the dominant competitive moves as REACH deadlines approach.
Among London-based ingredient houses, Tate & Lyle PLC exemplifies the regulatory-compliant archetype through multi-jurisdiction fiber claim navigation. Roquette Frères represents the backward-integrated model with captive sorbitol and citric acid supply chains. CJ CheilJedang occupies a position as the Asian specialist competing on confectionery-grade customization for sugar-reduced formulations.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| DuPont de Nemours, Inc. |
| Henan Tailijie Biotech |
| Roquette Frères |
| Ingredion Incorporated |
| Cargill Incorporated |
| CJ CheilJedang |
| Samyang Corporation |
| Baolingbao Biology |
| Others |
Value Network & Pricing Analysis
Premium-grade enzymatic modification separates from commodity melt-phase polymerization across both pricing power and supply chain complexity. REACH-compliant European producers command sustained premiums through dedicated regulatory teams and backward-integrated sorbitol supply, while Asian commodity synthesis facilities compete on volume scale with thinner documentation support.
Pricing Analysis
Volume concentration in sweetener-grade polydextrose compresses margins, while specialty stabilizer and emulsifier tiers retain pricing power through certification depth. Three-tier pricing structure across premium, standard, and economy levels tracks EFSA novel fiber claim status, FDA fiber definition clarity, and GB standard compliance as differentiation drivers. Cost compression in economy grades intensifies as Chinese domestic brands bypass import agents for direct synthesis facility contracts. Nutraceutical firms in tier-one cities show least price sensitivity due to aging-demographic premium positioning, while industrial bakeries negotiate aggressively on bulk tote volumes.
Supply Chain Analysis
Single-source vulnerability sits with European sorbitol and citric acid feedstock controllers given REACH registration deadline consolidation. Manufacturing gravity centers on China, France, and South Korea, with melt-phase polymerization capacity drawing from captive sorbitol supply chains in Lille and Busan. Tariff exposure runs through intermediate polydextrose shipments subject to evolving EU-China trade enforcement. Distribution runs through direct procurement platforms displacing traditional wholesale relationships among mid-sized compounders in Guangdong and Zhejiang provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic modification techniques are displacing legacy melt-phase polymerization as the dominant production paradigm, compressing quality differentiation between established suppliers and biotech entrants. This technology transition rewards regulatory dossier accumulation and precision molecular weight control capabilities.
For Market Incumbents: Cement EFSA-compliant fiber claim positions through centralized scientific assessment dossiers before REACH registration deadlines eliminate smaller competitors. Tate & Lyle PLC's London-based technical center exemplifies multi-jurisdiction navigation that protects premium positioning against enzymatic modification specialists entering from Germany and the Netherlands. Backward integration into sorbitol and citric acid feedstocks remains the critical defensive lever. For New Entrants and Emerging Players: The premium-to-economy price-point gap in bakery-grade stabilizers offers white-space entry for enzymatic processing specialists with narrower molecular weight distribution capabilities. South Korean and Japanese reduced-sugar confectionery applications show highest penetrability given tightening sugar reduction mandates. Direct procurement platform relationships with domestic Chinese brands in tier-one cities provide the fastest go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with enzymatic modification specialists given EFSA novel fiber pathway centralization and REACH compliance consolidation as catalysts. Long-term viability across the analysis window favors producers with demonstrated multi-jurisdiction regulatory dossier accumulation. The signal to watch is ECHA evaluation timeline extensions forcing smaller European producers into distressed exit scenarios.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Modification Adoption | German and Dutch specialty houses achieve tighter molecular weight control than melt-phase legacy systems. |
| REACH Registration Consolidation | ECHA evaluation deadlines force purification workflow consolidation or food-grade market exit. |
| Direct Procurement Platform Buildout | Mid-sized Chinese nutraceutical compounders bypass import agents for synthesis facility contracts. |
| EFSA Novel Fiber Dossier Accumulation | Centralized scientific assessment procedures create unified EU market access mechanisms. |
| Backward Integration into Sorbitol | Roquette Frères anchors position through captive feedstock supply chains in Lille. |
Research Methodology
Document review covered FDA Nutrition Facts Label guidance, EFSA novel fiber assessment procedures, SAMR GB standard filings, and REACH registration timelines, complemented by interviews with technical directors at European ingredient houses, procurement leads at Chinese nutraceutical brands, regulatory affairs specialists navigating ECHA processes, and plant managers at enzymatic modification facilities. Secondary validation drew from customs trade data, SEC 10-K disclosures, and food additive approval databases. Bottom-up segment sizing triangulated against top-down market construction.
Segment-level projections incorporated product type specifications, application performance requirements, end-user scale tiers, and distribution channel economics across the modeling period. CAGRs derived from historical volume trajectories, regulatory deadline impacts, and technology adoption curves. Forecast inputs included enzymatic processing penetration rates, REACH compliance cost pass-through assumptions, and direct procurement platform displacement patterns.
Underlying measurement precision varies by segment; sweetener-grade volumes carry tighter precision than specialty emulsifier niches given standardized specifications. Forecasts reflect documented assumptions about regulatory harmonization timelines and feedstock cost stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
South America Lipid Market
Ingredients
Rice Starch Market
Ingredients
Soy Hydrolysates Market
Ingredients
Mung Bean Starch Market
Ingredients
Potato Fiber Market
Ingredients
L-Arabinose Market
Ingredients
Codonopsis Extract Market
Ingredients
Avocado Powder Market
Ingredients
Low Fat Oil Market
Ingredients
Cognitive Ingredients Market
Ingredients
Carob Powder Market
Ingredients
All Purpose Flour Market
Ingredients
Avocado Oil Market
Ingredients
Cocoa Based Polyphenols Market
Ingredients
Vitamin C Ingredients Market
Ingredients
Coconut Oil Market