
 Asia-Pacific Lipids Market | 2026-2036
Asia-Pacific Lipids Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Lipids Market Outlook
Pharmaceutical companies are bifurcating from traditional food manufacturers as the dominant buyer archetype in Asia-Pacific lipid procurement. Cargill Incorporated leverages its integrated oilseed crushing network across Southeast Asia to secure raw material access. BASF SE anchors high-purity phospholipid supply for injectable drug formulations through German-engineered refining protocols adapted to regional facilities. Wilmar International dominates palm-derived triglyceride volumes with backward integration into Indonesian plantation assets.
Lipids comprise a broad class of hydrophobic or amphiphilic organic molecules including phospholipids, triglycerides, fatty acids, and sterols, typically characterized by hydrocarbon chain lengths of 12 to 24 carbons and melting points governed by saturation degree; these compounds serve as structural membrane components, energy storage media, and signaling molecule precursors across industrial applications. Fatty acids command the largest volume share in food and beverages where frying stability and shelf-life extension drive procurement economics. Phospholipids represent the fastest-expanding product category within pharmaceuticals as liposomal drug delivery systems gain clinical traction. Plant-based sources maintain cost leadership while microbial platforms capture margin pools in nutraceuticals where algal DHA commands certification premiums.
China's NMPA enforces pharmaceutical-grade lipid purity thresholds for excipient use in drug formulations, while India's CDSCO mandates microbial sterility documentation for lipid-based parenteral products. Japan's METI promotes bio-based lipid feedstock substitution through circular economy directives affecting import qualification criteria. Stakeholders must monitor regulatory divergence between national pharmacopeias when configuring regional manufacturing footprints and qualification dossiers.
Market Dynamics
Pharmaceutical-grade lipid procurement in Asia-Pacific is bifurcating as CDSCO and NMPA purity mandates force dedicated supply chains separate from food-grade channels, concentrating qualified capacity in Shandong and Jiangsu clusters.
Growth Catalysts
- Liposomal drug delivery:Injectable formulations for oncology and vaccines are absorbing high-purity phospholipid volumes previously allocated to nutraceuticals.
- FSSAI labeling tightening:India's nutraceutical standards are redirecting algal DHA sourcing toward microbial fermentation platforms with documented sterility chains.
- Shandong oleochemical clusters:Integrated fatty acid refining infrastructure is capturing pharmaceutical excipient qualification contracts from fragmented Southeast Asian processors.
Market Restraints
- Palm oil input volatility:Indonesian plantation supply disruptions propagate directly into triglyceride cost structures for regional formulators.
- Microbial sterility documentation:CDSCO parenteral lipid mandates create 18-24 month qualification timelines that freeze out mid-scale suppliers.
- Algal DHA certification premiums:Third-party sustainability verification adds 15-20% effective cost versus unverified fish oil alternatives in price-sensitive mass-market channels.
Strategic Opportunities
- Vietnam pharmaceutical manufacturing:Greenfield parenteral drug facilities are sourcing lipid excipients from qualified regional suppliers rather than European imports.
- Dual carbon goals alignment:China's MEE circular economy directives are creating preferential procurement status for bio-based lipid feedstocks in state tender processes.
- Direct-to-brand nutraceutical channels:E-commerce platforms are collapsing traditional distributor layers for omega-3 finished goods, enabling margin capture by upstream lipid processors.
Industry Challenges
- Pharmaceutical lipid purification:Chromatographic separation expertise for injectable-grade phospholipids is concentrated among German-trained engineering teams with limited regional availability.
- Cross-border qualification dossiers:Divergent pharmacopeia standards between NMPA, CDSCO, and PMDA require parallel documentation investments that fragment batch economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Lipids Market |
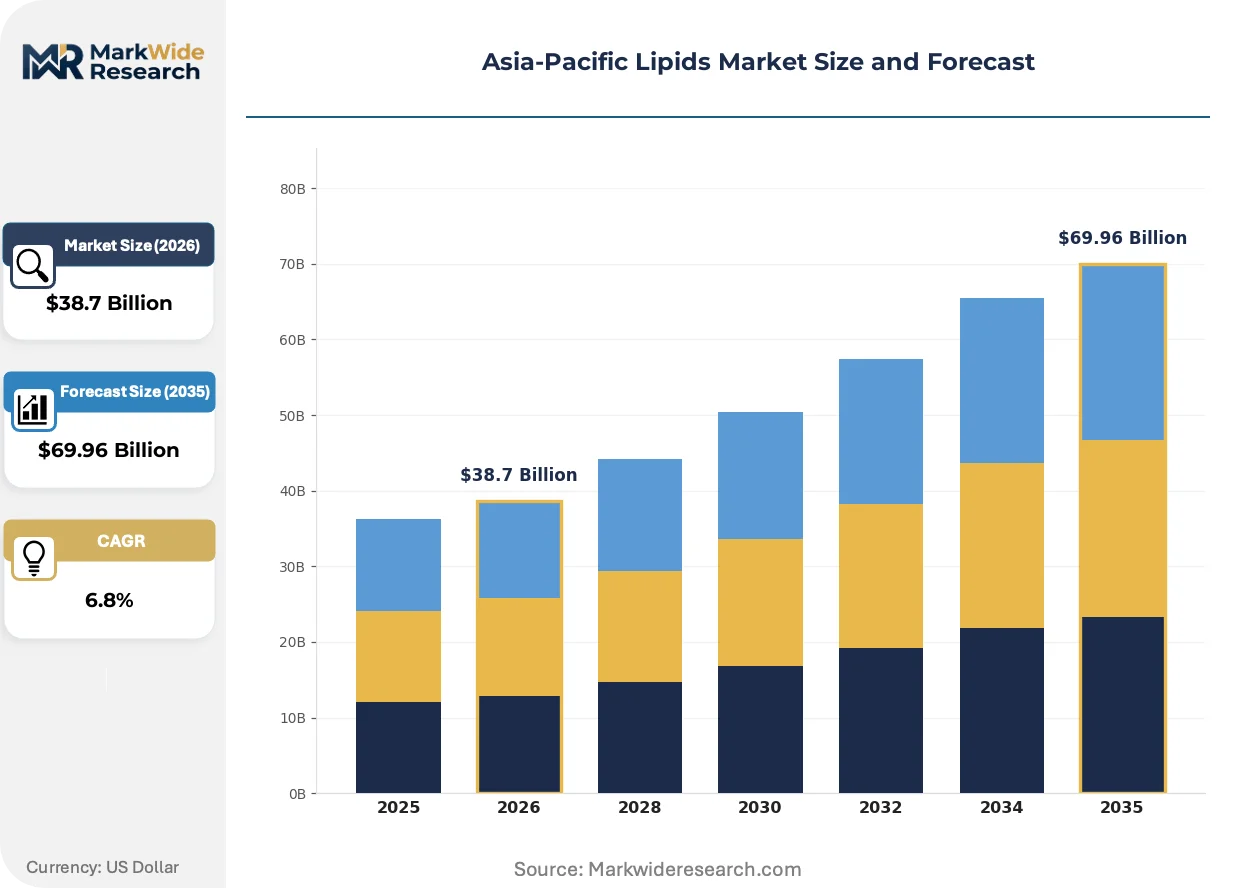
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
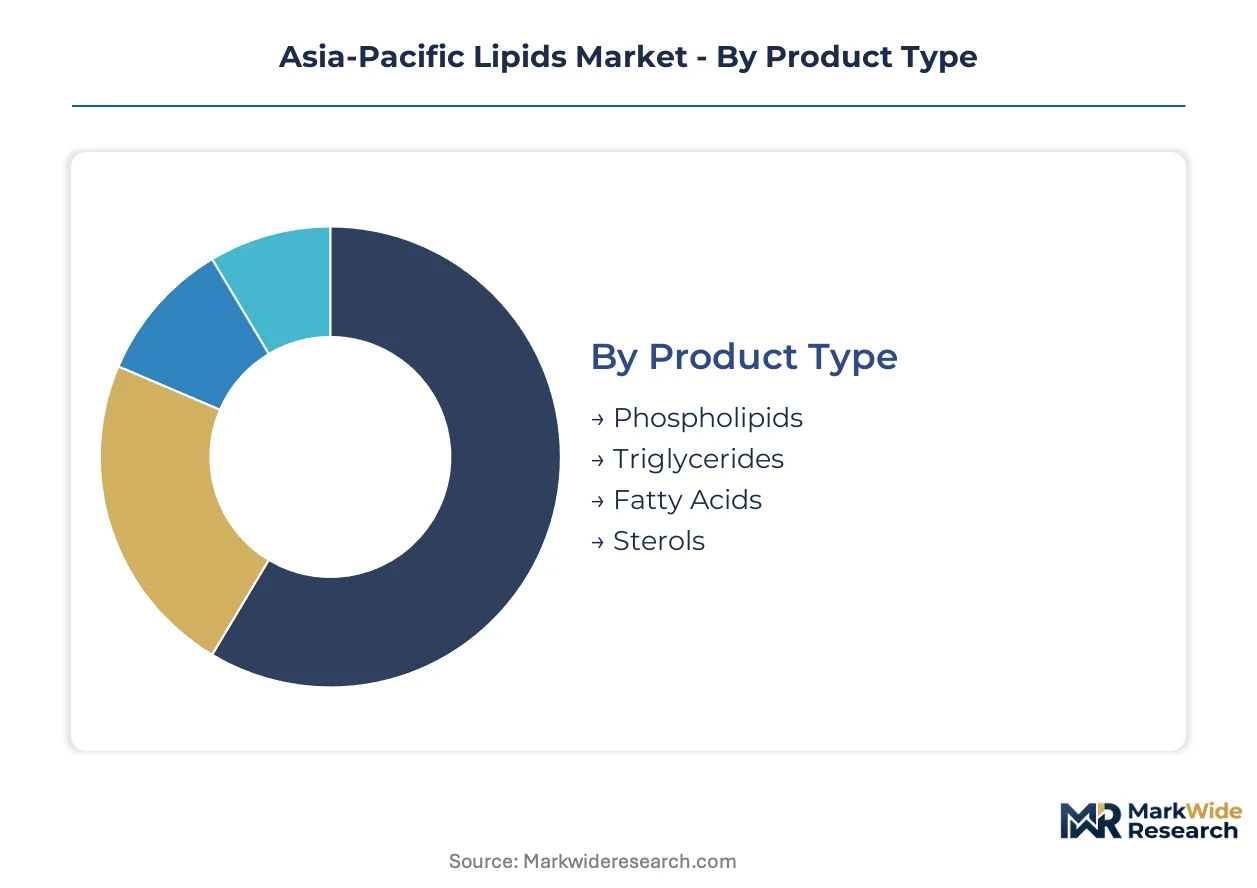
| Segmentation | Product Type: Phospholipids, Triglycerides, Fatty Acids, Sterols Application: Food & Beverages, Pharmaceuticals, Cosmetics, Nutraceuticals Source: Plant-Based, Animal-Based, Microbial, Synthetic End User: Food Manufacturers, Pharmaceutical Companies, Personal Care Brands, Dietary Supplement Producers |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Koninklijke DSM N.V., BASF SE, Kerry Group plc, Croda International Plc, Evonik Industries AG, Stepan Company, Wilmar International, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Lipids Market Strategic Shifts
Continuous processing and single-use bioreactor technologies are compressing microbial lipid production timelines while regulatory digitization is collapsing documentation cycles for pharmaceutical-grade materials.
Precision fermentation platforms for algal DHA and ARA are miniaturizing production footprints from industrial-scale stainless steel tanks to modular 50,000-liter single-use systems. Nutraceutical contract manufacturers in India are adopting these configurations to bypass capital-intensive fixed-asset investments. The technology is miniaturizing minimum viable scale thresholds, enabling distributed production closer to formulation facilities rather than concentrated coastal refineries.
Japan's METI circular economy directives are mandating bio-based feedstock substitution ratios in public procurement, creating preferential qualification pathways for microbial lipids over palm-derived alternatives. Industrial buyers are restructuring supply agreements to document renewable carbon content for compliance submissions. Pharmaceutical excipient suppliers with fermentation-based phospholipid portfolios are capturing tender advantages in METI-influenced purchasing categories.
Brand-direct procurement of lipid ingredients is displacing traditional distributor intermediaries in China's omega-3 supplement sector. E-commerce platforms are enabling finished goods manufacturers to qualify and contract upstream phospholipid processors directly, compressing margin layers and accelerating specification feedback loops. This channel disintermediation is most visible in Jiangsu and Zhejiang provinces where dietary supplement production clusters concentrate demand density sufficient to justify direct supplier relationships.
Asia-Pacific Lipids Market Segmentation
Channel configuration in Asia-Pacific lipids varies sharply by segment. Food-grade triglycerides flow through bulk commodity distributors, while pharmaceutical phospholipids demand qualified direct contracts with documented sterility chains.
Product Type:
Phospholipids and triglycerides anchor separate channel architectures. High-purity phospholipids bypass distributors entirely for parenteral drug manufacturers, whereas triglycerides move through oleochemical traders serving food and cosmetics formulators.
- Phospholipids:Amphiphilic molecules with glycerol-backboned hydrophilic head groups and dual fatty acid tails, essential for membrane structure and liposomal encapsulation. Demand concentrates in Jiangsu province where liposomal drug facilities source injectable-grade material under NMPA excipient mandates. CDSCO sterility documentation requirements extend qualification timelines to 18-24 months, freezing out commodity traders.
- Triglycerides:Energy-dense esters of glycerol and three fatty acids, dominating food frying and cosmetic emollient applications. Procurement clusters in Shandong oleochemical refineries feeding packaged food manufacturers across North China. Wilmar's backward integration into Indonesian plantation assets secures cost-competitive feedstock for regional formulators.
- Fatty Acids:Carboxylic acids with 12-24 carbon chains, split between food-grade stearic acid for confectionery and pharmaceutical-grade oleic acid for parenteral emulsions.
- Sterols:Cyclic alcohols including cholesterol and phytosterols, absorbed by nutraceutical tablet manufacturers for cholesterol-management positioning in India and China.
Triglycerides dominate installed base. Phospholipids are where expansion concentrates.
Application:
Cost tier stratification separates pharmaceutical applications from commodity food uses. Injectable-grade materials command 3-4x price multiples over food-grade equivalents, with documentation burdens determining supplier eligibility.
- Food & Beverages:Frying stability and shelf-life extension drive procurement of saturated fatty acids and modified triglycerides. Southeast Asian palm oil processors supply bulk volumes to instant noodle and snack manufacturers through regional trading houses.
- Pharmaceuticals:Liposomal oncology formulations and parenteral nutrition emulsions absorb high-purity phospholipid volumes. Japanese PMDA and Chinese NMPA pharmacopeia divergence forces parallel batch documentation that fragments economics for mid-scale suppliers.
- Cosmetics:Emollient triglycerides and phospholipid surfactants serve skin-care formulators in South Korea and Japan. Plant-derived positioning commands shelf-space premiums in clean-beauty channels.
- Nutraceuticals:Algal DHA and ARA for infant formula and omega-3 supplements. India's FSSAI labeling tightening redirects sourcing toward microbial fermentation platforms with documented sterility chains.
Food and beverages anchor volume. Pharmaceuticals are climbing the fastest.
Source:
Margin pools concentrate in microbial platforms despite higher unit costs. Certification premiums for algal DHA and fermentation-derived phospholipids capture value in regulated pharmaceutical and premium nutraceutical channels.
- Plant-Based:Palm, soybean, and rapeseed oils supply cost-leadership triglycerides and fatty acids. Indonesian plantation disruptions propagate directly into regional cost structures for food manufacturers.
- Animal-Based:Fish oil omega-3 concentrates and egg phospholipids serve nutraceutical and pharmaceutical niches. Sustainability verification gaps expose suppliers to substitution by microbial alternatives.
- Microbial:Precision fermentation platforms for algal DHA, ARA, and pharmaceutical-grade phospholipids. Single-use bioreactor adoption in India miniaturizes minimum viable scale thresholds for contract manufacturers.
- Synthetic:Chemically defined fatty acids and sterols for analytical standards and specialized pharmaceutical applications. Limited volume but irreplaceable for reference material consistency.
Plant-based sources dominate installed base. Microbial platforms are gaining share fastest.
End User:
Customer type determines contracting structure and technical service intensity. Pharmaceutical companies demand dedicated account management and joint qualification dossiers, while food manufacturers prioritize spot-market flexibility.
- Food Manufacturers:Bulk triglyceride and fatty acid buyers in China's Shandong and Jiangsu provinces. Procurement optimizes for frying stability metrics and supply security rather than purity certification.
- Pharmaceutical Companies:Injectable-grade phospholipid consumers with mandatory CDSCO, NMPA, or PMDA qualification requirements. BASF and specialized regional suppliers capture share through German-engineered refining protocols adapted to local facilities.
- Personal Care Brands:Cosmetic formulators in South Korea and Japan sourcing emollient triglycerides and surfactant phospholipids. Clean-label positioning drives preference for plant-derived and fermentation-based alternatives.
- Dietary Supplement Producers:Omega-3 encapsulators across China and India expanding phospholipid procurement for enhanced bioavailability formulations. E-commerce channel growth enables direct upstream contracting, collapsing traditional distributor layers.
Food manufacturers dominate installed base. Pharmaceutical companies are where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian plantation operators export refined palm-derived triglycerides to Chinese food manufacturers in Shandong province, establishing the dominant south-north trade corridor in Asia-Pacific lipid flows. This feedstock artery supplies oleochemical clusters that process pharmaceutical-grade fatty acids and food emulsifiers. Regional procurement patterns bifurcate between commodity bulk channels and qualified direct contracts for injectable-grade materials.
China
Shandong and Jiangsu provinces host concentrated oleochemical infrastructure feeding pharmaceutical excipient production. NMPA enforces purity thresholds for lipid materials used in drug formulations, forcing dedicated supply chain separation from food-grade channels. Integrated refineries in these coastal clusters capture qualification contracts from fragmented Southeast Asian processors.
India
Dietary supplement producers across Maharashtra and Gujarat are expanding phospholipid procurement for omega-3 encapsulation. FSSAI tightening of nutraceutical labeling standards redirects sourcing toward microbial fermentation platforms with documented sterility chains. CDSCO mandates for parenteral lipid products create 18-24 month qualification timelines that favor established suppliers.
Japan
Cosmetic formulators in the Kanto region source emollient triglycerides and phospholipid surfactants for clean-beauty positioning. METI circular economy directives mandate bio-based feedstock substitution ratios in public procurement, creating preferential pathways for microbial lipids over palm alternatives. Pharmaceutical excipient suppliers with fermentation-based portfolios capture tender advantages.
South Korea
Personal care brands in Seoul Capital Area drive demand for plant-derived emollients with sustainability verification. The national pharmaceutical regulator enforces documentation standards for lipid-based ingredients in functional cosmetics. Local contract manufacturers are adopting single-use bioreactor technologies to miniaturize production footprints.
Vietnam
Greenfield parenteral drug facilities in Ho Chi Minh City and Hanoi are sourcing lipid excipients from qualified regional suppliers rather than European imports. The country's national pharmaceutical regulator is harmonizing sterility documentation requirements with ASEAN standards. Industrial zones near these metros concentrate formulation capacity for domestic and export markets.
Asia-Pacific Lipids Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and qualification depth, creating a tiered structure where scale-driven commodity processors coexist with precision-focused pharmaceutical suppliers. The market segments into plantation-integrated traders, German-engineered refiners, and microbial fermentation specialists. Dominant competitive moves include backward integration into Indonesian plantation assets and technology licensing for single-use bioreactor deployment.
Within the integrated commodity tier, Wilmar International anchors palm-derived triglyceride supply through captive plantation access. BASF SE exemplifies the pharmaceutical-grade specialist archetype with German-engineered refining protocols. Cargill Incorporated occupies a bridging position across food and pharmaceutical channels through its Southeast Asian oilseed crushing network. These three represent distinct strategic postures rather than direct substitutability.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Koninklijke DSM N.V. |
| BASF SE |
| Kerry Group plc |
| Croda International Plc |
| Evonik Industries AG |
| Stepan Company |
| Wilmar International |
| Others |
Value Chain & Pricing Dynamics
Eighteen-to-twenty-four month CDSCO qualification timelines for parenteral lipid products concentrate pricing power among established suppliers with documented sterility chains, while compressing margins for mid-scale processors unable to absorb batch documentation costs. This lead-time barrier reinforces a bifurcated structure where pharmaceutical-grade phospholipids command substantial premiums over food-grade triglycerides sourced through commodity channels.
Pricing Analysis
Current-generation single-use bioreactor-derived phospholipids price at multiples above prior-generation stainless steel tank output, while next-generation continuous processing platforms promise further unit cost compression. Three-tier pricing structure across pharmaceutical-grade, nutraceutical-grade, and food-grade levels anchors the market, with differentiation driven by NMPA certification status and documented sterility chains. Cost compression in food-grade triglycerides is intensifying because Indonesian plantation supply disruptions propagate directly into feedstock economics. Food manufacturers exhibit highest price sensitivity, while pharmaceutical companies accept premium positioning for qualified excipient security.
Supply Chain Analysis
Port congestion at Singapore and Shanghai container terminals elevates inbound logistics costs for microbial fermentation feedstocks arriving from North American and European specialty chemical suppliers. Geographic supply concentration centers on Indonesia for palm-derived triglycerides, China for oleochemical refining capacity in Shandong and Jiangsu provinces, and India for algal DHA fermentation platforms. Raw material dependencies include crude palm oil, soybean lecithin, and glucose feedstock for precision fermentation. Single-source vulnerability characterizes pharmaceutical-grade phospholipid supply given concentration of German-engineered refining expertise. Distribution runs through qualified direct contracts for injectable-grade materials and bulk commodity traders for food applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific lipids sit in early-cycle expansion as liposomal drug delivery penetration accelerates across oncology and vaccine formulations, creating qualified supply scarcity that favors incumbent capacity holders and well-capitalized entrants.
For Market Incumbents: Consolidate qualification dossier advantages by deepening backward integration into Indonesian plantation assets and expanding Shandong oleochemical capacity dedicated to NMPA-certified excipient production. Microbial platform specialists threaten margin pools in nutraceutical channels; defend through exclusive long-term supply agreements with Jiangsu liposomal drug facilities. For New Entrants and Emerging Players: Anchor in Vietnam's greenfield parenteral manufacturing corridor where qualified regional lipid suppliers remain undersupplied versus European import dependence. Target dietary supplement contract manufacturers in Maharashtra adopting single-use bioreactor configurations for algal DHA production. Pursue direct-to-brand e-commerce channel qualification to bypass entrenched distributor layers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across microbial fermentation sub-segments as modular 50,000-liter single-use systems miniaturize minimum viable scale thresholds. Long-term viability favors precision fermentation platforms with pharmaceutical qualification pathways over commodity oleochemical exposure. Monitor CDSCO-NMPA pharmacopeia harmonization progress as signal for cross-border batch economics consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Wilmar's Indonesian captive supply secures cost-competitive triglyceride feedstock for regional formulators. |
| Single-Use Bioreactor Deployment | Modular fermentation systems enable Indian contract manufacturers to bypass capital-intensive fixed-asset investments. |
| Pharmaceutical Excipient Qualification | BASF's German-engineered refining protocols capture NMPA-mandated injectable-grade phospholipid contracts. |
| Direct-to-Brand Channel Development | E-commerce platform qualification collapses distributor layers for Jiangsu omega-3 supplement producers. |
| Bio-Based Feedstock Certification | MEE circular economy compliance creates preferential tender status for microbial lipid suppliers in China. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pharmaceutical procurement directors, dietary supplement formulators, oleochemical plant managers, and regulatory affairs specialists across China, India, and Southeast Asia. Secondary validation drew from NMPA excipient filings, CDSCO sterility documentation registries, FSSAI nutraceutical labeling directives, customs trade data for palm oil and soybean lecithin flows, and BASF SE and Wilmar International SEC disclosures. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, source, and end-user dimensions.
Across the analysis window, the forecasting framework applied segmented growth rate derivation by phospholipid versus triglyceride product lines, pharmaceutical versus food application tiers, and microbial versus plant-based source categories. CAGRs were computed from base-year installed capacity and demand penetration curves, incorporating liposomal drug facility buildout pipelines, FSSAI regulatory implementation timelines, and METI circular economy procurement quotas as industry-specific inputs.
Underlying assumptions cover sustained NMPA and CDSCO purity mandate enforcement, with deviation risk concentrated in Indonesian plantation supply disruptions and pharmacopeia harmonization delays. Practitioners should keep alternative scenarios live as microbial platform cost curves and regulatory digitization timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Homecare Ingredients Market
Ingredients
United States Whey Protein Ingredients Market
Ingredients
Cocoa Bean Extract Market
Ingredients
Mineral Premix Market
Ingredients
Europe Protein Market
Ingredients
Hydrogenated Starch Market
Ingredients
Whipped Topping Concentrate Market
Ingredients
Liquid Malt Extract Products Market
Ingredients
Middle East and Africa Fruit and Vegetable Ingredients Market
Ingredients
Cocoa Solids Market
Ingredients
Colombia Food Ingredients Market
Ingredients
Global Arabinoxylan Fiber Market
Ingredients
Cheese Powder Market
Ingredients
Asia-Pacific Brewing Enzymes Market
Ingredients
Soluble Fibers Market
Ingredients
Calcium Caseinate Market