
 North America Carrageenan Market | 2026-2036
North America Carrageenan Market Size, Share, and Industry Trends Forecast 2026-2036
North America Carrageenan Market Analytics
Modular ingredient bundling is hardening as the dominant procurement pattern, with buyers assembling carrageenan into pre-validated stabilizer systems rather than sourcing single hydrocolloids. Cargill, Incorporated leverages its integrated seaweed supply chain to anchor pricing consistency across North American dairy and meat-alternative accounts. DuPont de Nemours, Inc. differentiates through biotechnology-driven consistency in kappa-grade extraction. Ingredients Solutions, Inc. specializes in smaller-batch lambda variants for regional cosmetic formulators.
North America carrageenan comprises sulfated galactan polysaccharides extracted primarily from Chondrus crispus and Eucheuma cottonii species, with gel strength measured in Bloom values and sulfate content distinguishing kappa, iota, and lambda types; these hydrocolloids function chiefly as gelling, thickening, and stabilizing agents in thermally processed foods and topical delivery systems. The kappa segment dominates volume due to its strong synergy with potassium ions in dairy applications, while lambda carrageenan commands margin premiums in personal care emulsions where cold-process compatibility reduces energy inputs. Blended formulations are gaining fastest in plant-based beverages, as manufacturers seek single-ingredient solutions that replicate the mouthfeel of casein micelle structures.
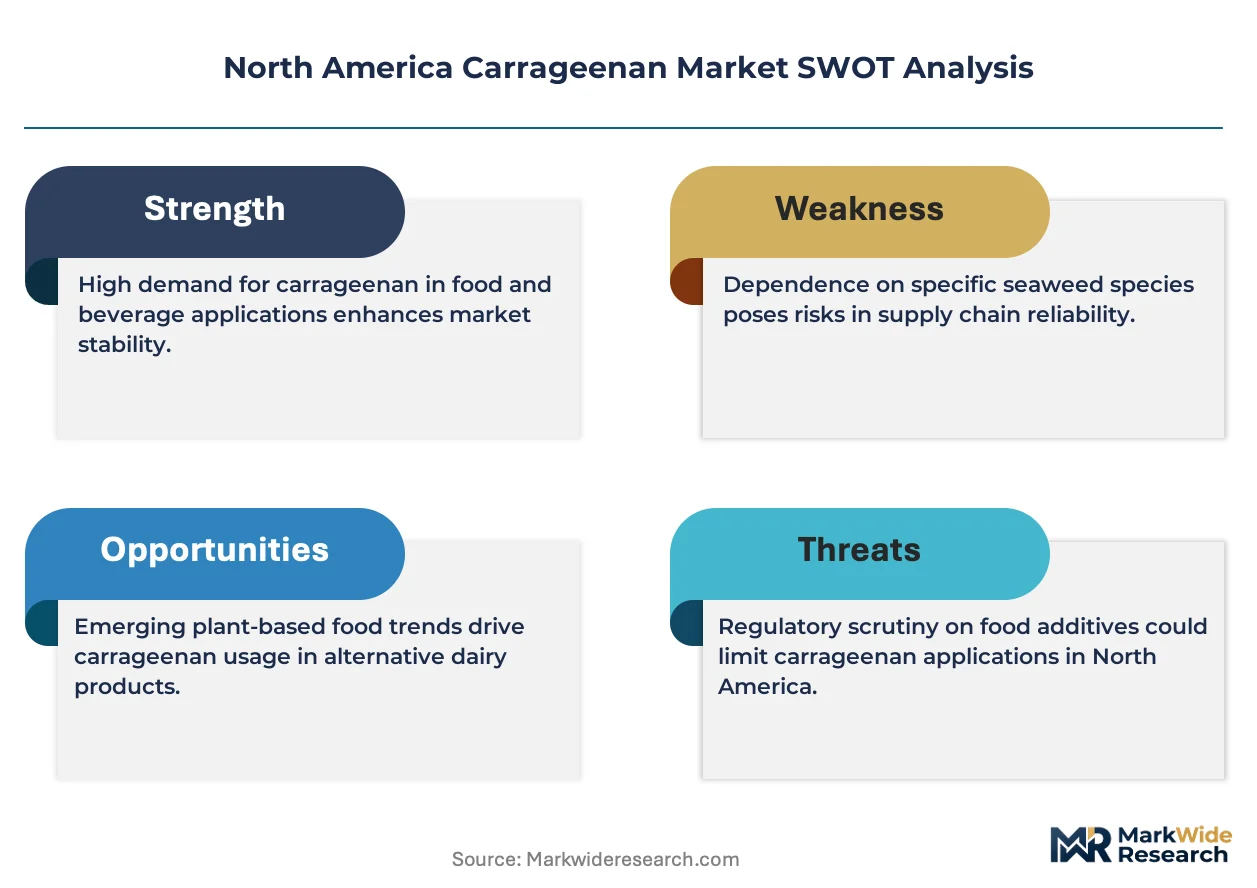
The FDA maintains GRAS oversight for food-grade carrageenan while California's Proposition 65 disclosure requirements create compliance layering for products sold across state lines. Health Canada's PMRA and the USDA's National Organic Program impose additional certification thresholds that filter market access for imported seaweed feedstocks. Stakeholders must monitor evolving state-level clean-label litigation and organic hydrocolloid traceability mandates to anticipate sourcing disruptions.
Market Dynamics
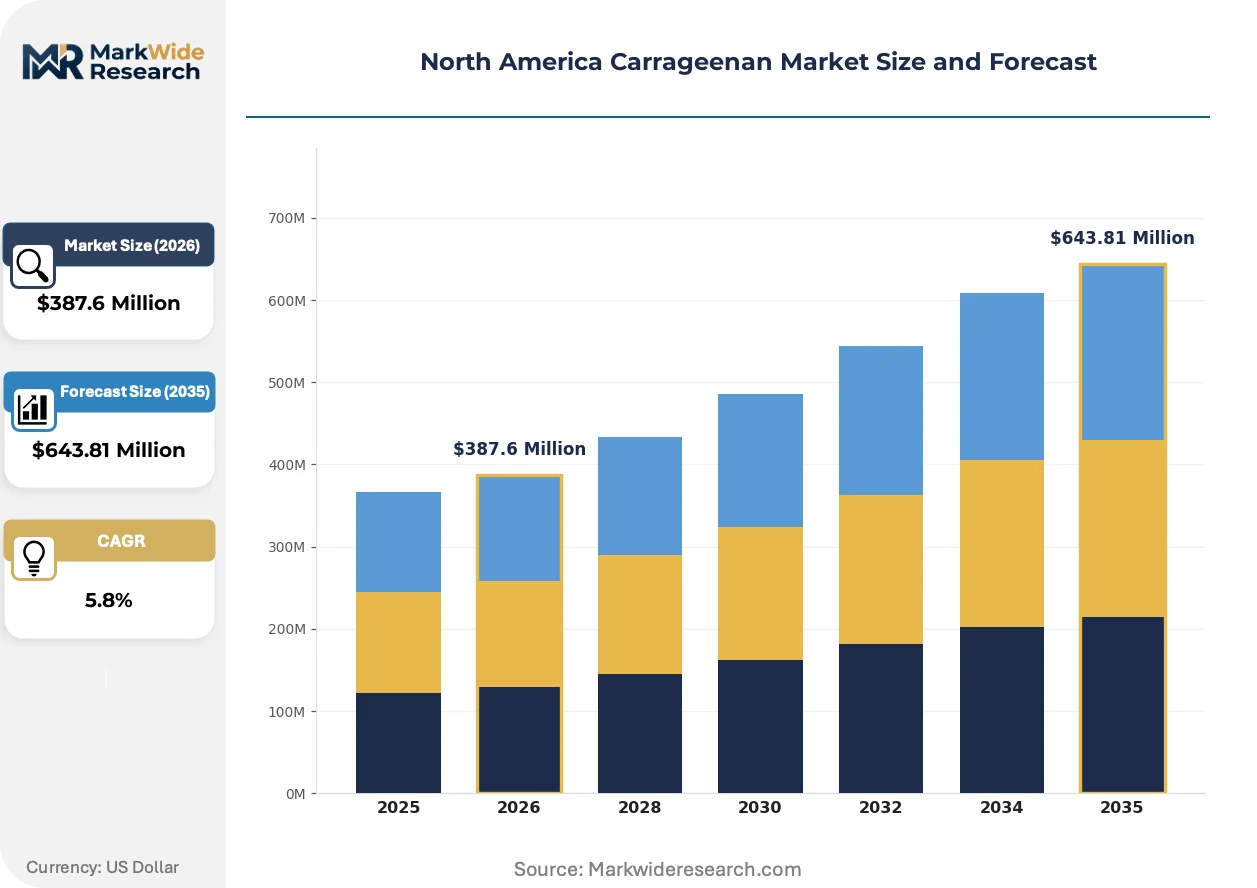
Modular ingredient bundling is hardening procurement patterns across North American food manufacturing, with buyers assembling carrageenan into pre-validated stabilizer systems rather than sourcing single hydrocolloids. This structural shift compresses supplier margins while rewarding integrated seaweed-to-hydrocolloid operators with pricing consistency.
Growth Catalysts
- Clean-label dairy alternatives:California's plant-based formulation corridor is pulling volume from food manufacturers seeking casein-mimicking mouthfeel in oat and almond beverages.
- FDA GRAS oversight tightening:Updated food additive review protocols are elevating purity benchmarks, filtering out low-grade imports and consolidating share among certified domestic processors.
- Lambda-grade cold-process compatibility:Personal care emulsion formulators value lambda carrageenan's energy-efficient integration, opening margin premiums in cosmetic applications.
Market Restraints
- Seaweed feedstock concentration:Chondrus crispus and Eucheuma cottonii sourcing clusters in Southeast Asian waters expose North American processors to shipping cost volatility and climate-related harvest disruptions.
- California Proposition 65 compliance layering:Disclosure requirements for products sold across state lines create regulatory friction that disadvantages smaller regional formulators lacking legal infrastructure.
- Guar gum substitution in beverages:Cost-sensitive beverage manufacturers are piloting guar-locust bean blends as partial carrageenan replacements in thermally processed applications.
Strategic Opportunities
- USDA National Organic Program certification:Organic hydrocolloid traceability mandates are creating tiered pricing power for certified North American seaweed cultivators.
- Blended kappa-iota systems:Single-ingredient solutions replicating dairy protein structures in plant-based cheese represent unpenetrated white space for hydrocolloid compounders.
- Health Canada PMRA alignment:Harmonized purity standards with US FDA protocols enable cross-border scale for processors investing in dual-certification infrastructure.
Industry Challenges
- Seaweed cultivation expertise scarcity:Marine agronomy talent capable of scaling Chondrus crispus tank operations remains concentrated in Atlantic Canada and coastal Maine.
- Dual-certification capex intensity:Simultaneous FDA GRAS and USDA Organic infrastructure requires multi-year capital deployment that strains mid-tier processors.
- Bloom value standardization delays:Inconsistent gel-strength measurement protocols across North American testing laboratories create specification disputes between buyers and suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Carrageenan Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kappa, Iota, Lambda, Blends Application: Food & Beverages, Pharmaceuticals, Personal Care, Industrial Distribution Channel: Direct Sales, Online Retail, Supermarkets, Distributors End User: Food Manufacturers, Cosmetic Companies, Healthcare Providers, Research Institutes |
| Companies Covered | DuPont de Nemours, Inc., Cargill, Incorporated, Ingredion Incorporated, CP Kelco U.S., Inc., Ingredients Solutions, Inc., FMC Corporation, W Hydrocolloids, Inc., Ashland Inc., TIC Gums, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Carrageenan Market Evolving Landscape
Biotechnology-driven extraction consistency and state-level clean-label litigation are actively compressing competitive timelines across North American carrageenan supply chains. Formulators now demand validated stabilizer systems rather than commodity hydrocolloids.
Enzyme-assisted extraction protocols are converging with traditional alkali processing to yield kappa-grade carrageenan with tighter Bloom value distributions. Large dairy-alternative manufacturers in California and Texas are adopting these hybrid methods at pilot scale. The technology is converging with potassium-ion synergy optimization to reduce gelling variability in plant-based cheese matrices.
California's Proposition 65 disclosure requirements are forcing reformulation cycles for carrageenan-containing products distributed across state lines. Food manufacturers serving multi-state retail channels must now maintain parallel label inventories or remove carrageenan entirely. The policy most affects mid-sized beverage brands lacking dedicated regulatory affairs functions.
Ingredient bundling contracts now dominate procurement between hydrocolloid suppliers and North American food manufacturers. Pre-validated stabilizer systems displace single-hydrocolloid spot purchasing, compressing supplier margins while locking in volume commitments. This pattern is most visible in Midwest dairy-alternative processing clusters serving national retail chains.
North America Carrageenan Market Segmentation
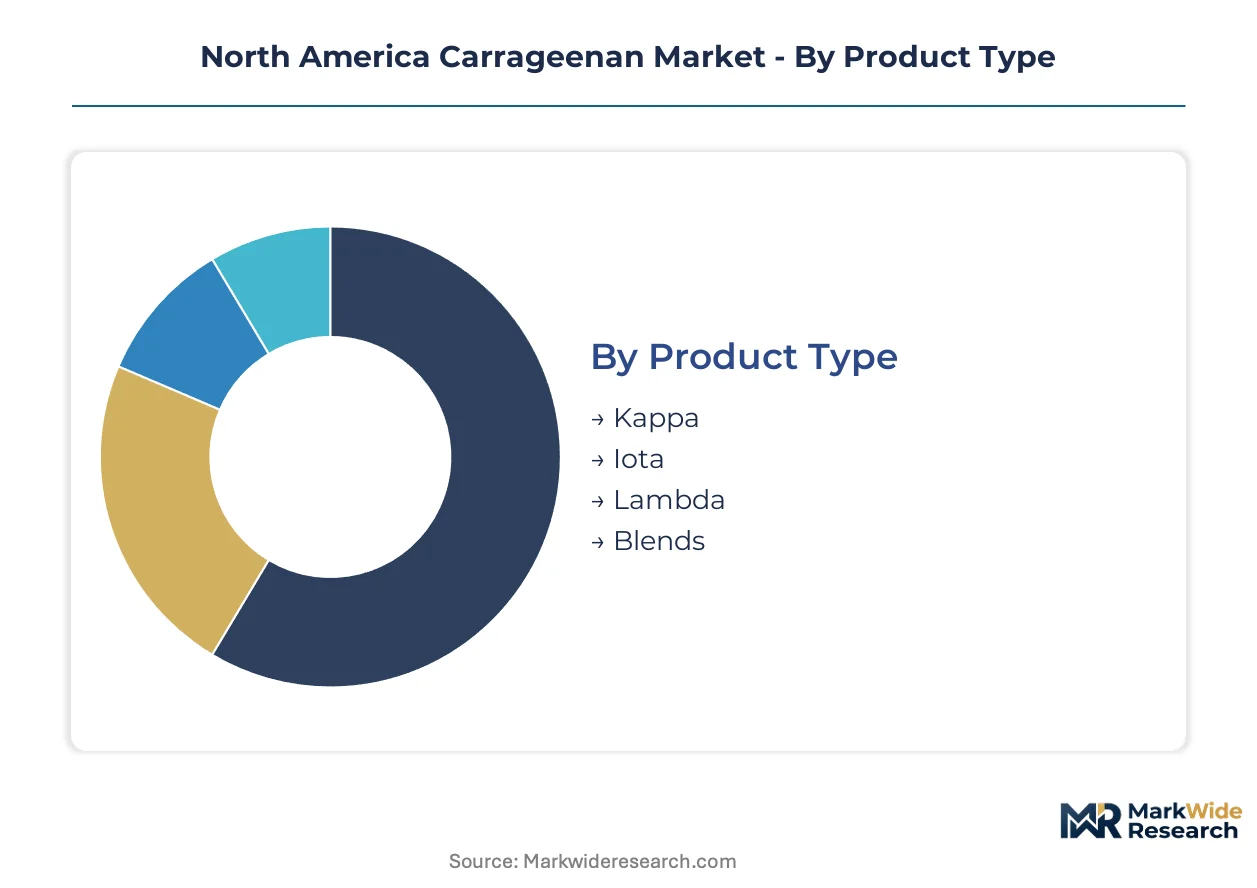
Carrageenan procurement patterns across North America diverge sharply by technical specification and end-use certification requirements. Manufacturers configure their sourcing strategies around gel-strength tolerances, regulatory compliance tiers, and formulation compatibility rather than commodity pricing alone.
Product Type:
The customization-to-standardization spectrum stretches from precision-extracted single-grade hydrocolloids to pre-compounded stabilizer blends engineered for specific mouthfeel replication.
- Kappa:Sulfated galactan with strong potassium-ion synergy forms brittle, thermo-reversible gels prized in dairy and plant-based cheese matrices. California's formulation corridor pulls concentrated volume for oat milk texturization, though FDA GRAS purity tightening filters out non-certified imports.
- Lambda:Cold-water soluble without gel formation, this grade carries margin premiums in personal care emulsions where energy-efficient processing reduces manufacturing overhead. Cosmetic formulators in the Northeast corridor specify lambda for leave-on topical delivery systems.
- Iota:Calcium-reactive soft gels suit freeze-thaw stable applications.
- Blends:Pre-validated kappa-iota combinations address single-ingredient sourcing preferences in plant-based beverage manufacturing.
Leading the category by volume: Kappa. Expanding most quickly: Blends.
Application:
Cost tier stratification separates mass-market food processing from premium personal care and regulated pharmaceutical applications.
- Food & Beverages:Thermally processed dairy alternatives, processed meats, and dessert gels consume the majority of North American carrageenan volume. Midwest manufacturing clusters serving national retail chains drive procurement consolidation into bundled stabilizer systems.
- Personal Care:Lambda-grade hydrocolloids function as suspending agents and emulsion stabilizers in premium skincare. Formulators prioritize cold-process compatibility to reduce energy inputs and preserve active ingredient integrity.
- Pharmaceuticals:Controlled-release tablet matrices and viscosity-modifying excipients demand certified purity grades with documented traceability.
- Industrial:Niche applications in textile sizing and oil drilling fluids operate at commodity price points with minimal specification stringency.
Dominating volume: Food & Beverages. Steepest expansion trajectory: Personal Care.
Distribution Channel:
Customer type and order scale determine channel selection, with large manufacturers bypassing intermediaries while smaller formulators rely on distributor technical support.
- Direct Sales:National dairy-alternative processors and meat-alternative manufacturers contract directly with integrated seaweed-to-hydrocolloid operators for volume pricing consistency and specification control.
- Distributors:Regional ingredient distributors provide technical formulation support and smaller minimum order quantities to mid-tier food manufacturers lacking in-house hydrocolloid expertise.
- Online Retail:Specialty cosmetic formulators and research laboratories source lambda-grade and small-batch kappa through digital channels.
- Supermarkets:Limited consumer-facing retail of food-grade carrageenan for home cooking applications.
Capturing largest share: Direct Sales. Gaining share fastest: Online Retail.
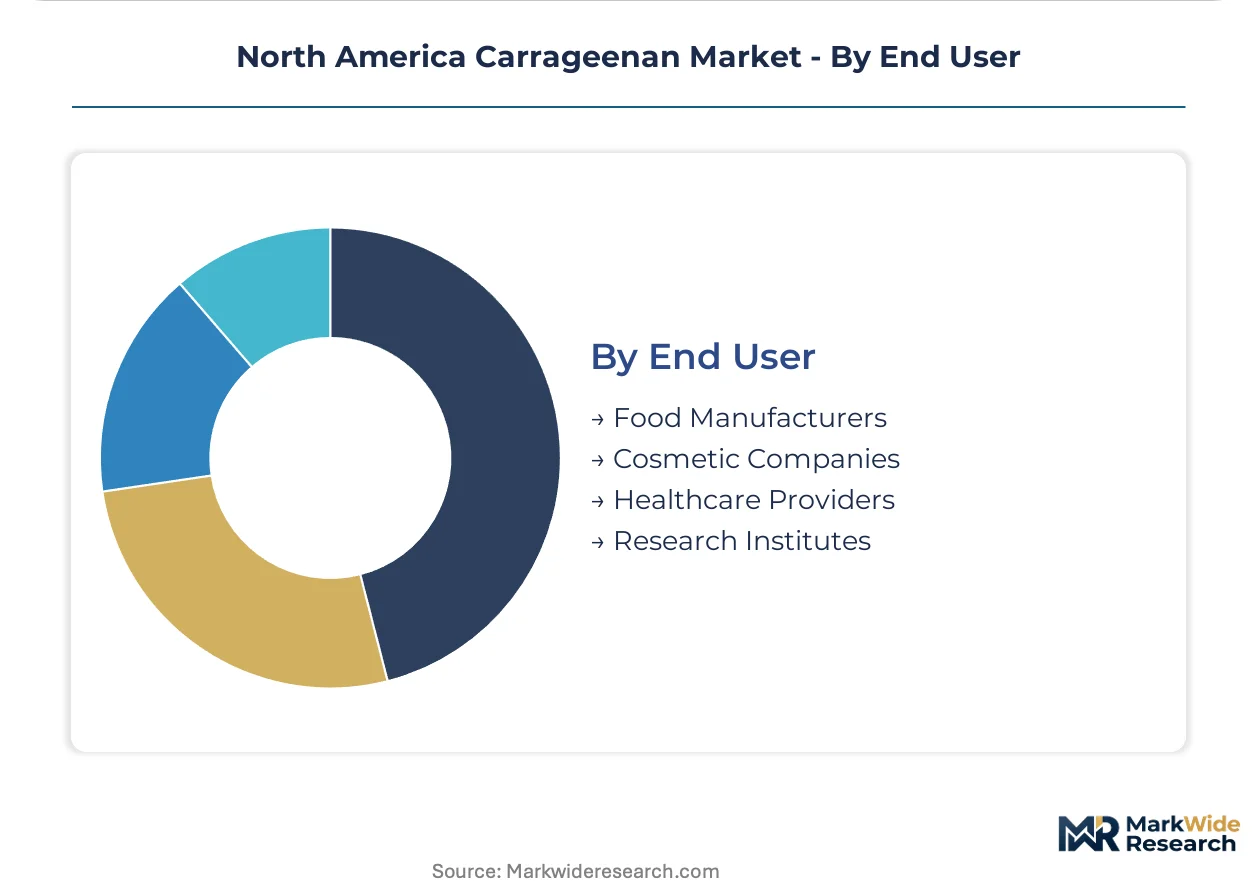
End User:
Geographic concentration of formulation expertise shapes demand clustering, with California and the Midwest anchoring distinct end-use specializations.
- Food Manufacturers:Plant-based beverage processors in California's formulation corridor and dairy-alternative facilities in the Midwest drive blended hydrocolloid adoption for casein-mimicking mouthfeel.
- Cosmetic Companies:Northeast and California personal care formulators specify lambda-grade carrageenan for premium emulsion stability in clean-label skincare lines.
- Healthcare Providers:Compounding pharmacies and nutritional supplement manufacturers utilize pharmaceutical-grade hydrocolloids for controlled-release applications.
- Research Institutes:Academic and commercial R&D facilities pilot novel extraction protocols and functional food applications.
Generating highest volume: Food Manufacturers. Climbing the fastest: Cosmetic Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's plant-based formulation corridor operates as the continent's dominant tax-advantaged zone, drawing hydrocolloid processors through clean-label R&D credits and proximity to oat milk manufacturing clusters.
United States
Oat milk processors in California and dairy-alternative facilities in the Midwest drive blended carrageenan procurement for casein-mimicking mouthfeel. FDA GRAS oversight tightening elevates purity benchmarks, filtering non-certified imports. Chicago and Minneapolis manufacturing clusters now contract directly with integrated seaweed-to-hydrocolloid operators for volume pricing consistency.
Canada
Atlantic Canada and coastal Maine concentrate marine agronomy talent for Chondrus crispus tank cultivation scaling. Health Canada's PMRA imposes certification thresholds that filter market access for imported seaweed feedstocks. Quebec and Ontario food manufacturers source lambda-grade hydrocolloids for premium personal care emulsions serving Northeast US cosmetic formulators.
Mexico
Processed meat and dessert gel manufacturers in Mexico City Metro and Guadalajara industrial zones consume thermally stable kappa carrageenan for domestic retail and US export channels. Mexico's national food safety regulator enforces additive purity standards aligned with FDA protocols. Nuevo León's manufacturing corridor hosts regional distributors providing technical formulation support to mid-tier food processors.
North America Carrageenan Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across North American carrageenan supply chains. The vendor base stratifies into three tiers: integrated seaweed-to-hydrocolloid operators commanding pricing consistency, biotechnology-driven extraction specialists, and regional batch processors serving niche cosmetic formulators. Consolidation pressure favors backward integration into captive seaweed supply. Strategic partnerships between hydrocolloid compounders and plant-based beverage manufacturers now displace spot purchasing.
Among US-based diversified conglomerates, Cargill, Incorporated anchors integrated supply chain positioning through its captive seaweed sourcing infrastructure. DuPont de Nemours, Inc. exemplifies biotechnology-driven consistency archetypes with its kappa-grade extraction specialization. Ingredients Solutions, Inc. occupies the regional specialist tier, serving smaller-batch lambda variant demand from Northeast cosmetic formulators.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc. |
| Cargill, Incorporated |
| Ingredion Incorporated |
| CP Kelco U.S., Inc. |
| Ingredients Solutions, Inc. |
| FMC Corporation |
| W Hydrocolloids, Inc. |
| Ashland Inc. |
| TIC Gums, Inc. |
| Others |
Value Network & Pricing Analysis
Captive seaweed sourcing through backward integration into Philippine and Indonesian cultivation zones anchors pricing power for North American hydrocolloid processors, while spot-market buyers absorb volatility from shipping cost swings and climate-driven harvest disruptions. FDA GRAS certification tiers create measurable price spreads between validated stabilizer systems and uncertified commodity grades.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent over contract pricing reward domestic compounders maintaining finished goods inventory in Chicago and Minneapolis distribution nodes. Three-tier pricing structure across premium certified, standard food-grade, and economy industrial tiers reflects Bloom value consistency and organic traceability investment. Pricing pressure stems from guar gum substitution trials in cost-sensitive beverage manufacturing. Mid-sized regional formulators exhibit highest price sensitivity due to California Proposition 65 compliance infrastructure costs.
Supply Chain Analysis
Freight cost volatility from Southeast Asian ports to Long Beach and Vancouver anchors supply chain risk assessment for North American processors dependent on Eucheuma cottonii and Chondrus crispus feedstocks. Raw material sourcing draws from Philippine seaweed farms, Indonesian coastal cultivation, and emerging Atlantic Canadian tank operations. Single-source vulnerability concentrates in the Mindanao Strait shipping corridor. Distribution runs through direct sales contracts with national dairy-alternative processors and regional distributor networks serving mid-tier formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzyme-assisted extraction protocols are displacing traditional alkali processing as the dominant technology transition, compressing competitive timelines for legacy operators while rewarding biotechnology-capable compounders with tighter specification control.
For Market Incumbents: Anchor pricing consistency through captive seaweed supply agreements in Philippine cultivation zones, insulating against freight volatility that erodes spot-market competitors. Invest in dual FDA GRAS and USDA Organic certification infrastructure to defend margin position against guar gum substitution in plant-based beverages. Prioritize kappa-iota blend R&D for single-ingredient dairy mouthfeel replication.
For New Entrants and Emerging Players: The premium-to-economy price gap in pharmaceutical-grade lambda carrageenan offers white-space entry for cold-process cosmetic formulators seeking energy-efficient emulsion stability. Target Northeast personal care manufacturers with certified small-batch production and technical formulation support. Pursue Health Canada PMRA alignment as a cross-border scale mechanism.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified food ingredient conglomerates seeking backward integration into seaweed supply. Long-term viability favors processors with demonstrated organic traceability and enzyme-extraction capability. Watch California clean-label litigation outcomes as the inflection signal for reformulation-driven demand shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seaweed Cultivation | Captive Eucheuma cottonii supply from Philippine farms reduces freight exposure for Midwest dairy-alternative processors. |
| Enzyme-Assisted Extraction Scale-Up | Hybrid alkali-enzyme protocols tighten Bloom value distributions for California oat milk formulators. |
| Dual Certification Infrastructure Investment | Simultaneous FDA GRAS and USDA Organic compliance unlocks tiered pricing power in national retail channels. |
| Pre-Validated Stabilizer System Development | Single-ingredient kappa-iota blends displace spot hydrocolloid purchasing in bundled procurement contracts. |
| Health Canada PMRA Alignment | Harmonized purity standards enable cross-border scale for processors serving Quebec and Ontario cosmetic manufacturers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hydrocolloid procurement managers at dairy-alternative processors, technical directors at cosmetic formulators, marine agronomists in Atlantic Canada, and distribution channel partners in the Midwest. FDA GRAS submission databases, USDA Organic certification registries, Health Canada PMRA filings, and Southeast Asian export customs documentation provided validation triangulation against bottom-up volume estimates and top-down market sizing.
Granularity-level modeling distinguished kappa, iota, and lambda grade specifications across food and beverage, personal care, pharmaceutical, and industrial end-uses, with additional segmentation by direct sales versus distributor channel dynamics. CAGRs were derived from trend extrapolation of clean-label adoption curves and enzyme-extraction technology penetration rates, calibrated against historical price elasticity in plant-based beverage substitution scenarios and organic certification premium sustainability.
Inputs from Philippine and Indonesian trade associations were available through the study window; gaps in real-time seaweed harvest yield data introduce uncertainty bands around feedstock cost assumptions. Stakeholders should weight assumptions against their own operating context and monitor evolving state-level disclosure requirements for reformulation risk exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Pea Fiber Market
Ingredients
Middle East and Africa Fruit and Vegetable Ingredients Market
Ingredients
Canada Whey Protein Ingredients Market
Ingredients
Cocoa Solids Market
Ingredients
Meat Starter Culture Market
Ingredients
Custom Dry Ingredients Blends Market
Ingredients
Barley Flake Market
Ingredients
Mirepoix Market
Ingredients
Hydrolyzed Starch Market
Ingredients
Middle East and Africa Lipids Market
Ingredients
Bay Leaf Oil Market
Ingredients
Green Gram Powder Market
Ingredients
Bromelain Ingredient Market
Ingredients
Soy Protein Concentrate Market
Ingredients
Carica Papaya Seed Oil Market
Ingredients
Whipped Topping Concentrate Market