
 Canada Varicose Vein Treatment Devices Market | 2026-2036
Canada Varicose Vein Treatment Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Varicose Vein Treatment Devices Market Intelligence
Health Canada Medical Device Licensing is reorganizing competitive entry requirements for manufacturers serving the Canadian market. Medtronic leverages its established cardiac and vascular infrastructure to sustain catheter supply relationships with major teaching hospitals. AngioDynamics anchors its position through specialized venous access and ablation portfolios tailored to outpatient settings. Sciton, Inc. differentiates via integrated laser platforms that serve both therapeutic and aesthetic applications in private clinic networks.
Canada varicose vein treatment devices encompass energy-based ablation systems, injectable sclerosants, and mechanical extraction tools designed to occlude or remove dysfunctional superficial veins, typically operating at wavelengths of 810–1470 nm for laser systems or generating thermal lesions at 85–120°C for radiofrequency catheters. Endovenous laser and radiofrequency technologies command the dominant share of procedural volume due to superior closure rates and same-day discharge protocols, while sclerotherapy retains strong positioning in cosmetic vein treatment where cost sensitivity shapes patient selection. Hospitals and specialty practices represent the core demand nodes, with outpatient centers capturing the fastest expansion as provincial health authorities expand ambulatory procedure funding.
Health Canada, the Canadian Standards Association, and provincial health technology assessment bodies collectively govern device approval, reimbursement eligibility, and clinical adoption protocols across jurisdictions. Health Canada's transition toward streamlined Class III device reviews is compressing time-to-market for novel ablation technologies, while provincial formularies determine which procedures receive public funding versus private payment. Stakeholders must monitor evolving HTA recommendations from Ontario Health and Alberta Health Services to anticipate reimbursement shifts that will reshape provider procurement priorities.
Market Dynamics
Health Canada's accelerated Class III device review timelines are compressing competitive entry windows for radiofrequency and laser ablation systems, forcing incumbent manufacturers to defend hospital procurement relationships through faster regulatory submissions and localized clinical evidence generation.
Growth Catalysts
- Provincial Ambulatory Funding Expansion:Ontario Health and Alberta Health Services are expanding same-day procedure reimbursement codes, channeling patient volume toward outpatient vein clinics equipped with endovenous laser systems.
- Radiofrequency Catheter Precision Gains:Temperature-controlled segmental ablation technology is reducing procedure times and improving closure consistency, driving replacement demand in Toronto and Vancouver hospital networks.
- Aesthetic-Therapeutic Convergence:Integrated laser platforms serving both medical varicose vein treatment and cosmetic spider vein removal are capturing dual-revenue streams in private dermatology and plastic surgery practices.
Market Restraints
- Reimbursement Fragmentation:Provincial formularies in Quebec and Atlantic Canada exclude several endovenous procedures from public coverage, limiting addressable patient pools to private-pay segments.
- Specialized Physician Supply Constraints:The Royal College of Physicians and Surgeons certification pathway for venous disease specialists produces fewer than fifteen new practitioners annually, constraining procedural capacity expansion.
- Sclerotherapy Cost Competition:Liquid and foam sclerosant injections retain strong positioning in cosmetic vein treatment due to lower per-procedure costs, pressuring ablation device pricing in private clinic segments.
Strategic Opportunities
- Western Canada Network Buildout:British Columbia and Alberta present underpenetrated vein clinic density relative to Ontario, creating whitespace for dedicated ambulatory centers in Calgary and Edmonton suburban corridors.
- Health Canada Streamlined Review Pathway:The regulator's transition toward prioritized review for novel ablation technologies offers first-mover advantage for manufacturers submitting robust Canadian clinical data packages.
- Telemedicine Pre-Screening Integration:Remote consultation platforms are reducing specialist consultation wait times, expanding geographic catchment areas for urban vein clinics and improving referral funnel efficiency.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Canadian universities produce limited graduates with combined optics and catheter design expertise, constraining domestic R&D expansion for laser system manufacturers.
- Provincial HTA Evidence Requirements:Ontario Health Technology Assessment and Alberta Health Services demand jurisdiction-specific cost-effectiveness data, forcing redundant clinical studies for national market access.
- Legacy Sclerotherapy Practice Inertia:Established dermatology practices with sunk investment in injection-based workflows resist capital equipment transitions despite superior ablation outcomes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Varicose Vein Treatment Devices Market |
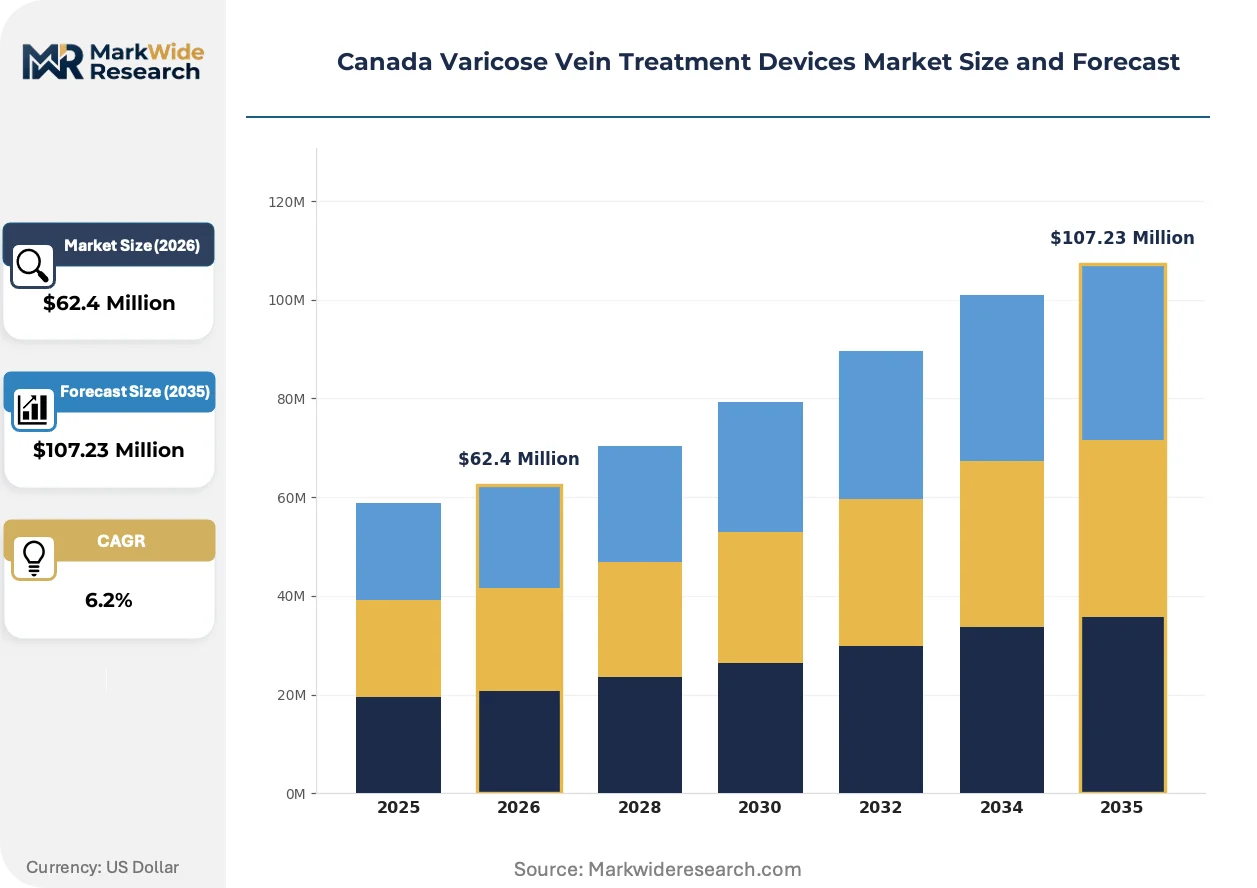
| Market Size in 2026 | $62.4 Million |
| Market Size in 2035 | $107.23 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endovenous Laser, Sclerotherapy, Phlebectomy, Compressive Therapy Technology: Laser, Radiofrequency, Ultrasound, Mechanical End User: Hospitals, Clinics, Outpatient Centers, Specialty Practices Application: Chronic Venous Insufficiency, Aesthetic Improvement, Pain Relief, Wound Healing |
| Companies Covered | AngioDynamics, Medtronic, Teleflex Incorporated, Sciton, Inc., Biolitec AG, Dornier MedTech, Merit Medical Systems, Alma Lasers, Boston Scientific Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Varicose Vein Treatment Devices Market Strategic Shifts & Innovations
Device miniaturization and real-time imaging integration are redefining procedural workflows across Canadian vein treatment settings, compressing the gap between hospital-based and clinic-based care standards.
Endovenous laser fiber technology is miniaturizing. 400-micron and smaller fiber diameters are enabling access through micro-introducer sheaths, reducing puncture site trauma and post-procedure bruising. Community-based vein clinics in Mississauga and Burnaby are adopting these systems at twice the rate of hospital outpatient departments. This miniaturization is compressing the equipment footprint required for procedure rooms, allowing dedicated vein clinics to operate profitably in smaller leased spaces.
Health Canada's Medical Device Single Audit Program recognition is harmonizing quality system inspections with FDA and European MDR requirements. Manufacturers with existing ISO 13485 certifications face reduced duplication in facility audits and documentation submissions. Class III laser and radiofrequency systems are experiencing the clearest timeline benefits, with several 2024 submissions achieving priority review status through this pathway.
Patient self-referral patterns are displacing traditional primary-care gatekeeping. Direct-to-clinic appointment booking through provincial health portals and private clinic websites now accounts for the majority of initial consultations in Ontario and British Columbia. This channel shift is fragmenting referral networks and forcing hospital-affiliated vein programs to invest in consumer-facing digital scheduling infrastructure to maintain volume.
Canada Varicose Vein Treatment Devices Market Segmentation
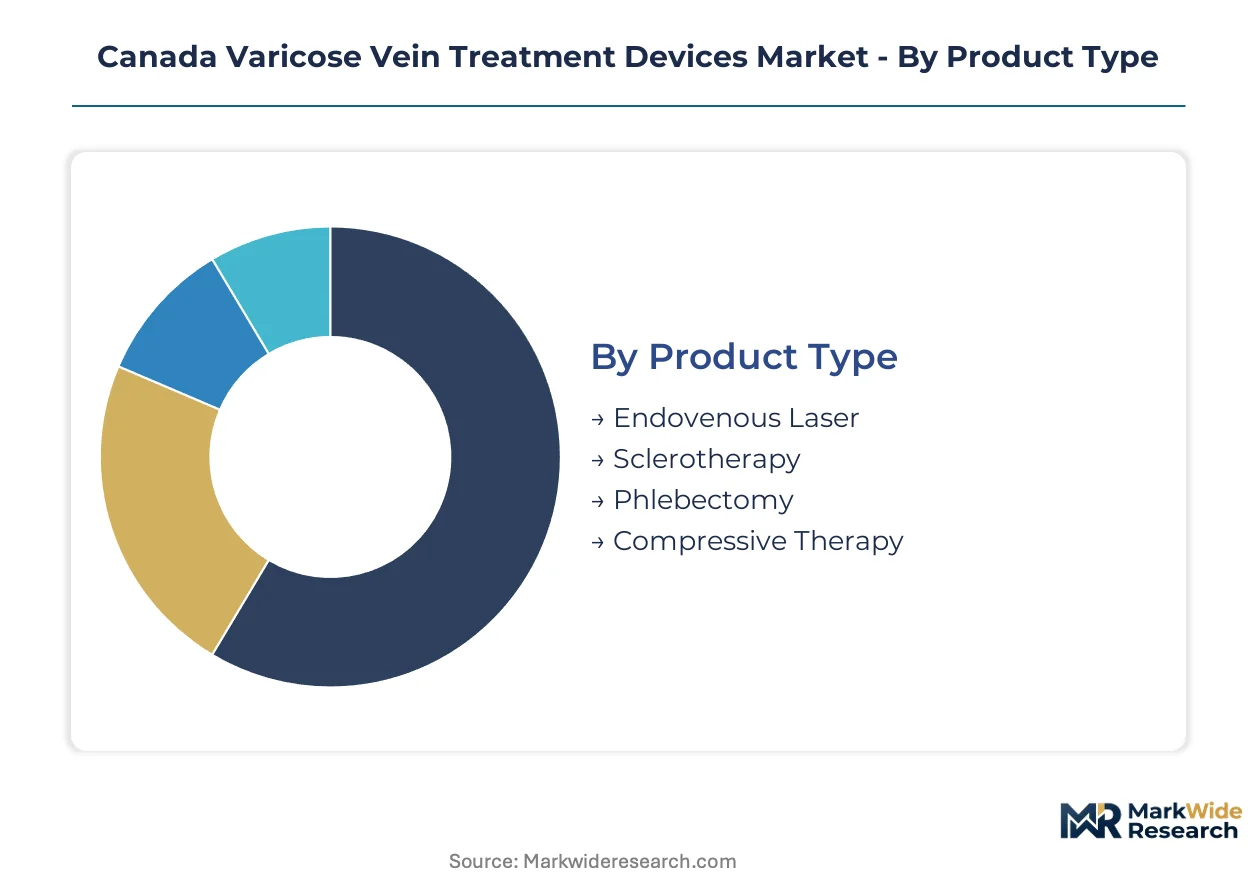
Varicose vein treatment devices in Canada flow through distinct procurement channels shaped by provincial reimbursement policies and procedural setting requirements. Understanding how product types, technologies, and end users align with these channels reveals where manufacturers must concentrate commercial resources.
Product Type:
Channel access varies sharply by product type, with hospital procurement committees controlling high-value ablation systems while private clinics self-fund sclerotherapy inventories.
- Endovenous Laser:Fiber-based systems operating at 810–1470 nm wavelengths deliver thermal occlusion of the great saphenous vein through percutaneous access. Demand concentrates in Toronto and Vancouver hospital networks where Ontario Health and BC provincial formularies reimburse endovenous procedures. Temperature-controlled delivery systems are displacing older bare-fiber designs in these accounts.
- Sclerotherapy:Liquid and foam sclerosant formulations chemically ablate superficial veins without capital equipment requirements. Private dermatology and plastic surgery practices across Montreal and Calgary purchase these agents directly, bypassing hospital procurement entirely. Cost sensitivity here pressures per-procedure pricing.
- Phlebectomy:Hook-based mechanical extraction tools for ambulatory stab avulsion procedures.
- Compressive Therapy:Gradient compression garments and pneumatic devices for post-procedural care and conservative management.
By volume, Sclerotherapy leads due to broad cosmetic application. By growth pace, Endovenous Laser is expanding most quickly as provincial ambulatory funding expands.
Technology:
Cost tier stratification separates premium thermal ablation platforms from lower-capital ultrasound guidance and mechanical alternatives.
- Laser:Diode and Nd:YAG platforms generating controlled photothermal injury. Teaching hospitals in Ontario prioritize 1470 nm systems for reduced post-procedural pain profiles.
- Radiofrequency:Segmental thermal ablation catheters with impedance-controlled energy delivery. Vancouver and Calgary outpatient centers favor these systems for faster procedure times and same-day discharge protocols.
- Ultrasound:Duplex imaging for pre-procedural mapping and real-time needle guidance.
- Mechanical:Rotational and chemical-mechanical hybrid devices for vein occlusion without thermal energy.
Radiofrequency systems command premium placement in high-volume urban centers. Ultrasound guidance is gaining share fastest as community clinics invest in imaging capability.
End User:
Customer type determines reimbursement pathway and equipment financing approach, with public hospital networks following capital budget cycles distinct from private clinic investment decisions.
- Hospitals:Academic medical centers and community hospitals with interventional radiology and vascular surgery departments. University Health Network in Toronto and Vancouver General Hospital anchor laser ablation volume through bundled payment arrangements with provincial health authorities.
- Clinics:Private dermatology, plastic surgery, and dedicated vein treatment facilities. Mississauga and Burnaby clinic clusters are expanding fastest as patient self-referral through provincial health portals displaces traditional primary care gatekeeping.
- Outpatient Centers:Hospital-affiliated ambulatory surgical facilities.
- Specialty Practices:Royal College-certified venous disease specialists operating independent practices.
Hospitals retain the largest installed base of capital equipment. Clinics are climbing the fastest as direct-to-consumer scheduling platforms expand geographic catchment.
Application:
Maturity differences separate established therapeutic indications from emerging aesthetic crossover demand.
- Chronic Venous Insufficiency:Medical-grade treatment for symptomatic venous reflux with edema, skin changes, or ulceration. Alberta Health Services expanded reimbursement codes for this indication, channeling volume toward Edmonton and Calgary procedural centers.
- Aesthetic Improvement:Cosmetic treatment of spider veins and minor reticular veins without underlying pathologic reflux. Quebec's exclusion of cosmetic procedures from public coverage limits this segment to private-pay channels in Montreal and Quebec City.
- Pain Relief:Symptomatic management of venous hypertension and aching.
- Wound Healing:Adjunctive treatment for venous stasis ulcers.
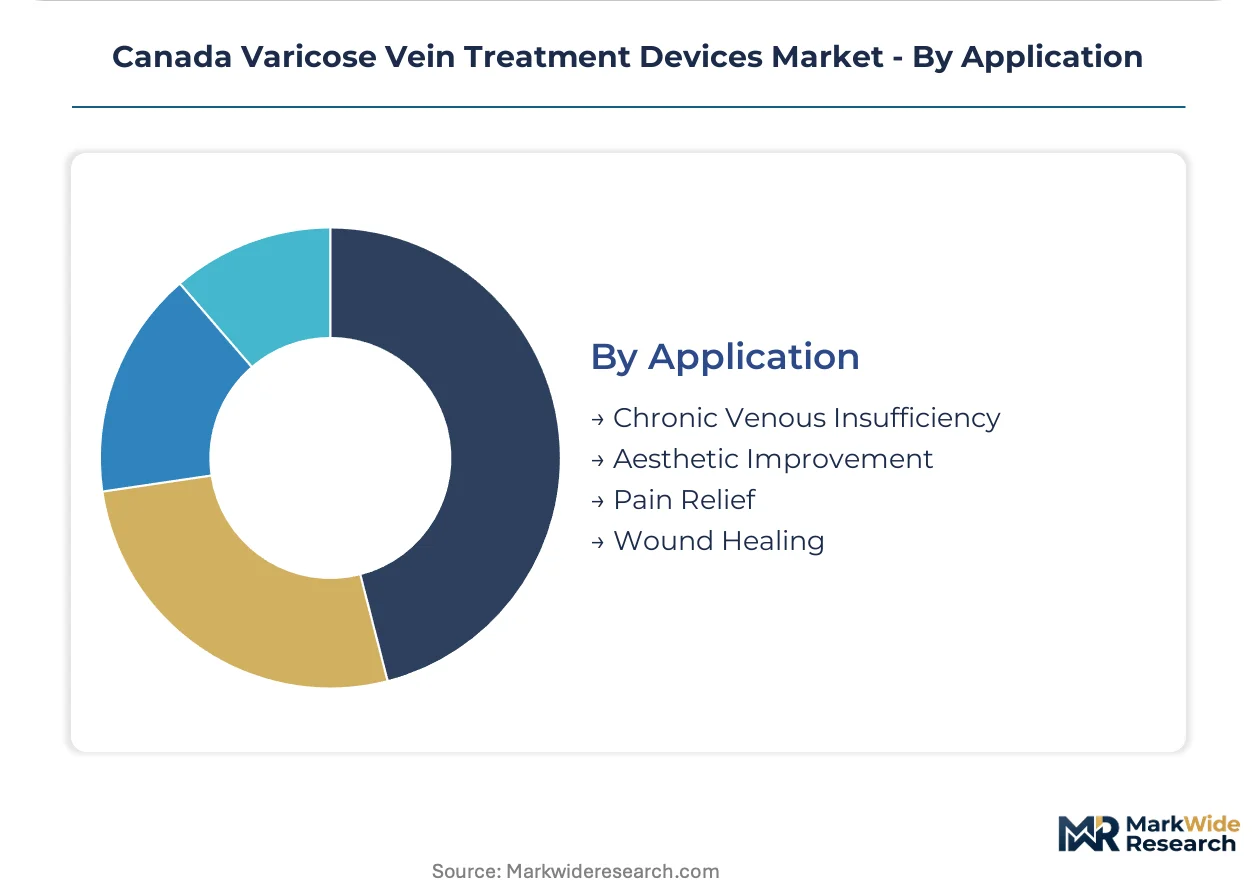
Chronic Venous Insufficiency drives the majority of reimbursed procedure volume. Aesthetic Improvement shows the steepest expansion trajectory as integrated laser platforms capture dual-revenue streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in Ontario and British Columbia dominate equipment acquisition decisions, while private clinic networks in Alberta and Quebec reshape patient access patterns through direct-to-consumer channels.
Ontario
Toronto's University Health Network and Mississauga clinic clusters anchor the largest procedural volume. Ontario Health expanded ambulatory reimbursement codes for endovenous laser treatments in 2023, accelerating same-day discharge protocols. The Greater Toronto Area hosts the densest concentration of Royal College-certified venous specialists.
British Columbia
Vancouver General Hospital and Burnaby outpatient centers favor radiofrequency systems for faster procedure times. BC's provincial formulary maintains broader endovenous coverage than Quebec, channeling patient volume toward Vancouver's hospital-affiliated ambulatory facilities. Community clinics in suburban corridors are expanding imaging capability.
Alberta
Calgary and Edmonton present underpenetrated vein clinic density relative to Ontario demand. Alberta Health Services added chronic venous insufficiency procedures to public coverage, creating procurement opportunities for catheter-based systems. The Calgary suburban corridor sees the fastest private clinic buildout.
Quebec
Montreal dermatology practices concentrate cosmetic sclerotherapy volume due to provincial exclusion of aesthetic procedures from public funding. The city's private-pay channels sustain demand for liquid and foam sclerosants. McGill University Health Centre maintains limited therapeutic ablation capacity.
Canada Varicose Vein Treatment Devices Market Key Industry Players
Player mix skews toward diversified medical device conglomerates with established vascular portfolios, creating tiered competition between hospital-focused capital equipment suppliers and clinic-oriented disposable specialists. Market structure concentrates around three strategic archetypes: cardiac-vascular platform players leveraging catheter supply relationships, laser-technology specialists with aesthetic-therapeutic crossover capability, and venous-access focused mid-cap operators. Dominant competitive moves include provincial formulary positioning to secure reimbursement-advantaged placement and ambulatory center partnership networks to capture self-referral patient flows.
Within the diversified platform tier, Medtronic anchors hospital procurement relationships through its established cardiac infrastructure, while AngioDynamics occupies a position serving outpatient settings with specialized venous access portfolios. Sciton, Inc. exemplifies the aesthetic-therapeutic convergence archetype through integrated laser platforms targeting private clinic networks. These three companies represent the competitive vectors shaping equipment financing approaches and technology adoption timelines across Canadian provincial markets.
| Leading Market Players |
|---|
| AngioDynamics |
| Medtronic |
| Teleflex Incorporated |
| Sciton, Inc. |
| Biolitec AG |
| Dornier MedTech |
| Merit Medical Systems |
| Alma Lasers |
| Boston Scientific Corporation |
| Others |
Cost & Logistics Intelligence
Long-term catheter supply agreements with Ontario teaching hospitals lock in multi-year price visibility for radiofrequency and laser ablation systems, insulating manufacturers from spot-market volatility while anchoring procurement committees to predictable capital expenditure cycles. Health Canada's Medical Device Single Audit Program recognition compresses compliance costs for suppliers holding parallel FDA and European MDR certifications, feeding through to modest pricing flexibility in competitive bid situations.
Pricing Analysis
Cost-plus contracts with Health Canada indexation clauses govern high-value capital equipment transactions, embedding regulatory compliance and quality system maintenance into baseline pricing. Three-tier pricing structure across premium, standard, and economy levels separates 1470 nm laser platforms with temperature-controlled delivery from bare-fiber systems and refurbished legacy units. Pricing pressure stems from sclerotherapy cost competition in Quebec and Atlantic Canada private-pay segments, where liquid and foam sclerosants undercut ablation device per-procedure economics. Cosmetic vein clinics exhibit highest price sensitivity due to uninsured patient out-of-pocket constraints, while Toronto hospital networks prioritize closure rate performance over capital cost minimization.
Supply Chain Analysis
Port congestion at Vancouver and container availability constraints on trans-Pacific lanes elevate inbound logistics costs for diode laser components and radiofrequency catheter electronics sourced from German and Japanese manufacturing facilities. Supply concentration rests on Germany, Japan, and the United States for precision optical fibers, impedance-controlled generators, and disposable catheter assemblies. Raw material dependencies include rare-earth doped glass fibers, biocompatible polymers for catheter sheaths, and semiconductor components for energy delivery control systems. Single-source vulnerability persists for 1470 nm wavelength-specific laser diodes, where qualified alternative suppliers require extended Health Canada re-registration timelines. Distribution runs through hospital procurement committees for capital equipment and direct-to-clinic disposable replenishment for sclerotherapy agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
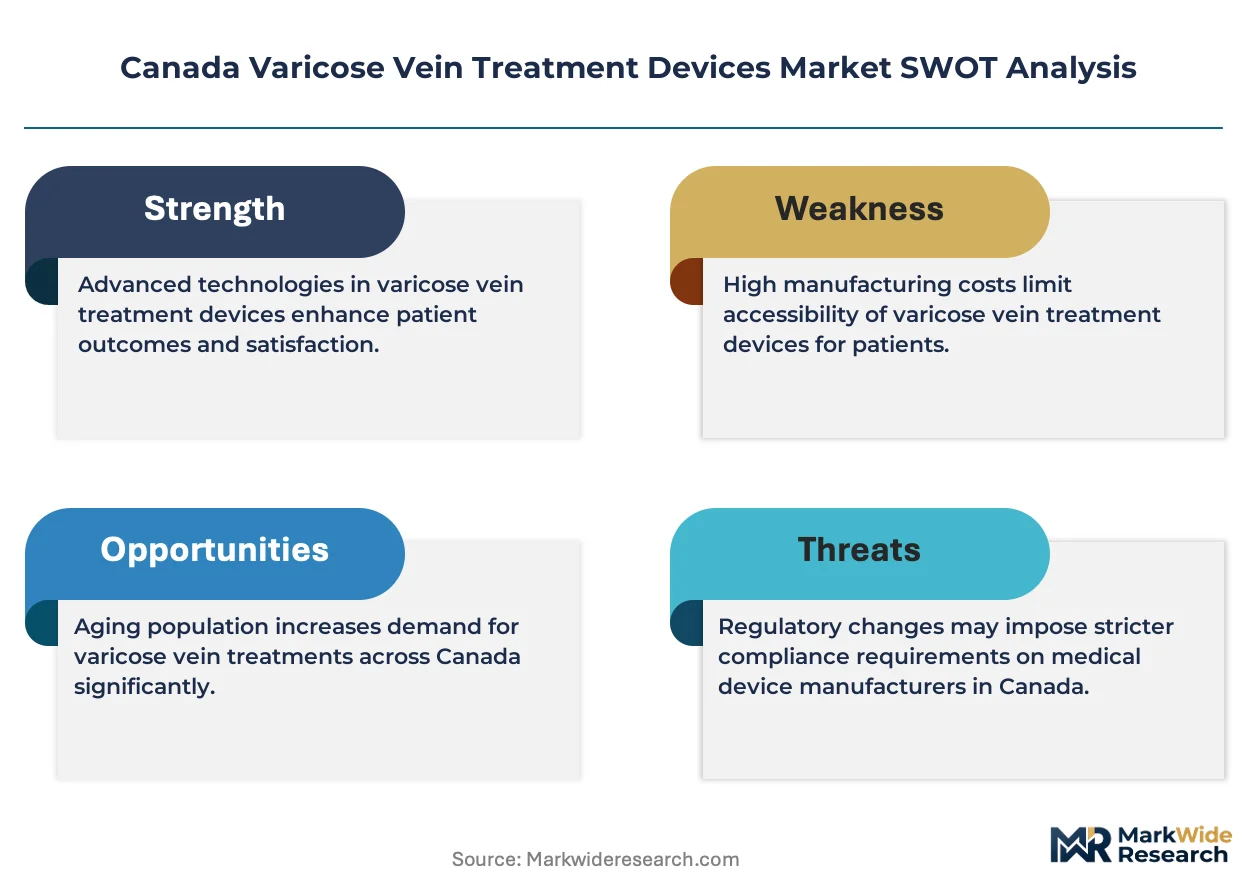
Health Canada's accelerated Class III device review timelines constitute a regulatory inflection disrupting incumbent procurement relationships, compressing competitive entry windows and rewarding manufacturers with pre-positioned clinical data packages. This structural shift elevates first-mover advantage for novel ablation technologies while forcing legacy players into defensive repositioning.
For Market Incumbents: Consolidate hospital procurement relationships through expedited regulatory submissions and Canadian-specific clinical evidence generation, defending against emerging laser-technology specialists threatening outpatient clinic share. Deepen backward integration into fiber-optic component supply to mitigate single-source vulnerability for wavelength-specific diodes. Prioritize certification investment in Health Canada's streamlined review pathway to maintain formulary-advantaged placement against faster-moving entrants.
For New Entrants and Emerging Players: Lead with underpenetrated vein clinic density in Calgary and Edmonton suburban corridors, where Alberta Health Services reimbursement expansion creates whitespace for ambulatory center partnerships. Target aesthetic-therapeutic convergence in private dermatology practices, capturing dual-revenue streams through integrated laser platforms serving both medical and cosmetic indications. Deploy telemedicine pre-screening integration as go-to-market angle, reducing specialist consultation wait times and expanding geographic catchment beyond traditional referral networks.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap venous-access specialists with Health Canada priority review status and established Alberta or British Columbia clinic partnerships, positioned for sustained viability across the five-to-ten year provincial reimbursement expansion horizon. Acquisition target archetype: laser-technology platforms with aesthetic crossover capability and disposable recurring revenue models. Signal to monitor: Ontario Health Technology Assessment recommendations shifting reimbursement thresholds between hospital and outpatient settings.
| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Priority Review Submission | Accelerated market access for novel ablation technologies compresses competitive entry timelines. |
| Provincial Formulary Positioning | Reimbursement-advantaged placement with Ontario Health secures hospital procurement committee preference. |
| Ambulatory Center Partnership Network | Direct-to-consumer scheduling platforms capture self-referral patient flows in Mississauga and Burnaby. |
| Clinical Evidence Generation Program | Canadian-specific data packages satisfy Alberta Health Services cost-effectiveness requirements. |
| Integrated Laser Platform Development | Dual therapeutic-aesthetic capability penetrates private dermatology practice capital equipment budgets. |
Research Approach
Initial hypotheses were tested against primary input from interventional radiologists, vascular surgeons, hospital procurement managers, and biomedical engineers, and refined through secondary validation against Health Canada Medical Device Licensing databases, provincial formulary records, GPO contracts, and hospital capital expenditure disclosures. Bottom-up triangulation across equipment installation records and procedure volume estimates converged with top-down analysis of manufacturer revenue allocations and import trade data.
Variance decomposition across technology, end-user, and application segments structured the analytical framework, with growth trajectories modeled over the projection horizon. CAGRs derived from fitted trend lines adjusted for provincial reimbursement policy inflections and regulatory review timeline compressions. Forecast inputs incorporated Health Canada submission pipeline tracking, Royal College specialist certification throughput, and ambulatory procedure funding expansion schedules.
Underlying assumptions cover stable Health Canada regulatory pathway efficiency, sustained provincial ambulatory reimbursement expansion, and constrained specialist supply growth, with deviation risk concentrated in Quebec formulary exclusion persistence and biomedical engineering talent scarcity constraining domestic R&D scaling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Diode Laser Aesthetic Medical Device Market
Medical Devices
Global Wearable Healthcare Devices Market
Medical Devices
Asthma Inhaler Device Market
Medical Devices
Flexible and Semi-Rigid Ureteroscopy Market
Medical Devices
Mexican Intraocular Lens Market
Medical Devices
Sensor Based Smart Catheters Market
Medical Devices
Tattoo Removal Lasers Market
Medical Devices
Global Total Wrist Replacement Market
Medical Devices
Insulin Delivery Devices (Idd) Market
Medical Devices
Global Bone Cement Market
Medical Devices
Home-Use Water Flosser Market
Medical Devices
Defibrillator Pads Market
Medical Devices
Surgical Robotic Services Market
Medical Devices
Pressure-Volume Loop Systems Market
Medical Devices
Repositioning and Offloading Devices Market
Medical Devices
Global Non-Surgical Skin Tightening Devices Market