
 Surgical Robotic Services Market | 2026-2036
Surgical Robotic Services Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Robotic Services Market Analytics
Software-defined feature licensing is recalibrating how surgical robotic vendors monetize installed systems. Intuitive Surgical leverages its da Vinci ecosystem to sustain recurring revenue through instrument tracking and analytics subscriptions. Stryker anchors its Mako service portfolio with predictive maintenance contracts that reduce orthopedic suite downtime. Medtronic competes through extended warranty and remote diagnostics packages tied to its Hugo platform.
Surgical robotic services encompass installation, maintenance, training, and consulting activities that ensure continuous operability of teleoperated and autonomous surgical platforms, typically governed by ISO 13485 quality management and IEC 62304 software lifecycle standards. The service type dimension concentrates margin pools in maintenance agreements, where multi-year contracts generate predictable cash flows and lock in consumable replenishment. End user segmentation shows hospitals commanding the largest installed base, while surgical centers represent the fastest-growing adoption channel as ambulatory procedural volumes expand.
FDA premarket notification and EU MDR conformity assessment shape service bundling requirements, compelling vendors to integrate training and software validation into commercial offerings. The country's national pharmaceutical regulator in Japan and Health Canada impose comparable clinical evidence standards that elevate field service complexity. Stakeholders must monitor how regulatory divergence across jurisdictions affects service localization costs and margin structures.
Market Dynamics
Service contract monetization is displacing capital equipment sales as the primary revenue architecture, compelling manufacturers to embed predictive analytics and remote diagnostics into multi-year agreements that lock in consumable replenishment cycles.
Growth Catalysts
- Ambulatory Surgical Center Expansion:Outpatient procedural volume migration in the United States is generating installed-base growth in compact robotic platforms requiring localized maintenance networks.
- FDA 510(k) Pathway Streamlining:Expedited premarket notification processing for software-only updates accelerates feature rollouts and associated subscription revenue recognition.
- Cloud-Based Remote Monitoring:Real-time instrument tracking and predictive failure algorithms reduce unplanned downtime, extending contract renewal rates.
Market Restraints
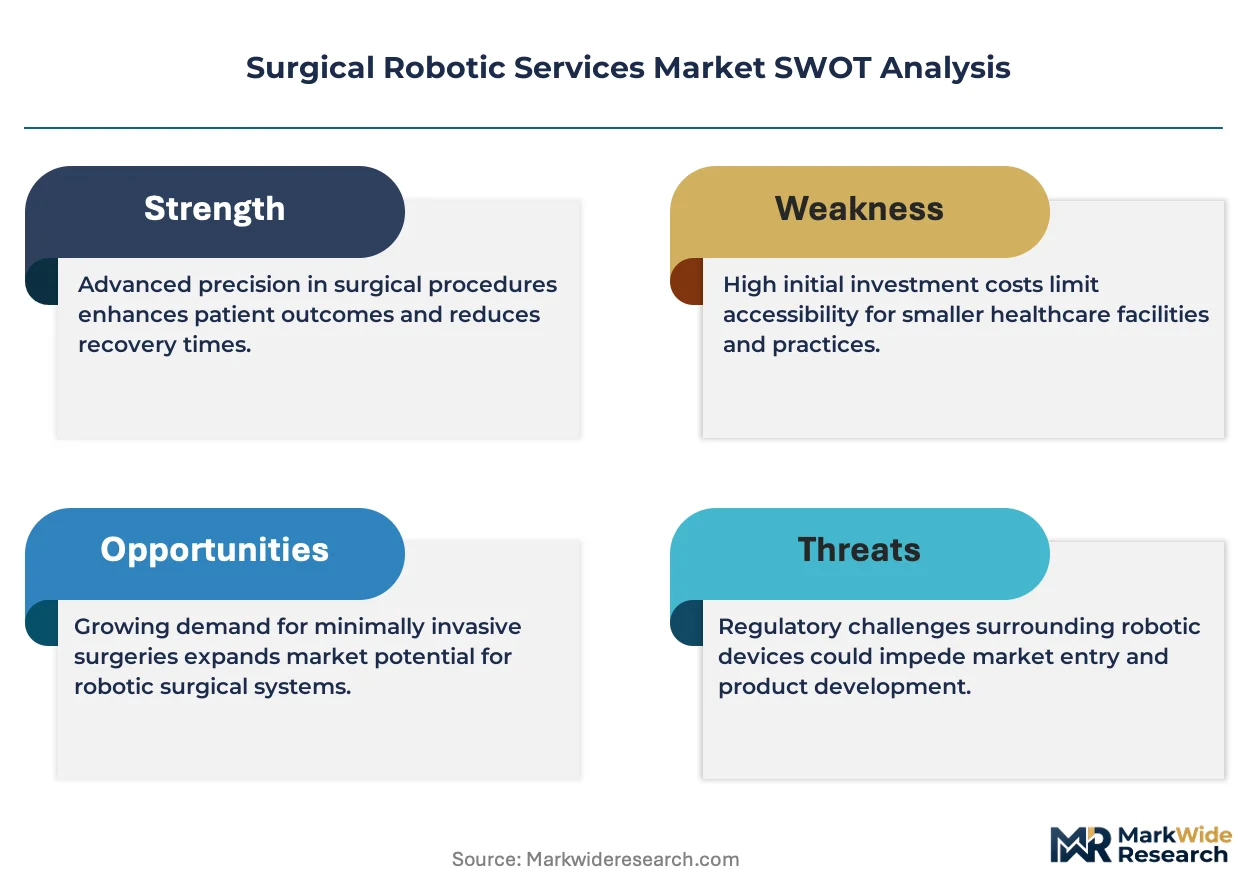
- Specialized Field Engineer Scarcity:ISO 13485-certified technicians command premium compensation, inflating service delivery costs across North American hospital networks.
- Consumable Price Compression:Single-use instrument reprocessing scrutiny limits per-procedure revenue yields in cost-conscious procurement environments.
- EU MDR Clinical Evidence Burden:Extended conformity assessment timelines delay service bundling approvals for software-integrated platforms in European markets.
Strategic Opportunities
- Japan PMDA Digital Health Integration:Regulatory receptivity to AI-assisted surgical guidance creates openings for algorithm-as-a-service licensing models.
- Orthopedic Procedure Volume Concentration:Knee and hip arthroplasty automation demand in Germany supports specialized Mako service hub establishment.
- Subscription-to-Outcome Pricing:Risk-sharing contracts tied to complication rate reductions align vendor incentives with hospital value-based care mandates.
Industry Challenges
- Legacy System Interoperability:Heterogeneous hospital IT architectures complicate unified dashboard deployment for fleet management software.
- Software Validation Cycle Compression:IEC 62304 documentation requirements for iterative updates strain quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Robotic Services Market |
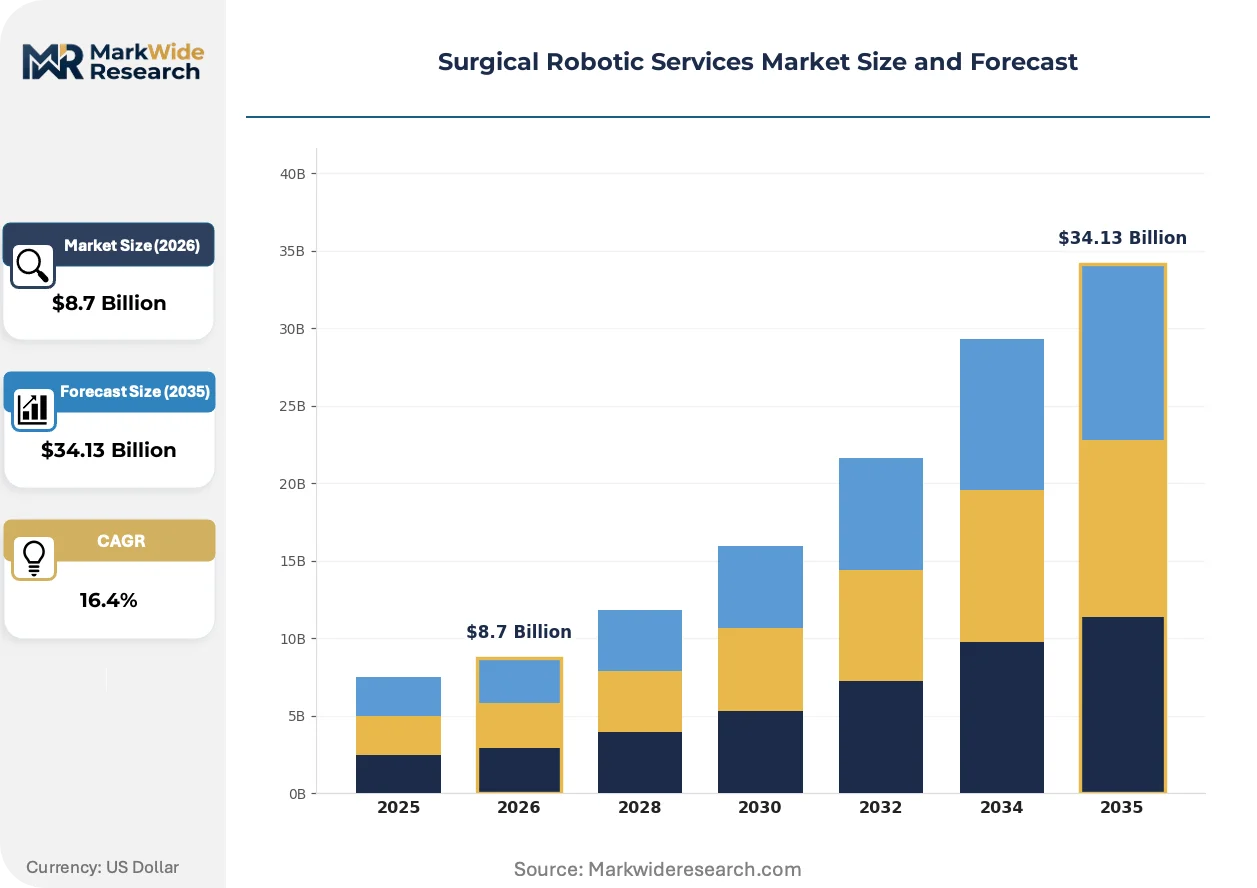
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
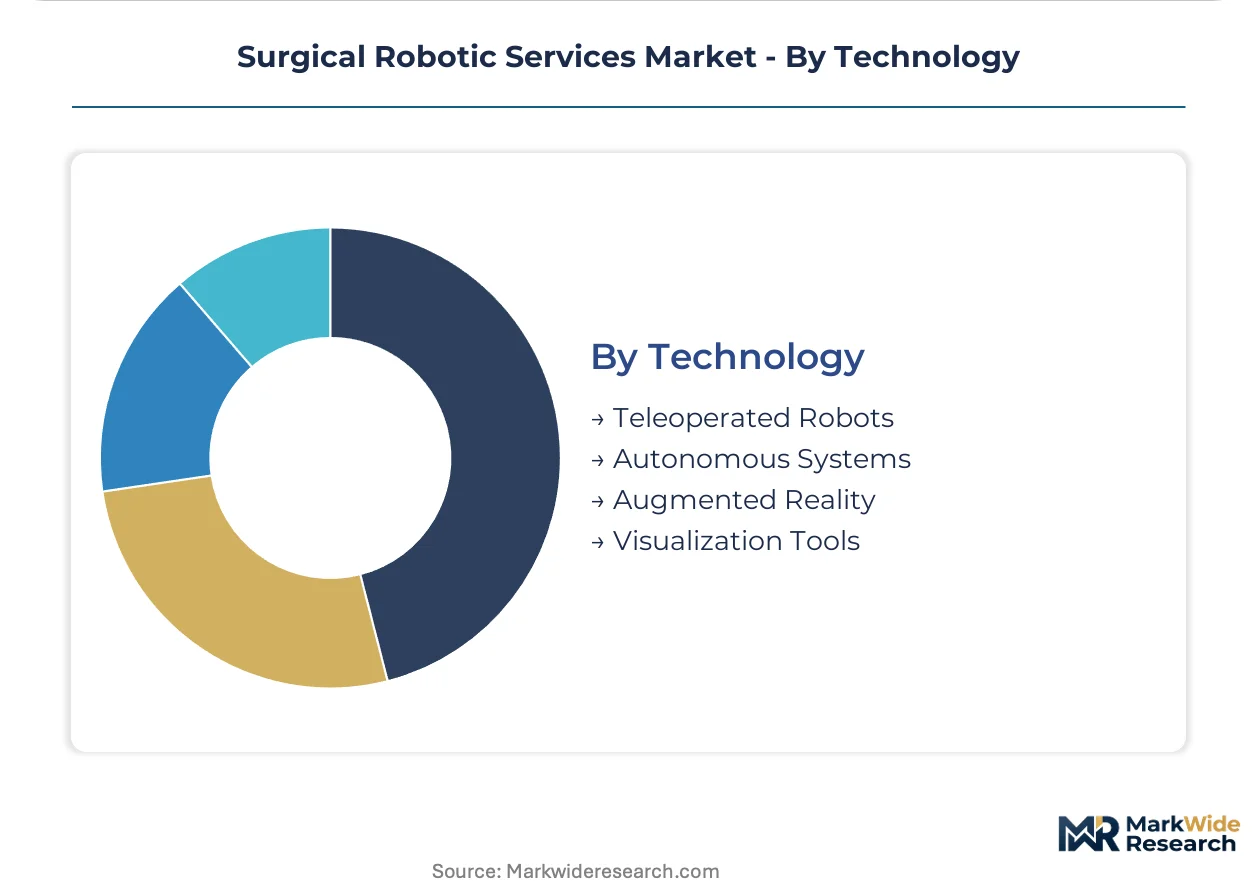
| Segmentation | Product Type: Robotic Arms, Control Systems, Surgical Instruments, Navigation Systems End User: Hospitals, Surgical Centers, Diagnostic Labs, Specialty Clinics Service Type: Installation, Maintenance, Training, Consulting Technology: Teleoperated Robots, Autonomous Systems, Augmented Reality, Visualization Tools |
| Companies Covered | Intuitive Surgical, Stryker, Medtronic, Johnson & Johnson, Zimmer Biomet, Smith & Nephew, CMR Surgical, Asensus Surgical, Accuray, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Robotic Services Market Evolving Landscape
Telepresence-assisted troubleshooting and edge-computing analytics are compressing mean-time-to-repair metrics while enabling preemptive component replacement before functional failure.
Digital twin simulation is electrifying preoperative planning workflows by creating patient-specific anatomical models that integrate with haptic feedback calibration. Academic medical centers in the United States are deploying these systems for resident training and complex case rehearsal. This capability is compressing learning curves and reducing intraoperative variability across high-volume surgical programs.
EU MDR Article 10 post-market surveillance requirements are mandating systematic clinical follow-up data collection for robotic-assisted procedures. Manufacturers must now embed outcome tracking modules into service contracts to satisfy notified body expectations. Orthopedic and gynecological applications face the steepest documentation burdens, driving consolidation toward vendors with established clinical registries.
Hospital procurement departments are unbundling training and maintenance components from traditional all-inclusive contracts. This fragmentation enables competitive benchmarking of discrete service elements but increases vendor administrative overhead. The United States exhibits the most advanced unbundling behavior, with IDN central procurement offices negotiating modular agreements across multi-hospital systems.
Surgical Robotic Services Market Segmentation
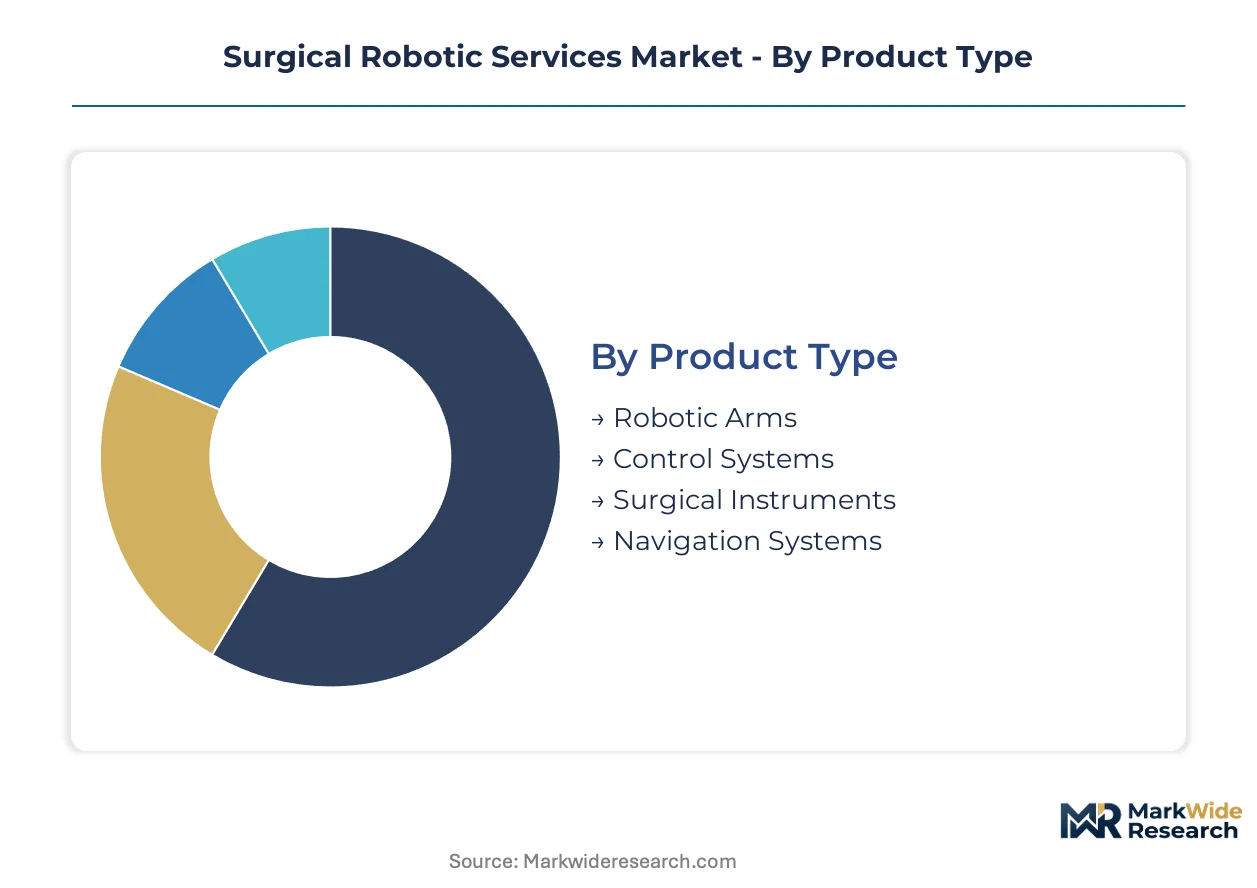
Service bundling strategies in surgical robotics diverge sharply across hardware categories, end-user scale, and technology maturity. Vendors calibrate contract structures to the depreciation profiles and regulatory burdens inherent to each segment axis.
Product Type:
Component complexity and regulatory classification density determine service contract duration and pricing architecture.
- Robotic Arms:Multi-joint manipulator assemblies with force-feedback sensors require ISO 13485-certified calibration protocols and joint lubrication schedules. Demand concentrates in academic medical centers across the United States where extended warranty terms protect capital-intensive installations against precision drift.
- Control Systems:Hardware-software integration platforms governing motion planning and safety interlocks. Surgical centers in Germany anchor replacement demand as ambulatory procedural volumes strain legacy console reliability.
- Surgical Instruments:Single-use and limited-reuse end effectors with embedded RFID tracking chips for sterilization cycle monitoring.
- Navigation Systems:Optical and electromagnetic tracking arrays for real-time instrument localization during image-guided procedures.
Mature deployment sits with Robotic Arms. Newer deployment is concentrated in Navigation Systems.
End User:
Procurement sophistication and case volume density shape service tier eligibility and response-time guarantees.
- Hospitals:Integrated delivery networks with centralized biomedical engineering departments negotiate enterprise-wide fleet management agreements. The United States exhibits the most advanced unbundling behavior, with IDN procurement offices dissecting training and maintenance components for competitive benchmarking.
- Surgical Centers:Ambulatory facilities with constrained square footage favor compact platforms requiring localized maintenance networks. These sites are expanding most quickly as outpatient procedural migration accelerates across North America.
- Diagnostic Labs:Pathology-focused installations with intermittent utilization patterns and lower throughput requirements.
- Specialty Clinics:Urology and gynecology-focused practices with procedure-specific platform configurations.
Contract standardization dominates Hospitals. Customization pressure concentrates in Surgical Centers.
Service Type:
Margin accretion potential and cash flow predictability vary across the service lifecycle, with post-installation activities commanding premium pricing power.
- Maintenance:Preventive and corrective service agreements covering hardware inspection, software patching, and component replacement. Multi-year contracts generate predictable cash flows and lock in consumable replenishment cycles for vendors.
- Training:Surgeon credentialing programs and staff certification modules tied to FDA-mandated proficiency requirements. Academic medical centers in the United States anchor demand as residency programs integrate robotic curricula.
- Installation:Site preparation, equipment positioning, and initial calibration activities with lower recurring revenue attachment.
- Consulting:Workflow optimization and OR integration advisory services with project-based fee structures.
Revenue concentration rests with Maintenance. Growth velocity peaks in Training.
Technology:
Autonomy levels and data architecture requirements determine validation burdens and software update frequencies.
- Teleoperated Robots:Master-slave architectures with haptic feedback loops requiring real-time latency optimization. FDA 510(k) pathway streamlining for software-only updates accelerates feature rollouts and subscription revenue recognition for these platforms.
- Autonomous Systems:Procedure-phase automation with pre-programmed motion sequences and safety boundary enforcement. Japan PMDA digital health integration creates openings for algorithm-as-a-service licensing models in this segment.
- Augmented Reality:Overlay visualization systems projecting anatomical guidance onto the surgical field.
- Visualization Tools:4K and 3D endoscopic imaging chains with color calibration and sterilizable camera heads.
Regulatory clarity favors Teleoperated Robots. Evidence generation demands concentrate in Autonomous Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Service production concentrates in the United States and Germany where OEMs maintain captive engineering workforces, while consumption spreads across hospital networks in Japan and the United Kingdom seeking localized maintenance coverage.
United States
Academic medical centers in Boston and Houston anchor installed-base expansion for multi-port robotic platforms. FDA 510(k) premarket notification requirements push manufacturers toward comprehensive training bundles that satisfy proficiency mandates. The Cleveland Clinic and Mayo Clinic networks negotiate enterprise-wide service agreements that unbundle maintenance from consumable replenishment.
Germany
Orthopedic procedure volume concentration in Bavaria and North Rhine-Westphalia supports specialized Mako service hub establishment. EU MDR Article 10 post-market surveillance requirements mandate systematic clinical follow-up data collection embedded in service contracts. Berlin-based hospital procurement offices dissect training components for competitive benchmarking across Charité and Vivantes networks.
Japan
PMDA digital health integration creates openings for algorithm-as-a-service licensing models in autonomous surgical guidance. METI funding for robotic surgery diffusion accelerates adoption in Kanto and Kansai metropolitan areas. Tokyo Women's Medical University and Osaka University Hospital anchor predictive maintenance contract demand for next-generation platforms.
United Kingdom
NHS England procurement frameworks favor multi-year service agreements with outcome-based pricing tied to complication rate reductions. MHRA conformity assessment timelines align with EU MDR standards for software-integrated platforms. Imperial College Healthcare and Guy's and St Thomas' NHS Foundation Trust drive unbundling behavior in London surgical networks.
Canada
Health Canada premarket notification requirements for robotic surgical devices elevate field service complexity in Ontario and Quebec hospital networks. Provincial health authorities in British Columbia negotiate centralized fleet management agreements for rural outreach programs. University Health Network in Toronto anchors western Canadian training and certification demand.
Surgical Robotic Services Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the service architecture. The market exhibits consolidated OEM dominance at the platform tier with fragmented specialization in regional maintenance networks. Two strategic archetypes prevail: integrated manufacturers capturing recurring revenue through captive service arms, and third-party service providers filling geographic coverage gaps for legacy installations. Competitive moves center on predictive analytics integration into multi-year agreements and unbundling of training modules to capture procurement office benchmarking.
Among integrated manufacturers, Intuitive Surgical, Stryker, and Medtronic exemplify distinct service monetization approaches. Intuitive Surgical leverages its da Vinci ecosystem position to sustain recurring instrument tracking and analytics subscriptions. Stryker anchors orthopedic service portfolios through predictive maintenance contracts reducing suite downtime. Medtronic competes via extended warranty and remote diagnostics packages tied to platform deployments. Each represents a variant of the bundled-service archetype displacing pure capital equipment transactions.
| Leading Market Players |
|---|
| Intuitive Surgical |
| Stryker |
| Medtronic |
| Johnson & Johnson |
| Zimmer Biomet |
| Smith & Nephew |
| CMR Surgical |
| Asensus Surgical |
| Accuray |
| Others |
Value Network & Pricing Analysis
ISO 13485-certified field engineers in the United States command premium compensation that widens pricing-tier spreads between academic medical centers and ambulatory surgical centers. Labor-cost differentials between North American and European service workforces feed directly into contract rate variations for predictive maintenance bundles.
Pricing Analysis
Margin tightening in multi-year maintenance contracts reflects consumable price compression scrutiny from hospital procurement offices. Three-tier pricing structure across premium, standard, and economy levels segments by response-time guarantees and analytics depth, with ISO 13485 certification tier as the primary quality differentiator. Cost-down pressure on training modules accelerates because IDN central procurement offices negotiate modular unbundling. Surgical centers exhibit the highest price sensitivity due to constrained capital budgets, while academic medical centers prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Freight costs for precision-calibrated robotic arm assemblies from Germany and the United States elevate landed costs for Asia-Pacific hospital networks. Component sourcing draws from Japanese force-feedback sensor manufacturers, German optical tracking array producers, and United States-based haptic calibration specialists. Single-source vulnerability concentrates in sterilizable camera head supply chains. Distribution runs through OEM captive service arms for platform-tier contracts, with third-party maintenance networks filling legacy system coverage gaps.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over predictive analytics software and consumable replenishment cycles determines margin capture. Players pursue downstream lock-in through multi-year service agreements that embed remote diagnostics and algorithm subscriptions.
For Market Incumbents: Deploy predictive maintenance algorithm development to deepen software-defined revenue attachment. Consolidate field service networks in Germany and Japan to preempt third-party encroachment on Mako and Hugo platform maintenance. ISO 13485-certified technician scarcity threatens response-time guarantees; accelerate in-house certification programs. For New Entrants and Emerging Players: The premium-to-economy pricing gap in ambulatory surgical center contracts offers white-space entry below Intuitive Surgical's da Vinci service tiers. Target orthopedic-focused surgical centers in North America with compact platform maintenance bundles. Pursue algorithm-as-a-service licensing through Japan PMDA digital health pathways. For Investors and Strategic Acquirers: Re-rating potential sits with regional third-party service providers given EU MDR post-market surveillance data collection mandates. Five-to-ten year viability hinges on clinical registry ownership and notified body relationships. Monitor FDA 510(k) software-only update volume as inflection indicator for subscription revenue velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Enterprise-wide fleet management agreements with IDNs lock in multi-year consumable replenishment cycles. |
| Software Companion Development | Predictive analytics modules embedded in service contracts satisfy EU MDR post-market surveillance requirements. |
| CE Marking Pathway | MDR conformity assessment for software-integrated platforms enables European service bundling approvals. |
| Reimbursement Strategy | Outcome-based pricing tied to complication rate reductions aligns with NHS England value-based procurement. |
| FDA Submission | 510(k) premarket notification streamlining for software-only updates accelerates feature rollout monetization. |
Research Methodology
Independent corroboration across hospital procurement managers, biomedical engineering directors, GPO contracts managers, and OEM service executives underwrites the qualitative findings. Primary fieldwork with Intuitive Surgical, Stryker, and Medtronic service operations teams combined with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, and hospital procurement database analysis. Bottom-up installed-base modeling and top-down market sizing triangulate volume estimates.
Rate-of-change decomposition across the projection horizon segments by service type, technology autonomy level, end-user scale, and regional regulatory cluster. CAGRs derive from instrument tracking data, contract renewal rates, and ambulatory procedural volume migration patterns. Software-defined feature licensing velocity and predictive maintenance attachment rates inform growth trajectory assumptions.
Underlying measurement precision varies by segment; maintenance contract value carries tighter precision than consulting revenue projections. Forecasts reflect assumptions about FDA pathway efficiency and EU MDR assessment timelines that regulatory divergence could revise. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Robotic Aseptic Syringe Filler Capper Market
Medical Devices
Transplant Monitoring Kits Market
Medical Devices
Japan Anesthesia Devices Market
Medical Devices
Vascular Screening Devices Market
Medical Devices
Oxygen Therapy Devices Market
Medical Devices
Bioimpedance Spectroscopy Market
Medical Devices
Pelvic Floor Electrical Stimulation Devices Market
Medical Devices
United Kingdom Ultrasound Devices Market
Medical Devices
Global Transradial Access Market
Medical Devices
Asia-Pacific Ultrasound Probe Disinfection Market
Medical Devices
Chest Drainage Devices Market
Medical Devices
Smart Patches Market
Medical Devices
Chile Artificial Organs and Bionic Implants Market
Medical Devices
Penile Implants Market
Medical Devices
Interventional Cardiology and Peripheral Vascular Devices Market
Medical Devices
North America Micro Invasive Glaucoma Surgery (MIGS) Devices Market