
 Urology Ultrasound Market | 2026-2036
Urology Ultrasound Market Size, Share, and Industry Trends Forecast 2026-2036
Urology Ultrasound Market Outlook
The EU Medical Device Regulation is restructuring procurement criteria across European urology practices, forcing manufacturers to recertify legacy systems under stricter clinical evidence rules. GE Healthcare leverages its installed base in academic medical centers to sustain service contract renewals. Siemens Healthineers anchors its position through integrated PACS connectivity that locks in hospital system loyalty.
Urology ultrasound employs high-frequency transducers, typically 3.5–7.5 MHz for renal imaging and 5.0–8.0 MHz for prostate visualization, generating real-time tomographic images of the urinary tract and male reproductive organs without ionizing radiation. Portable ultrasound systems now lead capital expenditure decisions among ambulatory urology clinics seeking to reduce patient throughput bottlenecks. Doppler technology commands premium positioning where vascular assessment of renal transplants or testicular perfusion drives clinical workflow value.
The FDA's 510(k) clearance pathway and the EU MDR's enhanced post-market surveillance requirements jointly shape device lifecycle economics, compressing amortization schedules for manufacturers. ISO 13485 quality management certification has become a non-negotiable qualifier for tenders issued by consolidated hospital purchasing networks. Stakeholders must monitor how AI-enabled image analysis modules trigger new software-as-a-medical-device classification debates that could fragment regulatory compliance costs across product portfolios.
Market Dynamics
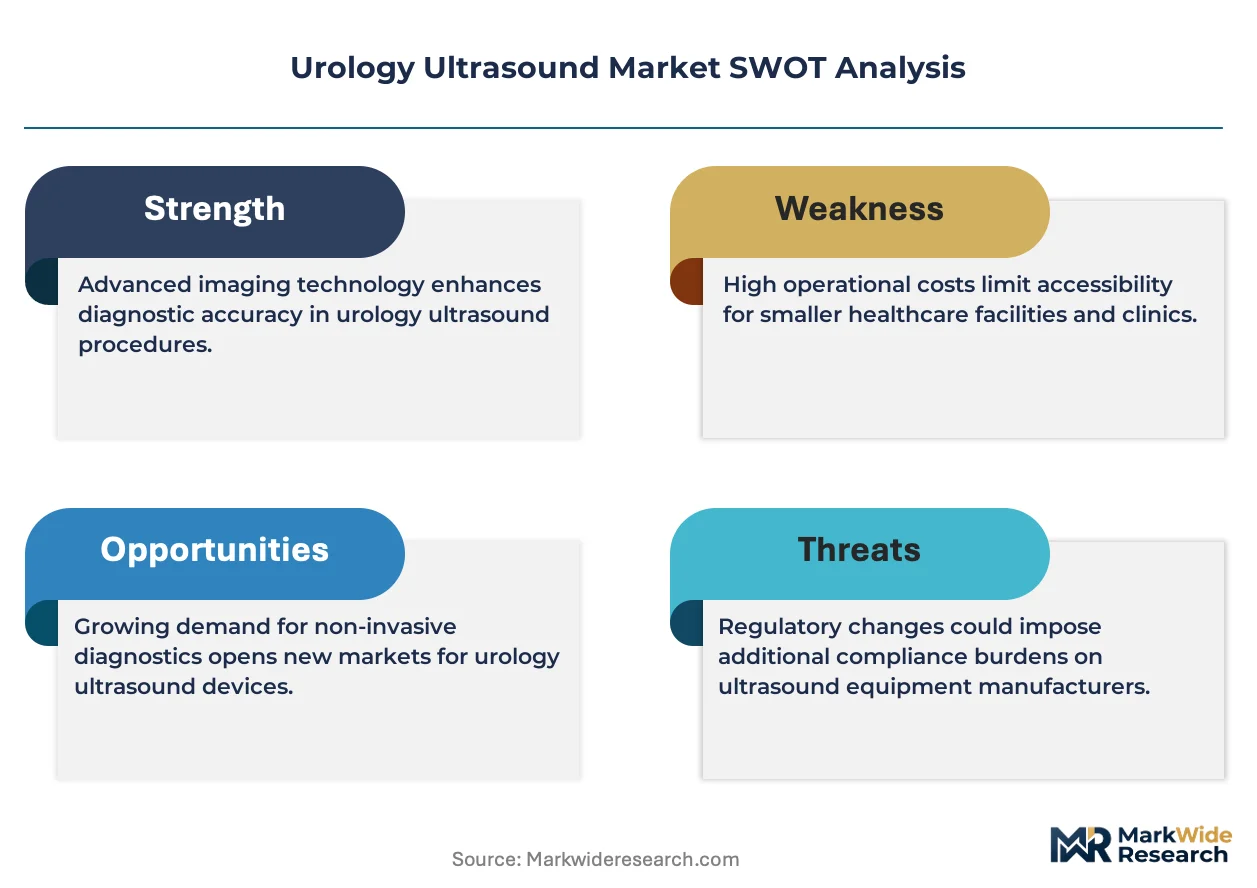
The EU Medical Device Regulation's recertification mandates are compressing device lifecycle economics and forcing manufacturers to rebuild clinical evidence portfolios for legacy ultrasound platforms.
Growth Catalysts
- Ambulatory clinic expansion:Germany's outpatient urology network is driving portable system procurement as clinics seek to eliminate patient throughput bottlenecks without capital-intensive fixed installations.
- CE marking under MDR:Stricter post-market surveillance requirements are filtering out marginal competitors and consolidating procurement decisions around ISO 13485-certified suppliers with robust quality management systems.
- High-frequency transducer advancement:5.0–8.0 MHz prostate visualization capabilities are expanding reimbursable diagnostic indications beyond traditional renal imaging into male reproductive health screening protocols.
Market Restraints
- Input cost volatility:Piezoelectric crystal supply concentration in East Asian component foundries exposes manufacturers to raw material price swings and geopolitical sourcing disruptions.
- Technical ceiling:Doppler vascular assessment remains operator-dependent, limiting standardization across community hospital settings where sonographer training depth varies.
- Regulatory friction:FDA 510(k) clearance timelines for AI-enabled image analysis modules are extending as software-as-a-medical-device classification debates fragment compliance pathways.
Strategic Opportunities
- Rural clinic penetration:India's tier-2 and tier-3 cities present white space for handheld ultrasound systems as CDSCO streamlines medical device import licensing for diagnostic imaging equipment.
- AI convergence:Real-time lesion detection algorithms are converging with cloud-based PACS architectures to enable remote diagnostic support for understaffed regional hospitals.
- Service contract unbundling:After-sales maintenance agreements are decoupling from hardware sales, creating recurring revenue streams independent of capital expenditure cycles.
Industry Challenges
- Sonographer training deficit:Specialized urology ultrasound competency gaps in community health systems delay point-of-care program rollouts and limit clinical utility capture.
- Legacy PACS integration:Hospital information system heterogeneity forces costly middleware development for seamless image workflow connectivity.
- Evidence generation burden:MDR clinical investigation requirements demand prospective data collection that strains R&D budgets for mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urology Ultrasound Market |
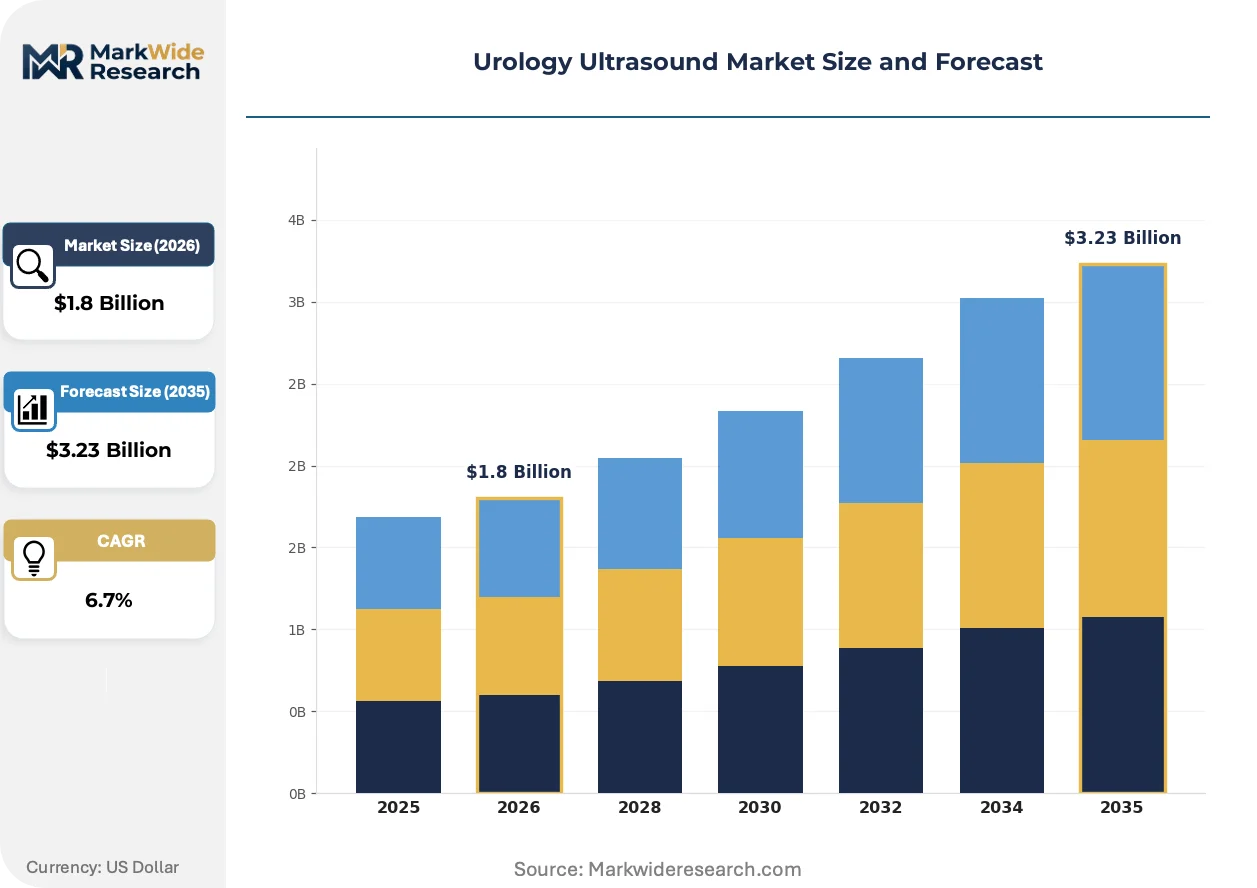
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Ultrasound, Transrectal Ultrasound, Doppler Ultrasound, Contrast-Enhanced Ultrasound Application: Kidney Stones, Prostate Examination, Bladder Assessment, Renal Failure Diagnosis End User: Hospitals, Diagnostic Centers, Urology Clinics, Research Institutions Technology: Ultrasound Imaging, 3D Imaging, High-Resolution Imaging, Doppler Technology |
| Companies Covered | Canon Medical Systems Corporation, Samsung Medison Co., Ltd., GE Healthcare, Fujifilm Holdings Corporation, Esaote SpA, Siemens Healthineers AG, Mindray Medical International Limited, BK Medical, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urology Ultrasound Market Strategic Shifts
Artificial intelligence modules are rewiring competitive differentiation in diagnostic imaging, while regulatory frameworks struggle to keep pace with software-driven functionality expansion.
Deep learning-based prostate volume measurement algorithms are converging with automated lesion contouring to reduce inter-operator variability in cancer staging workflows. Academic medical centers in the United States are piloting these tools for resident training standardization. The technology is compressing diagnostic turnaround times from imaging to biopsy decision.
The EU AI Act's risk classification system for medical decision-support software is triggering portfolio rearchitecture among ultrasound manufacturers with European market exposure. High-risk system designations impose conformity assessment burdens that favor established players with dedicated regulatory affairs infrastructure. Smaller vendors are retreating from AI-enabled feature development to avoid compliance cost exposure.
Hospital purchasing networks are consolidating vendor relationships around integrated imaging ecosystems that bundle hardware, software, and long-term service commitments. Independent ambulatory clinics resist this bundling, seeking modular procurement that preserves equipment interoperability flexibility. Germany's outpatient urology sector exhibits the strongest unbundled purchasing preference intensity.
Urology Ultrasound Market Segmentation
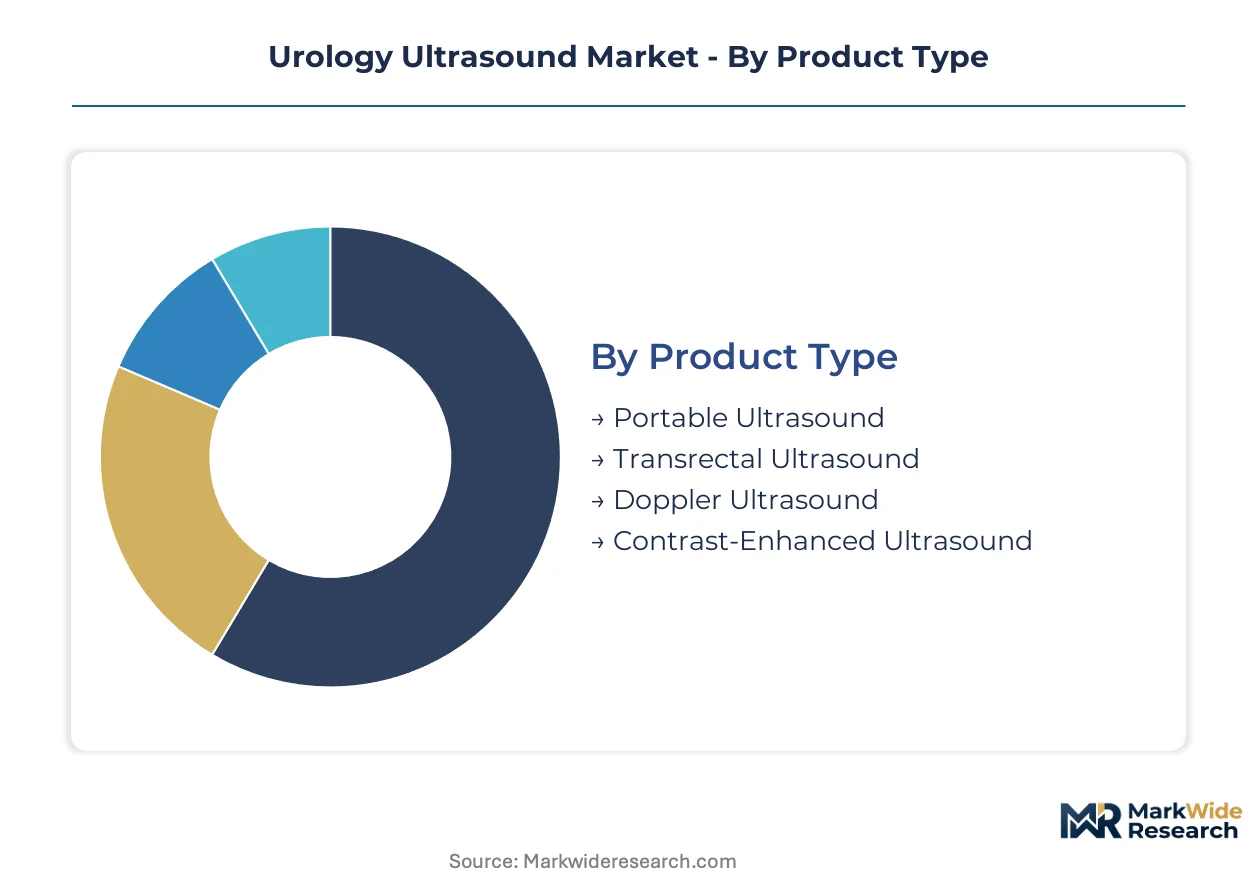
Urology ultrasound segmentation reveals distinct capital deployment patterns across hardware platforms, clinical applications, and care delivery settings. Procurement decisions diverge sharply between capital-intensive hospital installations and lean ambulatory clinic deployments.
Product Type:
Capital intensity varies dramatically across product categories, with fixed installations demanding infrastructure commitments while portable systems minimize upfront expenditure.
- Portable Ultrasound:Battery-powered cart-based or handheld units deploy 3.5–7.5 MHz transducers for renal and bladder imaging without dedicated procedure rooms. Germany's outpatient urology clinic network is consolidating procurement around these systems to eliminate patient throughput bottlenecks while avoiding construction costs.
- Transrectal Ultrasound:Dedicated 5.0–8.0 MHz endocavity probes enable prostate visualization with automated biopsy guidance capabilities. Academic medical centers in the United States anchor demand as residency programs standardize training protocols around integrated fusion biopsy platforms.
- Doppler Ultrasound:Vascular assessment functionality commands premium positioning for renal transplant perfusion monitoring.
- Contrast-Enhanced Ultrasound:Microbubble-based perfusion imaging expands reimbursable indications for complex renal mass characterization.
Most installed capacity flows through Portable Ultrasound. Expansion is steepest in Doppler Ultrasound.
Application:
Reimbursement density and procedure volume concentration determine where manufacturers prioritize clinical evidence generation and sales force deployment.
- Kidney Stones:Real-time stone localization and fragmentation guidance using 3.5–5.0 MHz abdominal probes supports extracorporeal shock wave lithotripsy workflows. Hospital emergency departments drive replacement demand as point-of-care protocols reduce CT radiation exposure.
- Prostate Examination:Volume measurement and lesion contouring for cancer staging workflows compress diagnostic turnaround times. The United States exhibits the strongest preference intensity for AI-enabled automated prostate volume algorithms in academic training environments.
- Bladder Assessment:Post-void residual volume measurement dominates ambulatory clinic utilization patterns.
- Renal Failure Diagnosis:Cortical thickness and echogenicity assessment supports chronic kidney disease monitoring protocols.
Procedure volume concentrates in Prostate Examination. Clinical utility expansion is advancing most quickly in Kidney Stones.
End User:
Purchasing authority structures and capital allocation cycles create divergent vendor engagement models across institutional settings.
- Hospitals:Consolidated purchasing networks negotiate multi-year service contracts with integrated PACS connectivity requirements. Siemens Healthineers anchors loyalty through enterprise imaging ecosystem bundling that locks in system-wide procurement decisions.
- Diagnostic Centers:High-throughput operations prioritize rapid exam turnaround and standardized reporting workflows. India's tier-2 and tier-3 cities present white space as CDSCO streamlines import licensing for diagnostic imaging equipment.
- Urology Clinics:Germany's outpatient network exhibits the strongest unbundled purchasing preference intensity.
- Research Institutions:Pilot funding drives early adoption of AI-enabled image analysis modules.
Capital deployment is heaviest in Hospitals. Share gain is steepest in Urology Clinics.
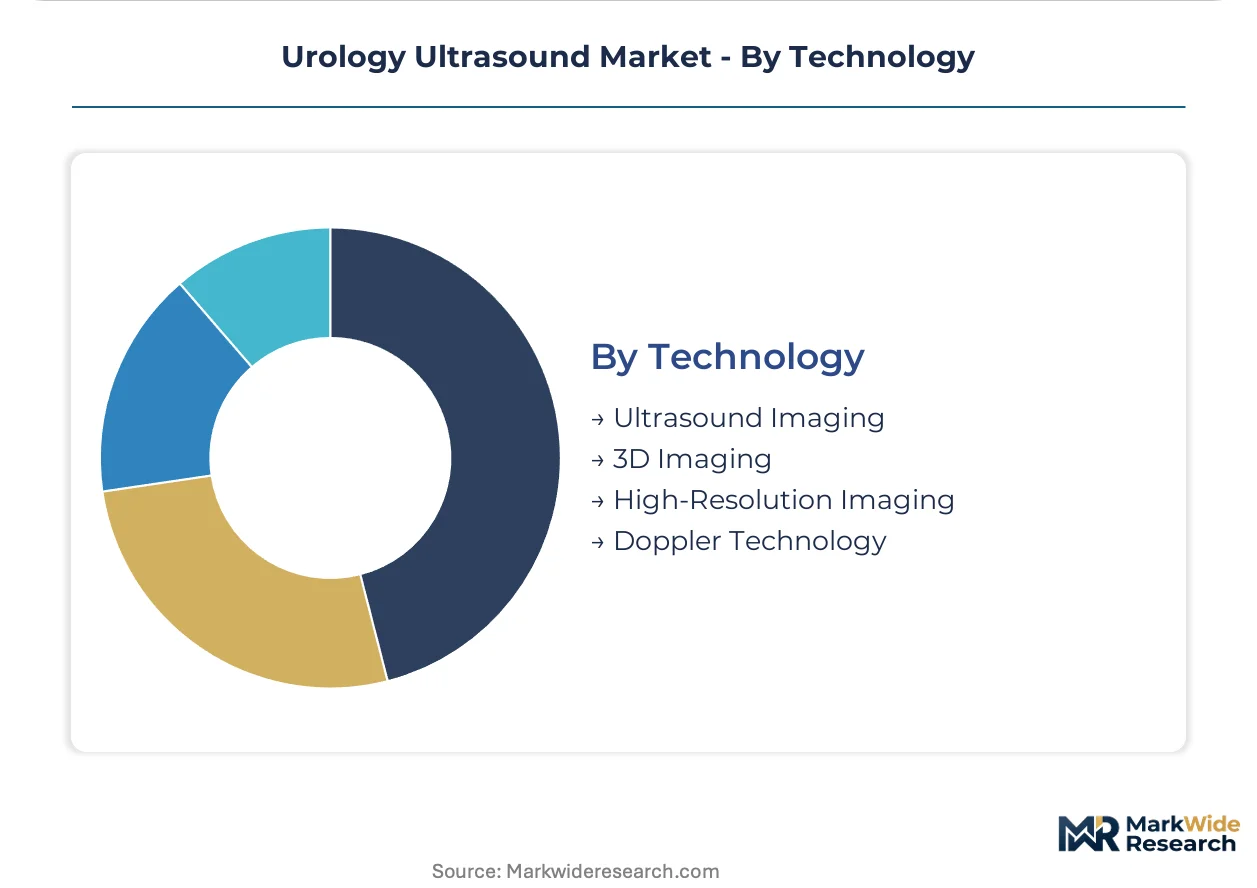
Technology:
Intellectual property concentration and regulatory classification complexity fragment competitive positioning across technical modalities.
- Ultrasound Imaging:Conventional B-mode tomography using piezoelectric crystal arrays generates real-time grayscale anatomical visualization. East Asian component foundries concentrate piezoelectric crystal supply, exposing manufacturers to raw material price volatility and geopolitical sourcing disruptions.
- 3D Imaging:Volume acquisition and multiplanar reconstruction enable spatial lesion characterization for surgical planning. The EU AI Act's risk classification system for medical decision-support software is triggering portfolio rearchitecture among manufacturers with European market exposure.
- High-Resolution Imaging:Broadband transducer technology expands diagnostic confidence for small renal mass detection.
- Doppler Technology:Spectral and color flow mapping remains operator-dependent, limiting standardization across community hospital settings.
Patent density clusters in 3D Imaging. Regulatory friction is most acute for Doppler Technology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The urology ultrasound industry traces its commercial origins to post-war German engineering clusters, where precision acoustic transducer manufacturing first achieved clinical scale. From these foundations, production expertise diffused through multinational medical device supply chains. Today, procurement patterns concentrate in health systems with dense outpatient urology networks and stringent device certification regimes.
United States
Academic medical centers drive demand for AI-enabled prostate volume algorithms and fusion biopsy platforms. FDA 510(k) clearance timelines for software-as-a-medical-device modules are extending as classification debates intensify. The Boston-Cambridge corridor anchors pilot programs for resident training standardization around automated lesion contouring systems.
Germany
Outpatient urology clinics prioritize portable systems to eliminate patient throughput bottlenecks without construction costs. EU MDR recertification mandates are filtering out marginal competitors and consolidating procurement around ISO 13485-certified suppliers. The Munich-Stuttgart axis concentrates service contract unbundling experiments that separate maintenance agreements from hardware sales.
China
Domestic manufacturers are capturing share in tier-2 and tier-3 hospital procurement through cost-optimized cart-based systems. NMPA streamlined registration pathways for diagnostic imaging equipment are accelerating import substitution. The Yangtze River Delta manufacturing belt hosts piezoelectric crystal foundries that supply transducer arrays across Asia-Pacific assembly networks.
India
Diagnostic imaging demand is expanding in tier-2 and tier-3 cities as urology clinic networks penetrate underserved populations. CDSCO import licensing streamlining for medical devices is reducing regulatory friction for handheld ultrasound distributors. Maharashtra's Mumbai-Pune corridor concentrates private diagnostic center chains that prioritize rapid exam turnaround and standardized reporting workflows.
Japan
Aging demographics are elevating reimbursable indications for renal failure monitoring and chronic kidney disease surveillance. PMDA post-market surveillance requirements align with global MDR trends in demanding robust clinical evidence portfolios. The Kansai region's Osaka-Kobe medical device cluster sustains precision manufacturing capabilities for high-frequency transducer arrays.
Urology Ultrasound Market Competitive Environment
Premium-margin players sit above commodity-margin players across service contract bundling and PACS integration dimensions. The vendor base stratifies between integrated imaging ecosystem providers, portable system specialists, and component-scale transducer manufacturers. Two strategic archetypes dominate: academic medical center anchors that lock in loyalty through residency training standardization, and ambulatory clinic suppliers that compete on capital expenditure minimization. Competitive moves concentrate on AI-enabled feature licensing and geographic expansion into underpenetrated outpatient networks.
Within the integrated ecosystem tier, Siemens Healthineers AG and GE Healthcare exemplify platform bundling strategies that embed hardware within enterprise imaging architectures. Among portable system specialists, Mindray Medical International Limited occupies a position representing cost-optimized cart-based configurations for high-volume clinic deployments. Esaote SpA anchors the European specialist archetype, sitting within the premium tier through focused clinical application depth rather than breadth.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Samsung Medison Co., Ltd. |
| GE Healthcare |
| Fujifilm Holdings Corporation |
| Esaote SpA |
| Siemens Healthineers AG |
| Mindray Medical International Limited |
| BK Medical |
| Koninklijke Philips N.V. |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap transducer specialists anchor the European supply base, enforcing pricing discipline through long-term service contract bundling that captures recurring revenue independent of hardware replacement cycles. This ownership structure limits aggressive price competition while concentrating procurement leverage among ISO 13485-certified suppliers with dedicated regulatory affairs infrastructure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the installed base by certification grade and PACS integration depth. Premium tiers command loyalty through Siemens Healthineers-style enterprise ecosystem bundling, while economy tiers face compression from Chinese cart-based imports in India's tier-3 diagnostic centers. Academic medical centers exhibit the lowest price sensitivity, prioritizing AI-enabled prostate volume algorithms over capital expenditure minimization.
Supply Chain Analysis
Dual-sourcing requirements for piezoelectric crystal arrays mandate qualification of both Japanese and Chinese foundries, though the Yangtze River Delta manufacturing belt retains dominant volume share. Transducer assembly draws from East Asian component networks while final system integration concentrates in Germany, the United States, and China. Single-source vulnerability in high-purity ceramic substrates exposes manufacturers to logistics chokepoint risk. Distribution runs through consolidated hospital purchasing networks in developed markets and independent medical device distributors in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The urology ultrasound market represents a late-cycle quality story as procurement committees elevate ISO 13485 certification and MDR compliance documentation above sticker-price minimization. Demand is shifting toward premium specifications for AI-enabled image analysis modules that reduce inter-operator variability in prostate cancer staging workflows.
For Market Incumbents: Acquire AI-enabled software module developers to fill capability gaps in automated lesion contouring before emerging specialists achieve FDA 510(k) clearance for standalone diagnostic algorithms. Defend service contract renewal rates by embedding predictive maintenance telemetry that raises switching costs for hospital systems. Prioritize backward integration into piezoelectric crystal supply to insulate margins from East Asian raw material volatility.
For New Entrants and Emerging Players: Capture India's tier-2 and tier-3 diagnostic center expansion as CDSCO import licensing streamlines create regulatory arbitrage opportunities against entrenched multinational incumbents. Target handheld ultrasound white space in Germany's outpatient urology clinic network where unbundled purchasing preference intensity resists ecosystem lock-in. Deploy direct clinical specialist sales teams rather than distributor intermediaries to demonstrate rapid exam turnaround value.
For Investors and Strategic Acquirers: Private equity firms with healthcare technology portfolios are the most active acquirer in this space, rolling up mid-tier service contract providers to build platform-scale recurring revenue bases. Long-term viability hinges on regulatory compliance infrastructure depth rather than hardware innovation velocity. Monitor EU AI Act high-risk system designations as the signal to watch for portfolio rearchitecture inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR recertification timelines filter marginal competitors and consolidate procurement around compliant suppliers. |
| Hospital System Partnership | Integrated PACS connectivity locks in enterprise-wide loyalty through Siemens Healthineers-style ecosystem bundling. |
| Software Companion Development | AI-enabled prostate volume algorithms reduce diagnostic turnaround times in academic medical center training protocols. |
| Reimbursement Strategy | Expanded indications for contrast-enhanced renal mass characterization capture premium positioning in cancer staging workflows. |
| Geographic Expansion | CDSCO regulatory streamlining opens tier-2 and tier-3 Indian cities for handheld system penetration. |
Study Parameters
Multiple input streams — primary interviews with hospital purchasing committee members, biomedical engineers, and GPO contracts managers; secondary validation against FDA 510(k) clearance databases, EU MDR notified body documentation, and hospital procurement records; and trade data from diagnostic imaging equipment import registries — were reconciled through bottom-up and top-down triangulation. Stakeholder perspectives from academic medical center radiology departments, outpatient urology clinic operators, and transducer component suppliers informed demand-side and supply-side calibration.
Data-stream reconciliation across product type, application, end-user category, and technology modality dimensions generated volume and value outputs over the projection horizon. CAGRs were derived from segmented growth rate reconciliation against macro healthcare expenditure trends and medical device regulatory cycle impacts. Forecast inputs incorporated EU MDR recertification timeline assumptions, AI-enabled software classification pathway probabilities, and ambulatory clinic capital deployment patterns.
EU AI Act risk classification shifts, FDA software-as-a-medical-device pathway extensions, and piezoelectric crystal supply disruptions are the dominant revision risks to modeled outputs. Deviation in MDR enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Voiding Cystourethrogram Market
Urology
Global Benign Prostatic Hyperplasia Treatment Market
Urology
Nordic Urinary Catheters Market
Urology
Renal Cyst Treatment Market
Urology
Cystectomy Market
Urology
Disposable Ureteroscope Market
Urology
Urology Forceps Market
Urology
Urinary Bag Market
Urology
Urology Robotic Surgery Market
Urology
India Urology Market
Urology
Prostate Cancer Minimally Invasive Surgery Market
Urology
Single Use Cystoscope Market
Urology
Ureter Cancer Treatment Market
Urology
Hematuria Treatment Market
Urology
Urethral Stricture Market
Urology
Pyelonephritis Treatment Market