
 Asthma Inhaler Device Market | 2026-2036
Asthma Inhaler Device Market Size, Share, and Industry Trends Forecast 2026-2036
Asthma Inhaler Device Market Analysis
Hospital procurement channels is reconfiguring how asthma inhaler device manufacturers reach institutional buyers. GlaxoSmithKline leverages its established formulary relationships to sustain volume commitments across integrated delivery networks. AstraZeneca competes through its digital respiratory portfolio, while Teva Pharmaceutical Industries anchors the generic segment with cost-focused metered-dose alternatives.
An asthma inhaler device is a pressurized or breath-actuated apparatus designed to aerosolize medication into particle sizes between one and five microns for deep lung deposition, serving the primary purpose of delivering bronchodilators and corticosteroids directly to inflamed airways. Metered-dose inhalers dominate hospital formularies due to their compact design and dose consistency, though dry powder inhalers are gaining share in home care settings where breath-actuated delivery reduces coordination errors. Smart inhalers within the technology segment command premium positioning as connectivity features enable adherence tracking, while conventional inhalers retain volume leadership in price-sensitive pharmacy channels.
The FDA regulates device-drug combination products under 21 CFR Part 4, requiring human factors validation for all new inhaler submissions, while the EMA's MDR framework imposes stricter clinical evidence thresholds for connected devices entering European markets. ISO 20072 standards govern testing protocols for oropharyngeal deposition profiles, directly shaping which platforms achieve regulatory clearance. Stakeholders must weigh the capital intensity of connected device development against the risk of formulary exclusion as payers tighten reimbursement criteria for non-adherence-linked therapies.
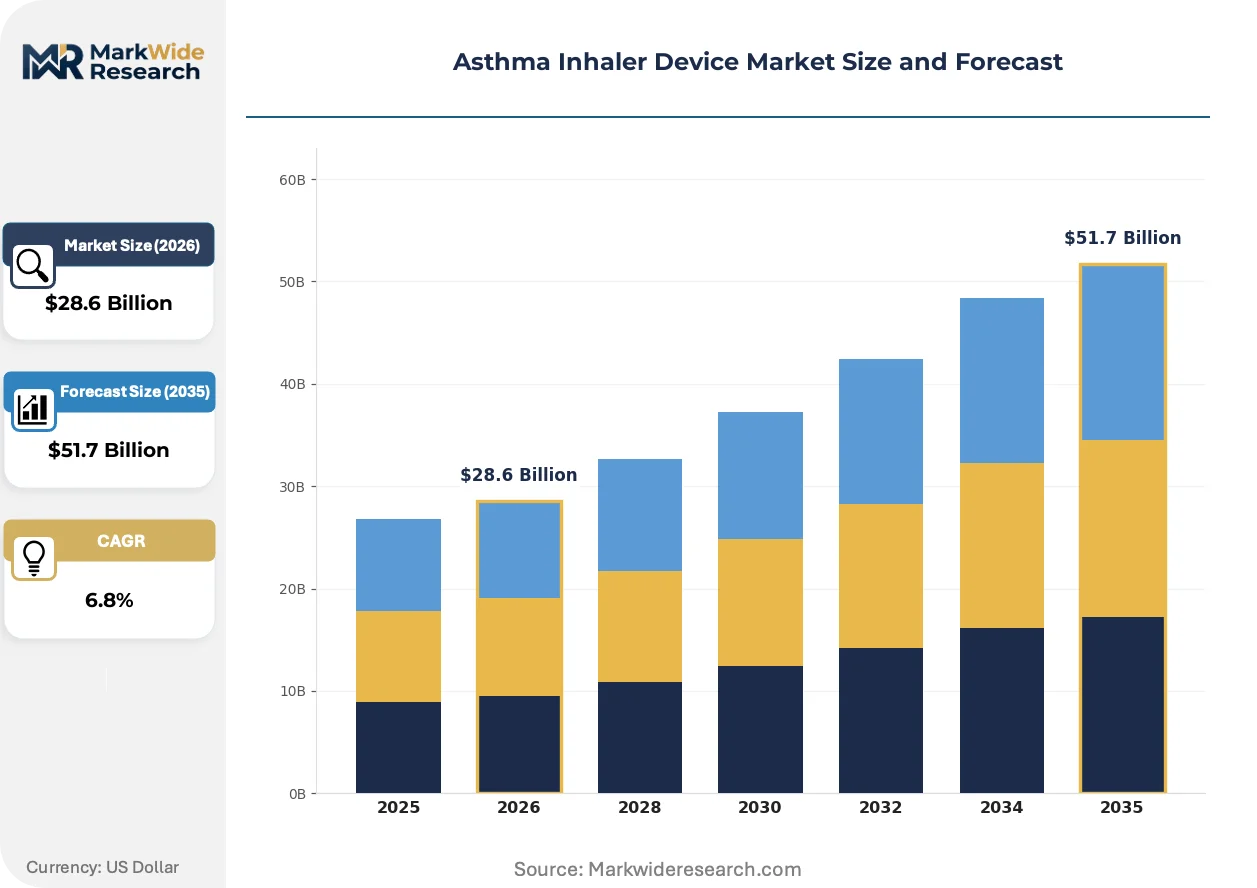
Market Dynamics
Hospital procurement consolidation is compressing vendor margins and forcing inhaler manufacturers to restructure their institutional sales organizations around integrated delivery network formularies rather than individual hospital accounts.
Growth Catalysts
- Pediatric respiratory clinic expansion:Rising childhood asthma prevalence is driving dedicated procurement programs across children's hospital networks, creating dedicated device volume pipelines.
- MDR framework for connected devices:The EMA's stricter clinical evidence thresholds for smart inhalers entering European markets is accelerating R&D investment in validated adherence-tracking platforms.
- FDA guidance on connected platforms:Updated human factors validation requirements under 21 CFR Part 4 are standardizing smart inhaler development protocols and reducing regulatory uncertainty for manufacturers.
Market Restraints
- Propellant supply concentration:Hydrofluoroalkane (HFA) propellant production concentrates among three chemical suppliers, exposing metered-dose inhaler manufacturers to input cost volatility and supply interruption risks.
- Reimbursement compression:United States payers are tightening criteria for non-adherence-linked respiratory therapies, threatening formulary exclusion for connected devices lacking proven outcomes data.
- Dry powder technical limitations:Breath-actuated delivery requires sufficient inspiratory flow rates, excluding severe asthma patients and limiting addressable patient populations in home care settings.
Strategic Opportunities
- Home care channel innovation:Direct-to-patient subscription models for smart inhaler resupply are bypassing traditional pharmacy distribution and capturing recurring revenue streams.
- ISO 20072 standardization:Unified oropharyngeal deposition testing protocols are reducing regulatory duplication costs and accelerating multi-market clearance timelines for new device platforms.
- India's respiratory disease burden:Underpenetrated metered-dose inhaler access in tier-2 and tier-3 cities presents volume expansion potential for cost-optimized device manufacturers.
Industry Challenges
- Human factors engineering talent scarcity:The specialized skill set required for FDA-mandated usability validation studies is concentrated among a limited pool of contract research organizations, creating recruitment bottlenecks.
- Legacy system integration complexity:Hospital electronic health record platforms use incompatible data standards, forcing smart inhaler manufacturers to maintain multiple connectivity protocols and raising deployment costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asthma Inhaler Device Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metered-Dose Inhalers, Dry Powder Inhalers, Nebulizers, Soft Mist Inhalers Delivery Mode: Oral Inhalation, Breath Actuated, Manual, Automated End User: Hospitals, Home Care, Clinics, Pharmacies Technology: Smart Inhalers, Digital Inhalers, Conventional Inhalers, Eco-Friendly Inhalers |
| Companies Covered | Teva Pharmaceutical Industries, Novartis, GlaxoSmithKline, Cipla, Chiesi Farmaceutici, Boehringer Ingelheim, Merck, PARI GmbH, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asthma Inhaler Device Market Emerging Trajectories
Connectivity features are migrating from premium positioning to baseline expectation as adherence data becomes central to payer reimbursement decisions and integrated care network performance metrics.
Smart inhaler sensor technology is migrating from Bluetooth-tethered smartphone apps to standalone cellular connectivity, eliminating patient smartphone dependency and expanding addressable populations to elderly users. Nursing homes and assisted living facilities are adopting these devices fastest, drawn by remote monitoring capabilities that reduce emergency department transfers. The shift is migrating from patient-managed adherence tools to facility-administered population health infrastructure, compressing hardware margins while expanding recurring software revenue.
The EMA's Medical Device Regulation is enforcing post-market clinical follow-up requirements for connected inhalers that exceed pre-MDR surveillance obligations, compelling manufacturers to maintain active patient registries. This industrial consequence has triggered restructuring of European commercial organizations around medical affairs teams capable of generating real-world evidence. Germany's statutory health insurance funds are most affected, conditioning reimbursement on demonstrated adherence improvements and forcing manufacturers to fund outcomes studies prior to listing.
Institutional buyers are consolidating respiratory device contracts at the integrated delivery network level, displacing individual hospital purchasing autonomy with centralized formulary committees. This concentration is compressing vendor sales cycles while extending contract durations, favoring manufacturers with established multi-hospital relationships. The United States exhibits the most visible shift, where Catholic health systems and for-profit chains are standardizing smart inhaler protocols across dozens of facilities simultaneously.
Asthma Inhaler Device Market Segmentation
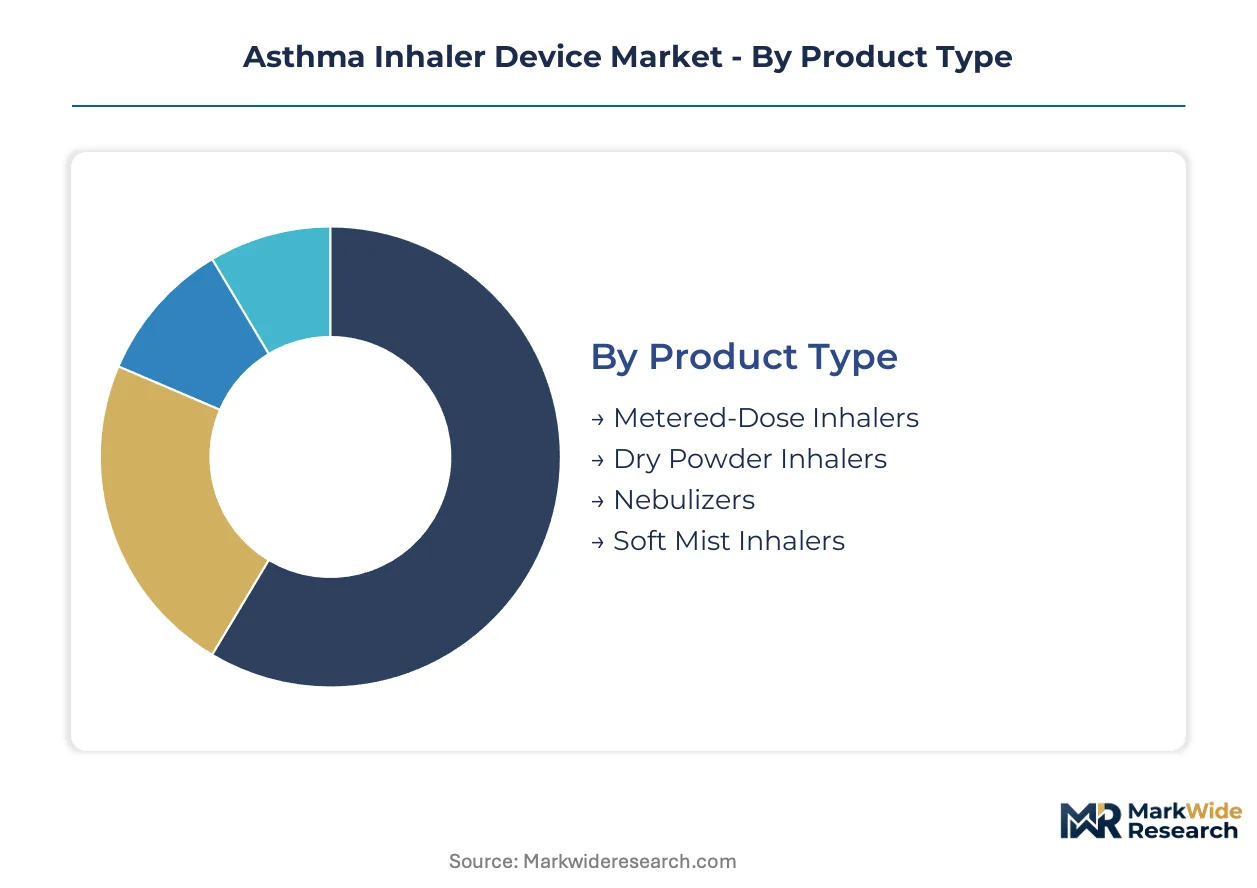
The asthma inhaler device market fragments across four distinct category axes, each reflecting divergent clinical requirements and procurement economics. Manufacturers must navigate these segment boundaries to optimize portfolio positioning across institutional and retail channels.
Product Type:
Mature pressurized systems anchor hospital procurement, while emerging breath-actuated platforms reshape home care economics.
- Metered-Dose Inhalers:Pressurized canister systems aerosolize medication through hydrofluoroalkane propellant, producing consistent particle sizes between one and five microns. United States integrated delivery networks standardize these devices across formulary committees due to dose reproducibility and compact form factors. Propellant supply concentration among three chemical suppliers exposes manufacturers to input cost volatility.
- Dry Powder Inhalers:Breath-actuated mechanisms eliminate coordination requirements by dispersing micronized drug from lactose carrier matrices. Home care settings in Germany favor these devices for elderly patients with limited hand-breath synchronization, though insufficient inspiratory flow rates exclude severe asthma populations. The EMA's MDR framework imposes stricter clinical evidence thresholds for connected variants entering European markets.
- Nebulizers:Compressor-driven or ultrasonic systems convert liquid medication into respirable mist for patients requiring high-dose bronchodilator delivery.
- Soft Mist Inhalers:Spring-mechanized devices generate slow-moving aerosol clouds independent of patient inspiratory effort, addressing coordination-challenged users.
Metered-dose inhalers handle the majority of throughput; dry powder inhalers are gaining share fastest in home care channels.
Delivery Mode:
Cost stratification separates premium automated systems from economy manual alternatives, with breath-actuated platforms occupying the mid-tier.
- Oral Inhalation:Standard mouthpiece delivery remains the default configuration across all device categories, with oropharyngeal deposition profiles governed by ISO 20072 testing protocols. United States pediatric respiratory clinics specify these systems for children aged five and above.
- Breath Actuated:Inspiratory flow triggers drug release automatically, eliminating the hand-lung coordination required by conventional pressurized systems. India's tier-2 and tier-3 cities present volume expansion potential for cost-optimized breath-actuated metered-dose alternatives.
- Manual:Patient-triggered activation demands precise timing between device actuation and inhalation onset.
- Automated:Electronic sensors coordinate drug release with detected inspiratory flow patterns.
Oral inhalation dominates prescription volumes; breath actuated is expanding most quickly as coordination-error reduction becomes a reimbursement criterion.
End User:
Customer type concentration shifts procurement influence from individual clinicians toward centralized supply chain functions.
- Hospitals:Acute care facilities prioritize device standardization across emergency departments and respiratory wards. Catholic health systems and for-profit chains in the United States are consolidating respiratory device contracts at the integrated delivery network level, displacing individual hospital purchasing autonomy.
- Home Care:Direct-to-patient subscription models for smart inhaler resupply bypass traditional pharmacy distribution. Nursing homes and assisted living facilities adopt cellular-connected devices fastest, drawn by remote monitoring capabilities that reduce emergency department transfers.
- Clinics:Outpatient respiratory specialists require portable devices for point-of-care demonstration and patient training.
- Pharmacies:Retail dispensaries manage recurring prescription fulfillment for chronic asthma maintenance therapy.
Hospitals concentrate the highest-value procurement decisions; home care is climbing the fastest on revenue contribution as subscription models mature.
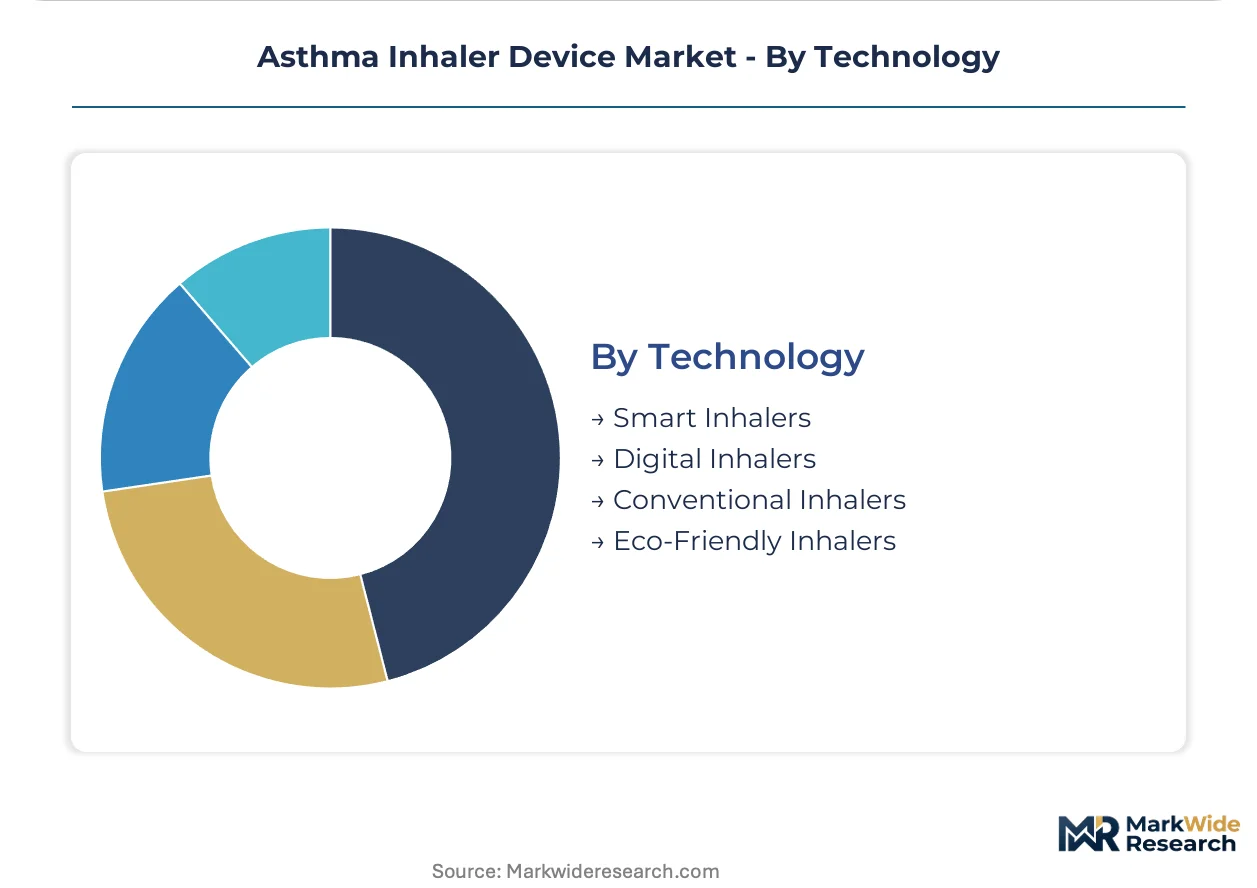
Technology:
Margin architecture separates premium connected platforms from commoditized conventional alternatives, with sustainability positioning emerging as a pricing differentiator.
- Smart Inhalers:Bluetooth or cellular-enabled sensors track actuation timing, technique quality, and adherence patterns, transmitting data to healthcare provider dashboards. Germany's statutory health insurance funds condition reimbursement on demonstrated adherence improvements, forcing manufacturers to fund outcomes studies prior to listing.
- Conventional Inhalers:Mechanical devices without connectivity features retain volume leadership in price-sensitive pharmacy channels. Teva Pharmaceutical Industries anchors this segment with cost-focused metered-dose alternatives.
- Digital Inhalers:Smartphone-tethered applications provide adherence feedback without embedded cellular modules.
- Eco-Friendly Inhalers:Propellant-free or low-global-warming-potential formulations address environmental compliance pressures from the EPA and EU F-Gas Regulation.
Conventional inhalers command the largest installed base; smart inhalers show the steepest expansion trajectory as payer reimbursement tightens around adherence documentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while cost-optimized manufacturing anchors India, creating a structural asymmetry that shapes procurement patterns across both markets. Germany enforces adherence-linked reimbursement that elevates smart inhaler premiums, whereas China's volume-driven respiratory disease burden rewards scale producers.
United States
Integrated delivery networks consolidate respiratory device contracts across Catholic health systems and for-profit chains, displacing individual hospital purchasing autonomy. The FDA's 21 CFR Part 4 framework mandates human factors validation for connected inhaler submissions, raising development barriers. Boston's medical technology corridor hosts multiple contract research organizations specializing in usability studies for smart inhaler platforms.
Germany
Statutory health insurance funds condition reimbursement on demonstrated adherence improvements, forcing manufacturers to fund outcomes studies prior to listing. The EMA's Medical Device Regulation enforces post-market clinical follow-up requirements that exceed pre-MDR surveillance obligations. Berlin and Munich anchor medical affairs teams generating real-world evidence for connected device registries.
India
Tier-2 and tier-3 cities present volume expansion potential for cost-optimized metered-dose inhaler manufacturers as respiratory disease burden outpaces device penetration. The Central Drugs Standard Control Organization regulates device-drug combinations under evolving quality standards. Mumbai and Ahmedabad concentrate generic pharmaceutical manufacturing capabilities serving domestic and export markets.
China
Domestic respiratory disease prevalence drives demand for nebulizer and soft mist platforms in hospital and home care channels. The National Medical Products Administration harmonizes combination product oversight with international standards. Shanghai and Suzhou host medical device manufacturing clusters producing cost-competitive inhaler components for regional distribution.
United Kingdom
National Health Service procurement frameworks prioritize device standardization across respiratory wards and community care settings. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit device regulations with retained EU MDR provisions. London's healthcare technology corridor attracts smart inhaler developers targeting adherence monitoring contracts.
Asthma Inhaler Device Market Vendor Landscape
Research-intensive multinationals and volume-focused generic specialists split the market across divergent margin architectures. The competitive structure concentrates around three strategic archetypes: connectivity-enabled platform developers commanding premium positioning, established pharmaceutical houses leveraging formulary relationships, and cost-optimized manufacturers capturing price-sensitive pharmacy channels. Dominant competitive moves include portfolio diversification into digital respiratory ecosystems and geographic expansion through localized manufacturing partnerships.
Within the research-intensive tier, GlaxoSmithKline and AstraZeneca occupy positions defined by digital respiratory portfolios and integrated care network penetration. Teva Pharmaceutical Industries anchors the generic segment with cost-focused alternatives. Among European-based developers, Chiesi Farmaceutici and Boehringer Ingelheim exemplify mid-cap specialists concentrating on breath-actuated and soft mist platforms. PARI GmbH represents the nebulizer equipment archetype with German engineering heritage.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries |
| Novartis |
| GlaxoSmithKline |
| Cipla |
| Chiesi Farmaceutici |
| Boehringer Ingelheim |
| Merck |
| PARI GmbH |
| AstraZeneca |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Singapore maritime corridor's container rate volatility transmits directly into metered-dose inhaler landed costs, amplifying price spreads between HFA propellant-linked pressurized systems and propellant-free dry powder alternatives while forcing manufacturers to absorb logistics swings or pass them to formulary committees.
Pricing Analysis
The customization-premium spread separates connected inhaler platforms with cellular telemetry from conventional mechanical devices, with smart inhalers commanding recurring SaaS-tiered subscriptions against per-unit transactional pricing for standard metered-dose alternatives. Price differentiation rests on FDA 21 CFR Part 4 certification investment and adherence data integration depth, with Germany's statutory insurers least sensitive due to outcomes-linked reimbursement and India's tier-3 pharmacy channels most exposed. Cost compression in conventional inhalers is intensifying because Teva Pharmaceutical Industries and Cipla anchor generic price floors, eroding margin buffers for mid-tier breath-actuated entrants.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for plastic molding components and electronic sensor modules. Manufacturing concentrates in China, Germany, and India, with HFA propellant feedstock drawing from three specialized chemical suppliers. Raw material dependencies span hydrofluoroalkane propellants, stainless steel canisters, and lactose carrier matrices. Distribution runs through integrated delivery network formulary committees in the United States and hospital procurement frameworks in Germany, displacing individual account autonomy with centralized contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
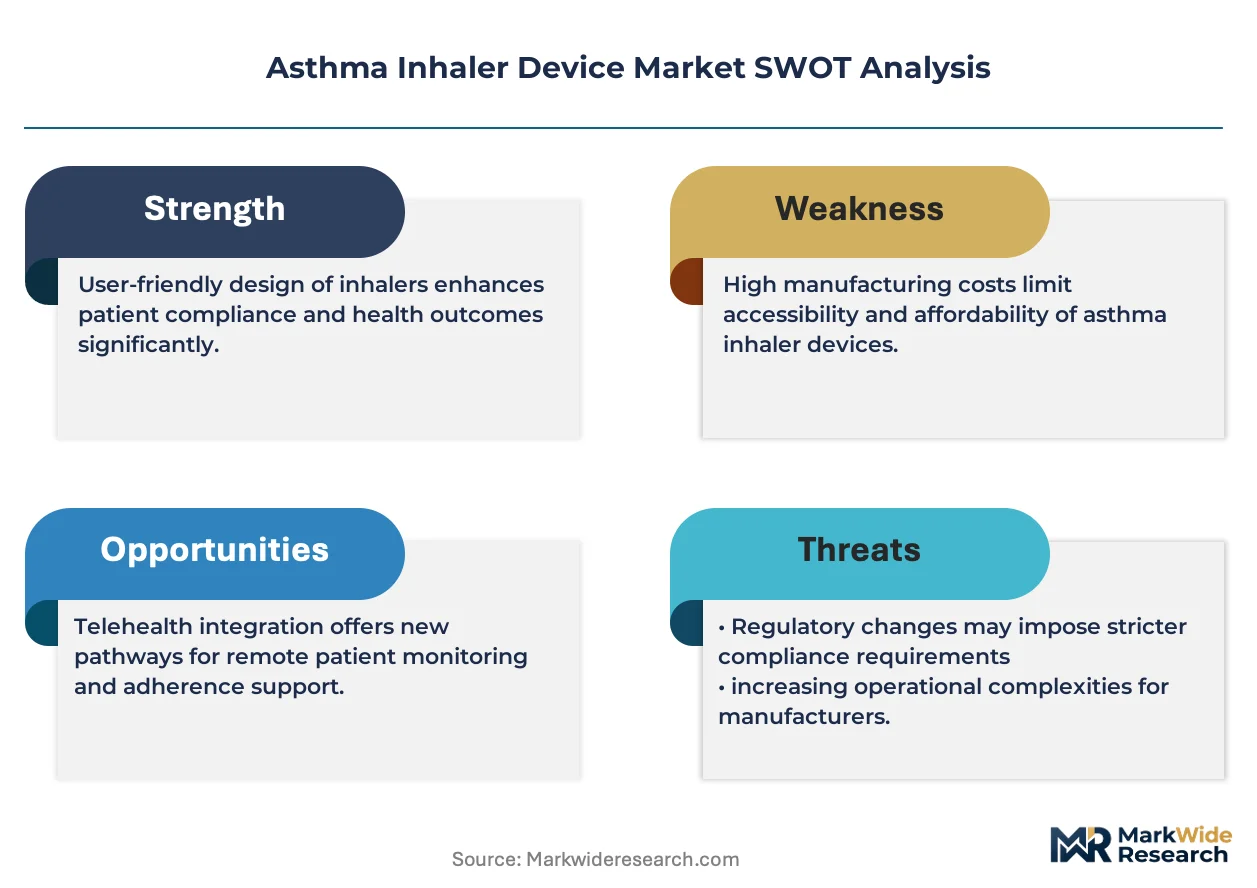
Incumbents face substitution pressure from digital respiratory platforms that bypass hardware margins entirely through software-only adherence monitoring, threatening device manufacturers with disintermediation if connectivity features fail to justify premium positioning.
For Market Incumbents: Build regulatory data moats through active patient registries that satisfy EMA MDR post-market surveillance obligations and preempt formulary exclusion. Anchor backward integration into HFA propellant supply through long-term offtake agreements with the three dominant chemical suppliers, mitigating input cost volatility that compresses metered-dose margins. Prioritize ISO 20072 deposition testing investment to accelerate multi-market clearance timelines and defend against emerging breath-actuated challengers.
For New Entrants and Emerging Players: Establish a beachhead in India's tier-2 and tier-3 cities where metered-dose inhaler penetration lags respiratory disease prevalence and price sensitivity favors cost-optimized alternatives. Target nursing home and assisted living facility channels with cellular-connected devices that eliminate smartphone dependency for elderly populations. Deploy direct-to-patient subscription models that bypass pharmacy distribution markups and capture recurring revenue streams.
For Investors and Strategic Acquirers: Connected device specialists with validated adherence-tracking platforms and established hospital system partnerships represent the most defensible acquisition archetype as payer reimbursement tightens around outcomes documentation. Long-term viability hinges on regulatory data generation capabilities that sustain formulary positioning across the analysis window. Watch FDA guidance evolution on human factors validation as the inflection signal for R&D cost escalation and competitive consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Cellular Connectivity Migration | Standalone telemetry eliminates smartphone dependency and expands elderly addressable populations. |
| EMA MDR Compliance Investment | Post-market clinical follow-up requirements force restructuring of European commercial organizations. |
| Integrated Delivery Network Partnership | Catholic health systems and for-profit chains standardize protocols across dozens of facilities simultaneously. |
| HFA Propellant Supply Security | Long-term offtake agreements with concentrated chemical suppliers mitigate input cost volatility. |
| Direct-to-Patient Subscription Launch | Bypassing pharmacy distribution captures recurring revenue and reduces channel margin leakage. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with respiratory device executives, hospital procurement managers, formulary directors, and payer access specialists; and secondary validation against FDA 510(k) filings, EMA MDR submissions, hospital GPO contracts, and ISO 20072 testing protocols. Bottom-up triangulation across device shipment estimates and top-down reconciliation against pharmaceutical manufacturer disclosures anchored volume and value outputs.
Forecast inputs spanned product type segmentation across metered-dose, dry powder, nebulizer, and soft mist platforms; technology tiers separating connected from conventional devices; and end-user channels including hospitals, home care, clinics, and pharmacies. CAGRs were derived from regression analysis of historical procurement patterns and projected formulary adoption curves, incorporating HFA propellant supply constraints and MDR regulatory compliance timelines as industry-specific modifiers across the projection horizon.
Sensitivities concentrate around FDA guidance evolution on connected platform validation, EMA MDR enforcement intensity, and integrated delivery network consolidation pace. Forecasts reflect documented assumptions regarding adherence data reimbursement traction and cellular connectivity adoption in elderly populations. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Airway Stent/Lung Stent Market
Medical Devices
Cannula Market
Medical Devices
Global Intravenous (IV) Equipment Market
Medical Devices
Electroencephalography Devices Market
Medical Devices
Retinal Surgery Devices Market
Medical Devices
Tissue Sectioning Market
Medical Devices
United States Stair Lift Market
Medical Devices
Implantable Pacemaker Market
Medical Devices
Global Soft Tissue Allografts Market
Medical Devices
Intrapartum Monitors Market
Medical Devices
Global Radiofrequency Ablation Devices Market
Medical Devices
Baby Ear Thermometer Market
Medical Devices
Fluid and Blood Warmer Market
Medical Devices
Feeding Tubes Market
Medical Devices
Snoring Control Devices Market
Medical Devices
Sacroiliac Joint Fusion Market