
 Insulin Delivery Devices (Idd) Market | 2026-2036
Insulin Delivery Devices (Idd) Market Size, Share, and Industry Trends Forecast 2026-2036
Insulin Delivery Devices (Idd) Market Foresight
Closed-loop automated delivery tier is collapsing the boundary between glucose sensing and insulin administration, forcing incumbents to recalibrate engineering roadmaps. Medtronic leverages its integrated ecosystem of pumps and sensors to sustain installed-base loyalty across multiple continents. Novo Nordisk A/S anchors its position through deep partnerships with pen and pump manufacturers, while Insulet Corporation differentiates via tubeless patch pump architecture that eliminates daily infusion set changes.
Insulin delivery devices constitute electromechanical and disposable systems engineered to administer controlled doses of insulin with subcutaneous precision, typically operating within 0.025-to-35-unit dosing ranges and integrating Bluetooth or near-field communication for data logging. Their commercial purpose centers on reducing glycemic variability while minimizing patient burden through programmable basal rates and bolus calculators. Insulin pumps and smart devices capture the fastest expansion as algorithm-driven closed-loop systems migrate from type 1 toward type 2 diabetes populations, while jet injectors occupy a narrow niche constrained by patient discomfort and reimbursement gaps. Homecare settings now generate the dominant volume flow as remote patient monitoring platforms validate outpatient glycemic control metrics to payers.
FDA premarket notification pathways and EMA Medical Device Regulation conformity assessments determine market access timelines for connected delivery systems, with both agencies intensifying cybersecurity validation requirements for Bluetooth-enabled devices. ISO 15197 and IEC 62304 standards govern glucose meter accuracy and software lifecycle processes, creating compliance thresholds that filter out undercapitalized entrants. Stakeholders must monitor evolving interoperability mandates that could force open-protocol architectures and erode proprietary ecosystem lock-in.
Market Dynamics
Closed-loop algorithm integration is collapsing the traditional separation between glucose monitoring and insulin administration, forcing device architectures toward unified electromechanical platforms that demand simultaneous hardware and software validation.
Growth Catalysts
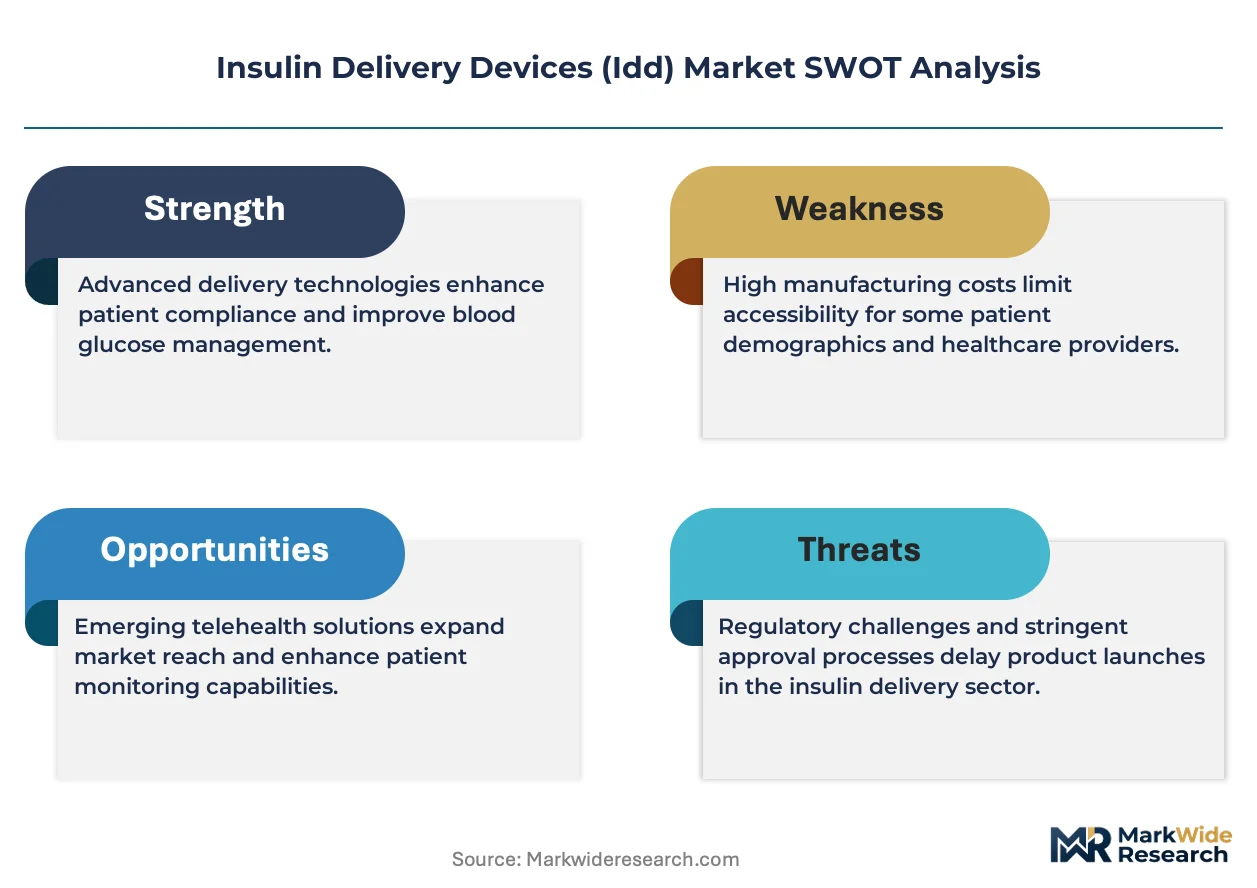
- Automated insulin delivery algorithms:FDA breakthrough device designation pathways are compressing approval timelines for hybrid closed-loop systems that adjust basal rates in real-time based on continuous glucose monitor inputs.
- Homecare reimbursement expansion:Germany's G-BA has extended DiGA (Digital Health Applications) coverage to connected insulin pens, validating remote glycemic data for outpatient diabetes management.
- Type 2 diabetes pump adoption:Simplified user interfaces and reduced training requirements are extending pump eligibility beyond traditional type 1 populations into insulin-intensive type 2 patients previously managed on multiple daily injections.
Market Restraints
- Disposable consumable costs:Infusion sets, reservoirs, and sensor adhesives create recurring out-of-pocket burdens that exceed $300 monthly for uninsured or underinsured patients in the United States.
- Single-source sensor dependency:Concentration of continuous glucose monitor manufacturing in specific semiconductor fabrication clusters creates vulnerability to foundry capacity constraints and export control disruptions.
- Jet injector reimbursement gaps:Medicare and most commercial payers classify needle-free insulin delivery as experimental, denying coverage despite comparable pharmacokinetic profiles to subcutaneous injection.
Strategic Opportunities
- Biosimilar insulin convergence:Falling prices for insulin glargine and lispro biosimilars in the United States are freeing patient budgets for device upgrades, particularly smart pens with dose logging.
- Interoperability mandates:FDA guidance on integrated continuous glucose monitor and pump communication standards is creating openings for modular device ecosystems that bypass proprietary lock-in.
- Retail pharmacy distribution:CVS and Walgreens are building in-store diabetes device fitting services, creating direct-to-patient channels that bypass traditional durable medical equipment suppliers.
Industry Challenges
- Software validation timelines:IEC 62304 medical device software lifecycle compliance for algorithm updates requires 12-18 month recertification cycles that lag behind agile development velocities.
- Cybersecurity workforce scarcity:Bluetooth-enabled pump and pen architectures demand specialized embedded security engineers, a talent pool concentrated in aerospace and automotive sectors with higher compensation benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulin Delivery Devices (Idd) Market |
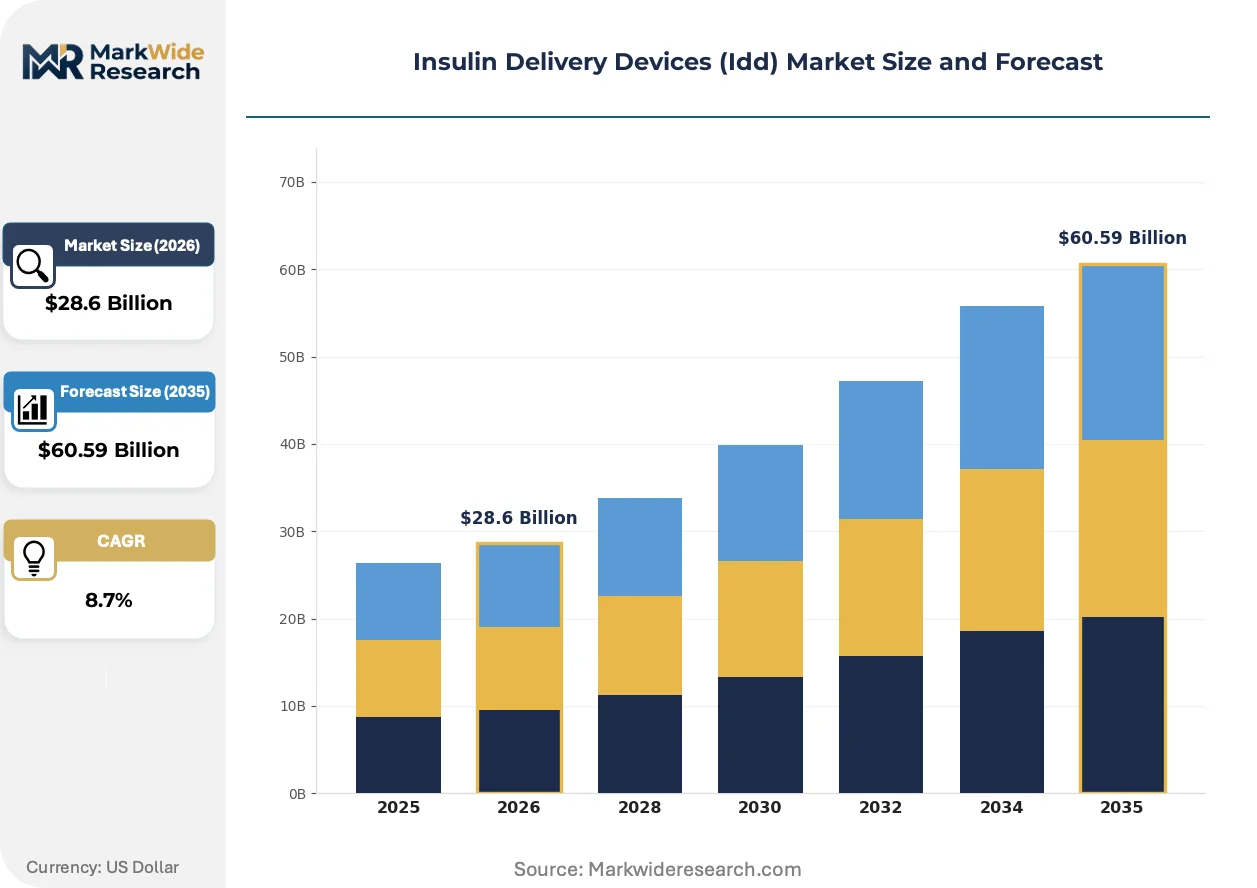
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Pens, Insulin Pumps, Jet Injectors, Smart Devices End User: Hospitals, Homecare Settings, Clinics, Diabetes Care Centers Technology: Continuous Glucose Monitoring, Smart Insulin Patches, Wearable Injectors, Automated Delivery Systems Administration Mode: Subcutaneous, Intravenous, Inhalation, Transdermal |
| Companies Covered | Medtronic, Novo Nordisk A/S, Insulet Corporation, Tandem Diabetes Care, Inc., Embecta Corp., Sanofi, Eli Lilly and Company, Ypsomed AG, F. Hoffmann-La Roche Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulin Delivery Devices (Idd) Market Shifts & Advancements
Algorithm-driven personalization is replacing fixed-dose protocols across insulin delivery modalities, compressing the gap between patient-specific glycemic targets and automated dose adjustment capabilities.
Tubeless patch pump form factors are displacing traditional tethered pump designs that require external tubing and daily infusion set changes. Adolescent and active adult type 1 diabetes patients are adopting these wearable devices at accelerated rates, drawn to waterproofing and discrete under-clothing placement. This shift is compressing market share for conventional pump architectures that dominate installed bases but impose higher daily management burdens.
EMA Medical Device Regulation Annex XVI expansions are capturing software-only glucose prediction applications under conformity assessment requirements previously limited to physical devices. Manufacturers must now compile clinical evidence for algorithm performance across diverse glycemic phenotypes. Patch pump and smart pen categories face the steepest compliance cost increases as they integrate predictive dosing suggestions.
Subscription-based device access models are replacing upfront capital purchases in United States commercial channels. Patients receive pump hardware, sensors, and unlimited supplies for fixed monthly fees, transferring obsolescence risk to manufacturers. This restructuring is most visible in employer-sponsored insurance plans where pharmacy benefit managers bundle diabetes device spending with insulin procurement.
Insulin Delivery Devices (Idd) Market Segmentation
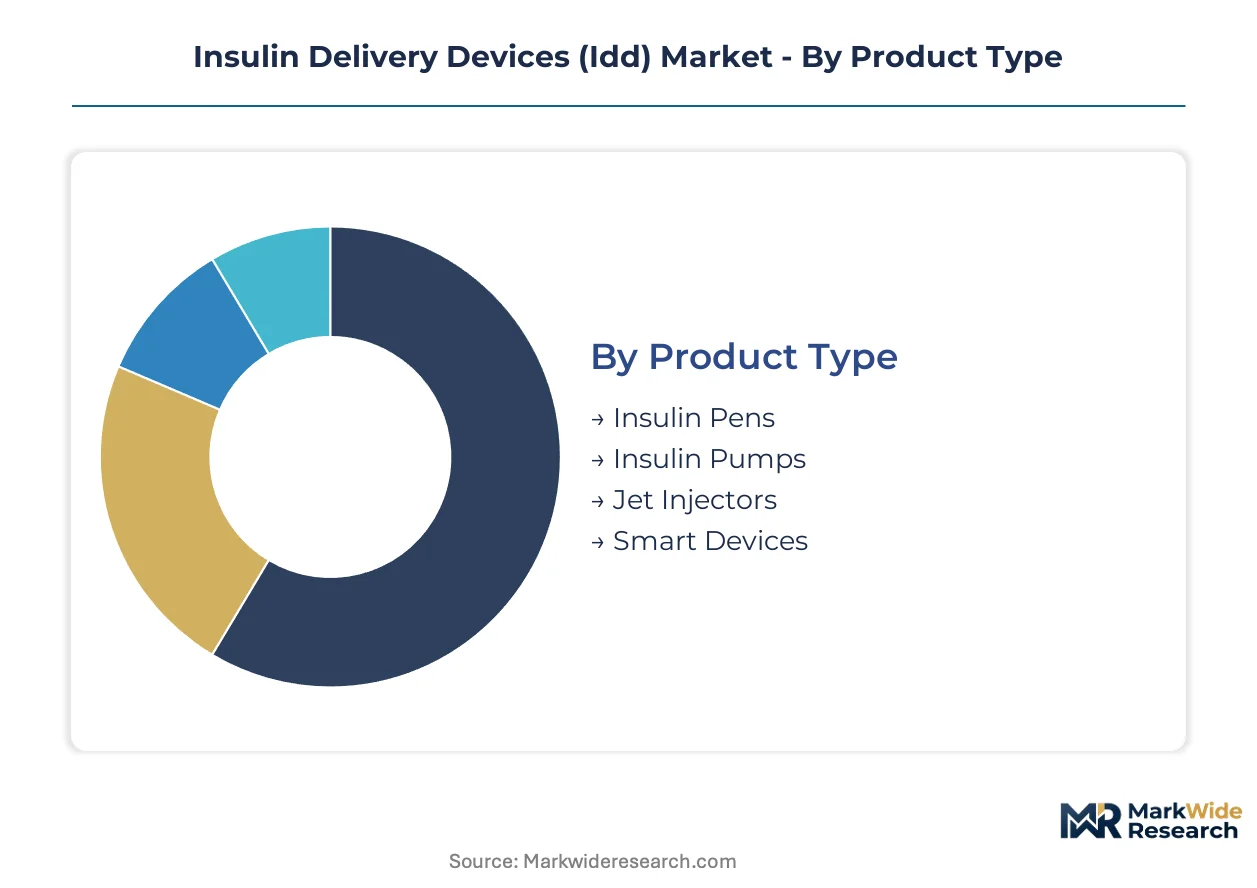
Segmentation in insulin delivery devices reveals divergent technology maturity curves and reimbursement pathways. Product architecture choices determine whether manufacturers compete on disposable volume or capital equipment lock-in. End-user concentration shapes regulatory validation priorities and distribution channel economics.
Product Type:
Domestic manufacturing concentration varies sharply across these categories, with pump assembly clustered in medical device hubs while pen production spreads across pharmaceutical supply chains.
- Insulin Pens:Disposable and reusable electromechanical injectors delivering 0.5-to-80-unit doses with dial-based dose selection. Demand concentrates in Germany and Japan where pharmacy reimbursement favors pen therapy over pump capital expenditure. The category benefits from biosimilar insulin price compression freeing patient budgets for dose-logging features.
- Insulin Pumps:Electromechanical infusion systems operating 0.025-to-35-unit basal ranges with programmable profiles. Export-led growth dominates as US and European manufacturers supply Middle Eastern and Asia-Pacific markets lacking domestic pump fabrication. FDA breakthrough designations for hybrid closed-loop variants accelerate patient migration from multiple daily injections.
- Jet Injectors:Needle-free pressure-driven devices forcing insulin through skin via high-velocity liquid streams. Medicare classification as experimental limits US adoption despite comparable pharmacokinetics.
- Smart Devices:Bluetooth-enabled pens and pumps with integrated dose logging and smartphone connectivity. Germany's DiGA coverage validates remote data for outpatient management.
Insulin pens hold the largest share; momentum sits with smart devices.
End User:
Cost tier stratification separates capital-intensive hospital procurement from recurring homecare consumable models.
- Hospitals:Acute care settings managing diabetic ketoacidosis and perioperative glycemic control with intravenous insulin protocols. Tethered pump dominance persists for inpatient critical care.
- Homecare Settings:Patient-managed outpatient environments where patch pumps and smart pens reduce clinical visit frequency. Volume expansion accelerates as remote monitoring platforms validate glycemic metrics to US and German payers. This segment captures the steepest expansion trajectory as algorithm-driven systems migrate toward type 2 populations.
- Clinics:Outpatient facilities providing device training and pump initiation services. Reimbursement for clinical time constrains penetration in markets without diabetes educator coverage.
- Diabetes Care Centers:Specialized institutions integrating continuous glucose monitor interpretation with pump optimization. Concentrated in urban clusters with endocrinology specialist density.
Homecare settings dominate volume; diabetes care centers concentrate value per patient.
Technology:
Application intensity varies from diagnostic adjunct to closed-loop therapeutic intervention.
- Continuous Glucose Monitoring:Subcutaneous sensor systems transmitting interstitial glucose data every 1-to-5 minutes. Semiconductor fabrication concentration in specific foundry clusters creates supply vulnerability.
- Smart Insulin Patches:Wearable single-use devices combining glucose sensing with micro-dose insulin delivery. Waterproofing and discrete placement drive adolescent and active adult adoption.
- Wearable Injectors:On-body bolus delivery systems for large-volume insulin doses. Patch pump architecture eliminates daily infusion set changes that burden conventional pump users.
- Automated Delivery Systems:Algorithm-driven closed-loop platforms adjusting basal rates in real-time based on sensor inputs. FDA and EMA pathways compress approval timelines for hybrid configurations.
Continuous glucose monitoring anchors installed base expansion; automated delivery systems command premium positioning.
Administration Mode:
Maturity differentiation separates decades-established subcutaneous protocols from emerging transdermal alternatives.
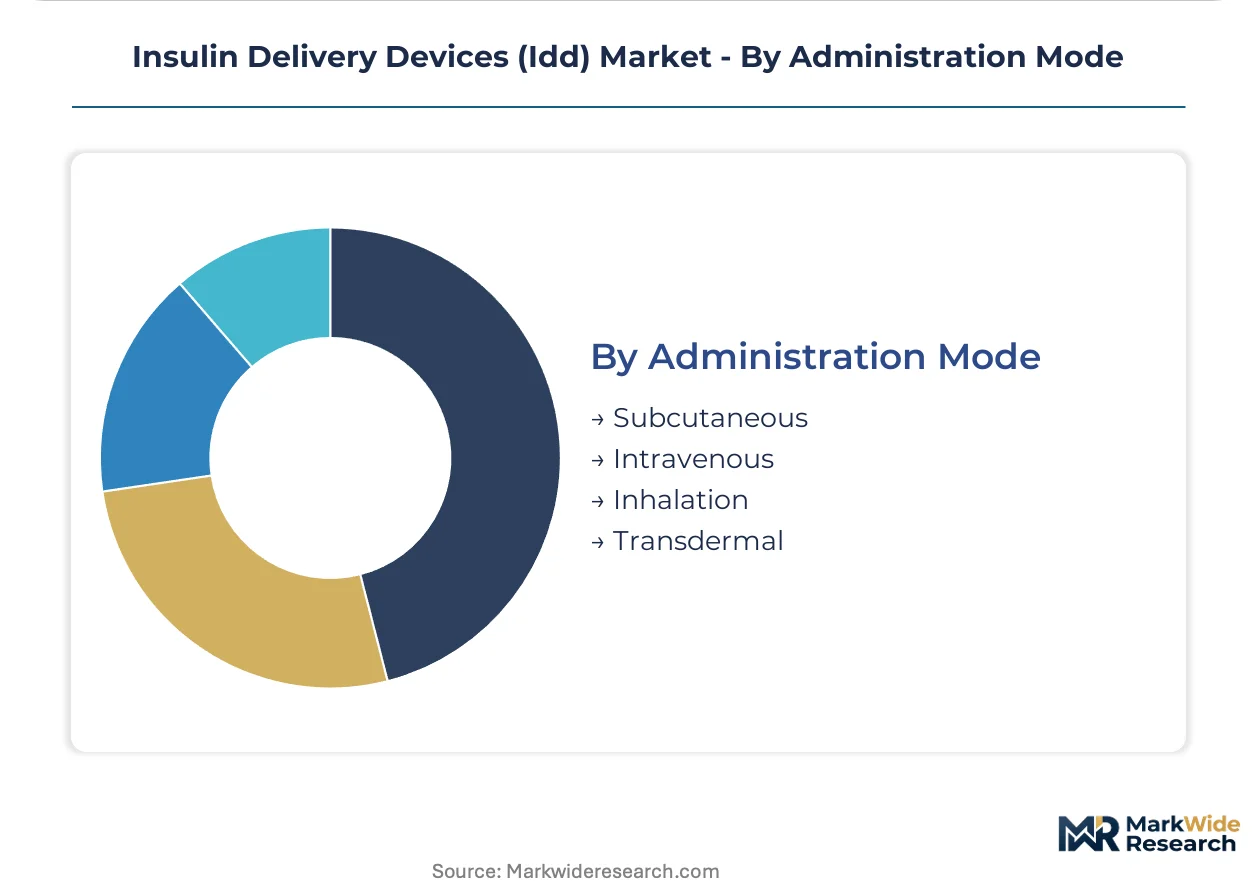
- Subcutaneous:Needle-based delivery into adipose tissue via pen, pump, or syringe. Dominates all geographies with mature reimbursement infrastructure.
- Intravenous:Hospital-restricted infusion for acute glycemic emergencies. Limited to institutional settings with intensive monitoring capability.
- Inhalation:Pulmonary insulin delivery bypassing injection burden. Previous commercial failures constrain prescriber confidence and payer coverage.
- Transdermal:Passive or active transport across skin barriers without needle penetration. Jet injector discomfort and pharmacokinetic variability restrict clinical uptake.
Subcutaneous administration retains volume leadership; transdermal approaches seek breakthrough validation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device assembly clusters concentrate in medical technology corridors across three continents, with regulatory validation pathways diverging sharply between FDA predicate routes and EMA MDR conformity assessments. Foundry capacity for sensor semiconductors localizes in East Asian fabrication zones, creating cross-border dependencies for finished device manufacturers.
United States
Employer-sponsored insurance plans drive subscription-based device access models, transferring hardware obsolescence risk to manufacturers. FDA breakthrough device designations compress approval timelines for hybrid closed-loop systems. The Minneapolis medical device corridor anchors pump and sensor ecosystem integration.
Germany
Pharmacy reimbursement frameworks favor pen therapy capital expenditure over pump hardware, accelerating smart pen adoption with dose-logging capabilities. The G-BA's DiGA coverage extension validates remote glycemic data for outpatient management. The Baden-Württemberg precision engineering cluster supplies electromechanical pen components.
Japan
Aging demographics expand insulin-intensive type 2 populations eligible for simplified pump interfaces. PMDA consultations align software lifecycle validation with IEC 62304 standards. The Kanagawa medical device manufacturing zone concentrates disposable pen needle production.
China
Domestic pump fabrication scales to reduce import dependency for algorithm-driven delivery systems. NMPA innovation pathway reviews accelerate local closed-loop product registrations. The Suzhou industrial park hosts multinational joint ventures for sensor-enabled pen assembly.
Switzerland
High-value diabetes care center density concentrates pump optimization services in urban German-speaking cantons. Swissmedic's streamlined software update protocols reduce recertification lag for algorithm improvements. The Basel pharmaceutical corridor anchors pen and disposable supply chain integration.
Insulin Delivery Devices (Idd) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated ecosystem providers commanding premium positioning against modular component specialists. The market structures around three tiers: full-stack automated delivery platforms, pen-focused pharmaceutical alliances, and disposable-optimized patch pump architectures. Dominant competitive moves include strategic partnerships between insulin manufacturers and device fabricators, plus vertical integration into sensor semiconductor sourcing.
Within the integrated ecosystem tier, Medtronic anchors multi-continental installed base retention through combined pump and continuous glucose monitor offerings. Novo Nordisk A/S occupies a partnership-dependent position, leveraging pharmaceutical scale to secure pen and pump co-development arrangements. Insulet Corporation exemplifies the tubeless architecture specialist archetype, eliminating daily infusion set changes through patch pump form factors.
| Leading Market Players |
|---|
| Medtronic |
| Novo Nordisk A/S |
| Insulet Corporation |
| Tandem Diabetes Care, Inc. |
| Embecta Corp. |
| Sanofi |
| Eli Lilly and Company |
| Ypsomed AG |
| F. Hoffmann-La Roche Ltd. |
| Others |
Supply & Pricing Matrix
Subscription-based capacity reservation contracts lock in sensor semiconductor allocations for pump manufacturers while capping monthly patient out-of-pocket exposure, binding supply security to price predictability across United States employer-sponsored plans and German DiGA reimbursement frameworks.
Pricing Analysis
FDA breakthrough device designation dictates the pricing tier structure for automated delivery systems, separating premium hybrid closed-loop configurations from standard pump architectures and economy pen-based alternatives. Price differentiation rests on algorithm sophistication and CGM integration depth, with certification tier (FDA 510(k) vs. De Novo pathway) amplifying brand positioning. Cost compression in the economy pen segment is intensifying because biosimilar insulin price erosion redirects patient budgets toward dose-logging features. Uninsured and underinsured populations exhibit highest price sensitivity to recurring consumable burdens, while commercially insured patients through pharmacy benefit managers show lowest sensitivity under bundled subscription models.
Supply Chain Analysis
Port congestion on Asia-Pacific trade lanes elevates inbound logistics costs for CGM sensor substrates and electromechanical pump components sourced from Taiwanese and South Korean foundries. Device assembly concentrates in United States medical technology corridors, German precision engineering clusters, and Japanese disposable manufacturing zones, drawing from semiconductor wafers, medical-grade polymers, and adhesive biocompatibility coatings. Single-source dependency on specific East Asian fabrication facilities creates vulnerability to export control disruptions. Distribution runs through durable medical equipment suppliers, retail pharmacy fitting services, and direct-to-patient subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from algorithm-driven software-only glucose management applications that bypass hardware procurement entirely, threatening installed-base retention across traditional pump architectures.
For Market Incumbents: Fortify ecosystem lock-in through backward integration into sensor semiconductor sourcing and exclusive hospital system partnerships that constrain competitor access to pump initiation sites. Algorithm-driven software-only competitors threaten hardware attach rates, making captive supply of CGM substrates a critical defensive lever. For New Entrants and Emerging Players: Anchor in the type 2 diabetes pump eligibility expansion, where simplified user interfaces and reduced training requirements open white-space among insulin-intensive patients previously managed on multiple daily injections. Retail pharmacy fitting services at CVS and Walgreens offer direct-to-patient channel access that bypasses entrenched durable medical equipment distribution. For Investors and Strategic Acquirers: Modular component specialists with FDA-cleared interoperability protocols represent the most attractive acquisition archetype, positioned to benefit from open-standard mandates eroding proprietary ecosystem control. Long-term viability hinges on algorithm validation cycles compressing toward agile development velocities. Watch for IEC 62304 recertification timeline reductions as the signal indicating regulatory adaptation to software-native competitors.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates market access for hybrid closed-loop systems competing against multiple daily injection protocols. |
| CE Marking Pathway under MDR Annex XVI | Captures software-only glucose prediction applications under conformity assessment requirements previously limited to physical devices. |
| Hospital System Partnership | Secures pump initiation sites and diabetes educator training capacity that constrain competitor patient onboarding. |
| Software Companion Development | Enables dose logging and remote monitoring integration that validates glycemic metrics to German G-BA and US payers. |
| Reimbursement Strategy | Aligns device procurement with pharmacy benefit manager bundling and DiGA coverage extension for connected pens. |
Research Methodology
A spread of perspectives from endocrinology specialists, biomedical engineers, hospital purchasing committees, and pharmacy benefit managers converged on the working assumptions driving segmentation splits and adoption trajectory estimates. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) and De Novo filings, EMA MDR submission databases, CMS Medicare reimbursement schedules, and German G-BA DiGA registry entries. Bottom-up patient population modeling and top-down device shipment triangulation anchored volume estimates.
Segmentation dimensions modeled span product architecture (pens, pumps, patch pumps, smart devices), end-user setting (hospital, homecare, clinic, diabetes care center), and technology integration level (standalone, CGM-integrated, closed-loop automated). CAGRs were derived from fitted adoption curves calibrated to reimbursement expansion timelines and regulatory approval velocity across the projection horizon. Algorithm validation cycle times and semiconductor foundry capacity constraints fed into supply-side capacity assumptions.
Material uncertainties — regulatory pathway delays, cybersecurity incident-driven certification suspensions, and foundry export control disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions about reimbursement framework stability and interoperability mandate implementation pace. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Self Care Medical Devices Market
Medical Devices
Global Stabilometric Platform Market
Medical Devices
Minimally Invasive Neurosurgical Devices Market
Medical Devices
Urology Guidewires Market
Medical Devices
France Ophthalmic Devices Market
Medical Devices
Latin America Biomedical Sensors Market
Medical Devices
Laser Therapy Devices Market
Medical Devices
Global Radial Artery Compression Devices Market
Medical Devices
Sperm Separation Systems Market
Medical Devices
Hysterectomy Devices Market
Medical Devices
PPG Biosensors Market
Medical Devices
Capnography Devices Market
Medical Devices
France Minimally Invasive Surgery Devices Market
Medical Devices
Peak Flow Meters Market
Medical Devices
Digital Magnifiers Market
Medical Devices
Global Smart Wearable Healthcare Devices Market