
 Tattoo Removal Lasers Market | 2026-2036
Tattoo Removal Lasers Market Size, Share, and Industry Trends Forecast 2026-2036
Tattoo Removal Lasers Market Outlook
The capital-intensity divergence between picosecond platform developers and legacy nanosecond manufacturers is rotating competitive advantage toward firms with in-house crystal growth and beam-delivery engineering. Cynosure leverages its integrated picosecond supply chain to sustain premium positioning across North American dermatology networks. Quanta System anchors European demand through specialized Q-switched and fractional laser portfolios tailored to regional pigmentation profiles. Lutronic competes in Asian markets with compact, multi-wavelength platforms optimized for smaller clinic footprints.
Tattoo removal lasers are medical-grade photonic devices that deliver ultrashort pulses of specific wavelengths to fragment dermal ink particles through selective photothermolysis, with pulse durations ranging from nanosecond to picosecond scales to accommodate varying ink compositions and skin types. These systems serve the commercial purpose of non-invasive pigment clearance across cosmetic, dermatological, and wellness settings. Q-Switched Laser technology dominates installed base volumes due to decades of clinical validation and lower capital thresholds, while picosecond platforms command premium positioning among high-volume practices seeking faster clearance protocols. Cosmetic Clinics represent the largest application channel by unit deployment, though Dermatology Centers capture disproportionate margin pools through physician-supervised protocols and combination therapy bundling.
FDA 510(k) premarket notification requirements govern device commercialization in the United States, while the EU Medical Device Regulation mandates notified body conformity assessment for CE marking across European markets. ISO 13485 quality management standards and IEC 60601-1 electrical safety frameworks shape manufacturing compliance burdens and OEM partnership eligibility. Stakeholders must monitor evolving state-level scope-of-practice regulations that determine whether non-physician operators can deploy these devices independently.
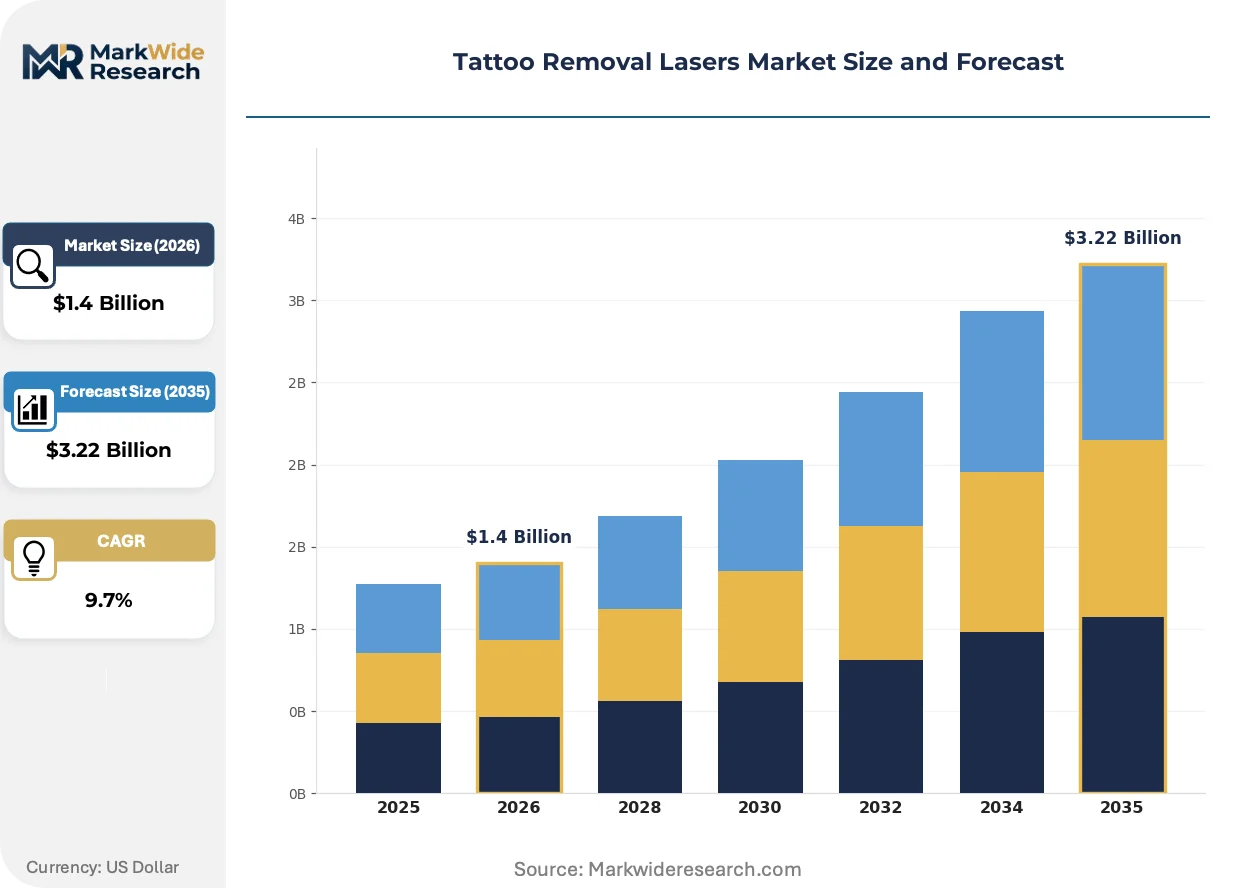
Market Dynamics
Picosecond pulse technology is compressing treatment protocols and forcing capital upgrades across installed bases, redistributing margin pools toward manufacturers with captive laser crystal supply chains.
Growth Catalysts
- FDA 510(k) Pathway Clarity:Streamlined premarket notification procedures accelerate commercialization timelines for novel wavelength platforms in United States dermatology networks.
- Dermatology Center Expansion:Physician-supervised clinics in metropolitan United States markets drive premium device procurement through bundled aesthetic service offerings.
- Picosecond Platform Adoption:Faster ink clearance protocols attract high-volume practices seeking competitive differentiation through reduced session counts.
Market Restraints
- Neodymium-Doped Yttrium Aluminum Garnet Crystal Supply:Concentrated sourcing from specialized optical foundries creates input cost volatility and lead time uncertainty for solid-state laser manufacturers.
- Technical Limitation on Fluorescent Inks:Titanium dioxide and UV-reactive pigments resist photothermal fragmentation across current wavelength portfolios, leaving residual clearance gaps.
- EU Medical Device Regulation Conformity Costs:Notified body assessment fees and clinical documentation requirements impose disproportionate burdens on smaller OEM entrants.
Strategic Opportunities
- Underpenetrated Secondary United States Markets:Non-metropolitan cosmetic clinics in Texas, Florida, and Arizona operate legacy Q-switched systems ripe for upgrade cycles.
- Combination Therapy Protocols:Integration of picosecond lasers with fractional resurfacing and topical delivery systems creates service bundling potential in wellness channels.
- State-Level Scope-of-Practice Liberalization:Expanding independent operator permissions for non-physician technicians in Nevada and Arizona broadens addressable user bases.
Industry Challenges
- Laser Safety Officer Certification Bottlenecks:Qualified training programs for ANSI Z136.3 compliance lag device deployment rates, constraining operational scaling.
- Legacy Q-Switched Integration Complexity:Retrofitting existing treatment rooms for picosecond power and cooling requirements demands substantial facility capex.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tattoo Removal Lasers Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.22 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Pulsed Dye Laser, Q-Switched Laser, Fractional Laser, RGB Laser Application: Cosmetic Clinics, Dermatology Centers, Spa & Wellness, Home Use End User: Individuals, Practitioners, Dermatologists, Medical Centers Distribution Channel: Online Retail, Medical Distributors, Direct Sales, Others |
| Companies Covered | Cynosure, Lumenis, Quanta System, Candela, Cutera, Lutronic, Removery, PiQo4, Enlighten, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tattoo Removal Lasers Market Strategic Shifts
Hardware miniaturization and wavelength multiplexing are compressing device footprints while expanding treatable pigment spectra, reshaping procurement criteria across clinic networks.
Multi-wavelength picosecond platforms is fragmenting competitive positioning by enabling single-device treatment of complex multicolor tattoos previously requiring sequential sessions with different systems. High-volume United States cosmetic clinics are adopting these systems to consolidate capital expenditure and reduce patient scheduling friction. The technology is fragmenting market share concentration by lowering the performance threshold for premium positioning.
EU Medical Device Regulation post-market surveillance requirements are extending clinical evidence obligations beyond initial CE marking, forcing manufacturers to maintain longitudinal safety databases. This policy compresses product lifecycle economics and favors established players with regulatory infrastructure. Dermatology centers in Germany and France are prioritizing vendors with demonstrated MDR compliance track records.
Leasing and subscription-based equipment access is displacing outright purchase in mid-tier United States cosmetic clinics facing capital constraint. Device-as-a-service models bundle maintenance, training, and consumables into predictable monthly outflows. This shift concentrates most visibly in California and New York metropolitan markets where clinic networks prioritize balance sheet flexibility over ownership.
Tattoo Removal Lasers Market Segmentation
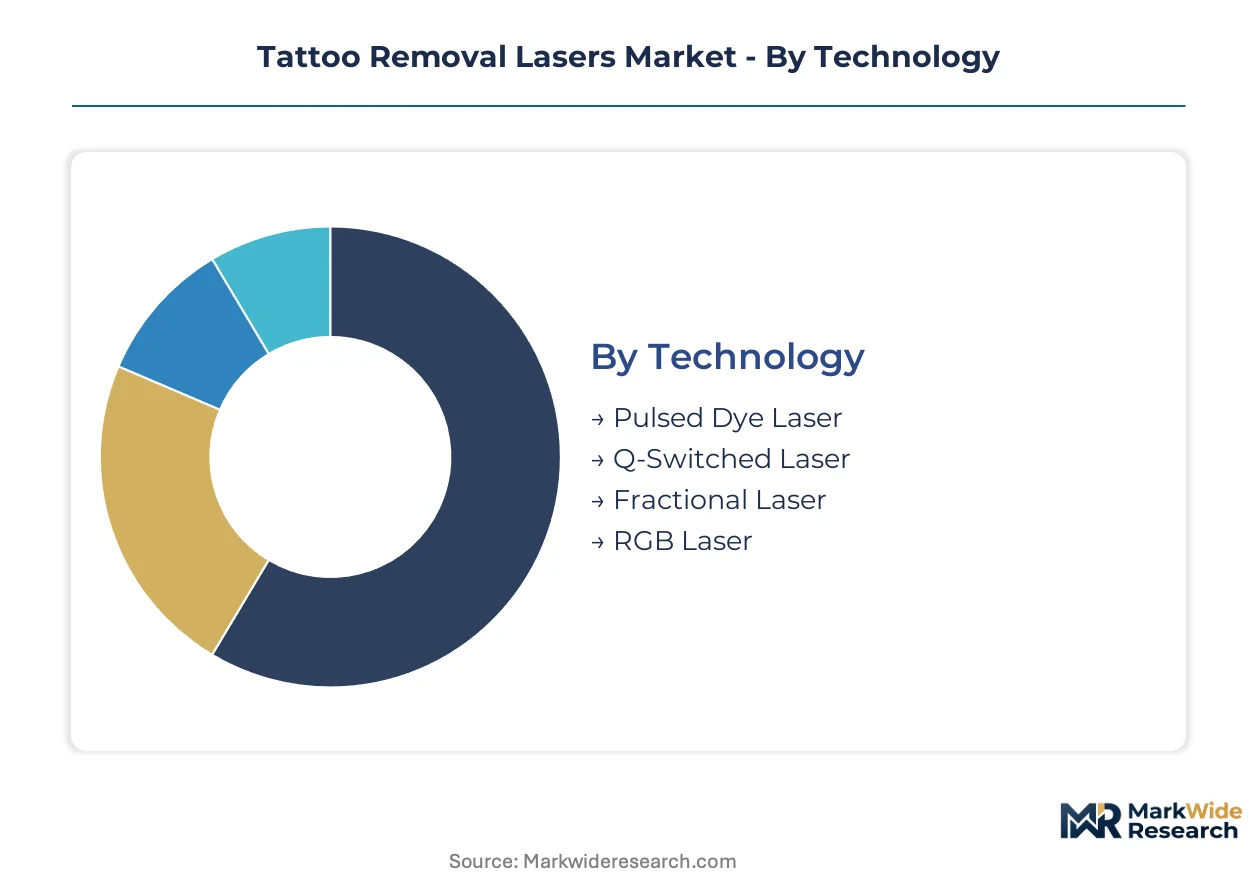
Segmentation in the tattoo removal lasers market reveals distinct procurement patterns across technology tiers and end-use settings. Understanding these divides enables manufacturers to align R&D investment with specific clinical workflows and capital constraints.
Technology:
Geographic demand spreads unevenly across these four modalities, with picosecond-class platforms concentrated in high-disposable-income metropolitan clusters while legacy systems penetrate cost-sensitive secondary markets.
- Q-Switched Laser:Nanosecond pulse platforms deliver 1064nm and 532nm wavelengths through Nd:YAG gain media. Demand concentrates in United States non-metropolitan cosmetic clinics and European mid-tier dermatology networks where capital budgets limit picosecond adoption. These systems retain installed base dominance due to decades of clinical validation and lower service contract burdens.
- Fractional Laser:Microbeam array technology creates controlled thermal zones for combination tattoo removal and scar revision protocols. Adoption clusters in German and French dermatology centers seeking bundled aesthetic service expansion under EU Medical Device Regulation frameworks.
- Pulsed Dye Laser:585-595nm wavelength platforms target vascular components and specific red ink formulations. Niche deployment in specialized pigmentation clinics across Japan and South Korea.
- RGB Laser:Multi-wavelength diode systems attempt single-device coverage of multicolor tattoos. Emerging traction in compact clinic footprints throughout India and Southeast Asian markets.
Q-Switched Laser holds the largest share; momentum sits with Fractional Laser combination protocols.
Application:
Customer type and session volume shape procurement decisions across these four settings, with physician-supervised channels commanding premium pricing and non-medical venues prioritizing lease flexibility.
- Dermatology Centers:Physician-staffed facilities deploy FDA 510(k)-cleared picosecond platforms for complex multicolor cases and adverse event management. United States metropolitan networks in California, New York, and Texas drive premium device procurement through bundled service offerings and combination therapy protocols.
- Cosmetic Clinics:Non-physician-operated aesthetic venues represent the broadest unit deployment base. These operators favor leasing arrangements and multi-wavelength systems to minimize capital exposure while accommodating diverse patient demographics.
- Spa & Wellness:Wellness-integrated settings in Nevada and Arizona exploit liberalized scope-of-practice regulations to offer tattoo fading as adjunct revenue streams. Regulatory fragmentation constrains expansion in states with stricter operator licensing.
- Home Use:Low-energy consumer devices occupy a marginal position due to safety liability exposure and limited efficacy against professional-grade inks. Minimal commercial significance outside direct-to-consumer e-commerce channels.
Cosmetic Clinics dominate unit volumes; Dermatology Centers capture the steepest expansion trajectory through premium positioning.
End User:
Procurement authority and reimbursement access create distinct purchasing workflows across these four stakeholder categories, with institutional buyers leveraging volume leverage unavailable to individual consumers.
- Dermatologists:Board-certified specialists drive specification requirements for picosecond platforms and influence hospital purchasing committee decisions. Their clinical authority shapes wavelength and pulse duration preferences across United States academic medical centers.
- Medical Centers:Hospital-affiliated dermatology departments consolidate capital expenditure through multi-year equipment leases and service bundling. Procurement committees prioritize vendors with ISO 13485 certification and established FDA compliance track records.
- Practitioners:Nurse practitioners and physician assistants in expanded-scope states operate under variable supervision requirements. Their device access depends on state-level scope-of-practice determinations in Arizona, Nevada, and Texas.
- Individuals:End consumers exercise indirect influence through clinic selection and treatment protocol preferences, though they lack direct procurement authority.
Dermatologists control specification-setting; Medical Centers are gaining share fastest through institutional procurement consolidation.
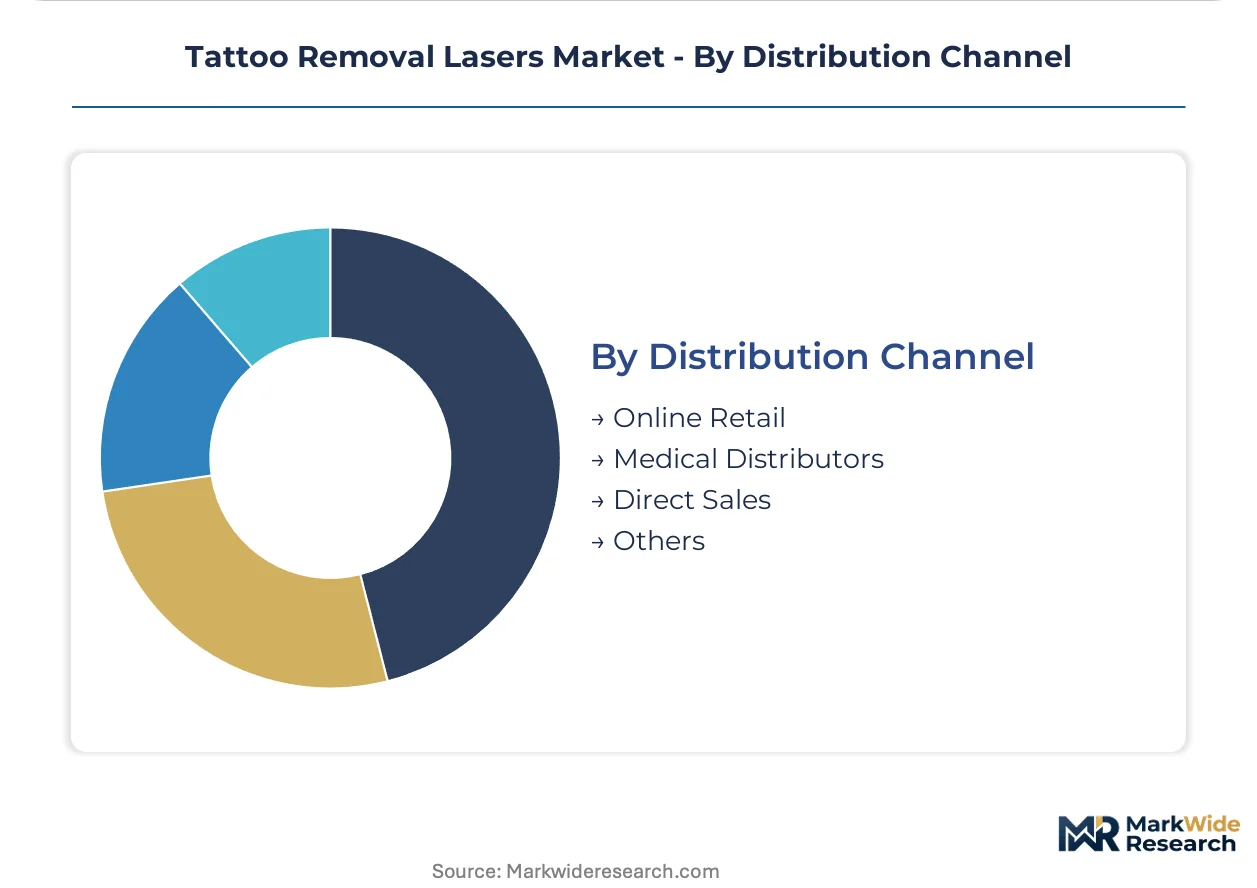
Distribution Channel:
Channel selection reflects capital availability and technical support requirements, with direct relationships favored for complex platform deployments and intermediaries serving price-sensitive segments.
- Direct Sales:Manufacturer field organizations handle picosecond platform placement, installation, and training for high-volume dermatology networks. These relationships bundle maintenance contracts and consumable supply agreements to secure recurring revenue.
- Medical Distributors:Specialized aesthetic device distributors serve mid-tier cosmetic clinics with credit financing and localized service capabilities. Networks like those in Florida and Arizona leverage regional regulatory expertise to facilitate faster deployment.
- Online Retail:E-commerce channels concentrate in consumer-grade and refurbished Q-switched systems. Limited penetration for FDA 510(k)-classified devices due to premarket notification requirements and installation complexity.
- Others:Equipment leasing companies and device-as-a-service providers emerging in California and New York metropolitan markets where clinic networks prioritize balance sheet flexibility.
Medical Distributors hold the largest share; momentum sits with Direct Sales as manufacturers pursue captive service revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium device procurement in United States metropolitan markets commands pricing multiples unavailable to operators in price-sensitive secondary geographies, creating a bifurcated regional revenue structure. This asymmetry concentrates manufacturer attention on high-disposable-income clusters while legacy systems dominate elsewhere. Regulatory fragmentation across national jurisdictions further segments commercialization strategies.
United States
California, New York, and Texas dermatology networks drive picosecond platform adoption through bundled aesthetic service offerings. FDA 510(k) premarket notification pathways govern device clearance timelines and commercialization sequencing. Los Angeles and Manhattan cosmetic clinic clusters prioritize leasing arrangements to preserve balance sheet flexibility amid rapid technology turnover.
Germany
Hospital-affiliated dermatology departments in Bavaria and North Rhine-Westphalia consolidate procurement through multi-year equipment leases. EU Medical Device Regulation notified body assessments impose clinical documentation burdens that favor established vendors with regulatory infrastructure. Frankfurt and Munich academic medical centers influence wavelength specifications across Central European networks.
China
Domestic manufacturers in the Yangtze River Delta and Pearl River Delta regions expand production capacity for compact multi-wavelength platforms. National Medical Products Administration registration requirements shape product development timelines for imported and locally-produced devices. Shanghai and Shenzhen clinic networks experiment with subscription-based equipment access models.
Japan
Specialized pigmentation clinics in Tokyo and Osaka deploy pulsed dye laser systems for vascular components and specific ink formulations. Ministry of Economy, Trade and Industry standards harmonization with IEC frameworks reduces technical barriers for multinational device suppliers. Kanto region dermatology centers prioritize vendors with demonstrated post-market surveillance capabilities.
Brazil
São Paulo and Rio de Janeiro aesthetic clinic networks represent the primary demand concentration in Latin America. National Health Surveillance Agency registration processes create extended commercialization timelines for foreign manufacturers. Southeast Brazilian operators favor Q-switched systems due to capital constraints and established service infrastructure.
Tattoo Removal Lasers Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with picosecond platform developers commanding premium positioning while legacy nanosecond manufacturers compete on installed base maintenance and refurbishment economics. The vendor base organizes into three strategic tiers: integrated picosecond specialists with captive crystal supply chains, diversified aesthetic device conglomerates with broad wavelength portfolios, and regional system integrators serving price-sensitive secondary markets. Dominant competitive moves include M&A activity targeting regulatory infrastructure and technology licensing arrangements that accelerate wavelength portfolio expansion.
Within the integrated technology tier, Cynosure exemplifies supply chain control through in-house picosecond platform development, while Quanta System anchors European positioning through specialized laser portfolios. Lutronic occupies a position in Asian market penetration with compact multi-wavelength systems. These three entities represent distinct archetypes: captive manufacturing integration, regional regulatory specialization, and footprint-optimized platform design.
| Leading Market Players |
|---|
| Cynosure |
| Lumenis |
| Quanta System |
| Candela |
| Cutera |
| Lutronic |
| Removery |
| PiQo4 |
| Enlighten |
| Others |
Value Chain & Pricing Dynamics
Sixteen-week lead times for Nd:YAG laser crystals concentrate pricing power among three optical foundries in Germany and the United States, compressing margins for device assemblers lacking captive supply while elevating premiums for integrated manufacturers. This supply bottleneck intersects with FDA 510(k) clearance timelines to create procurement urgency among dermatology networks seeking picosecond platform deployment.
Pricing Analysis
Configured-to-order picosecond systems command 40-60% premiums over standard Q-switched configurations, with customization extending to wavelength multiplexing and cooling architecture. Three-tier pricing structure across premium, standard, and economy levels stratifies by pulse duration capability and service bundling intensity. Pricing pressure stems from leasing model proliferation in California and New York metropolitan markets, where balance sheet flexibility preferences override ownership economics. Cosmetic clinics exhibit highest price sensitivity due to capital constraints and rapid technology turnover, while dermatology centers absorb premium positioning through procedure bundling.
Supply Chain Analysis
Port congestion on trans-Pacific lanes from Shanghai and Shenzhen elevates inbound logistics costs for Asian-manufactured diode arrays and power electronics. Nd:YAG crystal growth concentrates in Germany and the United States, with finished device assembly anchored in China, South Korea, and domestic United States facilities. The supply chain draws from specialized optical foundries for gain media, Japanese and German sources for precision optics, and Taiwanese foundries for control electronics. Single-source vulnerability in synthetic crystal production creates disruption exposure. Distribution runs through manufacturer direct sales for premium platforms and regional medical distributors for mid-tier cosmetic clinic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
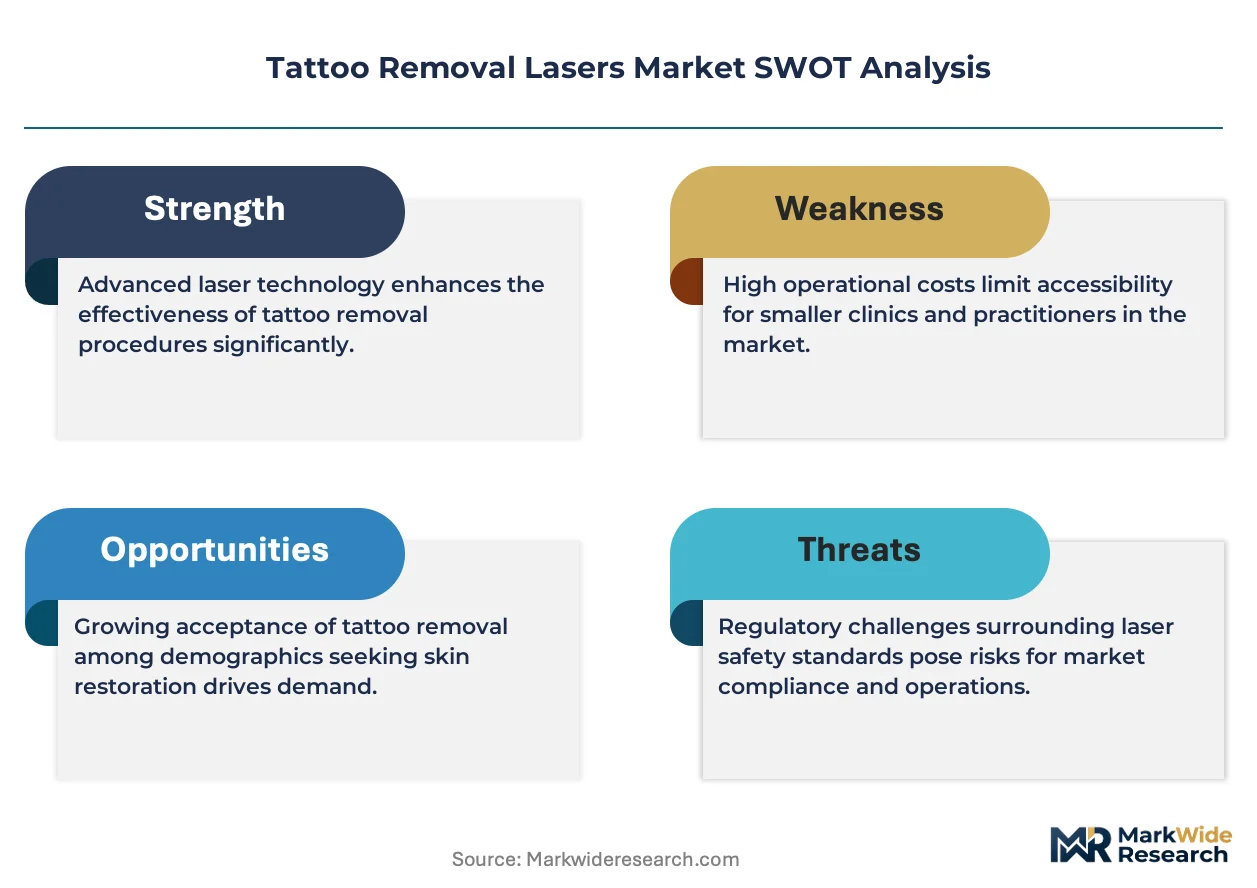
Platform economics are reshaping competitive boundaries as picosecond interoperability standards emerge, enabling third-party wavelength module integration that fragments proprietary ecosystem control.
For Market Incumbents: Fortify captive crystal supply positions through backward integration into Nd:YAG growth facilities or long-term offtake agreements with German and United States optical foundries. Accelerate FDA 510(k) pathway expertise accumulation to compress clearance timelines for multi-wavelength platforms. Defensive priority centers on neutralizing emerging RGB laser substitutes through patent portfolio enforcement and combination therapy protocol bundling. For New Entrants and Emerging Players: FDA 510(k) fast-track designation for picosecond platform variants targeting fluorescent ink limitations offers regulatory acceleration. White-space concentration sits in Texas, Florida, and Arizona non-metropolitan cosmetic clinics operating legacy Q-switched systems. Subscription-based equipment access models penetrate capital-constrained operators. Go-to-market execution should prioritize distributor partnerships with Nevada and Arizona regulatory expertise. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial laser parent companies with undermonetized medical aesthetic divisions. Five-to-ten year viability hinges on picosecond technology transition completion and MDR compliance infrastructure ownership. Acquisition archetype: mid-cap European manufacturers with CE marking track records and stranded Q-switched installed bases. Signal to monitor: state-level scope-of-practice liberalization velocity in Arizona, Nevada, and Texas.| Strategic Initiative | Industry Significance |
|---|---|
| Picosecond Platform FDA 510(k) Submission | Accelerates commercialization timelines for novel wavelength combinations in United States dermatology networks. |
| EU MDR Notified Body Certification | Unlocks CE marking for picosecond devices across German and French hospital-affiliated procurement committees. |
| Leasing and Subscription Model Expansion | Captures balance-sheet-constrained cosmetic clinics in California and New York metropolitan markets. |
| Combination Therapy Protocol Development | Creates service bundling potential with fractional resurfacing systems in wellness channel expansion. |
| Backward Integration into Crystal Supply | Secures Nd:YAG gain media availability against German and United States optical foundry concentration. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) premarket notification databases, EU MDR notified body assessment records, and hospital procurement contract filings. Interviews with dermatology practice administrators, biomedical equipment procurement officers, laser safety officers, and aesthetic device distributor principals informed demand-side validation. Secondary sources included ISO 13485 certification registries, state-level scope-of-practice regulatory filings, and dermatology society clinical guideline documents. Bottom-up unit deployment estimates triangulated against top-down manufacturer revenue segmentation.
Segmentation dimensions modeled include technology tier, end-use setting, and geographic regulatory cluster across the analysis window. Analytical framework incorporated pulse duration evolution curves, capital expenditure cycle timing, and reimbursement policy trajectory. CAGRs derived from installed base replacement dynamics and premium platform penetration rates. Industry-specific inputs encompassed Nd:YAG crystal supply lead times and FDA 510(k) clearance velocity by device modification category.
Underlying assumptions cover stable FDA premarket notification pathway timelines and EU MDR notified body capacity expansion, with deviation risk concentrated in synthetic crystal supply disruptions and state-level operator licensing reversals. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Computer-Aided Oral and Maxillofacial Surgery Market
Medical Devices
Global Motion Preservation Devices Market
Medical Devices
Ultrasonic Dissection Devices Market
Medical Devices
North America General Surgical Devices Market
Medical Devices
Global Prosthetic Heart Valve Market
Medical Devices
Bionic Devices Market
Medical Devices
Global Smart Implantable Pumps Market
Medical Devices
US Medical Sector Contract Electronic Manufacturing Market
Medical Devices
Arthroscopy Devices Market
Medical Devices
Global Lithotripsy Device Market
Medical Devices
Postpartum Hemorrhage (PPH) Devices Market
Medical Devices
Global Asthma and Copd Devices Market
Medical Devices
Australia Respiratory Devices Market
Medical Devices
Global Medical Composite Market
Medical Devices
Peritoneal Catheter Systems Market
Medical Devices
Tracheobronchial Stent Grafts Market