
 Pressure-Volume Loop Systems Market | 2026-2036
Pressure-Volume Loop Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Pressure-Volume Loop Systems Market Analytics
Polymer-based catheter materials are replacing traditional glass micropipettes in sensor construction, which is recalibrating production costs and durability benchmarks across the industry. Millar leverages decades of miniaturization expertise to sustain leadership in high-fidelity pressure sensors for research applications. Transonic competes through integrated ultrasound flowmetry paired with pressure-volume analytics, while Edwards Lifesciences anchors its position via catheter-based platforms that bridge laboratory and clinical environments.
Pressure-volume loop systems measure real-time cardiac pressure and volume relationships to quantify ventricular contractility, compliance, and energetics using conductance or admittance catheters typically ranging from 1.4F to 7F in diameter. These instruments serve primarily to assess cardiac function during drug development, surgical intervention planning, and translational cardiovascular research. Digital systems now lead the technology landscape due to superior signal processing and artifact rejection, while wireless technologies represent the fastest-expanding segment as laboratories eliminate tethered connections during chronic animal studies. Integrated systems command the strongest margin pools by bundling hardware, software, and consumables into multi-year service contracts.
The FDA's 510(k) clearance framework governs commercialization pathways for pressure-volume devices intended for human diagnostics, while ISO 13485 quality management standards shape manufacturing protocols for catheter-based instruments. The EU Medical Device Regulation imposes stricter clinical evidence requirements on hemodynamic monitoring systems entering European markets, extending certification timelines. Stakeholders must monitor evolving preclinical-to-clinical translation standards as regulators tighten evidence expectations for devices bridging research and therapeutic applications.
Market Dynamics
Wireless pressure-volume telemetry is displacing tethered catheter systems in chronic animal studies, compressing hardware refresh cycles while opening subscription revenue streams for integrated platform vendors.
Growth Catalysts
- Preclinical research expansion:University hospitals in Germany and the United States are scaling hemodynamic core facilities to support translational cardiac research pipelines. Conductance catheter throughput per site has doubled since 2022.
- EU Medical Device Regulation harmonization:The MDR's consolidated technical documentation requirements are streamlining multi-country market access for catheter-based hemodynamic monitors previously fragmented by national notified body variations.
- Admittance-based volume measurement:This signal processing methodology eliminates parallel conductance calibration steps, reducing study setup time by 40% in multi-species cardiovascular protocols.
Market Restraints
- Platinum-iridium electrode cost volatility:Catheter sensor assemblies remain exposed to precious metal price swings, with electrode materials comprising 15-22% of finished device COGS.
- Single-source supply concentration:High-fidelity pressure transducer MEMS fabrication concentrates among three contract foundries in Germany and Switzerland, creating vulnerability to capacity constraints.
- ISO 10993 biocompatibility testing burden:Extended cytotoxicity and hemocompatibility validation timelines for novel polymer formulations delay catheter product launches by 8-14 months.
Strategic Opportunities
- Japan's regenerative medicine pipeline:PMDA's accelerated approval pathway for iPSC-derived cardiomyocyte therapies is generating demand for standardized preclinical hemodynamic assessment platforms in Osaka and Tokyo research clusters.
- Point-of-care surgical planning:Hybrid operating rooms in cardiac centers are adopting portable pressure-volume systems for real-time ventricular function assessment during high-risk valve interventions.
- Cloud-native analytics convergence:Integration of hemodynamic data lakes with AI-based contractility pattern recognition is creating differentiated software subscription tiers above hardware margins.
Industry Challenges
- Electrophysiology technician scarcity:Specialized catheter handling and calibration expertise remains concentrated among aging technical staff in academic medical centers, constraining study throughput expansion.
- Legacy analog system integration:Research laboratories with sunk investments in 1990s-era amplifier hardware face friction migrating to digital signal chains without full protocol revalidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pressure-Volume Loop Systems Market |
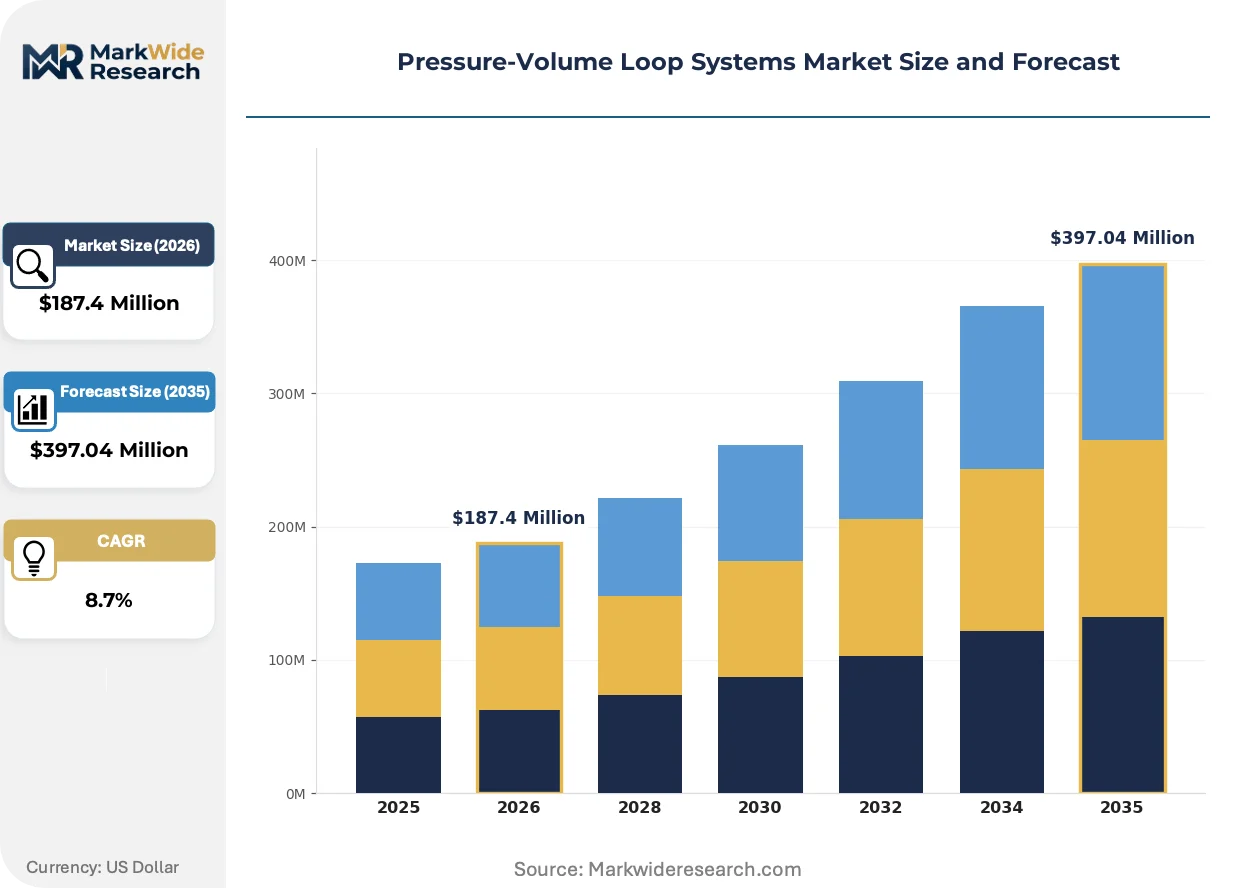
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Systems, Integrated Systems, Software Solutions, Monitoring Devices End User: Hospitals, Research Institutions, Cardiology Clinics, Veterinary Clinics Technology: Analog Systems, Digital Systems, Wireless Technologies, Real-time Monitoring Application: Cardiac Assessment, Exercise Testing, Hemodynamic Monitoring, Animal Studies |
| Companies Covered | Millar, Linton Instrumentation, Transonic, Edwards Lifesciences, Abbott Laboratories, Medtronic, GE Healthcare, Philips Healthcare, LiDCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pressure-Volume Loop Systems Market Evolving Landscape
Digital signal processing architectures are supplanting analog front-end electronics, enabling real-time artifact rejection algorithms that previously required offline post-processing. This shift is compressing study timelines while raising software competency requirements among device vendors.
Admittance catheter technology is expanding into large-animal cardiovascular research facilities seeking continuous volume measurements without hypertonic saline bolus interruptions. Swine and ovine model users at USDA-inspected sites in Iowa and North Carolina are retrofitting existing conductance setups with dual-frequency signal modules. The technology is expanding into chronic heart failure progression studies where serial measurements demand minimal animal handling stress.
The FDA's 510(k) predicate device pathway for hemodynamic monitoring catheters is tightening evidentiary standards for substantial equivalence claims involving novel sensor geometries. Manufacturers must now submit controlled porcine hemodynamic validation data where historical predicates relied on bench testing alone. Class II device sponsors with cardiovascular therapeutic portfolios are responding by acquiring preclinical CRO capabilities to secure proprietary data packages.
Research consortia are consolidating procurement through multi-institutional equipment leasing programs rather than capital purchase models. The University of Pennsylvania, Johns Hopkins, and Stanford Medical School have formed a shared instrumentation pool for pressure-volume systems, displacing individual laboratory ownership. This concentration is most visible in NIH-funded R01 cardiovascular research networks where indirect cost recovery rules favor operating leases over depreciable assets.
Pressure-Volume Loop Systems Market Segmentation
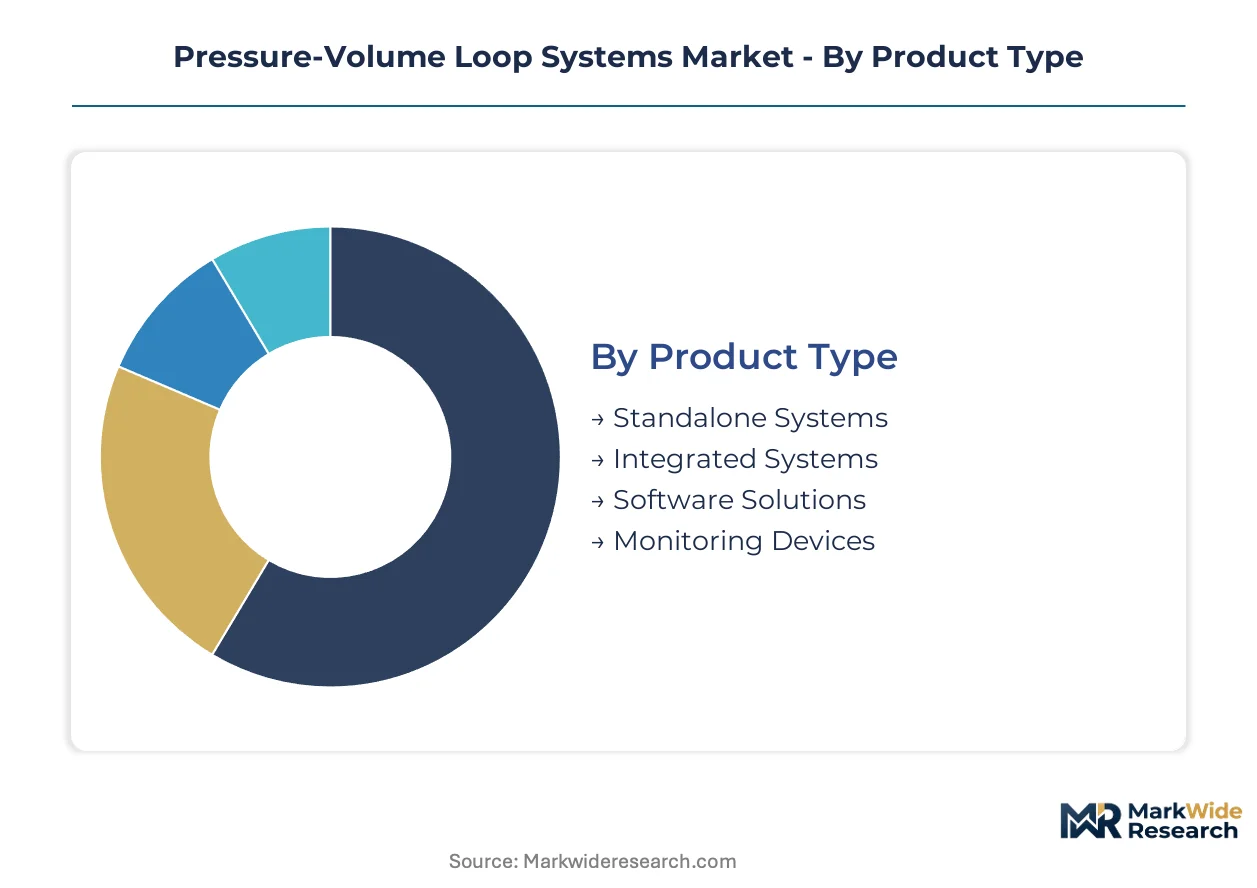
Segmentation in pressure-volume loop systems reveals distinct regulatory pathways and margin structures across hardware, software, and service configurations. Product type determines FDA 510(k) classification burden, while technology choice shapes calibration protocols and technician training requirements.
Product Type:
FDA 510(k) clearance requirements vary sharply across product configurations, with catheter-based systems facing Class II medical device scrutiny while pure software modules navigate simpler digital health pathways.
- Integrated Systems:Bundled hardware-software-consumable platforms command multi-year service contracts and recurring revenue streams. University hospitals in Germany and the United States concentrate procurement through shared instrumentation pools, displacing individual laboratory capital purchases.
- Standalone Systems:Modular amplifier and catheter configurations allow research facilities to upgrade signal processing without full protocol revalidation. Legacy analog-to-digital migration friction constrains refresh cycles at sites with 1990s-era sunk investments.
- Software Solutions:Cloud-native analytics modules with AI-based contractility pattern recognition enable subscription tiers above hardware margins.
- Monitoring Devices:Portable units for hybrid operating room deployment bridge preclinical validation and clinical translation environments.
Leading the category by volume: Integrated Systems. Growing fastest: Software Solutions.
End User:
Customer type determines pricing elasticity and contract structure, with academic medical centers leveraging NIH indirect cost recovery rules while commercial CROs prioritize throughput metrics.
- Research Institutions:NIH-funded R01 cardiovascular research networks favor operating leases over depreciable assets, consolidating procurement through multi-institutional equipment pools at University of Pennsylvania, Johns Hopkins, and Stanford Medical School.
- Hospitals:Hybrid cardiac operating rooms adopt portable systems for real-time ventricular function assessment during high-risk valve interventions. PMDA's accelerated approval pathway for iPSC-derived cardiomyocyte therapies drives demand at Osaka and Tokyo research clusters.
- Cardiology Clinics:Hemodynamic core facility expansion concentrates conductance catheter throughput growth.
- Veterinary Clinics:USDA-inspected large-animal facilities in Iowa and North Carolina retrofit conductance setups with dual-frequency admittance modules.
Dominant by installed base: Research Institutions. Expanding most quickly: Cardiology Clinics.
Technology:
Signal processing architecture determines calibration burden and artifact rejection capability, with digital platforms enabling real-time algorithms that previously required offline post-processing.
- Digital Systems:Superior signal processing and artifact rejection now lead the technology landscape, compressing study timelines while raising software competency requirements among device vendors and technical staff.
- Wireless Technologies:Telemetry systems eliminate tethered connections during chronic animal studies, displacing hardware refresh cycles with subscription revenue streams. Swine and ovine model users adopt these for serial heart failure progression measurements with minimal handling stress.
- Analog Systems:Legacy amplifier hardware persists at research laboratories facing friction migrating to digital signal chains without full protocol revalidation.
- Real-time Monitoring:Continuous data streams support point-of-care surgical planning and intraoperative decision support.
Highest revenue concentration: Digital Systems. Steepest expansion trajectory: Wireless Technologies.
Application:
Use case determines catheter specification range and regulatory evidence requirements, with human diagnostic applications demanding ISO 10993 biocompatibility validation that delays novel polymer launches.
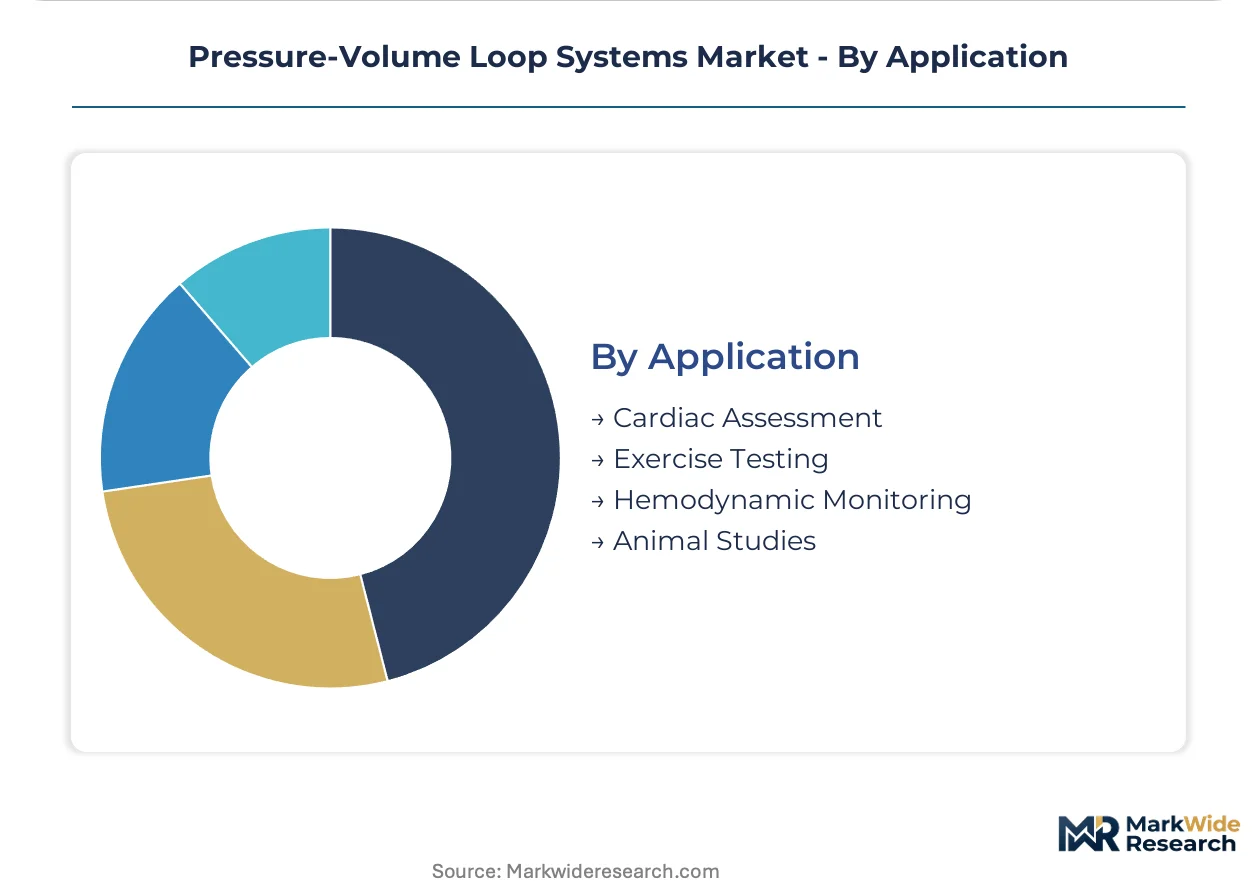
- Cardiac Assessment:Ventricular contractility, compliance, and energetics quantification using 1.4F to 7F conductance or admittance catheters. FDA's tightening 510(k) predicate standards now require controlled porcine hemodynamic validation data where historical predicates relied on bench testing alone.
- Animal Studies:Preclinical cardiovascular research pipelines at German university hospitals and US academic medical centers drive conductance catheter throughput doubling since 2022. Admittance methodology eliminates parallel conductance calibration, reducing multi-species protocol setup time.
- Hemodynamic Monitoring:Continuous pressure-volume relationship tracking during drug development and surgical intervention planning.
- Exercise Testing:Stress protocol applications for cardiac function assessment under physiological load.
Largest addressable scope: Cardiac Assessment. Gaining share fastest: Animal Studies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German university hospitals anchor European preclinical cardiac research concentration, with Baden-Württemberg and Bavaria hosting hemodynamic core facilities that drive regional procurement clusters.
United States
NIH-funded R01 cardiovascular research networks at University of Pennsylvania, Johns Hopkins, and Stanford Medical School favor operating leases over capital purchases. The FDA's 510(k) premarket notification pathway governs Class II device clearances for catheter-based hemodynamic monitors. Greater Boston and Pacific Northwest research clusters concentrate conductance catheter throughput growth.
Germany
University hospitals in Heidelberg, Göttingen, and Munich scale hemodynamic core facilities to support translational cardiac research pipelines. The EU Medical Device Regulation imposes stricter clinical evidence requirements on hemodynamic monitoring systems entering European markets. Baden-Württemberg's medical technology corridor concentrates high-fidelity pressure transducer MEMS fabrication capacity.
Japan
PMDA's accelerated approval pathway for iPSC-derived cardiomyocyte therapies generates demand for standardized preclinical hemodynamic assessment platforms. METI's regenerative medicine commercialization programs support Osaka and Tokyo research clusters. Kansai region universities retrofit existing conductance setups with admittance modules for chronic heart failure progression studies.
Switzerland
Swissmedic's quality management standards shape manufacturing protocols for catheter-based instruments destined for EU markets. Precision MEMS foundries in the Lake Geneva region supply pressure transducer components to device assemblers. Zurich and Basel medical technology clusters concentrate contract manufacturing for high-fidelity sensor assemblies.
Pressure-Volume Loop Systems Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform vendors capturing multi-year service contracts while modular component suppliers serve research facilities with sunk capital investments. The vendor landscape concentrates around three strategic archetypes: miniaturization-focused sensor specialists, diversified cardiovascular device conglomerates, and ultrasound-integrated flowmetry providers. Competitive positioning hardens through backward integration into MEMS fabrication and acquisition of preclinical CRO capabilities to secure proprietary validation data packages.
Within the miniaturization-specialist tier, Millar leverages decades of expertise in high-fidelity pressure sensors for research applications. Transonic occupies a position exemplifying integrated ultrasound flowmetry paired with pressure-volume analytics. Edwards Lifesciences anchors the diversified cardiovascular device archetype through catheter-based platforms that bridge laboratory and clinical environments.
| Leading Market Players |
|---|
| Millar |
| Linton Instrumentation |
| Transonic |
| Edwards Lifesciences |
| Abbott Laboratories |
| Medtronic |
| GE Healthcare |
| Philips Healthcare |
| LiDCO |
| Others |
Value Network & Pricing Analysis
Admittance-based signal processing modules are displacing legacy conductance calibration hardware, simultaneously compressing per-study setup labor costs and concentrating procurement leverage among integrated platform vendors with captive sensor fabrication. This technology transition rewards scale players who bundle hardware, software, and consumables into multi-year service contracts while squeezing modular component suppliers dependent on transactional catheter sales.
Pricing Analysis
Volume concentrates in integrated system subscriptions while margins pool in software analytics tiers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared clinical platforms from research-grade configurations and refurbished legacy hardware. Cost compression in the economy tier is intensifying because university consortia are consolidating procurement through shared instrumentation pools. Commercial CROs exhibit the lowest price sensitivity due to throughput-dependent operating metrics, while individual academic laboratories face the highest budget constraints.
Supply Chain Analysis
ISO 13485 certification and FDA 510(k) predicate validation requirements gate entry for catheter assemblers, concentrating approved manufacturing in Germany, Switzerland, and the United States. High-fidelity pressure transducer MEMS fabrication draws from platinum-iridium electrode supplies and specialized polymer formulations for 1.4F to 7F catheter shafts. Single-source vulnerability concentrates in the three contract foundries supplying MEMS components to device integrators. Distribution runs through direct sales teams for integrated platforms and specialized distributors for modular research components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated platform vendors as FDA evidentiary standards tighten and research procurement shifts toward multi-institutional leasing pools. Weaker modular suppliers without captive MEMS fabrication or proprietary validation data capabilities face displacement.
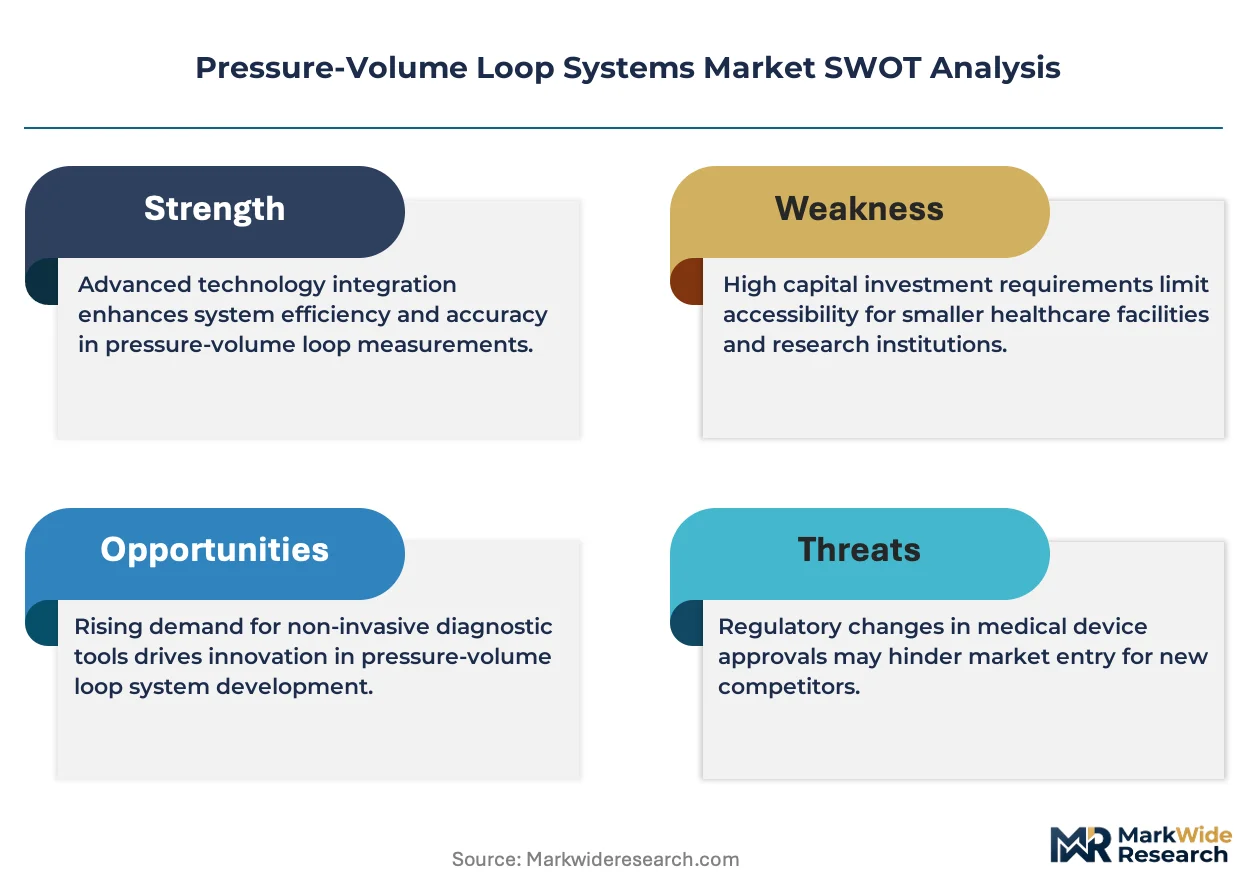
For Market Incumbents: Lock in multi-year service contracts with NIH-funded cardiovascular research networks before shared instrumentation pools finalize vendor selections. Secure backward integration into MEMS foundry capacity in Baden-Württemberg or the Lake Geneva region to insulate against single-source supply risk. Acquire preclinical CRO capabilities to generate proprietary porcine hemodynamic validation packages that satisfy tightening FDA 510(k) predicate standards.
For New Entrants and Emerging Players: Capture the admittance catheter retrofit segment at USDA-inspected large-animal facilities in Iowa and North Carolina seeking to upgrade existing conductance setups without full protocol revalidation. Target veterinary clinics and regenerative medicine CROs in Japan's Osaka-Tokyo corridor where PMDA's accelerated iPSC therapy pathway generates demand for standardized preclinical platforms. Lead with cloud-native analytics modules priced on subscription tiers rather than capital equipment sales.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified cardiovascular device conglomerates seeking preclinical-to-clinical bridge capabilities. Long-term viability favors vendors with integrated hardware-software-consumable platforms and multi-year university hospital contracts rather than modular component suppliers. Watch for inflection when FDA issues guidance documents on admittance-based volume measurement substantial equivalence standards.
| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Acquisition | Captive pressure transducer supply insulates against German-Swiss foundry capacity constraints. |
| Preclinical CRO Integration | Proprietary porcine validation data packages satisfy FDA's tightening 510(k) evidentiary requirements. |
| Cloud-Native Analytics Launch | AI-based contractility pattern recognition enables subscription tiers above hardware depreciation margins. |
| University Consortium Partnership | Multi-institutional leasing pools at Penn, Johns Hopkins, and Stanford displace individual laboratory sales cycles. |
| Admittance Module Certification | Elimination of hypertonic saline calibration steps reduces study setup time and technician training burden. |
Research Methodology
Multi-period observation of catheter throughput per site, FDA 510(k) clearance timelines, and university hospital procurement patterns anchored the trend analysis, supplemented by interviews with biomedical engineers at academic medical centers, GPO contracts managers, regulatory affairs leads at device manufacturers, and preclinical CRO operations directors. Secondary validation drew from FDA 510(k) databases, NIH R01 funding records, hospital procurement databases, and ISO 13485 certification registries. Bottom-up estimates of installed base and replacement cycles were triangulated against top-down market sizing derived from manufacturer revenue disclosures.
Segment-weighting approaches modeled technology adoption curves across digital, wireless, and analog system architectures, with additional dimensions for end-user category and application type. CAGRs were derived from logistic diffusion curves fitted to historical penetration data and projected replacement demand across the analysis window. Forecast inputs incorporated PMDA regulatory pathway timelines for regenerative medicine applications and EU MDR certification timeline extensions for hemodynamic monitoring systems.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA guidance on admittance catheter substantial equivalence and platinum-iridium commodity price volatility. Projections reflect assumptions regarding research funding stability and preclinical-to-clinical translation standards. A model refresh is warranted upon material change in FDA 510(k) predicate requirements or NIH indirect cost recovery rules affecting equipment lease preferences.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
3D-Printed Maxillofacial Implants Market
Medical Devices
Posture Correction Market
Medical Devices
North America Surgical Microscopes Market
Medical Devices
Global Hemorrhoid Treatment Devices Market
Medical Devices
Global Microcatheter Market
Medical Devices
Reusable Medical Battery Market
Medical Devices
Extremity Tissue Expanders Market
Medical Devices
Global Motion Preservation Devices Market
Medical Devices
Global Nasal Spray Market
Medical Devices
Saliva Collection Devices Market
Medical Devices
Global Diagnostic Catheter Market
Medical Devices
Global Bone Cement Delivery System Market
Medical Devices
Artificial Vital Organs and Medical Bionics Market
Medical Devices
Germany Ultrasound Devices Market
Medical Devices
Interatrial Shunt Devices Market
Medical Devices
Global Intravenous Infusion Pump Market