
 Repositioning and Offloading Devices Market | 2026-2036
Repositioning and Offloading Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Repositioning and Offloading Devices Market Outlook
Sensor-integrated pressure mapping is narrowing the performance gap between basic foam cushions and advanced dynamic support surfaces. Stryker leverages its hospital integration capabilities to bundle repositioning systems with broader patient handling portfolios. Guldmann anchors its position through ceiling lift and sling ecosystems that incorporate automated offloading protocols. Medline Industries, LP competes on distribution density, supplying standardized foam and gel products across acute and post-acute channels.
Repositioning and offloading devices are engineered support surfaces and mechanical systems designed to redistribute pressure, shear, and friction forces across the body, typically incorporating multi-layer polyurethane or viscoelastic memory foam constructions with density ratings between 40-80 kg/m³ for optimal immersion and envelopment. Their primary purpose is to prevent hospital-acquired pressure injuries and facilitate safe patient mobilization during recovery. Air mattress systems command premium positioning due to active pressure alternation capabilities, while foam cushions remain the volume backbone in long-term care facilities where capital budgets constrain technology uptake. Pressure ulcer prevention applications generate the most intensive clinical scrutiny and therefore the strongest pull for evidence-based product selection.
The FDA regulates these devices as Class I or II medical products depending on therapeutic claims, while the EU MDR imposes stricter clinical evidence requirements for pressure-redistributing devices marketed in Europe. State-level Medicaid reimbursement policies in the US and England's NHS pressure ulcer reduction targets directly shape procurement volume and product tier selection. Stakeholders must monitor evolving equivalence pathways under MDR and state waiver programs to anticipate which product categories will face access compression or accelerated adoption.
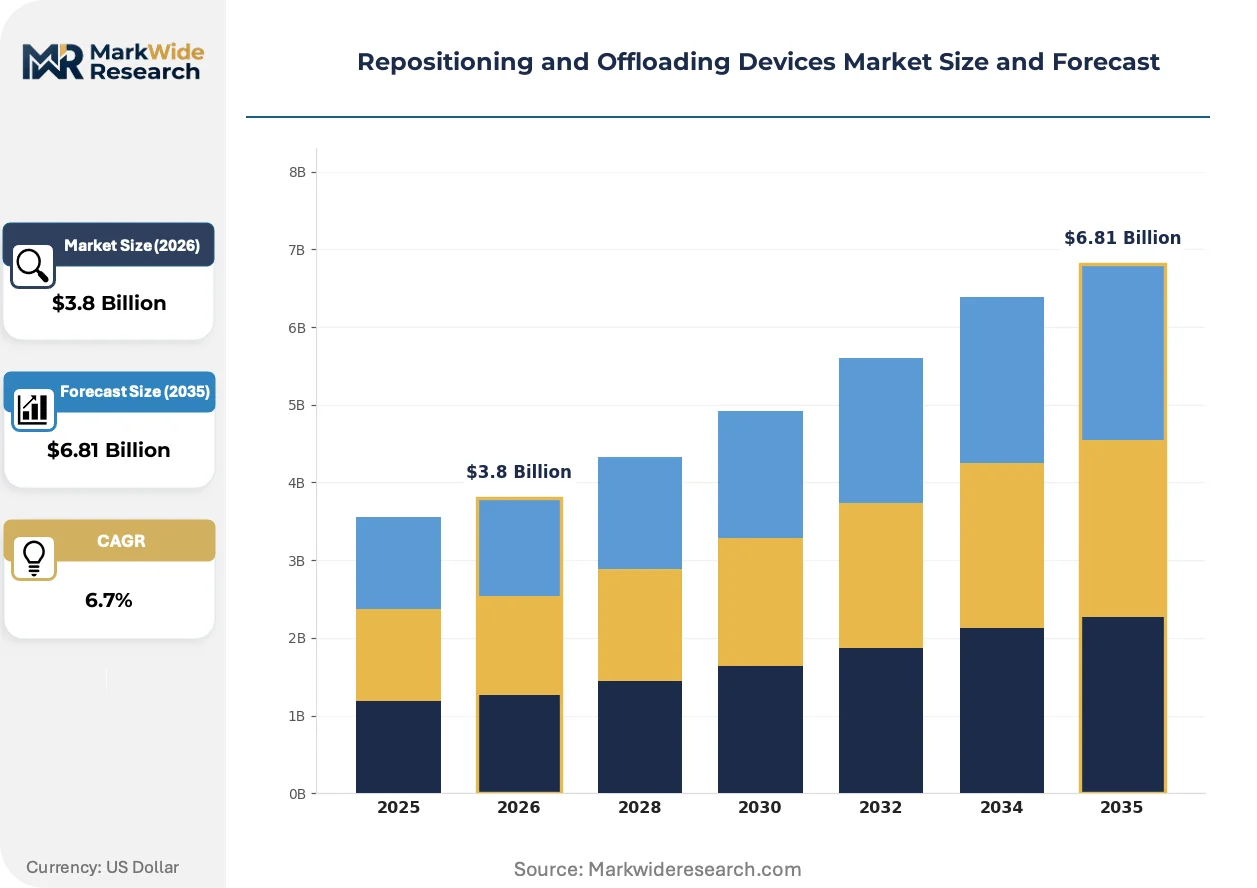
Market Dynamics
Sensor-integrated pressure mapping is compressing margins on basic foam cushions while elevating clinical expectations for evidence-based offloading performance across acute care procurement committees.
Growth Catalysts
- EU MDR clinical evidence mandates:Stricter post-market surveillance requirements for pressure-redistributing devices are filtering out low-evidence suppliers and consolidating procurement toward validated manufacturers in Germany and France.
- Medicaid reimbursement incentives:State-level pressure ulcer prevention protocols in the US tie hospital reimbursement to HAPU reduction metrics, directly expanding procurement of dynamic support surfaces.
- Viscoelastic memory foam density optimization:Advances in 60-80 kg/m³ foam formulations are improving immersion characteristics without active air systems, opening penetration in capital-constrained long-term care.
Market Restraints
- Polyether polyol price volatility:Feedstock cost swings for polyurethane foam raw materials compress margin predictability for mid-tier cushion manufacturers.
- Air pump component concentration:Alternating pressure mattress systems depend on diaphragm pump assemblies sourced primarily from East Asian contract manufacturers, creating supply vulnerability.
- Static foam performance ceiling:Basic polyurethane cushions cannot achieve active pressure redistribution, limiting their clinical acceptance in ICU and surgical recovery settings regardless of cost advantage.
Strategic Opportunities
- Home care channel expansion:Post-acute discharge protocols are extending device rental and purchase pathways into residential settings, creating direct-to-patient distribution models.
- AI-powered predictive offloading:Machine learning integration with pressure mapping sensors enables anticipatory repositioning alerts before tissue damage thresholds.
- Japan's aging-in-place infrastructure:METI subsidies for home medical equipment are accelerating adoption of automated repositioning systems outside institutional settings.
Industry Challenges
- Biomedical sensor calibration expertise:Pressure mapping system deployment requires specialized clinical engineering talent that acute care facilities struggle to recruit and retain.
- Legacy EHR integration friction:Automated offloading documentation systems face interoperability barriers with established electronic health record architectures, delaying workflow adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Repositioning and Offloading Devices Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Foam Cushions, Gel Pads, Air Mattresses, Specialty Cushions Application Area: Post-operative Care, Pressure Ulcer Prevention, Rehabilitation, Palliative Care End User: Hospitals, Long-term Care Facilities, Homecare Settings, Rehabilitation Centers Material: Polyurethane, Memory Foam, Thermoplastic, Silicone |
| Companies Covered | Medline Industries, LP, Permobil AB, Stryker, Guldmann, Invacare Corporation, Hill-Rom Services, Arjo Group, Sage Products LLC, Mölnlycke Health Care AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Repositioning and Offloading Devices Market Strategic Shifts
Active pressure alternation technologies are migrating from critical care into step-down units and post-acute facilities, rewriting performance benchmarks across the product hierarchy.
Capacitive sensor arrays embedded beneath viscoelastic foam layers are rendering obsolete manual repositioning schedules that rely on two-hour turn protocols. Hospital systems in the US and Germany are deploying these systems in medical-surgical wards to reduce nursing labor burden. The technology is rendering obsolete the traditional separation between "prevention" and "treatment" product tiers by delivering ICU-grade monitoring at mid-range price points.
The EU MDR's enhanced clinical evidence requirements for pressure-redistributing devices are accelerating documentation investments by manufacturers seeking CE marking renewal. Post-market surveillance obligations now mandate real-world performance data collection that smaller foam producers cannot sustain. German notified bodies are prioritizing review queues for sensor-integrated systems with published pressure mapping studies, compressing approval timelines for technology-heavy submissions.
Acute care procurement committees are unbundling device acquisition from service contracts, demanding separate pricing transparency for capital equipment, installation, and preventive maintenance. IDN consolidation in the US is centralizing purchasing authority to system-level value analysis committees that standardize across multiple hospital sites. This concentration is most visible in the Northeast and Midwest, where multi-hospital networks are consolidating supplier rosters to three to four validated vendors per product category.
Repositioning and Offloading Devices Market Segmentation
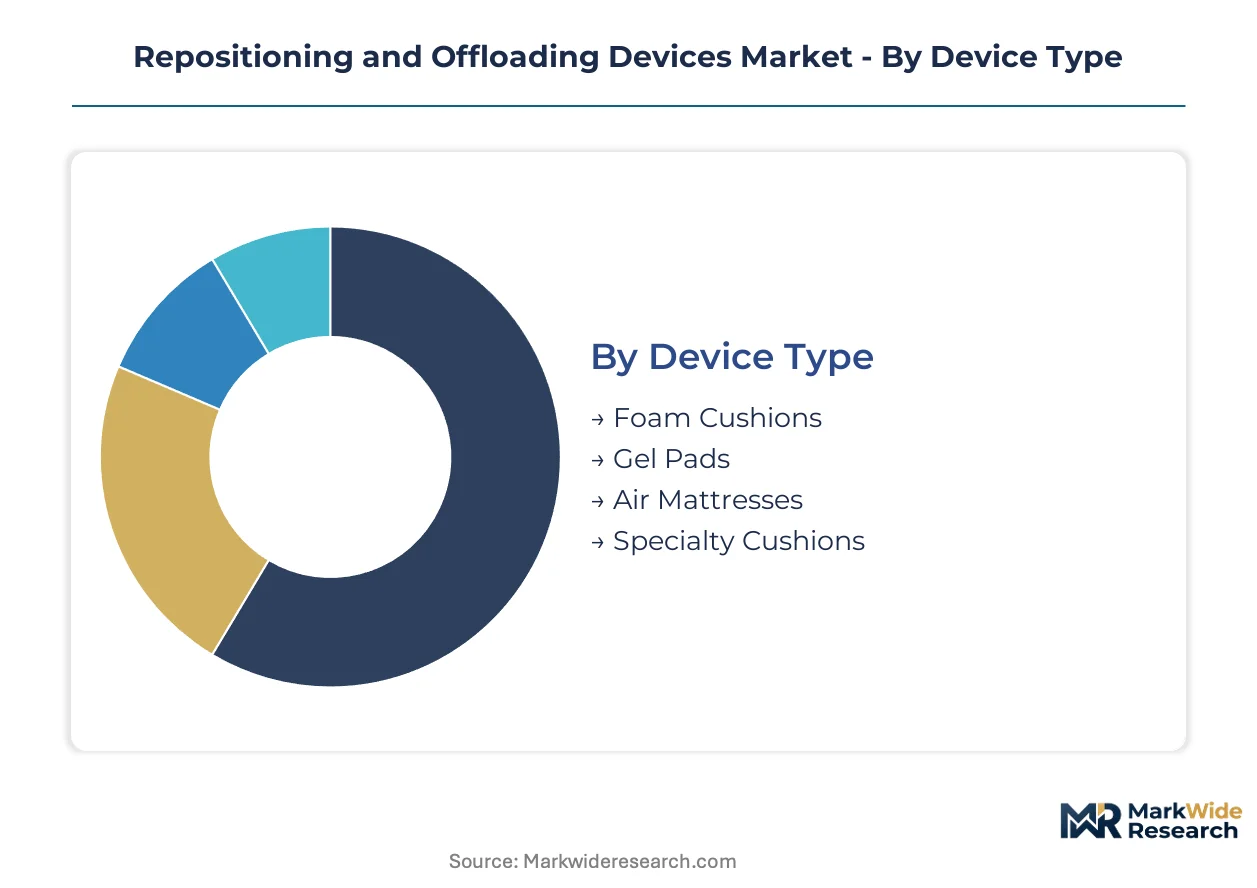
Repositioning and offloading devices serve heterogeneous clinical environments with divergent performance requirements and capital constraints. Segmentation reveals how procurement committees balance pressure redistribution efficacy against total cost of ownership across acute and post-acute channels.
Device Type:
After-sales service intensity varies sharply across device categories, with active air systems demanding preventive maintenance contracts while foam products require minimal field support.
- Air Mattresses:Alternating pressure systems incorporate diaphragm pump assemblies and sensor-integrated control units that redistribute pressure through cyclic inflation-deflation cycles. Demand concentrates in US hospital ICUs and German trauma centers where Medicaid reimbursement incentives and EU MDR clinical evidence mandates favor validated active systems over static alternatives.
- Foam Cushions:Multi-layer polyurethane constructions with 40-80 kg/m³ density ratings provide passive pressure redistribution through immersion and envelopment without powered components. Long-term care facilities in capital-constrained markets deploy these as volume backbone products, though their static performance ceiling limits penetration in surgical recovery settings.
- Gel Pads:Viscoelastic polymer formulations offer shear reduction properties for operating room tables and procedural stretchers.
- Specialty Cushions:Anatomically contoured designs address bariatric patient requirements and wheelchair seating applications.
Air mattresses hold the largest share; momentum sits with specialty cushions as bariatric patient populations expand.
Application Area:
Clinical scrutiny intensity drives product tier selection, with prevention applications commanding premium positioning over comfort-focused categories.
- Pressure Ulcer Prevention:Hospital-acquired pressure injury reduction protocols mandate evidence-based support surface selection with documented pressure mapping validation. US acute care systems tie procurement to HAPU metrics under state-level Medicaid incentives, while England's NHS pressure ulcer targets shape European demand patterns.
- Post-operative Care:Surgical recovery units require surfaces that balance offloading performance with safe patient mobilization protocols. German medical-surgical wards are deploying sensor-integrated systems to reduce nursing labor burden while maintaining mobility safety.
- Rehabilitation:Mobility-focused applications prioritize shear reduction and seated positioning for early mobilization protocols.
- Palliative Care:Comfort-oriented specifications emphasize pressure redistribution for immobile patients with limited repositioning tolerance.
Pressure ulcer prevention commands the dominant revenue position; post-operative care is climbing the fastest as sensor integration migrates from critical care into step-down units.
End User:
Procurement authority concentration shapes vendor access, with consolidated IDN purchasing desks demanding standardized product portfolios across multi-site deployments.
- Hospitals:Value analysis committees in US Northeast and Midwest health systems are consolidating supplier rosters to three to four validated vendors per category, demanding separate pricing transparency for equipment, installation, and preventive maintenance. FDA Class II device classification for therapeutic claims shapes product selection criteria.
- Long-term Care Facilities:Capital budget constraints favor static foam and gel products over active air systems, though viscoelastic density advances are narrowing the performance gap. These facilities represent the highest volume channel for standardized cushion procurement.
- Homecare Settings:Post-acute discharge protocols are extending rental and purchase pathways into residential environments, creating direct-to-patient distribution models requiring simplified user interfaces.
- Rehabilitation Centers:Mobility-focused procurement prioritizes safe patient handling integration with ceiling lift and sling ecosystems.
Hospitals generate the highest revenue per unit; homecare settings are expanding most quickly as aging-in-place infrastructure matures.
Material:
Raw material cost volatility and formulation proprietaryness determine margin stability across supplier tiers.
- Memory Foam:Viscoelastic polyurethane formulations with 60-80 kg/m³ density ratings optimize immersion characteristics without active air systems, opening penetration in capital-constrained channels while approaching active system performance benchmarks.
- Polyurethane:Standard polyether formulations dominate volume production for basic cushion applications where polyether polyol price volatility compresses margin predictability for mid-tier manufacturers.
- Silicone:Medical-grade elastomers provide durability and biocompatibility for specialty seating applications.
- Thermoplastic:Moldable polymers enable anatomical contouring for custom-fit positioning devices.
Polyurethane holds the largest installed base; memory foam is gaining share fastest as density optimization narrows the clinical performance gap with active systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export sensor-integrated pressure mapping systems to United States hospital networks under FDA Class II clearance pathways, establishing the primary transatlantic trade corridor for advanced offloading technologies.
United States
State-level Medicaid reimbursement incentives tie hospital payments to HAPU reduction metrics, expanding procurement of dynamic support surfaces. The FDA's updated medical device guidance accelerates compliance investments by domestic and foreign suppliers. IDN consolidation in the Northeast and Midwest concentrates purchasing authority within value analysis committees standardizing across multi-site deployments.
Germany
Aging demographics and trauma center specialization drive demand for alternating pressure systems in acute care settings. The EU MDR imposes stricter clinical evidence requirements, filtering procurement toward validated manufacturers with published pressure mapping studies. Notified bodies in Berlin and Munich prioritize review queues for technology-heavy submissions, compressing approval timelines.
Japan
METI subsidies for home medical equipment accelerate adoption of automated repositioning systems outside institutional settings. The PMDA regulates pressure-redistributing devices with evidence standards aligned to international ISO benchmarks. Industrial clusters in Osaka and Nagoya concentrate production of diaphragm pump assemblies serving regional air mattress manufacturers.
United Kingdom
NHS pressure ulcer reduction targets directly shape procurement volume and product tier selection across acute and community care trusts. England's National Institute for Health and Care Excellence publishes technology appraisals influencing support surface commissioning. Manufacturing activity concentrates in the Midlands, where foam converters supply standardized cushions to post-acute channels.
Canada
Health Canada regulates repositioning devices under the Medical Devices Regulations with classification pathways mirroring FDA frameworks. Provincial health authorities coordinate bulk procurement for long-term care facilities facing capital budget constraints. Ontario-based distributors serve as entry points for United States and European manufacturers seeking North American market access.
Repositioning and Offloading Devices Market Competitive Environment
On the supply side, the industry is consolidating around three strategic tiers: multinational hospital integration platforms, specialized patient handling ecosystems, and high-volume distribution networks serving capital-constrained channels. The competitive landscape rewards scale in regulatory compliance, density in acute care contracting, and flexibility in post-acute fulfillment. Dominant competitive moves include portfolio bundling of repositioning systems with broader patient handling equipment and geographic expansion through regional distribution partnerships.
Within the integration-platform tier, Stryker leverages hospital system relationships to bundle repositioning technologies with surgical and critical care portfolios. Guldmann anchors the specialized ecosystem segment through ceiling lift and sling systems that incorporate automated offloading protocols. Medline Industries, LP occupies the high-volume distribution position, supplying standardized foam and gel products across acute and post-acute channels where procurement prioritizes cost predictability over active pressure alternation.
| Leading Market Players |
|---|
| Medline Industries, LP |
| Permobil AB |
| Stryker |
| Guldmann |
| Invacare Corporation |
| Hill-Rom Services |
| Arjo Group |
| Sage Products LLC |
| Mölnlycke Health Care AB |
| Others |
Value Chain & Pricing Dynamics
Osaka's industrial cluster concentration for diaphragm pump assemblies directly shapes pricing power for alternating pressure mattress manufacturers serving United States hospital networks. Component scarcity at this chokepoint feeds downstream into premium positioning for active air systems versus static foam alternatives.
Pricing Analysis
The current-generation versus prior-generation versus next-generation pricing gap spans active sensor-integrated systems, basic alternating pressure units, and AI-powered predictive offloading platforms. Contract-based long-term procurement dominates, with price differentiation resting on FDA Class II certification tier and after-sales service bundling. Cost compression in mid-tier foam cushions is intensifying because polyether polyol feedstock volatility squeezes manufacturer margins. Long-term care facilities exhibit highest price sensitivity, while United States academic medical centers prioritize clinical validation over unit economics.
Supply Chain Analysis
East Asian contract manufacturers in China, South Korea, and Japan hold captive capacity for diaphragm pump assemblies and capacitive sensor arrays. Raw material dependencies center on polyurethane polyols, medical-grade silicone, and precision-molded thermoplastics. Single-source vulnerability concentrates in diaphragm pump component supply, with regional air mattress manufacturers tethered to Osaka and Nagoya production clusters. Distribution runs through group purchasing organizations and integrated delivery network value analysis committees in the United States Northeast and Midwest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in regulatory entrenchment. FDA Class II clearance pathways and EU MDR clinical evidence mandates create multi-year barriers that filter out undercapitalized competitors.
For Market Incumbents: Pre-empt margin erosion in basic foam cushions by accelerating backward integration into polyurethane formulation capabilities and securing long-term polyether polyol offtake agreements. Sensor-integrated system commoditization from emerging Asian manufacturers threatens premium positioning; defend through exclusive hospital system partnerships that bundle repositioning technologies with broader patient handling portfolios. For New Entrants and Emerging Players: Build out direct-to-patient distribution models targeting Japan's homecare channel where METI subsidies reduce customer acquisition friction. The most penetrable white space sits in AI-powered predictive offloading software companions that integrate with existing pressure mapping hardware, bypassing capital-intensive pump assembly manufacturing. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among sensor-integrated system manufacturers with preventive maintenance contract attach rates above seventy percent. Long-term viability over the coming decade favors vertically integrated players with in-house pump assembly production and published pressure mapping studies. Monitor FDA 510(k) submission volumes for predictive offloading algorithms as the inflection signal for technology migration timing.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR CE Marking Pathway | Notified bodies in Berlin prioritize sensor-integrated submissions with clinical evidence packages. |
| Hospital System Partnership | IDN consolidation in United States Midwest creates three-to-four vendor standardization opportunities. |
| Software Companion Development | AI-powered predictive offloading enables anticipatory repositioning alerts before tissue damage thresholds. |
| Backward Integration into Pump Assembly | In-house diaphragm production mitigates East Asian contract manufacturer concentration risk. |
| Reimbursement Strategy | State-level Medicaid HAPU metrics tie hospital payments to dynamic support surface procurement. |
Study Parameters
A spread of perspectives from biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and long-term care procurement directors converged on the working assumptions for this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EU MDR notified body submission databases, CMS Medicare reimbursement schedules, and hospital procurement contract repositories. Bottom-up unit economics triangulated against top-down spending estimates from integrated delivery network capital expenditure disclosures.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation modeled across device type, application area, end user, and material density tier. CAGRs derived from weighted average of historical procurement growth and forward-looking reimbursement policy trajectories. Forecast inputs incorporated polyether polyol price indices, Medicaid waiver program expansion timelines, and EU MDR transition completion rates by notified body.
Sensitivities concentrate around polyether polyol feedstock volatility, FDA guidance document revisions for software-as-medical-device classification, and state-level Medicaid reimbursement rate adjustments. Quarterly review of EU MDR certificate renewal queues, United States hospital capital budget approvals, and METI home medical equipment subsidy disbursements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Thrombectomy Devices Market
Medical Devices
Deaver Retractor Market
Medical Devices
Global Medical Device Labeling Market
Medical Devices
Global Dermatoscope Market
Medical Devices
Electrophysiology Ablation Market
Medical Devices
Veterinary Injectable Devices Market
Medical Devices
Cholesterol Monitors Market
Medical Devices
Microwave Ablation Devices Market
Medical Devices
Capsulotomy Market
Medical Devices
Pocket Otoscope Market
Medical Devices
North America Ablation Devices Market
Medical Devices
Surgical Incision Closure Devices Market
Medical Devices
Global Pulse Oximetry Market
Medical Devices
Portable Dialysis Machines Market
Medical Devices
Global Vein Finders Market
Medical Devices
High Frequency Chest-Wall Oscillation Devices Market