
 Home-Use Water Flosser Market | 2026-2036
Home-Use Water Flosser Market Size, Share, and Industry Trends Forecast 2026-2036
Home-Use Water Flosser Market Insights
Multi-source component procurement is recalibrating how home-use water flosser manufacturers balance cost against quality assurance. Waterpik leverages its captive injection-molding capacity in North America to protect margin pools on premium countertop units. Philips Sonicare competes through proprietary sonic motor architectures that reduce reliance on third-party pump suppliers. Panasonic Corporation anchors its position via integrated ceramic valve production at facilities in Japan, giving it tighter control over pressure consistency specifications.
A home-use water flosser is a powered oral hygiene appliance that directs pressurized pulsating or steady streams of water between teeth and below the gumline, typically operating at 10–100 psi to dislodge plaque and food debris without mechanical abrasion. The device serves consumers seeking alternatives to string floss, particularly those with braces, implants, or periodontal sensitivity. Cordless rechargeable models are capturing the fastest expansion as lithium-ion battery energy density improvements enable reservoir capacities above 200 mL in handheld form factors. Pulsating jet technology dominates unit economics due to simpler pump architectures and established repair ecosystems, though ultrasonic variants command premium positioning through reduced gingival irritation claims. Orthodontic patients represent a concentrated demand pool where tip compatibility and pressure control features directly influence repurchase rates.
The FDA regulates home-use water flossers as Class I medical devices under 21 CFR 872.5470, requiring adherence to good manufacturing practice standards without premarket notification for most configurations. The ADA Seal of Acceptance program shapes consumer trust and retail placement, with manufacturers submitting clinical efficacy data to the American Dental Association for evaluation. ISO 13485 quality management certification increasingly gates distribution through European pharmacy channels under the EU Medical Device Regulation framework. Stakeholders must monitor how evolving sustainability mandates from the EU Green Deal affect plastic-intensive reservoir and housing supply chains.
Market Dynamics
Orthodontic patient volumes and ADA guideline updates are restructuring demand composition for powered interdental cleaning, shifting channel economics toward dental professional endorsement as the primary trust mechanism.
Growth Catalysts
- ADA Seal of Acceptance:The American Dental Association's clinical evaluation program validates efficacy claims, unlocking pharmacy shelf placement and insurance reimbursement pathways for qualifying devices.
- Lithium-ion energy density gains:Battery chemistry improvements enable 200 mL-plus reservoir capacity in handheld cordless units, collapsing the performance gap with countertop systems.
- Orthodontic patient expansion:Rising clear aligner and fixed-brace volumes create concentrated demand pools where tip compatibility and pressure control drive repurchase decisions.
Market Restraints
- ABS plastic cost volatility:Reservoir and housing production faces input price swings tied to petrochemical feedstock markets, compressing margin buffers on economy-tier SKUs.
- Pump supplier concentration:Diaphragm and piston pump manufacturing clusters in select East Asian manufacturing zones, creating single-source vulnerability for mid-tier assemblers.
- String floss substitution persistence:Low-cost manual alternatives retain habitual use among price-sensitive demographics, limiting category conversion rates.
Strategic Opportunities
- EU Green Deal compliance:Sustainability mandates on plastic-intensive supply chains favor manufacturers with recycled-content reservoir programs and modular repair architectures.
- Periodontal sensitivity segments:Ultrasonic jet variants command premium positioning through reduced gingival irritation claims, opening clinical-channel partnerships.
- Direct-to-consumer subscription:Tip replenishment models bypass retail margin extraction while capturing predictable recurring revenue streams.
Industry Challenges
- ISO 13485 certification timelines:Quality management system audits for EU Medical Device Regulation compliance extend 12-18 months, gating pharmacy distribution access.
- Pressure calibration expertise:Ceramic valve specification and pulsation frequency tuning require specialized fluid dynamics talent scarce in consumer appliance engineering pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home-Use Water Flosser Market |
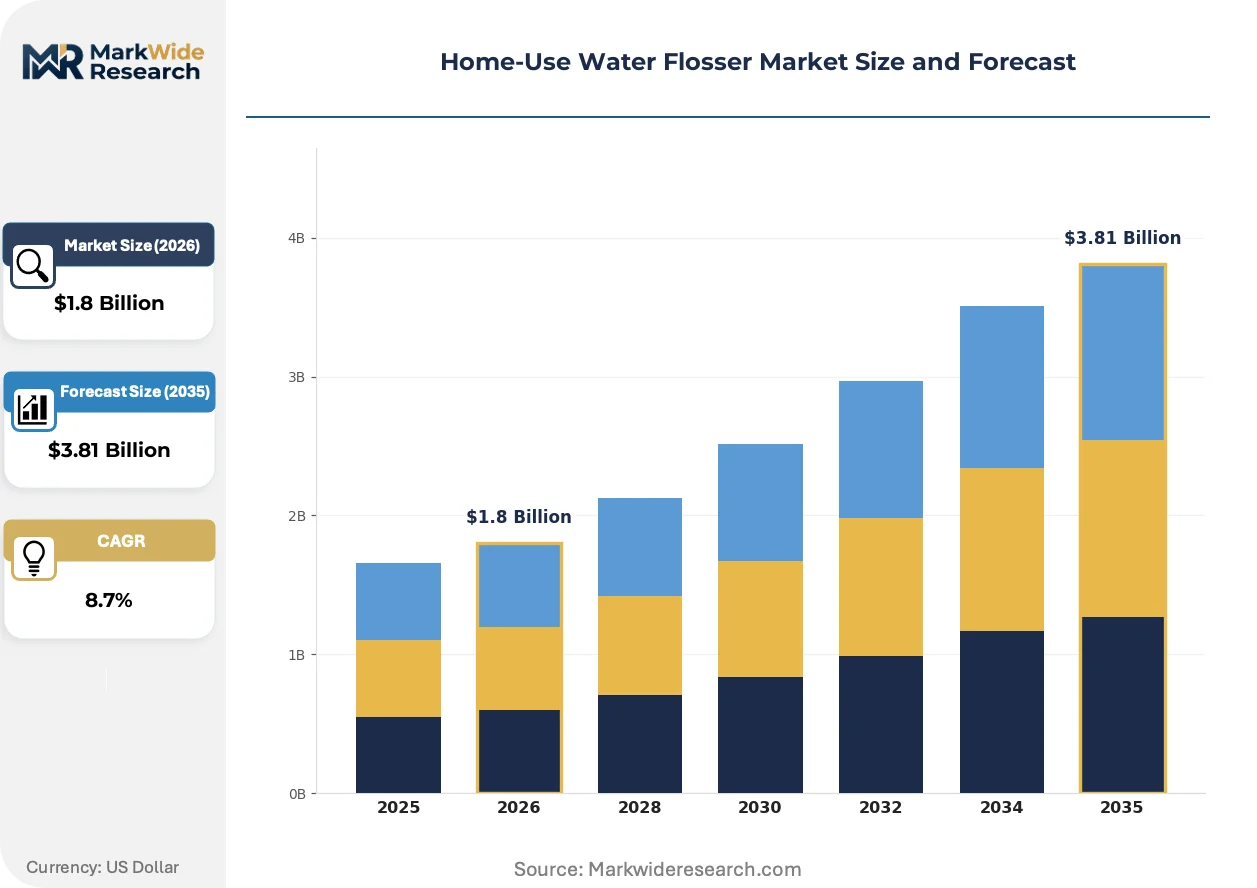
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Cordless, Rechargeable, Manual Technology: Pulsating Jet, Sonic, Ultrasonic, Rotary Feature: Water Pressure Control, Reservoir Capacity, Tip Compatibility, Auto Shut-off End User: Children, Adults, Seniors, Orthodontic Patients |
| Companies Covered | Waterpik, Philips Sonicare, Panasonic Corporation, Oral-B, Nicefeel, H2ofloss, Waterpulse, Hydro Floss, FlyCat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home-Use Water Flosser Market Trends and Innovations
Smart pressure modulation and sustainability-driven material transitions are redefining product architecture, while regulatory frameworks on medical device traceability reshape quality assurance investments.
Microprocessor-controlled pressure feedback is automating real-time pulsation adjustment based on gumline resistance detection. Orthodontic practices are piloting these systems for patient home-use compliance monitoring. The technology is automating the shift from fixed-pressure hardware toward adaptive therapeutic devices that reduce tissue trauma incidents.
EU Medical Device Regulation serialization requirements are mandating unique device identifiers on reservoir assemblies and handpiece components. Manufacturers must deploy track-and-trace infrastructure across Asian contract manufacturing partners. Cordless rechargeable lines face the steepest compliance cost escalation due to battery-cell integration complexity.
Subscription-based tip replenishment is displacing retail-driven replacement purchases among millennial and Gen Z household formations. Dental clinic waiting rooms have emerged as high-conversion discovery channels, with QR-code-activated enrollment capturing contact data for automated refill scheduling. Urban United States markets exhibit the highest subscription attach rates, correlating with direct-to-consumer brand awareness investments.
Home-Use Water Flosser Market Segmentation
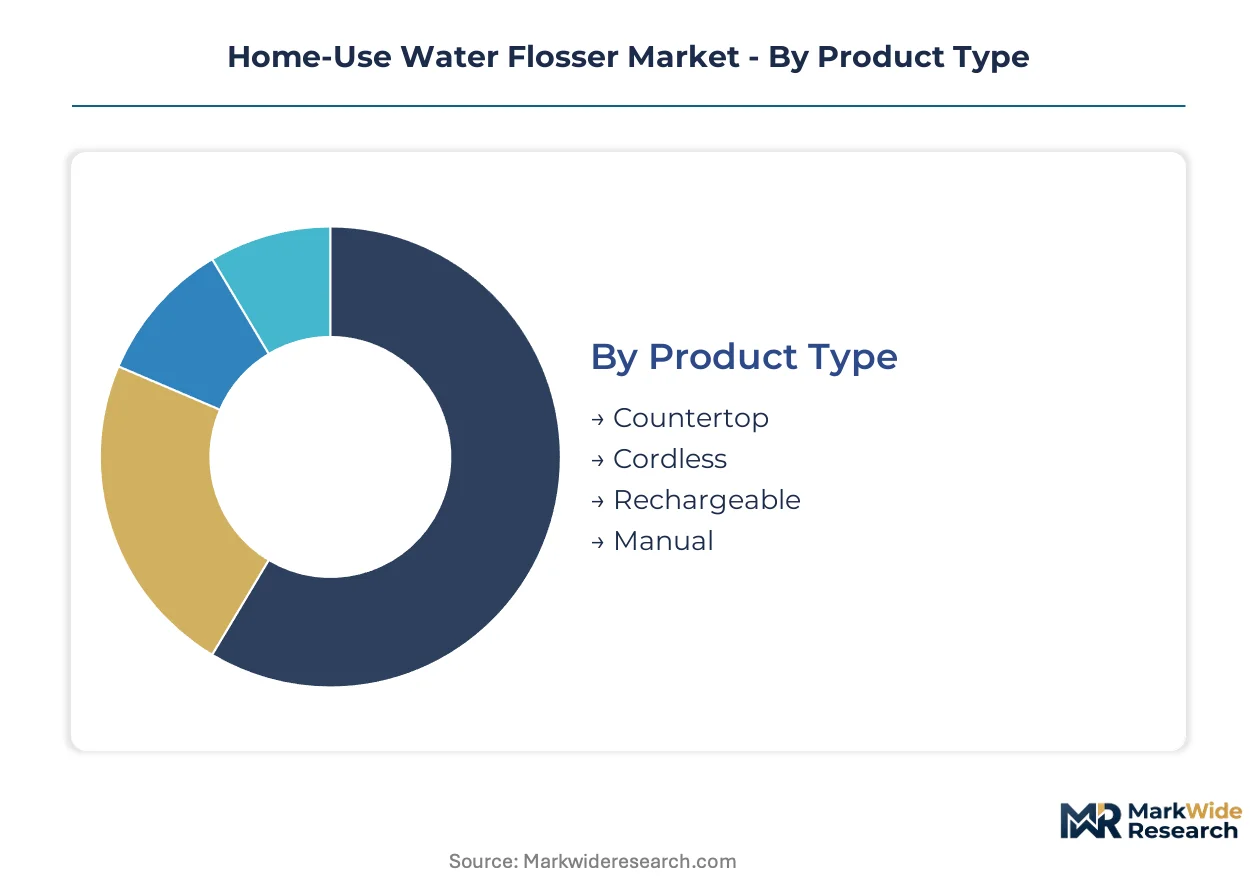
Segmentation in the home-use water flosser market determines which regulatory pathways manufacturers must navigate and which channel strategies unlock volume. Product architecture choices directly dictate FDA classification tiers, ADA Seal eligibility, and ISO 13485 audit scope.
Product Type:
FDA 21 CFR 872.5470 applies uniformly across all configurations, though countertop units face simpler quality management documentation while cordless rechargeable models trigger additional lithium-ion battery safety protocols under UN 38.3 transport regulations.
- Countertop:Mains-powered units with 600 mL-plus reservoirs dominate therapeutic-grade pressure output, typically 70-100 psi. Dental clinics in the United States recommend these for fixed-brace patients where sustained pulsation cycles matter. Demand clusters in suburban household formations with dedicated bathroom counter space.
- Cordless:Battery-dependent handheld units below 400 mL capacity sacrifice pressure consistency for portability. Lithium-ion energy density improvements above 250 Wh/kg now enable 45-minute operation cycles. Orthodontic teens represent the fastest-expanding user pool for school and travel use cases.
- Rechargeable:Docking-station designs with removable battery packs split the difference between countertop performance and cordless mobility. European pharmacy channels favor this architecture for MDR traceability compliance.
- Manual:Hand-pump mechanisms without electrical components fall outside FDA medical device classification, limiting reimbursement pathways but enabling mass-market price positioning.
Leading the category by volume: Countertop. Growing fastest: Cordless.
Technology:
Patent thickets and fluid dynamics expertise requirements create divergent margin profiles across technology platforms, with simpler pump architectures enabling economy-tier production and complex transducer systems defending premium positioning.
- Pulsating Jet:Diaphragm or piston pumps generate intermittent 10-100 psi streams through mechanical valving. Repair ecosystems and component standardization keep production costs contained. This platform anchors volume production for price-sensitive demographics.
- Sonic:Integrated motor-pump architectures leverage proprietary magnetic drive systems to reduce component count. Philips Sonicare's captive motor production in Southeast Asia illustrates how backward integration into drive system manufacturing protects margin pools.
- Ultrasonic:Piezoelectric transducers generate cavitation bubbles for plaque disruption below 10 psi, reducing gingival trauma claims. Clinical-channel partnerships in Germany and Japan favor this technology for periodontal sensitivity segments.
- Rotary:Centrifugal impeller designs create continuous laminar flow rather than pulsation, offering quieter operation at the cost of interdental penetration efficacy. Niche positioning targets shared-living environments.
Highest margin capture: Ultrasonic. Steepest volume expansion: Pulsating Jet.
Feature:
Feature bundling strategies separate pharmacy-grade positioning from mass retail, with ADA Seal eligibility requiring specific pressure control documentation and tip compatibility testing.
- Water Pressure Control:Microprocessor-modulated output with 3-10 discrete settings enables ADA efficacy submissions. FDA Class I exemptions still mandate pressure calibration records for units claiming therapeutic benefit.
- Reservoir Capacity:200 mL thresholds distinguish handheld from countertop classification in EU pharmacy channels. Modular reservoir designs support Green Deal compliance through recycled-content replacement programs.
- Tip Compatibility:Standardized Luer-lock or proprietary quick-connect systems determine accessory revenue capture. Subscription tip replenishment models favor proprietary interfaces.
- Auto Shut-off:Timer-based safety cutoffs address pediatric use liability concerns. This feature gates insurance reimbursement in select United States dental benefit plans.
Primary purchase driver: Water Pressure Control. Fastest-attaching subscription feature: Tip Compatibility.
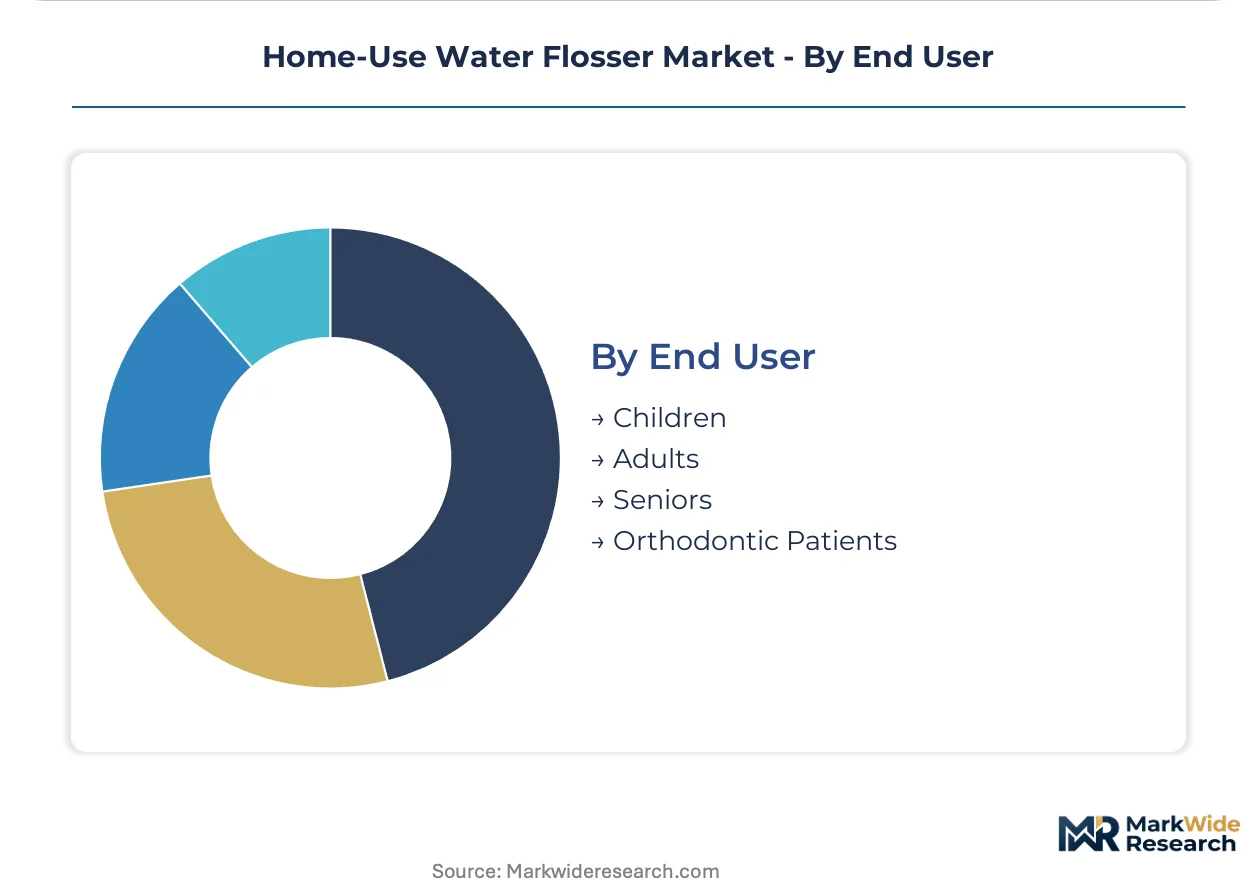
End User:
Demographic targeting reshapes regulatory emphasis, with pediatric claims triggering additional FDA scrutiny and orthodontic positioning requiring clinical trial documentation for ADA Seal consideration.
- Children:Units with 30 psi maximum output and colorful housing designs face CPSC toy safety overlays in addition to FDA medical device requirements. Parental purchase decisions prioritize auto shut-off and tip ejection safety mechanisms.
- Adults:The broadest segment spans preventive maintenance users to early periodontal disease management. ADA Seal recognition drives pharmacy channel placement for this demographic.
- Seniors:Arthritis-friendly grip geometries and large-button interfaces address dexterity limitations. Medicare Advantage plans in Florida and Arizona pilot reimbursement for prescribed units.
- Orthodontic Patients:Clear aligner and fixed-brace volumes create concentrated demand where tip compatibility with bracket systems determines repurchase rates. Dental professional endorsement serves as the primary trust mechanism.
Largest absolute volume: Adults. Fastest clinical-channel conversion: Orthodontic Patients.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for home-use water flossers concentrates in the United States, where ADA guideline updates and orthodontic patient volumes drive category expansion. Other developed markets follow with varying regulatory frameworks and channel structures.
United States
Orthodontic patient volumes and dental professional endorsement create concentrated demand pools in suburban household formations. The FDA regulates these devices as Class I medical devices under 21 CFR 872.5470, requiring good manufacturing practice adherence without premarket notification for most configurations. Manufacturing clusters in the Great Lakes region support captive injection-molding capacity for premium countertop units.
Germany
Periodontal sensitivity segments favor ultrasonic jet variants for reduced gingival irritation claims. The EU Medical Device Regulation mandates ISO 13485 quality management certification for pharmacy channel distribution, with serialization requirements for unique device identifiers. Industrial concentration in Baden-Württemberg supports precision ceramic valve production for pressure consistency specifications.
Japan
Integrated production of ceramic valves and compact form factors aligns with domestic preferences for bathroom appliance efficiency. The PMDA maintains alignment with international medical device standards while METI oversees industrial quality frameworks. Manufacturing facilities in the Chubu region anchor pressure calibration expertise for pulsation frequency tuning.
China
Domestic assembly capacity for diaphragm and piston pumps serves mid-tier global supply chains. NMPA medical device classification parallels FDA frameworks, enabling export-oriented production. Manufacturing zones in the Yangtze River Delta concentrate pump supplier networks, creating single-source vulnerability patterns for assemblers.
United Kingdom
Pharmacy channel placement depends on CE marking and adherence to EU-originated regulatory frameworks during post-Brexit transition periods. The MHRA maintains medical device oversight with continued reference to European harmonized standards. Distribution logistics concentrate in the Midlands corridor for retail and clinical channel fulfillment.
Home-Use Water Flosser Market Competitive Landscape
Backward integration into critical component manufacturing dominates the current landscape, with manufacturers securing captive supply of pumps, motors, and precision valves. The vendor base separates into three tiers: established oral care multinationals with dental professional channel access, mid-tier assemblers dependent on East Asian pump suppliers, and emerging direct-to-consumer brands leveraging subscription tip replenishment models. Strategic archetypes include vertical integrators defending margin pools, technology licensors extracting royalty streams, and platform aggregators capturing recurring revenue through consumable attachment. M&A activity and capacity expansion in North American injection-molding represent the dominant competitive moves.
Within the established multinational tier, Waterpik, Philips Sonicare, and Panasonic Corporation exemplify divergent defensive strategies. Waterpik anchors the North American premium countertop segment through captive manufacturing infrastructure. Philips Sonicare occupies a position defined by proprietary drive system architectures that reduce supplier dependency. Panasonic Corporation represents the integrated production model with domestic Japanese facilities controlling critical valve specifications. These three entities collectively illustrate how component-level backward integration, magnetic drive system ownership, and ceramic valve production each defend margin pools against commodity assemblers.
| Leading Market Players |
|---|
| Waterpik |
| Philips Sonicare |
| Panasonic Corporation |
| Oral-B |
| Nicefeel |
| H2ofloss |
| Waterpulse |
| Hydro Floss |
| FlyCat |
| Others |
Pricing and Supply Chain Analysis
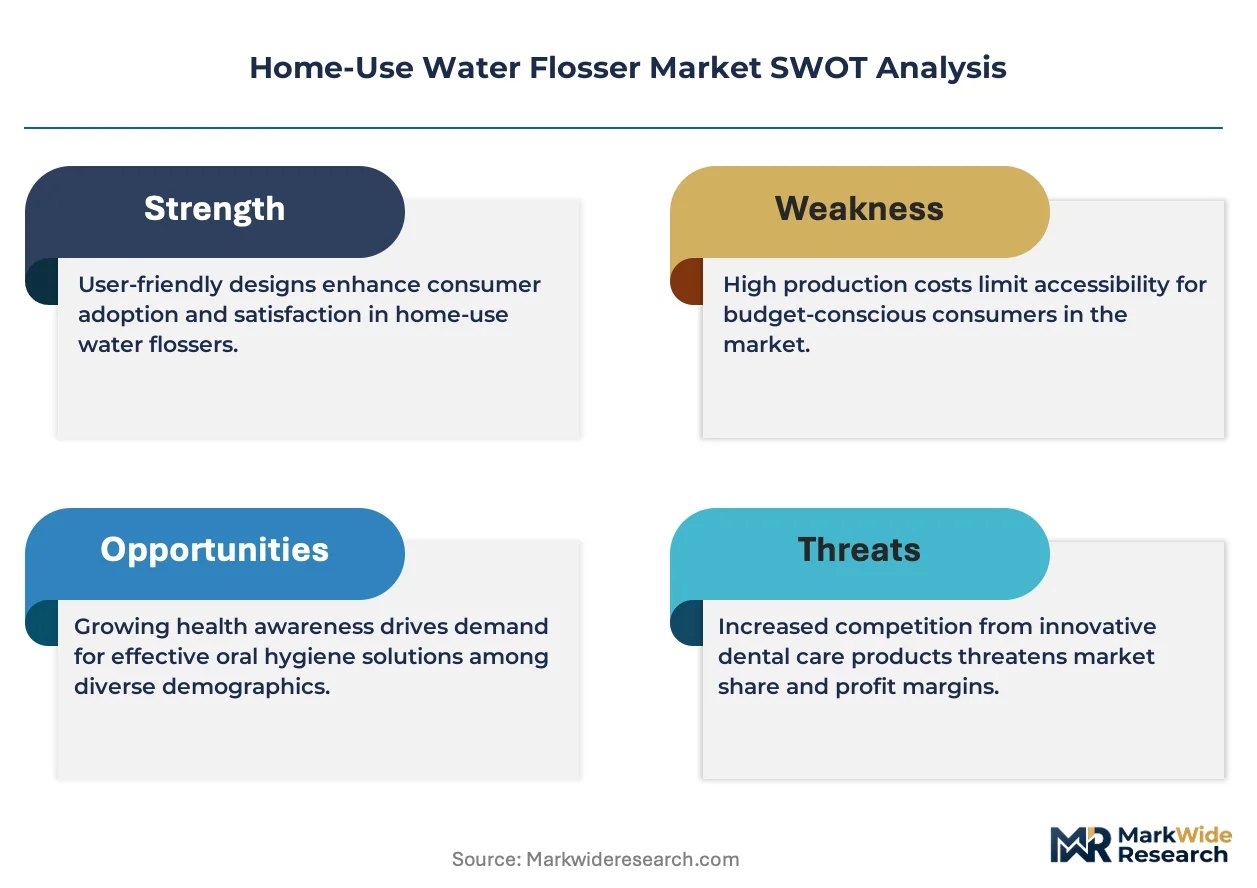
Acrylonitrile butadiene styrene (ABS) resin price volatility cascades through injection-molding supply chains into three distinct pricing tiers for home-use water flosser manufacturers, with petrochemical feedstock swings compressing margin buffers on economy-tier SKUs while premium countertop units retain pricing power through captive North American production.
Pricing Analysis
Volume production concentrates in pulsating jet configurations where repair ecosystems and component standardization enable economy positioning, while ultrasonic variants capture premium-mid-economy pricing differentiation through clinical-channel partnerships in Germany and Japan. Price differentiation hinges on ADA Seal certification status and reservoir capacity thresholds, with ISO 13485 compliance adding audit-cost premiums to pharmacy-grade units. Pricing pressure stems from lithium-ion battery cell integration complexity in cordless lines, elevating BOM costs faster than countertop alternatives. Price-sensitive demographics in mass retail channels resist conversion from manual floss, while orthodontic patient segments show lowest sensitivity due to dental professional endorsement.
Supply Chain Analysis
EU Green Deal domestic-content mandates on plastic-intensive reservoirs are reshaping sourcing toward recycled-content programs and modular repair architectures, forcing manufacturers to requalify Asian contract partners. Pump component manufacturing clusters in China, South Korea, and Japan, with diaphragm and piston production concentrated in Yangtze River Delta zones. Raw material dependencies include ABS resin for housings, lithium-ion cells for cordless power systems, and precision ceramic substrates for pressure valves. Single-source vulnerability runs through East Asian pump supplier networks. Distribution runs through dental professional channels for therapeutic-grade units and mass retail for consumer-positioned lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The home-use water flosser market operates as a cost-of-compliance story where EU Medical Device Regulation ISO 13485 certification timelines create 12-18 month barrier-to-entry moats, advantaging incumbents with established quality management infrastructure over aspirant entrants lacking pharmacy channel access.
For Market Incumbents: Acquire captive injection-molding capacity in North America to protect margin pools on premium countertop units against ABS cost volatility. Secure backward integration into ceramic valve production to defend pressure calibration expertise against fluid dynamics talent scarcity. Expand direct-to-consumer subscription tip replenishment models to bypass retail margin extraction and capture predictable recurring revenue. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting millennial and Gen Z household formations in urban United States markets where brand awareness investments correlate with highest attach rates. Exploit white-space in ultrasonic jet variants for periodontal sensitivity segments, opening clinical-channel partnerships in Germany and Japan where reduced gingival irritation claims command premium positioning. Target orthodontic teen travel-use cases with compact cordless designs. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier assemblers with pump supplier diversification programs in East Asian manufacturing zones, where single-source vulnerability creates acquisition targets with fixable supply chain architectures. Long-term viability over a 5-10 year window rests on EU Green Deal compliance infrastructure and MDR traceability systems. Watch lithium-ion energy density improvements above 250 Wh/kg as the signal for cordless lines collapsing the performance gap with countertop systems.| Strategic Initiative | Industry Significance |
|---|---|
| ADA Seal Certification Investment | Unlocks pharmacy shelf placement and insurance reimbursement pathways for qualifying devices. |
| Backward Integration into Ceramic Valve Production | Protects pressure consistency specifications against fluid dynamics talent scarcity in consumer appliance engineering. |
| Direct-to-Consumer Subscription Launch | Captures predictable recurring revenue through tip replenishment models bypassing retail margin extraction. |
| EU Green Deal Compliance Program | Enables recycled-content reservoir programs and modular repair architectures for pharmacy channel access. |
| Smart Pressure Modulation Development | Automates real-time pulsation adjustment for orthodontic practice compliance monitoring partnerships. |
Research Methodology
Independent corroboration across dental clinic procurement managers, biomedical engineers at orthodontic practices, GPO contracts administrators, and retail category buyers underwrites the qualitative findings in this study. Primary interviews with fluid dynamics specialists and injection-molding operations directors combined with secondary validation from FDA 510(k) filings, ADA Seal submission databases, EU MDR notified body records, and customs trade data on ABS resin imports. Bottom-up unit shipment estimates triangulate against top-down value projections across product type, technology platform, and end-user segmentation.
Comparable historical reference periods anchored the forecast window to pre-pandemic orthodontic patient volume baselines and post-MDR implementation regulatory compliance cost structures. The analytical framework models countertop, cordless, rechargeable, and manual product architectures alongside pulsating jet, sonic, ultrasonic, and rotary technologies, with end-user splits across children, adults, seniors, and orthodontic patients. CAGRs derive from pressure calibration expertise scarcity curves and lithium-ion energy density improvement trajectories as industry-specific forecast inputs.
ABS resin price volatility, pump supplier concentration in East Asian zones, and ADA guideline update timing are the dominant revision risks that could alter trajectory assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Artificial Organs and Bionic Implants Market
Medical Devices
Italy Aesthetic Devices Market
Medical Devices
Speech Generating Devices Market
Medical Devices
Global Robotic Nurse Assistant Market
Medical Devices
Global Thoracic Drainage Devices Market
Medical Devices
Italy Contraceptive Devices Market
Medical Devices
Biological Microscope Market
Medical Devices
Global Scleral Lens Market
Medical Devices
Asia-Pacific Breast Biopsy Market
Medical Devices
Ventilation Devices Market
Medical Devices
US Neurothrombectomy Devices Market
Medical Devices
Prescription Goggles Market
Medical Devices
Cardiac Poc Testing Devices Market
Medical Devices
Novel Vaccine Delivery Systems Market
Medical Devices
Dual Chamber Prefilled Syringes Market
Medical Devices
UK Surgical Devices Market