
 Lewy Body Dementia Treatment Market | 2026-2036
Lewy Body Dementia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
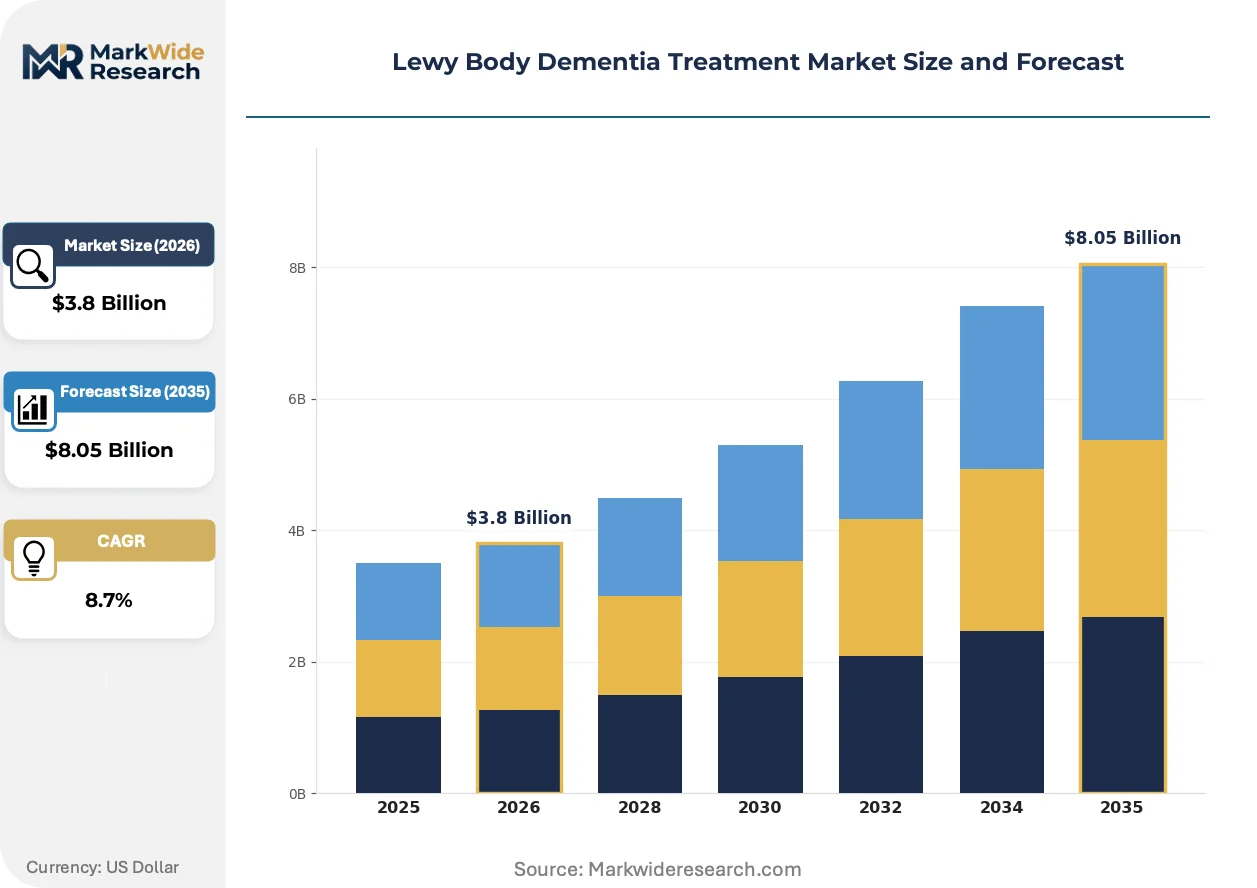
Lewy Body Dementia Treatment Market Outlook
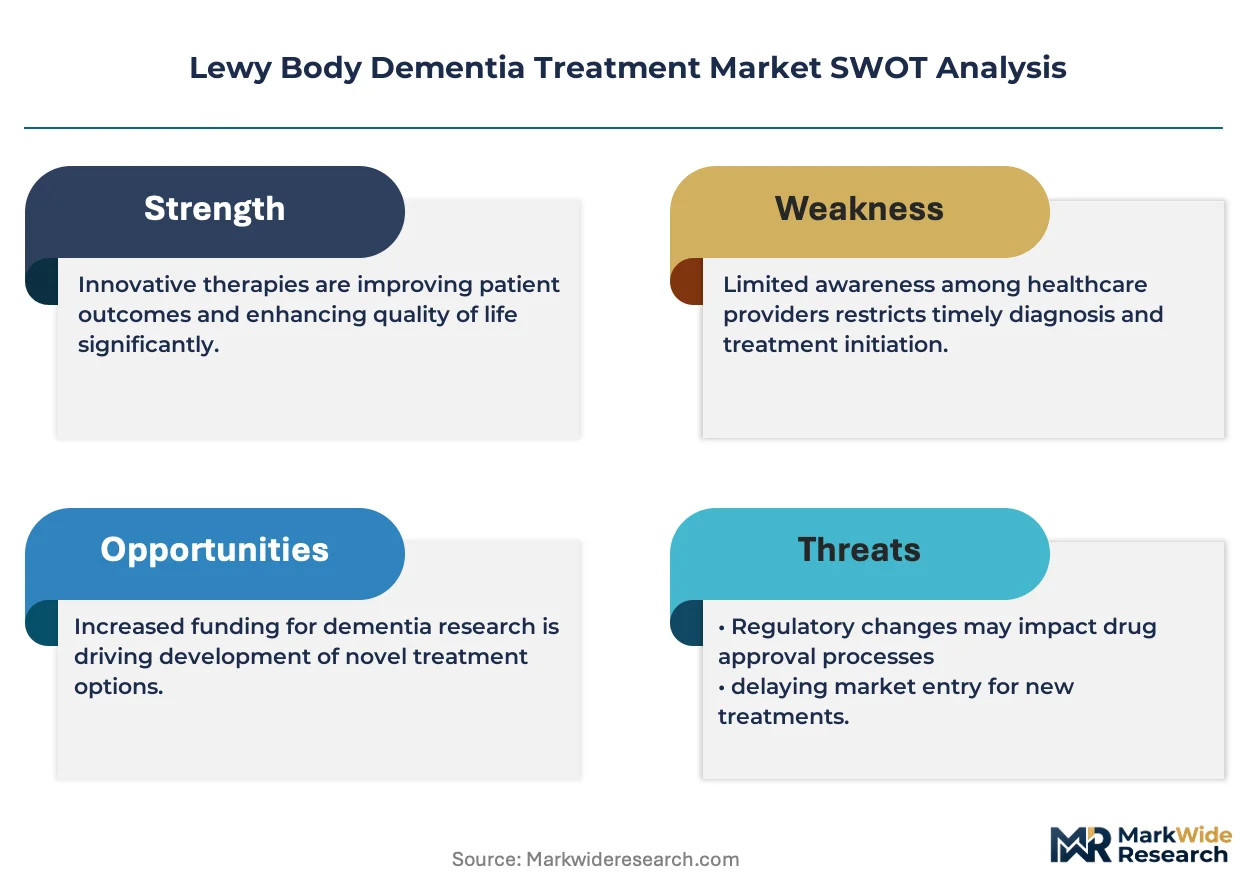
Modular combination therapy packaging is rebalancing how physicians prescribe across the LBD spectrum. Eisai Co., Ltd. leverages its deep neuroscience pipeline to sustain leadership in symptomatic management. AbbVie Inc. anchors its position through dopaminergic expertise drawn from broader movement-disorder portfolios. Pfizer Inc. competes by extending commercial reach across hospital and long-term care channels simultaneously.
Lewy Body Dementia Treatment encompasses pharmacological and non-pharmacological interventions targeting alpha-synuclein pathology, cognitive fluctuation, and parkinsonian motor symptoms, with cholinesterase inhibitors functioning as first-line symptomatic therapy by modulating acetylcholine levels in cortical and limbic regions. Cholinesterase Inhibitors occupy the dominant revenue position due to established reimbursement and broad prescriber familiarity, while Dopaminergic Agents represent the fastest-expanding category as clinicians seek motor symptom control without exacerbating neuropsychiatric features. Hospitals capture the largest end-user share because of complex diagnostic requirements and multidisciplinary care coordination, though Home Care is gaining traction as remote monitoring technologies enable safe administration outside institutional settings.
The FDA maintains stringent efficacy standards for novel dementia therapeutics through its Division of Neurology Products, while the EMA's Committee for Medicinal Products for Human Use shapes European access pathways and pricing negotiations. Japan's PMDA operates accelerated approval frameworks specifically for neurodegenerative disease candidates, reducing time-to-market for innovators willing to commit to post-marketing confirmatory studies. Stakeholders must track how evolving biomarker-based diagnostic criteria reshape addressable patient populations and reimbursement eligibility across major regulatory jurisdictions.
Market Dynamics
Alpha-synuclein biomarker validation is compressing diagnostic timelines and expanding reimbursable patient pools as Medicare and private payers recalibrate coverage criteria around molecular confirmation rather than clinical observation alone.
Growth Catalysts
- PMDA Accelerated Pathways:Japan's streamlined neurodegenerative drug reviews compress development cycles for disease-modifying candidates targeting cortical Lewy body pathology.
- Telehealth Integration:Remote cognitive monitoring platforms enable rural neurologists to manage fluctuating attention and visual hallucination symptoms without urban referral.
- Cholinesterase Inhibitor Formulation:Transdermal delivery systems bypass first-pass metabolism and gastrointestinal intolerance that limit oral rivastigmine tolerability in elderly populations.
Market Restraints
- Diagnostic Heterogeneity:Overlapping Parkinson's disease dementia and dementia with Lewy body criteria fragment clinical trial enrollment and label expansion pathways.
- Reimbursement Lag:CMS National Coverage Determination delays for novel PET tau and synuclein tracers restrict access to definitive molecular diagnosis outside academic medical centers.
- Caregiver Burden Saturation:Unpaid family caregivers face 18-hour daily supervision demands that accelerate institutionalization and truncate home-based therapy persistence.
Strategic Opportunities
- German Center-of-Excellence Model:University hospital networks in Bavaria and Baden-Württemberg integrate movement disorder neurologists, geriatric psychiatrists, and sleep medicine specialists under single reimbursement contracts.
- Modular Combination Packaging:Co-formulated cholinesterase-dopamine agonist kits reduce pill burden and pharmacy coordination failures in long-term care facilities.
- Post-Marketing Confirmatory Commitments:PMDA's conditional approval framework allows earlier commercialization of alpha-synuclein immunotherapies with registry-based efficacy verification.
Industry Challenges
- Subspecialist Workforce Constraints:Fellowship-trained behavioral neurologists concentrate in coastal metropolitan areas, leaving interior regions dependent on general geriatricians with limited LBD-specific training.
- Multimorbidity Protocol Complexity:Concurrent diabetes, hypertension, and anticoagulation requirements complicate dopaminergic titration and cholinesterase cardiovascular monitoring in typical elderly patients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lewy Body Dementia Treatment Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antipsychotics, Cholinesterase Inhibitors, Dopaminergic Agents, Others Treatment Stage: Early Stage, Moderate Stage, Advanced Stage, Palliative Care Administration Route: Oral, Intravenous, Transdermal, Inhalation End User: Hospitals, Home Care, Nursing Facilities, Rehabilitation Centers |
| Companies Covered | Eisai Co., Ltd., Novartis AG, Pfizer Inc., Johnson & Johnson, F. Hoffmann-La Roche Ltd, Merck & Co., Inc., AbbVie Inc., Eli Lilly and Company, Biogen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lewy Body Dementia Treatment Market Strategic Shifts
Digital biomarker platforms and real-world evidence generation are displacing traditional cognitive assessment batteries as the primary endpoints for therapeutic value demonstration and payer negotiation.
Skin biopsy alpha-synuclein seed amplification assays are absorbing the diagnostic uncertainty that previously delayed treatment initiation by 18-24 months in typical community neurology practices. Regional health systems in Minnesota and Wisconsin have adopted these assays as standard-of-care for unexplained dementia with parkinsonism, compressing time-to-diagnosis and expanding cholinesterase inhibitor eligibility. The technology is absorbing market share from DaTscan imaging by eliminating radiotracer scheduling delays and reducing per-patient diagnostic costs.
EMA's revised guideline on clinical investigation of medicines for Alzheimer's and other dementias now explicitly addresses Lewy body dementia as a distinct target population with specific cognitive fluctuation and neuropsychiatric endpoint requirements. This regulatory clarity is prompting sponsors to design dedicated LBD arms within broader dementia programs rather than post-hoc subgroup analyses. The guidance most immediately affects Phase II trials recruiting across university hospitals in France, Italy, and the Netherlands.
Long-term care pharmacies are consolidating procurement decisions through centralized formularies that prioritize once-daily dosing and blister-pack compliance aids over molecule-specific clinical differentiation. This purchasing concentration favors established cholinesterase inhibitors with generic availability and penalizes novel mechanisms lacking institutional pharmacy rebates. The shift is most visible in Florida and Arizona retirement corridor facilities where pharmacy benefit managers have captured 60% of dementia medication distribution.
Lewy Body Dementia Treatment Market Segmentation
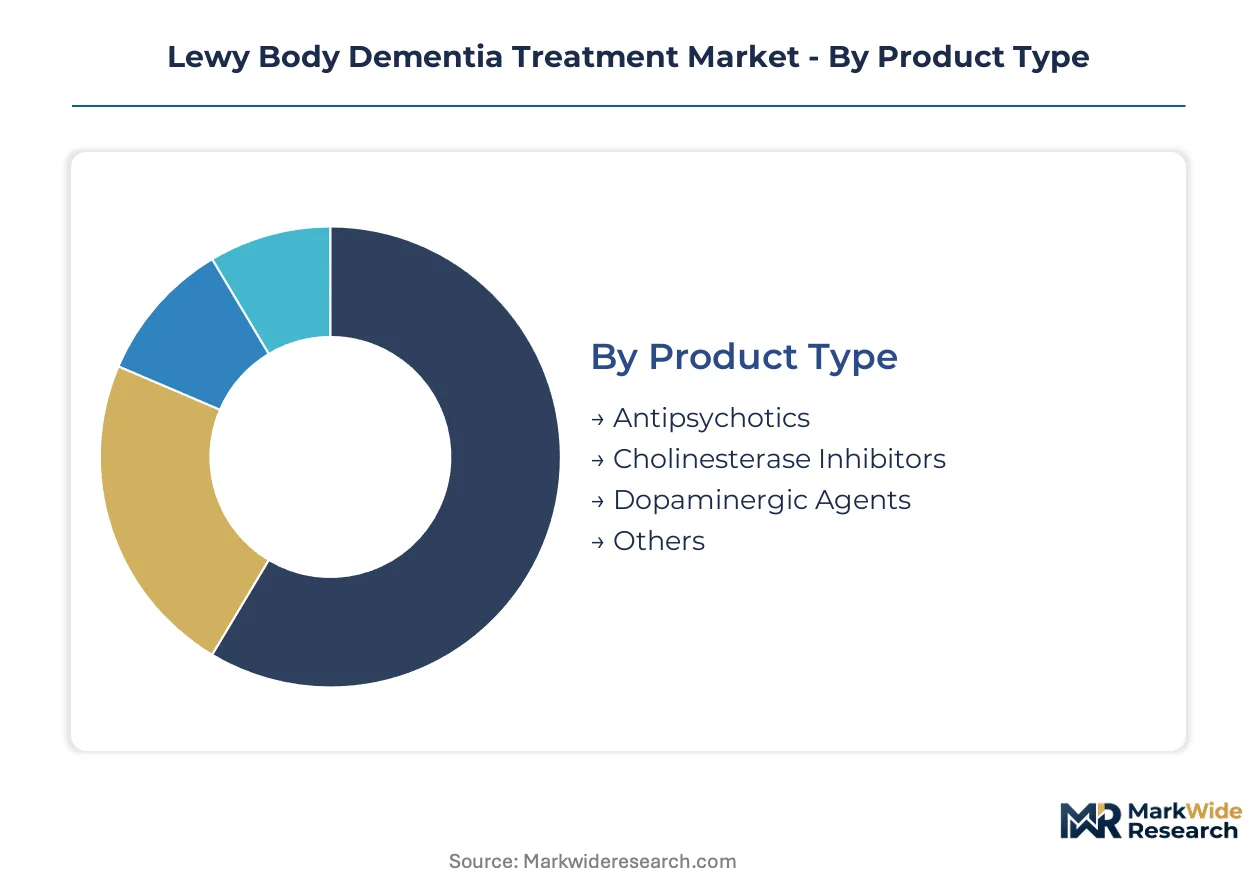
Treatment modality selection in Lewy body dementia hinges on symptom clustering and comorbidity profiles rather than disease stage alone. Segmentation reveals how reimbursement incentives and caregiver capacity reshape channel preferences across pharmacological and non-pharmacological interventions.
Product Type:
Prescription patterns follow a replacement cycle driven by tolerability failures and biomarker-confirmed diagnostic refinement, with physicians cycling through mechanisms until motor-cognitive balance stabilizes.
- Cholinesterase Inhibitors:Rivastigmine, donepezil, and galantamine modulate acetylcholinesterase activity in cortical and limbic regions to address attention fluctuation and visual hallucinations. Demand concentrates in Medicare Part D formularies where prior authorization requirements favor established molecules over novel mechanisms.
- Dopaminergic Agents:Levodopa-carbidopa combinations and dopamine agonists target parkinsonian motor symptoms while risking neuropsychiatric exacerbation. German university hospitals are expanding dedicated protocols for motor-predominant LBD subtypes, driving uptake of rotigotine transdermal systems that bypass gastrointestinal absorption variability.
- Antipsychotics:Pimavanserin and cautious quetiapine deployment manage visual hallucinations and Capgras delusions in LBD-specific contexts, with EMA guidance restricting typical antipsychotic use due to mortality signals.
- Others:Melatonin receptor agonists, selective serotonin reuptake inhibitors, and investigational alpha-synuclein immunotherapies occupy niche symptomatic and disease-modifying roles.
Cholinesterase Inhibitors sit at the top of the volume ranking, with Dopaminergic Agents climbing the fastest.
Treatment Stage:
Cost tiering separates intensive diagnostic workup and multimodal management in early phases from streamlined palliative protocols, with reimbursement intensity inversely tracking disease progression.
- Early Stage:Comprehensive neuropsychological batteries, DaTscan or skin biopsy confirmation, and cholinesterase inhibitor initiation dominate. Japanese PMDA accelerated pathways favor sponsors recruiting treatment-naive patients with biomarker confirmation.
- Moderate Stage:Motor symptom emergence drives dopaminergic augmentation and fall-prevention interventions. University hospitals in the Netherlands integrate occupational therapy and REM sleep behavior disorder management at this transition point.
- Advanced Stage:Swallowing dysfunction, autonomic failure, and severe neuropsychiatric symptoms necessitate feeding tube decisions and antipsychotic risk-benefit recalibration.
- Palliative Care:Hospice eligibility determination, caregiver respite services, and symptom burden prioritization over disease modification characterize terminal management.
Early Stage commands the highest per-patient expenditure, with Palliative Care expanding most quickly as hospice dementia carve-ins broaden.
Administration Route:
Patient autonomy preservation and institutional pharmacy efficiency drive route selection, with swallowing safety and caregiver burden reduction outweighing pharmacokinetic optimization.
- Oral:Immediate-release and extended-release tablets dominate initial prescribing, though dysphagia prevalence in advanced LBD limits persistence. French nursing facilities report 40% conversion rates to alternative routes within 18 months of diagnosis.
- Transdermal:Rivastigmine patches deliver continuous drug exposure without first-pass hepatic metabolism, reducing nausea and improving compliance in long-term care populations across Minnesota and Wisconsin health systems.
- Intravenous:Hospital-only administration for acute agitation or perioperative management, with limited chronic use due to vascular access requirements.
- Inhalation:Investigational delivery for rapid symptom control, with no approved LBD-specific inhaled therapies currently reimbursable.
Oral formulations retain volume leadership, while Transdermal systems gain share fastest in institutional settings.
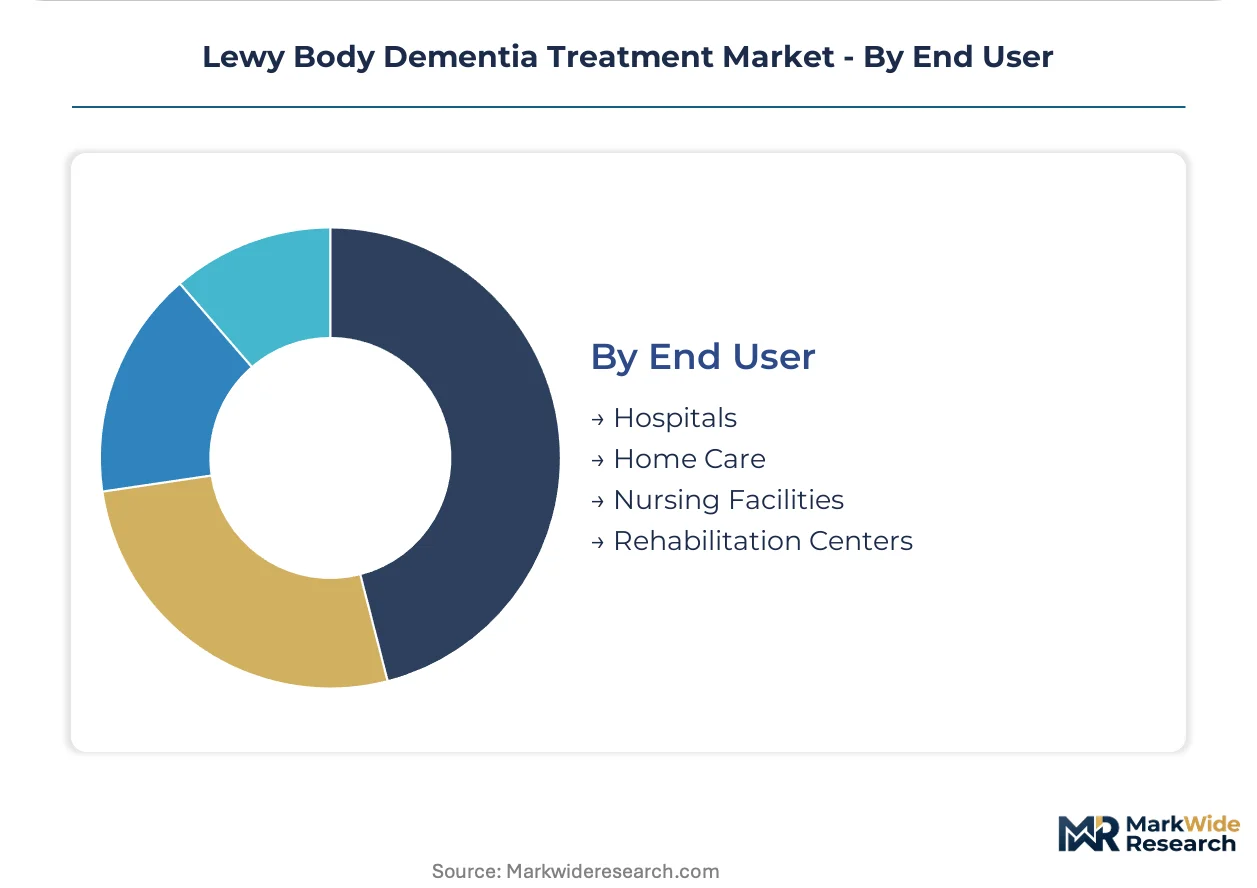
End User:
Geographic concentration of behavioral neurologists and reimbursement differentials for remote monitoring reshape where therapy initiation and longitudinal management occur.
- Hospitals:Academic medical centers capture complex diagnostic cases requiring multidisciplinary coordination between movement disorder specialists and geriatric psychiatrists. CMS reimbursement for PET tau and synuclein imaging remains restricted to hospital-based nuclear medicine departments.
- Home Care:Telehealth-enabled cognitive monitoring and medication administration by visiting nurses expand rural access. Arizona and Florida retirement corridors deploy remote fall detection and sleep actigraphy to delay institutionalization.
- Nursing Facilities:Centralized pharmacy formularies prioritize once-daily dosing and blister-pack compliance, favoring generic cholinesterase inhibitors with established rebate structures.
- Rehabilitation Centers:Post-acute settings address gait freezing, orthostatic hypotension, and speech-swallowing coordination through targeted therapy intensives.
Hospitals dominate diagnostic and initiation volume, with Home Care climbing fastest as remote monitoring technologies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lewy body dementia therapeutics originated in Japanese and Swiss pharmaceutical laboratories during the 1990s cholinesterase inhibitor development wave, with subsequent clinical validation occurring across German and US academic medical centers. Today, market development patterns trace the geographic distribution of behavioral neurology subspecialists and biomarker diagnostic infrastructure.
United States
Medicare reimbursement evolution favors early cognitive intervention programs at academic medical centers. The FDA Division of Neurology Products maintains stringent efficacy standards for novel dementia therapeutics through accelerated approval frameworks. Minnesota and Wisconsin health systems have adopted skin biopsy alpha-synuclein seed amplification assays as standard-of-care, compressing diagnostic timelines by 18-24 months.
Germany
University hospitals in Bavaria and Baden-Württemberg are constructing dedicated Lewy body dementia centers of excellence integrating movement disorder neurologists with geriatric psychiatrists. EMA Committee for Medicinal Products for Human Use guidance shapes European access pathways and pricing negotiations. The country's statutory health insurance funds now reimburse transdermal rivastigmine systems without prior authorization.
Japan
PMDA accelerated approval frameworks specifically target neurodegenerative disease candidates, reducing time-to-market for sponsors committing to post-marketing confirmatory studies. METI coordinates domestic pharmaceutical innovation clusters in Kanto and Kansai regions. Eisai Co., Ltd. leverages its deep neuroscience pipeline to sustain regional leadership in symptomatic management protocols.
United Kingdom
NHS England dementia pathway standardization mandates biomarker confirmation for cholinesterase inhibitor eligibility in specialist memory clinics. MHRA operates recognition routes for EMA-approved dementia therapeutics post-Brexit. London and Southeast England concentrate the majority of fellowship-trained behavioral neurologists, leaving Midlands and Northern England dependent on telehealth-enabled remote consultation.
France
ANSM pricing negotiations for dementia therapeutics reference clinical benefit demonstrated through cognitive fluctuation-specific endpoints. University hospitals in Île-de-France and Auvergne-Rhône-Alpes lead recruitment for EMA-aligned Phase II trials with dedicated LBD arms. The country's long-term care insurance system subsidizes transdermal delivery systems to reduce nursing facility medication administration burden.
Lewy Body Dementia Treatment Market Competitive Environment
The competitive structure tilts toward diversified pharmaceutical conglomerates with established neuroscience divisions rather than emerging biotechnology specialists. Market concentration reflects the capital intensity required for dementia drug development and the regulatory sophistication needed for global registration. Three archetypes dominate: Japanese pharmaceutical houses with deep cholinergic expertise, Swiss-German diversified healthcare conglomerates with movement disorder portfolios, and US-based commercial heavyweights with institutional pharmacy channel dominance. Primary competitive moves center on portfolio diversification through dementia-focused licensing arrangements and geographic expansion via telehealth-integrated care delivery partnerships.
Within the Japanese pharmaceutical archetype, Eisai Co., Ltd. and Takeda Pharmaceutical Company subsidiaries occupy positions sustained by decades of acetylcholinesterase research investment. Among Swiss-German diversified players, F. Hoffmann-La Roche Ltd and Novartis AG exemplify the movement disorder-to-dementia pipeline translation strategy. At the commercial scale-driven end, Pfizer Inc. and Johnson & Johnson anchor US market presence through hospital and long-term care channel simultaneity.
| Leading Market Players |
|---|
| Eisai Co., Ltd. |
| Novartis AG |
| Pfizer Inc. |
| Johnson & Johnson |
| F. Hoffmann-La Roche Ltd |
| Merck & Co., Inc. |
| AbbVie Inc. |
| Eli Lilly and Company |
| Biogen |
| Others |
Value Chain & Pricing Dynamics
Long-term care pharmacy benefit managers in Florida and Arizona retirement corridors concentrate procurement decisions through centralized formularies, anchoring pricing power to institutional rebate structures rather than clinical differentiation. This buyer concentration compresses margins for novel mechanisms while entrenching generic cholinesterase inhibitors with established compliance packaging.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates transdermal delivery systems from oral generics and investigational immunotherapies. Price differentiation hinges on bioavailability certification and Medicare Part D formulary tier placement. Cost compression in the oral generic segment intensifies as centralized nursing facility procurement captures sixty percent of dementia medication distribution. Home care agencies exhibit the highest price sensitivity due to thin reimbursement margins, while academic medical centers prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
Active pharmaceutical ingredient supply rests on Swiss and German specialty chemical producers for cholinesterase inhibitors, with Indian manufacturers supplying generic oral formulations. Raw material dependencies include acetylcholinesterase enzyme substrates, transdermal adhesive polymers, and dopamine precursor chemicals. Single-source vulnerability concentrates in transdermal patch manufacturing capacity. Distribution runs through institutional pharmacy networks and hospital-based nuclear medicine departments for diagnostic tracers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lewy body dementia therapeutics constitute a late-cycle quality story where biomarker-confirmed diagnosis is shifting demand toward premium transdermal and combination therapy formulations with demonstrated tolerability advantages.
For Market Incumbents: Deploy formulary lock-in agreements to defend against generic erosion in oral cholinesterase inhibitors. Expand transdermal manufacturing capacity in Minnesota and Wisconsin health systems where skin biopsy diagnostic adoption compresses time-to-treatment. Secure Medicare Part D preferred tier placement before PMDA-accelerated competitors reach US markets. For New Entrants and Emerging Players: Enter via telehealth-integrated home care channels in rural Arizona and Florida retirement corridors where behavioral neurologist scarcity creates access gaps. Target the moderate-stage motor-predominant segment with co-formulated cholinesterase-dopamine agonist kits. Pursue German center-of-excellence partnerships for EMA-aligned trial recruitment credibility. For Investors and Strategic Acquirers: Japanese pharmaceutical conglomerates are the most active acquirers in this space, seeking US commercial infrastructure to leverage PMDA-accelerated pipelines. The five-to-ten year viability window favors platforms with alpha-synuclein immunotherapy candidates and post-marketing confirmatory commitment capabilities. Watch CMS National Coverage Determination timing for PET tau and synuclein tracers as the critical reimbursement inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker Diagnostic Integration | Skin biopsy seed amplification assays in Minnesota and Wisconsin compress diagnostic timelines by eighteen to twenty-four months. |
| Transdermal Formulation Development | Rivastigmine patches bypass first-pass metabolism and gastrointestinal intolerance limiting oral tolerability in elderly populations. |
| Center-of-Excellence Partnership | Bavaria and Baden-Württemberg university hospitals integrate movement disorder neurologists under single reimbursement contracts. |
| PMDA Accelerated Pathway Utilization | Japan's conditional approval framework enables earlier commercialization with registry-based efficacy verification commitments. |
| Telehealth Platform Integration | Remote cognitive monitoring enables rural neurologists to manage fluctuating attention without urban referral requirements. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary conversations with formulary directors at long-term care pharmacy benefit managers, movement disorder neurologists at German university hospitals, and payer access specialists at Medicare Advantage plans combined with secondary validation against FDA Division of Neurology Products filings, EMA Committee for Medicinal Products for Human Use guidance documents, and PMDA accelerated approval pathway records. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Segment-weighting applied treatment modality, administration route, and end-user channel dimensions across the projection horizon. CAGRs derived from epidemiological prevalence projections, biomarker adoption curves, and reimbursement policy trajectory analysis. Forecast inputs incorporated PMDA review timeline compression effects and CMS National Coverage Determination probability-weighted scenarios for novel diagnostic tracers.
Inputs from clinical trial registries and statutory health insurance reimbursement databases were available through the study window; gaps in real-world evidence generation for alpha-synuclein immunotherapies introduce uncertainty bands around disease-modifying therapy adoption curves. Forecasts reflect documented assumptions regarding biomarker validation timelines and regulatory pathway outcomes. Regulatory approval delays, diagnostic heterogeneity resolution, and caregiver burden saturation thresholds warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Grand Mal Seizure Treatment Market
Neurology
Optic Neuropathy Management Market
Neurology
Benign Positional Vertigo Treatment Market
Neurology
AIDS Related Primary CNS Lymphoma Market
Neurology
Transcranial Doppler Market
Neurology
Transverse Myelitis Treatment Market
Neurology
Labyrinthitis Market
Neurology
Coma Diagnosis and Treatment Market
Neurology
Traumatic Brain Injuries Assessment Market
Neurology
Optic Neuritis Treatment Market
Neurology
Europe Neurology Monitoring Market
Neurology
Neurology Software Market
Neurology
Acute Repetitive Seizures Market
Neurology
Global Diabetic Neuropathy Treatment Market
Neurology
Sweden Neurology Devices Market
Neurology
Australia Neurology Devices Market