
 Global Total Wrist Replacement Market | 2026-2036
Global Total Wrist Replacement Market Size, Share, and Industry Trends Forecast 2026-2036
Global Total Wrist Replacement Market Foresight
Implant maintenance and revision service contracts are rebalancing how orthopedic vendors capture lifetime value from each wrist arthroplasty patient. Zimmer Biomet leverages its extensive field service network to sustain long-term implant surveillance programs. Stryker Corporation anchors its competitive position through proprietary instrument sets and surgeon training ecosystems.
Total wrist replacement denotes the surgical substitution of the radiocarpal and midcarpal joints with a mechanical prosthesis, typically comprising a radial metal component and a carpal polyethylene or ceramic insert designed to restore range of motion and relieve pain in end-stage wrist arthritis. Modular prosthesis designs dominate current surgical preference due to intraoperative adaptability and reduced revision complexity, while cementless implant variants represent the fastest-growing technology segment as osseointegration surfaces improve fixation durability. Metal-on-polyethylene bearing couples retain the largest installed base, though cross-linked polyethylene formulations are displacing conventional liners in premium device tiers.
The FDA's 510(k) premarket notification framework governs device clearance in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for European market access. Japan's PMDA maintains distinct biocompatibility testing protocols that extend registration timelines for foreign manufacturers. Stakeholders must monitor evolving post-market surveillance mandates and reimbursement thresholds across these jurisdictions to anticipate shifts in competitive positioning.
Market Dynamics
Modular prosthesis architectures are compressing revision timelines and reconfiguring how orthopedic vendors structure implant lifecycle economics around each wrist arthroplasty patient.
Growth Catalysts
- Cementless fixation surfaces:Osseointegration coatings on radial metal components eliminate cement-related complications and reduce secondary revision rates in primary wrist replacement procedures.
- Japan's PMDA biocompatibility protocols:Streamlined equivalence pathways for ceramic-polyethylene bearing couples accelerate foreign manufacturer entry into high-volume Japanese orthopedic centers.
- Specialty orthopedic clinics:Dedicated wrist arthroplasty centers concentrate surgical volume and standardize implant selection protocols across high-throughput US and German markets.
Market Restraints
- Titanium alloy supply concentration:Aerospace and medical grade titanium sourcing clusters in limited US and Japanese smelter networks, exposing implant manufacturers to input price volatility.
- EU Medical Device Regulation clinical evidence thresholds:Stricter post-market surveillance and PMCF study requirements extend European market access timelines by 18-24 months for novel carpal component designs.
- Ankle and shoulder arthroplasty substitution:Alternative joint replacement procedures compete for limited orthopedic surgeon training bandwidth and hospital capital allocation.
Strategic Opportunities
- Underpenetrated Indian market:Rising diabetes-related wrist arthropathy incidence and expanding private hospital networks create first-mover positioning for cementless implant portfolios.
- Remote implant monitoring platforms:Digital radiographic surveillance systems enable proactive revision scheduling and recurring service revenue streams outside traditional sales cycles.
- Cross-linked polyethylene formulations:Advanced liner materials reduce wear debris generation and open premium tier positioning for extended-warranty implant contracts.
Industry Challenges
- Hand and wrist fellowship pipeline constraints:Limited accredited training programs restrict qualified surgeon availability for complex revision wrist arthroplasty procedures.
- ISO 5832 biomaterial certification complexity:Multi-jurisdictional testing requirements for novel cobalt-chrome alloys delay product launch sequencing across FDA, PMDA, and Health Canada pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Total Wrist Replacement Market |
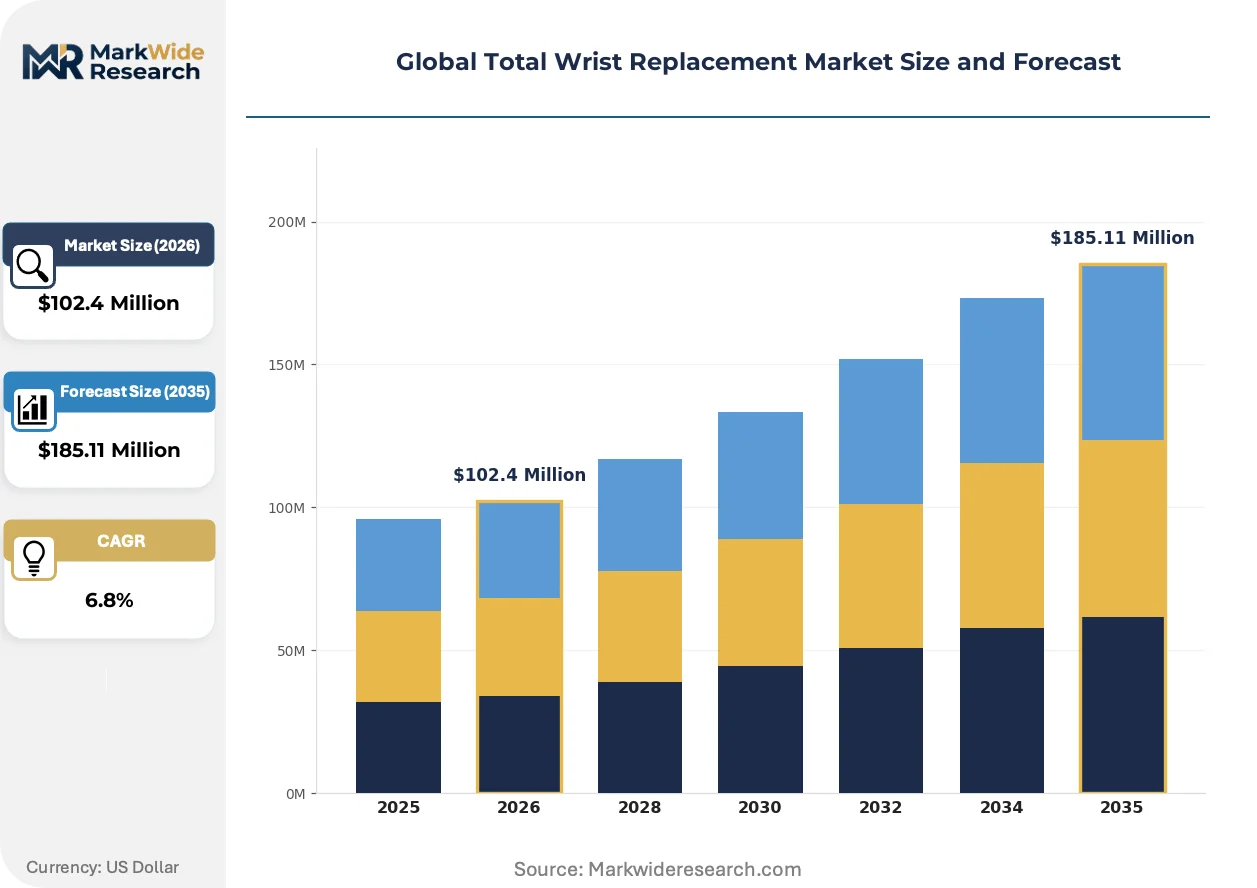
| Market Size in 2026 | $102.4 Million |
| Market Size in 2035 | $185.11 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Prosthesis, Cemented Implant, Cementless Implant, Hybrid Implant Technology: Metal-on-Polyethylene, Ceramic-on-Ceramic, Metal-on-Metal, Cross-linked Polyethylene Application: Rheumatoid Arthritis, Osteoarthritis, Post-Traumatic Arthritis, Avascular Necrosis End User: Specialty Orthopedic Clinics, Ambulatory Surgery Centers, Rehabilitation Facilities, Orthopedic Hospitals |
| Companies Covered | Zimmer Biomet, Stryker Corporation, Smith & Nephew, DePuy Synthes, Integra LifeSciences Corporation, Arthrex, Acumed LLC, Enovis, MicroPort Orthopedics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Total Wrist Replacement Market Shifts & Advancements
Digital preoperative planning platforms and patient-specific instrumentation are compressing operative time variability and standardizing implant positioning accuracy across heterogeneous surgeon experience levels.
Patient-specific 3D-printed surgical guides derived from preoperative CT datasets are automating radial component resection angle selection and reducing intraoperative fluoroscopy exposure. High-volume orthopedic centers in Germany and the United States deploy these guides for complex revision cases where native anatomy is distorted. The technology is automating operative workflow standardization previously dependent on individual surgeon tacit knowledge.
The EU Medical Device Regulation's Unique Device Identification mandates and enhanced post-market clinical follow-up requirements are restructuring how implant manufacturers organize vigilance data collection. European notified bodies now demand systematic registry participation for wrist arthroplasty cohorts. Premium device tiers face disproportionate documentation burdens as manufacturers stratify portfolio submissions by clinical evidence depth.
Hospital procurement committees are consolidating implant vendor contracts and unbundling instrument set ownership from device pricing. Integrated delivery networks in the United States negotiate multi-year sole-source agreements covering primary and revision wrist replacement systems. This concentration is most visible in tertiary referral centers where orthopedic service line administrators prioritize standardization over surgeon-specific brand preferences.
Global Total Wrist Replacement Market Segmentation
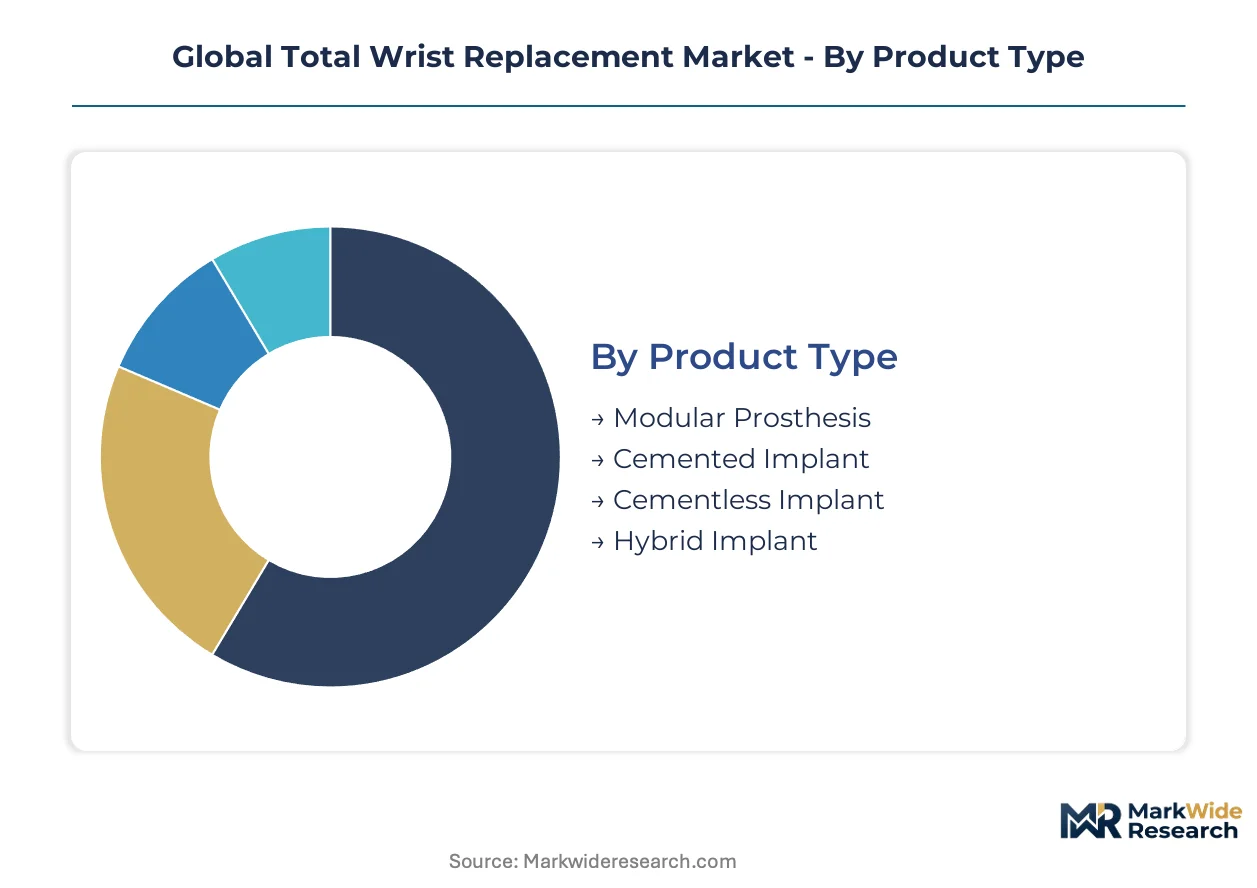
Total wrist replacement segmentation reveals how implant economics stratify across fixation philosophies, bearing technologies, and care delivery settings. Supply concentration in titanium alloy networks and polyethylene resin channels directly shapes which product configurations achieve commercial scale.
Product Type:
Titanium alloy sourcing clusters in US and Japanese smelter networks, concentrating manufacturing capacity for specific fixation architectures.
- Modular Prosthesis:Radial metal components and interchangeable carpal inserts enable intraoperative adaptability to distorted anatomy. Demand concentrates in German and US tertiary centers where revision volume justifies inventory investment. Osseointegration surface improvements on radial stems are compressing revision timelines for this configuration.
- Cementless Implant:Porous-coated radial components achieve biological fixation without bone cement, eliminating cement-related complications in primary procedures. Japanese orthopedic centers drive adoption as PMDA equivalence pathways streamline foreign manufacturer entry. This architecture gains share fastest among younger, active patients.
- Cemented Implant:Polymethylmethacrylate fixation remains prevalent in elderly populations with compromised bone quality.
- Hybrid Implant:Combines cemented radial stems with cementless carpal components for selective fixation.
Today's leader: Modular Prosthesis. Tomorrow's challenger: Cementless Implant.
Technology:
Cross-linked polyethylene formulations are displacing conventional liners as hospital procurement committees prioritize extended-warranty contracts.
- Metal-on-Polyethylene:Cobalt-chrome radial heads articulate against ultra-high-molecular-weight polyethylene carpal inserts, retaining the largest installed base. US specialty orthopedic clinics standardize on this couple for primary procedures where cost containment dominates procurement criteria. Wear debris generation remains the primary long-term failure mode.
- Cross-linked Polyethylene:Irradiated and thermally treated liner materials reduce oxidative degradation and wear rates versus conventional polyethylene. German high-volume centers deploy these bearings for complex revision cases where implant longevity is paramount. Premium tier positioning enables recurring service revenue through extended surveillance contracts.
- Ceramic-on-Ceramic:Alumina or zirconia bearing surfaces eliminate metal ion release concerns in metal-sensitive patients.
- Metal-on-Metal:Large-diameter articulations now restricted to salvage indications following adverse local tissue reaction concerns.
Cross-linked Polyethylene is climbing the fastest, though Metal-on-Polyethylene retains volume dominance through procurement standardization.
Application:
Rheumatoid arthritis patient volumes in US and German rheumatology-orthopedics integrated practices anchor primary wrist arthroplasty demand.
- Rheumatoid Arthritis:Systemic inflammatory destruction of radiocarpal joints creates predictable deformity patterns amenable to modular prosthesis correction. Specialty orthopedic clinics in the United States concentrate this surgical volume through dedicated hand and wrist fellowship programs. Biologic therapy advances are delaying but not eliminating surgical candidacy.
- Osteoarthritis:Degenerative wear of the scapholunate articulation progresses to pancarpal involvement in older populations. German orthopedic hospitals report expanding case volume as patient expectations for preserved wrist motion rise. Post-traumatic osteoarthritis represents a substantial referral stream from workers compensation networks.
- Post-Traumatic Arthritis:Intra-articular fracture sequelae produce asymmetric joint destruction requiring patient-specific instrumentation.
- Avascular Necrosis:Scaphoid or lunate osteonecrosis advances to carpal collapse in specific demographic risk profiles.
Rheumatoid Arthritis anchors current procedural volume. Osteoarthritis presents the steepest expansion trajectory as population aging accelerates.
End User:
Integrated delivery networks in the United States are consolidating vendor contracts around sole-source agreements that privilege high-throughput facilities.
- Specialty Orthopedic Clinics:Dedicated hand and wrist centers achieve surgical volume thresholds that justify dedicated instrument sets and surgeon training ecosystems. These facilities in Germany and the United States standardize implant selection protocols across attending staff. Digital preoperative planning platforms deploy most intensively in this setting.
- Ambulatory Surgery Centers:Freestanding surgical facilities capture select primary wrist arthroplasty cases meeting stringent patient selection criteria. US outpatient reimbursement policies are expanding case eligibility for cementless implant procedures with reduced anesthesia requirements. Capital equipment constraints limit complex revision access.
- Orthopedic Hospitals:Tertiary referral centers manage revision case complexity and fellowship training obligations.
- Rehabilitation Facilities:Post-acute settings coordinate implant surveillance and functional outcome monitoring.
Specialty Orthopedic Clinics dominate current value capture. Ambulatory Surgery Centers are gaining share fastest as case selection criteria broaden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production and registration strategies toward jurisdictions where 510(k) equivalence pathways compress time-to-market versus EU MDR clinical evidence burdens. Manufacturers now sequence FDA clearance ahead of European notified body submissions to capture revenue earlier in product lifecycles.
United States
Specialty orthopedic clinics in urban corridors drive procedural concentration through dedicated hand and wrist fellowship programs. FDA 510(k) premarket notifications govern device clearance with streamlined predicate-based reviews. Hospital procurement committees in tertiary centers negotiate multi-year sole-source agreements that privilege standardized implant protocols over surgeon-specific preferences.
Germany
High-volume orthopedic hospitals anchor European wrist arthroplasty demand through integrated rheumatology-orthopedics practices treating inflammatory joint destruction. EU Medical Device Regulation imposes stricter post-market surveillance and PMCF study requirements that extend market access timelines. The Baden-Württemberg and Bavaria clusters concentrate digital preoperative planning platform deployment for complex revision cases.
Japan
PMDA biocompatibility testing protocols create distinct registration pathways that foreign manufacturers navigate for ceramic-polyethylene bearing couple approvals. Tokyo and Osaka metropolitan areas concentrate surgical volume in academic medical centers with established arthroplasty registries. Streamlined equivalence pathways for specific bearing technologies accelerate market entry relative to full clinical trial requirements.
India
Rising diabetes-related wrist arthropathy incidence expands addressable patient populations in private hospital networks across Maharashtra and Karnataka. CDSCO medical device regulations are evolving toward risk-based classification systems that align with international harmonization efforts. Metro hospital chains in Mumbai and Bengaluru build dedicated hand surgery units that standardize cementless implant selection protocols.
Global Total Wrist Replacement Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated orthopedic conglomerates controlling premium-tier pricing through proprietary instrument ecosystems while regional fabricators compete on procurement standardization. The vendor base concentrates around three archetypes: full-line orthopedic multinationals with field service networks, mid-tier extremity-focused specialists, and emerging Asia-Pacific manufacturers leveraging cost-optimized production. Dominant competitive moves include hospital vendor contract consolidation and surgeon training ecosystem investments that lock in protocol standardization.
Among full-line orthopedic conglomerates, Zimmer Biomet and Stryker Corporation exemplify the integrated-service archetype through extensive field infrastructure and long-term implant surveillance programs. Smith & Nephew occupies a position within the extremity-specialist tier, representing mid-scale players that concentrate portfolio depth over breadth. These three anchors illustrate how competitive positioning stratifies between scale-driven service integration and focused clinical application expertise.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Stryker Corporation |
| Smith & Nephew |
| DePuy Synthes |
| Integra LifeSciences Corporation |
| Arthrex |
| Acumed LLC |
| Enovis |
| MicroPort Orthopedics |
| Others |
Supply & Pricing Matrix
Titanium alloy spot pricing on the London Metal Exchange cascades through orthopedic implant manufacturing into three distinct procurement tiers: premium ceramic-polyethylene bearing couples for academic medical centers, standard metal-on-polyethylene configurations for integrated delivery networks, and economy cemented implants for cost-constrained ambulatory surgery centers. Hospital procurement committees exploit this raw material transparency to negotiate multi-year sole-source contracts that lock in volume discounts against aerospace-grade titanium supply volatility.
Pricing Analysis
Distributor margins of 15-25 percent on instrument sets separate premium-tier vendors from direct-to-hospital contract manufacturers. Price differentiation hinges on FDA 510(k) predicate lineage and extended-warranty service bundling, with cross-linked polyethylene formulations commanding 40 percent premiums over conventional liners. Pricing pressure stems from GPO consolidation in US tertiary centers, compressing margins fastest for mid-tier extremity specialists. Ambulatory surgery centers exhibit highest price sensitivity, while German high-volume orthopedic hospitals prioritize implant longevity over acquisition cost.
Supply Chain Analysis
Titanium alloy feedstock rests on US and Japanese smelter networks, concentrating forging capacity for radial metal components in Pittsburgh and Osaka industrial corridors. Cobalt-chrome casting draws from German precision foundries, while ultra-high-molecular-weight polyethylene resin sources from Belgian and Saudi petrochemical complexes. Single-source vulnerability pervades aerospace-grade titanium sponge, where defense contractor offtake agreements crowd medical allocation. Distribution runs through orthopedic specialty distributors with consigned instrument set inventory, extending vendor working capital requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Medical Device Regulation's PMCF study mandates compound competitive advantage for incumbents with established clinical registries, accelerating demand concentration toward vendors with systematic post-market surveillance infrastructure.
For Market Incumbents: Deploy long-term implant surveillance contracts to lock hospital system loyalty against emerging Asia-Pacific manufacturers. Cementless fixation surface R&D investment defends premium positioning as PMDA equivalence pathways lower Japanese market entry barriers for foreign competitors. Backward integration into titanium alloy forging capacity insulates margin compression from aerospace demand spikes.
For New Entrants and Emerging Players: Capture underpenetrated Indian private hospital networks through diabetes-related wrist arthropathy screening partnerships with endocrinology practices. Maharashtra and Karnataka metro chains offer lowest competitive density for cementless implant portfolios. Direct-to-hospital pricing models bypass distributor markups that disadvantage new market entrants against established GPO relationships.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale extremity specialists possessing ceramic-polyethylene bearing couples already cleared through PMDA biocompatibility protocols. Long-term viability favors targets with surgeon training ecosystems rather than pure device manufacturers. Watch FDA 510(k) clearance velocity for novel carpal component designs as inflection signal for competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Multi-year sole-source agreements with integrated delivery networks lock procurement standardization against surgeon brand preferences. |
| CE Marking Pathway | EU MDR clinical evidence requirements extend timelines but create regulatory moats for systematic registry participants. |
| Software Companion Development | Digital preoperative planning platforms automate radial component positioning and reduce operative time variability. |
| Reimbursement Strategy | CMS outpatient procedure code expansion for cementless implants broadens ambulatory surgery center eligibility. |
| Backward Integration | In-house titanium alloy forging capacity insulates margin pressure from aerospace demand competition. |
Research Methodology
Bottom-up wrist arthroplasty procedural volume modeling reconciled against top-down orthopedic implant manufacturing capacity tracking forms the analytical core of this study. Primary interviews with hand and wrist fellowship directors, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers combined with secondary validation against FDA 510(k) premarket notification databases, EU EUDAMED vigilance records, PMDA approval summaries, and hospital procurement contract disclosures. Triangulation across these sources ensures segmentation integrity across fixation philosophy, bearing technology, and end-user facility type.
Historical trendline analysis of wrist replacement procedural volumes and implant pricing trajectories informed projection modeling across the analysis window. Segmentation dimensions include prosthesis architecture, bearing couple composition, primary versus revision indication, and care delivery setting. CAGRs derive from regression analysis of procedural growth rates, implant ASP evolution, and geographic market penetration patterns. Forecast inputs incorporate rheumatoid arthritis prevalence projections, diabetes-related arthropathy incidence curves, and orthopedic surgeon fellowship pipeline constraints.
Regulatory timeline delays, titanium alloy price volatility, and surgeon training program expansion failures are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions about 510(k) clearance velocity, EU MDR notified body capacity, and Japanese equivalence pathway stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Middle East and Africa Refractive Surgery Devices Market
Medical Devices
Tumour Ablation Devices Market
Medical Devices
Capsulotomy Market
Medical Devices
Heel Pressure Injury Relieving Devices Market
Medical Devices
Latin America Breast Biopsy Needle Market
Medical Devices
Global Traumatic Brain Injury Assessment and Management Devices Market
Medical Devices
Global Wedge Pressure Catheter Market
Medical Devices
US Mechanical Ventilator Market
Medical Devices
Hydrogel Contact Lenses Market
Medical Devices
Asia Pacific Portable X-Ray Devices Market
Medical Devices
Global Cranial Fixation and Stabilization Systems Market
Medical Devices
Bone Densitometer Devices Market
Medical Devices
Cardioscope Market
Medical Devices
Vascular Guidewires Market
Medical Devices
Hearing Devices 3D Printing Market
Medical Devices
Global Medical Device Cleaning Market