
 Global Bone Cement Market | 2026-2036
Global Bone Cement Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bone Cement Market Analysis
Antibiotic-loaded formulation standards is bifurcating the competitive landscape into premium validated tiers and commodity non-PMA grades. Stryker Corporation leverages its orthopedic systems integration to sustain high switching costs across hospital accounts. Zimmer Biomet anchors its position through geographic dominance in European joint reconstruction markets. DePuy Synthes differentiates via R&D intensity in next-generation biodegradable cements.
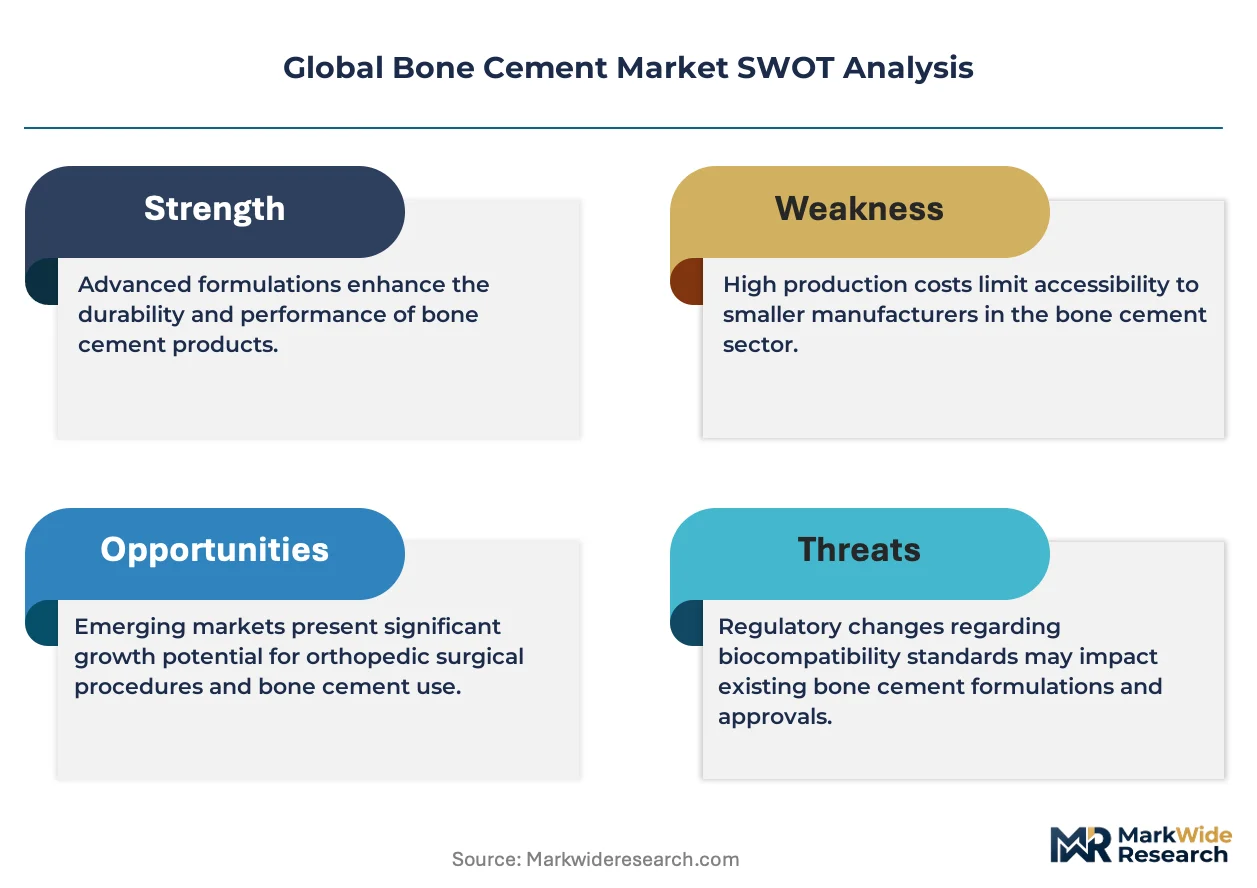
Bone cement is a polymethyl methacrylate-based biomaterial formulated with liquid monomer and powdered polymer components that polymerize in situ to achieve interdigitation with cancellous bone, typically achieving compressive strength of 70-90 MPa upon curing. Its primary purpose is to fix orthopedic implants to bone and deliver localized antibiotic prophylaxis in load-bearing arthroplasty procedures. Antibiotic-loaded cements command the dominant margin pool due to infection prevention value in revision surgery cases. Joint replacement applications lead volume absorption while spine surgery represents the fastest-growing procedural segment. Ambulatory surgical centers are reshaping distribution economics by demanding smaller kit formats and direct vendor-managed inventory.
FDA PMA pathways govern permanent implant cement categories in the United States, while Europe's MDR and ISO 5833 standards enforce biocompatibility and mechanical performance benchmarks for market access. These frameworks elevate validation costs for entrants but protect incumbent positions through clinical data requirements. Stakeholders must monitor how CMS reimbursement shifts toward outpatient settings reshape procurement specifications and channel preferences.
Market Dynamics
Antibiotic-loaded cement formulations are bifurcating procurement specifications across hospital systems, with permanent implant grades commanding premium positioning against commodity alternatives as infection prevention protocols tighten in arthroplasty.
Growth Catalysts
- MDR clinical data mandates:Europe's Medical Device Regulation elevates validation requirements for permanent implant cements, protecting incumbent positions through clinical evidence barriers.
- Ambulatory surgical center expansion:United States outpatient arthroplasty volumes are concentrating demand for smaller kit formats and vendor-managed inventory solutions.
- Revision surgery infection protocols:Hospital antibiotic stewardship programs are mandating prophylactic cement use in load-bearing joint reconstruction cases.
Market Restraints
- Methyl methacrylate monomer volatility:Petrochemical feedstock fluctuations compress margin predictability for PMMA-based formulations.
- PMA pathway capital intensity:FDA premarket approval requirements for permanent implant cements impose multi-million-dollar validation burdens on new entrants.
- Ceramic-on-ceramic bearing substitution:Cementless fixation alternatives in hip arthroplasty are capturing select patient cohorts with sufficient bone quality.
Strategic Opportunities
- Indian joint reconstruction penetration:Underpenetrated hip and knee replacement volumes in tier-2 and tier-3 cities offer expansion corridors for standard-grade formulations.
- Spine surgery application growth:Vertebral augmentation and tumor stabilization procedures are emerging as high-margin procedural segments.
- Biodegradable cement R&D convergence:Osteoconductive resorbable formulations combining calcium phosphate with PMMA matrices address revision surgery bone stock preservation needs.
Industry Challenges
- Polymerization reaction control:Exothermic curing profiles require precise operating room temperature management to prevent thermal necrosis in adjacent tissue.
- ISO 5833 mechanical compliance:Compressive strength and fatigue resistance certification timelines extend product development cycles by 18-24 months.
- Antibiotic elution kinetics standardization:Inconsistent release rate testing protocols across notified bodies complicate multi-market registration strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bone Cement Market |
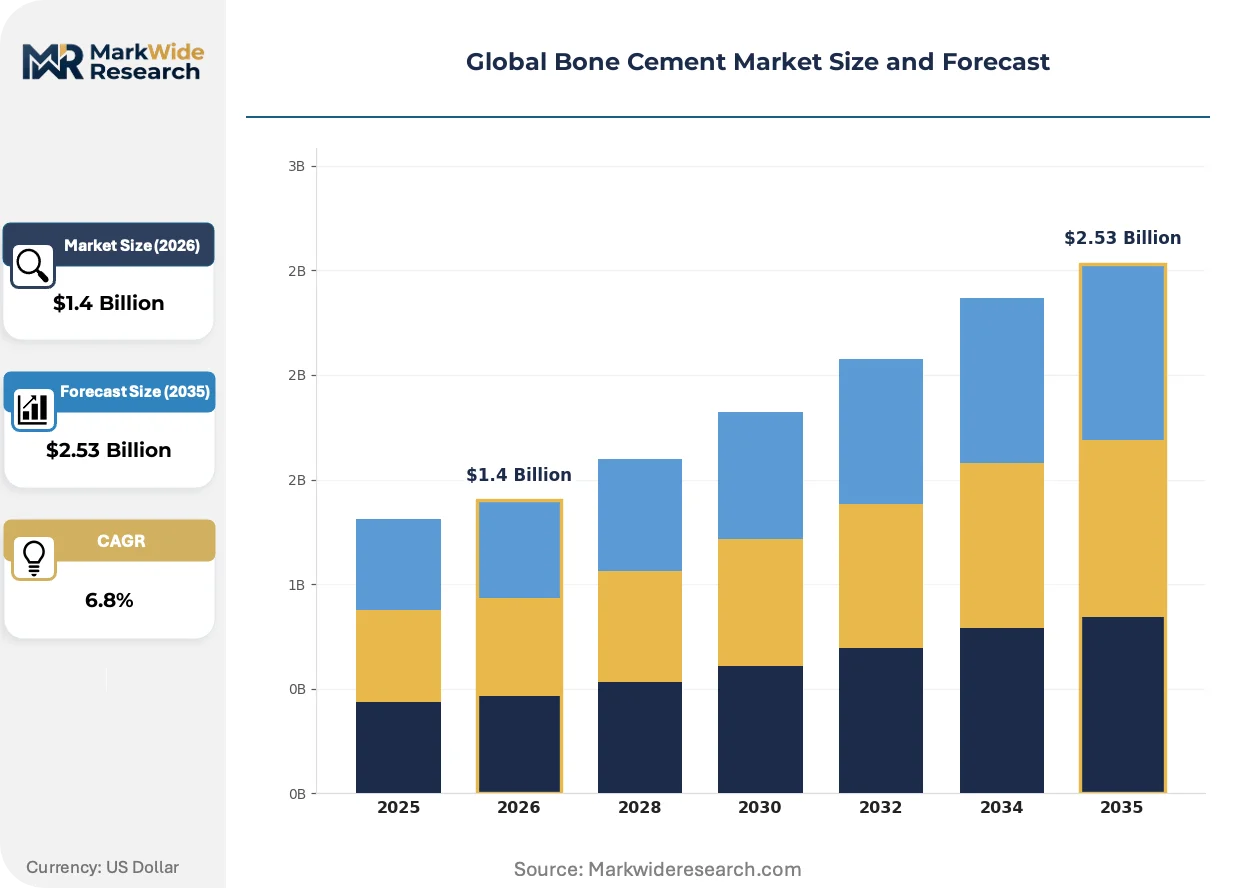
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PMA, Non-PMA, Biodegradable, Antibiotic-Loaded End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Ambulatory Surgical Centers Application: Joint Replacement, Spine Surgery, Trauma Surgery, Dental Surgery Distribution Channel: Direct Sales, Distributors, Online Platforms, Wholesalers |
| Companies Covered | Stryker Corporation, Zimmer Biomet Holdings, Inc., DePuy Synthes (Johnson & Johnson), Smith & Nephew plc, Heraeus Medical GmbH, Medtronic plc, B. Braun Melsungen AG, Exactech, Inc., Arthrex, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bone Cement Market Emerging Trajectories
Formulation chemistry and delivery mechanisms are converging to address unmet needs in infection prevention, operative efficiency, and bone-implant interface longevity across arthroplasty and spinal applications.
Smart cements incorporating antibiotic elution sensors and pH-responsive polymer networks are displacing conventional passive-release formulations in high-risk revision cases. Academic medical centers in Germany and the United States are piloting these systems for real-time infection monitoring. The displacement is compressing competitive differentiation around static antibiotic loading concentrations.
Europe's MDR Article 10 post-market surveillance requirements are mandating systematic clinical follow-up data collection for permanent implant cements. Manufacturers must now maintain active implant registries and submit periodic safety update reports. High-volume joint reconstruction centers in France and the Netherlands are restructuring procurement contracts to exclude suppliers lacking MDR-compliant technical documentation.
Direct-to-facility vendor-managed inventory is consolidating purchasing authority within integrated delivery networks. Ambulatory surgical centers in the United States are bypassing traditional distributor tiers through consignment arrangements with orthopedic systems suppliers. This channel compression is most visible in Texas and Florida markets where outpatient arthroplasty volumes are concentrating fastest.
Global Bone Cement Market Segmentation
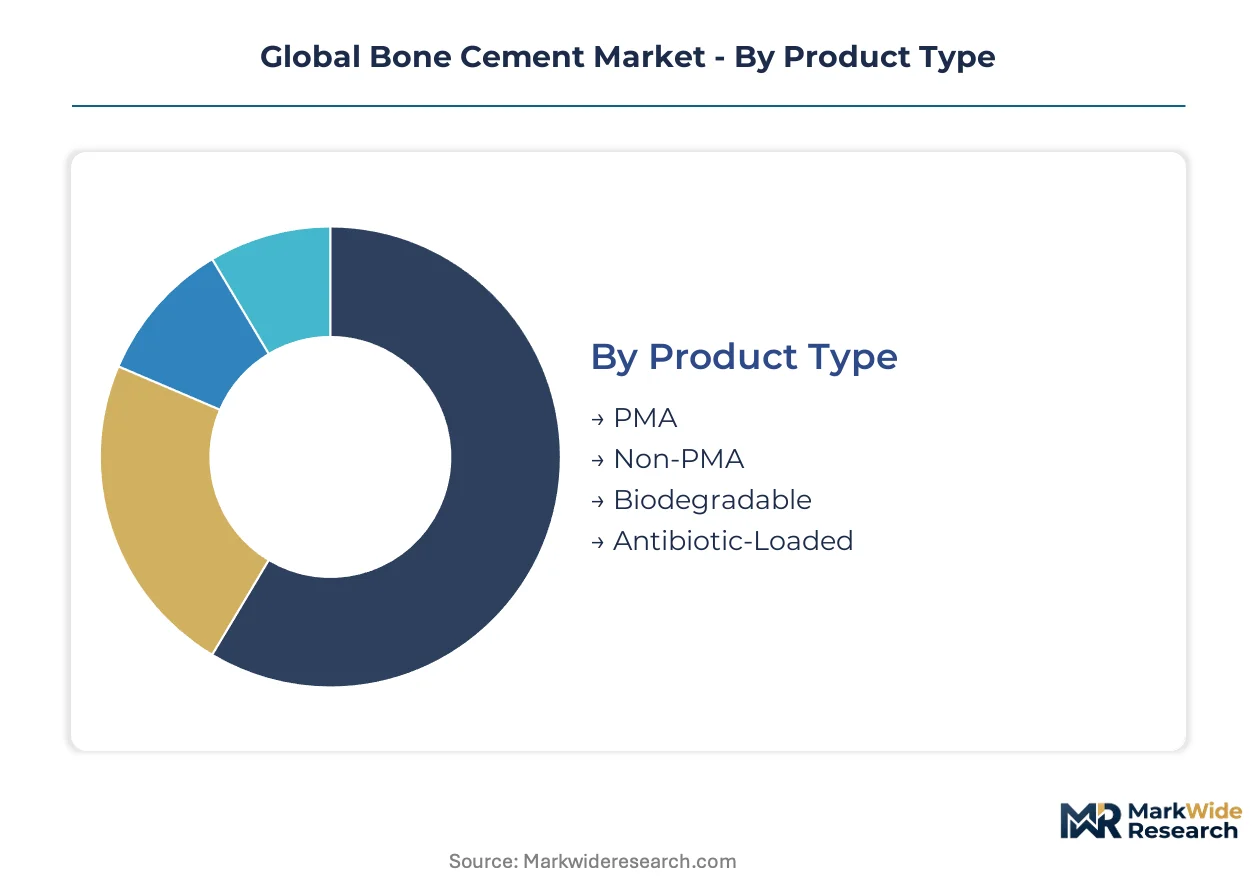
Segmentation in bone cement markets reveals how regulatory pathways, procedural settings, and supply chain configurations create distinct competitive arenas. Each dimension carries implications for validation costs, margin structures, and channel strategy.
Product Type:
Domestic procurement concentrates in PMA-validated grades across the United States and European hospital systems, while export-led demand from India and Brazil absorbs standard non-PMA formulations for cost-sensitive joint reconstruction programs.
- PMA:Premarket Approval cement grades meet FDA permanent implant standards with full clinical dossiers. United States academic medical centers mandate these formulations for load-bearing arthroplasty, with switching costs reinforced by surgeon training and institutional procurement protocols.
- Antibiotic-Loaded:PMMA matrices impregnated with gentamicin or vancomycin deliver localized prophylaxis. German and Dutch hospital systems are consolidating procurement around validated elution profiles as MDR post-market surveillance requirements tighten.
- Non-PMA:Standard-grade formulations serve provisional fixation and emerging market price tiers.
- Biodegradable:Calcium phosphate-PMMA hybrid matrices address revision surgery bone preservation.
Antibiotic-Loaded holds the largest share; momentum sits with Biodegradable.
End User:
Cost tier differentiation separates capital-intensive hospital integrated delivery networks from lean ambulatory operators seeking vendor-managed inventory terms.
- Hospitals:Academic medical centers and community hospital systems command procurement volume through orthopedic service line integration. United States IDNs in Texas and Florida are consolidating purchasing authority across expanding outpatient arthroplasty footprints.
- Ambulatory Surgical Centers:Freestanding surgical facilities concentrate same-day joint replacement volumes. These operators demand smaller kit formats and direct consignment arrangements that compress distributor margins.
- Orthopedic Clinics:Specialist practices handle preoperative planning and postoperative monitoring.
- Rehabilitation Centers:Post-acute facilities influence cement selection through readmission risk protocols.
Hospitals anchor volume absorption; Ambulatory Surgical Centers are climbing the fastest.
Application:
Volume concentration in mature joint reconstruction contrasts with application expansion in spinal procedures.
- Joint Replacement:Hip and knee arthroplasty consumes the dominant cement volume across United States, Germany, and United Kingdom markets. Revision surgery protocols are mandating antibiotic-loaded formulations as standard of care.
- Spine Surgery:Vertebral augmentation and tumor stabilization applications are gaining procedural share. French and Japanese spine centers are piloting high-viscosity cements for kyphoplasty with reduced extravasation risk.
- Trauma Surgery:Fracture fixation applications utilize provisional cement stabilization.
- Dental Surgery:Maxillofacial implant fixation represents a specialized niche segment.
Joint Replacement dominates revenue contribution; Spine Surgery shows the steepest expansion trajectory.
Distribution Channel:
Customer type stratification separates direct vendor relationships with integrated networks from fragmented distributor coverage of independent facilities.
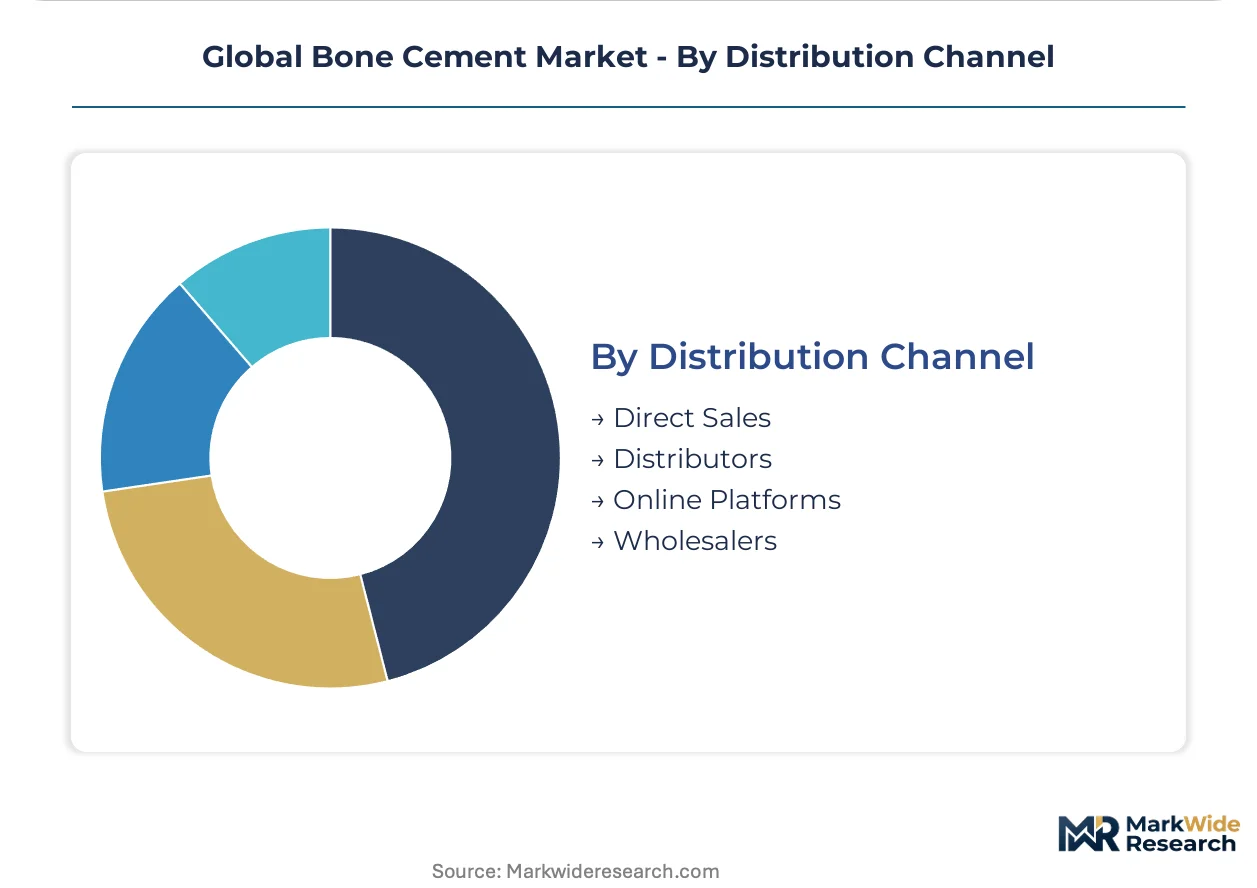
- Direct Sales:Orthopedic systems suppliers maintain captive sales forces for IDN accounts. Stryker and Zimmer Biomet deploy dedicated representatives to manage consignment inventory and surgeon training programs.
- Distributors:Independent medical device distributors serve mid-tier hospitals and regional orthopedic practices. These intermediaries face margin compression as manufacturers consolidate channel control.
- Online Platforms:E-procurement portals are emerging for standard-grade cement consumables.
- Wholesalers:Broad-line medical supply wholesalers handle commodity formulations.
Direct Sales captures premium pricing; Online Platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from German and Swiss manufacturers supply established hospital networks across Western Europe, while United States producers retain domestic procurement dominance through PMA-validated supply chains. Import dependency in India and Brazil sustains demand for standard-grade formulations.
United States
Outpatient arthroplasty migration to ambulatory surgical centers is compressing distributor tiers and consolidating purchasing authority within Texas and Florida integrated delivery networks. FDA PMA pathways govern permanent implant cement categories, elevating validation costs for non-domestic entrants. Cleveland Clinic and Mayo Clinic procurement systems mandate antibiotic-loaded formulations as revision surgery standards tighten.
Germany
Academic medical centers in Berlin and Munich anchor European demand for smart cement formulations with integrated antibiotic elution monitoring. EMA and MDR Article 10 post-market surveillance requirements enforce systematic clinical follow-up data collection. The Rhine-Ruhr industrial corridor concentrates manufacturing capacity for high-viscosity spine surgery cements.
India
Tier-2 and tier-3 city hospital expansion is absorbing standard non-PMA cement volumes for cost-sensitive joint reconstruction programs. CDSCO medical device registration pathways are harmonizing with ISO 5833 mechanical performance benchmarks. Maharashtra and Gujarat orthopedic clusters are localizing kit assembly for domestic procurement efficiency.
Japan
Aging demographics and kyphoplasty procedural growth are driving vertebral augmentation cement absorption in Tokyo and Osaka spine centers. PMDA pharmaceutical and medical device agency oversight aligns with JIS biocompatibility standards for permanent implant materials. The Nagoya medical device manufacturing belt supplies high-viscosity formulations with reduced extravasation risk profiles.
Brazil
Private hospital chains in São Paulo and Rio de Janeiro are upgrading joint replacement service lines toward antibiotic-loaded cement protocols. ANVISA medical device registration requirements are converging with international ISO certification timelines. The Southeast industrial corridor imports PMMA raw materials while domestic formulators compete on kit customization.
Global Bone Cement Market Vendor Landscape
Listed leaders compete with private specialists across validation tier access, with publicly traded orthopedic systems suppliers defending hospital account relationships through integrated training and consignment inventory programs. Market structure concentrates procurement authority among three to five vertically integrated manufacturers with captive distribution networks. Strategic archetypes span orthopedic systems integrators, specialty biomaterial formulators, and regional kit assemblers. Dominant competitive moves include direct-to-facility vendor-managed inventory consolidation and MDR-compliant clinical data registry establishment.
Within the orthopedic systems integrator tier, Stryker Corporation and Zimmer Biomet Holdings occupy positions defined by hospital account switching costs and geographic procurement consolidation. DePuy Synthes exemplifies the R&D-intensive archetype pursuing next-generation biodegradable cement matrices. These three listed entities anchor competitive dynamics through PMA pathway dominance and European MDR technical documentation advantages.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet Holdings, Inc. |
| DePuy Synthes (Johnson & Johnson) |
| Smith & Nephew plc |
| Heraeus Medical GmbH |
| Medtronic plc |
| B. Braun Melsungen AG |
| Exactech, Inc. |
| Arthrex, Inc. |
| Others |
Supply Flow & Price Mechanics
MDR clinical data mandates gate both supply qualification and price differentiation simultaneously, elevating PMA-validated formulations to premium tiers while compressing margins on standard non-PMA grades as European hospital systems consolidate procurement around compliant documentation.
Pricing Analysis
Hospital integrated delivery networks anchor contract-based long-term offtake structures across United States and German markets, with price differentiation driven by FDA PMA certification tier and surgeon training integration. Cost compression in standard non-PMA grades is intensifying because Brazilian and Indian hospital chains prioritize procurement efficiency over brand premium. Ambulatory surgical centers exhibit highest price sensitivity due to lean operating models, while academic medical centers demonstrate lowest sensitivity given infection protocol mandates.
Supply Chain Analysis
Vendor-managed inventory lead times have compressed to 48-72 hours for consignment arrangements at Texas and Florida ambulatory centers. Manufacturing concentrates in Germany, Switzerland, and the United States for PMA-validated grades, while India and Brazil localize kit assembly for standard formulations. Raw material sourcing draws from Saudi Arabian petrochemical feedstocks for methyl methacrylate monomer, Belgian polymer powder suppliers, and Chinese antibiotic active pharmaceutical ingredients. Single-source vulnerability in PMMA monomer supply creates exposure to petrochemical price cycles. Distribution runs through direct sales forces for IDN accounts and independent distributors for mid-tier hospitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as ceramic-on-ceramic cementless fixation captures select hip arthroplasty cohorts with sufficient bone quality, requiring strategic repositioning around revision surgery infection protocols.
For Market Incumbents: Secure MDR-compliant clinical data registries across German and Dutch hospital systems to elevate switching costs, while deepening backward integration into antibiotic active pharmaceutical ingredient sourcing to defend margin position against generic formulation pressure from Indian kit assemblers. For New Entrants and Emerging Players: CDSCO fast-track pathways for ISO 5833 mechanical compliance offer entry corridors into Maharashtra and Gujarat tier-2 city hospitals, with spine surgery vertebral augmentation applications presenting the most penetrable segment given lower PMA validation barriers and demand for high-viscosity formulations with reduced extravasation risk. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biodegradable cement R&D programs combining calcium phosphate with PMMA matrices, signaling long-term viability concentration among orthopedic systems integrators with captive hospital account relationships and active implant registry infrastructure. Acquisition targets should display MDR Article 10 post-market surveillance compliance and direct-to-facility consignment capabilities. The signal to watch is CMS reimbursement acceleration toward outpatient arthroplasty settings.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Clinical Data Registry Establishment | European hospital procurement contracts now exclude suppliers lacking Article 10 compliant technical documentation. |
| Vendor-Managed Inventory Consolidation | Texas and Florida integrated delivery networks are bypassing distributor tiers through direct consignment arrangements. |
| Biodegradable Cement R&D Convergence | Calcium phosphate-PMMA hybrid matrices address revision surgery bone stock preservation needs in academic medical centers. |
| Antibiotic Elution Sensor Integration | German and United States academic centers pilot smart cements for real-time infection monitoring in high-risk cases. |
| Direct-to-Facility Channel Control | Ambulatory surgical center expansion demands smaller kit formats and compressed lead times from orthopedic systems suppliers. |
Methodological Framework
Initial hypotheses were tested against primary input from orthopedic surgeons, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers and refined through secondary validation against FDA PMA filings, EMA MDR technical documentation databases, hospital procurement contract registries, and ISO 5833 mechanical performance certification records. Bottom-up demand modeling across procedural volume segments triangulated with top-down manufacturer capacity assessments.
Variance decomposition across product type, end user facility tier, application segment, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segmented volume absorption trajectories and pricing tier elasticity assumptions, incorporating methyl methacrylate monomer feedstock cost indices, joint replacement procedural growth rates, and ambulatory surgical center penetration curves as industry-specific forecast inputs.
Underlying assumptions cover MDR implementation timelines, CMS reimbursement shifts toward outpatient settings, and ceramic-on-ceramic bearing substitution rates, with deviation risk concentrated in petrochemical feedstock volatility and antibiotic elution kinetics standardization delays across notified bodies. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Veterinary Ultrasound Scanners Market
Medical Devices
Transcatheter Pacing System Market
Medical Devices
Vaginal Specula Market
Medical Devices
Manual Resuscitators Market
Medical Devices
Global Transradial Access Market
Medical Devices
Versatile Cryosurgical Devices Market
Medical Devices
Veterinary Arthroscopy Device Market
Medical Devices
Glass Syringe Market
Medical Devices
IoT Medical Devices Market
Medical Devices
Global Oxygen Conservation Devices Market
Medical Devices
Small Bowel Enteroscopes Market
Medical Devices
Small Bone and Joint Devices Market
Medical Devices
Automated CPR Devices Market
Medical Devices
Diabetes Devices Market
Medical Devices
Pressure-Volume Loop Systems Market
Medical Devices
Global Antimicrobial Coatings for Medical Devices Market