
 Chronic Total Occlusion Catheter Market | 2026-2036
Chronic Total Occlusion Catheter Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Total Occlusion Catheter Market Analytics
CE marking under the EU Medical Device Regulation is redrawing competitive access across Europe, raising clinical evidence requirements for chronic total occlusion catheters. Boston Scientific Corporation leverages integrated electrophysiology and interventional cardiology portfolios to sustain hospital contract stickiness. Medtronic Plc anchors its position through deep structural heart relationships that extend into CTO procedure bundles. Abbott Laboratories differentiates via optical coherence tomography-guided workflow ecosystems that tighten device-cath lab integration.
Chronic total occlusion catheters are specialized coronary and peripheral vascular devices engineered with tapered hydrophilic coatings, composite torque shafts, and variable stiffness transitions to navigate heavily calcified or fibrotic arterial blockages. Guide wire segments dominate procedural economics due to repeat consumption per case and rapid innovation cycles in tip load and polymer jacket configurations. Balloon catheters compete on crossing profile and rated burst pressure specifications, while intracoronary imaging technology integration is reshaping real-time procedural decision-making and premium pricing capture.
FDA premarket notification pathways and the EU MDR clinical evaluation requirements govern market entry timelines and post-market surveillance obligations for CTO catheter manufacturers. Japan's PMDA sakigake designation system offers priority review incentives that accelerate commercialization for novel crossing technologies. Stakeholders must monitor evolving reimbursement benchmarks for complex PCI procedures and the pace of hospital consolidation into integrated delivery networks that reshape procurement centralization.
Market Dynamics
CTO catheter development is compressing under dual pressures from EU MDR clinical evidence mandates and cath lab consolidation into integrated delivery networks demanding bundled pricing.
Growth Catalysts
- Aging demographics:Germany, Japan, and the United States are expanding procedural volumes as coronary artery disease prevalence rises among patients over 65.
- PMDA sakigake designation:Japan's priority review system accelerates commercialization timelines for novel crossing technologies.
- Optical coherence tomography:Real-time imaging integration tightens device-cath lab workflow capture and supports premium positioning.
Market Restraints
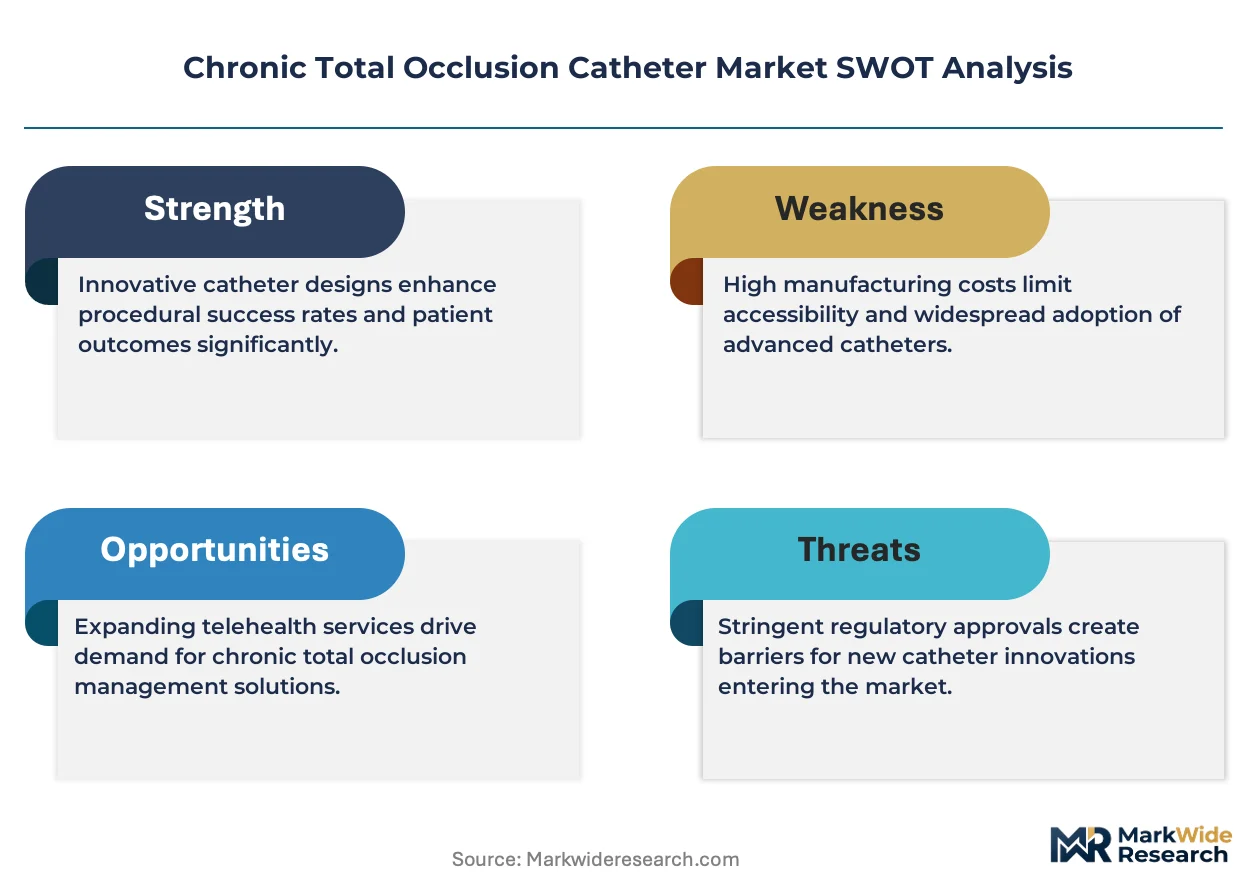
- EU MDR clinical evaluation:Expanded post-market surveillance obligations and notified body bottlenecks extend CE marking timelines.
- Nitinol supply concentration:Superelastic alloy sourcing clusters in a limited supplier base create input vulnerability.
- Coronary bypass substitution:Surgical revascularization retains preference for complex multivessel disease in select patient cohorts.
Strategic Opportunities
- Peripheral CTO expansion:Femoropopliteal and below-the-knee applications remain underpenetrated relative to coronary procedures.
- Robotic navigation convergence:Magnetic and robotic guidewire systems promise precision crossing in tortuous anatomy.
- FDA breakthrough device pathway:Expedited premarket review compresses development-to-revenue cycles for first-in-class technologies.
Industry Challenges
- Crossing specialist scarcity:Procedural complexity demands operators with dedicated CTO fellowship training that outpaces supply.
- Legacy cath lab integration:New catheter platforms require compatibility layers with installed imaging and hemodynamic monitoring infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Total Occlusion Catheter Market |
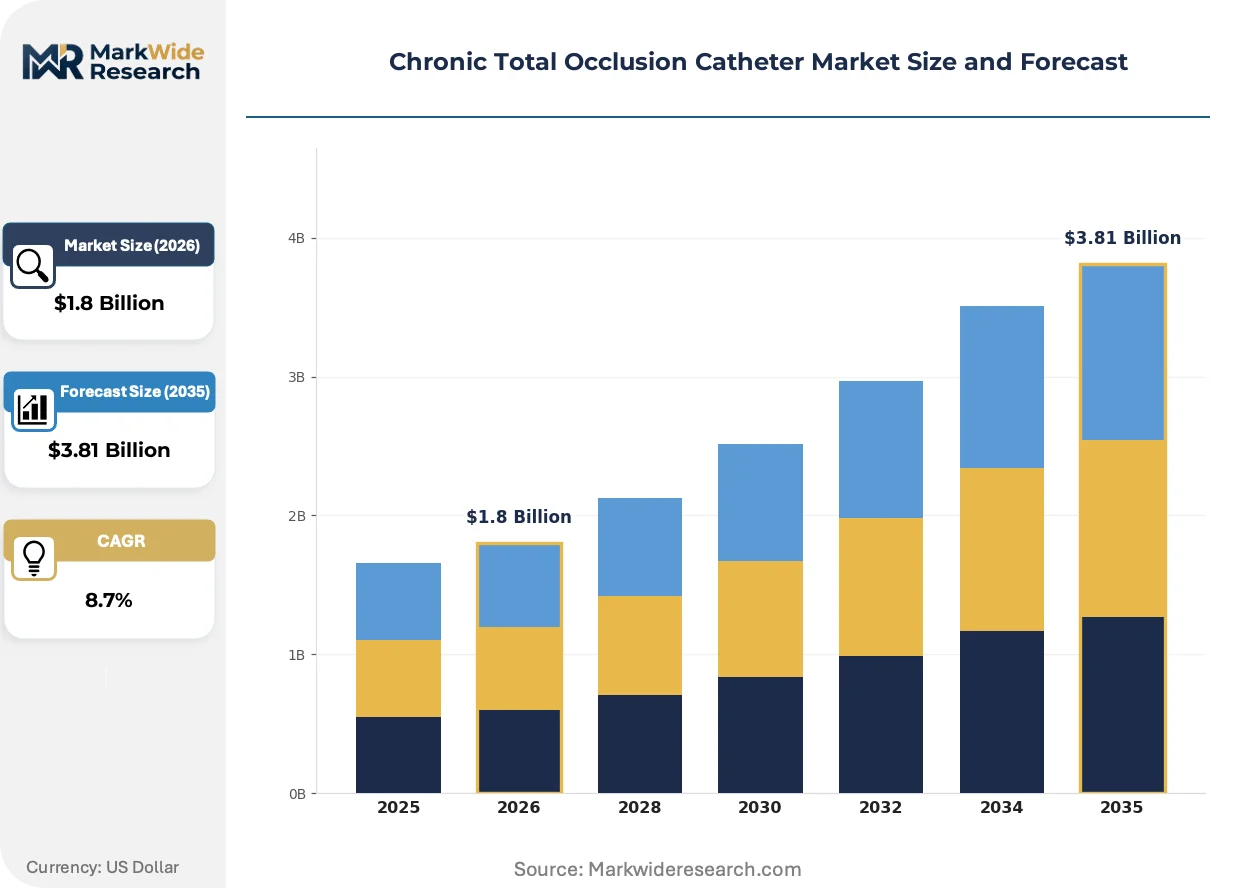
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon, Stent, Guide Wire, Accessory End User: Hospitals, Cardiology Centers, Ambulatory Surgical Centers, Research Institutions Technology: Optical Coherence Tomography, Intracoronary Imaging, Angiography, Ultrasound Procedure Type: Coronary Interventions, Peripheral Interventions, Renal Interventions, Electrophysiology |
| Companies Covered | Boston Scientific Corporation, Medtronic Plc, Abbott Laboratories, Asahi Intecc Co Ltd, Terumo Corporation, Cardinal Health, Cook Medical, Teleflex Incorporated, Reflow Medical Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Total Occlusion Catheter Market Evolving Landscape
Device architecture is pivoting toward precision navigation and real-time physiological feedback, compressing the gap between diagnostic imaging and therapeutic action.
Polymer-jacketed guidewire technology is miniaturizing tip loads below 3 grams while maintaining torque response. High-volume interventional cardiology centers in Germany and Japan are adopting these platforms for antegrade dissection and re-entry techniques. This capability is miniaturizing the learning curve for complex PCI and expanding the addressable operator base.
CE marking under EU MDR is redrawing competitive access across Europe. Clinical evidence requirements now mandate prospective registry data for chronic total occlusion indications, favoring manufacturers with established European investigator networks. Balloon catheter segments face the steepest compliance cost escalation.
Hospital procurement is consolidating vendor relationships into single-source contracts spanning electrophysiology and interventional portfolios. Integrated delivery networks in the United States are unbundling device procurement from procedure reimbursement, forcing manufacturers to demonstrate total cost-of-ownership metrics. This compression is most visible in catheterization lab networks exceeding 50 sites.
Chronic Total Occlusion Catheter Market Segmentation
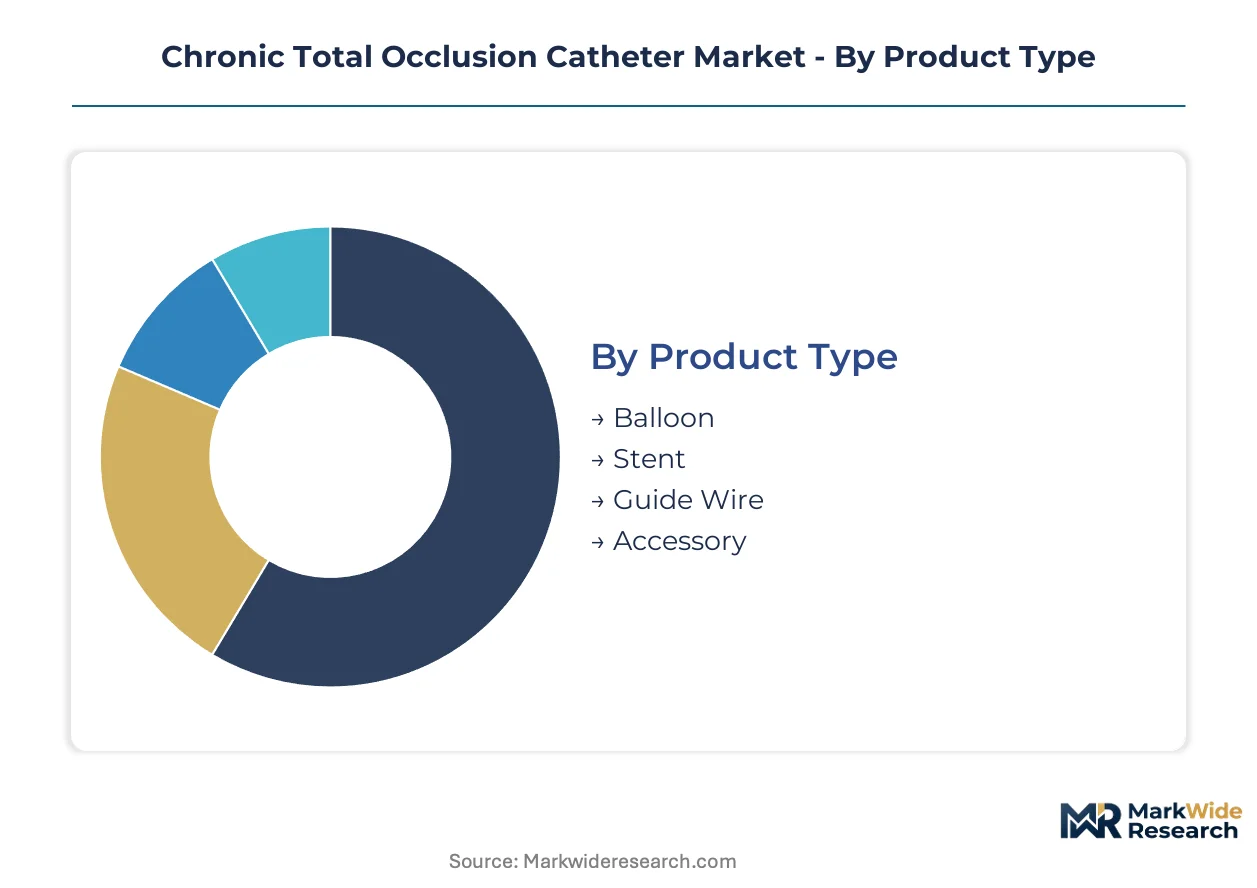
CTO catheter purchasing patterns diverge sharply across clinical settings and procedural complexity tiers. Device specifications, imaging integration requirements, and operator training levels create distinct demand profiles that manufacturers must address through parallel product architectures.
Product Type:
Domestic production clusters in the United States and Germany supply balloon and guidewire platforms, while Japanese manufacturers concentrate on precision guidewire exports across Asia-Pacific. Stent and accessory segments rely more heavily on contract manufacturing networks spanning Southeast Asia and Eastern Europe.
- Balloon:Low-profile crossing balloons with rated burst pressures exceeding 20 atmospheres enable lesion modification in calcified coronary segments. Demand concentrates in German and Japanese cardiology centers performing antegrade dissection and re-entry techniques, driven by reimbursement stability for complex PCI procedures.
- Guide Wire:Polymer-jacketed configurations with tapered hydrophilic coatings and composite torque shafts navigate tortuous arterial anatomy. United States integrated delivery networks consume high volumes due to repeat utilization per case and rapid turnover of tip load specifications from 1.5g to 12g ranges.
- Stent:Drug-eluting platforms deployed post-lesion crossing in coronary and peripheral applications.
- Accessory:Microcatheters, extension cables, and torque devices supporting procedural workflow efficiency.
Guide wire holds the largest share; momentum sits with balloon platforms integrating real-time imaging feedback.
End User:
Procurement authority concentrates differently across settings—hospital networks leverage volume scale, while cardiology centers prioritize device-physician relationship continuity.
- Hospitals:Academic medical centers and community hospital systems with catheterization lab infrastructure exceeding three suites. These facilities bundle CTO procedures with structural heart and electrophysiology service lines, creating multi-departmental contract stickiness for device vendors.
- Cardiology Centers:Dedicated interventional facilities in Germany, Japan, and the United States performing high procedural volumes. Operator specialization in antegrade and retrograde crossing techniques drives premium device uptake and rapid adoption of next-generation guidewire platforms.
- Ambulatory Surgical Centers:Limited penetration due to procedural complexity and emergency backup requirements.
- Research Institutions:Preclinical and clinical trial sites evaluating novel crossing technologies.
Hospitals dominate volume; cardiology centers command the steepest expansion trajectory as procedural specialization deepens.
Technology:
Imaging modality selection tracks directly with cath lab capital equipment installed base and operator training investment.
- Optical Coherence Tomography:Near-infrared light-based imaging achieving 10-micron resolution for plaque characterization and guidewire positioning. Japanese and German centers lead adoption, leveraging PMDA and EU MDR regulatory clarity to justify premium system investments.
- Intracoronary Imaging:Integrated ultrasound and optical platforms enabling real-time procedural decision-making. United States hospital networks deploy these systems across integrated delivery networks to standardize outcomes documentation for payor contracting.
- Angiography:Conventional X-ray fluoroscopy remains the baseline imaging standard.
- Ultrasound:Intravascular ultrasound systems providing cross-sectional vessel architecture assessment.
Optical coherence tomography captures the premium tier; intracoronary imaging platforms are gaining share fastest through workflow integration mandates.
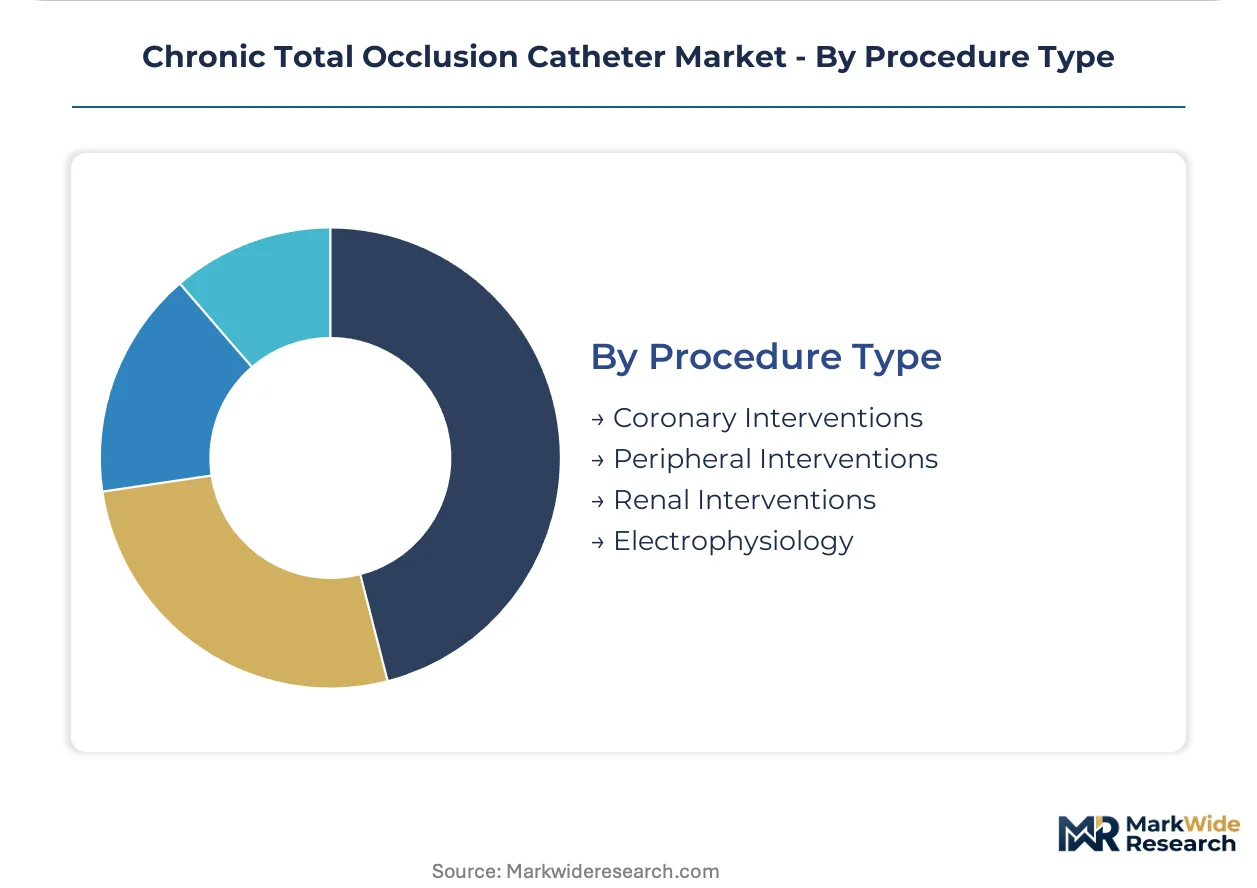
Procedure Type:
Coronary applications anchor current revenue, while peripheral expansion offers the clearest volume growth pathway as operator training programs mature.
- Coronary Interventions:Native vessel and graft CTO recanalization in left anterior descending, right coronary, and circumflex arteries. United States, German, and Japanese centers drive procedural economics through dedicated CTO fellowship programs and registry participation.
- Peripheral Interventions:Femoropopliteal and below-the-knee arterial recanalization for critical limb ischemia. Underpenetrated relative to coronary procedures, this segment attracts investment as crossing technology miniaturization enables tibial vessel navigation.
- Renal Interventions:Renal artery CTO recanalization for resistant hypertension management.
- Electrophysiology:Concomitant procedures requiring vascular access and mapping catheter navigation.
Coronary interventions retain volume leadership; peripheral applications show the steepest expansion trajectory as device miniaturization unlocks below-the-knee procedures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA breakthrough device designations and Japan's PMDA sakigake pathway are compressing commercialization timelines for next-generation crossing technologies. German reimbursement stability for complex PCI procedures sustains premium device uptake across integrated cath lab networks.
United States
Integrated delivery networks exceeding 50 sites are unbundling device procurement from procedure reimbursement, forcing total cost-of-ownership demonstrations. FDA premarket notification pathways govern market entry timelines for CTO catheter manufacturers. The Cleveland Clinic and Mayo Clinic catheterization clusters standardize outcomes documentation for payor contracting.
Germany
Cardiology centers in Munich and Heidelberg perform high procedural volumes with dedicated CTO fellowship programs. CE marking under EU MDR mandates prospective registry data for chronic total occlusion indications, favoring established European investigator networks. The Baden-Württemberg medical device corridor concentrates balloon catheter production and precision guidewire manufacturing.
Japan
PMDA sakigake designation offers priority review incentives that accelerate commercialization for novel crossing technologies. Tokyo and Osaka academic medical centers lead optical coherence tomography adoption for real-time plaque characterization. Aging demographics above age 65 are expanding procedural volumes for antegrade dissection and re-entry techniques.
China
NMPA regulatory pathways are streamlining for innovative cardiovascular devices while maintaining post-market surveillance obligations. Shanghai and Beijing hospital networks are expanding catheterization lab infrastructure to address rising coronary artery disease prevalence. Domestic manufacturers are capturing share in balloon catheter segments through cost-competitive positioning.
Chronic Total Occlusion Catheter Market Competitive Landscape
Player mix skews toward diversified cardiovascular conglomerates with integrated electrophysiology and interventional portfolios. The vendor base concentrates around three strategic archetypes: diversified medical technology conglomerates with structural heart relationships, precision guidewire specialists with polymer jacket expertise, and integrated delivery network contract holders with electrophysiology bundling capability. Dominant competitive moves include hospital procurement consolidation into single-source contracts and regulatory pathway optimization through FDA breakthrough and PMDA sakigake designations.
Among diversified cardiovascular technology conglomerates, Boston Scientific Corporation, Medtronic Plc, and Abbott Laboratories occupy positions that exemplify integrated portfolio strategies. These entities represent the contract stickiness archetype through multi-departmental hospital relationships spanning electrophysiology and interventional cardiology. Asahi Intecc Co Ltd and Terumo Corporation exemplify the precision manufacturing specialist archetype with concentrated expertise in guidewire torque response and hydrophilic coating technologies.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic Plc |
| Abbott Laboratories |
| Asahi Intecc Co Ltd |
| Terumo Corporation |
| Cardinal Health |
| Cook Medical |
| Teleflex Incorporated |
| Reflow Medical Inc |
| Others |
Value Network & Pricing Analysis
Capacity utilization at German and Japanese guidewire production facilities runs above industry benchmarks, compressing unit economics for precision torque shaft manufacturing while elevating price floors for polymer-jacketed platforms. This scale concentration grants incumbent manufacturers asymmetric power in contract negotiations with United States integrated delivery networks.
Pricing Analysis
Certification level (FDA breakthrough versus standard 510(k)) creates the primary spread between premium and standard tier positioning. Three-tier pricing structure across premium, standard, and economy levels tracks with CE marking status under EU MDR and PMDA sakigake designation in Japan. Pricing pressure stems from hospital procurement consolidation into single-source electrophysiology bundles. Academic medical centers exhibit lowest price sensitivity; ambulatory surgical centers face steepest budget constraints.
Supply Chain Analysis
Inventory lead times for nitinol superelastic alloy extend disproportionately relative to other catheter inputs, tethering production schedules to Taiwanese and Japanese metallurgical suppliers. Nitinol wire, hydrophilic polymer coatings, and composite torque filaments anchor bill-of-materials exposure. Single-source vulnerability concentrates in superelastic alloy feedstock. Distribution runs through GPO contracts and direct hospital system agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chronic total occlusion catheter development is accelerating under FDA breakthrough device compressions and PMDA sakigake pathways, creating inflection velocity for first-in-class crossing technologies.
For Market Incumbents: Shield market position through backward integration into nitinol alloy sourcing and captive hydrophilic coating production. Deepen structural heart procedure bundles to raise switching costs for integrated delivery networks. Prioritize CE marking pathway investments under EU MDR to defend European access against notified body bottlenecks. For New Entrants and Emerging Players: FDA breakthrough device designation offers the fastest regulatory fast-track for novel magnetic navigation platforms. Peripheral CTO applications in below-the-knee segments present the most penetrable white space. Target robotic guidewire convergence angles in partnership with academic catheterization labs lacking incumbent vendor lock-in. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision guidewire specialists with polymer jacket expertise and rapid tip load innovation cycles. Five-to-ten year viability favors manufacturers with established PMDA and FDA regulatory track records. Watch PMDA sakigake approval velocity as inflection signal for Japanese market access premium.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Compresses premarket review timelines for first-in-class crossing technologies. |
| CE Marking Pathway | Secures European access under EU MDR clinical evidence mandates. |
| Hospital System Partnership | Locks multi-departmental contracts across electrophysiology and interventional portfolios. |
| Software Companion Development | Integrates optical coherence tomography guidance into real-time procedural workflows. |
| Reimbursement Strategy | Aligns device positioning with complex PCI procedure benchmarks in United States and Germany. |
Research Methodology
Initial hypotheses were tested against primary input from interventional cardiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers and refined through secondary validation. Sources included FDA 510(k) and breakthrough device filings, PMDA approval databases, hospital procurement records, and CMS Medicare reimbursement schedules. Bottom-up procedure volume estimates and top-down device consumption models were triangulated.
Variance decomposition across product type, end user, technology, and procedure type dimensions structured the analytical framework. CAGRs were derived from fitted growth curves anchored to demographic projections and procedural adoption curves. Forecast inputs incorporated cath lab infrastructure expansion, operator fellowship training rates, and regulatory pathway velocity.
Decision-makers should treat outputs as directional under stable reimbursement and consolidation assumptions; material deviation in FDA review timelines or EU MDR notified body capacity would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global 3D Vascular Ultrasound Imaging Market
Cardiovascular Devices
Global Coronary Stent Market
Cardiovascular Devices
Drug Eluting Balloon Market
Cardiovascular Devices
Global Cardiovascular Disease Monitoring and Diagnostic Devices Market
Cardiovascular Devices
Cardiovascular Repair and Reconstruction Devices Market
Cardiovascular Devices
India Cardiovascular Devices Market
Cardiovascular Devices
South Korea Cardiovascular Devices Market
Cardiovascular Devices
Cardiovascular Anastomosis Devices Market
Cardiovascular Devices
Absorbable Heart Stent Market
Cardiovascular Devices
Stent Grafts Market
Cardiovascular Devices
LAMEA Cardiac Surgical Devices Market
Cardiovascular Devices
Europe Heart Valve Repair and Replacement Market
Cardiovascular Devices
Global Angio Suites Market
Cardiovascular Devices
Mobile Stroke Unit (MSTU) Market
Cardiovascular Devices
Single-Use Hemoperfusion Device Market
Cardiovascular Devices
Abdominal Stent Graft System Market