
 Defibrillator Pads Market | 2026-2036
Defibrillator Pads Market Size, Share, and Industry Trends Forecast 2026-2036
Defibrillator Pads Market Analysis
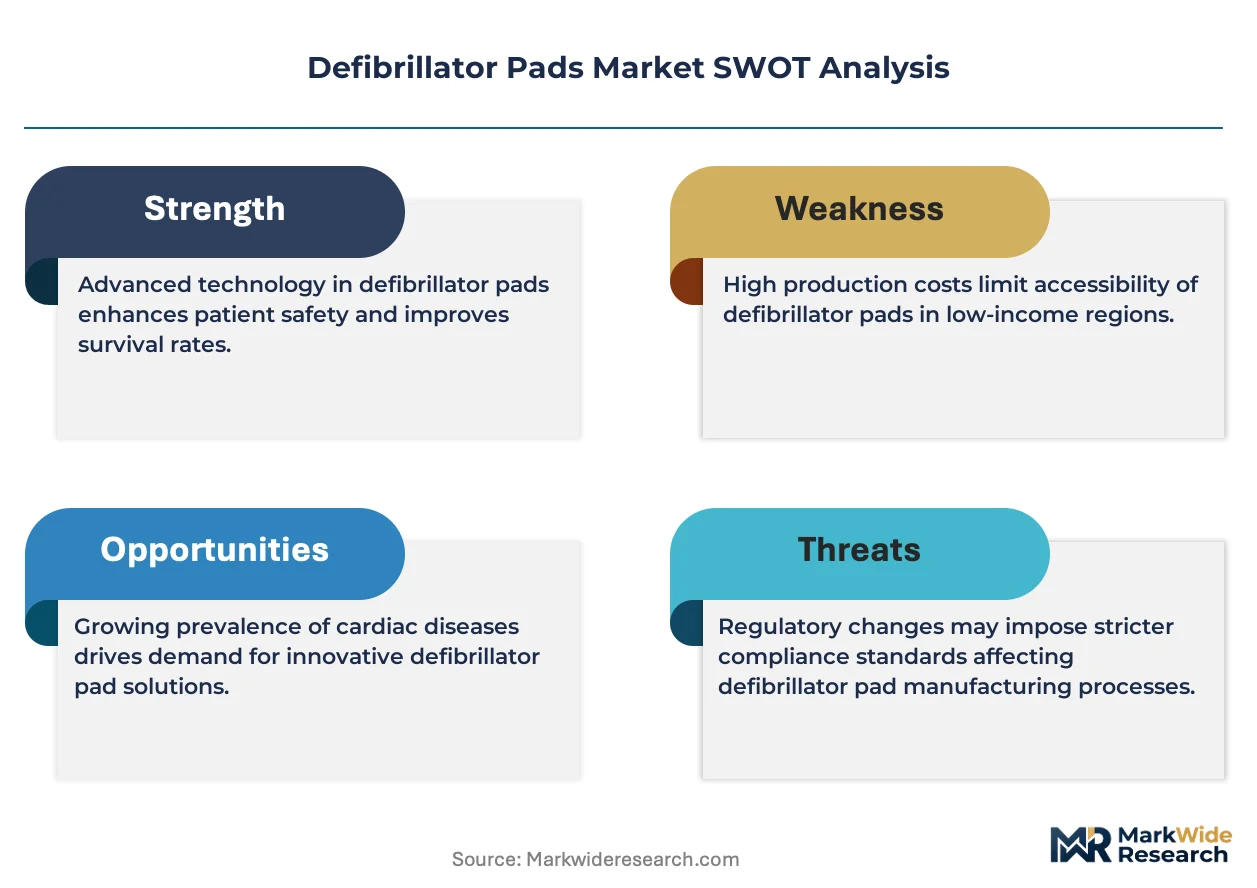
Wireless telemetry integration is fragmenting the traditional defibrillator pad technology stack, forcing manufacturers to embed real-time impedance monitoring and Bluetooth-enabled feedback loops directly into disposable electrodes. Philips leverages its cardiac resuscitation ecosystem to sustain premium positioning across hospital procurement channels. Zoll Medical Corporation anchors its market presence through proprietary connector designs that lock institutions into recurring pad purchases. Medtronic competes by dominating the emergency medical services segment with ruggedized pad constructions engineered for pre-hospital environments.
Defibrillator pads are single-use adhesive electrodes constructed from conductive hydrogel layers laminated to metalized polymer substrates, designed to deliver biphasic energy waveforms from external defibrillators to a patient's thorax with impedance below 100 ohms. Adult Pads generate the dominant revenue share due to standardized deployment across automated external defibrillator networks and hospital crash carts, while Pediatric Pads command higher unit margins through specialized surface area reduction and dose-attenuation engineering. The Standard Connector category leads volume shipments, though Snap Connector configurations are gaining traction in European markets where rapid pad replacement protocols prioritize mechanical reliability over cost minimization.
FDA 510(k) clearance pathways and the EU Medical Device Regulation's Class IIa designation shape product development timelines, forcing manufacturers to validate hydrogel shelf-life stability and electrical performance across temperature extremes before commercial release. The EU AI Act's emerging requirements for algorithm-enabled diagnostic devices will extend to next-generation pads incorporating rhythm-analysis sensors, adding compliance layers for firms pursuing intelligent electrode platforms. Stakeholders must monitor regulatory divergence between FDA's predicate-device framework and EMA's escalating clinical-evidence demands, as this friction will determine which connector standards and gel formulations achieve cross-border scale.
Market Dynamics
Wireless telemetry integration is fragmenting the traditional defibrillator pad technology stack, forcing manufacturers to embed real-time impedance monitoring and Bluetooth-enabled feedback loops directly into disposable electrodes. This shift compresses margins on legacy pad designs while creating new competitive battlegrounds around data interoperability and cardiac resuscitation ecosystem lock-in.
Growth Catalysts
- EU Medical Device Regulation Class IIa designation:The MDR's stricter clinical-evidence requirements are accelerating hospital procurement of certified pads with validated hydrogel shelf-life stability, displacing uncertified alternatives from European supply chains.
- Public access defibrillation programs:Municipalities across the United States, Germany, and Japan are deploying automated external defibrillator networks in airports, stadiums, and transit hubs, standardizing pad replacement cycles and volume commitments.
- Biphasic waveform technology:Next-generation defibrillators require impedance-matched pads engineered for truncated exponential waveforms, creating pull-through demand for advanced conductive hydrogel formulations.
Market Restraints
- Silver/silver chloride price volatility:Conductive hydrogel formulations depend on precious metal salts whose spot-market fluctuations compress manufacturing margins and complicate long-term supply agreements.
- FDA 510(k) predicate-device framework:The agency's reliance on substantial equivalence rather than de novo pathways creates regulatory friction for novel connector designs and gel chemistries, extending commercialization timelines.
- Reusable electrode substitution:Some hospital systems are piloting sterilizable conductive pads for controlled clinical environments, threatening single-use pad volumes in cost-sensitive procurement channels.
Strategic Opportunities
- Underpenetrated EMS segments in India:The country's expanding emergency medical services infrastructure lacks standardized defibrillator protocols, creating first-mover advantages for pad manufacturers establishing training and supply partnerships.
- EU AI Act algorithmic device pathways:Intelligent electrodes incorporating rhythm-analysis sensors will require new compliance frameworks, rewarding early movers who validate machine-learning-enabled diagnostic capabilities.
- Direct-to-facility distribution:Bypassing traditional medical device distributors through hospital system group purchasing organizations reduces channel costs and captures procurement data for predictive pad replenishment.
Industry Challenges
- Biocompatibility testing bottlenecks:ISO 10993 cytotoxicity and sensitization studies require specialized contract research organizations with limited capacity, delaying MDR and FDA submission timelines.
- Legacy defibrillator connector incompatibility:Proprietary pad-to-device interfaces from established manufacturers fragment procurement standardization, forcing hospitals to maintain multiple pad inventories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Defibrillator Pads Market |
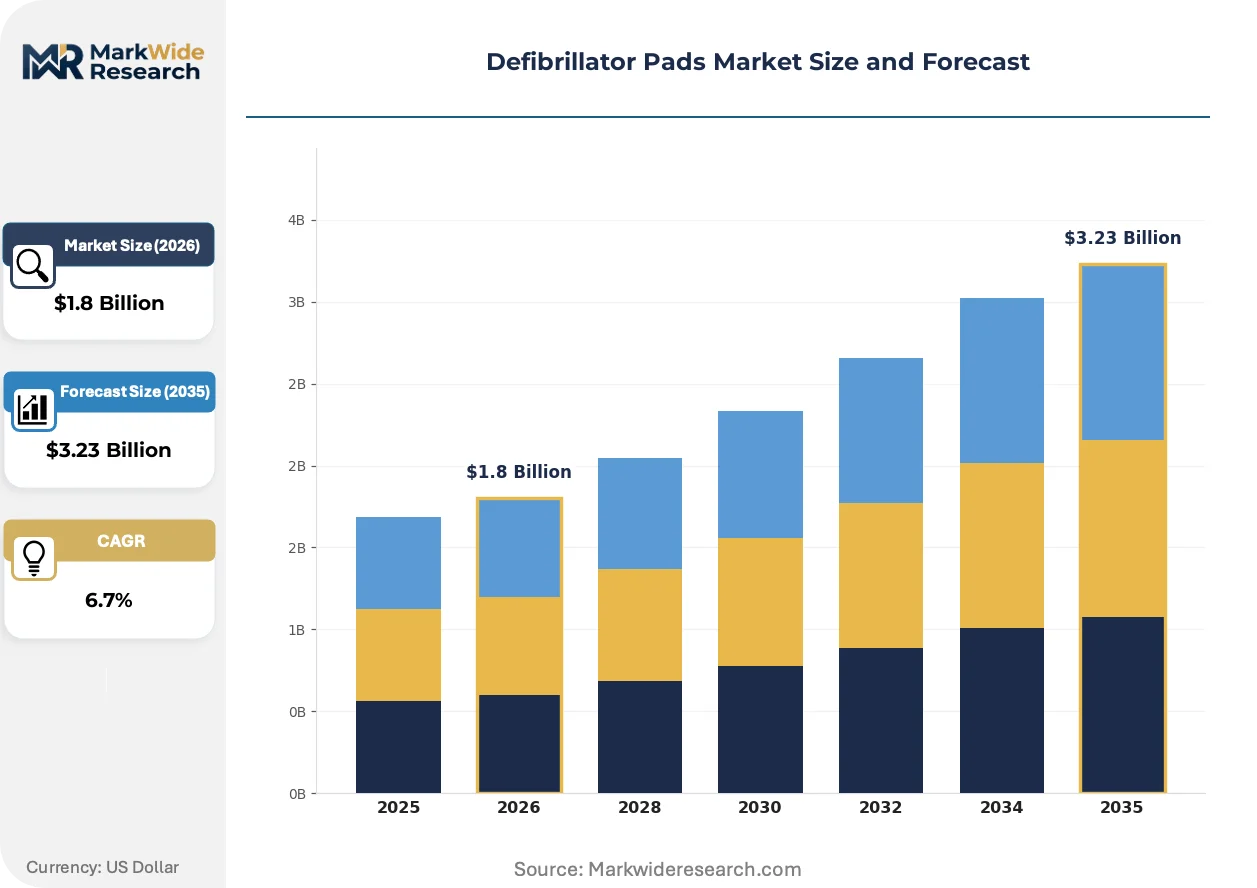
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adult Pads, Pediatric Pads, Training Pads, Specialty Pads Connection Type: Standard Connector, Snap Connector, Adhesive Connector, Others End User: Hospitals, Emergency Medical Services, Clinics, Home Care Packaging Type: Single Pack, Multi Pack, Bulk Packaging, Trial Pack |
| Companies Covered | Cardiac Science, Medline Industries, Philips, 3M, Cardinal Health, Zoll Medical Corporation, Stryker Corporation, ConMed, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Defibrillator Pads Market Emerging Trajectories
Real-time physiological monitoring is embedding intelligence at the electrode-patient interface, converting passive conductive pads into active diagnostic nodes. This transformation is compressing the traditional separation between defibrillation hardware and disposable consumables.
Conductive polymer nanocomposites are digitizing impedance measurement precision at the hydrogel-skin boundary. Emergency medical services fleets in Germany and Japan are adopting these materials for pre-hospital cardiac arrest protocols. The technology is digitizing field-triage decision-making by transmitting waveform quality data to receiving hospitals before patient arrival.
REACH Annex XVII restrictions on phthalate plasticizers are forcing reformulation of medical-grade adhesives used in pad construction. Manufacturers are validating alternative tackifiers derived from rosin esters and hydrogenated hydrocarbon resins. Pediatric pad categories face the steepest compliance burden given stricter exposure limits for vulnerable populations.
Hospital procurement departments are consolidating defibrillator pad purchasing through integrated delivery networks that negotiate multi-year sole-source agreements. Group purchasing organizations are displacing individual facility negotiations in the United States. This concentration is most visible in academic medical centers where standardization across affiliated community hospitals drives volume commitments.
Defibrillator Pads Market Segmentation
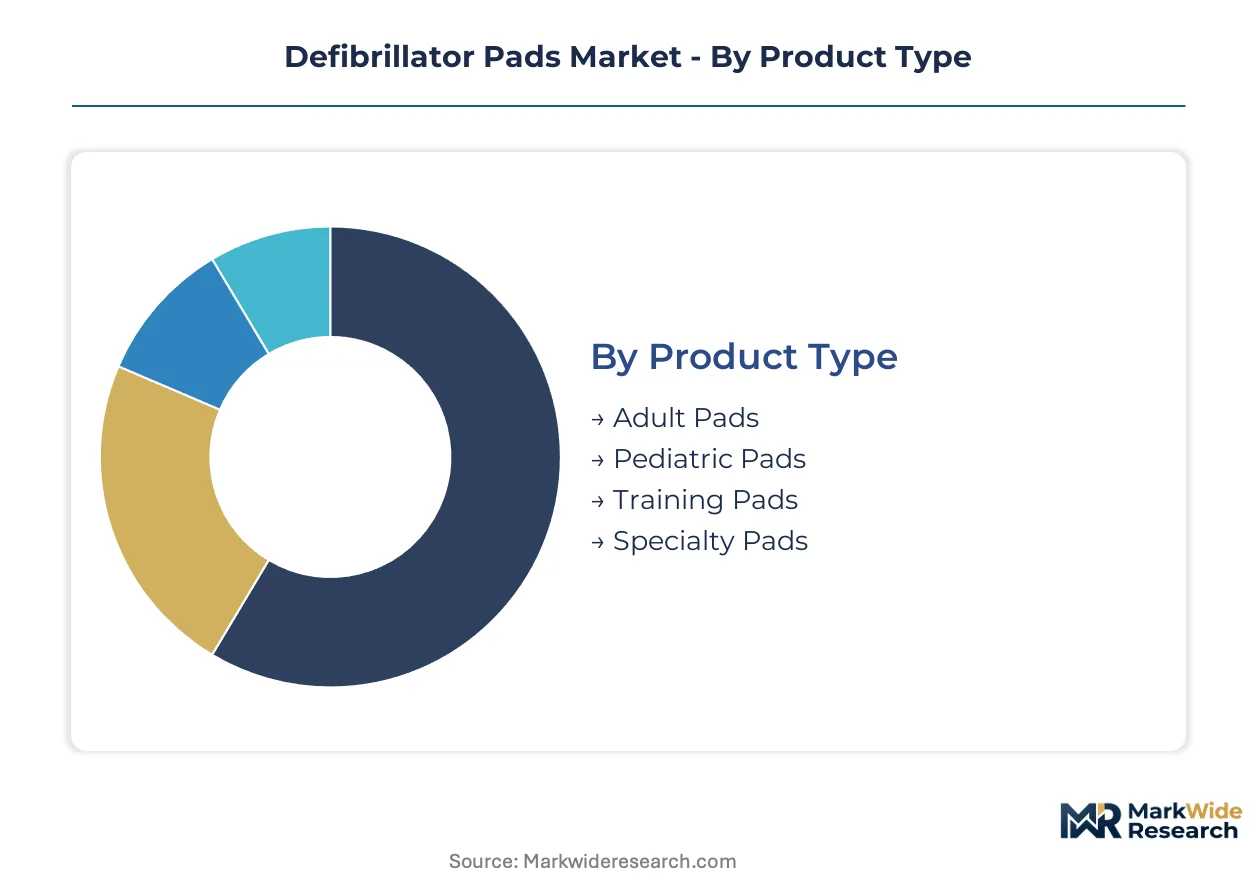
Defibrillator pad manufacturers engineer product portfolios around four intersecting dimensions: patient physiology, device interface protocols, care setting workflows, and inventory management economics. Each segmentation axis shapes procurement patterns, margin structures, and regulatory validation requirements differently.
Product Type:
Patient age and clinical indication create distinct use-case spectrums across pad categories, from mass-market adult deployment to specialized pediatric attenuation engineering.
- Adult Pads:These electrodes employ standardized conductive hydrogel surface areas of 80-100 cm² optimized for thoracic impedance below 75 ohms in patients over eight years old. Demand concentrates in United States airport automated external defibrillator networks and German hospital crash cart standardization programs, driven by municipal public access defibrillation mandates. The dominant share belongs to Adult Pads, while Pediatric Pads is closing the gap fastest.
- Pediatric Pads:Surface area reduction to 30-50 cm² combined with dose-attenuation resistors limits energy delivery to 50-75 joules appropriate for patients under 25 kg. Japanese emergency medical services fleets and United States pediatric hospital systems prioritize these configurations despite 40-60% unit price premiums.
- Training Pads:Reusable adhesive formulations with simulated impedance profiles support automated external defibrillator instruction without consumable waste. Flight crew certification programs and corporate wellness initiatives in Germany constitute primary demand nodes.
- Specialty Pads:Bipolar configurations for internal mammary artery surgery and radiolucent designs for catheterization laboratories address procedural niches. Academic medical centers in Japan and the United States drive sporadic high-margin procurement.
Adult Pads command procurement volume leadership through automated external defibrillator network saturation, though Pediatric Pads expansion accelerates with pediatric cardiac arrest protocol standardization.
Connection Type:
Mechanical interface reliability versus cost minimization creates tiered procurement preferences across healthcare delivery contexts.
- Standard Connector:Two-pin or three-pin plug configurations compatible with legacy defibrillator hardware dominate hospital procurement in cost-sensitive environments. United States integrated delivery networks and Indian emergency medical services infrastructure favor this category for inventory simplification.
- Snap Connector:Metal dome-and-socket mechanisms enable rapid pad replacement under time pressure, commanding preference in European emergency medical services protocols. German Red Cross ambulance specifications and French hospital rapid response teams validate this mechanical approach.
- Adhesive Connector:Integrated conductive adhesive layers eliminate separate cable attachment, reducing field failure modes in pre-hospital environments. Japanese mountain rescue services and United States wilderness emergency medical technician programs pilot these configurations.
- Others:Proprietary magnetic alignment systems and wireless capacitive coupling interfaces remain experimental, confined to research hospital consortia in Germany and Japan.
Standard Connector maintains installed base dominance through backward compatibility requirements, yet Snap Connector gains procurement share fastest as European emergency medical services prioritize mechanical reliability.
End User:
Care setting acuity and response time pressure generate divergent pad performance specifications and replenishment cadences.
- Hospitals:Inpatient cardiac arrest response protocols demand pads with validated two-year shelf stability and immediate impedance consistency across temperature-controlled storage. United States academic medical centers and Japanese tertiary hospitals drive volume through crash cart standardization.
- Emergency Medical Services:Pre-hospital environments require ruggedized hydrogel formulations maintaining adhesion through perspiration, rain, and temperature extremes from -20°C to 60°C. German ambulance fleet procurement and United States fire-rescue integration programs prioritize environmental resilience.
- Clinics:Outpatient diagnostic and surgical facilities utilize lower-rotation pad inventories with extended shelf-life requirements. United States ambulatory surgery centers and Japanese specialty cardiac clinics constitute fragmented demand.
- Home Care:Automated external defibrillator units for high-risk cardiac patients require consumer-intuitive packaging and simplified application instructions. United States remote patient monitoring programs and Japanese aging-in-place initiatives pilot limited deployment.
Hospitals anchor procurement volume through crash cart density and regulatory compliance mandates, though Emergency Medical Services exhibits the steepest expansion trajectory as pre-hospital cardiac arrest protocols proliferate.
Packaging Type:
Inventory carrying cost economics and expiration risk management shape procurement format preferences across facility types.
- Single Pack:Individual sterile pouches minimize waste from partial case usage in low-frequency arrest environments. United States rural hospitals and Japanese community clinics favor this format despite per-unit cost premiums.
- Multi Pack:Five-unit or ten-unit cases balance expiration risk aggregation with procurement efficiency. German hospital group purchasing organizations and United States integrated delivery networks standardize on this configuration.
- Bulk Packaging:Fifty-unit or hundred-unit master cases serve high-volume emergency medical services fleets and automated external defibrillator network maintenance contractors. Indian emergency medical services infrastructure and United States municipal public access programs drive demand.
- Trial Pack:Two-unit introductory configurations support device evaluation and training program initiation. Medical device distributors in Germany and Japan utilize these for customer acquisition.
Multi Pack commands procurement preference through expiration risk distribution and handling efficiency, while Bulk Packaging climbs fastest as emergency medical services fleet standardization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export defibrillator pads to United States hospital networks under long-term group purchasing agreements, establishing the transatlantic corridor as the dominant trade flow in this medical consumables segment.
United States
Public access defibrillation mandates in airports and transit hubs drive municipal procurement volumes. FDA 510(k) predicate-device requirements shape product development timelines for hydrogel formulations. Boston's academic medical center cluster standardizes crash cart inventories across affiliated community hospitals.
Germany
Ambulance fleet modernization programs prioritize ruggedized pad constructions for pre-hospital environments. EU Medical Device Regulation Class IIa designation accelerates certified pad displacement of uncertified alternatives. The Red Cross specifications in Bavaria establish connector standards adopted across Central European emergency services.
Japan
Aging-in-place initiatives pilot home care automated external defibrillator deployment for high-risk cardiac patients. PMDA consultation pathways influence pediatric pad validation requirements. Tokyo's tertiary hospital network drives volume through standardized crash cart protocols.
India
Emergency medical services infrastructure expansion creates first-mover opportunities for training and supply partnerships. CDSCO medical device rules govern import registration for foreign-manufactured pads. Maharashtra's urban ambulance fleets lack standardized defibrillator protocols, fragmenting procurement.
Defibrillator Pads Market Vendor Landscape
Channel-controlling players compete with product-specialist players across hospital procurement and emergency medical services segments. The vendor base concentrates around cardiac resuscitation ecosystem providers and standalone disposable electrode manufacturers. Three archetypes dominate: diversified medical technology conglomerates with cardiac portfolios, pure-play emergency care specialists, and contract manufacturers serving private-label distributors. Strategic moves center on proprietary connector lock-in and direct-to-facility distribution bypass.
Among diversified technology conglomerates, Philips and Medtronic exemplify ecosystem-anchored positioning. Zoll Medical Corporation occupies the emergency care specialist tier. These three represent distinct competitive vectors: Philips leverages integrated cardiac resuscitation platforms, Medtronic dominates pre-hospital emergency segments, and Zoll Medical Corporation anchors market presence through proprietary mechanical designs.
| Leading Market Players |
|---|
| Cardiac Science |
| Medline Industries |
| Philips |
| 3M |
| Cardinal Health |
| Zoll Medical Corporation |
| Stryker Corporation |
| ConMed |
| Medtronic |
| Others |
Supply Flow & Price Mechanics
Boston's medical device manufacturing corridor concentrates hydrogel formulation capacity and electrode substrate lamination, translating upstream material leverage into pricing power for manufacturers serving United States hospital group purchasing organizations. This geographic concentration enables volume-based contract negotiations that compress margins for second-tier suppliers while sustaining premium positioning for FDA-validated pad producers.
Pricing Analysis
Next-generation Bluetooth-enabled pads command 35-50% premiums over legacy designs lacking real-time impedance feedback, while standard adult pads face commoditization pressure from private-label distributors. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) certification status, with uncertified economy pads losing procurement share to MDR-validated alternatives. Pricing pressure stems from silver/silver chloride feedstock volatility and integrated delivery network consolidation. Emergency medical services fleets exhibit highest price sensitivity due to budget constraints, while Japanese tertiary hospitals prioritize performance over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize procurement relationships between United States hospital systems and contract manufacturers, straining working capital for smaller electrode producers. Hydrogel production concentrates in Germany, Japan, and the United States, with conductive polymer substrates sourced from South Korean and Taiwanese specialty chemical suppliers. Supply chain risk centers on single-source dependency for medical-grade adhesive formulations compliant with REACH Annex XVII phthalate restrictions. Distribution runs through regional medical device distributors and direct-to-facility group purchasing organization channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defibrillator pad economics increasingly hinge on recurring revenue from predictive replenishment services and training program subscriptions, which expand faster than hardware procurement as automated external defibrillator networks mature. This service-attach dynamic rewards manufacturers building data infrastructure for usage monitoring and expiration tracking.
For Market Incumbents: Pre-empt proprietary connector obsolescence by accelerating wireless telemetry pad development before Bluetooth-enabled diagnostics become table stakes. Backward integration into conductive hydrogel production secures margin control against silver salt price volatility. Lock in multi-year sole-source agreements with expanding United States integrated delivery networks before group purchasing organization consolidation peaks. For New Entrants and Emerging Players: Establish a beachhead in India's emergency medical services infrastructure by partnering with state-level ambulance fleet operators lacking standardized defibrillator protocols. Pediatric pad categories offer penetrable white space given specialized dose-attenuation engineering requirements that deter commodity producers. Lead with training pad bundled offerings to bypass entrenched hospital procurement relationships. For Investors and Strategic Acquirers: Long-term, this sits as a consumables-annuity play because pad replacement cycles synchronize with automated external defibrillator network maintenance contracts regardless of device OEM. Target acquisition archetypes include regional contract manufacturers with validated MDR technical documentation and established European emergency medical services channel relationships. Monitor FDA de novo pathway utilization for intelligent electrode submissions as inflection indicator for next-generation platform transitions.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | Accelerates certified pad displacement of uncertified alternatives in EU hospital procurement. |
| Wireless Telemetry Pad Development | Captures premium positioning as Bluetooth-enabled feedback loops become standard-of-care. |
| Direct-to-Facility Distribution Partnership | Bypasses traditional medical device distributors to capture procurement data for predictive replenishment. |
| Conductive Hydrogel Backward Integration | Insulates margins from silver/silver chloride spot-market volatility and supply disruption. |
| Pediatric Pad Regulatory Validation | Opens specialized high-margin segment with dose-attenuation engineering barriers to commodity competition. |
Methodological Framework
Desk research of FDA 510(k) premarket notification databases, EU MDR technical documentation registries, and hospital group purchasing organization contract disclosures preceded structured interviews with biomedical engineers, emergency medical services procurement officers, GPO contracts managers, and conductive materials R&D directors. Secondary validation drew from customs trade data, ISO 10993 biocompatibility testing records, and cardiac resuscitation protocol standardization documents. Bottom-up pad shipment estimates by connector type and end-use setting triangulated against top-down defibrillator unit installation data.
Assumptions held fixed include sustained MDR Class IIa enforcement intensity, continued silver/silver chloride feedstock availability, and stable biphasic waveform technology standards. The analytical framework modeled volume and value outputs across patient age segment, device interface protocol, care setting acuity, and packaging format dimensions over the projection horizon. CAGRs derived from regression analysis of historical procurement cycles correlated with public access defibrillator program expansion rates and hospital crash cart standardization timelines.
Sensitivities concentrate around EU AI Act algorithmic device pathway implementation timing, REACH Annex XVII adhesive reformulation compliance costs, and FDA predicate-device framework evolution for novel gel chemistries. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and technology substitution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Plastic Surgery Devices Market
Medical Devices
Retinal Implant Market
Medical Devices
Urodynamic Devices Market
Medical Devices
Global Dry Powder Inhaler (DPI) Market
Medical Devices
Endoscopic Mucosal Resection Device Market
Medical Devices
France Anesthesia Devices Market
Medical Devices
Dialysis Disposable Devices Market
Medical Devices
Animal Ultrasound Market
Medical Devices
Implantable Drug Eluting Devices Market
Medical Devices
Intervertebral Implants Market
Medical Devices
Multi-Channel Infusion Pumps Market
Medical Devices
Robotic Angiography Systems Market
Medical Devices
Benign Prostatic Hyperplasia (BPH) Treatment Devices Market
Medical Devices
Global Patient-Controlled Analgesic Pumps Market
Medical Devices
Global Breast Surgery Retractors Market
Medical Devices
Band Ligators Market