
 LED Control Unit Market | 2026-2036
LED Control Unit Market Size, Share, and Industry Trends Forecast 2026-2036
LED Control Unit Market Foresight
Silicon carbide is displacing silicon in power management circuits and is realigning cost structures across mid-to-high power LED control architectures. Signify Holding leverages vertical integration from semiconductor sourcing to fixture assembly, sustaining margin control across European commercial projects. Texas Instruments anchors its position through R&D intensity in precision analog dimming ICs, while Schneider Electric competes on building-management-system interoperability.
An LED control unit is an electronic device that modulates electrical power delivery to light-emitting diode arrays, typically incorporating microcontrollers, MOSFET drivers, and communication interfaces operating between 12V and 480V input ranges, with dimming resolution down to 0.1% in premium architectures. Its primary commercial purpose is to enable precise luminous output regulation, color temperature management, and networked scheduling for energy optimization in built environments. Networked control systems now capture the deepest margin pools as building operators prioritize centralized energy analytics over standalone switching, while wireless Bluetooth segments expand fastest in residential retrofit applications where wiring costs deter wired alternatives. Wired installations still dominate industrial end-use due to electromagnetic immunity requirements in manufacturing floors.
The EU Ecodesign Directive and CE marking requirements mandate minimum controllability standards for lighting products sold across member states, directly conditioning product design cycles and market access timelines. The US FCC regulates wireless control emissions, while China's MIIT governs Zigbee spectrum allocation for smart building networks, creating multi-jurisdictional compliance burdens for module suppliers. Stakeholders must monitor divergence between regional cybersecurity mandates for connected lighting infrastructure, as forthcoming requirements in the EU AI Act and analogous US frameworks will likely reshape firmware validation costs and competitive positioning for control unit vendors.
Market Dynamics
Silicon carbide power semiconductors are compressing thermal management costs and enabling higher-density LED control architectures in commercial and industrial deployments. This material transition is redrawing competitive boundaries between discrete component suppliers and integrated module vendors.
Growth Catalysts
- EU Ecodesign Directive:Mandates for minimum controllability standards in lighting products sold across member states are accelerating retrofit cycles in German, French, and British municipal infrastructure.
- Smart city infrastructure:Networked street lighting deployments in Chinese and Indian urban corridors are embedding centralized control units with real-time energy analytics capabilities.
- Silicon carbide MOSFETs:These wide-bandgap devices are reducing switching losses in mid-to-high power LED drivers, enabling smaller form factors in industrial high-bay applications.
Market Restraints
- Silicon carbide substrate shortage:Wafer supply constraints from dominant producers in the United States and Japan are inflating input costs for power management ICs.
- Electromagnetic compatibility certification:CE marking requirements for conducted emissions testing add twelve-to-eighteen month validation timelines for new wireless control architectures.
- Legacy fluorescent ballast installed base:Extended replacement cycles in budget-constrained municipal sectors in Southern Europe delay LED control unit penetration.
Strategic Opportunities
- India's commercial real estate pipeline:Green building certification mandates under the Energy Conservation Building Code are creating specification pull for networked controls in new construction.
- Bluetooth Mesh residential retrofit:Wireless commissioning without rewiring is unlocking single-family and multi-tenant residential segments previously inaccessible to wired systems.
- EU AI Act cybersecurity provisions:Forthcoming firmware validation requirements for connected infrastructure will favor vendors with pre-certified secure boot architectures.
Industry Challenges
- Firmware engineering talent scarcity:Shortages of embedded systems developers with Zigbee and Thread protocol expertise are constraining product roadmap velocity for mid-tier vendors.
- Legacy DALI integration complexity:Backward compatibility requirements with existing building automation buses are extending engineering cycles and inflating non-recurring engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Control Unit Market |
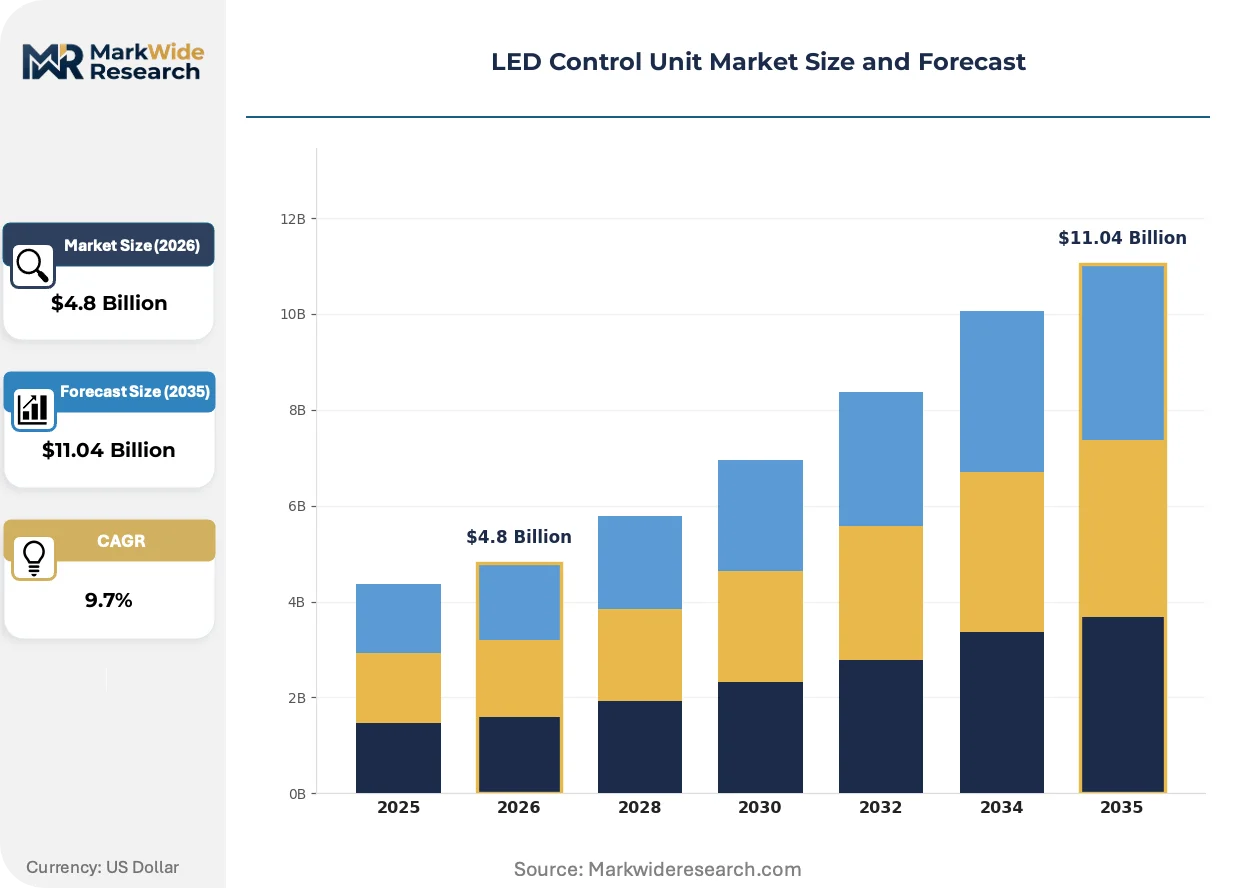
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Networked, Dimmable, Programmable Technology: Wired, Wireless, Zigbee, Bluetooth End User: Commercial, Residential, Industrial, Hospitality Installation: Surface Mount, Flush Mount, Recessed, Pendant |
| Companies Covered | Signify Holding, Acuity Brands Lighting, Lutron Electronics, Schneider Electric, Texas Instruments, Analog Devices, Legrand, General Electric Company, Eaton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Control Unit Market Shifts & Advancements
Power semiconductor materials, wireless protocol stacks, and cybersecurity mandates are simultaneously reshaping product architectures and vendor qualification criteria. These forces are compressing development timelines while expanding the addressable application perimeter.
GaN-on-silicon transistors are penetrating sub-500W LED driver applications with switching frequencies above 1MHz, enabling passive component miniaturization. Chinese power supply manufacturers are adopting these devices aggressively for cost-sensitive commercial downlight modules. GaN power electronics is converging with digital control loops to eliminate electrolytic capacitors and extend operational lifetime in thermally challenging luminaire enclosures.
The EU AI Act's risk classification framework for connected building infrastructure is mandating formal firmware validation and documentation trails for control units with autonomous dimming algorithms. This regulatory pressure is elevating compliance costs for module suppliers without established quality management systems. Premium-tier vendors with pre-existing ISO 27001 certifications are capturing specification share in German and Dutch commercial projects where cybersecurity clauses are hardening.
Building operators are unbundling hardware procurement from energy management service contracts, shifting specification authority from electrical contractors to facilities management platforms. This purchasing transformation is compressing vendor margins on standalone control units while expanding recurring software revenue pools. The Netherlands and Nordic markets exhibit this behavioral shift most acutely, where ESCO-led retrofit models dominate municipal and healthcare verticals.
LED Control Unit Market Segmentation
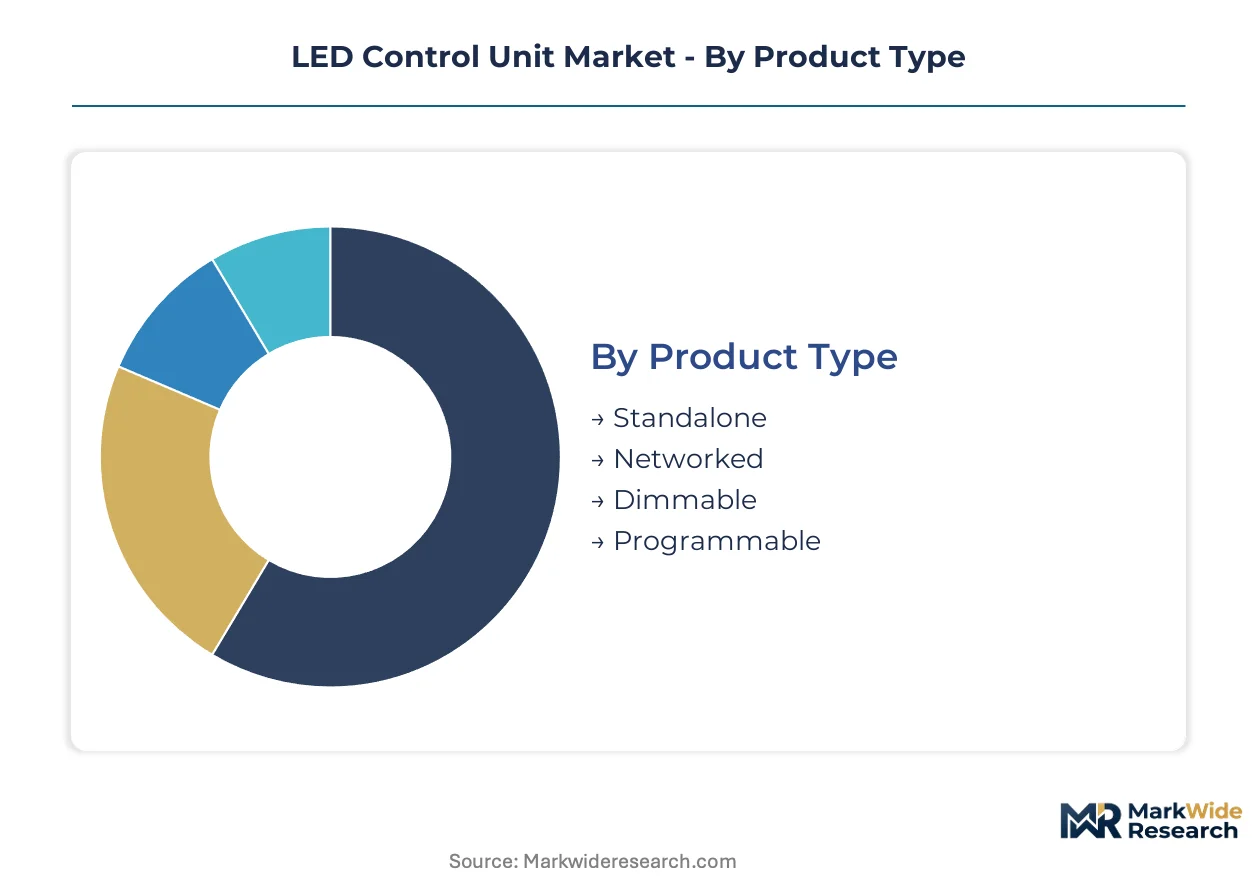
LED control unit procurement decisions hinge on interoperability requirements, retrofit constraints, and energy management sophistication. Specification authority increasingly rests with facilities management platforms rather than electrical contractors, reshaping how vendors align product portfolios to buyer workflows.
Product Type:
Buyers prioritize centralized energy analytics capabilities over standalone switching, elevating specification criteria for data integration and remote commissioning.
- Standalone:Self-contained units with local dimming and scheduling functions serve budget-constrained retrofit projects. Municipal sectors in Southern Europe favor these for extended fluorescent replacement cycles where networked infrastructure investment lags.
- Networked:Centralized control architectures with real-time energy analytics capture the deepest margin pools. Building operators in Germany, the Netherlands, and Nordic markets unbundle hardware from ESCO-led service contracts, shifting purchasing authority toward facilities management platforms.
- Dimmable:Analog and digital dimming modules with resolution down to 0.1% serve premium commercial installations. Precision luminous output regulation matters most in healthcare and museum verticals where circadian lighting protocols apply.
- Programmable:Firmware-configurable units with scene-setting and occupancy-based automation. The EU AI Act's risk classification framework elevates compliance costs for autonomous dimming algorithms without established quality management systems.
Networked leads on scale; programmable leads on momentum.
Technology:
Installation cost structures and electromagnetic immunity requirements determine protocol selection across end-use environments.
- Wired:DALI and 0-10V architectures dominate industrial floors where electromagnetic immunity is mandatory. Manufacturing facilities in Germany and Japan specify wired controls for immunity to motor drive interference.
- Wireless:Radio-frequency modules eliminate rewiring costs in residential retrofit. Single-family and multi-tenant segments previously inaccessible to wired systems now specify wireless for speed of deployment.
- Zigbee:Mesh networking protocols governed by China's MIIT spectrum allocation for smart building networks. Multi-jurisdictional compliance burdens constrain module suppliers serving cross-border projects.
- Bluetooth:Bluetooth Mesh enables wireless commissioning without electrical contractor involvement. Residential retrofit applications expand fastest where wiring costs deter wired alternatives.
Wired dominates industrial specification; Bluetooth expands most quickly in residential retrofit.
End User:
Energy efficiency mandates and green building certification requirements shape vertical-specific demand patterns.
- Commercial:Office and retail installations prioritize networked controls with centralized analytics. China's commercial real estate sector embeds these systems in new construction as developers respond to tightening efficiency standards.
- Residential:Single-family and multi-tenant retrofit drives wireless adoption. Bluetooth Mesh segments unlock specification where electrical contractor availability constrains wired deployment timelines.
- Industrial:High-bay and manufacturing floor applications specify wired architectures for electromagnetic immunity. Silicon carbide MOSFETs enable smaller form factors in thermally challenging luminaire enclosures.
- Hospitality:Guest room and public space controls balance aesthetic integration with energy management. Scene-setting and circadian programming differentiate premium property offerings.
Commercial commands the largest addressable base; hospitality shows steepest expansion trajectory.
Installation:
Architectural integration requirements and ceiling construction types determine form factor selection.
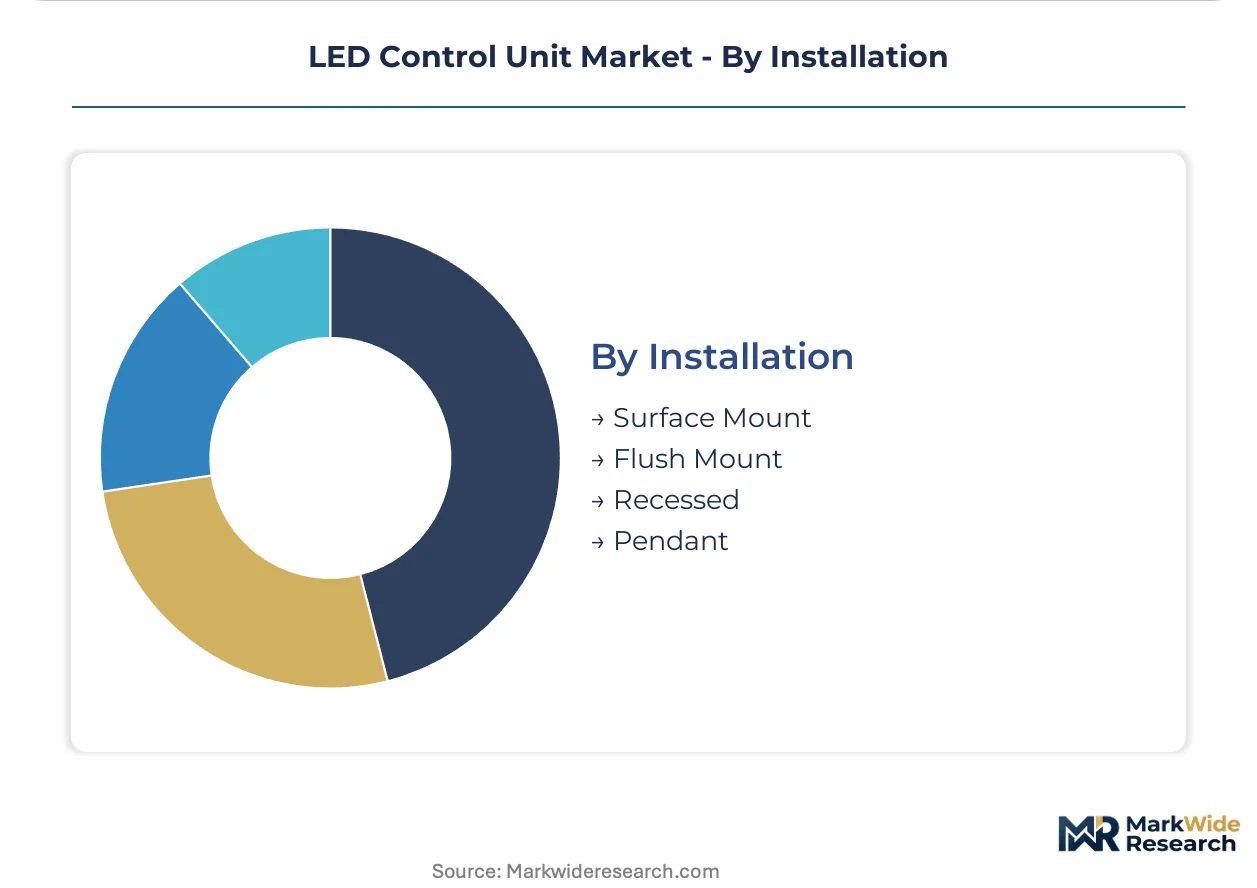
- Surface Mount:Exposed ceiling applications in industrial and historic retrofit where plenum access is restricted. German municipal infrastructure projects specify these for speed of deployment in street lighting upgrades.
- Flush Mount:Seamless ceiling integration for premium commercial and hospitality interiors. Dutch and Nordic healthcare facilities prioritize these for infection control and cleanability.
- Recessed:Plenum-mounted units for suspended ceiling grids in standard office construction. Volume concentration in Chinese commercial real estate new build.
- Pendant:Suspended luminaire controls for high-ceiling applications and architectural feature lighting. Industrial high-bay and atrium installations in Indian commercial real estate pipeline.
Recessed leads on volume scale; surface mount gains share fastest in infrastructure retrofit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Pearl River Delta anchors LED control unit manufacturing density, with Shenzhen and Guangzhou hosting vertically integrated electronics clusters that feed networked lighting deployments across domestic commercial real estate.
China
Commercial real estate developers in Shanghai and Beijing embed networked control systems in new construction to meet tightening efficiency standards under the MIIT's smart building directives. The MIIT governs Zigbee spectrum allocation for smart building networks, creating compliance frameworks that domestic vendors navigate more efficiently than foreign entrants. Shenzhen's electronics manufacturing corridor concentrates module assembly capacity, with local producers supplying Bluetooth Mesh and Zigbee controllers for residential retrofit across the Yangtze River Delta.
Germany
Municipal street lighting retrofits in Berlin, Munich, and Hamburg drive specification pull for DALI-architected networked controls with centralized energy analytics. The EU Ecodesign Directive mandates minimum controllability standards, accelerating replacement cycles in German municipal infrastructure. Bavaria's industrial automation corridor specifies wired LED control architectures for manufacturing floors, prioritizing electromagnetic immunity in automotive and machinery production environments.
United States
Healthcare and educational facilities in Texas, California, and the Northeast prioritize programmable controls with circadian lighting protocols for occupant wellness applications. The FCC regulates wireless control emissions, adding validation timelines for Bluetooth and Zigbee module deployments. Greater Boston's commercial real estate pipeline specifies networked controls with building-management-system interoperability, reflecting facilities management platform purchasing authority.
India
Green building certification mandates under the Energy Conservation Building Code create specification pull for networked controls in Mumbai and Delhi-NCR commercial construction. The Bureau of Indian Standards (BIS) establishes technical norms for lighting control products, conditioning market access for domestic and imported modules. Bangalore's technology campus expansion embeds intelligent lighting systems, with developers specifying centralized analytics for energy optimization in new IT park construction.
Netherlands
ESCO-led retrofit models dominate municipal and healthcare verticals, shifting purchasing authority toward facilities management platforms and away from electrical contractors. The EU AI Act's forthcoming cybersecurity provisions for connected infrastructure elevate compliance costs for control unit vendors without established quality management systems. Eindhoven's lighting technology cluster hosts R&D operations for precision dimming architectures serving museum and healthcare circadian lighting applications.
LED Control Unit Market Competitive Landscape
Global majors compete with regional champions across semiconductor sourcing and fixture assembly integration. The vendor base stratifies into three tiers: diversified electrical conglomerates with building-management-system portfolios, semiconductor specialists with precision analog dimming ICs, and vertically integrated lighting manufacturers controlling margin pools from chip to luminaire. Consolidation pressures concentrate among mid-tier module suppliers lacking certified secure boot architectures for forthcoming EU AI Act compliance. Dominant competitive moves include backward integration into silicon carbide power semiconductor sourcing and strategic partnerships with facilities management platforms for ESCO-led service contract positioning.
Among diversified electrical conglomerates, Signify Holding and Schneider Electric exemplify archetypes pursuing building-management-system interoperability as a specification wedge. Signify Holding represents vertical integration from semiconductor sourcing through fixture assembly, while Schneider Electric anchors a position on platform-level energy analytics integration. Texas Instruments sits within the semiconductor specialist tier, with precision analog dimming IC R&D intensity sustaining specification authority in premium commercial and healthcare verticals.
| Leading Market Players |
|---|
| Signify Holding |
| Acuity Brands Lighting |
| Lutron Electronics |
| Schneider Electric |
| Texas Instruments |
| Analog Devices |
| Legrand |
| General Electric Company |
| Eaton Corporation |
| Others |
Supply & Pricing Matrix
Backward integration into silicon carbide substrate sourcing anchors margin control for tier-one LED control unit vendors while compressing pricing power for module assemblers dependent on external wafer supply. Signify Holding's captive semiconductor procurement and Schneider Electric's platform-level energy analytics bundling illustrate how upstream control and downstream service attachment reshape competitive pricing dynamics across German and Dutch commercial projects.
Pricing Analysis
Silicon carbide wafer cost pass-through from United States and Japanese substrate suppliers is intensifying margin pressure across mid-tier power management IC vendors. Three-tier pricing structure across premium, standard, and economy levels separates vendors with ISO 27001 cybersecurity certifications from uncertified competitors facing EU AI Act compliance cost inflation. Municipal sectors in Southern Europe exhibit highest price sensitivity due to extended fluorescent replacement cycles, while healthcare and museum verticals in Germany and the Netherlands absorb premium pricing for 0.1% dimming resolution and circadian protocol support.
Supply Chain Analysis
Reverse-logistics flows for failed LED control units remain underdeveloped across European and North American markets, with refurbishment programs concentrated among Signify Holding's commercial service contracts in the Netherlands. Manufacturing draws from China's Pearl River Delta module assembly clusters, United States silicon carbide wafer fabrication, and Japanese power semiconductor packaging operations. Single-source vulnerability in wide-bandgap substrate supply from Wolfspeed and Coherent facilities creates tariff exposure risk under evolving United States-China trade frameworks. Distribution runs through electrical wholesale channels for wired industrial specifications and direct-to-platform routes for ESCO-led networked control deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon carbide power semiconductor cost compression and premium-tier specification pull for cybersecurity-certified architectures create dual margin expansion pathways for positioned vendors across the analysis window.
For Market Incumbents: Deploy firmware engineering talent retention programs to counter Zigbee and Thread protocol expertise scarcity constraining mid-tier competitor roadmap velocity. Prioritize pre-certified secure boot architecture investment ahead of EU AI Act enforcement timelines to capture specification share in German and Dutch commercial projects where cybersecurity clauses harden. Extend backward integration into silicon carbide substrate allocation agreements with United States and Japanese suppliers to defend input cost position against wafer supply constraints. For New Entrants and Emerging Players: Begin with Bluetooth Mesh residential retrofit specification in China's Yangtze River Delta and India's Mumbai-Delhi commercial corridors, where wiring cost avoidance unlocks previously inaccessible single-family and multi-tenant segments. Target India's Energy Conservation Building Code compliance-driven new construction pipeline for networked control specification pull. Pursue white-label module supply partnerships with domestic lighting fixture manufacturers to bypass direct incumbent channel conflicts. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier module suppliers with certified secure boot architectures because EU AI Act compliance cost inflation will strand uncertified competitors without quality management systems. Five-to-ten year viability concentrates in vendors with pre-existing ISO 27001 certifications and established facilities management platform relationships in ESCO-led retrofit markets. Monitor divergence between regional cybersecurity mandates for connected lighting infrastructure as early signal for firmware validation cost inflection and competitive repositioning velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Backward Integration | Captive wafer supply from United States and Japanese producers insulates margin compression from substrate shortage conditions. |
| Secure Boot Architecture Certification | Pre-certified firmware validation pathways capture specification authority ahead of EU AI Act risk classification enforcement. |
| ESCO Service Contract Positioning | Facilities management platform partnerships in Netherlands and Nordic markets shift purchasing authority from electrical contractors. |
| Bluetooth Mesh Residential Deployment | Wireless commissioning without rewiring unlocks China's Yangtze River Delta and Indian multi-tenant retrofit segments. |
| Precision Analog Dimming IC R&D | 0.1% resolution capability sustains premium positioning in German healthcare and Dutch museum circadian lighting applications. |
Research Methodology
Bottom-up commercial real estate and municipal infrastructure modeling reconciled against top-down semiconductor supply tracking forms the analytical core of this study. Primary interviews with facilities management platform directors, electrical contractor procurement leads, LED fixture OEM technical specification managers, and building automation system integrators were validated against secondary sources including MIIT smart building directive filings, EU Ecodesign Directive implementation reports, FCC wireless emission certification databases, and Bureau of Indian Standards technical norm publications.
Historical trendline analysis across networked control penetration rates and standalone unit replacement cycles established baseline growth parameters over the projection horizon. Segmentation dimensions encompassed product architecture type, wired versus wireless protocol selection, end-use vertical classification, and installation form factor preference. CAGR derivation incorporated silicon carbide MOSFET adoption velocity, Bluetooth Mesh commissioning cost trajectories, and regional green building certification mandate enforcement intensity as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including potential divergence between EU AI Act and United States cybersecurity framework implementation timelines, unanticipated silicon carbide substrate supply disruptions from geopolitical events, and acceleration or deceleration of fluorescent ballast replacement cycles in Southern European municipal budgets. Practitioners should monitor regulatory harmonization progress, wide-bandgap semiconductor capacity announcements, and ESCO contract model geographic expansion for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
North America Indoor LED Lighting Market
LED
LED Lighting Controllers Market
LED
Asia Pacific LED Lighting Market
LED
Europe LED Packaging Market
LED
North America Commercial LED Lighting Market
LED
Dual-Digit 7 Segment LED Displays Market
LED
Linear LED Strip Fixture Market
LED
LED Lighting Market
LED
GCC LED Lighting Market
LED
LED Services Market
LED
LED and OLED Display Market
LED
Middle East LED Lights Market
LED
China LED Market
LED
7 Segment LED Displays Market
LED
South America LED Lighting Market
LED
Global Outdoor LED Lighting Market